
 Spine Bone Stimulators Market | 2026-2036
Spine Bone Stimulators Market Size, Share, and Industry Trends Forecast 2026-2036
Spine Bone Stimulators Market Outlook
Software-defined treatment protocols embedded in non-invasive stimulator units is shifting the value proposition from hardware ownership to algorithm-driven therapy customization. Medtronic plc leverages its neurotechnology infrastructure to integrate spinal cord stimulation with bone healing platforms. Orthofix Medical Inc. specializes in pulsed electromagnetic field systems for ambulatory settings. DJO LLC competes through direct-to-patient rental and purchase channels that bypass traditional hospital procurement.
Spine bone stimulators are electrophysical devices that deliver targeted bioelectric, ultrasonic, or electromagnetic energy to accelerate osteogenesis and spinal fusion following vertebral surgery, typically operating at frequencies below 100 Hz with prescribed daily treatment durations. These devices serve orthopedic surgeons and rehabilitation specialists seeking to reduce non-union rates and shorten postoperative recovery intervals. Implantable stimulators command premium positioning due to surgical placement requirements and dedicated power systems, while non-invasive units dominate volume through home-based administration. Ultrasonic technology segments attract investment for their penetration depth advantages in multilevel fusion cases, though bioelectric platforms retain the broadest clinical validation.
The FDA's 510(k) premarket notification framework and the European Union's Medical Device Regulation govern device safety and clinical evidence standards, with both bodies intensifying scrutiny of real-world fusion outcome data to support clearance renewals. The Centers for Medicare and Medicaid Services in the United States and Germany's Federal Joint Committee influence adoption velocity through procedural coding and reimbursement rate determinations for bone growth stimulation. Stakeholders must monitor evolving payer evidence requirements and regulatory convergence between premarket approval pathways and post-market surveillance obligations.
Market Dynamics
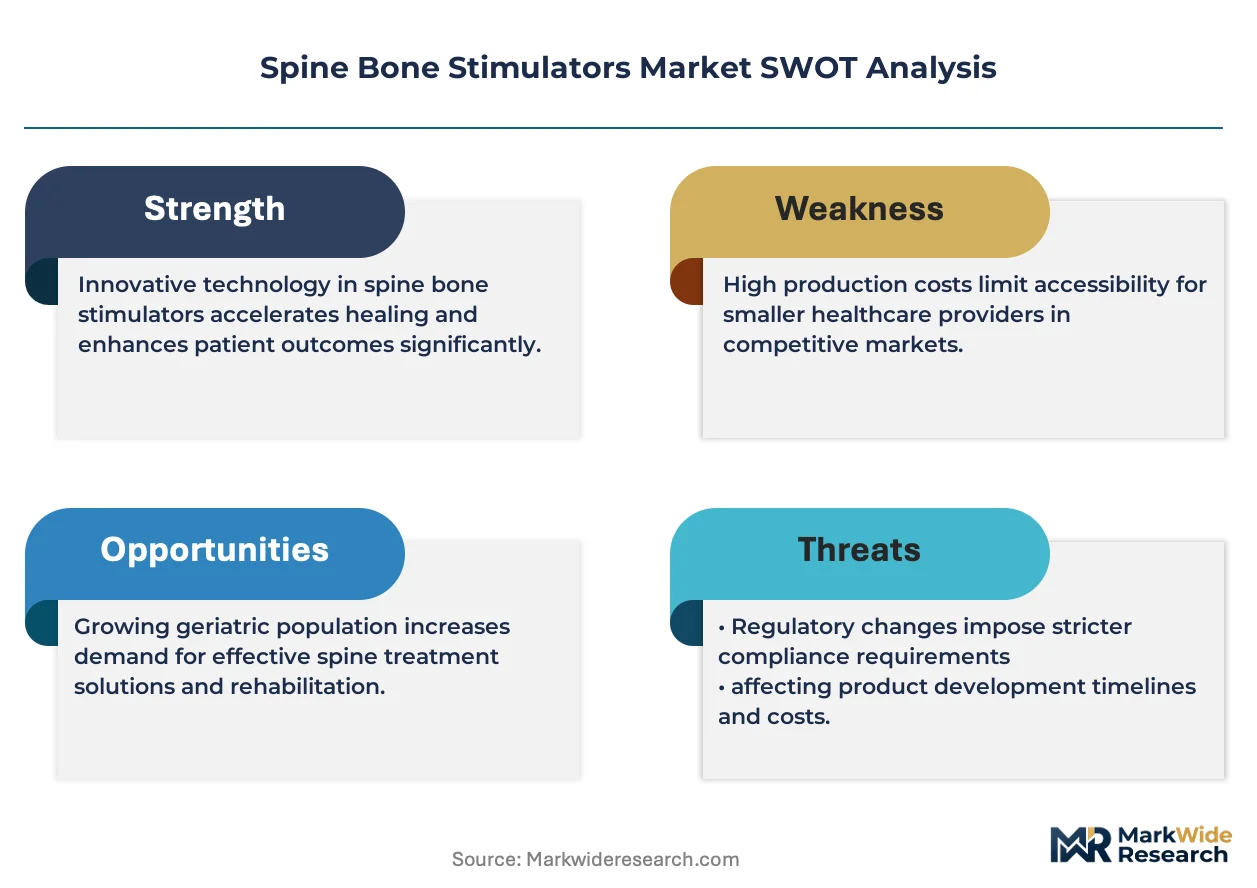
Software-defined treatment protocols embedded in non-invasive stimulator units are shifting the value proposition from hardware ownership to algorithm-driven therapy customization, compressing traditional device margins while opening recurring revenue streams.
Growth Catalysts
- Aging demographics:The United States population over 65 drives procedural volumes for spinal fusion surgeries, expanding the addressable patient pool for post-operative stimulation protocols.
- CMS reimbursement frameworks:Centers for Medicare and Medicaid Services procedural coding for bone growth stimulation reduces out-of-pocket burdens and accelerates clinical adoption in ambulatory surgical centers.
- Ultrasonic penetration depth:Multilevel fusion cases increasingly favor ultrasonic technology segments for their superior energy delivery through complex spinal anatomy.
Market Restraints
- Implantable device cost structure:Surgical placement requirements and dedicated power systems for implantable stimulators limit accessibility in cost-sensitive payer environments.
- Clinical evidence thresholds:FDA 510(k) clearance renewals intensify scrutiny of real-world fusion outcome data, extending development timelines and raising capital requirements.
- Non-invasive substitution:Home-based bioelectric platforms capture volume from implantable alternatives through comparable efficacy claims and reduced complication profiles.
Strategic Opportunities
- Germany's Federal Joint Committee:Reimbursement rate determinations for bone growth stimulation in Europe's largest healthcare market create expansion pathways for ambulatory protocols.
- Neurotechnology convergence:Spinal cord stimulation infrastructure is converging with bone healing platforms, enabling integrated therapy ecosystems for complex spinal disorders.
- Direct-to-patient channels:Rental and purchase models bypassing traditional hospital procurement unlock access in underserved rural and suburban markets.
Industry Challenges
- Algorithm validation timelines:Software-defined treatment protocols require extensive clinical validation to satisfy FDA post-market surveillance obligations for algorithm updates.
- Legacy system integration:Electronic health record compatibility and workflow integration with existing orthopedic practice management systems create deployment friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spine Bone Stimulators Market |
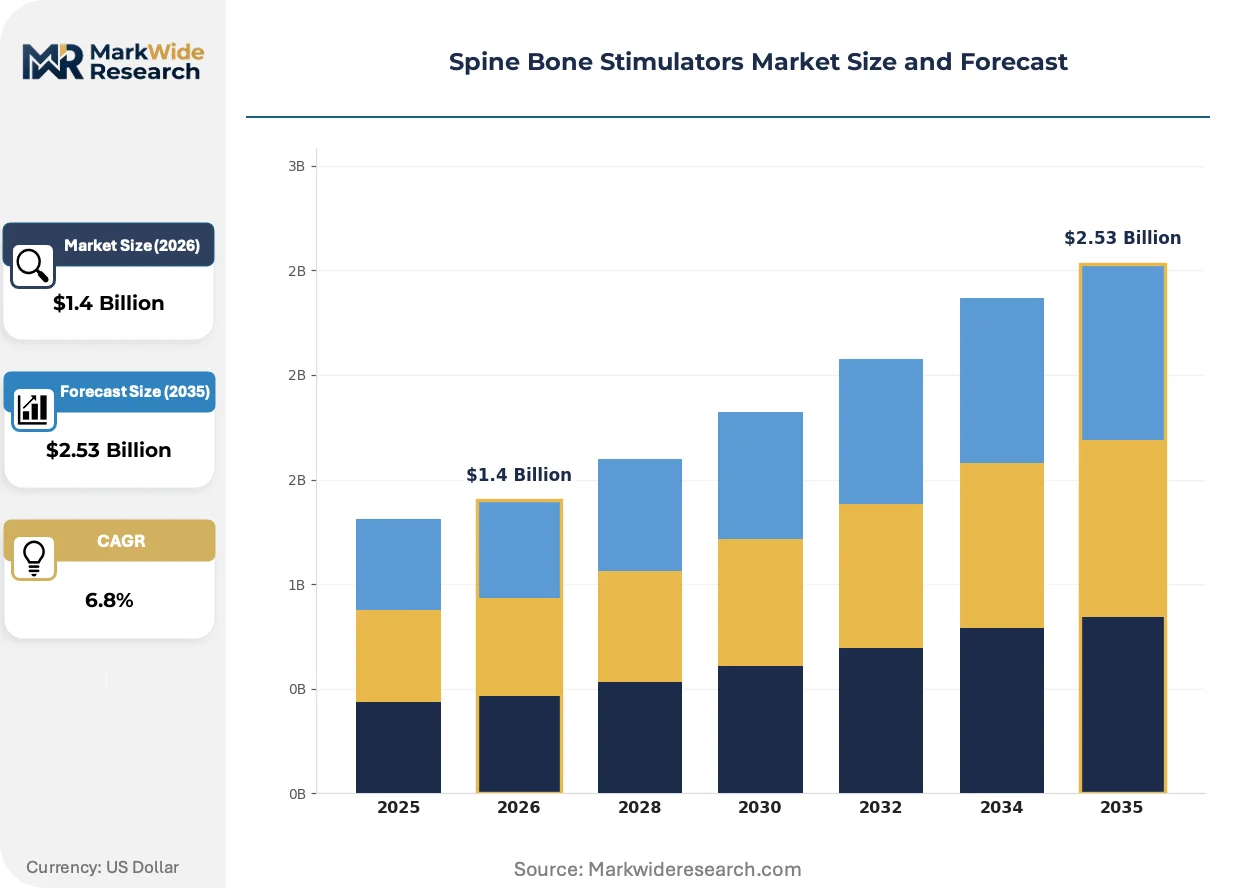
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Implantable, Non-invasive, Pulsed Electromagnetic Field, Ultrasound End User: Hospitals, Orthopedic Clinics, Rehabilitation Centers, Home Care Technology: Bioelectric, Ultrasonic, Electromagnetic, Low-Frequency Delivery Mode: Transcutaneous, Invasive, Surface Application, Wearable |
| Companies Covered | Medtronic plc, Orthofix Medical Inc., Zimmer Biomet Holdings, Inc., Bioventus, DJO LLC, Arthrex, Inc., Stryker Corporation, Smith & Nephew plc, Ossatec Benelux BV, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spine Bone Stimulators Market Strategic Shifts
Electrophysical delivery mechanisms are fragmenting into specialized energy modalities, each targeting distinct fusion pathologies and patient mobility requirements.
Ultrasonic bone stimulation technology delivers targeted acoustic energy at frequencies optimized for osteogenesis acceleration in multilevel spinal fusion cases. Academic medical centers in the United States are adopting these systems for complex revision surgeries where vascularized bone grafts face compromised healing environments. The technology is converging with intraoperative navigation platforms to enable real-time dosage adjustment based on bone density mapping.
The European Union's Medical Device Regulation intensifies post-market surveillance obligations for bone growth stimulators through expanded clinical follow-up requirements. Manufacturers must now submit periodic safety update reports with fusion outcome data spanning multi-year patient cohorts. Implantable stimulator segments face the steepest compliance burden due to their invasive classification and battery-related biocompatity concerns.
Orthopedic clinics are unbundling device procurement from therapy management, separating hardware acquisition from algorithm subscription and remote patient monitoring services. This restructuring compresses capital expenditure cycles while elongating vendor relationships through recurring clinical support contracts. The United States ambulatory surgery center segment exhibits the most pronounced shift toward outcome-contingent payment structures tied to fusion confirmation imaging.
Spine Bone Stimulators Market Segmentation
Product configuration and care setting selection determine reimbursement pathways and clinical workflow integration for spine bone stimulators. Segmentation reveals how technology modality and delivery mechanism shape patient access and provider economics.
Product Type:
Cost tier and surgical risk tolerance drive procurement decisions across ambulatory and inpatient settings.
- Implantable:Surgically embedded units with internal power systems deliver continuous electrical stimulation directly to fusion sites. Demand concentrates in academic medical centers performing complex multilevel revisions where patient compliance with external devices proves unreliable. Surgical placement requirements and premium pricing limit penetration in cost-sensitive payer environments.
- Non-invasive:External devices applied through skin electrodes or coils enable home-based administration without operative risk. Orthopedic clinics in the United States favor these units for ambulatory surgical center discharges where remote monitoring supports adherence tracking. CMS procedural coding and rental reimbursement frameworks accelerate clinical adoption over implantable alternatives.
- Pulsed Electromagnetic Field:Coil-based systems generate time-varying magnetic fields to induce osteogenic currents in bone tissue.
- Ultrasound:Acoustic energy devices penetrate deeper through spinal anatomy for multilevel fusion cases.
Volume sits with Non-invasive; growth tilts toward Ultrasound.
End User:
Site-of-care migration from hospitals to outpatient settings is redistributing device procurement authority.
- Hospitals:Inpatient surgical departments manage implantable stimulator placement during index fusion procedures. Demand concentrates in tertiary referral centers handling complex deformity corrections and revision surgeries where integrated operating room workflows support sterile device handling.
- Orthopedic Clinics:Specialized spine practices prescribe non-invasive units for postoperative protocols and non-surgical candidates. United States ambulatory surgery centers within these networks capture shifting procedural volumes through same-day discharge pathways.
- Rehabilitation Centers:Post-acute facilities incorporate stimulators into multimodal recovery programs.
- Home Care:Direct-to-patient rental channels bypass institutional procurement for rural and suburban access.
Procurement authority is shifting from Hospitals to Orthopedic Clinics; Home Care channels are expanding most quickly.
Technology:
Energy modality selection depends on fusion pathology, penetration depth requirements, and existing clinical validation.
- Bioelectric:Direct current and capacitive coupling systems operating below 100 Hz deliver targeted electrical fields to osteoblast populations. United States orthopedic surgeons favor these platforms for their extensive peer-reviewed evidence base and established CPT coding. Long-term outcome data supports FDA 510(k) clearance renewals and payer coverage determinations.
- Ultrasonic:Acoustic wave propagation at megahertz frequencies achieves superior penetration through soft tissue and bone. Academic medical centers adopt these systems for multilevel fusions and compromised graft beds where vascularization limits healing. Integration with intraoperative navigation enables real-time dosage adjustment.
- Electromagnetic:Inductive coupling generates therapeutic currents without skin contact.
- Low-Frequency:Sub-hertz pulsed protocols target cellular membrane permeability modulation.
Installed base concentrates in Bioelectric; technology investment flows toward Ultrasonic.
Delivery Mode:
Patient mobility requirements and treatment duration shape interface design and adherence engineering.
- Transcutaneous:Electrode-based systems deliver current across intact skin to underlying fusion sites. Home care settings in the United States prefer these configurations for their simplicity and minimal training requirements. Daily treatment duration protocols typically require 30-60 minute sessions.
- Invasive:Percutaneous lead placement enables targeted delivery without full surgical implantation. Pain management specialists utilize these systems for patients requiring intermediate invasiveness between external and fully implanted options.
- Surface Application:Non-contact electromagnetic coils enable therapy through clothing and dressings.
- Wearable:Garment-integrated designs support continuous ambulatory delivery during daily activities.
Transcutaneous systems dominate prescription volume; Wearable formats are gaining share fastest through adherence optimization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Device manufacturing concentrates in the United States and Western Europe, while procedural demand spreads across aging populations in developed healthcare systems. Production clusters align with established orthopedic technology corridors, yet reimbursement frameworks determine where clinical adoption accelerates fastest.
United States
The FDA's 510(k) clearance pathway and CMS procedural coding for bone growth stimulation create the world's most mature commercial environment. Centers for Medicare and Medicaid Services reimbursement frameworks reduce patient out-of-pocket burdens, accelerating ambulatory surgical center adoption. Minneapolis and Warsaw, Indiana host concentrated orthopedic device manufacturing operations serving domestic and export markets.
Germany
The Federal Joint Committee's reimbursement rate determinations shape bone growth stimulation access across Europe's largest healthcare market. EU Medical Device Regulation compliance requirements intensify post-market surveillance obligations for manufacturers serving German patients. Berlin and Munich medical technology clusters specialize in electromagnetic and ultrasonic stimulation system development.
Japan
PMDA regulatory frameworks govern bone stimulator market entry, with aging demographics driving procedural volumes for spinal fusion surgeries. METI industrial policy supports medical device innovation through targeted R&D subsidies and streamlined approval pathways. Tokyo and Osaka metropolitan areas concentrate orthopedic specialist practices prescribing non-invasive stimulation protocols.
United Kingdom
NICE technology appraisals influence National Health Service coverage determinations for bone growth stimulation following spinal surgery. MHRA post-Brexit regulatory autonomy maintains alignment with EU MDR standards while streamlining domestic market access. London and Manchester academic medical centers lead clinical validation studies for ultrasonic and bioelectric stimulation platforms.
Australia
TGA medical device registration requirements and private health insurance reimbursement patterns shape market development for bone stimulators. An aging population and high rates of spinal surgery create demand for post-operative fusion acceleration technologies. Sydney and Melbourne orthopedic networks increasingly prescribe home-based non-invasive stimulation for ambulatory surgical center discharges.
Spine Bone Stimulators Market Competitive Environment
Top-tier vendors anchor premium implantable and integrated technology segments, while mid-tier specialists compete on ambulatory non-invasive protocols and direct-to-patient distribution models. The vendor base stratifies across neurotechnology conglomerates, dedicated orthopedic device manufacturers, and emerging ultrasonic technology developers. Strategic archetypes include integrated spine therapy platform builders, rental-channel direct marketers, and academic medical center specialty suppliers. Dominant competitive moves center on neurotechnology convergence with spinal cord stimulation infrastructure and outcome-contingent payment structures tied to fusion confirmation imaging.
Within the neurotechnology-integrated tier, Medtronic plc and Stryker Corporation exemplify platform builders leveraging existing spinal intervention infrastructure. Among dedicated orthopedic specialists, Orthofix Medical Inc. and DJO LLC occupy positions emphasizing ambulatory care settings and alternative procurement channels. Zimmer Biomet Holdings, Inc. represents the diversified orthopedic conglomerate archetype with broad trauma and reconstruction portfolios extending into bone healing adjacencies.
| Leading Market Players |
|---|
| Medtronic plc |
| Orthofix Medical Inc. |
| Zimmer Biomet Holdings, Inc. |
| Bioventus |
| DJO LLC |
| Arthrex, Inc. |
| Stryker Corporation |
| Smith & Nephew plc |
| Ossatec Benelux BV |
| Others |
Value Chain & Pricing Dynamics
Biomedical engineering talent concentration in Minneapolis and Warsaw, Indiana compresses manufacturing labor-cost differentials into pricing-tier spreads that separate implantable surgical systems from ambulatory rental units.
Pricing Analysis
Margin tightening in non-invasive segments reflects algorithm-subscription bundling that shifts revenue from hardware margins to recurring clinical support fees. Three-tier pricing structure across premium implantable, standard non-invasive, and economy rental programs differentiates by surgical risk profile and reimbursement coding tier. Cost compression accelerates in home-care channels as direct-to-patient procurement bypasses hospital markup structures. Ambulatory surgery centers exhibit highest price sensitivity; academic medical centers performing complex revisions demonstrate lowest sensitivity due to outcome-contingent payment structures.
Supply Chain Analysis
Dual-sourcing requirements from United States hospital purchasing committees mandate qualified suppliers for both implantable power systems and external coil assemblies across domestic and German manufacturing bases. Component supply draws from precision electronics clusters in Taiwan, medical-grade polymer producers in Germany, and semiconductor fabricators in the United States. Single-source vulnerability concentrates in customized battery cells for implantable units. Distribution runs through orthopedic device distributors, GPO contracts, and direct-to-patient rental platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply constraints in FDA-cleared algorithm validation capacity prop pricing power for vendors with established 510(k) clearance histories and real-world fusion outcome databases.
For Market Incumbents: Acquire ambulatory surgery center network relationships to secure prescription volume against ultrasonic technology substitution. Defensive consolidation centers on backward integration into coil manufacturing and captive algorithm development teams. Capacity addition in Germany's Federal Joint Committee reimbursement zone offsets CMS pricing pressure in United States markets. For New Entrants and Emerging Players: Direct-to-patient digital channels unlock rural and suburban access bypassing hospital procurement gatekeepers. White-space targets include home-care wearable formats and ultrasonic platforms for multilevel fusion cases. Go-to-market angle emphasizes adherence-tracking software bundled with hardware rental. For Investors and Strategic Acquirers: Re-rating potential sits with neurotechnology-integrated platform builders given spinal cord stimulation convergence catalysts. Long-term viability framing favors vendors with recurring algorithm-subscription revenue and outcome-contingent contract structures. Acquisition target archetype: ambulatory-focused non-invasive specialists with CMS coding expertise. Signal to watch: FDA post-market surveillance obligation intensity for algorithm updates.| Strategic Initiative | Industry Significance |
|---|---|
| 510(k) Clearance Pathway Acceleration | FDA premarket notification expertise compresses time-to-revenue for algorithm-driven therapy updates. |
| Reimbursement Strategy Development | CMS procedural coding and Germany's Federal Joint Committee rate determinations shape addressable patient pools. |
| Software Companion Development | Algorithm subscription platforms shift vendor economics from hardware sales to recurring clinical support revenue. |
| Hospital System Partnership | Academic medical center alliances validate ultrasonic technology for complex multilevel fusion cases. |
| CE Marking Pathway | EU MDR compliance enables access to Europe's largest healthcare market through Berlin and Munich clusters. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with orthopedic surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers combined with FDA 510(k) databases, CMS reimbursement schedules, and EU MDR submission records. Bottom-up patient volume modeling and top-down vendor revenue triangulation validated segment-level outputs.
Product-type granularity modeled implantable versus non-invasive configurations; technology modality captured bioelectric, ultrasonic, electromagnetic, and low-frequency segments; end-user dimensions tracked hospitals, orthopedic clinics, rehabilitation centers, and home care channels; delivery mode distinguished transcutaneous, invasive, surface application, and wearable formats. CAGRs derived from procedural volume trends, reimbursement rate trajectories, and technology substitution curves across the projection horizon. Forecast inputs incorporated aging demographic surgical demand and ambulatory surgery center site-of-care migration.
The model holds under stable FDA 510(k) clearance timelines and CMS coding continuity; deviation in post-market surveillance obligation intensity or Federal Joint Committee reimbursement restriction would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Nurse Call Systems Market
Medical Devices
North America Non-Surgical Procedures Market
Medical Devices
Blood Thawing System Market
Medical Devices
South America Single-Use Medical Device Reprocessing Market
Medical Devices
Percutaneous Nephrostomy Catheters Market
Medical Devices
Catheter Introducer Sheaths Market
Medical Devices
Global Medical Drones Market
Medical Devices
Orthodontic Equipment Market
Medical Devices
Smart Vision Aids Market
Medical Devices
New Zealand Diabetes Devices Market
Medical Devices
US Surgical Microscopes Market
Medical Devices
Global Capillary Blood Collection Devices Market
Medical Devices
Global Angiography Catheters Market
Medical Devices
3D Printing for Surgical Procedures Market
Medical Devices
Intravaginal Device Market
Medical Devices
Steerable Needles Market