
 Global Chondrosarcoma Market | 2026-2036
Global Chondrosarcoma Market Size, Share, and Industry Trends Forecast 2026-2036
Global Chondrosarcoma Market Foresight
Consolidation among academic medical centers and specialized sarcoma centers is recalibrating procurement patterns for advanced chondrosarcoma therapies. F. Hoffmann-La Roche leverages its diagnostic-pharmaceutical integration to capture molecular testing-linked treatment decisions. Bristol-Myers Squibb Company anchors its position through sustained investment in immuno-oncology platforms applicable to rare sarcomas. Novartis AG differentiates via targeted therapy pipelines directed at specific genomic alterations in cartilaginous tumors.
Chondrosarcoma denotes a heterogeneous group of malignant bone tumors arising from cartilage-producing cells, characterized by histological grading from low-grade lesions with indolent courses to dedifferentiated variants requiring multimodal intervention; these tumors primarily affect the pelvis, femur, and shoulder girdle in adults aged 40 to 70. Surgery retains primacy as the curative modality for localized disease, though limb-salvage complexity sustains premium pricing for reconstructive implants and adjuvant delivery systems. Targeted therapy represents the fastest-expanding segment as FGFR inhibitors and IDH-mutant directed agents reshape treatment algorithms for unresectable or metastatic cases. Intravenous delivery dominates current revenue pools, yet oral formulations are gaining share as patient preference shifts toward ambulatory care models.
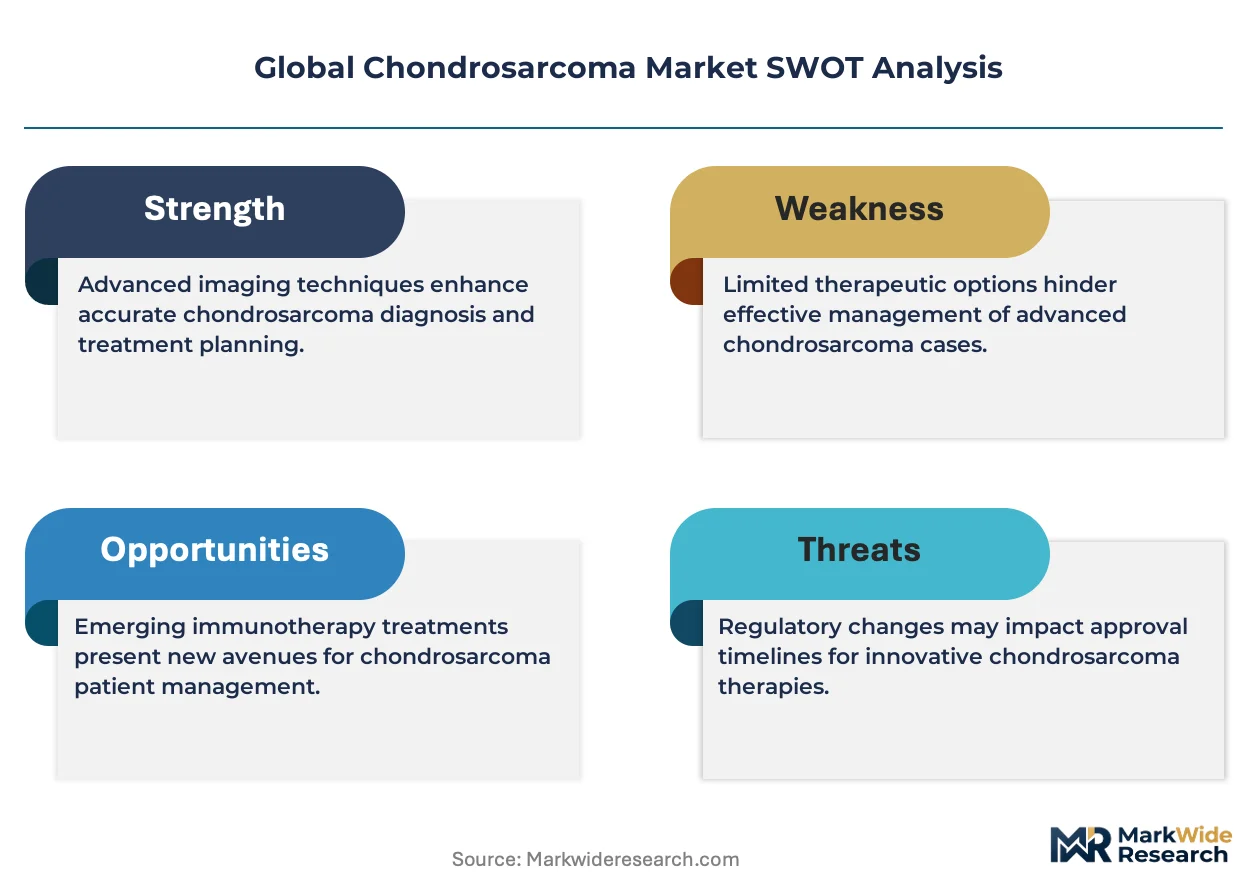
The FDA's orphan drug program and EMA's similar designation framework shape clinical trial incentives and extended exclusivity timelines for chondrosarcoma developers. REACH compliance and CE marking requirements under the EU MDR govern biomaterial safety standards for orthopedic implants used in limb-salvage procedures. Stakeholders must monitor biomarker-driven trial designs and regulatory harmonization across FDA, EMA, and PMDA jurisdictions to optimize development economics for this orphan indication.
Market Dynamics
Academic medical centers are consolidating molecular profiling capabilities for rare bone malignancies, reshaping how chondrosarcoma therapies are procured and administered across referral networks. This concentration of diagnostic expertise is creating new gatekeeper dynamics between testing infrastructure and treatment selection.
Growth Catalysts
- FDA Orphan Drug Designation:The pathway accelerates novel therapy development through extended exclusivity timelines and clinical trial incentives for developers targeting this rare indication.
- FGFR Inhibitor Advancement:Targeted agents directed at fibroblast growth factor receptor alterations are expanding addressable patient populations in unresectable disease.
- Sarcoma Center Density in Germany:Concentrated referral networks in Bavaria and Baden-Württemberg sustain premium procedural volumes for complex limb-salvage interventions.
Market Restraints
- Biomaterial Cost Volatility:Reconstructive implant inputs face price pressure from titanium and polyethylene supply fluctuations, compressing margins on limb-salvage procedures.
- Diagnostic Infrastructure Concentration:Molecular testing capacity clusters in United States academic centers and select Japanese institutions, limiting patient access in peripheral markets.
- EUMDR Compliance Burden:CE marking requirements under the Medical Device Regulation extend certification timelines for orthopedic implant manufacturers serving European sarcoma centers.
Strategic Opportunities
- Oral Formulation Expansion:Ambulatory care models in Japan favor tablet-based targeted therapies over intravenous delivery, opening formulation differentiation opportunities.
- IDH-Mutant Directed Pipelines:Isocitrate dehydrogenase inhibitor development targets a genomically defined subset with limited current therapeutic options.
- India Diagnostic Partnerships:Underpenetrated molecular profiling infrastructure in Mumbai and Delhi sarcoma units creates joint venture potential for testing platform deployment.
Industry Challenges
- Sarcoma Pathology Specialist Scarcity:Accurate chondrosarcoma grading requires subspecialized bone tumor expertise concentrated in fewer than fifty centers worldwide.
- Multi-Jurisdictional Trial Complexity:Harmonizing FDA, EMA, and PMDA requirements for biomarker-driven study designs extends development timelines and regulatory expenditure.
- Limb-Salvage Reconstruction Integration:Coordination between orthopedic oncologists and prosthetic engineers introduces surgical planning friction and outcome variability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Chondrosarcoma Market |
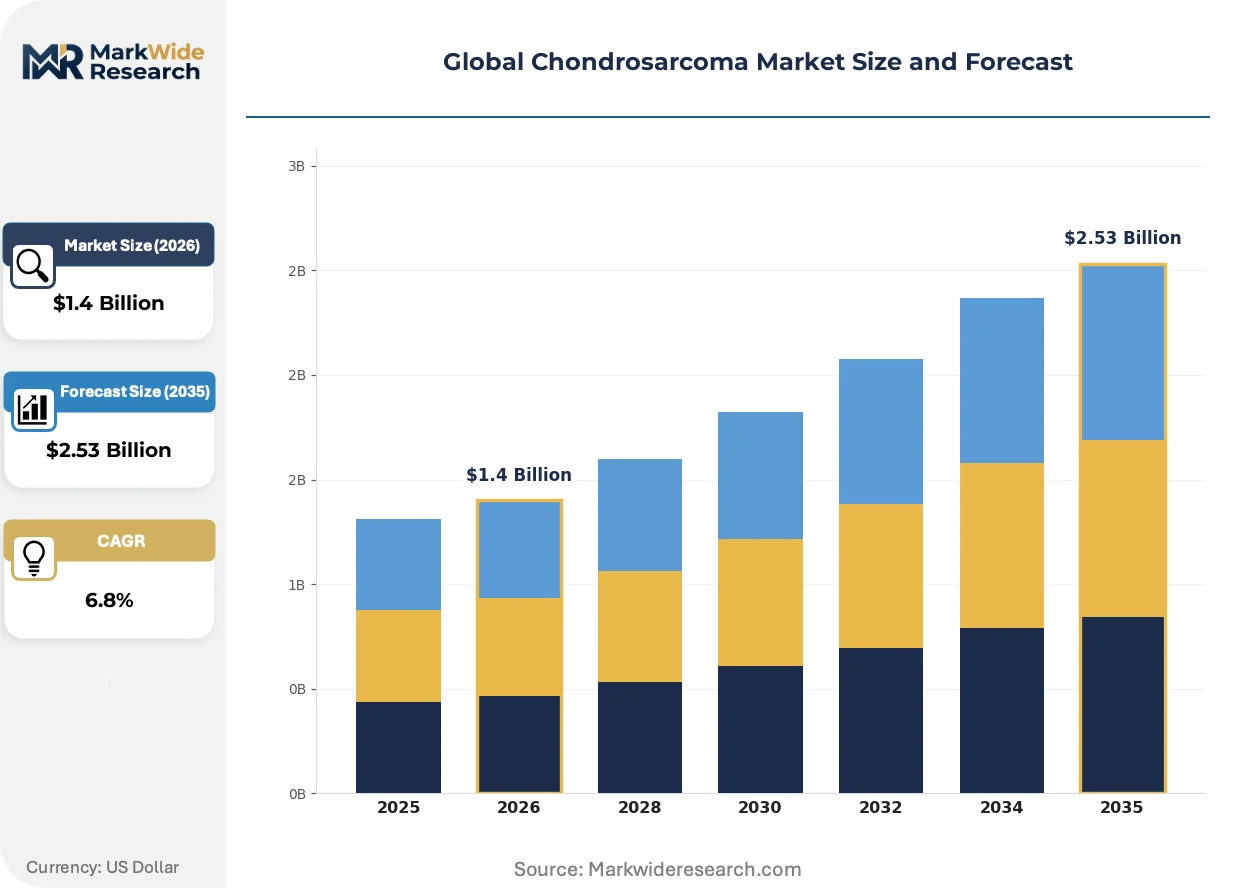
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgery, Radiotherapy, Chemotherapy, Targeted Therapy End User: Hospitals, Clinics, Research Laboratories, Homecare Settings Treatment Stage: Adjuvant, Neoadjuvant, Palliative, Ongoing Care Delivery Mode: Intravenous, Oral, Localized, Combination Therapy |
| Companies Covered | F. Hoffmann-La Roche, Eli Lilly and Company, Bristol-Myers Squibb Company, Takeda Pharmaceutical Company Limited, AbbVie Inc., Novartis AG, Pfizer Inc., Inhibrx, Amgen Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Chondrosarcoma Market Shifts & Advancements
Next-generation sequencing platforms are embedding into standard-of-care pathways for cartilaginous tumors, altering how treatment algorithms are constructed and reimbursed. This molecularization of sarcoma management is compressing the gap between diagnostic insight and therapeutic action.
Liquid biopsy technologies for circulating tumor DNA detection are integrating into monitoring protocols for metastatic chondrosarcoma patients. Academic centers in Boston and Heidelberg are adopting these platforms for longitudinal disease surveillance, enabling earlier intervention timing and reducing reliance on radiographic progression endpoints. The technology is integrating treatment decision workflows by providing real-time genomic evolution data that static tissue biopsies cannot capture.
REACH compliance requirements and the EU MDR framework are tightening biomaterial traceability standards for orthopedic implants used in limb-salvage surgery. Manufacturers serving European sarcoma centers must now maintain extended documentation chains for titanium alloy sourcing and polyethylene cross-linking processes. Implant suppliers with pre-existing quality management systems are absorbing these requirements faster than smaller competitors, consolidating procurement relationships with major German and French academic hospitals.
Patient preference for ambulatory administration is redirecting development investment toward oral kinase inhibitors and subcutaneous immunotherapy formulations. Japanese sarcoma centers report rising demand for home-based treatment models that minimize travel burden for elderly patient populations. United States specialty pharmacies are capturing dispensing volume previously held by hospital outpatient departments, fragmenting traditional revenue capture for academic medical center oncology practices.
Global Chondrosarcoma Market Segmentation
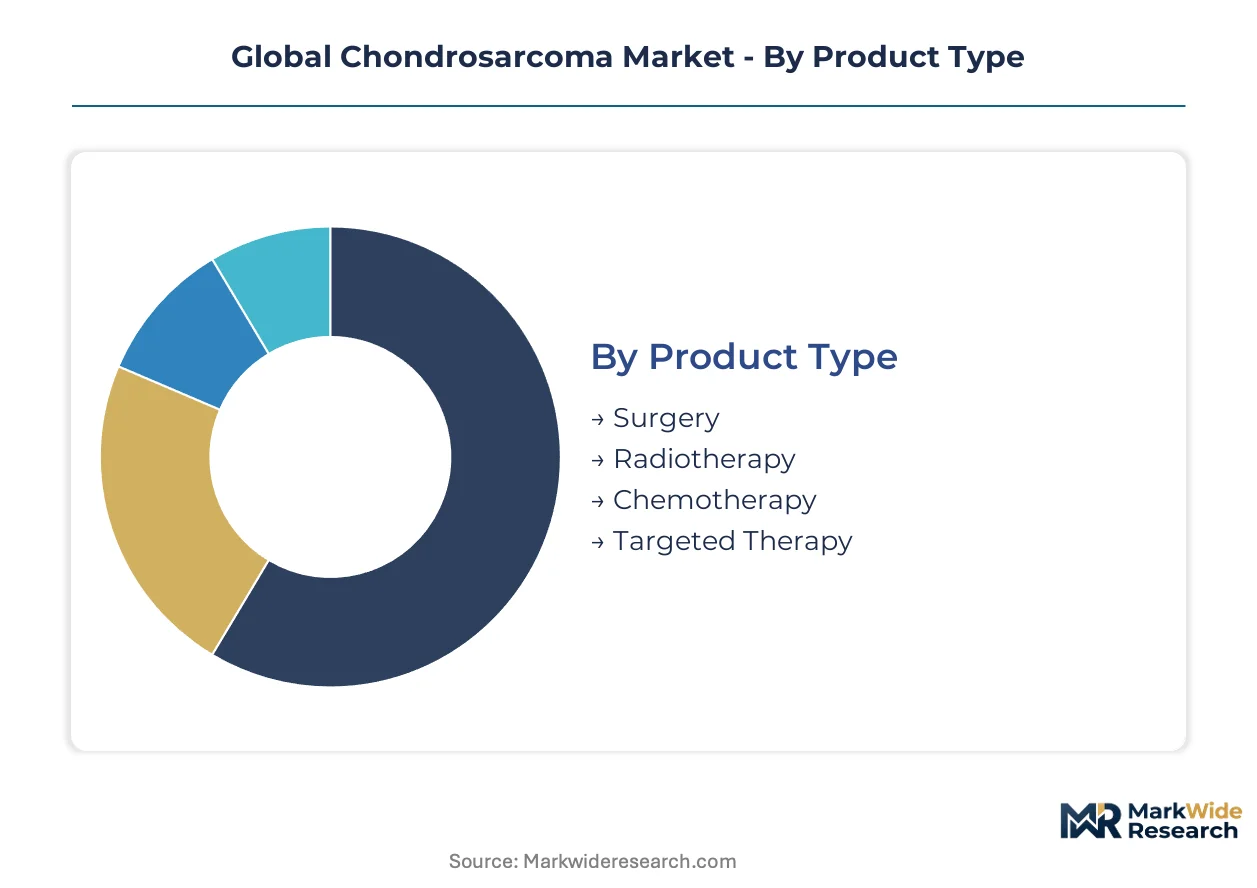
Chondrosarcoma treatment selection hinges on histological grade, anatomical location, and molecular profile. Segmentation reveals how procurement patterns split between curative surgical interventions and chronic systemic management for metastatic disease.
Product Type:
Surgical centers prioritize limb-salvage complexity; systemic therapy buyers prioritize genomic eligibility and reimbursement pathways.
- Surgery:Limb-salvage procedures with endoprosthetic reconstruction dominate curative protocols for localized pelvic and femoral lesions. German sarcoma centers in Bavaria sustain the highest procedural volumes for complex pelvic reconstructions requiring custom titanium implants.
- Targeted Therapy:FGFR inhibitors and IDH-mutant directed agents address unresectable or metastatic populations previously limited to cytotoxic options. Academic medical centers in Boston and Heidelberg are embedding molecular profiling to gate access to these therapies.
- Radiotherapy:Proton beam facilities in Japan and the United States treat skull base and spinal chondrosarcomas where surgical morbidity is prohibitive.
- Chemotherapy:Limited efficacy in conventional chondrosarcoma restricts use to dedifferentiated subtypes with sarcomatous transformation.
Surgery leads volumes today; targeted therapy is gaining share fastest.
End User:
Facility type determines reimbursement capture and care model intensity across the treatment continuum.
- Hospitals:Academic medical centers with integrated sarcoma programs control access to molecular testing and complex limb-salvage surgery. United States NCI-designated cancer centers concentrate the highest case volumes for multimodal management.
- Research Laboratories:Centralized molecular profiling hubs in Tokyo, Heidelberg, and Boston process next-generation sequencing for treatment-naive and progressive disease. These laboratories function as gatekeepers for clinical trial enrollment and targeted therapy authorization.
- Clinics:Community oncology practices in the United States refer nearly all chondrosarcoma cases to academic centers, limiting direct procurement.
- Homecare Settings:Japanese sarcoma networks are piloting oral kinase inhibitor dispensing through specialty pharmacies with remote monitoring protocols.
Hospitals anchor revenue capture; research laboratories are expanding their influence fastest.
Treatment Stage:
Timing relative to definitive surgery shapes therapeutic intent and duration economics.
- Adjuvant:Post-surgical systemic therapy for high-grade or margin-positive resections. United States sarcoma centers apply this selectively given limited evidence of survival benefit in conventional chondrosarcoma.
- Neoadjuvant:Pre-operative systemic therapy to enable limb-salvage in initially unresectable pelvic or shoulder girdle disease. German centers are exploring this approach for dedifferentiated variants.
- Palliative:Symptom-directed radiation and systemic therapy for metastatic or recurrent disease. Oral formulations are displacing intravenous delivery in this stage.
- Ongoing Care:Surveillance protocols with liquid biopsy monitoring are extending treatment relationships beyond traditional endpoints.
Adjuvant therapy dominates current utilization; neoadjuvant approaches are climbing the fastest.
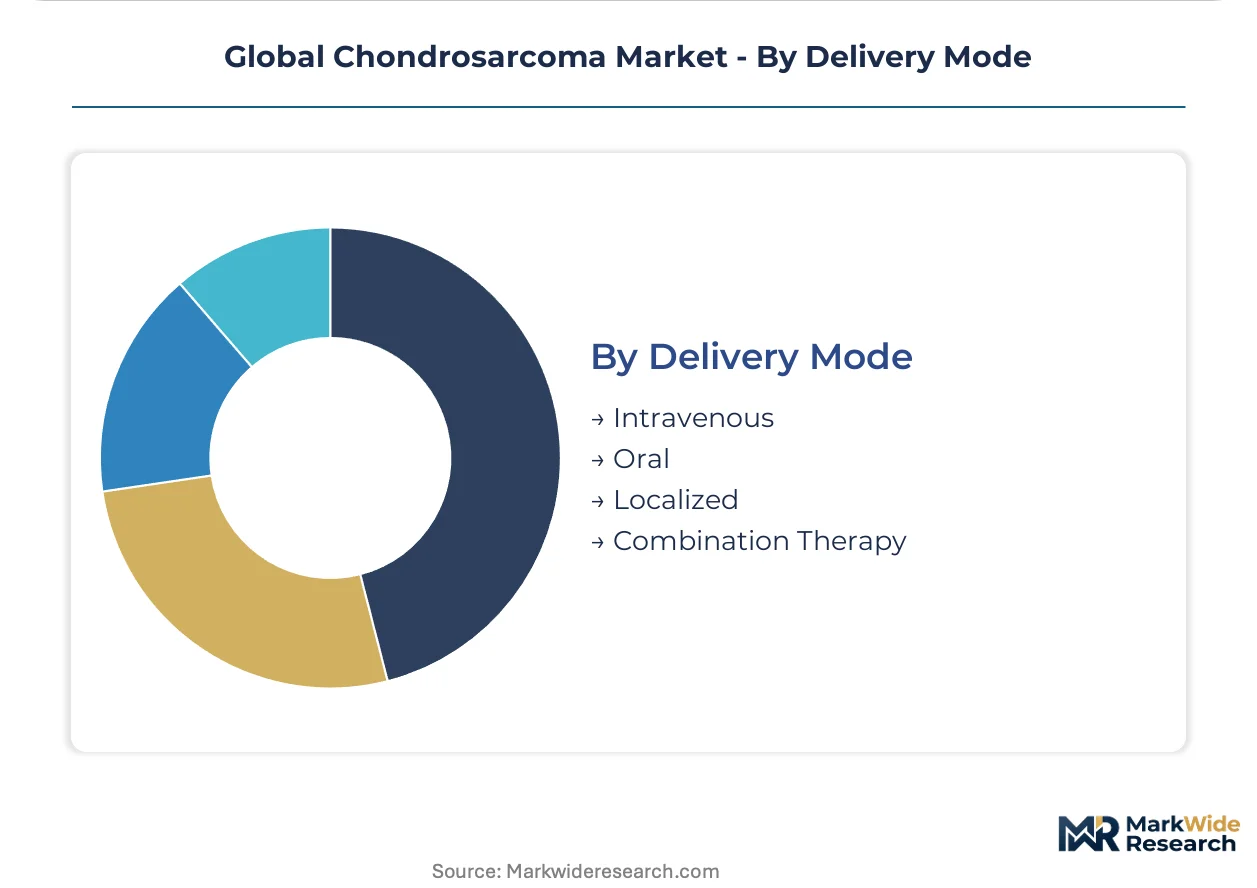
Delivery Mode:
Administration setting requirements differentiate hospital-dependent from ambulatory-capable options.
- Intravenous:Hospital outpatient department administration of cytotoxic and biologic agents. United States academic centers retain this revenue despite shift toward specialty pharmacy dispensing.
- Oral:Kinase inhibitors for FGFR-altered and IDH-mutant disease enable home-based administration. Japanese patient preference for minimizing travel burden accelerates formulation development toward this mode.
- Localized:Isolated limb perfusion and intra-arterial delivery for regional disease control in select European centers.
- Combination Therapy:Sequential or concurrent multimodal delivery requiring care coordination across surgical and medical oncology services.
Intravenous delivery retains the largest share; oral formulations are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sarcoma pathology specialists concentrate in fewer than fifty academic centers worldwide, anchoring regional treatment capacity and molecular testing access. These workforce clusters determine where complex limb-salvage surgery and targeted therapy enrollment concentrate.
United States
NCI-designated cancer centers in Boston, Houston, and New York anchor the highest case volumes for multimodal chondrosarcoma management. FDA orphan drug designation accelerates clinical trial incentives for developers targeting this rare indication. The Massachusetts General Hospital sarcoma program processes next-generation sequencing for treatment-naive and progressive disease.
Germany
Bavarian and Baden-Württemberg sarcoma networks sustain premium procedural volumes for complex pelvic reconstructions requiring custom titanium implants. EUMDR compliance extends CE marking timelines for orthopedic implant manufacturers serving European centers. The Heidelberg University Hospital integrates liquid biopsy platforms for longitudinal disease surveillance.
Japan
Tokyo and Osaka academic centers report rising demand for home-based treatment models that minimize travel burden for elderly patient populations. PMDA regulatory harmonization with FDA and EMA shapes biomarker-driven trial designs for rare sarcomas. The National Cancer Center Hospital East pilots oral kinase inhibitor dispensing through specialty pharmacies with remote monitoring protocols.
United Kingdom
Royal National Orthopaedic Hospital in Stanmore and Birmingham's Queen Elizabeth Hospital concentrate bone tumor expertise for complex limb-salvage referrals. NHS England specialized commissioning frameworks govern access to molecular testing and targeted therapy authorization. The Royal Marsden sarcoma unit embeds next-generation sequencing into standard-of-care pathways.
India
Mumbai and Delhi sarcoma units face underpenetrated molecular profiling infrastructure, creating joint venture potential for testing platform deployment. CDSCO regulatory pathways for orphan oncology indications remain less developed than FDA or EMA frameworks. Tata Memorial Centre in Mumbai processes the highest bone tumor surgical volumes in South Asia.
Global Chondrosarcoma Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the chondrosarcoma therapy landscape, creating tiered competitive dynamics. The market structure consolidates around large pharmaceutical developers with immuno-oncology and targeted therapy platforms, while mid-cap biotech firms concentrate on genomically defined subsets. Three archetypes dominate: integrated diagnostic-pharmaceutical conglomerates, immuno-oncology platform anchors, and targeted therapy specialists. M&A activity targets molecular profiling capabilities, while strategic partnerships concentrate on biomarker-driven trial enrollment.
Among Swiss-based pharmaceutical conglomerates, F. Hoffmann-La Roche exemplifies diagnostic-pharmaceutical integration that captures molecular testing-linked treatment decisions. Bristol-Myers Squibb Company anchors the immuno-oncology platform tier through sustained investment in platforms applicable to rare sarcomas. Novartis AG occupies a position within the targeted therapy specialist archetype, with pipelines directed at specific genomic alterations in cartilaginous tumors.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche |
| Eli Lilly and Company |
| Bristol-Myers Squibb Company |
| Takeda Pharmaceutical Company Limited |
| AbbVie Inc. |
| Novartis AG |
| Pfizer Inc. |
| Inhibrx |
| Amgen Inc. |
| Others |
Supply & Pricing Matrix
Orphan drug premium tiers versus commodity reconstructive hardware bifurcate procurement economics across academic medical centers, with FDA-designated targeted therapies commanding value-based pricing while titanium implant sourcing faces input cost compression from metal alloy volatility. This divergence concentrates margin capture with molecularly-enabled pharmaceutical developers while squeezing orthopedic device suppliers serving limb-salvage programs.
Pricing Analysis
Capacity additions in United States specialty pharmacy networks are reshaping price floors for oral kinase inhibitors, displacing hospital outpatient department markups previously embedded in intravenous administration. Three-tier pricing structure across premium FGFR inhibitors, standard cytotoxic regimens, and economy supportive care segments stratifies reimbursement pathways. Pricing pressure stems from Medicare Part D negotiation authority expanding into rare oncology indications. Community oncology practices exhibit highest price sensitivity; NCI-designated cancer centers prioritize clinical efficacy over acquisition cost.
Supply Chain Analysis
CE marking requirements under EU MDR and FDA 510(k) pathways gate supplier qualification for reconstructive implant manufacturers, extending certification timelines and consolidating procurement relationships. Titanium alloy feedstock concentrates in China, Russia, and South Africa; polyethylene cross-linking technology anchors in Germany and Japan. Supply chain risk centers on single-source vulnerability for custom pelvic implant fabrication. Distribution runs through integrated delivery networks at major academic medical centers, with limited spot purchasing for emergency limb-salvage cases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chondrosarcoma therapy procurement has shifted toward molecularly-qualified premium interventions, with academic medical centers prioritizing biomarker-linked treatment algorithms over empirical chemotherapy selection. This quality migration favors developers with diagnostic-pharmaceutical integration capabilities.
For Market Incumbents: Anchor market position through captive molecular testing infrastructure that gates access to proprietary targeted therapies. Defensive consolidation should prioritize backward integration into next-generation sequencing platform control, countering the threat of independent laboratory intermediaries capturing patient data and influencing treatment selection. Capacity addition in Japanese specialty pharmacy networks represents a critical lever for oral formulation volume capture. For New Entrants and Emerging Players: FDA orphan drug designation in the United States opens a window for accelerated market entry through extended exclusivity timelines and clinical trial incentives. White-space targets include IDH-mutant directed pipelines for genomically defined subsets with limited current therapeutic options, and diagnostic partnerships in Indian metropolitan sarcoma units where molecular profiling infrastructure remains underpenetrated. A go-to-market angle emphasizing ambulatory administration models aligns with Japanese patient preference for home-based care. For Investors and Strategic Acquirers: Consolidation pressure builds where molecular profiling capabilities concentrate in fewer than fifty academic centers worldwide, creating scarcity value for diagnostic platform assets. Long-term viability over the next decade hinges on biomarker-driven trial enrollment infrastructure and regulatory harmonization across FDA, EMA, and PMDA jurisdictions. Acquisition targets should display integrated diagnostic-therapeutic positioning or rare sarcoma specialization depth. The signal to watch is liquid biopsy platform adoption rates in Boston and Heidelberg academic centers as an indicator of surveillance protocol standardization.| Strategic Initiative | Industry Significance |
|---|---|
| Biomarker-Driven Trial Design | EMA and PMDA harmonization with FDA protocols accelerates rare sarcoma enrollment across Heidelberg, Boston, and Tokyo centers. |
| Oral Formulation Development | Japanese specialty pharmacy dispensing models favor tablet-based FGFR inhibitors over intravenous delivery infrastructure. |
| Diagnostic Platform Acquisition | Next-generation sequencing hubs in academic medical centers function as gatekeepers for targeted therapy authorization. |
| Orphan Drug Designation Pathway | FDA extended exclusivity timelines reward developers addressing genomic subsets with limited therapeutic alternatives. |
| Limb-Salvage Implant Innovation | Custom titanium pelvic reconstruction demand in Bavarian sarcoma networks sustains premium procedural economics. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with sarcoma program directors, orthopedic oncologists, formulary access specialists, and molecular pathology laboratory directors alongside secondary validation. FDA orphan drug designations, EMA submissions, ClinicalTrials.gov entries, and hospital procurement databases anchored supply-side intelligence. Patient advocacy organization publications and CMS Medicare claims patterns informed demand characterization. Bottom-up procedure volume modeling and top-down pharmaceutical revenue triangulation cross-validated market size estimates.
Historical reference periods anchored growth trajectory assumptions across the projection horizon, with segmentation modeling spanning treatment modality, histological grade, molecular eligibility, delivery mode, and regional regulatory cluster. CAGRs derived from procedure volume trends, pricing evolution in targeted therapy categories, and implant procurement patterns across major academic medical centers. Forecast inputs incorporated orphan drug approval velocity, biomarker penetration rates in NCI-designated cancer centers, and specialty pharmacy dispensing shift assumptions.
Revisions become necessary when regulatory harmonization timelines shift, biomarker-driven trial designs encounter enrollment barriers, or reconstructive implant input costs experience sustained volatility. Forecasts reflect documented assumptions regarding molecular testing infrastructure expansion, reimbursement pathway stability for oral oncology agents, and academic medical center consolidation patterns. A model refresh is warranted upon material change in FDA orphan drug incentive structures or EUMDR certification burden for orthopedic device manufacturers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Narcolepsy Market
Specialty Medicine
Global Pancreatic Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Food Allergy Treatment Market
Specialty Medicine
Global Chronic Idiopathic Constipation Market
Specialty Medicine
Uterine Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Bartter Syndrome Treatment Market
Specialty Medicine
Dupuytrens Disease Market
Specialty Medicine
Cerebral Palsy Market
Specialty Medicine
Myelofibrosis Market
Specialty Medicine
Bullous Pemphigoid Treatment Market
Specialty Medicine
Gingivostomatitis Market
Specialty Medicine
Retroperitoneal Fibrosis Treatment Market
Specialty Medicine
Facial Paralysis Market
Specialty Medicine
Cystinuria Treatment Market
Specialty Medicine
Pemphigus Vulgaris (PV) Treatment Market
Specialty Medicine
China Ulcerative Colitis Market