
 Global Retinal Biologics Market | 2026-2036
Global Retinal Biologics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Retinal Biologics Market Foresight
Gene-editing platforms and sustained-release delivery systems is reconfiguring how biologics are engineered for posterior-segment diseases. Regeneron Pharmaceuticals leverages its trap-antibody fusion architecture to anchor its position in neovascular retinal disorders. F. Hoffmann-La Roche Ltd. competes through dual-antibody strategies that extend its therapeutic reach across multiple retinal indications. Novartis differentiates via geographic manufacturing scale that controls supply security across North American and European distribution networks.
Retinal biologics are protein-based therapeutics, typically monoclonal antibodies or recombinant fusion proteins formulated for intraocular delivery, designed to modulate angiogenic, inflammatory, or neuroprotective pathways within the retina and choroid. Anti-VEGF agents dominate the product-type landscape as the established standard for macular edema and neovascular age-related macular degeneration, while sustained-release implants represent the fastest-expanding delivery-mode segment by addressing the compliance burden of frequent intravitreal injections. Specialty hospitals capture the deepest margin pools among end-user channels due to their capacity for same-day surgical scheduling and integrated diagnostic-imaging workflows.
The FDA's breakthrough therapy designation and the EMA's priority medicines scheme compress clinical development timelines, reshaping how manufacturers allocate regulatory resources across Phase III trial designs. ISO 13485 quality management standards and the EU Medical Device Regulation govern the device-drug combination products increasingly paired with biologic payloads. Stakeholders must monitor how real-world evidence requirements from payers in Germany, Japan, and the United States reshape post-market commitment obligations and pricing negotiations.
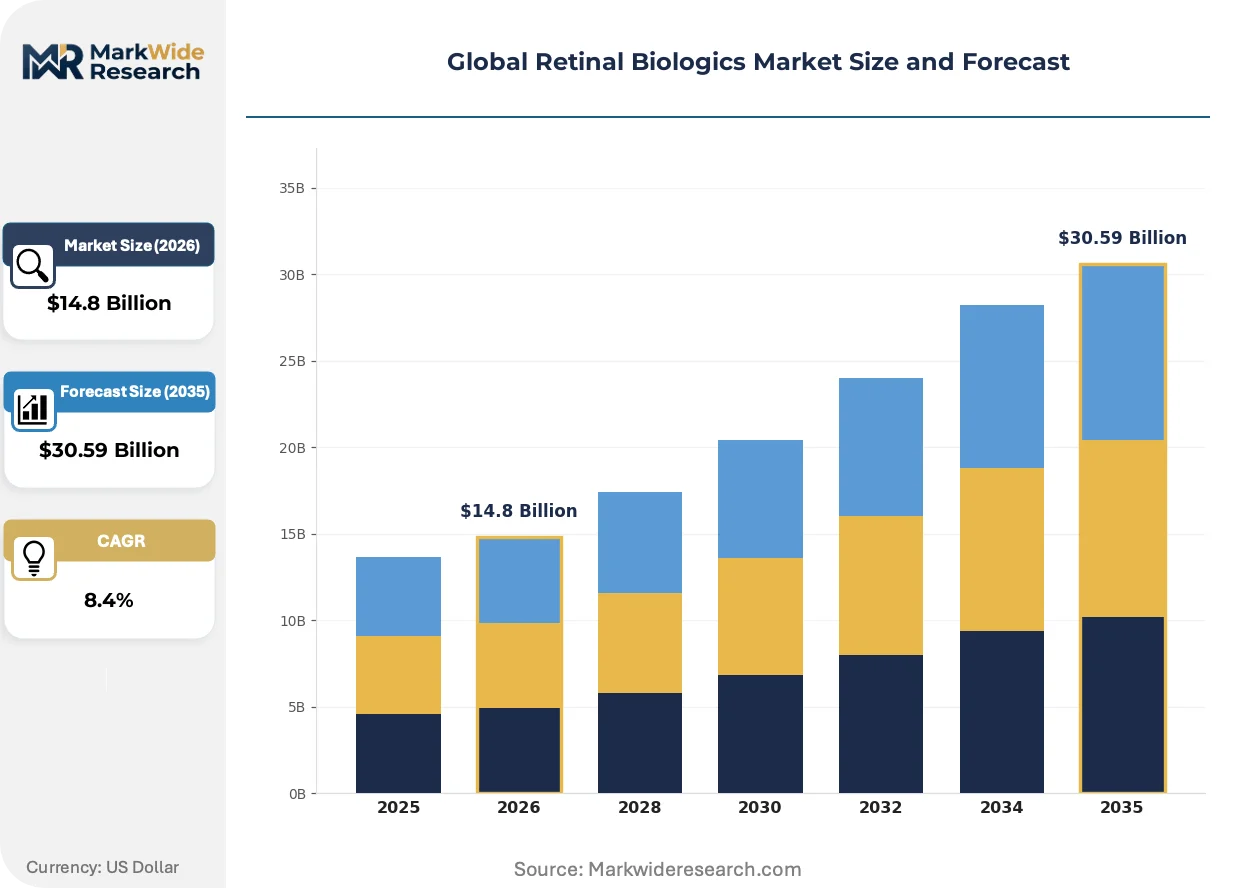
Market Dynamics
Gene-editing platforms and sustained-release delivery systems are compressing treatment paradigms for posterior-segment diseases, forcing manufacturers to reallocate R&D budgets toward device-drug combination products that reduce injection frequency burdens.
Growth Catalysts
- Medicare Part B reimbursement frameworks:The United States maintains stable payment rates for intravitreal injection procedures performed in outpatient settings. This policy continuity incentivizes specialty hospitals to expand ophthalmic biologics programs.
- Anti-VEGF agent refinements:Protein engineering advances extend dosing intervals for macular edema therapies. Patient compliance improves measurably when treatment burdens drop from monthly to quarterly administration cycles.
- Specialty hospital infrastructure:Same-day surgical scheduling capacity and integrated diagnostic-imaging workflows concentrate margin capture. These facilities now handle the majority of complex retinal procedures in major metropolitan clusters.
Market Restraints
- Biologics manufacturing concentration:Active pharmaceutical ingredient production clusters in Switzerland and Ireland create supply security vulnerabilities. Single-source dependencies for fusion protein cell lines amplify disruption risks.
- Cold chain complexity:Temperature excursions during distribution degrade protein stability. The EU Medical Device Regulation imposes additional traceability burdens on combination product shipments.
- Small-molecule VEGF inhibitor development:Oral and topical alternatives to intravitreal injection threaten biologic positioning. Ophthalmic pharmaceutical pipelines contain multiple non-biological angiogenesis modulators.
Strategic Opportunities
- Japan's aging demographic profile:The country exhibits the highest per-capita incidence of neovascular age-related macular degeneration among major markets. PMDA priority review vouchers accelerate market entry timelines for novel therapies.
- Sustained-release implant platforms:Biodegradable reservoirs and refillable devices address the compliance gap. These delivery modes enable multi-year dosing schedules that transform patient management economics.
- Real-world evidence mandates:German payers now require post-market outcome data for continued reimbursement listing. Manufacturers that build prospective registry infrastructure gain negotiating leverage.
Industry Challenges
- Vitreoretinal surgeon training pipelines:Fellowship program capacity constraints limit the pool of qualified injection specialists. Academic medical centers struggle to expand training slots proportionally to patient volume growth.
- ISO 13485 quality system integration:Device-drug combination products require simultaneous compliance with pharmaceutical GMP and medical device quality standards. Dual-framework audits extend certification timelines.
- Patent estate fragmentation:Multiple overlapping intellectual property claims surround trap-antibody fusion architectures. Freedom-to-operate analyses consume substantial legal resources prior to Phase III initiation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Retinal Biologics Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $30.59 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anti-VEGF Agents, Corticosteroids, Immunomodulators, Growth Factors, Neuroprotective Agents Therapy Area: Age-Related Macular Degeneration, Diabetic Retinopathy, Retinal Vein Occlusion, Uveitis, Stargardt Disease End User: Ophthalmic Clinics, Specialty Hospitals, Research Institutes, Ambulatory Surgical Centers, Diagnostic Centers Delivery Mode: Intravitreal Injection, Subretinal Injection, Topical Application, Periocular Injection, Sustained Release Implants |
| Companies Covered | Regeneron Pharmaceuticals, Inc., F. Hoffmann-La Roche Ltd., Novartis AG, Bayer AG, AbbVie Inc., Amgen Inc., Santen Pharmaceutical Co., Ltd., Bausch Health Companies Inc., Spark Therapeutics, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Retinal Biologics Market Shifts & Advancements
Retinal biologics development is converging around three vectors: molecular engineering that extends therapeutic durability, regulatory frameworks that compress approval timelines, and care delivery models that shift administration sites toward lower-cost settings.
CRISPR-based gene-editing platforms is hybridizing with adeno-associated viral delivery vectors to enable single-administration corrections for inherited retinal dystrophies. Academic research centers in the United States and United Kingdom are advancing first-in-human trials for Leber congenital amaurosis variants. This convergence is collapsing the distinction between chronic therapy and curative intervention in ophthalmic drug development.
The FDA's breakthrough therapy designation creates accelerated approval pathways for therapies demonstrating substantial improvement over existing standards. Manufacturers receive rolling review privileges and intensive agency guidance that compress traditional Phase III timelines. Retinal indication programs now routinely target priority review vouchers to maximize commercial exclusivity periods.
Integrated practice units are consolidating diagnostic, therapeutic, and monitoring functions under single organizational structures. Ophthalmology networks in Germany and the Netherlands are unbundling after-sales follow-up from initial procedure billing. This reconfiguration concentrates patient data assets that support outcome-based contracting with statutory health insurers.
Global Retinal Biologics Market Segmentation
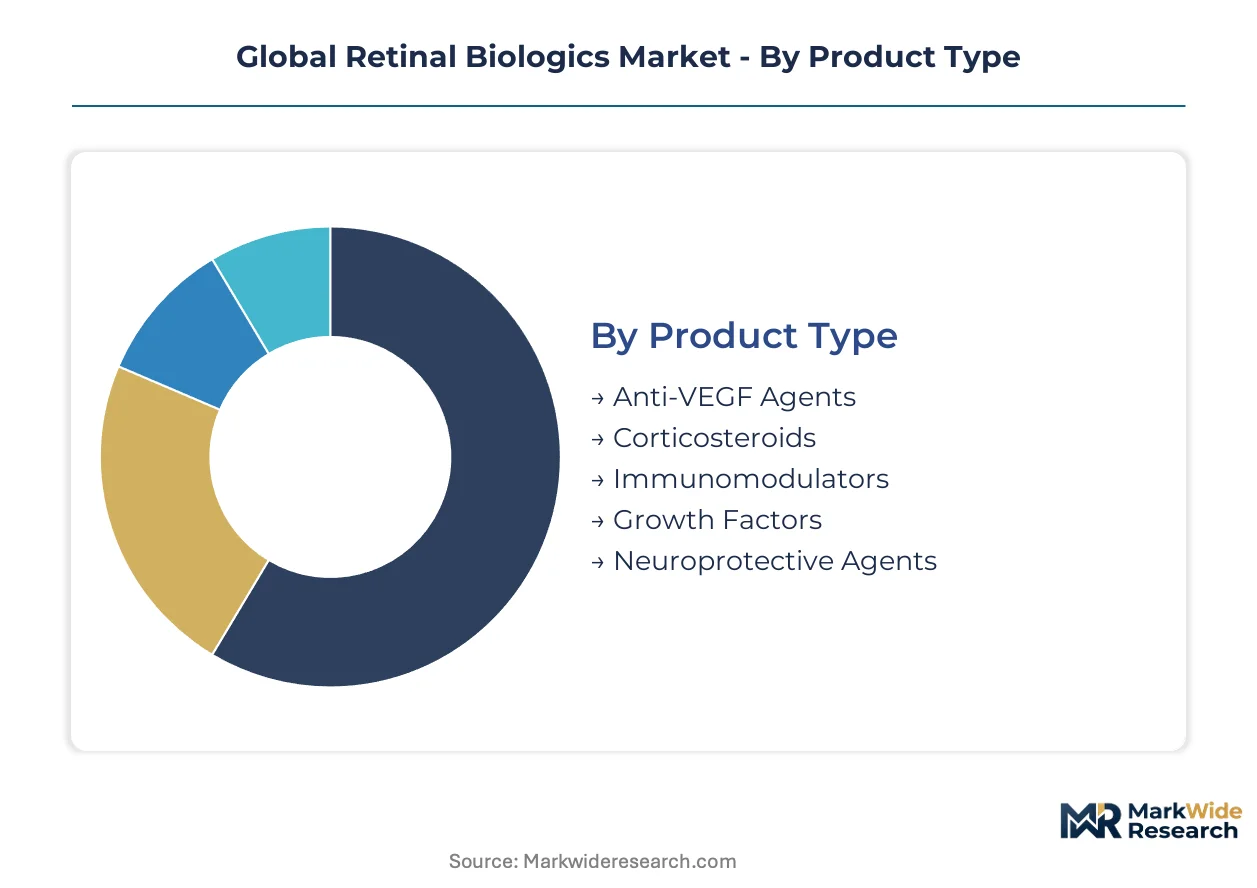
Retinal biologics segmentation reflects divergent clinical workflows across chronic maintenance therapies versus curative interventions. Product engineering decisions, reimbursement site preferences, and administration complexity create distinct commercial pockets within each dimension.
Product Type:
Protein engineering architectures span trap-antibody fusions, recombinant cytokines, and monoclonal antibodies targeting distinct pathological pathways.
- Anti-VEGF Agents:Trap-antibody fusion proteins and humanized monoclonals that sequester vascular endothelial growth factor isoforms. Demand concentrates in United States Medicare Part B reimbursement channels where intravitreal injection frequency drives practice economics. Dosing interval extension remains the primary competitive battlefield.
- Corticosteroids:Sustained-release intravitreal implants and periocular formulations targeting inflammatory macular edema. Germany's statutory health insurers now require real-world outcome registries for continued listing, reshaping post-market evidence commitments.
- Immunomodulators:Interleukin inhibitors and complement pathway modulators for non-infectious uveitis.
- Growth Factors:Recombinant proteins promoting retinal pigment epithelium regeneration.
- Neuroprotective Agents:Ciliary neurotrophic factor variants and anti-apoptotic peptides for inherited retinal dystrophies.
The dominant share belongs to Anti-VEGF Agents, while Neuroprotective Agents are closing the gap fastest through gene therapy convergence.
Therapy Area:
Indication selection determines trial design complexity, regulatory pathway eligibility, and pricing negotiation leverage.
- Age-Related Macular Degeneration:Neovascular and atrophic subtypes representing the largest addressable patient populations. Japan's PMDA priority review vouchers accelerate market entry for novel therapies targeting this indication. Wet AMD anti-VEGF maintenance regimens generate the highest per-patient lifetime value.
- Diabetic Retinopathy:Proliferative and diabetic macular edema variants with expanding screening programs in India and China. United States preventive care mandates now cover annual retinal imaging for diabetic populations.
- Retinal Vein Occlusion:Branch and central subtypes requiring urgent anti-VEGF intervention.
- Uveitis:Intermediate, posterior, and panuveitis variants with corticosteroid-sparing biologic demand.
- Stargardt Disease:Inherited macular dystrophy with emerging gene therapy pipelines.
Age-Related Macular Degeneration commands the deepest revenue pool, though Stargardt Disease is expanding most quickly via CRISPR platform investments.
End User:
Site-of-care economics and surgical scheduling capacity segment margin capture across delivery settings.
- Specialty Hospitals:Integrated diagnostic-imaging workflows and same-day surgical scheduling concentrate complex retinal procedure volumes. These facilities capture premium reimbursement rates in United States metropolitan clusters where vitreoretinal surgeon density is highest.
- Ophthalmic Clinics:High-frequency injection maintenance programs with streamlined patient throughput. Germany's integrated practice unit models are unbundling follow-up monitoring from initial procedure billing.
- Ambulatory Surgical Centers:Lower-cost settings gaining share for established anti-VEGF maintenance.
- Research Institutes:Gene therapy first-in-human trials and natural history study enrollment.
- Diagnostic Centers:Imaging referral hubs feeding treatment decisions to intervention sites.
Specialty Hospitals retain the highest per-procedure margins, while Ambulatory Surgical Centers are gaining share fastest through site-of-care migration.
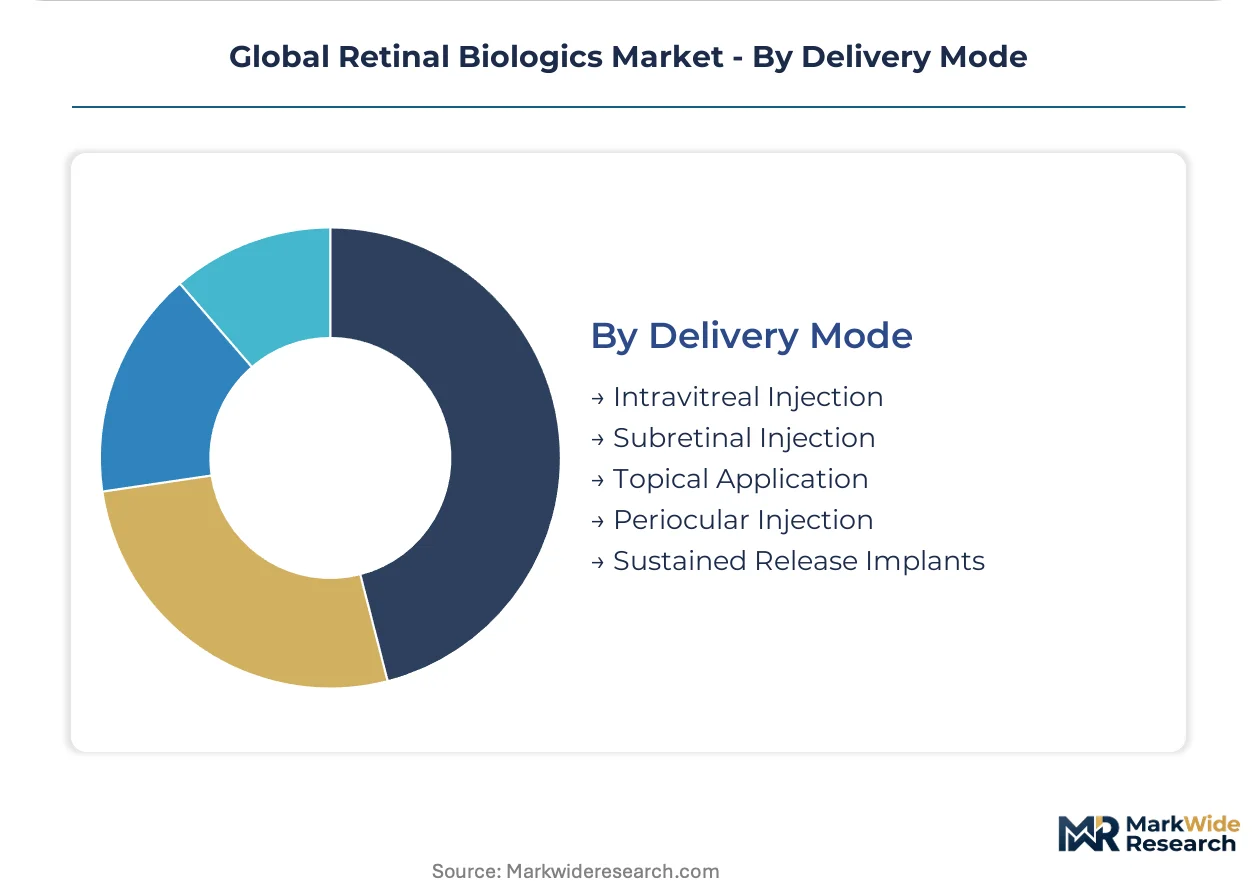
Delivery Mode:
Administration route selection shapes patient compliance, manufacturing complexity, and combination product regulatory burden.
- Intravitreal Injection:Trans-scleral needle delivery of anti-VEGF and corticosteroid formulations. United States specialty hospitals perform the majority of these procedures, with Medicare reimbursement stability supporting program expansion.
- Sustained Release Implants:Biodegradable reservoirs and refillable devices reducing injection frequency from monthly to multi-year intervals. EU Medical Device Regulation imposes traceability requirements on these combination products.
- Subretinal Injection:Surgical delivery for gene therapy vectors under general anesthesia.
- Periocular Injection:Less invasive corticosteroid administration with lower complication risk.
- Topical Application:Emerging formulations for anterior segment penetration challenges.
Intravitreal Injection maintains procedure volume dominance, though Sustained Release Implants show the steepest expansion trajectory as manufacturers address compliance burdens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics for retinal biologics reveal concentrated manufacturing in Switzerland and Ireland against dominant consumption in the United States and Japan. Active pharmaceutical ingredient production clusters in Basel and Dublin supply fusion protein cell lines to global markets. Cold chain logistics networks radiate from these hubs toward specialty hospital clusters in major metropolitan areas.
United States
Medicare Part B reimbursement frameworks stabilize payment rates for intravitreal injection procedures performed in outpatient settings. The FDA's breakthrough therapy designation compresses Phase III timelines for novel retinal treatments. Specialty hospitals in metropolitan clusters concentrate complex retinal procedure volumes through integrated diagnostic-imaging workflows.
Germany
Statutory health insurers now mandate real-world outcome registries for continued reimbursement listing of corticosteroid implants. The EU Medical Device Regulation imposes additional traceability burdens on combination product shipments. Integrated practice units in ophthalmology networks unbundle follow-up monitoring from initial procedure billing.
Japan
The country exhibits the highest per-capita incidence of neovascular age-related macular degeneration among major markets. PMDA priority review vouchers accelerate market entry timelines for novel therapies targeting retinal indications. Tokyo and Osaka metropolitan areas concentrate vitreoretinal surgeon density and same-day surgical scheduling capacity.
Switzerland
Active pharmaceutical ingredient production for trap-antibody fusion architectures clusters in Basel. Swissmedic maintains stringent quality oversight for biologics manufacturing facilities. The Rhine corridor serves as a distribution hub for cold chain shipments to European specialty hospitals.
India
Expanding diabetic retinopathy screening programs drive demand for anti-VEGF maintenance therapies. CDSCO regulatory pathways are streamlining approval processes for imported biologic reference products. Mumbai and Bangalore ophthalmic centers are building fellowship training capacity for vitreoretinal specialists.
Global Retinal Biologics Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic archetypes: large-cap pharmaceutical conglomerates with trap-antibody fusion platforms, mid-tier biotech specialists in gene therapy vectors, and diversified health care companies with ophthalmic device-drug combination portfolios. Competitive positioning hinges on dosing interval extension capabilities, manufacturing scale for cold chain distribution, and regulatory navigation of accelerated approval pathways. Dominant competitive moves include strategic partnerships for sustained-release implant technology and geographic expansion into Japan's aging demographic markets.
Within the large-cap pharmaceutical tier, Regeneron Pharmaceuticals, Inc. and F. Hoffmann-La Roche Ltd. occupy anchor positions through distinct antibody engineering architectures. Novartis AG exemplifies the diversified conglomerate archetype with manufacturing scale controlling supply security across North American and European distribution networks. These three entities collectively represent the competitive core against which mid-tier specialists and emerging gene therapy platforms define their market entry strategies.
| Leading Market Players |
|---|
| Regeneron Pharmaceuticals, Inc. |
| F. Hoffmann-La Roche Ltd. |
| Novartis AG |
| Bayer AG |
| AbbVie Inc. |
| Amgen Inc. |
| Santen Pharmaceutical Co., Ltd. |
| Bausch Health Companies Inc. |
| Spark Therapeutics, Inc. |
| Others |
Supply & Pricing Matrix
Rhine corridor cold chain logistics anchor cost dynamics across European distribution networks, where Basel and Dublin manufacturing clusters translate temperature-controlled freight premiums into downstream price stratification between originator biologics and follow-on alternatives.
Pricing Analysis
Next-generation sustained-release implants command substantial premiums over monthly intravitreal injection regimens, while prior-generation anti-VEGF agents face erosion from biosimilar entry. Three-tier pricing structure across premium, standard, and economy levels reflects dosing interval differentiation, ISO 13485 certification tiers, and bundled diagnostic-imaging service packages. Price erosion runs through the standard tier as German statutory payers tighten real-world evidence requirements. Ambulatory surgical centers exhibit highest price sensitivity due to Medicare site-of-care differentials, while specialty hospitals absorb premium positioning through integrated workflow efficiencies.
Supply Chain Analysis
Extended payment terms from Swiss and Irish API manufacturers to global distributors compress working capital cycles across downstream channels. Active pharmaceutical ingredient production clusters in Switzerland, Ireland, and the United States, with fusion protein cell lines drawing from Chinese hamster ovary bioreactor inputs and single-use bioprocessing consumables. Single-source dependencies for trap-antibody fusion architectures create vulnerability to Swissmedic regulatory inspection backlogs. Distribution runs through certified cold chain partners to specialty hospital clusters in metropolitan areas.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Retinal biologics incumbents face substitution pressure from oral small-molecule VEGF inhibitors and gene-editing curative platforms that threaten chronic maintenance paradigms.
For Market Incumbents: Harden patent estates around trap-antibody fusion architectures through freedom-to-operate litigation reserves and secondary formulation claims. Deepen backward integration into cell line development capabilities to reduce single-source API dependencies. Secure priority review voucher strategies to extend commercial exclusivity windows against biosimilar erosion.
For New Entrants and Emerging Players: India's expanding diabetic retinopathy screening infrastructure offers the most penetrable geography for anti-VEGF maintenance therapies, where CDSCO streamlined pathways reduce regulatory lag. Target sustained-release implant partnerships with established device manufacturers to bypass ISO 13485 certification barriers. Build prospective outcome registries to satisfy German payer real-world evidence mandates and secure reimbursement listing.
For Investors and Strategic Acquirers: Gene therapy vector specialists with adeno-associated viral delivery platforms and Leber congenital amaurosis clinical data packages represent priority acquisition archetypes. Long-term viability hinges on curative versus chronic therapy positioning over the coming decade. Monitor PMDA priority review voucher issuance rates as inflection indicator for Japan market entry timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | CRISPR-based gene-editing platforms accelerate inherited retinal dystrophy correction timelines through FDA breakthrough therapy pathways. |
| Regulatory Approval Pathway | PMDA priority review vouchers compress Japanese market entry for novel neovascular AMD therapies targeting aging demographics. |
| Manufacturing Scale-Up | Basel and Dublin API capacity expansion secures cold chain supply security across North American and European specialty hospital networks. |
| Pipeline Diversification | Sustained-release implant partnerships address compliance burdens and transform patient management economics for chronic retinal conditions. |
| Reimbursement Strategy | German statutory health insurer registry commitments reshape post-market evidence obligations and pricing negotiation leverage. |
Research Methodology
Initial hypotheses were tested against primary input from drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers and refined through secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and CMS Medicare reimbursement databases. Bottom-up patient volume modeling and top-down pharmaceutical revenue triangulation converged on segment-level estimates.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation modeling across product type, therapy area, end user channel, and delivery mode dimensions. CAGRs derived from historic growth trajectory analysis and forward-looking reimbursement policy assumptions incorporated anti-VEGF dosing interval extension trends and gene therapy regulatory pathway acceleration.
Practitioners should monitor biosimilar approval timelines, small-molecule VEGF inhibitor clinical readouts, and gene therapy durability data for early signals of paradigm shift. Forecasts reflect documented assumptions; macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Neurosyphilis Market
Specialty Medicine
Diverticulitis Disease Market
Specialty Medicine
Global Targeted Cancer Therapy Market
Specialty Medicine
Bacteriophages Therapy Market
Specialty Medicine
Small Molecule Targeted Cancer Therapy Market
Specialty Medicine
Global Laryngeal Cancer Therapeutics Market
Specialty Medicine
Nonerosive Reflux Disease Treatment Market
Specialty Medicine
Fibrodysplasia Ossificans Progressiva (FOP) Treatment Market
Specialty Medicine
Wilms Tumor Treatment Market
Specialty Medicine
Primary Biliary Cholangitis (PBC) Treatment Market
Specialty Medicine
HTLV-1 Associated Myelopathy (HAM) Market
Specialty Medicine
Inflammatory Diseases Market
Specialty Medicine
Bartter Syndrome Treatment Market
Specialty Medicine
Latin America Liver Cancer Treatment Market
Specialty Medicine
Global Major Depressive Disorder (MDD) Market
Specialty Medicine
Gastrointestinal Stromal Tumor (GIST) Therapeutics Market