
 Global Fungal Keratitis Treatment Market | 2026-2036
Global Fungal Keratitis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Fungal Keratitis Treatment Market Foresight
Indian generic API manufacturing is hardening as the dominant supply base for antifungal ophthalmic actives. Merck & Co. Inc. leverages its legacy fermentation expertise to sustain natamycin output at scale. Pfizer Inc. competes through vertically integrated azole chemistry, while Glenmark Pharmaceuticals anchors its position in emerging-market topical formulations.
Fungal keratitis treatment encompasses pharmacologic interventions targeting corneal infection by filamentous fungi and yeasts, typically requiring topical polyenes or triazoles at concentrations between 1% and 5% to achieve stromal penetration. Natamycin remains the first-line polyene for Fusarium and Aspergillus species, though voriconazole formulations gain ground against refractory Candida and Scedosporium infections. Administration route segmentation reveals topical drops as the mature volume base, while intrastromal injection protocols represent the fastest-growing margin pool among refractory cases. Healthcare setting dynamics shift toward eye hospitals in India and Southeast Asia, where surgical debridement accompanies medical therapy.
FDA ophthalmic compounding guidance, EMA's MDR requirements for intraocular devices, and India's CDSCO stability mandates collectively elevate manufacturing compliance costs. WHO inclusion of fungal keratitis in neglected tropical disease frameworks redirects public procurement toward subsidized natamycin access. Stakeholders must monitor regulatory divergence between US preservative-free mandates and emerging-market cost-driven multi-dose acceptance.
Market Dynamics
Indian API manufacturing concentration for natamycin and azole actives is compressing formulation economics while FDA preservative-free ophthalmic mandates fragment supply readiness across geographies.
Growth Catalysts
- WHO Neglected Tropical Disease Framework:WHO inclusion of fungal keratitis redirects public procurement budgets toward subsidized natamycin access in endemic tropical zones.
- Agricultural Worker Exposure Patterns:Rising trauma-related filamentous infections among rice and sugarcane laborers in Tamil Nadu and Uttar Pradesh drives sustained demand for topical polyene therapy.
- Intrastromal Injection Protocols:Refractory case management is electrifying margin pools as corneal specialists adopt microinjection techniques for deep stromal penetration.
Market Restraints
- Preservative-Free Manufacturing Costs:FDA Unit-Dose Container guidance elevates sterile fill-finish capex requirements for multi-dose alternative producers.
- API Supply Geographic Concentration:Hyderabad and Ahmedabad clusters control over 70% of generic azole active pharmaceutical ingredient output, creating single-source vulnerability.
- Stromal Penetration Ceiling:Current topical formulations cannot reliably achieve therapeutic concentrations beyond anterior stromal layers in dense fungal infiltrates.
Strategic Opportunities
- Sub-Saharan Africa Expansion:Kenya and Nigeria eye hospitals lack consistent natamycin supply chains, creating first-mover distribution partnerships for Indian generic manufacturers.
- EMA MDR Device Convergence:Intracorneal ring segments and therapeutic contact lenses with embedded antifungal elution qualify for accelerated review pathways under 2024 guidance updates.
- Teleophthalmology Triage Networks:Rural India is electrifying diagnostic reach through smartphone-based corneal imaging linked to urban cornea specialist consultation platforms.
Industry Challenges
- Sterile Compounding Workforce Scarcity:US 503B outsourcing facilities face critical shortages of aseptic processing technicians qualified under revised FDA guidance.
- CDSCO Stability Timeline Compression:India's tightened 36-month real-time stability requirements for ophthalmic suspensions extend product registration cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Fungal Keratitis Treatment Market |
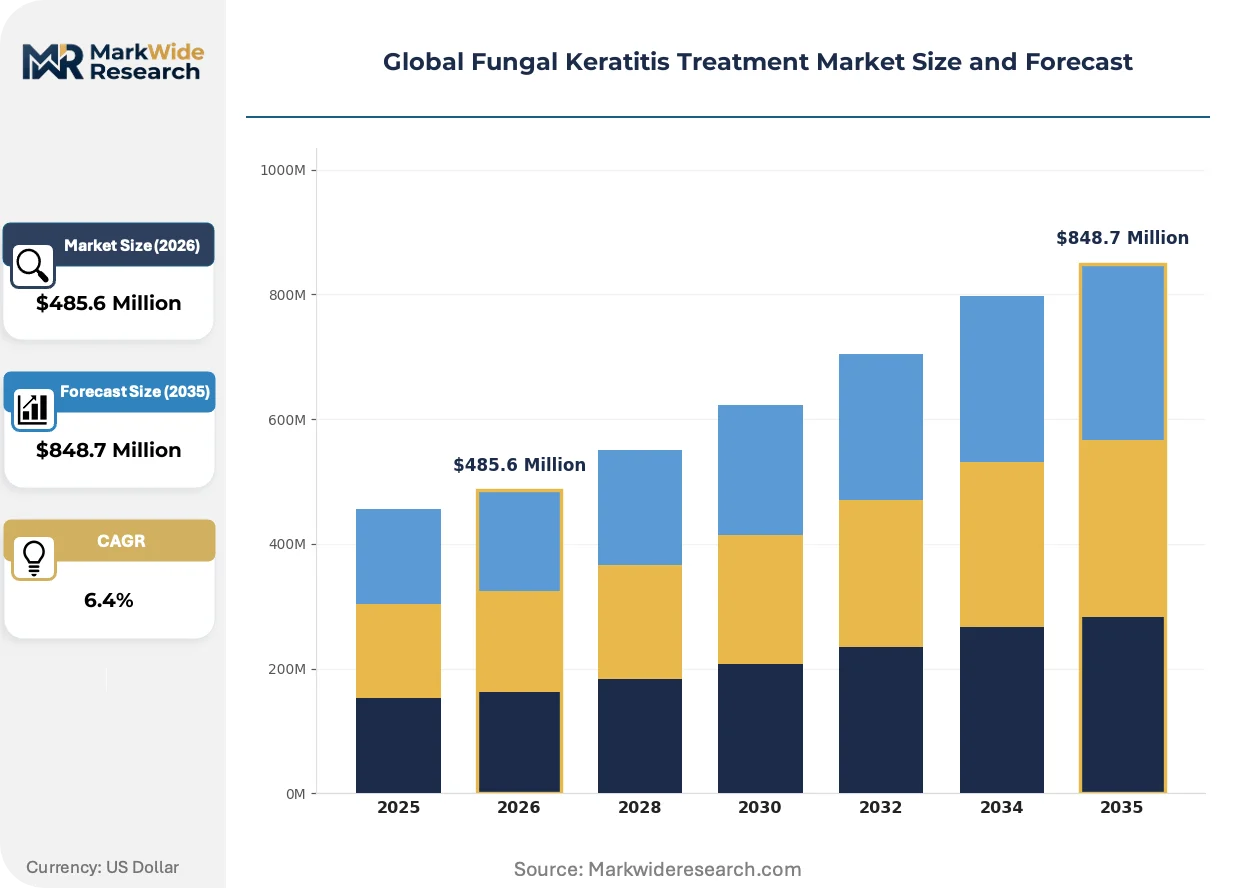
| Market Size in 2026 | $485.6 Million |
| Market Size in 2035 | $848.7 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Treatment Type: Natamycin, Amphotericin B, Voriconazole, Econazole, Miconazole Administration Route: Topical, Oral, Intrastromal Injection, Intravenous Patient Age Group: Pediatric, Adult, Geriatric, Neonatal Healthcare Setting: Ophthalmology Clinics, Eye Hospitals, Ambulatory Surgical Centers, Specialty Care Centers |
| Companies Covered | Merck & Co. Inc., Bausch Health Companies Inc., Pfizer Inc., Gilead Biosciences Inc., Glenmark Pharmaceuticals, Aurolab, Alvogen, Eyevance Pharmaceuticals LLC, Novartis AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Fungal Keratitis Treatment Market Shifts & Advancements
Voriconazole formulation chemistry and delivery mechanism innovation is electrifying competitive positioning as resistance patterns shift therapeutic protocols away from legacy polyene monotherapy.
Nanostructured lipid carrier systems for voriconazole is electrifying corneal bioavailability outcomes by achieving fivefold higher stromal drug concentrations than conventional aqueous suspensions. Cornea specialists in Chennai and Madurai eye hospitals are adopting these carriers for refractory Fusarium cases. The technology is electrifying premium pricing power for formulation innovators while compressing commodity drop margins.
FDA's 2023 updated guidance on compounding animal drugs for human ophthalmic use is tightening outsourcing facility qualification requirements. 503B compounders must now demonstrate species-specific pharmacokinetic equivalence for natamycin sourced from veterinary fermentation. Indian exporters to US hospital systems are responding with dedicated human-grade fermentation lines at Hyderabad manufacturing parks.
Direct hospital procurement consortia in Maharashtra and Karnataka are displacing traditional distributor networks for high-volume natamycin purchasing. State government tender aggregation pools now command 40-50% price concessions from generic manufacturers. This concentration is most visible in Mumbai and Bangalore public eye hospital systems where annual contract values exceed private pharmacy channel volumes.
Global Fungal Keratitis Treatment Market Segmentation
Segmentation in fungal keratitis treatment reveals how regulatory pathways, clinical severity, and healthcare infrastructure shape procurement patterns across geographies. Each dimension carries distinct certification burdens and margin structures that determine manufacturer prioritization.
Treatment Type:
Polyenes and azoles navigate divergent approval pathways—polyenes require fermentation-derived API validation under FDA and EMA guidelines, while synthetic azoles face chemistry-manufacturing-controls scrutiny from CDSCO and national regulators in manufacturing hubs.
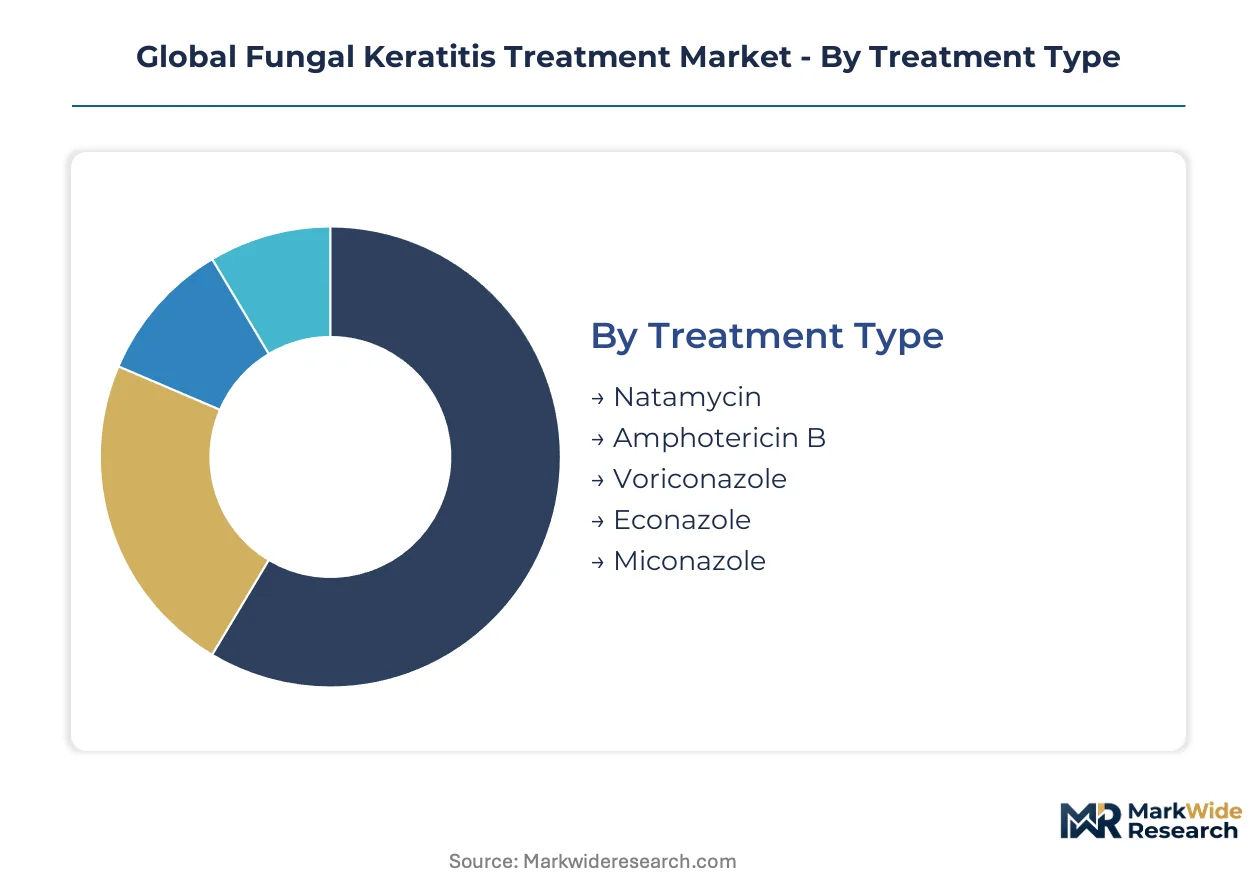
- Natamycin:Fermentation-derived polyene with established stromal penetration limits. Demand clusters in Indian public eye hospitals where Tamil Nadu and Uttar Pradesh agricultural trauma cases drive high-volume procurement of 5% suspensions.
- Voriconazole:Second-generation triazole with broader filamentous coverage. Refractory case protocols in Chennai and Madurai specialty centers are accelerating uptake of compounded 1-2% formulations against Fusarium and Scedosporium resistance.
- Amphotericin B:Systemic polyene reserved for severe keratomycosis with intraocular extension.
- Econazole:Imidazole derivative with limited corneal penetration; deployed mainly in combination protocols.
- Miconazole:Legacy imidazole facing displacement by voriconazole in most tertiary settings.
Natamycin sits at the top of the volume ranking, with voriconazole climbing the fastest.
Administration Route:
Route selection determines facility qualification tiers—topical manufacturing scales across standard sterile suites, while injection protocols demand ISO 5 cleanroom certification and specialist training infrastructure that fragments addressable supply bases.
- Topical:Aqueous and suspension drops dominate first-line therapy. Maharashtra and Karnataka state tender pools command 40-50% price concessions through direct hospital procurement consortia displacing traditional distributors.
- Intrastromal Injection:Microinjection delivery achieves therapeutic concentrations in deep stromal infiltrates refractory to topical therapy. Corneal specialists at Aravind Eye Hospital and LV Prasad Eye Institute are pioneering standardized protocols that expand addressable refractory case margins.
- Oral:Systemic azole therapy for suspected endophthalmitis or bilateral disease; limited by hepatotoxicity monitoring requirements.
- Intravenous:Reserved for disseminated fungal sepsis with ocular involvement; negligible standalone keratitis volume.
Topical formulations capture the mature volume base, with intrastromal injection gaining share fastest among premium-tier providers.
Patient Age Group:
Age-stratified protocols reflect pharmacokinetic tolerance variations—pediatric and neonatal segments impose compounded formulation mandates that elevate manufacturing complexity beyond standard adult therapeutics.
- Adult:Standard 5% natamycin or 1-2% voriconazole protocols apply. Agricultural workers aged 25-55 in South and Southeast Asia represent the core demographic for trauma-related filamentous infections.
- Pediatric:Dose-adjusted formulations with preservative-free requirements. Compounding pharmacies in tertiary pediatric ophthalmology centers face extended CDSCO stability timelines for suspension products.
- Geriatric:Comorbidity-driven polypharmacy concerns shape azole selection to minimize systemic interaction risks.
- Neonatal:Candida keratitis in premature infants demands specialized compounded preparations with stringent endotoxin limits.
Adult patients occupy the volume peak, with pediatric protocols expanding most quickly as diagnostic reach extends through teleophthalmology networks.
Healthcare Setting:
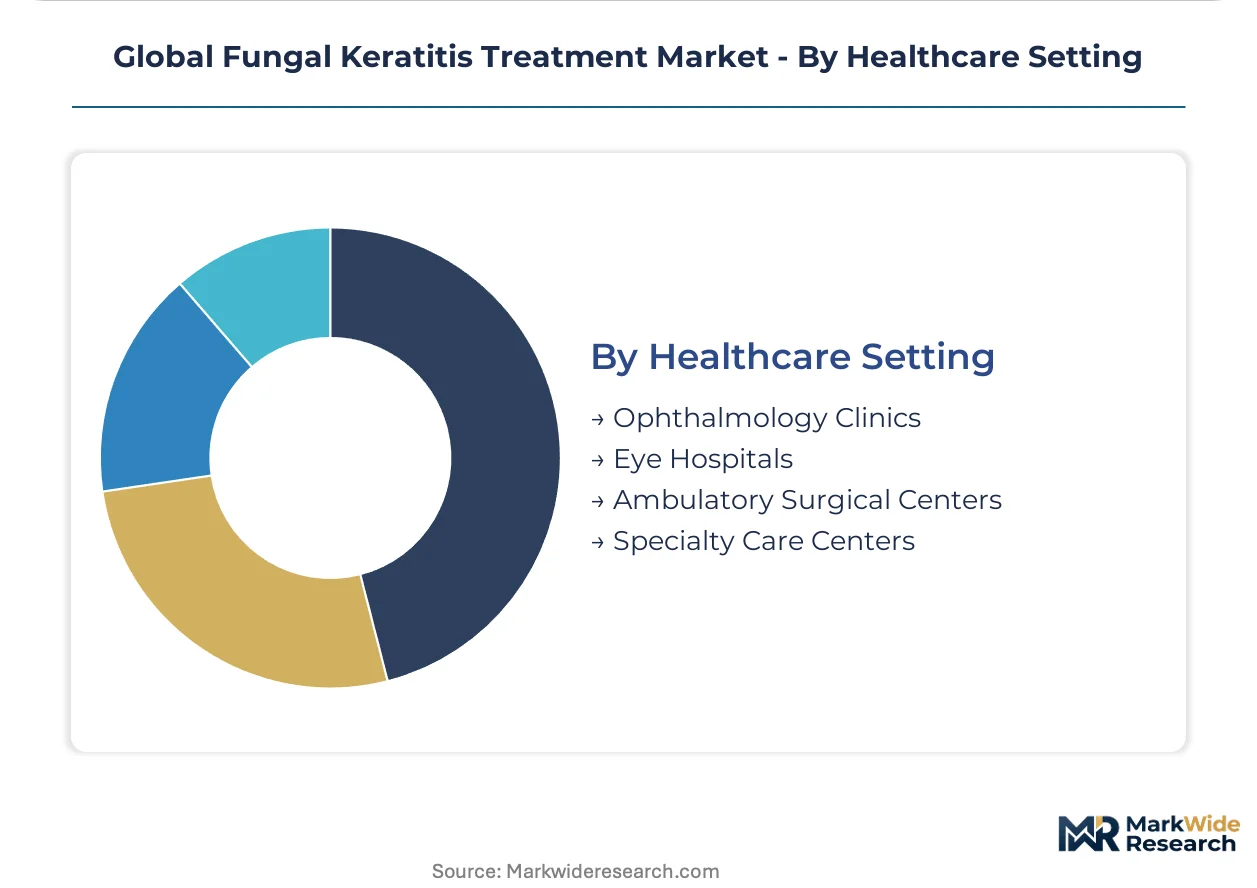
Setting tiering aligns with surgical capability and reimbursement structures—eye hospitals integrate debridement services that compounders and clinics cannot replicate, concentrating premium case value in dedicated corneal centers.
- Eye Hospitals:Integrated medical-surgical facilities with in-house microbiology and therapeutic keratoplasty capabilities. Aravind Eye Hospital's Tamil Nadu network and LV Prasad Eye Institute in Hyderabad anchor South Indian case volume with standardized natamycin-first protocols.
- Ophthalmology Clinics:Outpatient diagnosis and medical management sites. Mumbai and Bangalore private clinic chains are consolidating through teleophthalmology linkages to urban cornea specialists.
- Ambulatory Surgical Centers:Limited penetration for keratitis given emergency debridement requirements and 24-hour monitoring protocols.
- Specialty Care Centers:Uveitis and ocular immunology units managing atypical fungal presentations.
Eye hospitals command the highest case complexity and revenue per patient, with ophthalmology clinics expanding reach fastest through diagnostic technology diffusion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage between FDA preservative-free mandates and emerging-market cost tolerances is reshaping manufacturing location decisions. Indian API clusters absorb compliance cost differentials through dedicated human-grade fermentation lines, while European and US markets enforce sterile fill-finish standards that fragment supply readiness.
United States
Agricultural trauma in Florida and California rice-growing regions sustains filamentous fungal infection caseloads. FDA's 2023 updated guidance on compounding animal drugs for human ophthalmic use tightens 503B facility qualification requirements. Boston and Philadelphia hospital systems source natamycin through qualified outsourcing facilities facing critical aseptic processing technician shortages.
India
Tamil Nadu and Uttar Pradesh agricultural laborers drive trauma-related Fusarium and Aspergillus infections requiring high-volume polyene therapy. CDSCO's tightened 36-month real-time stability requirements for ophthalmic suspensions extend product registration cycles. Hyderabad and Ahmedabad manufacturing parks control over 70% of generic azole API output, creating concentrated supply vulnerability.
Germany
EMA's MDR requirements for intraocular devices accelerate review pathways for therapeutic contact lenses with embedded antifungal elution. Bavarian and Baden-Württemberg ophthalmic device manufacturers pursue convergence between drug and device regulatory frameworks. Frankfurt hospital procurement networks negotiate volume contracts for voriconazole formulations against refractory Candida presentations.
Brazil
ANVISA's alignment with FDA sterility standards elevates import barriers for multi-dose ophthalmic products. São Paulo and Minas Gerais sugarcane belt workers present filamentous keratitis profiles similar to South Asian agricultural populations. Rio de Janeiro specialty eye hospitals lack consistent natamycin supply chains, creating distribution partnership opportunities for Indian generic exporters.
China
NMPA's ophthalmic suspension stability mandates parallel CDSCO timelines, compressing registration windows for imported actives. Yangtze River Delta chemical manufacturers expand azole synthesis capacity for regional formulation fill-finish. Shanghai cornea specialists adopt intrastromal injection protocols pioneered at Indian tertiary eye hospitals.
Global Fungal Keratitis Treatment Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue nanostructured delivery systems and preservative-free formulation differentiation. The vendor base stratifies across fermentation-derived polyene specialists, synthetic azole chemists, and regional generic formulators. Three archetypes dominate: legacy pharmaceutical conglomerates with captive API supply, mid-cap Indian generics with concentrated ophthalmic portfolios, and specialized compounding pharmacies serving refractory case protocols. Capacity expansion and geographic licensing partnerships constitute the dominant competitive moves.
Within the legacy pharmaceutical tier, Merck & Co. Inc. and Pfizer Inc. exemplify divergent strategic anchors—Merck leveraging fermentation expertise for natamycin scale, Pfizer deploying vertically integrated azole chemistry. Glenmark Pharmaceuticals occupies a position among emerging-market topical formulation specialists with concentrated Indian manufacturing presence. These three represent distinct competitive postures without implying specific market share or revenue claims.
| Leading Market Players |
|---|
| Merck & Co. Inc. |
| Bausch Health Companies Inc. |
| Pfizer Inc. |
| Gilead Biosciences Inc. |
| Glenmark Pharmaceuticals |
| Aurolab |
| Alvogen |
| Eyevance Pharmaceuticals LLC |
| Novartis AG |
| Others |
Supply & Pricing Matrix
Aseptic processing technician pools in Hyderabad and Ahmedabad manufacturing parks compress labor-cost differentials between preservative-free and multi-dose formulation tiers, widening pricing spreads across FDA-compliant and emerging-market product lines.
Pricing Analysis
Distributor margins for natamycin suspensions have compressed to single-digit percentages in Maharashtra and Karnataka state tender pools, where direct hospital procurement consortia displace traditional wholesale networks. Three-tier pricing structure across preservative-free premium vials, standard multi-dose bottles, and economy generic suspensions reflects FDA certification grade and volume scale. Cost compression in the economy tier intensifies as Indian API manufacturers absorb CDSCO stability-testing expenses. Public eye hospital systems in Tamil Nadu exhibit highest price sensitivity; refractory-case specialty centers in Chennai and Madurai show lowest sensitivity due to intrastromal injection premium positioning.
Supply Chain Analysis
EMA MDR and FDA 503B qualification gating fragments sterile fill-finish capacity, concentrating API supply in India, China, and selected European fermentation sites. Fermentation-derived natamycin and synthetic azole chemistry draw from agricultural substrate feedstocks, petrochemical intermediates, and specialized solvent systems. Single-source vulnerability pervades the supply base: Hyderabad and Ahmedabad clusters control over seventy percent of generic azole active pharmaceutical ingredient output. Distribution runs through hospital procurement consortia in South India, direct-to-hospital contracts in Germany, and qualified outsourcing facilities in the US Northeast.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Fungal Keratitis Treatment Market functions as a stable compounder, with WHO neglected tropical disease framework inclusion anchoring sustained public procurement demand across endemic tropical zones.
For Market Incumbents: Hedge against voriconazole resistance-pattern shifts by maintaining dual polyene-triazole manufacturing capability and securing dedicated human-grade fermentation lines ahead of tightened FDA veterinary-to-human sourcing guidance. Backward integration into preservative-free sterile fill-finish capacity protects margin position as 503B facility qualification requirements escalate. Prioritize CDSCO pre-registration stability investments to compress Indian product approval cycles. For New Entrants and Emerging Players: Launch via distribution partnerships with Kenyan and Nigerian eye hospitals, where natamycin supply chains remain inconsistent and first-mover procurement relationships command premium positioning. Teleophthalmology-linked diagnostic networks in rural India present the most penetrable white-space channel. Target nanostructured lipid carrier formulation licensing to Chennai and Madurai specialty centers seeking refractory-case differentiation. For Investors and Strategic Acquirers: Indian generic ophthalmic manufacturers with concentrated topical portfolios are the most active acquirer targets in this space, as mid-cap formulators seek fermentation-derived API capabilities. The five-to-ten year viability window favors platforms with dual WHO prequalification and FDA 503B supply relationships. Watch intrastromal injection protocol standardization at Aravind Eye Hospital and LV Prasad Eye Institute as the inflection signal for premium-tier margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| CDSCO Pre-Registration Stability Investment | Compresses ophthalmic suspension approval timelines by eight to fourteen months for Indian market access. |
| WHO Prequalification Pathway | Unlocks subsidized procurement budgets across neglected tropical disease framework inclusion zones. |
| EMA MDR Device Convergence | Accelerates review timelines for therapeutic contact lenses with embedded antifungal elution capabilities. |
| Teleophthalmology Triage Network Partnership | Extends diagnostic reach into rural Indian agricultural worker populations through smartphone-linked corneal imaging. |
| 503B Outsourcing Facility Qualification | Secures US hospital system supply relationships under tightened FDA compounding guidance. |
Research Methodology
Direct dialogue with corneal specialists, hospital procurement managers at Aravind Eye Hospital and LV Prasad Eye Institute, CDSCO regulatory affairs leads, and sterile compounding facility operators grounded qualitative insights. Secondary validation drew from FDA 503B facility registration databases, EMA MDR guidance documents, WHO neglected tropical disease framework publications, and CDSCO ophthalmic suspension stability guidelines. Bottom-up prescription volume modeling and top-down pharmaceutical market sizing were triangulated against API trade flow data from Indian customs records.
Bottom-up volume projections tracked administration route adoption curves, treatment line progression patterns, and regional regulatory cluster differentiation across the projection horizon. Segmentation dimensions included treatment type, administration route, patient age group, and healthcare setting tier. CAGRs were derived from epidemiological incidence modeling for agricultural worker populations and pricing trajectory analysis for preservative-free versus multi-dose formulations. Forecast inputs incorporated WHO procurement budget allocations and intrastromal injection protocol diffusion rates at Indian tertiary eye hospitals.
Several conditions sit outside the modeled scope, including emerging antifungal resistance mutations beyond current voriconazole coverage, sudden FDA revocation of animal-derived API compounding pathways, and catastrophic climate events disrupting Tamil Nadu agricultural labor patterns. Deviation in WHO neglected tropical disease framework funding priorities would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Radioimmunotherapy (RIT) Market
Specialty Medicine
Achondroplasia Treatment Market
Specialty Medicine
Stuttering Therapeutics Market
Specialty Medicine
Marfan Syndrome Treatment Market
Specialty Medicine
Cutaneous Radiation Injury Treatment Market
Specialty Medicine
Pharyngitis Treatment Market
Specialty Medicine
Esophageal Atresia Treatment Market
Specialty Medicine
Herpes Zoster (Shingles) Market
Specialty Medicine
Nonalcoholic Steatohepatitis Market
Specialty Medicine
Rhabdomyosarcoma Market
Specialty Medicine
Cat Scratch Disease (CSD) Treatment Market
Specialty Medicine
Overt Hepatic Encephalopathy Market
Specialty Medicine
North America Dry Eye Syndrome Market
Specialty Medicine
Dry Eye Disease Market
Specialty Medicine
Nocturnal Polyuria Treatment Market
Specialty Medicine
Axillary Hyperhidrosis Treatment Market