
 Pigmented Villonodular Synovitis Treatment Market | 2026-2036
Pigmented Villonodular Synovitis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Pigmented Villonodular Synovitis Treatment Market Analytics
Orphan drug designation is hardening the cost-of-entry calculus for developers of PVNS-targeted therapies. Novartis AG leverages its established oncology infrastructure to sustain clinical trial momentum across rare soft-tissue indications. Bristol-Myers Squibb Company anchors its position through deep immuno-oncology expertise that extends into difficult-to-treat synovial pathologies.
Pigmented villonodular synovitis constitutes a locally aggressive proliferative disorder of synovial membrane characterized by hemosiderin-laden macroph infiltration, typically affecting large joints such as knee, hip, and ankle with predilection for tendon sheaths and bursae. The condition demands therapeutic intervention to preserve joint function, manage recurrent effusions, and prevent progressive osteoarticular destruction. Tyrosine kinase inhibitors command expanding prescriber attention as systemic options for diffuse unresectable disease, while intra-articular injection routes retain primacy for localized presentations where direct delivery maximizes tissue exposure and minimizes systemic burden. Hospitals dominate end-user demand by concentrating arthroscopic expertise, imaging capacity, and multidisciplinary sarcoma review boards.
The FDA orphan drug program, EMA's priority medicines scheme, and Japan's SAKIGAKE designation framework collectively shape clinical development timelines, reimbursement negotiations, and market access trajectories for novel PVNS therapeutics. These regulatory instruments reward sponsors with protocol assistance, fee waivers, and extended exclusivity that alter portfolio prioritization decisions across biopharma pipelines. Stakeholders must monitor how evolving biomarker qualification standards and decentralized trial modalities reshape evidence-generation requirements for this ultra-rare indication.
Market Dynamics
Orphan drug designation pathways are restructuring development economics for ultra-rare synovial neoplasms, concentrating R&D investment among sponsors with existing oncology infrastructure and reshaping competitive entry thresholds across the therapeutic landscape.
Growth Catalysts
- FDA Orphan Drug Incentives:Extended market exclusivity and tax credits for clinical trial expenditures accelerate sponsor commitment to diffuse PVNS indications previously deemed commercially unviable.
- Tyrosine Kinase Inhibitor Expansion:Systemic therapy pipelines targeting CSF1R signaling are generating prescriber familiarity with medical management alternatives to repeated surgical intervention.
- Specialized Sarcoma Center Concentration:Patient volume aggregation in tertiary referral networks streamlines clinical trial enrollment and post-market surveillance for novel therapeutic modalities.
Market Restraints
- Diagnostic Latency:Pathologic confirmation delays averaging 18-24 months from symptom onset compress the addressable treatment window and complicate trial endpoint design.
- Reimbursement Complexity:Heterogeneous coding for diffuse versus localized disease phenotypes creates prior authorization friction and coverage determination inconsistency across payers.
- Surgical Standard-of-Care Entrenchment:Arthroscopic synovectomy retains primacy in orthopedic training curricula, limiting medical therapy penetration in community practice settings.
Strategic Opportunities
- Liquid Biopsy Development:Circulating biomarker assays for CSF1R pathway activation could enable non-invasive disease monitoring and therapy selection without repeated joint aspiration.
- Japan SAKIGAKE Pathway:Expedited review designation for innovative therapies addresses the country's concentrated elderly population with high joint-preservation demand.
- Intra-Articular Formulation Innovation:Depot delivery systems extending local drug exposure offer differentiation from systemic administration in localized disease presentations.
Industry Challenges
- Pathologist Specialization Scarcity:Diagnostic expertise in tenosynovial giant cell tumor histopathology concentrates in academic medical centers, creating geographic disparities in accurate case identification.
- Longitudinal Data Infrastructure:Natural history registries capturing recurrence patterns post-surgical and post-medical therapy remain underdeveloped, constraining health technology assessment submissions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pigmented Villonodular Synovitis Treatment Market |
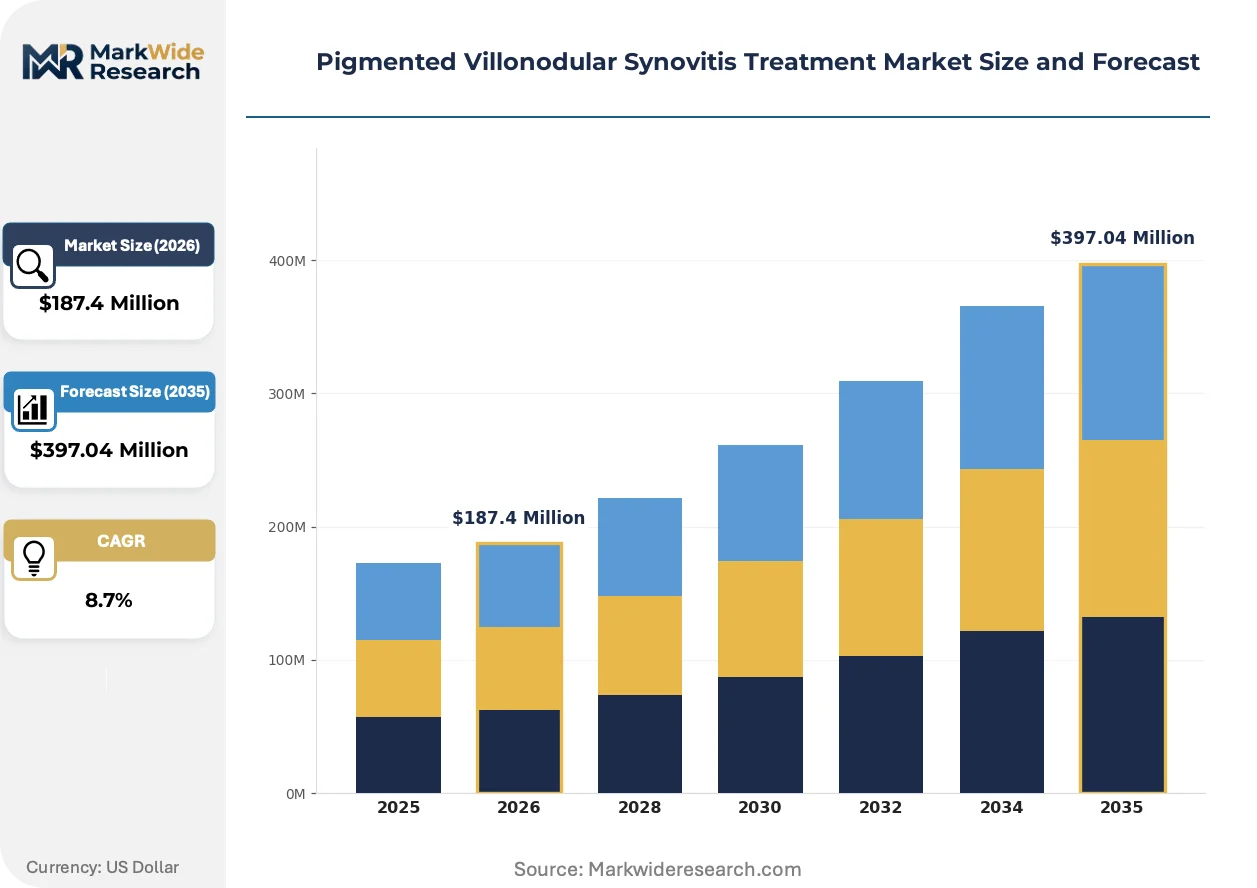
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Type: Non-Steroidal Anti-Inflammatory Drugs, Corticosteroids, Disease-Modifying Antirheumatic Drugs, Tyrosine Kinase Inhibitors Administration Route: Oral, Intra-articular Injection, Intravenous, Topical End User: Hospitals, Outpatient Clinics, Rehabilitation Centers, Homecare Therapeutic Area: Orthopedics, Rheumatology, Pain Management, Surgical Treatment |
| Companies Covered | Novartis AG, F. Hoffmann-La Roche, Bristol-Myers Squibb Company, Daiichi Sankyo, AbbVie Inc., Deciphera Pharmaceuticals, Plexxikon Inc., Acceleron Pharma, Calithera Biosciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pigmented Villonodular Synovitis Treatment Market Evolving Landscape
Computational pathology and real-world evidence platforms are transforming how ultra-rare synovial disorders generate regulatory-grade data, compressing traditional clinical development timelines while raising evidentiary standards for mechanism-based therapies.
Artificial intelligence-enabled histopathology analysis is automating CSF1R expression scoring and hemosiderin quantification in synovial biopsy specimens. Academic pathology departments at tertiary sarcoma centers are deploying these tools to standardize diagnostic criteria across multi-site clinical trials. This automation is compressing inter-reader variability and accelerating biomarker-enriched patient stratification for targeted therapy cohorts.
EMA's priority medicines scheme is accelerating assessment timelines for therapies addressing unmet needs in rare musculoskeletal neoplasms. The framework's enhanced regulatory dialogue provisions enable adaptive trial designs that reduce patient exposure to placebo comparators. Diffuse PVNS presentations with high recurrence risk following surgical failure are attracting scheme utilization as sponsors seek conditional marketing authorization pathways.
Centralized procurement through hospital pharmacy and therapeutics committees is displacing individual prescriber autonomy in high-cost targeted therapy selection. Specialty pharmacy distribution channels are capturing patient onboarding and adherence monitoring functions previously managed in orthopedic clinics. Germany's hospital reimbursement structure, with its emphasis on diagnosis-related group refinements for rare diseases, is accelerating this consolidation in European markets.
Pigmented Villonodular Synovitis Treatment Market Segmentation
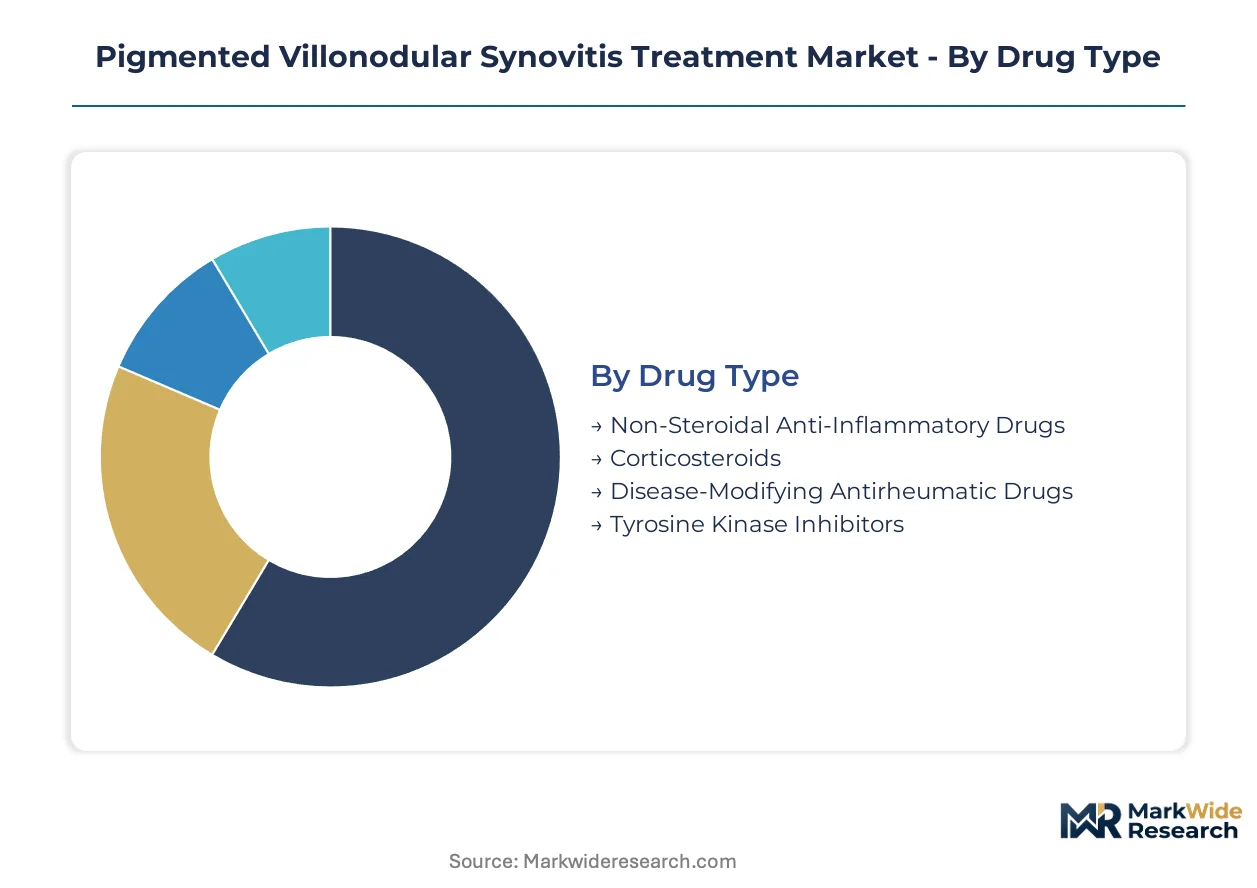
Treatment modality selection in PVNS hinges on disease phenotype, joint accessibility, and prescriber specialty training. Segmentation reveals how diffuse versus localized presentations drive divergent therapeutic pathways and reimbursement logic across care settings.
Drug Type:
Cost tier differentiation separates acute symptom management from disease-modifying interventions in this rare neoplasm.
- Non-Steroidal Anti-Inflammatory Drugs:First-line agents for pain and inflammation control in early-stage presentations. Demand concentrates in outpatient orthopedic clinics across Germany where gatekeeping protocols require conservative trials before specialist referral.
- Corticosteroids:Potent anti-inflammatory compounds delivered via intra-articular or systemic routes. Rheumatology departments at US academic medical centers favor these for rapid effusion reduction while awaiting definitive histopathology.
- Disease-Modifying Antirheumatic Drugs:Immunomodulatory agents repurposed from rheumatoid arthritis protocols. Japan's elderly population with comorbid autoimmune conditions generates prescribing volume for methotrexate combinations.
- Tyrosine Kinase Inhibitors:CSF1R-targeted small molecules transforming systemic management of diffuse unresectable disease. Pexidartinib and imatinib pipelines command premium pricing and specialized pharmacy distribution in tertiary sarcoma centers.
NSAIDs lead volumes today; tyrosine kinase inhibitors are gaining share fastest.
Administration Route:
Application context determines whether therapy prioritizes local tissue exposure or systemic biomarker modulation.
- Oral:Systemic delivery enabling patient self-administration and adherence monitoring through specialty pharmacy programs. Chronic therapy protocols for diffuse PVNS favor this route in US and European markets with established oral oncology infrastructure.
- Intra-articular Injection:Direct joint delivery maximizing synovial drug concentration while sparing systemic exposure. Arthroscopy suites at German hospital-based orthopedic departments perform these procedures under image guidance.
- Intravenous:Infusion-based administration for hospitalized patients or high-bioavailability requirements. Japanese sarcoma centers utilize IV methylprednisolone pulses for acute inflammatory flares.
- Topical:Transdermal formulations for periarticular soft tissue symptoms. Limited penetration in PVNS due to deep joint involvement restricts this route to adjuvant perioperative pain management.
Intra-articular injection dominates procedural volumes; oral administration is climbing the fastest as systemic therapy pipelines mature.
End User:
Customer type fragmentation reflects credentialing requirements for arthroscopic intervention versus medical therapy prescribing authority.
- Hospitals:Integrated settings housing multidisciplinary sarcoma boards, advanced imaging, and surgical suites. Tertiary centers in the United States, Germany, and Japan aggregate complex diffuse cases requiring combined modality management.
- Outpatient Clinics:Community-based orthopedic and rheumatology practices handling localized presentations and post-surgical surveillance. Prior authorization complexity for targeted therapies limits their systemic therapy penetration.
- Rehabilitation Centers:Post-intervention facilities focusing on joint function preservation and mobility restoration. Post-synovectomy protocols in German rehabilitation networks emphasize early mobilization to prevent arthrofibrosis.
- Homecare:Settings for oral therapy administration and remote monitoring. Specialty pharmacy nursing services in the US manage pexidartinib hepatotoxicity monitoring in home-based patients.
Hospitals capture the highest acuity cases; homecare is expanding most quickly with oral targeted therapy adoption.
Therapeutic Area:
Specialty training backgrounds create divergent diagnostic and treatment philosophies for this histiocytic neoplasm.
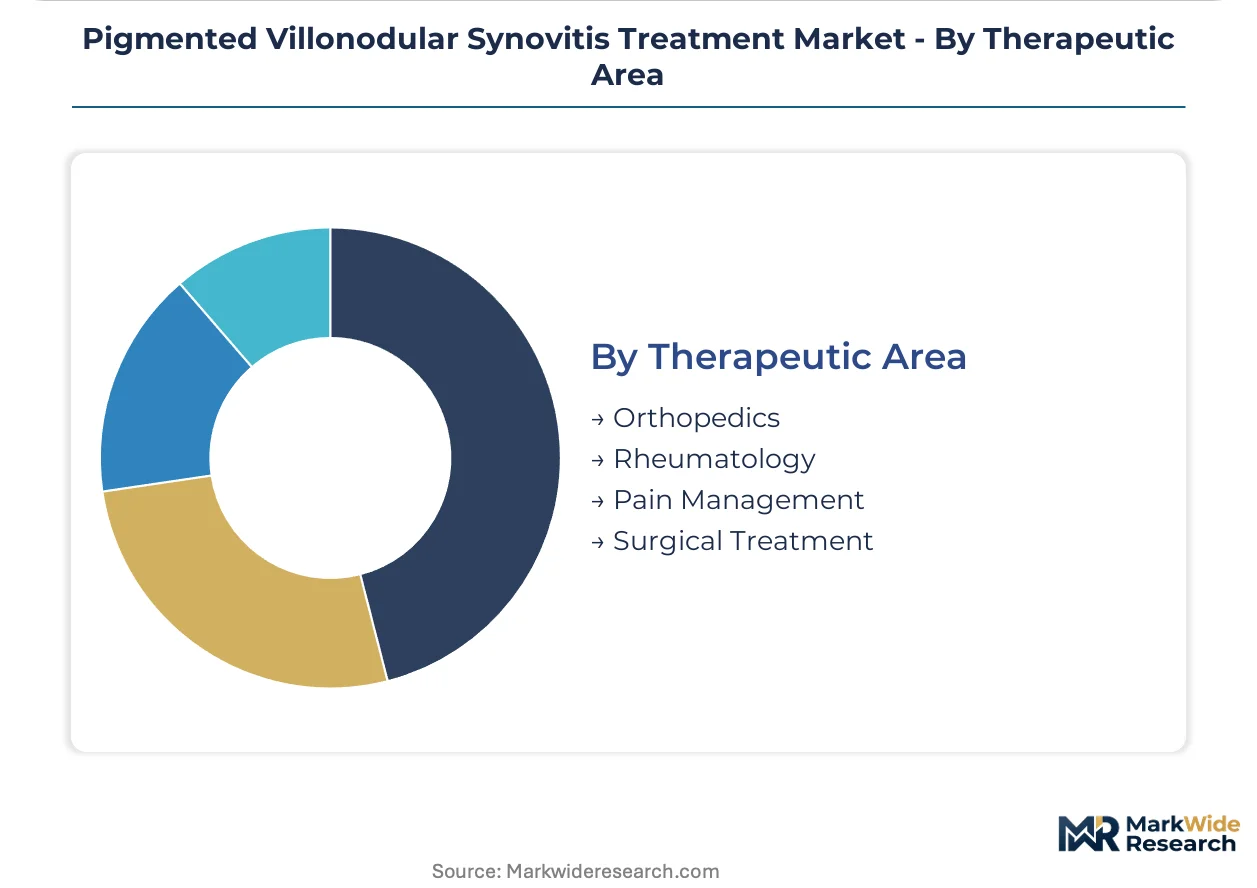
- Orthopedics:Surgical specialists performing arthroscopic synovectomy and joint-preserving procedures. Orthopedic oncology fellowship programs at US academic centers concentrate expertise in tenosynovial giant cell tumor management.
- Rheumatology:Medical specialists employing immunomodulatory and targeted systemic approaches. EULAR guidelines and CSF1R biomarker research drive rheumatology engagement in diffuse phenotypes across European referral networks.
- Pain Management:Anesthesia-trained interventionalists performing image-guided injections and neuromodulation. Chronic post-surgical pain syndromes in recurrent PVNS generate demand for their services.
- Surgical Treatment:Open and arthroscopic proceduralists addressing mechanical joint destruction. Radical synovectomy and joint replacement for end-stage disease concentrate in high-volume sarcoma surgery units.
Orthopedics anchors procedural volumes; rheumatology shows the steepest expansion trajectory with targeted medical therapy development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized orthopedic oncologists and sarcoma pathologists concentrate in tertiary referral networks across the United States, Germany, and Japan. These clinical hubs anchor regional demand for PVNS-targeted therapies and shape cross-border patient mobility patterns.
United States
Academic medical centers in Boston, Houston, and New York City aggregate complex diffuse PVNS cases requiring combined surgical and medical management. The FDA's orphan drug designation pathway accelerates sponsor commitment to CSF1R inhibitor development through tax credits and extended exclusivity provisions. Memorial Sloan Kettering Cancer Center and MD Anderson Cancer Center operate dedicated tenosynovial giant cell tumor programs that streamline clinical trial enrollment.
Germany
Hospital-based orthopedic departments in Berlin, Munich, and Hamburg perform high-volume arthroscopic synovectomy procedures while expanding systemic therapy adoption. EMA's priority medicines scheme enables adaptive trial designs that reduce placebo exposure in rare musculoskeletal neoplasms. The Charité-Universitätsmedizin Berlin hosts a reference pathology laboratory standardizing CSF1R immunohistochemistry across European clinical trials.
Japan
An aging population with elevated joint-preservation demand concentrates patient volumes in Tokyo, Osaka, and Nagoya sarcoma centers. PMDA's SAKIGAKE designation framework expedites review timelines for innovative therapies addressing ultra-rare indications. National Cancer Center Hospital East maintains a prospective registry capturing long-term recurrence patterns following pexidartinib exposure.
Switzerland
Basel and Zurich anchor pharmaceutical R&D infrastructure supporting rare disease therapeutic development. Swissmedic's expedited access pathway facilitates early patient access to CSF1R-targeted agents prior to full marketing authorization. The University Hospital of Basel operates a multidisciplinary sarcoma board integrating orthopedic surgery, pathology, and medical oncology expertise.
United Kingdom
London, Manchester, and Birmingham tertiary centers manage complex recurrent cases referred from regional orthopedic networks. The MHRA's innovative licensing pathway supports conditional approvals based on single-arm trial data in ultra-rare neoplasms. The Royal National Orthopaedic Hospital in Stanmore maintains a national referral service for tenosynovial giant cell tumors.
Pigmented Villonodular Synovitis Treatment Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the PVNS therapeutic landscape, creating a tiered competitive structure. Large-cap oncology franchises leverage existing clinical infrastructure and regulatory relationships to sustain pipeline momentum in ultra-rare indications. Mid-cap biotech specialists concentrate exclusively on CSF1R pathway modulation and tenosynovial neoplasm biology. Dominant competitive moves include strategic partnerships for biomarker co-development and geographic licensing arrangements that accelerate market access in concentrated sarcoma center networks.
Among diversified pharmaceutical conglomerates, Novartis AG and Bristol-Myers Squibb Company occupy positions that exemplify scale-driven oncology infrastructure deployment. F. Hoffmann-La Roche anchors the European contingent with established rare disease commercialization capabilities. These entities represent the integrated tier where portfolio breadth supports sustained investment in ultra-rare synovial neoplasms despite limited addressable patient populations.
| Leading Market Players |
|---|
| Novartis AG |
| F. Hoffmann-La Roche |
| Bristol-Myers Squibb Company |
| Daiichi Sankyo |
| AbbVie Inc. |
| Deciphera Pharmaceuticals |
| Plexxikon Inc. |
| Acceleron Pharma |
| Calithera Biosciences |
| Others |
Value Network & Pricing Analysis
Specialty pharmacy consolidation in the United States is forcing manufacturers toward direct distribution agreements that compress intermediary margins while elevating compliance costs for hepatotoxicity monitoring programs. Hospital procurement committees in Germany and Japan are responding with centralized tendering that rewards volume commitments with preferential formulary placement.
Pricing Analysis
Bundled service contracts combining drug supply with companion diagnostic testing command premium positioning against unbundled per-dose transactional models. Three-tier pricing structure across premium CSF1R inhibitors, standard corticosteroid regimens, and economy NSAID protocols reflects clinical outcome differentiation and orphan drug exclusivity status. Pricing pressure stems from biosimilar anticipation in the tyrosine kinase inhibitor class and mandatory rebate negotiations under Medicare Part D redesign. Community orthopedic clinics exhibit highest price sensitivity due to prior authorization friction, while tertiary sarcoma centers demonstrate lowest sensitivity given bundled reimbursement through diagnosis-related group refinements.
Supply Chain Analysis
Cold chain logistics costs for biologic CSF1R inhibitors elevate landed costs by 15-20 percent relative to small-molecule alternatives, compressing distributor margins on intra-articular depot formulations. Active pharmaceutical ingredient production concentrates in Switzerland, Ireland, and Singapore, with formulation finishing distributed across regional hubs serving the United States, Germany, and Japan. Supply chain risk centers on single-source dependency for CSF1R monoclonal antibody production, where facility contamination or regulatory inspection delays would disrupt global availability. Distribution runs through specialty pharmacy networks that capture patient onboarding, adherence monitoring, and adverse event reporting functions previously managed within hospital-based orthopedic departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage opportunities concentrate in Japan's SAKIGAKE pathway, where expedited regulatory review compresses time-to-market by 12-18 months relative to standard EMA timelines, offsetting higher clinical trial costs in Tokyo and Osaka sarcoma centers.
For Market Incumbents: Deploy regulatory exclusivity extensions through pediatric indication development and orphan drug designation stacking to defend against CSF1R biosimilar entry. Consolidate manufacturing footprint into Switzerland and Singapore to exploit bilateral trade agreements that minimize tariff exposure on high-value biologic shipments. Deepen hospital system partnerships through risk-sharing arrangements that tie reimbursement to recurrence-free survival endpoints. For New Entrants and Emerging Players: AI-enabled histopathology diagnostic platforms offer technology-first entry into the CSF1R biomarker scoring segment currently dominated by manual academic pathology review. White-space targets include liquid biopsy development for non-invasive disease monitoring and intra-articular depot formulation innovation extending local drug exposure beyond current corticosteroid persistence windows. A go-to-market angle anchored in decentralized trial modalities can accelerate enrollment in diffuse PVNS cohorts without reliance on concentrated sarcoma center networks. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap biotech specialists holding exclusive CSF1R pathway intellectual property and tenosynovial neoplasm clinical datasets. Long-term viability over a 5-10 year horizon hinges on successful navigation of biomarker qualification standards and conditional marketing authorization conversions. Acquisition targets should demonstrate prospective registry infrastructure capturing longitudinal recurrence patterns. The signal to watch is EMA priority medicines scheme utilization rates, which indicate sponsor confidence in adaptive trial designs and accelerated assessment pathways.| Strategic Initiative | Industry Significance |
|---|---|
| Orphan Drug Designation Stacking | FDA and EMA incentives compound development economics for sponsors addressing ultra-rare synovial neoplasms. |
| Companion Diagnostic Co-development | CSF1R immunohistochemistry standardization across Charité-Universitätsmedizin Berlin and Memorial Sloan Kettering accelerates biomarker-enriched enrollment. |
| Specialty Pharmacy Integration | Vertical control over patient onboarding and hepatotoxicity monitoring displaces traditional hospital pharmacy functions in US markets. |
| Japan SAKIGAKE Pathway Utilization | PMDA expedited review compresses regulatory timelines for innovative therapies in aging populations with joint-preservation demand. |
| Real-World Evidence Platform Deployment | Computational pathology and decentralized trial modalities reshape evidence-generation requirements for mechanism-based therapies. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists with secondary validation against FDA orphan drug filings, EMA priority medicines submissions, ClinicalTrials.gov entries, and hospital formulary databases. Bottom-up patient volume estimates across tertiary sarcoma centers in the United States, Germany, and Japan were triangulated against top-down pharmaceutical revenue disclosures and diagnosis-related group reimbursement schedules.
Historical reference periods anchored the forecast window through retrospective analysis of pexidartinib adoption curves, imatinib off-label utilization patterns, and arthroscopic synovectomy procedure volumes. Segmentation dimensions modeled include treatment modality, administration route, disease phenotype, prescriber specialty, and regional regulatory cluster. CAGRs were derived through log-linear regression of segment-level growth trajectories, with inputs from CSF1R inhibitor pipeline advancement timelines and biomarker qualification standard evolution.
The model holds under stable orphan drug incentive frameworks and continued sarcoma center concentration; deviation in reimbursement policy toward site-neutral payment or biosimilar accelerated approval would shift volume trajectories. Stakeholders should weight assumptions against their own operating context and monitor regulatory guidance updates on decentralized trial acceptability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Global Interstitial Cystitis Market
Specialty Medicine
Global Graves Disease Market
Specialty Medicine
Hemochromatosis Treatment Market
Specialty Medicine
Botulism Treatment Market
Specialty Medicine
Neuromyelitis Optica Market
Specialty Medicine
Intussusception Market
Specialty Medicine
Global Acute Agitation and Aggression Treatment Market
Specialty Medicine
Idiopathic Thrombocytopenic Purpura Therapeutics Market
Specialty Medicine
Global Lupus Market
Specialty Medicine
Alport Syndrome Treatment Market
Specialty Medicine
Generalized Myasthenia Gravis (GMG) Management Market
Specialty Medicine
Cat Scratch Disease (CSD) Treatment Market
Specialty Medicine
Frontotemporal Dementia Management Market
Specialty Medicine
Allergic Conjunctivitis Market
Specialty Medicine
Non-Alcoholic Fatty Liver Disease (NAFLD) Market
Specialty Medicine
Intramedullary Osteosarcoma Treatment Market