
 Global Allergy Vaccine Market | 2026-2036
Global Allergy Vaccine Market Size, Share, and Industry Trends Forecast 2026-2036
Global Allergy Vaccine Market Foresight
Recombinant allergen components are shifting product economics away from crude natural extracts toward precision-defined immunotherapy agents. ALK-Abelló A/S leverages its vertically integrated extract sourcing to sustain cost advantages across European and North American distribution networks. STALLergenes Greer Ltd. anchors its competitive position through specialized manufacturing scale in sublingual tablet formats. Allergy Therapeutics plc competes via differentiated polymerized allergoid technology that modifies allergen structure while preserving immunogenicity.
Allergy vaccines are biologic preparations containing standardized allergen extracts or recombinant proteins formulated for repeated administration to induce antigen-specific immune tolerance, typically measured in biological units or micrograms of major allergen. These products serve the primary commercial purpose of modifying allergic disease progression rather than merely suppressing symptoms through pharmacologic intervention. Subcutaneous immunotherapy retains the largest revenue share due to decades of clinical validation and established reimbursement codes across mature healthcare systems. Sublingual immunotherapy represents the fastest-expanding segment as patient preference for home-based administration drives formulary expansion in Germany, France, and Italy. Recombinant DNA technology commands premium positioning within the technology landscape, though adjuvant-enhanced formulations are gaining traction as developers seek to shorten treatment durations and improve compliance profiles.
The FDA oversees allergen extract licensing through the Biologics License Application pathway, while the EMA's Committee for Medicinal Products for Human Use evaluates centralized marketing authorizations for sublingual and subcutaneous products across EU member states. ISO 13485 quality management standards govern manufacturing consistency, with national pharmacopeias specifying extract potency assays that directly shape product release criteria and batch-to-batch variability limits. Stakeholders must monitor how the EU Green Deal's pharmaceutical sustainability requirements will reshape extract sourcing, cold-chain logistics, and single-dose packaging decisions across the supply base.
Market Dynamics
Recombinant allergen technology is compressing manufacturing economics while FDA's evolving guidance on allergen immunotherapy products accelerates standardization across development pathways, forcing extract-dependent producers to retool purification infrastructure.
Growth Catalysts
- EMA's MDR framework:Centralized marketing authorizations for sublingual and subcutaneous products streamline cross-border commercialization across Germany, France, and Italy, reducing regulatory duplication costs.
- Pediatric centers:Parents seeking disease-modifying therapies for children with allergic conditions are driving formulary expansion in specialist clinic networks.
- Home-based administration:Patient preference for sublingual tablet formats over clinic-based injections is reshaping reimbursement negotiations with private payers.
Market Restraints
- Natural extract volatility:Batch-to-batch variability in pollen and dust mite sourcing from concentrated European cultivation regions creates potency standardization costs.
- Cold-chain infrastructure:Temperature-sensitive allergoid formulations require specialized logistics networks that remain underdeveloped in secondary metropolitan areas.
- Biologics substitution:Monoclonal antibodies targeting IgE-mediated pathways compete directly with immunotherapy for severe allergic asthma cases.
Strategic Opportunities
- India's CDSCO pathway:The country's national pharmaceutical regulator is establishing allergen-specific immunotherapy guidelines, opening registration routes for recombinant products.
- Adjuvant convergence:Combination of toll-like receptor agonists with recombinant proteins enables shortened treatment durations, addressing compliance drop-off in year-two protocols.
- Direct-to-patient channels:Telemedicine platforms in Brazil are piloting remote supervision models for sublingual immunotherapy initiation.
Industry Challenges
- ISO 13485 implementation:Small extract processors struggle with quality management system documentation requirements for major allergen quantification.
- Extract sourcing reconfiguration:EU Green Deal pharmaceutical sustainability mandates force suppliers to audit cultivation water usage and pesticide residues.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Allergy Vaccine Market |
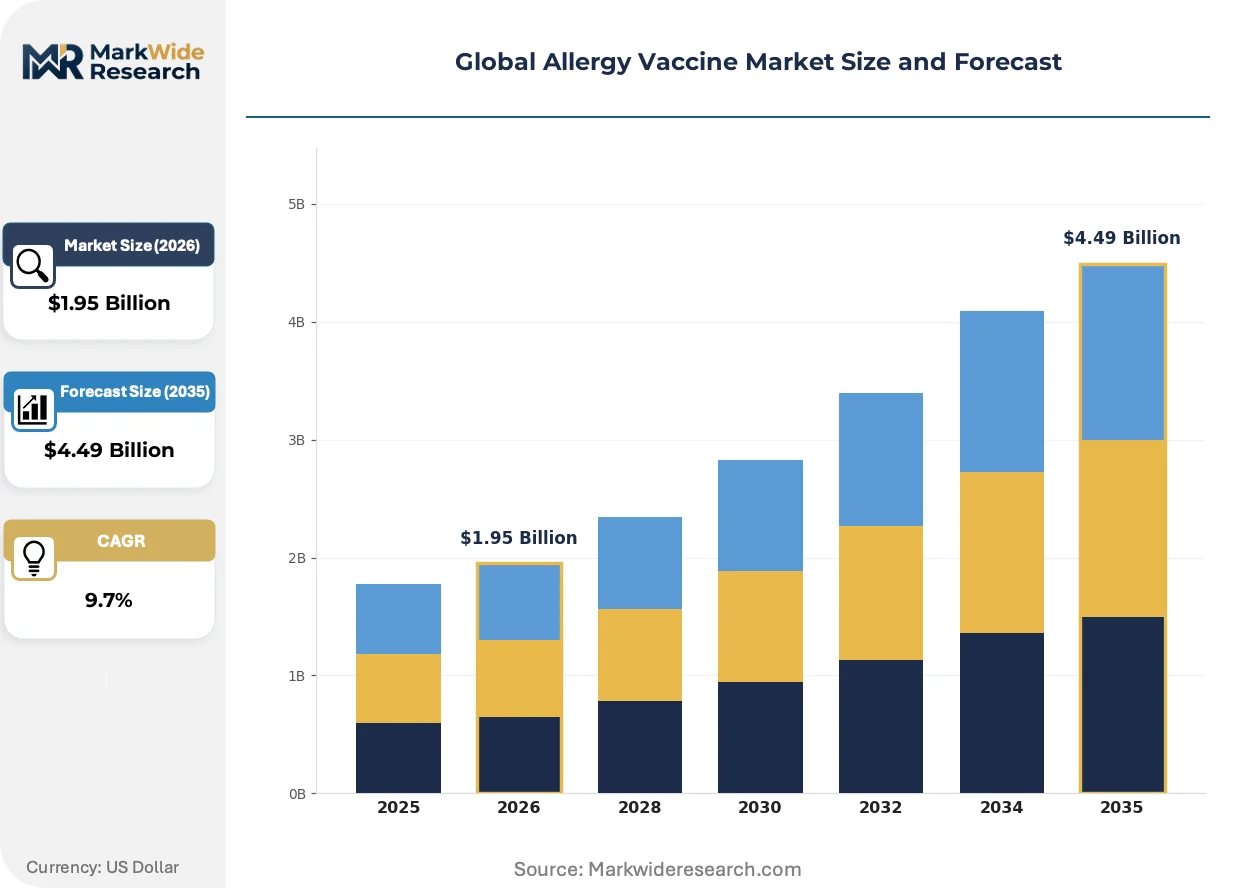
| Market Size in 2026 | $1.95 Billion |
| Market Size in 2035 | $4.49 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Subcutaneous Immunotherapy, Sublingual Immunotherapy, Oral Immunotherapy, Nasal Vaccines Application: Rhinitis, Asthma, Atopic Dermatitis, Food Allergy, Insect Sting Allergy Technology: Recombinant DNA Technology, Peptide-Based Vaccines, Virus-Like Particles, Adjuvant-Enhanced Vaccines End User: Specialty Allergy Clinics, Pediatric Centers, Research Laboratories, Immunotherapy Providers |
| Companies Covered | ALK-Abelló A/S, STALLergenes Greer Ltd., Allergy Therapeutics plc, HAL Allergy B.V., DBV Technologies S.A., Merck & Co., Inc., Novartis AG, Biomay AG, HollisterStier Allergy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Allergy Vaccine Market Shifts & Advancements
Precision-defined immunotherapy agents are displacing crude natural extracts across formulation pipelines, while regulatory convergence and patient-administration preferences compress traditional clinic-based models.
Recombinant DNA technology produces allergen components with defined tertiary structures and consistent glycosylation patterns. Pediatric allergists in the United States and Germany are adopting these formulations for polysensitized patients requiring tailored extract mixes. This precision is expanding into premium positioning that commands reimbursement premiums over natural extract alternatives.
EMA's F-Gas Regulation and associated pharmaceutical sustainability requirements are reshaping cold-chain logistics decisions. Manufacturers must now document refrigerant choices and thermal packaging recyclability in marketing authorization applications. Sublingual tablet producers with ambient-stable formulations gain competitive advantage in southern European distribution.
Specialist clinic networks in the United States are unbundling after-sales adherence monitoring from product dispensing. Third-party digital health platforms now track patient-reported symptom scores and medication logs, with allergists reviewing data remotely. This separation is most visible in Texas and Florida, where large independent practice associations negotiate formulary placement based on platform integration capabilities.
Global Allergy Vaccine Market Segmentation
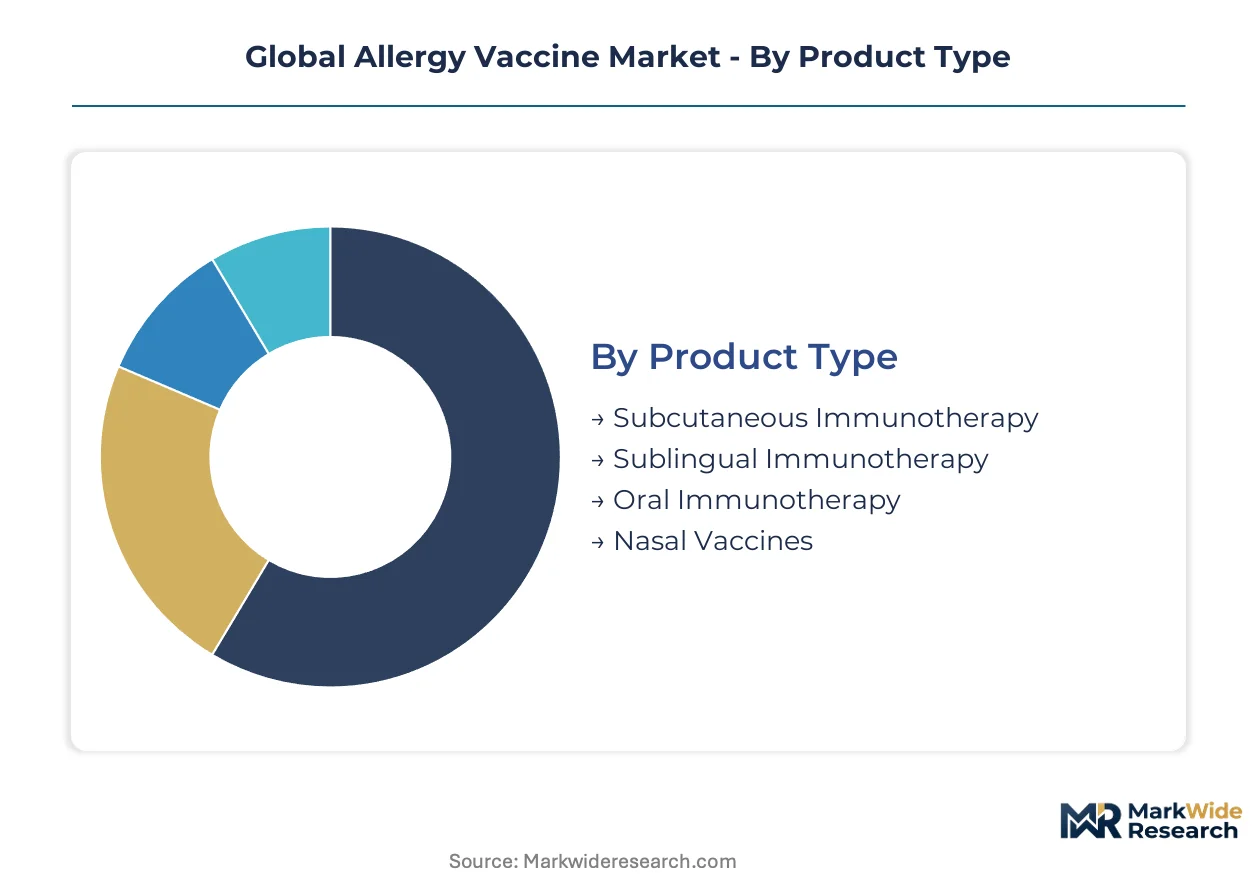
Segmentation in allergy vaccines reveals how administration route, disease target, and production technology each create distinct value pools with separate reimbursement dynamics and regulatory pathways. Understanding these divisions exposes where capital is concentrating and which configurations command pricing premiums.
Product Type:
Patient tolerance for clinic visits versus home administration determines route selection and directly shapes compliance economics across treatment protocols.
- Subcutaneous Immunotherapy:Allergen extracts or recombinant proteins formulated for injection delivery, typically administered in escalating dose protocols over 3-5 years. Demand concentrates in Germany and the United States, where established reimbursement codes and specialist clinic density sustain high patient throughput despite the burden of frequent office visits.
- Sublingual Immunotherapy:Standardized allergen tablets or drops placed under the tongue for daily home administration, requiring only initial physician supervision. Pediatric centers in France and Italy are driving formulary expansion as parents prioritize convenience and reduced school absence.
- Oral Immunotherapy:Food allergen desensitization protocols delivered through controlled ingestion regimens, primarily for peanut and egg allergies. Research laboratories in the United States are advancing protocols toward commercial scalability.
- Nasal Vaccines:Aerosolized allergen formulations targeting mucosal immune tolerance induction. Limited clinical validation restricts current deployment to experimental settings in Switzerland and the Netherlands.
Subcutaneous immunotherapy leads on scale; sublingual immunotherapy leads on momentum.
Application:
Disease severity and chronicity determine treatment duration, with conditions requiring lifelong management generating superior lifetime value per patient.
- Rhinitis:Seasonal and perennial allergic rhinitis constitute the foundational indication for immunotherapy, with pollen and dust mite allergens dominating prescription volumes. Specialty allergy clinics in the United States and Germany process the highest patient volumes due to pollen belt geography and insurance coverage structures.
- Asthma:Allergic asthma represents a higher-acuity indication where immunotherapy competes directly with monoclonal antibody biologics. Pediatric centers in Italy and Spain are expanding access as EMA guidelines strengthen evidence requirements for biologic substitution.
- Atopic Dermatitis:Emerging application with mechanistic rationale but limited regulatory approvals, currently concentrated in academic medical center trials.
- Food Allergy:Peanut, tree nut, and egg allergies drive development pipelines, with oral immunotherapy protocols advancing through FDA and EMA review pathways.
- Insect Sting Allergy:Vespid and honeybee venom immunotherapy serves a smaller but high-compliance population with clear fatality risk reduction, sustaining premium pricing in German and Austrian markets.
Rhinitis commands volume concentration; food allergy applications are climbing the fastest.
Technology:
Manufacturing precision and intellectual property protection separate premium-priced recombinant platforms from commodity extract production.
- Recombinant DNA Technology:Defined allergen components produced through microbial or mammalian expression systems with consistent post-translational modification. Immunotherapy providers in Germany and Switzerland are adopting these formulations for polysensitized patients requiring customized allergen cocktails.
- Peptide-Based Vaccines:Synthetic T-cell epitope peptides designed to induce tolerance without IgE-mediated allergic reactions. Research laboratories in the United Kingdom and the Netherlands are advancing candidates through early-phase trials.
- Virus-Like Particles:Self-assembling protein shells displaying allergen epitopes with enhanced immunogenicity and stability profiles. Limited commercial presence outside exploratory programs.
- Adjuvant-Enhanced Vaccines:Toll-like receptor agonists or depot formulations combined with allergen components to accelerate immune tolerance induction and shorten treatment duration. Specialty allergy clinics in the United States are piloting these protocols to address year-two compliance drop-off.
Recombinant DNA technology dominates revenue capture; adjuvant-enhanced vaccines are gaining share fastest.
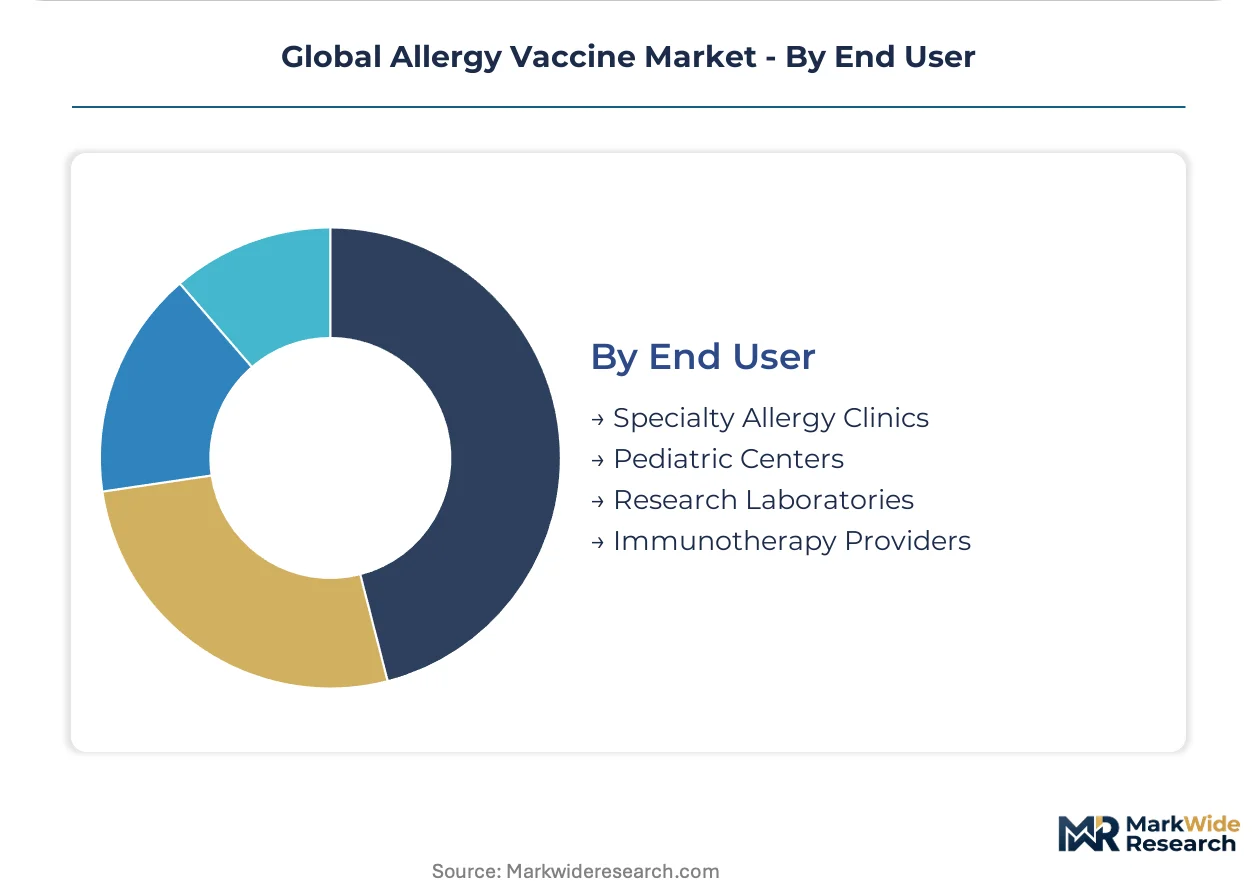
End User:
Site of care determines reimbursement mechanics, with institutional purchasing power concentrating in integrated clinic networks.
- Specialty Allergy Clinics:Dedicated immunology practices with extract compounding capabilities and established patient recall systems. United States and German networks are consolidating through private equity acquisition, centralizing formulary decision-making.
- Pediatric Centers:Hospital-based allergy divisions with family-centered care protocols and school partnership programs. French and Italian pediatric allergy services are expanding sublingual tablet dispensing to reduce injection burden.
- Research Laboratories:Academic and contract research organizations conducting Phase I-III trials and mechanistic studies. Swissmedic and FDA inspection histories shape site selection for pivotal studies.
- Immunotherapy Providers:Integrated delivery networks and pharmacy benefit managers managing population-level allergy care contracts. Brazilian telemedicine platforms are piloting remote sublingual initiation models.
Specialty allergy clinics lead on scale; pediatric centers lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German specialist clinic networks anchor commercial demand for subcutaneous and sublingual formulations, while reimbursement infrastructure variations across mature healthcare systems create divergent access patterns for precision immunotherapy agents.
United States
Pediatric centers in Texas and Florida drive sublingual tablet adoption as parents prioritize home-based administration over clinic visits. FDA's evolving guidance on allergen immunotherapy products accelerates standardization across Biologics License Application pathways. Independent practice associations in the Southeast negotiate formulary placement based on digital adherence platform integration.
Germany
Pollen belt geography sustains the highest patient throughput for subcutaneous immunotherapy in European specialist clinic networks. EMA's MDR framework streamlines centralized marketing authorizations, reducing cross-border commercialization costs for sublingual products. Bavarian extract processors face EU Green Deal sustainability mandates requiring cultivation water audits and pesticide residue documentation.
France
Pediatric allergy services in Paris and Lyon expand sublingual tablet dispensing to reduce injection burden for school-age children. ANSM oversees national pharmacopeia compliance for extract potency assays shaping batch release criteria. The Île-de-France region concentrates immunotherapy provider consolidation through hospital network procurement centralization.
Italy
Specialist clinics in Lombardy and Emilia-Romagna process rising volumes of polysensitized patients requiring tailored allergen cocktails. EMA guidelines strengthening evidence requirements for biologic substitution expand immunotherapy access for allergic asthma cases. Milan-based research laboratories advance adjuvant-enhanced formulation protocols through early-phase trials.
Switzerland
Swissmedic inspection histories shape site selection for pivotal studies among contract research organizations in Basel and Zurich. Recombinant DNA technology developers concentrate precision-defined allergen production for export to German and French markets. The country's pharmaceutical sustainability requirements exceed EU baselines, forcing cold-chain logistics reconfiguration for temperature-sensitive allergoid formulations.
Global Allergy Vaccine Market Competitive Landscape
Global majors compete with regional champions across extract sourcing and recombinant manufacturing capabilities, producing a tiered structure where scale-driven players coexist with technology specialists. The vendor base separates into three archetypes: vertically integrated extract processors with captive cultivation networks, recombinant platform developers commanding premium positioning, and sublingual formulation specialists leveraging manufacturing scale in tablet formats. Dominant competitive moves include strategic partnerships for adjuvant convergence and geographic expansion through regulatory pathway navigation.
Within the recombinant technology tier, ALK-Abelló A/S and Biomay AG exemplify precision-defined immunotherapy development, while STALLergenes Greer Ltd. anchors the sublingual formulation specialist position. These entities occupy distinct competitive spaces based on manufacturing architecture rather than overlapping product portfolios, with each representing a viable path to patient access across divergent reimbursement environments.
| Leading Market Players |
|---|
| ALK-Abelló A/S |
| STALLergenes Greer Ltd. |
| Allergy Therapeutics plc |
| HAL Allergy B.V. |
| DBV Technologies S.A. |
| Merck & Co., Inc. |
| Novartis AG |
| Biomay AG |
| HollisterStier Allergy |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up specialist clinic networks in the United States and Germany concentrate purchasing power for sublingual and subcutaneous formulations, compressing margins for extract-dependent suppliers while rewarding recombinant platform developers with pricing premiums tied to precision manufacturing.
Pricing Analysis
Input-cost pass-through from pollen and dust mite cultivation volatility in Bavaria and northern Italy forces extract processors to absorb potency standardization expenses rather than transfer full burden to clinic networks. Pricing stratifies across recombinant premium tiers, natural extract standard tiers, and adjuvant-enhanced economy tiers based on immunogenicity consistency and treatment duration guarantees. Cost compression in natural extract segments is intensifying because EU Green Deal sustainability mandates require pesticide residue documentation and water usage audits. Pediatric centers demonstrate lowest price sensitivity due to parental prioritization of disease-modifying outcomes, while general practitioner networks in secondary metropolitan areas resist formulary expansion without reimbursement parity.
Supply Chain Analysis
Dual-sourcing requirements from EMA-inspected manufacturers compel clinic networks to qualify both German and Swiss suppliers for critical allergoid formulations, preventing single-source dependency despite concentration advantages. Geographic supply anchors in Germany, Switzerland, and Denmark feed extract processing and recombinant production infrastructure. Raw material dependencies span cultivated pollen grains, laboratory-grade reagents for protein expression, and toll-like receptor agonist adjuvants. Single-source vulnerability persists for specialized cold-chain logistics serving temperature-sensitive allergoid batches. Distribution runs through specialist clinic networks and hospital-based pediatric centers in mature European markets, with emerging direct-to-patient channels piloting in Brazilian telemedicine platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The allergy vaccine market functions as a stable compounder, with chronic disease prevalence and pediatric treatment expansion generating predictable demand trajectories resistant to cyclical disruption.
For Market Incumbents: Lock in extract sourcing contracts with Bavarian and Danish cultivation cooperatives before EU Green Deal sustainability audits escalate compliance costs. Consolidate formulation capabilities in sublingual tablet manufacturing to defend against biologics substitution in severe allergic asthma cases. Prioritize ISO 13485 certification investments for quality management documentation that satisfies FDA Biologics License Application scrutiny.
For New Entrants and Emerging Players: Telemedicine-enabled remote supervision models offer the lowest barrier to patient access for sublingual immunotherapy initiation in underpenetrated Latin American markets. Target polysensitized patient populations in Italian and Spanish pediatric centers where tailored allergen cocktails command reimbursement premiums. Deploy direct-to-patient digital health platforms with symptom tracking integration to bypass established clinic network gatekeepers.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap extract processors lacking recombinant platform diversification, presenting consolidation opportunities before technology displacement accelerates. Long-term viability over a five-to-ten year window favors entities with vertically integrated cultivation and precision manufacturing capabilities. Watch FDA guidance finalization on allergen immunotherapy standardization as the inflection signal for regulatory pathway clarity.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | EMA centralized marketing authorizations reduce cross-border commercialization friction for sublingual tablets in Germany and France. |
| Manufacturing Scale-Up | Sublingual tablet production expansion in Switzerland addresses ambient-stable formulation demand across southern European distribution. |
| Backward Integration | Captive pollen cultivation in Bavaria secures extract supply consistency against EU Green Deal sustainability mandate disruption. |
| Pipeline Diversification | Adjuvant-enhanced recombinant programs shorten treatment duration to combat year-two compliance drop-off in pediatric protocols. |
| Strategic Partnership | Digital health platform integration with Texas and Florida independent practice associations enables remote adherence monitoring revenue streams. |
Research Methodology
Coverage spans North America, Western Europe, and Latin America, with primary inputs from each region combined with secondary validation. Drug development executives at recombinant platform developers, regulatory affairs leads navigating FDA and EMA pathways, formulary directors at pediatric centers, and payer access specialists informed demand and pricing dynamics. Secondary sources included FDA Biologics License Application filings, EMA Committee for Medicinal Products for Human Use submissions, ClinicalTrials.gov protocol registries, and national pharmacopeia extract potency standards. Bottom-up patient volume modeling and top-down healthcare expenditure allocation triangulated market sizing.
Rate-of-change decomposition across the projection horizon separated volume growth from pricing dynamics and mix shift effects. Segmentation dimensions encompassed administration route, disease target, production technology, and regional regulatory cluster. CAGRs derived from patient population epidemiology, treatment penetration assumptions, and reimbursement expansion trajectories. Forecast inputs incorporated pediatric center expansion rates, biologics substitution pressure in allergic asthma, and cold-chain logistics infrastructure development.
The model assumes a particular technology adoption path; alternative pathways for peptide-based T-cell epitope vaccines would alter the outlook if clinical validation accelerates beyond current exploratory programs. Forecasts reflect assumptions regarding EMA MDR framework implementation consistency and FDA guidance finalization timelines. Deviation in EU Green Deal pharmaceutical sustainability enforcement stringency would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Global Thyroid Disorder Market
Specialty Medicine
Splenomegaly Therapeutics Market
Specialty Medicine
Polychondritis Disease Treatment Market
Specialty Medicine
Global Stroke Therapeutics Market
Specialty Medicine
GCC Idiopathic Pulmonary Fibrosis Treatment Market
Specialty Medicine
Global Gastrointestinal Stromal Tumors Market
Specialty Medicine
Relapsing-Remitting Multiple Sclerosis (MS) Market
Specialty Medicine
Cervical Cancer Therapeutics Market
Specialty Medicine
Hypophosphatasia Treatment Market
Specialty Medicine
HER2 Positive Gastric Cancer Market
Specialty Medicine
Disruptive Behavior Disorders Market
Specialty Medicine
Hepatic Insufficiency/Liver Failure Market
Specialty Medicine
Leukocyte Adhesion Deficiency Management Market
Specialty Medicine
Neurosyphilis Market
Specialty Medicine
Progressive Supranuclear Palsy (PSP) Market
Specialty Medicine
Osteogenesis Imperfecta Treatment Market