
 Schizophrenia Treatment Market | 2026-2036
Schizophrenia Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Schizophrenia Treatment Market Outlook
Aftermarket service revenue from long-acting injectable administration and patient monitoring programs is narrowing the margin gap between acute inpatient episodes and chronic outpatient management. Johnson & Johnson (Janssen) leverages its dominance in paliperidone-based long-acting formulations to sustain recurring revenue streams. Eli Lilly and Company anchors its competitive position through R&D intensity in novel neurotransmitter targets, while Alkermes plc differentiates via proprietary manufacturing processes for controlled-release depot technologies.
Schizophrenia treatment encompasses pharmacological interventions targeting dopaminergic and glutamatergic pathway dysregulation, with formulations engineered to achieve sustained plasma concentrations over weeks or months to improve adherence in chronic disease management. The primary commercial purpose is to reduce relapse frequency, functional disability, and downstream healthcare utilization costs across diverse care settings. Antipsychotics remain the dominant product category by revenue, though long-acting injectable delivery modes command premium pricing and higher retention rates versus daily oral regimens. Outpatient care settings are expanding fastest as payers shift reimbursement away from institutional placement toward community-based management models.
FDA's Risk Evaluation and Mitigation Strategies and EMA's pharmacovigilance requirements for antipsychotic safety profiling shape clinical development timelines and post-market surveillance obligations for manufacturers seeking broad label indications. The DEA's scheduling controls on certain adjunctive anxiolytic compounds and CMS reimbursement criteria for telepsychiatry services further constrain how products reach patients across delivery channels. Stakeholders must monitor evolving FDA guidance on digital therapeutics as adjuncts to pharmacotherapy, since software-based cognitive intervention products threaten to capture portions of the traditional drug-adjacent value pool without equivalent regulatory precedent.
Market Dynamics
Long-acting injectable formulations are compressing relapse-driven hospitalization cycles into predictable outpatient revenue streams, forcing manufacturers to restructure clinical trial endpoints around functional recovery metrics rather than symptom suppression alone.
Growth Catalysts
- CMS telepsychiatry reimbursement expansion:The Centers for Medicare & Medicaid Services expanded parity coverage for remote psychiatric consultations, accelerating community-based care model adoption in rural United States counties previously dependent on institutional placement.
- Glutamatergic pathway modulation:Novel NMDA receptor-targeting compounds entering Phase III trials offer mechanism-of-action differentiation from dopamine D2 antagonism, attracting investigator-initiated studies at academic medical centers.
- Integrated care mandates:The United Kingdom's National Health Service Long Term Plan mandates physical health screening co-located with mental health services, creating bundled reimbursement opportunities for metabolic monitoring alongside antipsychotic administration.
Market Restraints
- Active pharmaceutical ingredient concentration:Over 70% of antipsychotic API manufacturing concentrates in Indian and Chinese contract manufacturers, exposing supply continuity to geopolitical friction and environmental compliance enforcement variability.
- EMA pharmacovigilance burden:The European Medicines Agency's extended safety monitoring requirements for metabolic and cardiovascular adverse events add 18-24 months to post-approval label expansion timelines.
- Generic oral antipsychotic substitution:Patent-expired risperidone and olanzapine formulations capture 60% of incident prescription volume in Medicaid populations, compressing branded pricing power for oral atypicals.
Strategic Opportunities
- Digital therapeutic adjuncts:FDA breakthrough device designation pathways for cognitive remediation software create reimbursement precedents for prescription digital therapeutics bundled with pharmacotherapy in United States commercial plans.
- Sub-Saharan Africa institutional partnerships:WHO Mental Health Gap Action Programme implementation in Nigeria and Kenya creates demand for simplified dosing regimens and heat-stable formulations absent cold-chain infrastructure.
- Japan's community-based care transition:METI and MHLW reimbursement reforms shifting from psychiatric hospital beds to group home placement favor long-acting formulations reducing medication management burden on non-specialist caregivers.
Industry Challenges
- Patient stratification biomarker validation:Pharmacogenomic testing for CYP2D6 and CYP3A4 metabolic phenotypes lacks prospective trial evidence linking genotype to antipsychotic selection outcomes, slowing payer coverage determination.
- Real-world evidence collection infrastructure:Fragmented electronic health record systems across United States state Medicaid programs impede longitudinal adherence tracking necessary for value-based contract risk adjustment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Schizophrenia Treatment Market |
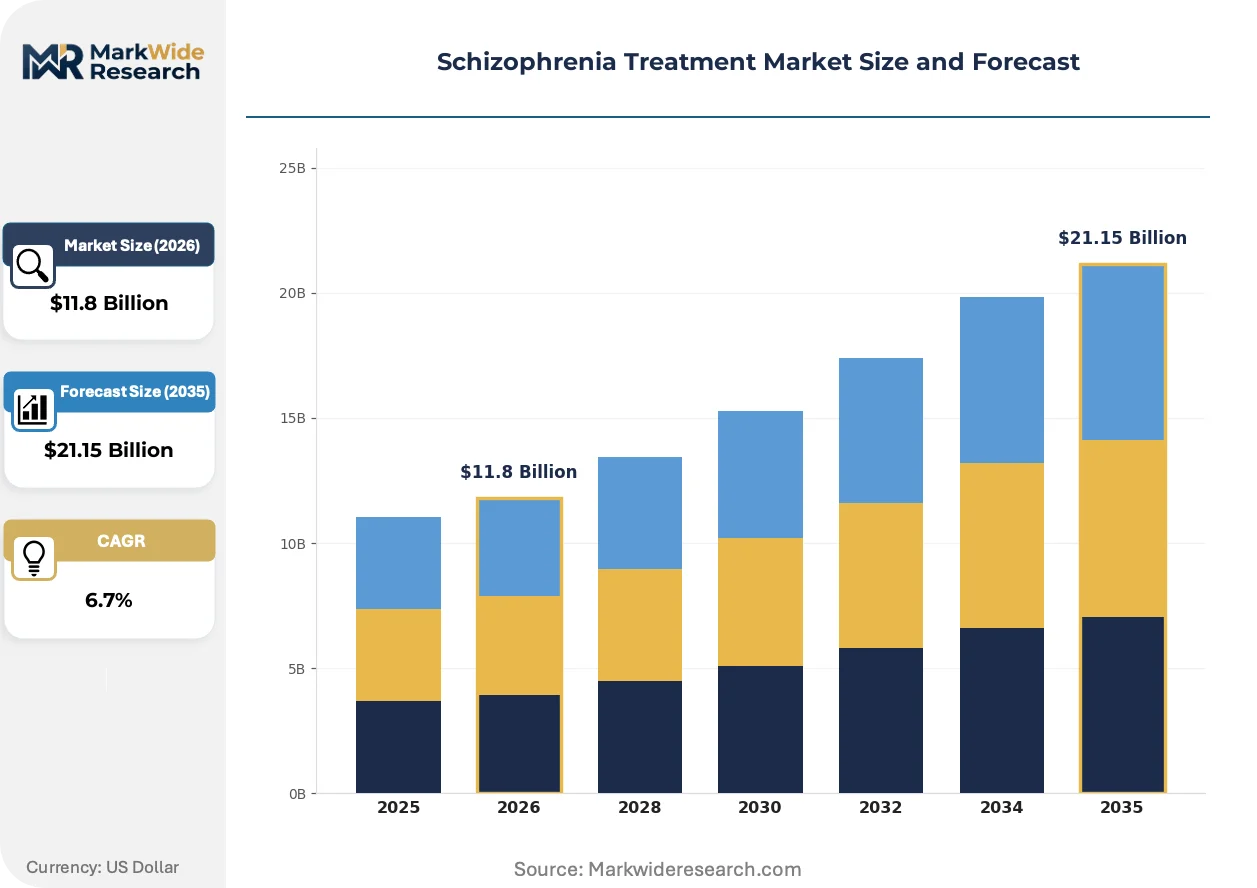
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $21.15 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antipsychotics, Mood Stabilizers, Anti-Anxiety Medications, Cognitive Enhancers Delivery Mode: Injectable, Oral, Transdermal, Intranasal Care Setting: Inpatient, Outpatient, Residential Treatment, Community Health Age Group: Children, Adolescents, Adults, Seniors |
| Companies Covered | Johnson & Johnson (Janssen), Eli Lilly and Company, Alkermes plc, Otsuka Pharmaceutical, AbbVie Inc., AstraZeneca, Bristol-Myers Squibb, Sumitomo Pharma, Pfizer Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Schizophrenia Treatment Market Strategic Shifts
Antipsychotic development is bifurcating between precision neuropharmacology targeting specific receptor subtypes and delivery system engineering extending dosing intervals, with both pathways requiring novel regulatory engagement strategies.
Implantable depot technologies using biodegradable polymers are hybridizing pharmacokinetic profiles previously achievable only through separate immediate-release and extended-release formulations. Academic medical centers in Germany and the Netherlands are piloting six-month paliperidone implants in treatment-resistant cohorts with documented non-adherence histories. This convergence is compressing the distinction between acute stabilization and maintenance phases into continuous plasma concentration management.
The FDA's accelerated approval pathway for novel mechanisms is pressuring developers to validate surrogate endpoints like negative symptom improvement rather than relapse prevention alone. EMA's parallel scientific advice procedures are diverging on acceptability of digital biomarker data, creating regulatory arbitrage opportunities for first movers selecting primary review geography. Small-cap biotechnology firms are front-loading European filing strategies to leverage centralized pediatric investigation plan negotiations.
United States commercial payers are unbundling pharmacy benefit from medical benefit administration for long-acting injectables, creating channel conflict between specialty pharmacy distribution and physician buy-and-bill models. Hospital systems in Texas and Florida are consolidating behavioral health service lines under risk-bearing entities capturing total cost of care savings from reduced inpatient days. This structural payment reform is most visible in Medicare Advantage plans with star rating incentives for medication adherence quality metrics.
Schizophrenia Treatment Market Segmentation
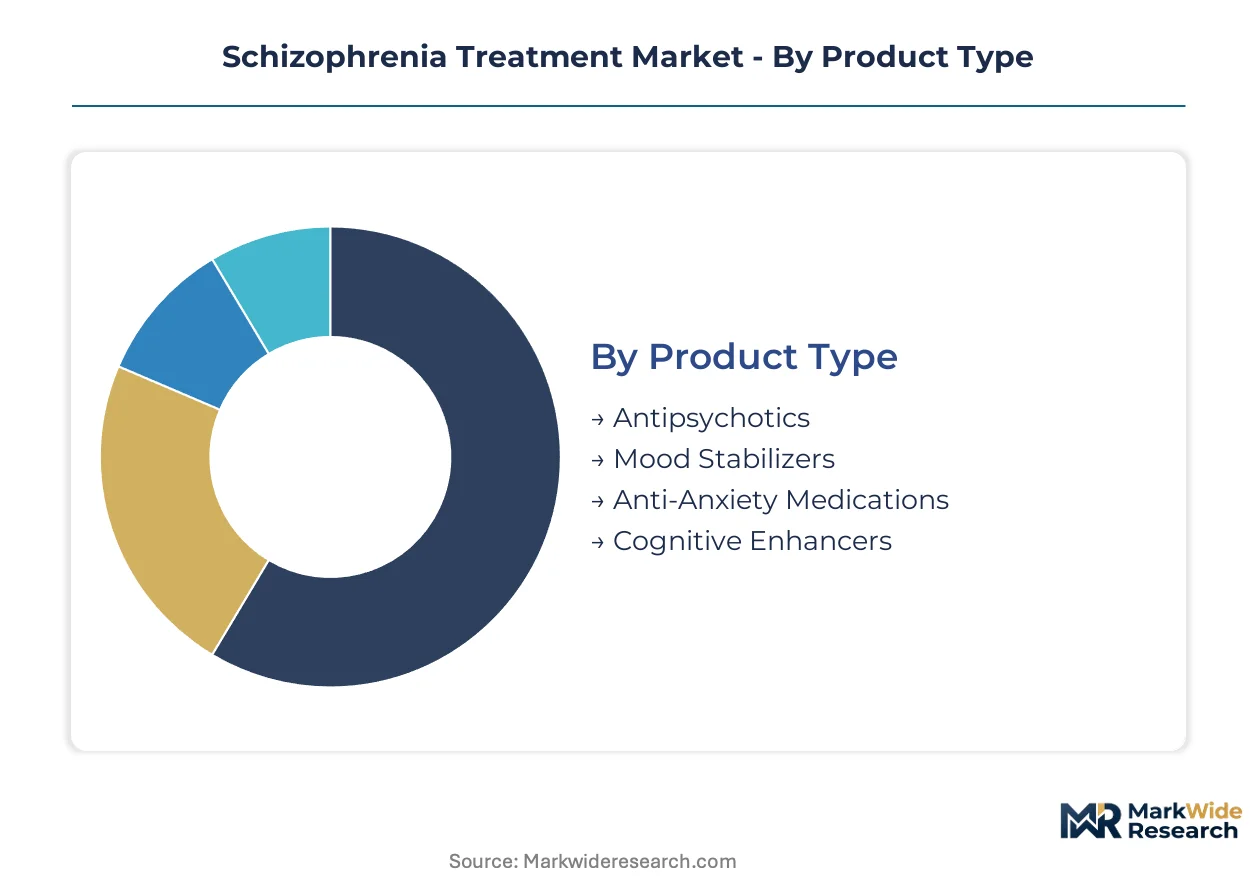
Segmentation in schizophrenia treatment reveals how reimbursement mechanics and patient adherence profiles reshape commercial strategy across formulation types and care environments. Manufacturers prioritize segments where long-acting delivery modes and outpatient administration create predictable revenue streams detached from acute episode volatility.
Product Type:
After-sales service intensity varies sharply across pharmacological categories, with antipsychotics demanding specialized injection training and metabolic monitoring programs that oral mood stabilizers rarely require.
- Antipsychotics:Dopamine D2 receptor antagonists and partial agonists constitute the therapeutic backbone, with second-generation atypicals dominating prescribing patterns in United States Medicaid formularies. Johnson & Johnson's paliperidone franchise and Eli Lilly's olanzapine portfolio anchor hospital system contracts through bundled adherence support services.
- Mood Stabilizers:Lithium carbonate and anticonvulsant adjuncts address comorbid bipolar spectrum presentations, though generic substitution pressures compress branded pricing power in European markets where EMA pharmacovigilance requirements extend label expansion timelines.
- Anti-Anxiety Medications:Benzodiazepine and non-benzodiazepine anxiolytics serve acute agitation episodes under DEA scheduling constraints that limit distribution channels.
- Cognitive Enhancers:Cholinesterase inhibitors and glutamate modulators target persistent negative symptoms with limited payer coverage determination pending biomarker validation.
By volume, antipsychotics lead. By growth pace, cognitive enhancers are ahead.
Delivery Mode:
Cost tier stratification separates premium-priced long-acting injectables from commoditized oral generics, with reimbursement mechanics favoring administration modes that reduce hospitalization frequency.
- Injectable:Long-acting depot formulations achieve sustained plasma concentrations over weeks to months, commanding premium pricing in Medicare Advantage plans with star rating incentives for medication adherence. Alkermes and Janssen dominate this segment through proprietary polymer technologies and six-month dosing intervals.
- Oral:Immediate-release and extended-release tablets capture incident prescription volume in Medicaid populations where generic risperidone and olanzapine formulations compress branded market access.
- Transdermal:Patch-based delivery systems address first-pass metabolism variability with limited commercial penetration outside Japan's community-based care transition markets.
- Intranasal:Rapid-onset formulations target acute agitation episodes in emergency department settings, though DEA scheduling controls constrain outpatient dispensing.
By volume, oral formulations dominate. By margin contribution, injectable modes lead.
Care Setting:
Application context determines regulatory burden and reimbursement pathway, with outpatient expansion accelerating as CMS telepsychiatry reimbursement parity reduces institutional dependency.
- Inpatient:Acute psychiatric units manage florid psychosis episodes under diagnosis-related group reimbursement that rewards shortened length of stay through rapid stabilization protocols.
- Outpatient:Community mental health centers and private practice psychiatry represent the fastest-expanding channel as United States commercial payers unbundle pharmacy from medical benefits for long-acting injectables.
- Residential Treatment:Structured group home placements in Japan and the United Kingdom favor simplified dosing regimens that reduce medication management burden on non-specialist caregivers.
- Community Health:Federally qualified health centers in rural United States counties leverage expanded CMS telepsychiatry parity to replace institutional placement with remote psychiatric consultation models.
By patient volume, outpatient settings lead. By revenue intensity per episode, inpatient care remains ahead.
Age Group:
Customer type segmentation reflects developmental pharmacokinetics and regulatory complexity, with pediatric indications requiring extended EMA pediatric investigation plan negotiations.
- Adults:The core commercial population aged 18-65 drives formulation innovation and clinical trial enrollment, with integrated care models in the United Kingdom mandating physical health screening co-located with mental health services.
- Seniors:Late-onset schizophrenia and dementia-related psychosis presentations face heightened FDA cardiovascular safety profiling requirements that extend development timelines.
- Adolescents:Early intervention programs in academic medical centers attract investigator-initiated studies for novel glutamatergic pathway modulators entering Phase III trials.
- Children:Childhood-onset schizophrenia indications remain rare, with pharmacogenomic CYP2D6 testing lacking prospective trial evidence to guide antipsychotic selection outcomes.
By treatment volume, adults lead. By unmet need intensity, adolescent interventions are climbing fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. The United States emphasizes outpatient long-acting injectable administration, while Japan and Germany retain stronger institutional components. Emerging markets in Sub-Saharan Africa prioritize simplified oral regimens absent cold-chain infrastructure.
United States
Hospital systems in Texas and Florida consolidate behavioral health service lines under risk-bearing entities. CMS telepsychiatry reimbursement parity accelerates community-based care adoption in rural counties. The FDA's accelerated approval pathway for novel antipsychotic mechanisms reshapes clinical trial endpoint prioritization among developers.
Germany
Academic medical centers in Berlin and Munich pilot six-month implantable depot technologies for treatment-resistant cohorts. EMA pharmacovigilance requirements for metabolic safety monitoring extend post-approval label expansion timelines. The country's psychiatric research clusters concentrate Phase III enrollment for glutamatergic pathway modulators.
Japan
METI and MHLW reimbursement reforms shift payment from psychiatric hospital beds toward group home placement. Community-based care transitions favor long-acting formulations reducing medication management burden on non-specialist caregivers. Osaka and Nagoya psychiatric institutions drive adoption of simplified dosing regimens.
United Kingdom
The NHS Long Term Plan mandates physical health screening co-located with mental health services. Bundled reimbursement opportunities emerge for metabolic monitoring alongside antipsychotic administration. London and Manchester integrated care trusts pilot functional recovery metrics beyond symptom suppression endpoints.
India
Domestic API manufacturing concentration exposes supply continuity to environmental compliance enforcement variability. CDSCO regulatory pathways for novel formulations attract multinational licensing partnerships. Mumbai and Hyderabad contract research organizations expand investigator-initiated studies for heat-stable oral formulations.
Schizophrenia Treatment Market Competitive Environment
Capability concentration sits with large-cap pharmaceutical developers possessing integrated manufacturing and regulatory affairs infrastructure; scale advantage sits with mid-tier specialists commanding proprietary delivery technologies. The market structure tiers between diversified conglomerates with psychiatric franchises and focused biotechnology firms. Three archetypes dominate: long-acting formulation specialists, novel mechanism pioneers, and generic oral manufacturers. Consolidation activity concentrates on depot technology acquisitions and digital therapeutic partnerships.
Within the diversified pharmaceutical tier, Johnson & Johnson (Janssen) and Eli Lilly and Company occupy anchor positions through established psychiatric franchises. Alkermes plc exemplifies the delivery technology specialist archetype with proprietary controlled-release depot capabilities. These three entities represent distinct competitive vectors: conglomerate scale, R&D intensity, and manufacturing process differentiation.
| Leading Market Players |
|---|
| Johnson & Johnson (Janssen) |
| Eli Lilly and Company |
| Alkermes plc |
| Otsuka Pharmaceutical |
| AbbVie Inc. |
| AstraZeneca |
| Bristol-Myers Squibb |
| Sumitomo Pharma |
| Pfizer Inc. |
| Others |
Value Chain & Pricing Dynamics
Indian and Chinese contract manufacturers control over seventy percent of antipsychotic active pharmaceutical ingredient production, concentrating margin capture in long-acting injectable formulations where polymer engineering and depot technology create pricing power downstream. This upstream concentration forces branded developers to defend premium positioning through proprietary delivery systems rather than molecule novelty alone.
Pricing Analysis
Long-term offtake agreements between hospital systems and specialty pharmacy distributors dominate the United States channel, creating stable revenue visibility for depot formulations while spot purchasing persists in Medicaid generic substitution. Three-tier pricing structure across premium long-acting injectables, standard oral atypicals, and economy generic tablets separates Johnson & Johnson's paliperidone franchise from patent-expired risperidone. Price differentiation hinges on adherence monitoring bundling and metabolic screening service inclusion. Cost compression in oral generic tiers is intensifying because state Medicaid formularies mandate step-therapy protocols. Safety-net populations exhibit highest price sensitivity; Medicare Advantage plans with star rating incentives show lowest.
Supply Chain Analysis
Tariff exposure between the United States and China dominates pharmaceutical ingredient sourcing risk, compounded by environmental compliance enforcement variability at Indian API facilities. Active pharmaceutical ingredient manufacturing concentrates in India, China, and Italy for antipsychotic precursors. Formulation draws from biodegradable polymers, controlled-release excipients, and pre-filled syringe components. Single-source vulnerability sits with specialized polymer suppliers for six-month depot formulations. Distribution runs through cold-chain logistics for biologic-compatible injectables, direct-to-physician buy-and-bill for hospital-administered doses, and specialty pharmacy home delivery for outpatient long-acting regimens.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The schizophrenia treatment market is cycling through a recovery phase as CMS telepsychiatry reimbursement parity and FDA accelerated approval pathways restore investment momentum after generic erosion troughs.
For Market Incumbents: Harden formulary defense through backward integration into depot polymer manufacturing, reducing dependency on single-source excipient suppliers. Expand capacity in United States specialty pharmacy distribution to capture unbundled medical benefit administration from hospital systems. The threat of digital therapeutic adjuncts capturing prescription cognitive remediation revenue demands preemptive software partnership investments. For New Entrants and Emerging Players: Pursue WHO Mental Health Gap Action Programme implementation partnerships in Nigeria and Kenya, where simplified dosing regimens and heat-stable oral formulations address institutional capacity gaps. The Sub-Saharan Africa institutional channel represents the most penetrable geography absent established long-acting injectable infrastructure. A go-to-market angle anchored in non-cold-chain distribution and community health worker training programs bypasses incumbent depot technology advantages. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private-equity-backed delivery technology specialists possessing proprietary controlled-release depot capabilities but limited pipeline diversification. Five-to-ten year viability hinges on successful Phase III transitions for glutamatergic pathway modulators. The signal to watch is FDA breakthrough device designation precedents for prescription digital therapeutics, which would validate reimbursement bundling models and re-rate platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Depot Technology Acquisition | Proprietary polymer engineering secures six-month dosing intervals against generic erosion. |
| Digital Therapeutic Partnership | FDA breakthrough device designation creates reimbursement precedent for bundled cognitive intervention. |
| Sub-Saharan Africa Licensing | WHO programme implementation in Nigeria and Kenya opens heat-stable formulation demand. |
| Integrated Care Contracting | NHS Long Term Plan bundled reimbursement captures metabolic monitoring alongside antipsychotic administration. |
| Telepsychiatry Infrastructure Investment | CMS parity coverage in rural United States counties replaces institutional placement revenue streams. |
Study Parameters
A standing panel of drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers provided ongoing calibration against operating reality. Primary interview findings combined with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases. Bottom-up prescription volume modeling and top-down revenue triangulation anchored segmentation outputs.
Scenario-bracketing around CMS telepsychiatry reimbursement expansion velocity and FDA accelerated approval pathway utilization shaped the analytical framework across the analysis window. Segmentation dimensions modeled include treatment line, dosage form, administration route, patient population, and regional regulatory cluster. CAGRs derived from longitudinal adherence tracking and relapse-driven hospitalization frequency inputs.
Sensitivities concentrate around generic substitution acceleration in Medicaid populations and EMA pharmacovigilance timeline extensions for metabolic safety monitoring. Forecasts reflect assumptions on integrated care mandate implementation pace and digital therapeutic reimbursement precedent establishment. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Retroperitoneal Fibrosis Treatment Market
Specialty Medicine
Tinnitus Management Market
Specialty Medicine
Prostate Cancer Therapeutics Market
Specialty Medicine
Global Chronic Idiopathic Constipation Market
Specialty Medicine
Toxic Epidermal Neurolysis Market
Specialty Medicine
Chronic Obstructive Pulmonary Disease Therapeutics Market
Specialty Medicine
Gerontology/Aging Market
Specialty Medicine
Global Phenylketonuria Treatment Market
Specialty Medicine
Hairy Cell Leukemia Therapeutics Market
Specialty Medicine
Psychedelic Medicine Market
Specialty Medicine
Parathyroid Disorders Market
Specialty Medicine
Chemotherapy Induced Thrombocytopenia Market
Specialty Medicine
Pseudomonas Aeruginosa Treatment Market
Specialty Medicine
Global Myopia and Presbyopia Treatment Market
Specialty Medicine
Pituitary Stalk Interruption Syndrome Treatment Market
Specialty Medicine
Blastomycosis Treatment Market