
 Global Allergic Rhinitis Market | 2026-2036
Global Allergic Rhinitis Market Size, Share, and Industry Trends Forecast 2026-2036
Global Allergic Rhinitis Market Foresight
Fixed-dose combination packaging of antihistamines with intranasal corticosteroids is hardening as the default prescribing format in managed care settings. GSK plc. leverages its respiratory portfolio breadth to sustain formulary positioning across hospital and retail channels. Sanofi anchors its presence through dual-brand strategies that span both prescription and over-the-counter segments. Glenmark Pharmaceuticals Ltd. competes on cost-engineered oral tablet variants targeting pharmacy-dominant markets.
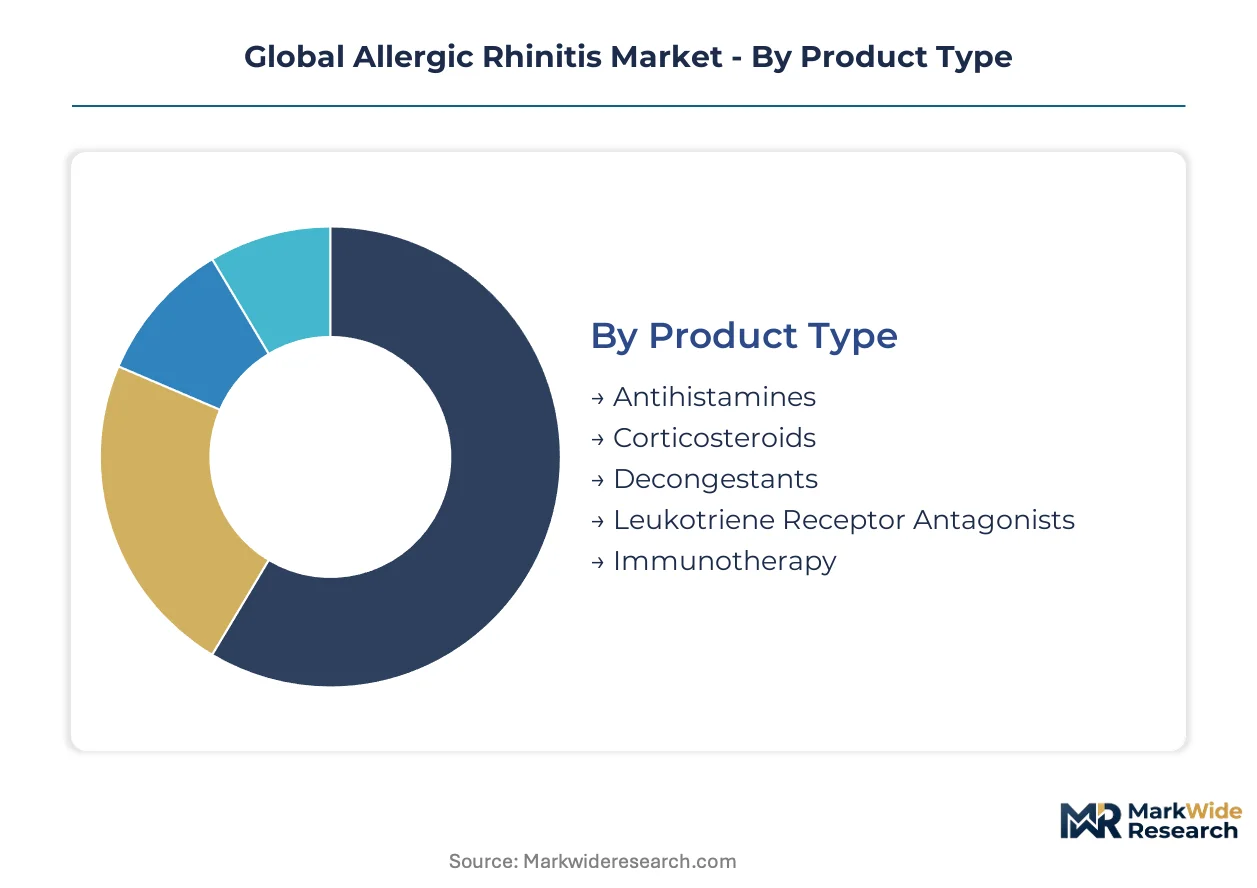
Allergic rhinitis is a type I hypersensitivity-mediated inflammatory condition of the nasal mucosa, characterized by IgE-driven mast cell degranulation and subsequent histamine, leukotriene, and prostaglandin release, with primary therapeutic objectives centered on symptom suppression and disease modification. Corticosteroids and antihistamines command the largest revenue pools, reflecting entrenched efficacy profiles and broad prescriber familiarity, while immunotherapy represents the fastest-expanding segment as sublingual tablet formulations reduce the treatment burden of injectable protocols. Nasal sprays retain dominant delivery share due to direct mucosal targeting, though oral tablets sustain volume leadership in pharmacy-directed self-care markets.
FDA, EMA, and Japan's PMDA each enforce distinct efficacy and safety benchmarks for intranasal products, with the FDA's bioequivalence requirements for generic corticosteroid sprays creating substantial barriers to abbreviated new drug approvals. The EU's MDR framework now demands enhanced clinical evidence for sublingual immunotherapy devices, extending development timelines for European market entrants. Stakeholders must weigh regulatory divergence against the margin advantages of platform technologies that satisfy multiple jurisdiction standards simultaneously.
Market Dynamics
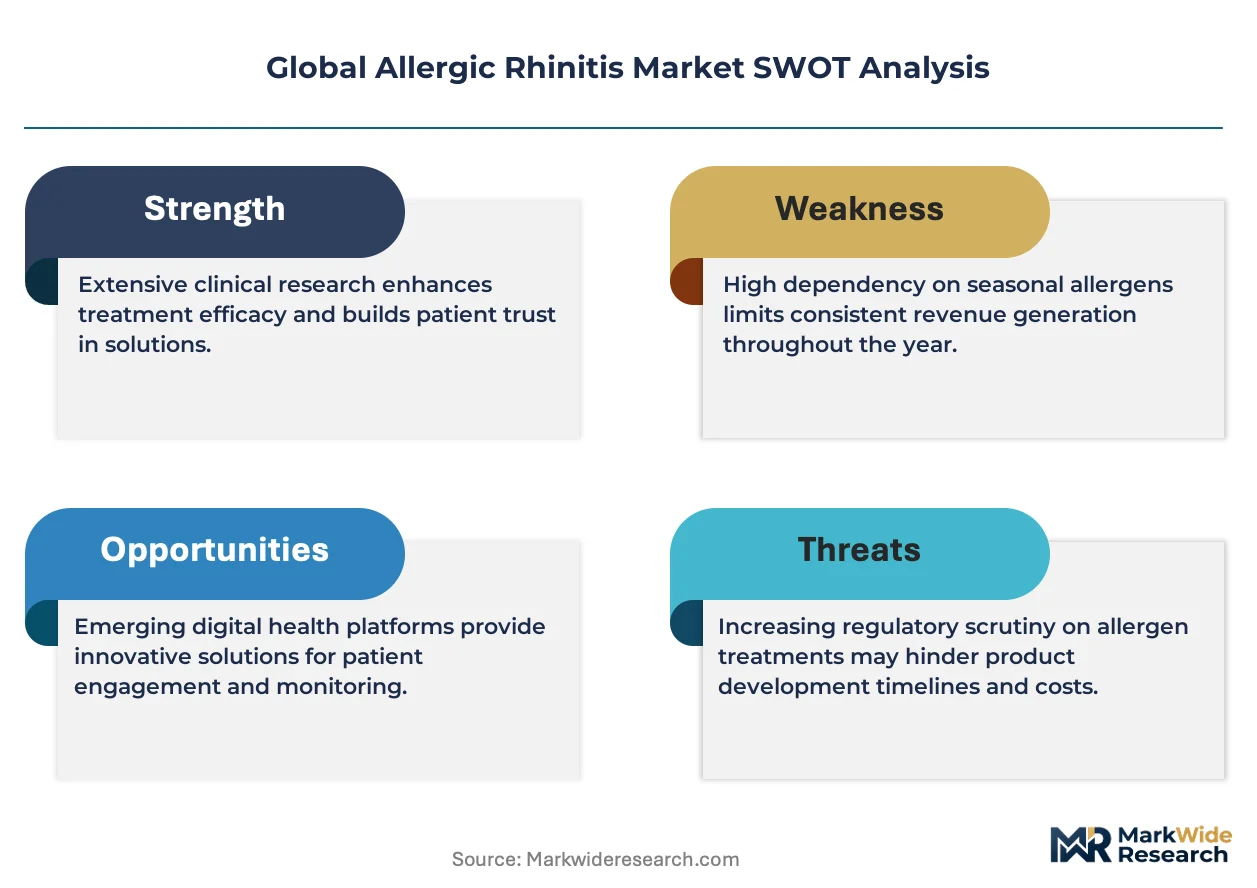
The FDA's accelerated approval pathways for biologic rhinitis therapies are compressing development timelines and forcing incumbents to restructure their clinical trial architectures around biomarker-driven endpoints rather than traditional symptom scores.
Growth Catalysts
- Sublingual Immunotherapy Tablets:Sublingual formulations eliminate injection burden and expand treatable patient pools beyond specialist clinic catchments. Germany's pediatric allergy centers now standardize these protocols.
- Japan's Cedar Pollen Dominance:Cedar pollen immunotherapy commands outpatient ENT practice in Japan, creating concentrated demand for seasonal dosing regimens and localized manufacturing capacity.
- EMA's MDR Framework Adaptation:Enhanced clinical evidence requirements for sublingual immunotherapy devices, while extending timelines, validate premium positioning for compliant platform technologies.
Market Restraints
- FDA Bioequivalence Barriers:The FDA's bioequivalence requirements for generic intranasal corticosteroid sprays block abbreviated new drug approvals, entrenching originator pricing power.
- Supply Concentration in Active Pharmaceutical Ingredients:Corticosteroid API production concentrates in Indian and Chinese contract manufacturers, exposing formulators to import inspection delays and geopolitical friction.
- Injectable Immunotherapy Limitations:Subcutaneous protocols require specialist administration infrastructure, restricting access in rural and primary care settings where allergist density is low.
Strategic Opportunities
- Pediatric Formulation Gaps:Taste-masked sublingual tablets for children under 12 remain underdeveloped, with regulatory precedents from PMDA and EMA creating pathway clarity for first entrants.
- Telehealth-Driven Prescription Flows:Virtual allergy consultations are rerouting patients from retail pharmacy self-selection to physician-directed biologic prescriptions, reshaping channel economics.
- Fixed-Dose Combination Packaging:Antihistamine-corticosteroid bundles in unit-dose formats align with managed care formulary compliance requirements and reduce patient adherence failure.
Industry Challenges
- Cross-Jurisdictional Regulatory Divergence:FDA, EMA, and PMDA maintain non-harmonized efficacy endpoints for intranasal products, forcing redundant clinical programs or geographic market sequencing.
- Biomarker Validation Complexity:IgE threshold standardization for patient stratification in biologic trials lacks consensus between academic consortia and regulatory agencies, delaying protocol finalization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Allergic Rhinitis Market |
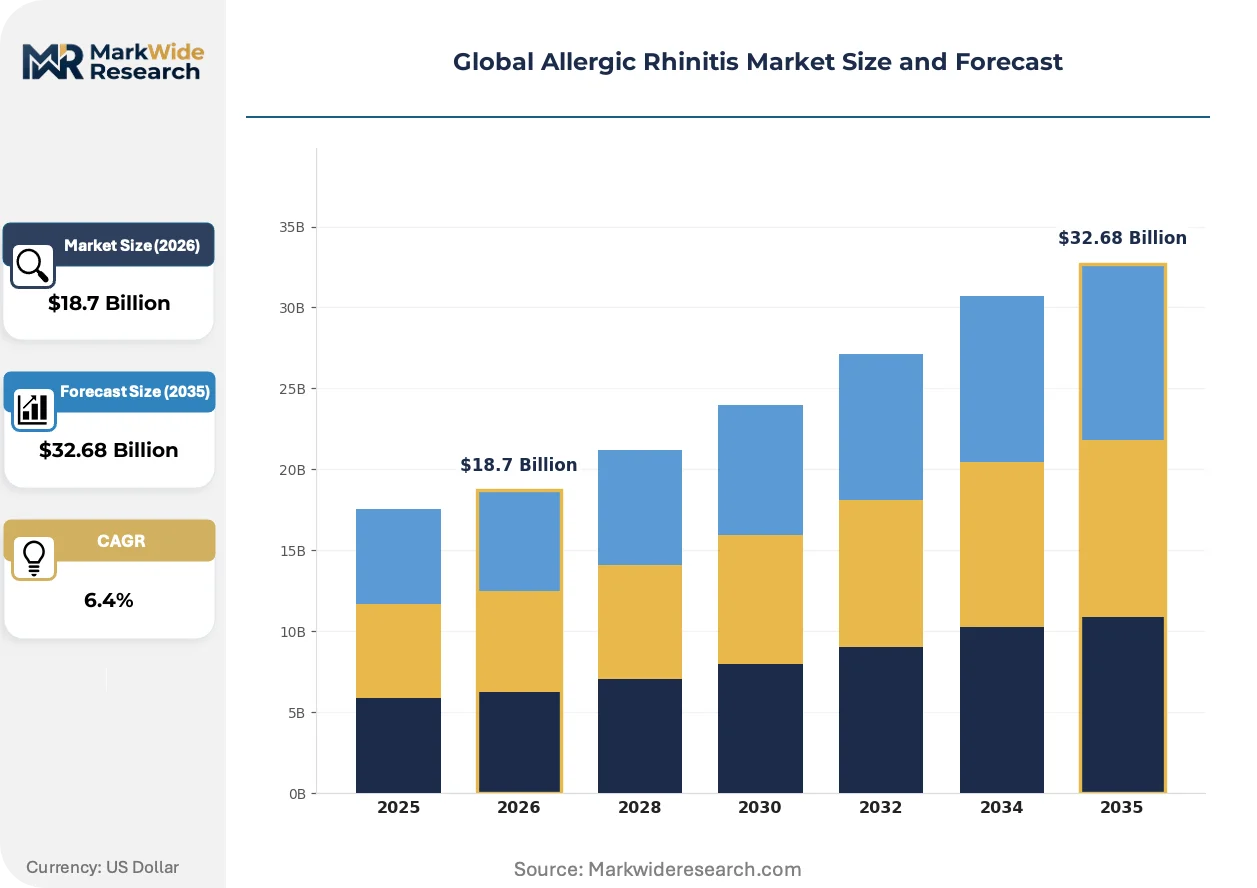
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antihistamines, Corticosteroids, Decongestants, Leukotriene Receptor Antagonists, Immunotherapy Therapy Area: Seasonal Allergic Rhinitis, Perennial Allergic Rhinitis, Occupational Rhinitis, Drug-Induced Rhinitis End User: Hospitals, Clinics, ENT Specialists, Allergy Centers, Pharmacies Delivery Mode: Nasal Sprays, Oral Tablets, Eye Drops, Injections, Nasal Drops |
| Companies Covered | GSK plc., Teva Pharmaceutical Industries Ltd., Merck & Co., Inc., Sanofi, Novartis AG, Boehringer Ingelheim International GmbH, Johnson & Johnson Services, Inc., Glenmark Pharmaceuticals Ltd., AstraZeneca, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Allergic Rhinitis Market Shifts & Advancements
Biologic mechanisms are penetrating allergic rhinitis treatment hierarchies previously dominated by small-molecule symptom suppressants, while formulation science and regulatory science evolve in parallel to accommodate precision immunology.
Sublingual immunotherapy tablets containing standardized allergen extracts are absorbing patient volumes from subcutaneous injection clinics by enabling home administration without anaphylaxis monitoring infrastructure. Primary care physicians in Germany and Japan are adopting these protocols for moderate-severity patients previously referred to specialists. This absorption is compressing the addressable market for injectable products and reallocating margin toward formulation and stability expertise rather than clinical service delivery.
The EU's Medical Device Regulation now mandates enhanced clinical evidence for sublingual immunotherapy delivery systems, extending development timelines for European market entrants by 18-24 months relative to prior directives. Device manufacturers must demonstrate bioavailability equivalence and patient handling safety under real-use conditions. Sublingual tablet developers with existing MDR-compliant dossiers are leveraging this friction to defend positioning against later entrants.
Self-directed pharmacy purchasing of oral antihistamines is fragmenting as managed care formularies harden around prescription-grade intranasal corticosteroids with demonstrated adherence monitoring. Pharmacy benefit managers in the United States are deploying step-therapy protocols that require documented generic antihistamine failure before approving branded nasal spray coverage. This behavioral shift is most visible in employer-sponsored insurance plans, where absenteeism reduction metrics drive preference toward sustained symptom control over acute relief.
Global Allergic Rhinitis Market Segmentation
Allergic rhinitis treatment pathways diverge sharply across patient severity, prescriber setting, and reimbursement access. Understanding these segment boundaries reveals where formulation innovation and channel strategy unlock margin.
Product Type:
Prescribers cycle through product classes based on symptom persistence and prior response failure, with each upgrade path carrying distinct reimbursement and adherence economics.
- Antihistamines:First-generation compounds block H1 receptors peripherally but cross the blood-brain barrier, while second- and third-generation variants reduce sedation liability. Pharmacy-directed self-care in Germany and Japan absorbs the largest volumes, though step-therapy protocols in US managed care are pushing patients toward intranasal alternatives faster.
- Corticosteroids:Intranasal formulations suppress multiple inflammatory mediators through genomic and non-genomic glucocorticoid receptor activation. ENT specialists in Japanese cedar pollen corridors and US allergy centers prescribe these as maintenance therapy, with adherence monitoring now embedded in employer-sponsored benefit designs.
- Decongestants:Alpha-adrenergic agonists provide rapid nasal patency through mucosal vasoconstriction. Rebound congestion limits duration of use to three days in most regulatory jurisdictions.
- Leukotriene Receptor Antagonists:Oral montelukast-class agents interrupt cysteinyl leukotriene signaling for patients with comorbid asthma. FDA black-box warnings for neuropsychiatric events have constrained pediatric prescribing in the United States.
- Immunotherapy:Sublingual tablets and subcutaneous injections modify disease course through allergen-specific tolerance induction. Germany's pediatric allergy centers and Japan's outpatient ENT practices are standardizing sublingual protocols, displacing injection burden.
Corticosteroids sit at the top of the volume ranking, with immunotherapy climbing the fastest.
Therapy Area:
Duration and trigger predictability shape treatment intensity, with seasonal patterns enabling pre-emptive dosing and perennial cases demanding year-round maintenance.
- Seasonal Allergic Rhinitis:IgE-mediated responses to tree, grass, or ragweed pollen concentrate morbidity into discrete calendar windows. Japanese cedar pollen corridors generate concentrated demand for sublingual immunotherapy with precisely timed initiation protocols.
- Perennial Allergic Rhinitis:Continuous exposure to house dust mites, pet dander, or mold spores produces persistent symptoms requiring daily pharmacologic control. German allergy centers report higher biologic referral rates for this population due to corticosteroid resistance.
- Occupational Rhinitis:High-molecular-weight proteins and low-molecular-weight chemicals trigger workplace-specific sensitization. Compensation frameworks in France and Germany determine whether treatment costs fall on employers or statutory health insurance.
- Drug-Induced Rhinitis:Rhinitis medicamentosa from decongestant overuse and other iatrogenic forms require withdrawal protocols rather than intensified therapy.
Seasonal allergic rhinitis dominates prescription volumes, though perennial cases generate the steepest per-patient revenue trajectories.
End User:
Site-of-care migration is redrawing prescriber influence, with telehealth platforms capturing triage decisions previously owned by retail pharmacists.
- Hospitals:Emergency departments manage acute decompensations and anaphylaxis-adjacent presentations. Admission criteria hinge on respiratory compromise rather than rhinitis severity alone.
- Clinics:Primary care physicians initiate step-therapy protocols and handle routine exacerbations. Germany's Hausarzt-centered gatekeeping system concentrates first-line prescribing in this channel.
- ENT Specialists:Otolaryngologists manage refractory cases with structural complications or surgical candidacy. Japan's cedar pollen corridors have embedded immunotherapy administration deeply in ENT outpatient practice.
- Allergy Centers:Specialist immunologists conduct skin testing, initiate desensitization, and prescribe biologics. Pediatric-focused centers in Munich and Hamburg are expanding sublingual tablet adoption.
- Pharmacies:Self-directed purchasing of oral antihistamines persists in markets with limited prescription requirements. US pharmacy benefit managers are compressing this channel through formulary step-therapy mandates.
Pharmacies retain the largest patient touchpoint count, with allergy centers expanding most quickly.
Delivery Mode:
Formulation selection balances onset speed, mucosal targeting precision, and patient handling competence across age groups.
- Nasal Sprays:Pump-actuated aqueous or aerosol suspensions deposit active ingredient directly onto inflamed mucosa. FDA bioequivalence requirements for generic corticosteroid sprays have blocked abbreviated approvals, preserving originator pricing.
- Oral Tablets:Systemic absorption enables symptom control without patient technique dependency. Pharmacy-dominant markets in India and Brazil sustain volume leadership for this format.
- Eye Drops:Topical antihistamine or mast cell stabilizer formulations address the ocular component of allergic conjunctivitis-rhinitis syndrome.
- Injections:Subcutaneous immunotherapy and biologic monoclonals require specialist administration infrastructure. Rural access limitations are compressing addressable volume toward urban allergy centers.
- Nasal Drops:Liquid instillations suit infants and patients with anatomical variations preventing spray penetration. Compliance challenges limit adoption beyond pediatric and geriatric niches.
Nasal sprays command the highest value per unit, with injections gaining share fastest among severe refractory populations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Allergic rhinitis therapeutics originated in European university clinics during the 1950s, with subcutaneous immunotherapy protocols first standardized in British and German research hospitals before pharmaceutical industrialization transferred manufacturing scale to the United States and Japan.
United States
Employer-sponsored insurance plans now embed adherence monitoring for intranasal corticosteroids, redirecting pharmacy self-care toward prescription-grade maintenance therapy. FDA bioequivalence requirements for generic nasal sprays preserve originator pricing power and compress abbreviated approval volumes. The Southeast corridor from Atlanta to Raleigh concentrates allergy center density where biologic referral rates climb fastest.
Germany
Pediatric allergy centers in Munich and Hamburg have standardized sublingual immunotherapy tablets, displacing injection burden for moderate-severity patients. EMA's MDR framework demands enhanced clinical evidence for sublingual delivery systems, extending European development timelines. The Bavarian cluster around Munich anchors the country's immunotherapy protocol development and specialist training density.
Japan
Cedar pollen immunotherapy commands outpatient ENT practice, creating concentrated demand for precisely timed seasonal dosing regimens. PMDA regulatory precedents for pediatric sublingual formulations provide pathway clarity for taste-masked tablet developers. The Kanto region surrounding Tokyo embeds the highest specialist density for pollen-specific desensitization administration.
India
Pharmacy-directed markets sustain volume leadership for cost-engineered oral antihistamine tablets, with urban self-care penetration outpacing prescription conversion. CDSCO import inspection protocols for corticosteroid APIs expose formulators to supply friction from Chinese contract manufacturers. The Mumbai-Pune corridor concentrates domestic formulation capacity and distribution infrastructure.
United Kingdom
General practitioner gatekeeping concentrates first-line prescribing in primary care clinics, with referral thresholds to allergy specialists rising under NHS cost-containment pressure. MHRA alignment with EMA immunotherapy device standards streamlines dossier preparation for European market entrants. The Greater Manchester cluster hosts the NHS's largest respiratory research network and pediatric allergy trial recruitment.
Global Allergic Rhinitis Market Competitive Landscape
Premium-margin players sit above commodity-margin players across formulation complexity and regulatory dossier depth, with originator intranasal corticosteroids commanding price multiples over generic oral antihistamines. The vendor base stratifies into three archetypes: respiratory portfolio conglomerates leveraging formulary breadth, dual-brand strategists spanning prescription and over-the-counter channels, and cost-focused tablet specialists targeting pharmacy-dominant emerging markets. Consolidation pressure concentrates among mid-scale immunotherapy developers seeking MDR-compliant device platforms, while capacity expansion targets sublingual tablet manufacturing for German and Japanese demand corridors.
Within the respiratory portfolio tier, GSK plc. and Sanofi occupy positions defined by formulary anchoring across hospital and retail channels, with Sanofi's dual-brand architecture exemplifying prescription-to-consumer span. Glenmark Pharmaceuticals Ltd. represents the cost-engineered tablet archetype, competing on pharmacy-channel price positioning in volume-driven markets. These three entities illustrate the competitive divergence between premium-formulation defense and commodity-scale penetration.
| Leading Market Players |
|---|
| GSK plc. |
| Teva Pharmaceutical Industries Ltd. |
| Merck & Co., Inc. |
| Sanofi |
| Novartis AG |
| Boehringer Ingelheim International GmbH |
| Johnson & Johnson Services, Inc. |
| Glenmark Pharmaceuticals Ltd. |
| AstraZeneca |
| Others |
Supply & Pricing Matrix
Managed care formularies in the United States anchor pricing power for originator intranasal corticosteroids, compressing generic substitution through FDA bioequivalence barriers that preserve premium positioning against pharmacy-channel oral antihistamines.
Pricing Analysis
Three-tier pricing structure across originator intranasal sprays, branded oral tablets, and generic antihistamines stratifies the market by prescriber access and reimbursement tier. Price differentiation hinges on FDA bioequivalence certification status and formulary placement depth within employer-sponsored benefit designs. Pricing pressure stems from step-therapy protocols pushing patients toward lower-cost oral generics before branded nasal spray approval. Pharmacy-directed self-care segments exhibit highest price sensitivity, while hospital and allergy center channels absorb premium positioning with minimal elasticity.
Supply Chain Analysis
EMA MDR certification and FDA bioequivalence dossiers gate European and North American market access for sublingual immunotherapy devices and intranasal spray manufacturers. Corticosteroid active pharmaceutical ingredient production concentrates in India and China, with formulation finishing distributed across Germany, Japan, and the United States. Supply chains draw from specialized allergen extract cultivation facilities in Northern Europe and standardized chemical synthesis operations in Asian contract manufacturing hubs. Single-source vulnerability in Indian API production exposes formulators to CDSCO import inspection delays. Distribution runs through hospital procurement systems, retail pharmacy networks, and direct-to-specialist channels for immunotherapy products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The allergic rhinitis market compounds steadily through immunotherapy conversion from symptom suppression to disease modification, with sublingual tablet formulations capturing patient volumes previously managed through chronic pharmaceutical use.
For Market Incumbents: Cement formulary anchoring through fixed-dose combination packaging that satisfies managed care adherence monitoring requirements, while building backward integration into corticosteroid API production to mitigate Indian and Chinese supply concentration risks. Prioritize MDR-compliant device platforms for European sublingual immunotherapy defense against later entrants facing extended approval timelines. For New Entrants and Emerging Players: Pediatric patients under 12 represent the most penetrable white-space segment, with taste-masked sublingual tablets lacking regulatory precedents despite PMDA and EMA pathway clarity for first movers. Target telehealth-directed prescription flows that reroute patients from pharmacy self-selection toward physician-managed biologic initiation, using virtual allergy consultation platforms as the primary go-to-market channel. For Investors and Strategic Acquirers: Respiratory portfolio conglomerates are the most active acquirer in this space, seeking MDR-compliant sublingual tablet platforms to fill immunotherapy gaps. The market supports long-term viability through chronic disease prevalence and therapy escalation patterns from antihistamines to corticosteroids to biologics. Watch FDA biomarker-driven endpoint standardization for biologic trials as the signal indicating accelerated approval pathway maturation and competitive restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| MDR-Compliant Device Development | EMA's enhanced clinical evidence requirements extend timelines but validate premium positioning for compliant sublingual platforms. |
| Fixed-Dose Combination Packaging | Antihistamine-corticosteroid bundles align with US employer-sponsored plan adherence monitoring and step-therapy protocols. |
| Pediatric Formulation Development | PMDA and EMA regulatory precedents create pathway clarity for taste-masked sublingual tablets targeting the under-12 segment. |
| Telehealth Platform Integration | Virtual allergy consultations reroute patients from pharmacy self-care toward physician-directed biologic prescriptions. |
| API Supply Security Investment | Backward integration into corticosteroid active pharmaceutical ingredient production mitigates Indian and Chinese concentration risk. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with drug development executives, regulatory affairs leads, formulary directors at pharmacy benefit managers, and ENT specialists in German and Japanese treatment centers with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases. Bottom-up patient volume modeling and top-down revenue triangulation cross-checked segment estimates across therapy lines and administration routes.
Comparable historical periods anchored the projection horizon, with analytical frameworks modeling patient flow from first-line antihistamines through corticosteroid escalation to immunotherapy and biologic conversion across seasonal and perennial disease phenotypes. CAGRs were derived from segmented growth rate aggregation, incorporating immunotherapy adoption curves, generic penetration limits imposed by FDA bioequivalence requirements, and regional regulatory cluster differentiation between FDA, EMA, and PMDA jurisdictions.
Inputs from clinical trial registries and formulary databases were available through the study window; gaps in real-world adherence monitoring data and telehealth prescription flow quantification introduce uncertainty bands around channel shift assumptions. Forecasts reflect documented assumptions regarding immunotherapy conversion rates and biologic eligibility expansion. A model refresh is warranted upon material change in FDA biomarker endpoint standardization or EMA MDR enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Mental Retardation Treatment Market
Specialty Medicine
Hereditary Angioedema Market
Specialty Medicine
Ovarian Cancer Therapeutics Market
Specialty Medicine
Thyroid Cancer Therapeutics Market
Specialty Medicine
Bulimia Nervosa Market
Specialty Medicine
Global Actinic Keratosis Treatment Market
Specialty Medicine
Global Occupational Medicines Market
Specialty Medicine
Axial Spondyloarthritis Treatment Market
Specialty Medicine
Pharyngitis Treatment Market
Specialty Medicine
Global Pemphigus Vulgaris Market
Specialty Medicine
Global Hypoparathyroidism Treatment Market
Specialty Medicine
Idiopathic Pulmonary Fibrosis (IPF) Market
Specialty Medicine
Eosinophilia Therapeutics Market
Specialty Medicine
Fibroadenoma Market
Specialty Medicine
Polyarticular Juvenile Idiopathic Market
Specialty Medicine
Bronchiectasis Therapeutic Market