
 Europe Precision Medicine Market | 2026-2036
Europe Precision Medicine Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Precision Medicine Market Insights
The EU Green Deal is hardening carbon-accounting requirements across pharmaceutical supply chains. Roche leverages captive manufacturing of sequencing consumables to sustain margin control. Thermo Fisher Scientific anchors its European position through regional distribution hubs in Switzerland and the Netherlands.
Precision medicine deploys patient-specific molecular profiling to guide therapeutic selection, using genomic sequencers that detect single-nucleotide variants at coverage depths exceeding 30x. Diagnostic Tests command the largest revenue pool due to recurring ordering patterns in hospital laboratories. Bioinformatics represents the fastest-expanding technology segment as cloud-based variant interpretation displaces on-premise pipelines.
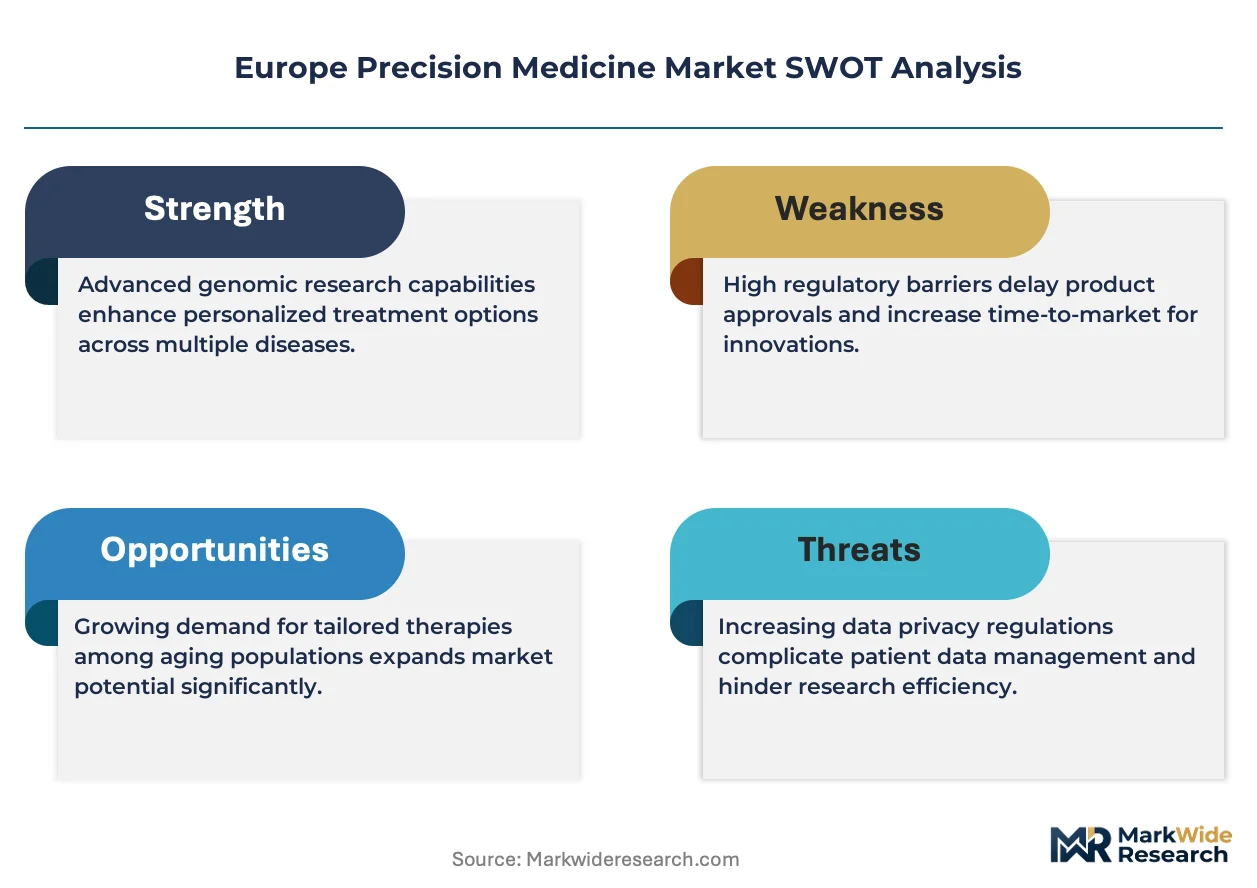
EMA's centralized marketing authorization for advanced therapy medicinal products shapes product development timelines, while GDPR constrains cross-border genomic data transfers between member states. The EU AI Act imposes conformity requirements on diagnostic algorithms that clinicians must integrate. Stakeholders must monitor how national reimbursement bodies calibrate precision diagnostic tariffs against standard-of-care benchmarks.
Market Dynamics
The EU AI Act is restructuring how algorithmic diagnostic tools enter clinical workflows, forcing developers to pre-certify decision-support systems before hospital procurement teams can adopt them. This regulatory inflection point is compressing product development timelines while elevating compliance costs across the value chain.
Growth Catalysts
- Oncology Hospital Networks:France's regional cancer centers are consolidating molecular profiling into standardized care pathways, creating recurring demand for companion diagnostic testing.
- EMA Centralized Authorization:The streamlined marketing approval for advanced therapy medicinal products is accelerating cell and gene therapy launches across member states.
- Cloud-Based Variant Interpretation:Bioinformatics platforms are displacing on-premise pipelines in hospital laboratories, reducing infrastructure overhead while expanding analytical throughput.
Market Restraints
- GDPR Cross-Border Friction:Genomic data transfer restrictions between member states fragment multi-center clinical trials and delay biomarker discovery programs.
- Sequencing Consumable Concentration:Captive manufacturing of reagents and flow cells by dominant suppliers limits price competition and creates supply vulnerability.
- Reimbursement Calibration Lag:National health technology assessment bodies apply standard-of-care benchmarks to precision diagnostics, compressing tariff margins below innovation costs.
Strategic Opportunities
- Eastern European Hospital Digitization:Poland and Romania are deploying EU cohesion funds to modernize pathology infrastructure, creating first-mover advantages for integrated diagnostic platforms.
- EU Green Deal Supply Chain Mandates:Carbon-accounting requirements for pharmaceutical logistics are favoring regional distribution hubs over intercontinental supply chains.
- AI-Enabled Remote Pathology:The convergence of digital slide scanning and machine learning classification is enabling hub-and-spoke laboratory networks in underserved regions.
Industry Challenges
- Bioinformatics Talent Scarcity:Clinical laboratories face acute shortages of variant scientists capable of interpreting complex genomic signatures under diagnostic-grade quality standards.
- MDR Certification Timelines:In vitro diagnostic manufacturers confront extended conformity assessment periods that delay product launches and freeze R&D roadmaps.
- Legacy LIS Integration Complexity:Hospital information systems require costly middleware development to ingest molecular diagnostic results into electronic health records.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Precision Medicine Market |
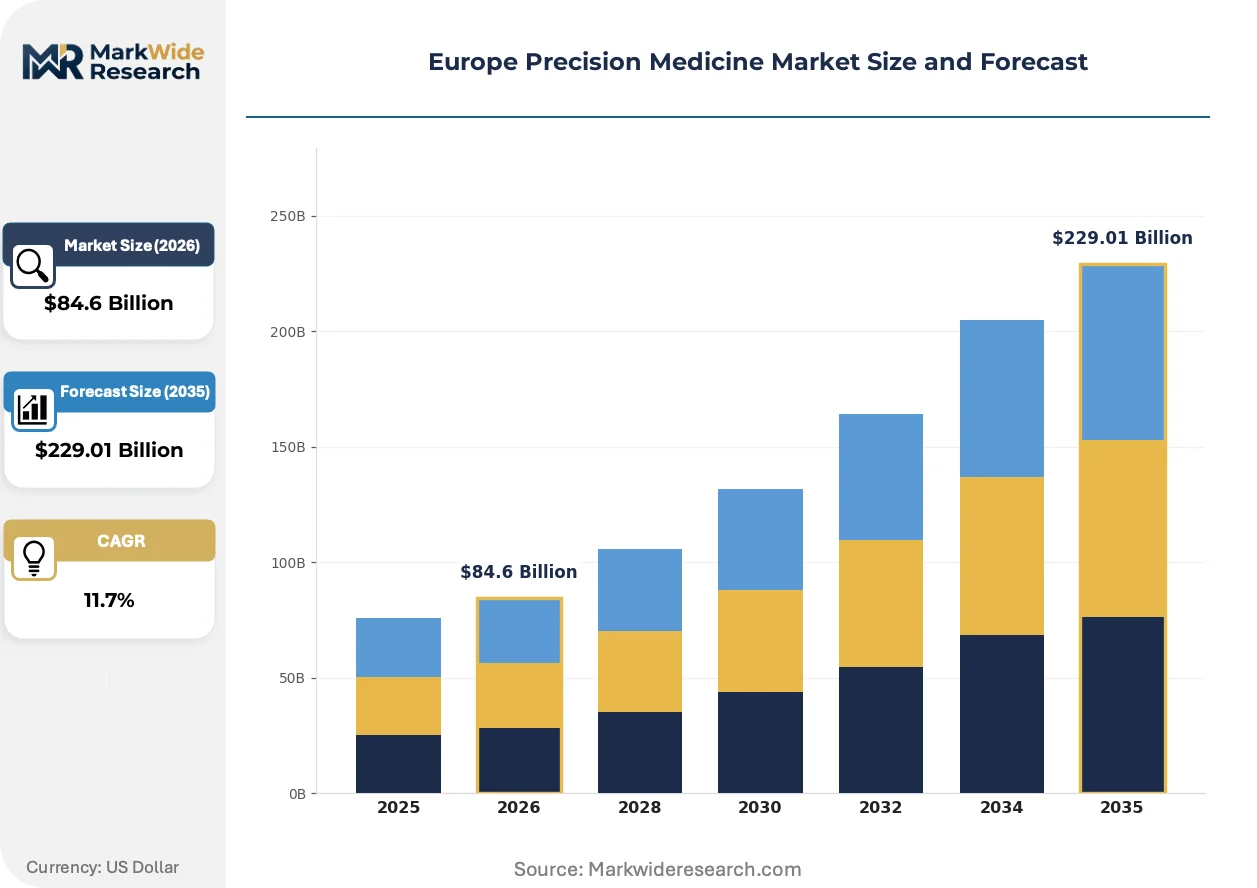
| Market Size in 2026 | $84.6 Billion |
| Market Size in 2035 | $229.01 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Tests, Therapeutics, Genomic Sequencers, Biomarkers Technology: NGS, Bioinformatics, Imaging, Analytical Platforms Application: Oncology, Neurology, Rare Diseases, Cardiovascular End User: Hospitals, Research Institutes, Pharmaceutical Companies, Diagnostic Labs |
| Companies Covered | Roche, QIAGEN N.V., Thermo Fisher Scientific, AstraZeneca PLC, Novartis, Illumina, Abbott, Philips, SOPHiA GENETICS SA, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Precision Medicine Market Trends and Innovations
Cloud-native bioinformatics is redrawing competitive boundaries in molecular diagnostics. Three interconnected developments are compressing analytical turnaround times while expanding access to complex genomic interpretation across European healthcare systems.
Next-generation sequencing platforms are decentralizing variant analysis from centralized academic centers into community hospital laboratories. Mid-sized pathology departments in Germany and the Netherlands are adopting benchtop sequencers with integrated cloud pipelines, collapsing the historical two-week send-out turnaround to 72-hour in-house reporting. This geographic compression of analytical capability is eroding the referral-based revenue models of national sequencing hubs.
The EU AI Act's conformity requirements are reshaping algorithmic clinical decision tools. Developers must now document training data provenance and algorithmic transparency before CE marking, elevating documentation burdens while excluding black-box models from reimbursable care pathways. Oncology decision-support systems face the steepest compliance ramps, with French and German notified bodies applying the strictest interpretive standards.
Hospital procurement teams are consolidating molecular diagnostic contracts under multi-year partnership frameworks. Single-source agreements covering instruments, consumables, and bioinformatics subscriptions are displacing transactional reagent purchasing in France's public hospital networks. This vendor consolidation concentrates purchasing power while locking laboratories into proprietary analytical ecosystems, with the tightest contract terms appearing in Paris and Lyon metropolitan clusters.
Europe Precision Medicine Market Segmentation
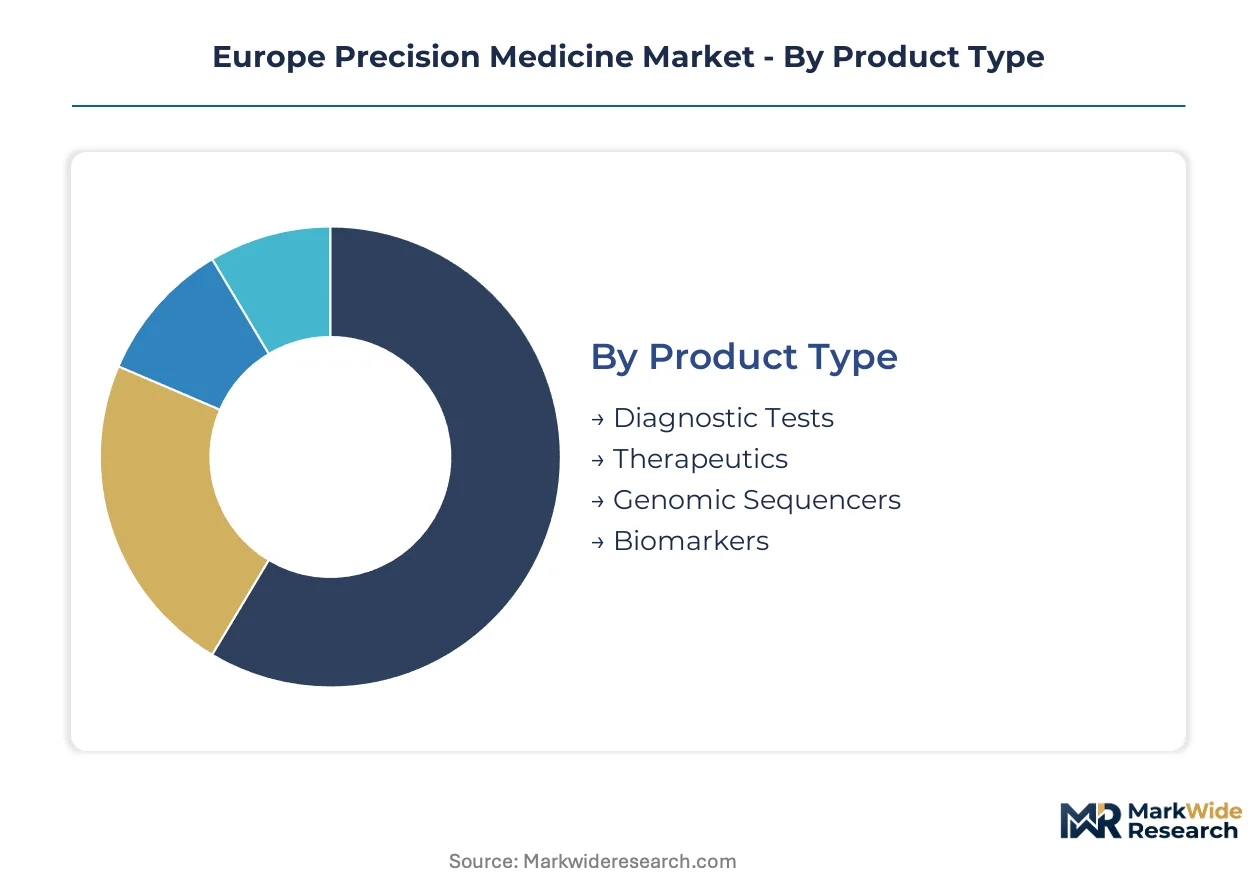
Segmentation in Europe's precision medicine market reveals divergent capital requirements and margin profiles across the value chain. Diagnostic platforms demand heavy upfront instrument investment while bioinformatics layers generate recurring software revenues with minimal marginal cost.
Product Type:
Capital intensity varies dramatically across product categories, with sequencing infrastructure requiring the heaviest fixed-asset deployment.
- Diagnostic Tests:Recurring reagent-based testing generates stable revenue streams in hospital laboratories. France's regional cancer centers are consolidating companion diagnostic ordering into standardized pathways, creating predictable demand cycles for molecular profiling panels.
- Genomic Sequencers:High-throughput sequencing platforms represent the largest capital outlay per installation. German pathology departments are prioritizing benchtop systems with integrated cloud pipelines to collapse turnaround times from weeks to days.
- Therapeutics:Patient-specific cell and gene therapies command premium pricing under EMA centralized authorization pathways.
- Biomarkers:Proprietary biomarker signatures enable differentiated therapeutic positioning and companion diagnostic pairing.
Diagnostic Tests absorb the bulk of installed capacity; Bioinformatics is expanding most quickly.
Technology:
Technology layers stratify by infrastructure dependency, with cloud-native solutions displacing on-premise hardware.
- NGS:Next-generation sequencing platforms detect single-nucleotide variants at coverage depths exceeding 30x. Mid-sized laboratories in the Netherlands are adopting integrated benchtop sequencers to bring analysis in-house from academic referral centers.
- Bioinformatics:Cloud-based variant interpretation pipelines reduce infrastructure overhead while expanding analytical throughput. GDPR constraints on cross-border genomic data transfers fragment multi-center deployment architectures.
- Imaging:Digital pathology and radiomics integrate molecular signatures with morphological assessment.
- Analytical Platforms:Integrated hardware-software systems bundle sequencing with interpretation workflows.
NGS retains the deepest installed base; Bioinformatics is climbing the fastest.
Application:
Clinical applications concentrate demand differently across European healthcare systems, with oncology commanding the most mature reimbursement frameworks.
- Oncology:Solid tumor and hematological malignancy profiling dominates molecular diagnostic volumes. French hospital networks are embedding companion diagnostic testing into first-line treatment protocols for lung and colorectal cancers.
- Rare Diseases:Exome and genome sequencing accelerates diagnostic odyssey resolution for undiagnosed genetic conditions. National health systems in Germany and France have established dedicated rare disease centers with centralized sequencing access.
- Neurology:Neurodegenerative and neurodevelopmental disorder profiling expands as biomarker validation matures.
- Cardiovascular:Pharmacogenomic testing for anticoagulant and statin response remains underpenetrated relative to oncology.
Oncology captures the dominant revenue share; Rare Diseases is gaining share fastest.
End User:
Customer types exhibit divergent procurement patterns, with hospital networks consolidating purchasing power under multi-year framework agreements.
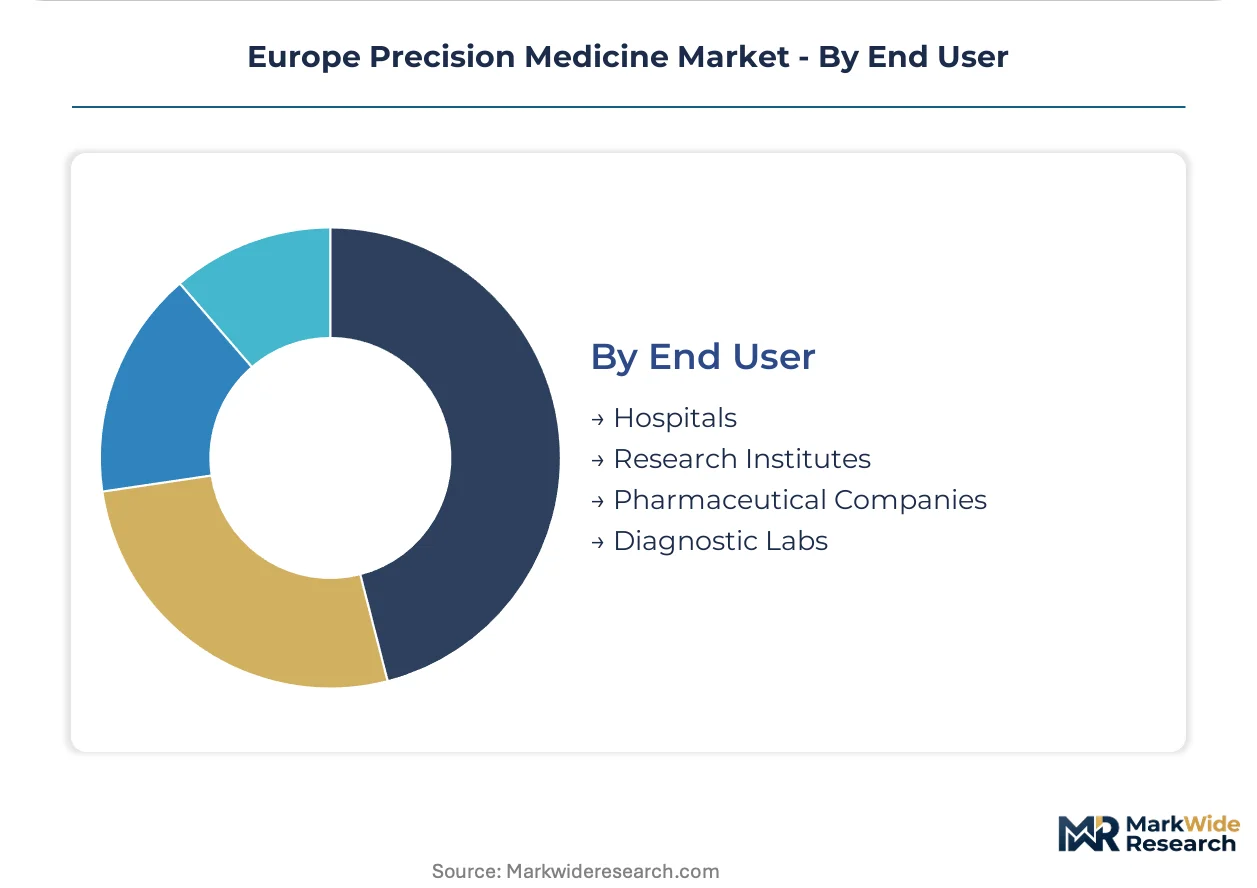
- Hospitals:Public hospital networks in France and Germany are consolidating molecular diagnostic contracts under single-source partnerships covering instruments, consumables, and bioinformatics subscriptions.
- Pharmaceutical Companies:Drug developers deploy companion diagnostics to stratify patient populations and secure EMA marketing authorization. German pharmaceutical manufacturers are accelerating in-house sequencing capabilities to control biomarker discovery timelines.
- Research Institutes:Academic medical centers drive technology adoption ahead of clinical translation.
- Diagnostic Labs:Independent reference laboratories compete on turnaround time and specialized assay menus.
Hospitals command the largest procurement volumes; Pharmaceutical Companies are deepening investment fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of sequencing consumables and diagnostic instruments concentrates in Switzerland and the Netherlands, while clinical consumption spreads across hospital networks in Germany, France, and the United Kingdom. This geographic split shapes procurement patterns and regulatory compliance burdens differently across member states.
Germany
Bavaria and Baden-Württemberg host dense clusters of pharmaceutical manufacturers accelerating in-house companion diagnostic capabilities. The country's national pharmaceutical regulator, the Federal Institute for Drugs and Medical Devices, enforces strict MDR certification timelines that compress product launch windows. Berlin-Brandenburg anchors public-private sequencing partnerships linking Charité hospital networks with industrial biotech zones.
France
Île-de-France and Lyon metropolitan clusters concentrate oncology hospital networks embedding molecular profiling into standardized lung and colorectal cancer pathways. ANSM and CNIL jointly oversee diagnostic algorithm transparency requirements under the EU AI Act. The Gustave Roussy institute in Villejuif drives companion diagnostic adoption into first-line treatment protocols.
United Kingdom
Greater London and Cambridge biotech corridors concentrate genomic medicine research translation into NHS hospital procurement. The Medicines and Healthcare products Regulatory Agency aligns post-Brexit device regulations with retained EU MDR frameworks. Genomics England's 100,000 Genomes Project infrastructure in Cambridge sustains rare disease sequencing demand.
Netherlands
The Randstad region anchors Thermo Fisher Scientific's European distribution hub serving sequencing consumables across the continent. Dutch pathology laboratories in Utrecht and Rotterdam lead benchtop sequencer adoption with integrated cloud bioinformatics pipelines. The Healthcare Inspectorate enforces GDPR-compliant genomic data handling in multi-center research networks.
Switzerland
Basel and Zurich metropolitan areas concentrate captive manufacturing of sequencing reagents and flow cells sustaining margin control for dominant suppliers. Swissmedic maintains independent marketing authorization pathways that parallel EMA centralized procedures. Roche's manufacturing footprint in Basel shapes regional supply chain resilience for European diagnostic markets.
Europe Precision Medicine Market Competitive Landscape
The competitive structure tilts toward integrated diagnostic-therapeutic conglomerates with captive supply chains and specialized bioinformatics platform developers. Tier-one players combine instrument manufacturing with recurring consumable revenue streams, while mid-tier specialists compete on cloud-native variant interpretation speed. Strategic moves concentrate on M&A for biomarker portfolios and strategic partnerships for AI-enabled diagnostic algorithms.
Among Switzerland-based conglomerates, Roche exemplifies the vertically integrated archetype spanning sequencing consumables through clinical decision support. Thermo Fisher Scientific occupies a similar position through regional distribution hub control. SOPHiA GENETICS SA represents the cloud-native specialist tier with hospital-focused bioinformatics platforms.
| Leading Market Players |
|---|
| Roche |
| QIAGEN N.V. |
| Thermo Fisher Scientific |
| AstraZeneca PLC |
| Novartis |
| Illumina |
| Abbott |
| Philips |
| SOPHiA GENETICS SA |
| Others |
Pricing and Supply Chain Analysis
Cloud-native bioinformatics pipelines are collapsing infrastructure costs for mid-sized hospital laboratories while simultaneously concentrating purchasing power under multi-year framework agreements. This technology transition simultaneously erodes price premiums for on-premise sequencing systems and locks laboratories into proprietary consumable ecosystems.
Pricing Analysis
Margin tightening in diagnostic consumables reflects captive manufacturing concentration among dominant suppliers controlling reagent and flow cell production. Three-tier pricing structure across premium, standard, and economy levels stratifies by throughput capacity and bioinformatics integration depth. Cost-down pressure on mid-tier benchtop systems accelerates because hospital procurement teams are consolidating contracts under single-source partnerships. Community pathology laboratories exhibit the highest price sensitivity, while national sequencing hubs prioritize analytical performance over unit economics.
Supply Chain Analysis
Regional distribution centers in Switzerland and the Netherlands anchor sequencing consumable logistics across European hospital networks. Captive manufacturing of flow cells and reagents concentrates in Basel and Zurich metropolitan clusters, with downstream distribution running through Thermo Fisher Scientific's Randstad hub. Supply chain vulnerability hinges on single-source dependencies for specialized polymerases and optical detection components. Just-in-time reagent replenishment models dominate procurement, compressing inventory buffers and amplifying disruption risk from logistics chokepoints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sequencing consumable manufacturing capacity constraints prop pricing power for incumbent suppliers, creating defensive moats around installed instrument bases.
For Market Incumbents: Cement market position through backward integration into specialty reagent production and exclusive bioinformatics platform development. Consolidate purchasing relationships with France's regional cancer centers under extended framework agreements before MDR certification timelines freeze competitive entry. Prioritize GDPR-compliant cloud infrastructure investment to preempt cross-border data transfer restrictions fragmenting multi-center deployments. For New Entrants and Emerging Players: Mid-sized pathology departments in Poland and Romania represent the most penetrable buyer archetype, with EU cohesion funds financing infrastructure modernization absent legacy system lock-in. Target cloud-native variant interpretation platforms with rapid-deployment models that bypass capital-intensive instrument sales cycles. Partner with Eastern European hospital networks seeking to collapse send-out turnaround times without academic center dependency. For Investors and Strategic Acquirers: Exit pathways concentrate in specialty bioinformatics platform acquisitions by diagnostic conglomerates seeking software recurring revenue streams. Long-term viability favors developers with CE-marked algorithms under EU AI Act conformity frameworks and established hospital procurement relationships. Watch EMA centralized authorization timelines for advanced therapy medicinal products as the critical inflection signal for companion diagnostic demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU AI Act conformity documentation enables hospital procurement access for algorithmic decision-support tools. |
| Hospital System Partnership | Multi-year framework agreements with French public hospital networks lock in recurring consumable revenue streams. |
| Software Companion Development | Cloud-native variant interpretation pipelines displace on-premise infrastructure while expanding analytical throughput. |
| Backward Integration | In-house reagent manufacturing insulates margin control from supply concentration among dominant flow cell suppliers. |
| Reimbursement Strategy | HTA body engagement calibrates precision diagnostic tariffs against standard-of-care benchmarks in Germany and France. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with diagnostic platform manufacturers, hospital laboratory directors, regulatory affairs specialists, and health technology assessment officers combined with EMA submission databases, MDR certification registries, and hospital procurement records. Bottom-up instrument installation counts and top-down healthcare expenditure flows were triangulated to validate market sizing.
Granularity-level modeling disaggregated revenue across product type, technology layer, clinical application, and end-user category throughout the forecast period. CAGRs derived from instrument replacement cycles, consumable pull-through rates, and bioinformatics subscription expansion trajectories. Pricing assumptions incorporated MDR compliance cost pass-through and GDPR infrastructure investment requirements.
Revisions become necessary when EMA authorization timelines shift, MDR certification backlogs extend, or EU AI Act interpretive guidance tightens algorithmic transparency requirements. Forecasts reflect documented assumptions regarding hospital digitization fund deployment and cross-border genomic data transfer regulatory evolution. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Sex Cord-Gonadal Stromal Tumor Market
Specialty Medicine
Global Bile Duct Cancer Market
Specialty Medicine
Post-Traumatic Stress Disorder Treatment Market
Specialty Medicine
Herpes Zoster (Shingles) Market
Specialty Medicine
SPINA Bifida and Hydrocephalus Market
Specialty Medicine
Global Epilepsy Market
Specialty Medicine
Checkpoint Inhibitor Refractory Cancer Market
Specialty Medicine
US Actinic Keratosis Treatment Market
Specialty Medicine
Radiation-Induced Fibrosis Treatment Market
Specialty Medicine
Malabsorption Syndrome Market
Specialty Medicine
Bleeding Disorders Treatment Market
Specialty Medicine
Global Cancer Biological Therapy Market
Specialty Medicine
North America Alopecia Market
Specialty Medicine
Herpangina Treatment Market
Specialty Medicine
Schizophrenia Treatment Market
Specialty Medicine
Lateral Epicondylitis (Tennis Elbow) Treatment Market