
 Toxoplasmosis Treatment Market | 2026-2036
Toxoplasmosis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Toxoplasmosis Treatment Market Analysis
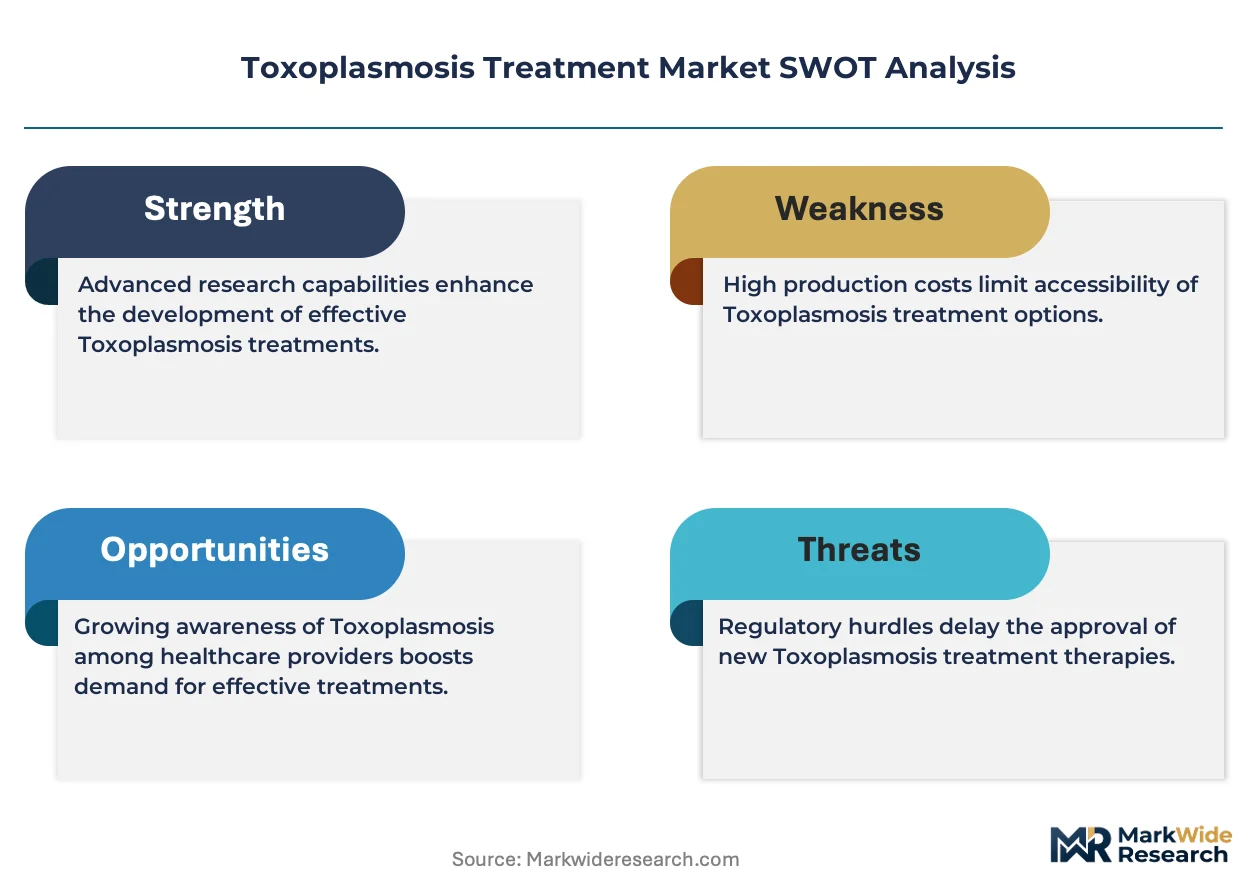
Immunocompromised patient cohorts are redrawing demand patterns across the toxoplasmosis treatment landscape, pulling volume toward tertiary care centers managing transplant recipients and HIV-positive individuals. F. Hoffmann-La Roche AG leverages its diagnostic-to-therapeutic integration to anchor positions in companion testing workflows. Teva Pharmaceutical Industries Ltd sustains broad generic coverage across pyrimethamine and sulfadiazine formulations. Vyera Pharmaceuticals LLC specializes in controlled-distribution models for niche anti-parasitic therapies.
Toxoplasmosis treatment encompasses pharmacological interventions targeting Toxoplasma gondii infection, with standard regimens combining pyrimethamine, sulfadiazine, and leucovorin to inhibit parasitic folate metabolism and prevent bone marrow suppression. These therapies serve primarily to prevent congenital transmission, treat active encephalitis in immunocompromised hosts, and manage ocular disease progression. Pyrimethamine retains dominant position as the anchor agent in first-line combination protocols, while clindamycin gains share among sulfa-allergic patient subsets. Homecare delivery modes are expanding fastest as oral bioavailability enables outpatient management of stable patients, though intravenous channels capture higher per-treatment value in acute settings.
FDA orphan drug designations and EMA pediatric investigation requirements shape clinical development priorities and market access timelines for novel toxoplasmosis therapies. The WHO's inclusion of toxoplasmosis in neglected disease frameworks influences public procurement patterns in endemic regions. Stakeholders must monitor regulatory convergence between FDA and EMA on bioequivalence standards for generic pyrimethamine as this determines competitive entry dynamics and pricing trajectories across developed markets.
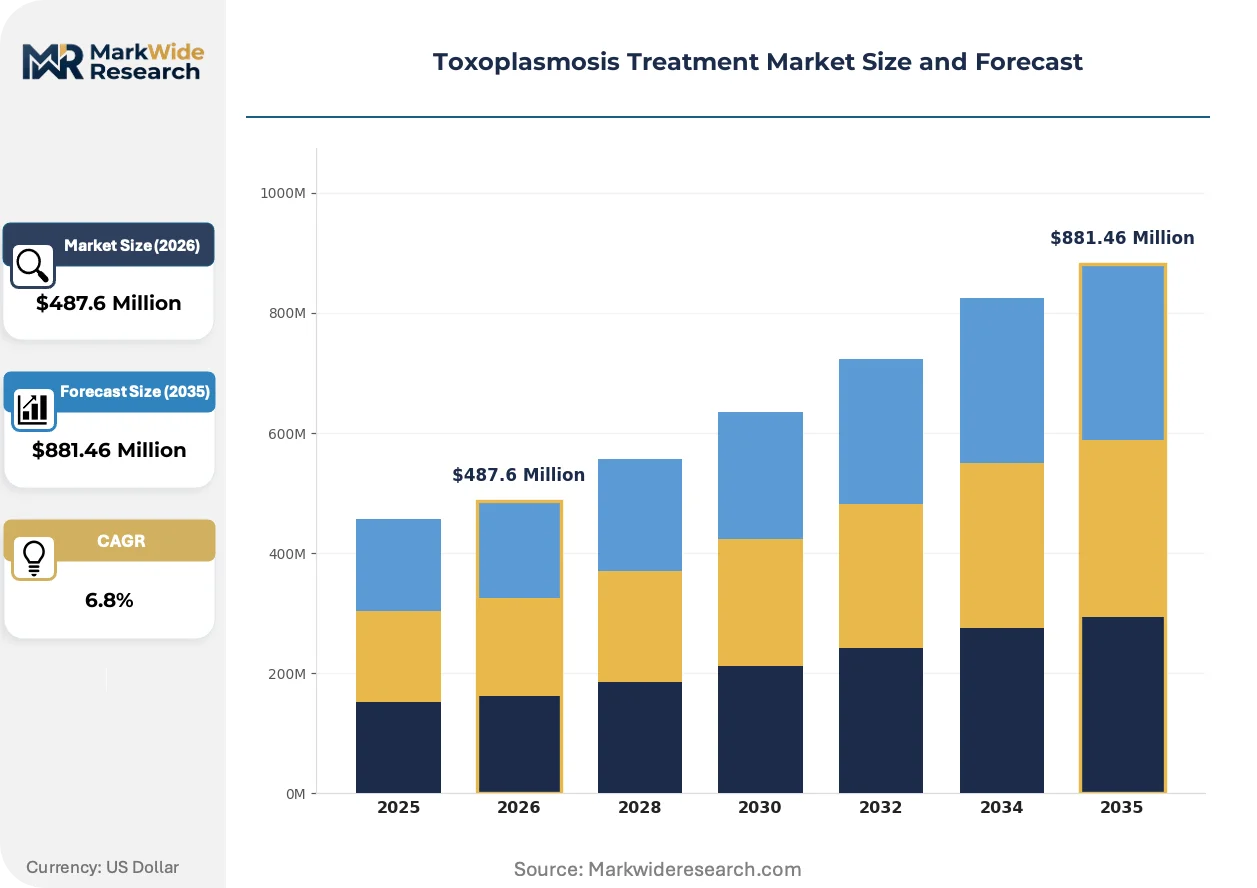
Market Dynamics
The toxoplasmosis treatment landscape is being fundamentally restructured by the expanding immunocompromised patient population, which is pulling clinical volume toward specialized infectious disease centers and reshaping both drug development priorities and distribution infrastructure investments.
Growth Catalysts
- Orphan Drug Incentives:FDA tax credits and market exclusivity provisions are accelerating clinical trial enrollment for novel anti-parasitic compounds targeting congenital toxoplasmosis.
- Diagnostic Integration:PCR-based Toxoplasma gondii detection platforms are compressing time-to-treatment decisions and expanding addressable patient pools in tertiary care settings.
- Homecare Expansion:Oral bioavailability of pyrimethamine-sulfadiazine regimens is enabling outpatient management protocols that reduce hospital bed-day consumption.
Market Restraints
- API Supply Concentration:Pyrimethamine active pharmaceutical ingredient production concentrates among a limited set of contract manufacturers, creating vulnerability to single-source disruptions.
- Sulfa Allergy Prevalence:Approximately one in ten patients exhibits hypersensitivity to sulfadiazine, forcing costly therapeutic substitutions toward clindamycin-based alternatives with inferior CNS penetration.
- Reimbursement Compression:Medicare Part B and commercial payers are tightening prior authorization requirements for branded anti-parasitic therapies, pressuring formulary positioning.
Strategic Opportunities
- Pediatric Investigation Mandates:EMA's requirement for pediatric study plans creates first-mover advantages for sponsors that complete age-appropriate dosing trials ahead of regulatory deadlines.
- Companion Diagnostic Convergence:Integration of pharmacogenomic screening for TPMT enzyme activity with pyrimethamine prescribing is opening personalized dosing protocols that reduce toxicity events.
- Telemedicine Channels:Remote infectious disease consultations are expanding access to specialist-directed toxoplasmosis management in rural and underserved catchment areas.
Industry Challenges
- Trial Recruitment Bottlenecks:Rare disease prevalence complicates patient accrual for toxoplasmosis studies, extending development timelines and inflating per-patient costs.
- Manufacturing Scale Constraints:Batch production of pyrimethamine requires specialized containment infrastructure that limits capacity expansion and creates supply-demand mismatches during demand surges.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Toxoplasmosis Treatment Market |
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pyrimethamine, Sulfadiazine, Clindamycin, Atovaquone End User: Hospitals, Clinics, Homecare, Long-term Care Facilities Delivery Mode: Oral, Intravenous, Subcutaneous, Topical Patient Demographics: Immunocompromised Patients, Pregnant Women, Infants, General Population |
| Companies Covered | F. Hoffmann-La Roche AG, Teva Pharmaceutical Industries Ltd, Vyera Pharmaceuticals LLC, Mangalam Drugs and Organics Ltd, Dr. Reddy's Laboratories Ltd, Pfizer Inc., Novartis AG, Sanofi S.A., Amneal Pharmaceuticals, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Toxoplasmosis Treatment Market Emerging Trajectories
Three interconnected developments are reshaping how toxoplasmosis therapies reach patients: molecular diagnostic platforms are compressing diagnostic uncertainty, regulatory frameworks are rewarding pediatric development, and care delivery models are migrating toward ambulatory settings.
Atovaquone-based combination regimens are decomposing the historical dominance of pyrimethamine-sulfadiazine protocols in sulfa-intolerant populations. Transplant centers and HIV clinics are adopting these alternatives at accelerating rates despite higher per-dose costs. The structural consequence is a bifurcated first-line market where anchor therapy selection depends increasingly on companion allergy testing rather than universal protocol application.
EMA's pediatric investigation plan requirements are mandating age-stratified pharmacokinetic studies for all novel toxoplasmosis submissions. This regulatory pressure is forcing sponsors to allocate development resources toward neonatal and adolescent cohorts that were historically excluded from trials. European markets are responding with earlier engagement between industry and the Paediatric Committee to streamline study design acceptance.
Specialist infectious disease practices are unbundling acute care from longitudinal management, creating discrete revenue streams for stable patient monitoring. Home infusion pharmacies and specialty distributors are capturing value previously retained by hospital outpatient departments. This channel migration is most pronounced in Germany and Japan, where reimbursement frameworks explicitly favor ambulatory parenteral therapy administration.
Toxoplasmosis Treatment Market Segmentation
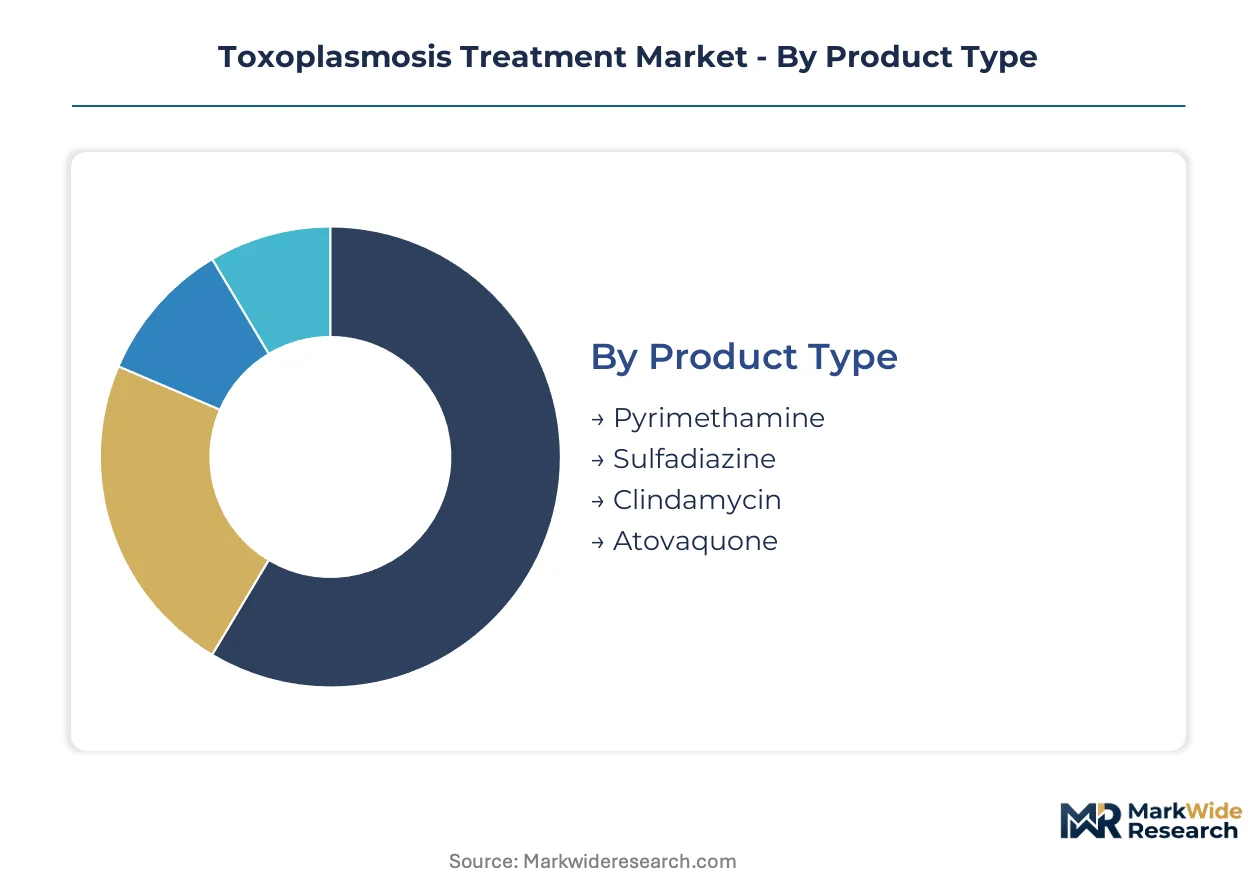
Toxoplasmosis treatment demand fragments across pharmacologic classes, care settings, and patient risk profiles. Each segment carries distinct regulatory requirements, reimbursement pathways, and supply chain vulnerabilities that reshape competitive positioning.
Product Type:
Pyrimethamine anchors domestic demand in the United States and Germany where specialist infectious disease infrastructure supports complex combination protocols. Sulfadiazine and clindamycin serve export-led markets with constrained formulary budgets. Atovaquone concentrates in Japan and tertiary transplant centers globally.
- Pyrimethamine:Folate antagonist that inhibits Toxoplasma gondii dihydrofolate reductase, forming the backbone of first-line combination therapy with sulfadiazine and leucovorin rescue. Demand concentrates in US academic medical centers managing HIV-associated encephalitis, where FDA orphan drug incentives have preserved branded pricing power despite generic availability.
- Sulfadiazine:Sulfonamide antimicrobial that synergizes with pyrimethamine to block parasitic nucleic acid synthesis, requiring alkaline hydration protocols to prevent crystalluria. Export volumes dominate in Latin American and Southeast Asian markets where WHO essential medicines procurement shapes tender dynamics.
- Clindamycin:Lincosamide antibiotic with intracellular penetration suitable for sulfa-allergic patients, though inferior CNS distribution limits encephalitis applications. European hospital pharmacies in France and Italy drive volume for this substitution pathway.
- Atovaquone:Hydroxynaphthoquinone compound disrupting mitochondrial electron transport, increasingly adopted in transplant protocols despite higher per-dose cost. Japanese reimbursement frameworks favor this agent for maintenance therapy.
Pyrimethamine commands the established base. The steepest expansion runs through atovaquone as sulfa intolerance reshapes first-line selection.
End User:
Cost tiers separate acute inpatient management from ambulatory maintenance, with reimbursement rates determining channel profitability. High-complexity cases concentrate in tertiary hospitals while stable patients migrate toward lower-cost settings.
- Hospitals:Tertiary academic centers capture complex encephalitis and congenital cases requiring intravenous induction and multidisciplinary coordination. German university hospitals anchor European volume through centralized referral networks.
- Clinics:Outpatient infectious disease practices manage stable immunocompromised patients on oral maintenance regimens, with Medicare Part B reimbursement shaping US site-of-care decisions.
- Homecare:Specialty pharmacies deliver oral pyrimethamine-sulfadiazine directly to immunocompromised patients, reducing hospital exposure risk. This channel is expanding most quickly in Japan where home nursing supports remote monitoring.
- Long-term Care Facilities:Skilled nursing settings manage ocular toxoplasmosis in elderly populations with limited transport capacity, particularly in rural US catchment areas.
Hospitals retain the highest per-patient value. Homecare is gaining share fastest as oral bioavailability enables outpatient protocol adoption.
Delivery Mode:
Application requirements dictate route selection, with CNS penetration needs favoring intravenous induction and patient stability enabling oral step-down. Manufacturing complexity separates high-margin parenteral from commoditized oral formulations.
- Oral:Tablet and suspension formulations of pyrimethamine and sulfadiazine enable outpatient maintenance, with bioavailability exceeding 90% for both agents. This route dominates volume in stable HIV and transplant populations across US and European markets.
- Intravenous:Hospital-administered clindamycin and sulfadiazine achieve rapid therapeutic levels in acute encephalitis, capturing premium reimbursement under Medicare Severity Diagnosis-Related Groups. Japanese tertiary centers favor this route for initial CNS infection management.
- Subcutaneous:Limited applications in patients with compromised enteral absorption, primarily in German and Swiss palliative care settings where oral tolerance fails.
- Topical:Ocular formulations for anterior segment disease, concentrated in ophthalmology practices in France and Italy with specialized compounding capabilities.
Oral administration commands the volume base. Intravenous delivery maintains the steepest value-per-dose trajectory in acute care settings.
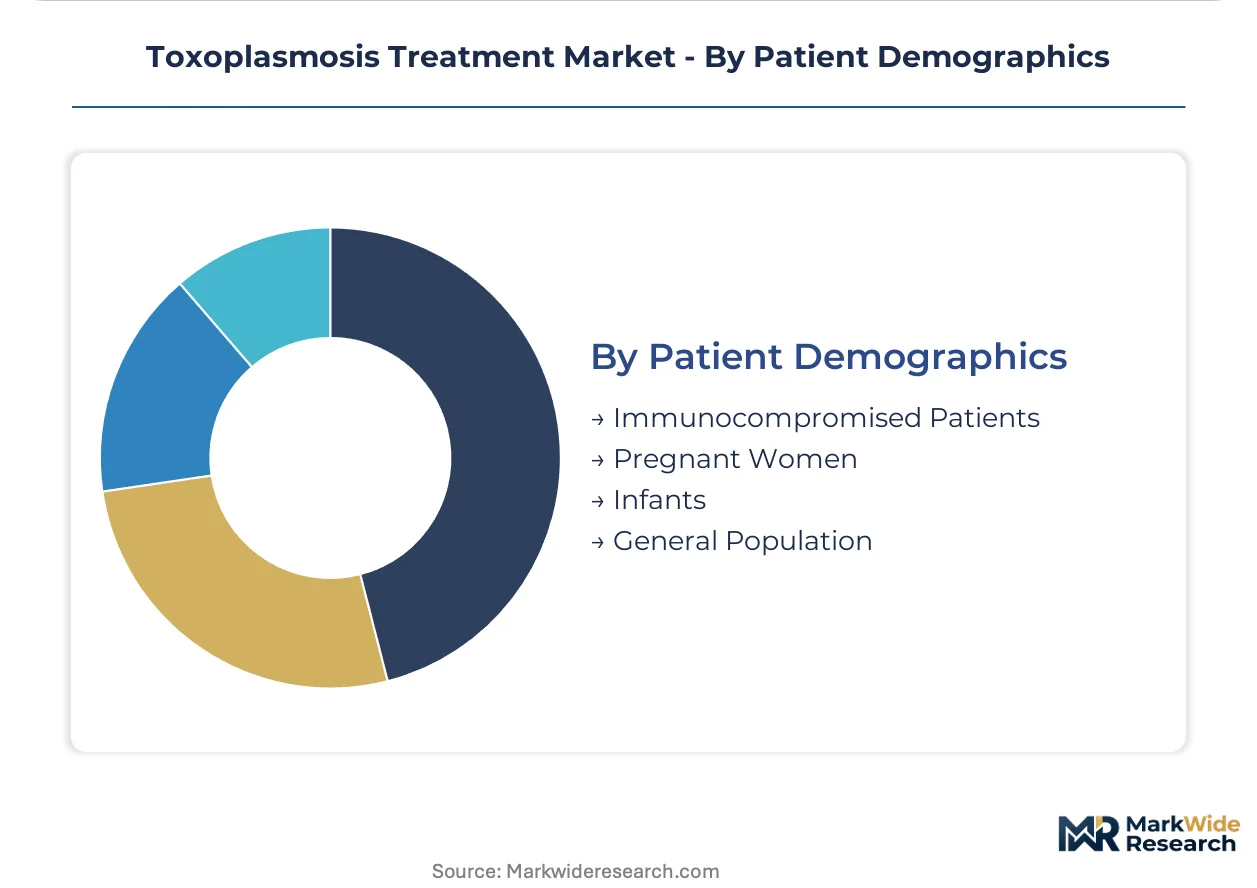
Patient Demographics:
Risk stratification determines treatment intensity, with immunocompromised and pregnant populations triggering mandatory prophylaxis protocols. Pediatric investigation requirements from EMA reshape development priorities for neonatal indications.
- Immunocompromised Patients:HIV-positive individuals with CD4 counts below 100 cells/µL and solid organ transplant recipients on calcineurin inhibitors constitute the core treatment cohort. US and Japanese transplant centers drive demand for lifelong suppressive therapy.
- Pregnant Women:Seroconversion during gestation triggers immediate spiramycin or pyrimethamine-sulfadiazine intervention to prevent congenital transmission. French and Brazilian public health systems maintain active screening programs.
- Infants:Congenitally infected neonates require year-long combination therapy, with EMA pediatric investigation mandates accelerating age-appropriate formulation development.
- General Population:Immunocompetent individuals with isolated lymphadenitis or ocular disease represent sporadic demand concentrated in Mediterranean and Latin American endemic regions.
Immunocompromised patients anchor the revenue base. Pregnant women represent the most regulated expansion pathway as congenital prevention protocols extend geographically.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German pharmaceutical exports anchor European supply to United States transplant centers, while Japanese API manufacturers feed pyrimethamine production networks across Asia-Pacific.
United States
HIV-associated encephalitis and solid organ transplant protocols drive pyrimethamine demand at academic medical centers. FDA orphan drug tax credits accelerate congenital toxoplasmosis trials. The Boston-Cambridge cluster concentrates specialist infectious disease practices managing immunocompromised cohorts.
Germany
Centralized referral networks at university hospitals coordinate complex congenital cases across federal states. EMA pediatric investigation mandates reshape submission timelines for European market access. The Rhine-Ruhr region anchors wholesale distribution infrastructure serving Western European markets.
Japan
Transplant center density and aging HIV populations sustain maintenance therapy volumes. PMDA reimbursement frameworks favor atovaquone for outpatient protocols. Tokyo-Osaka metropolitan corridors concentrate homecare pharmacy networks delivering oral regimens.
France
Active prenatal screening programs trigger immediate spiramycin intervention upon seroconversion. ANSM pharmacovigilance requirements shape post-market surveillance obligations. The Paris basin hosts ophthalmology practices specializing in ocular toxoplasmosis management.
Brazil
Congenital prevention protocols in public health systems expand addressable patient pools. ANVISA bioequivalence standards determine generic pyrimethamine entry dynamics. São Paulo state anchors specialist diagnostic capacity serving Latin American referral networks.
Toxoplasmosis Treatment Market Vendor Landscape
Player mix skews toward diversified pharmaceutical conglomerates with infectious disease portfolios and generic specialists with parasitic therapy focus. Market structure concentrates around three archetypes: integrated diagnostic-therapeutic platforms, high-volume generic manufacturers, and niche controlled-distribution operators. Consolidation pressures favor M&A between API producers and finished-dose formulators. Capacity expansion targets pyrimethamine containment infrastructure.
Within the diagnostic-integrated tier, F. Hoffmann-La Roche AG occupies a position linking PCR detection platforms to treatment protocols. Among generic specialists, Teva Pharmaceutical Industries Ltd and Vyera Pharmaceuticals LLC exemplify divergent models—broad portfolio coverage versus controlled-distribution focus for niche anti-parasitic therapies. These three anchors represent how regulatory incentives and supply chain configuration reshape competitive positioning across developed markets.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche AG |
| Teva Pharmaceutical Industries Ltd |
| Vyera Pharmaceuticals LLC |
| Mangalam Drugs and Organics Ltd |
| Dr. Reddy's Laboratories Ltd |
| Pfizer Inc. |
| Novartis AG |
| Sanofi S.A. |
| Amneal Pharmaceuticals, Inc. |
| Others |
Supply Flow & Price Mechanics
Atovaquone displacement of pyrimethamine-sulfadiazine in sulfa-intolerant protocols simultaneously redraws API sourcing geography toward Japanese manufacturers and compresses pricing premiums for legacy combination therapies. This substitution dynamic concentrates purchasing power among transplant centers capable of negotiating volume-based contracts for higher-cost alternatives.
Pricing Analysis
Generational pricing gaps separate established pyrimethamine-sulfadiazine regimens from atovaquone-based alternatives and emerging antiparasitic candidates. Three-tier pricing structure across branded originators, authorized generics, and commodity API-sourced formulations reflects FDA orphan drug exclusivity periods and EMA pediatric investigation completion status. Cost compression in the generic pyrimethamine tier intensifies as Indian API producers expand containment capacity. Academic medical centers exhibit lowest price sensitivity due to bundled reimbursement under Medicare Severity Diagnosis-Related Groups, while outpatient clinics face tightening prior authorization requirements.
Supply Chain Analysis
Inventory buffers for pyrimethamine API remain thin across European and North American formulators, with lead times extending during regulatory inspection cycles at Indian and Chinese contract manufacturers. Active pharmaceutical ingredient production concentrates in India, China, and Japan, drawing from specialized folate precursor chemistries and containment infrastructure. Supply chain vulnerability centers on single-source dependencies for pyrimethamine dihydrofolate reductase inhibitor synthesis. Distribution runs through specialty pharmaceutical wholesalers serving hospital pharmacies and homecare infusion networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Companion diagnostic integration is transforming toxoplasmosis treatment into a platform-coordinated ecosystem where PCR detection workflows and pharmacogenomic screening interoperate with therapeutic selection. This interoperability shift rewards stakeholders that control both testing infrastructure and drug distribution channels.
For Market Incumbents: Consolidate diagnostic-therapeutic integration through PCR platform acquisitions and pharmacogenomic partnership structures. Defensive positioning requires captive pyrimethamine API supply through backward integration into Indian or Chinese containment manufacturing. Threat of atovaquone substitution in transplant protocols demands formulary lock-in through bundled testing-and-treatment contracts. For New Entrants and Emerging Players: Anchor in pediatric formulation development to exploit EMA investigation plan deadlines and FDA orphan drug exclusivity windows. White-space concentration sits with neonatal dosing regimens and age-appropriate suspension formulations. Go-to-market leverage emerges through telemedicine-linked homecare delivery partnerships bypassing hospital outpatient department capture. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed specialty pharmaceutical platforms holding controlled-distribution licenses for pyrimethamine. Long-term viability hinges on regulatory moat sustainability around pediatric indication expansion and companion diagnostic co-development. Signal to monitor: FDA-EMA convergence on bioequivalence standards for generic pyrimethamine entry.| Strategic Initiative | Industry Significance |
|---|---|
| Pediatric Formulation Development | EMA investigation plan compliance unlocks European market access ahead of regulatory deadlines. |
| Companion Diagnostic Integration | PCR detection platform bundling with pyrimethamine prescribing captures testing-to-treatment workflow value. |
| API Manufacturing Scale-Up | Containment capacity expansion in India reduces single-source vulnerability for folate antagonist supply. |
| Homecare Channel Partnership | Specialty pharmacy network access enables outpatient oral regimen delivery bypassing hospital margins. |
| Pharmacogenomic Screening Adoption | TPMT enzyme activity testing integration reduces toxicity events and supports personalized dosing protocols. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA orphan drug designations, EMA pediatric investigation plan submissions, ClinicalTrials.gov enrollment data, and WHO essential medicines procurement records. Interviews with infectious disease specialists, hospital pharmacy directors, specialty distributor account managers, and regulatory affairs leads at pharmaceutical sponsors informed demand and access assumptions. Bottom-up patient volume estimates triangulated against top-down pharmaceutical expenditure data across the analysis window.
Segmentation dimensions modeled include pharmacologic class, care setting, delivery mode, and patient risk stratification across the projection horizon. Compound annual growth rates derived from epidemiological trend analysis, immunocompromised population expansion projections, and reimbursement framework evolution. Forecast inputs incorporated transplant center density metrics, HIV prevalence surveillance, and congenital screening program expansion rates.
Material uncertainties — API supply disruptions, regulatory bioequivalence standard revisions, and sulfa allergy protocol shifts — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding orphan drug incentive continuity and pediatric investigation timeline adherence. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Tropical Spastic Paraparesis Market
Specialty Medicine
North America Gastric Cancer Market
Specialty Medicine
Atopic Dermatitis Market
Specialty Medicine
Primary Hyperoxaluria Treatment Market
Specialty Medicine
Chronic Inflammatory Demyelinating Polyneuropathy (CIDP) Treatment Market
Specialty Medicine
Toxic Shock Syndrome Treatment Market
Specialty Medicine
Barlow's Syndrome Market
Specialty Medicine
Scleritis Market
Specialty Medicine
Chromoblastomycosis Treatment Market
Specialty Medicine
Interstitial Lung Disease Treatment Market
Specialty Medicine
Chronic Obstructive Pulmonary Disease Therapeutics Market
Specialty Medicine
Kaposi Sarcoma Market
Specialty Medicine
Growth Hormone Deficiency Market
Specialty Medicine
Dural Arteriovenous Fistulas Treatment Market
Specialty Medicine
Oral Cancer Treatment Market
Specialty Medicine
Subdural Haematoma Market