
 Environmental Test Chambers Market | 2026-2036
Environmental Test Chambers Market Size, Share, and Industry Trends Forecast 2026-2036
Environmental Test Chambers Market Intelligence
The shift towards solution-based sales models combining equipment with long-term service contracts is rewriting distribution channels. This change favors manufacturers with extensive direct sales and service networks. ESPEC CORP leverages its global manufacturing footprint to serve multinational clients across key industrial zones. Weiss Technik differentiates through its specialization in highly customized chamber solutions for aerospace and defense, while Thermotron Industries sustains a strong position in the North American automotive testing sector.
An environmental test chamber is an enclosed space used to replicate specific climatic conditions for product reliability testing. These systems control parameters like temperature, often from -70°C to +180°C, and relative humidity to assess material and component durability. Climate chambers, which integrate both temperature and humidity functions, constitute a significant product category. Demand from electronics testing applications within manufacturing facilities is particularly robust, focused on ensuring the resilience of semiconductors and printed circuit boards.
Product validation is governed by standards like ISO 16750 for automotive electronics and IEC standards for electrical components, mandating rigorous environmental testing. Regulations such as the EU's REACH and RoHS directives also influence the materials used in chamber construction and the products being tested. Consequently, manufacturers must align their chamber capabilities with evolving testing protocols for new technologies like electric vehicle batteries and advanced telecommunication hardware.
Market Dynamics
The market's central dynamic is the collision between accelerating product innovation in electronics and automotive sectors and tightening environmental regulations. This forces manufacturers to develop chambers that can validate complex, next-generation technologies while simultaneously complying with stringent new rules on refrigerants and materials.
Growth Catalysts
- Automotive Electrification Standards:The enforcement of standards like ISO 16750 for road vehicle electronics compels extensive environmental testing for electric vehicle components, including battery packs, inverters, and onboard chargers, which must withstand extreme thermal and climatic stress.
- Advanced Telecommunication Hardware:Proliferation of 5G and next-generation network infrastructure requires rigorous reliability testing of semiconductors and printed circuit boards, which are exposed to higher thermal loads and require precise temperature and humidity simulation for validation.
- Manufacturing Hub Investment:Significant investment in advanced manufacturing within China, particularly for new energy vehicles and consumer electronics, creates concentrated demand for high-throughput environmental test chambers to support local production and quality control mandates.
Market Restraints
- High Capital Expenditure:The significant upfront investment required for large-capacity or highly specialized test chambers, such as those for aerospace or battery abuse testing, can be a barrier for smaller companies or research institutions with limited budgets.
- Refrigerant Supply Constraints:Phasedowns of high-GWP refrigerants under regulations like the EU's F-Gas Regulation create supply chain volatility and increase costs for alternative, compliant refrigerants, impacting equipment manufacturing and service.
- Technical Complexity of Simulation:Replicating combined environmental stresses, such as rapid temperature cycling with simultaneous vibration and humidity control, presents significant engineering challenges, limiting the availability of highly integrated and reliable systems for niche applications.
Strategic Opportunities
- Service and Solution Bundling:A shift toward offering integrated solutions that combine chamber hardware with long-term service contracts, remote monitoring, calibration services, and data analytics provides a recurring revenue stream and deepens customer relationships.
- Emerging Energy Technologies:The development of hydrogen fuel cells and grid-scale energy storage systems opens a new frontier for environmental testing, requiring chambers designed to handle unique safety protocols and operational parameters for these technologies.
- Geographic Expansion in Southeast Asia:As electronics and automotive manufacturing expands in countries like Vietnam and Thailand, there is a growing opportunity to establish local sales and service networks to supply testing equipment to these nascent industrial ecosystems.
Industry Challenges
- Skilled Technician Scarcity:A persistent shortage of service technicians with dual expertise in advanced refrigeration systems and modern digital control platforms hinders maintenance, repair, and calibration services, impacting equipment uptime for end-users.
- Rapidly Evolving Compliance:Manufacturers face the constant challenge of redesigning equipment to align with a complex web of evolving international standards from bodies like IEC and ISO, alongside regional material directives such as REACH and RoHS.
- Legacy System Integration:Integrating modern, network-enabled test chambers with clients' existing, often proprietary, factory floor data acquisition and management systems creates significant software and hardware compatibility hurdles, delaying deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Environmental Test Chambers Market |
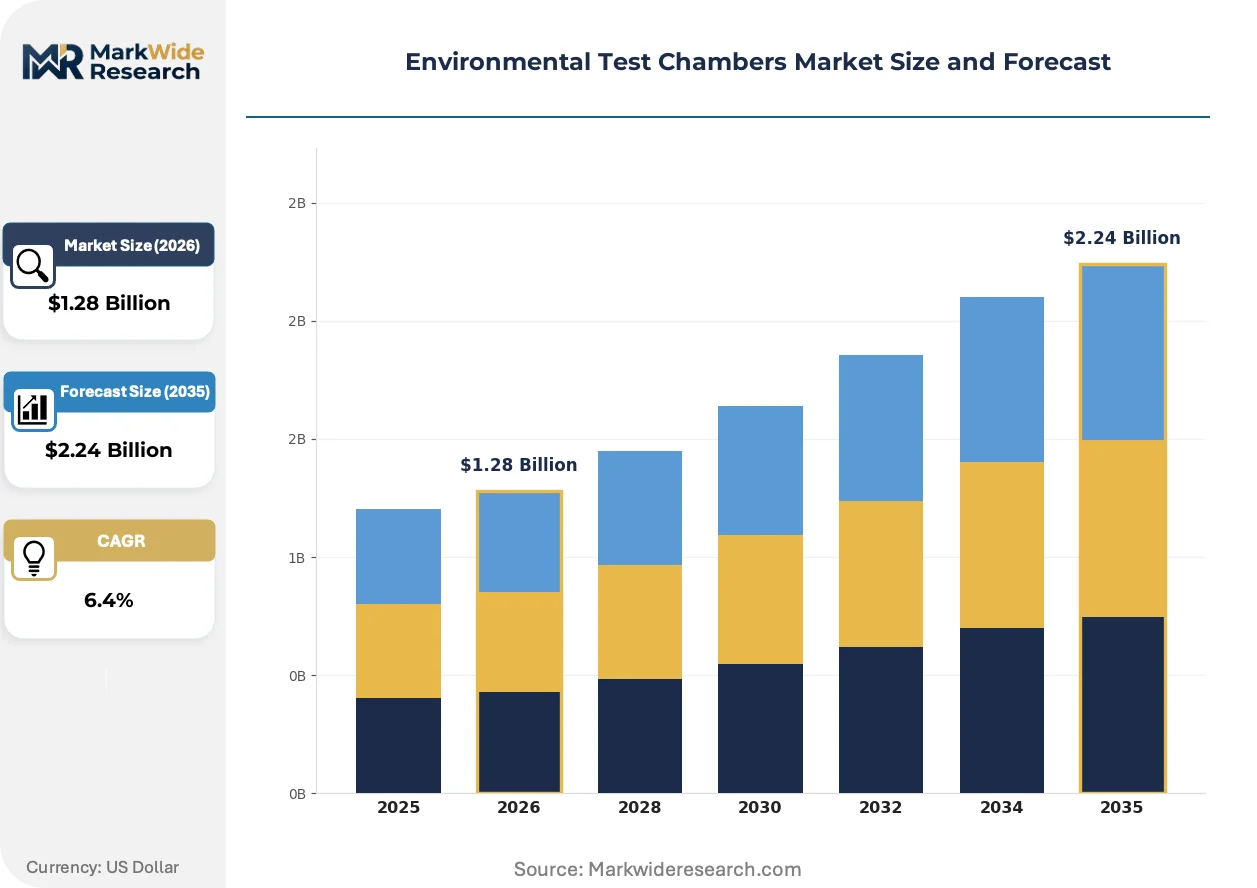
| Market Size in 2026 | $1.28 Billion |
| Market Size in 2035 | $2.24 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Temperature Test Chambers, Humidity Test Chambers, Climate Chambers, Altitude Test Chambers Application: Aerospace Testing, Automotive Testing, Electronics Testing, Pharmaceutical Testing End User: Research Laboratories, Manufacturing Facilities, Quality Control Departments, Educational Institutions Technology: Refrigeration Technology, Heating Technology, Control Systems, Monitoring Systems |
| Companies Covered | ESPEC CORP, Weiss Technik, Thermotron Industries, BINDER GmbH, Angelantoni Test Technologies, Climatic Testing Systems, Inc. (CTS), Hastest Solutions Inc., CM Envirosystems, Russells Technical Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Environmental Test Chambers Market Strategic Shifts & Innovations
The evolution of environmental testing is defined by its transformation into a data-centric discipline. Smart chambers equipped with advanced sensors and connectivity are enabling a move from simple pass-fail validation to predictive reliability engineering based on digital models and real-time performance data.
Integrated Industrial Internet of Things (IIoT) sensors provide continuous data streams on temperature, humidity, and other parameters directly from the test chamber. Automotive and aerospace manufacturers are rapidly adopting this technology to gain deeper insights into component behavior under stress. This integration of real-time data with predictive analytics software is digitizing the entire product validation workflow, turning static tests into dynamic component lifetime modeling exercises.
The European Union's F-Gas Regulation mandates a significant phasedown of hydrofluorocarbons (HFCs) based on their Global Warming Potential (GWP). This directly forces chamber manufacturers to re-engineer refrigeration systems, moving away from traditional refrigerants. The temperature and climate chamber segments are most affected, compelling a rapid transition to low-GWP alternatives or entirely different cooling technologies to remain compliant in the European market.
A discernible behavioral shift is occurring as end-users favor long-term, comprehensive service agreements over simple one-time equipment purchases. This model disrupts the traditional sales channels dominated by third-party distributors, fostering direct relationships between chamber manufacturers and their clients. This trend is particularly visible within the North American and European automotive sectors, where uptime and calibration traceability are paramount.
Environmental Test Chambers Market Segmentation
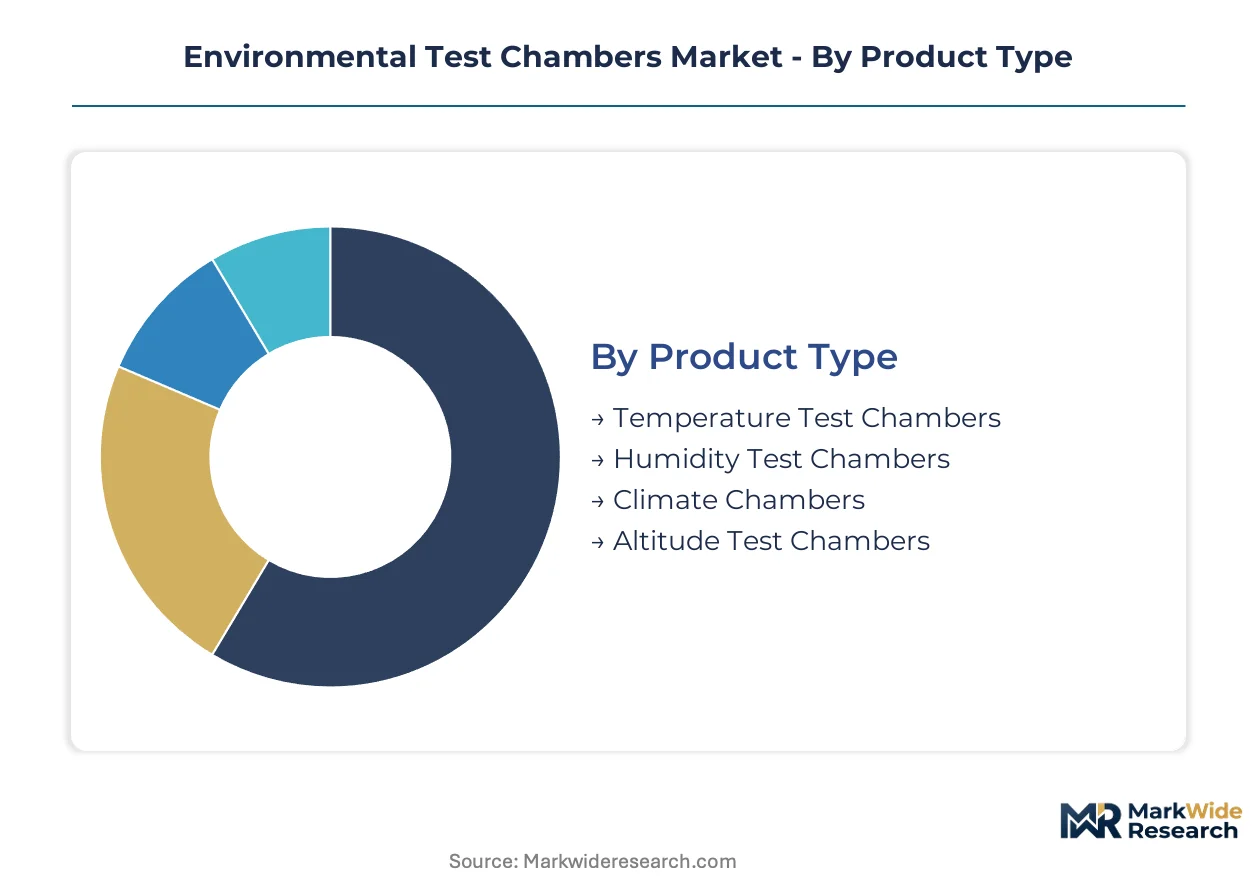
Understanding the Environmental Test Chambers Market through segmentation reveals distinct demand patterns and technological priorities. This detailed breakdown helps manufacturers align product development with specific industry needs and end-user requirements. Analyzing these segments provides clarity on where investment and innovation are most impactful.
Product Type:
The market for environmental test chambers spans a diverse use-case spectrum, ranging from basic thermal validation to complex multi-parameter simulations.
- Climate Chambers:These integrate both temperature and humidity control, offering a comprehensive simulation environment for product reliability. Demand from electronics testing applications within manufacturing facilities is particularly robust, focused on ensuring the resilience of semiconductors and printed circuit boards.
- Temperature Test Chambers:These systems primarily control temperature, often from -70°C to +180°C, to assess material and component durability. Automotive manufacturers in Germany utilize these extensively for validating engine components and electronic control units under extreme thermal cycling.
- Humidity Test Chambers:These focus on precise relative humidity control, crucial for assessing material degradation and component performance in moisture-rich environments.
- Altitude Test Chambers:These chambers simulate low-pressure, high-altitude conditions, essential for aerospace component testing and packaging integrity for air freight.
The dominant share belongs to Climate Chambers, while Temperature Test Chambers are closing the gap fastest.
Application:
Application-specific demands dictate the precise configuration and performance requirements for environmental test chambers across various industries.
- Automotive Testing:This application validates vehicle components against extreme thermal and climatic stresses, particularly for electric vehicle batteries, inverters, and onboard chargers. Standards like ISO 16750 compel extensive environmental testing for road vehicle electronics.
- Electronics Testing:This segment focuses on ensuring the resilience of semiconductors and printed circuit boards against temperature and humidity fluctuations. Proliferation of 5G infrastructure in China requires rigorous reliability testing for advanced telecommunication hardware.
- Aerospace Testing:Chambers for this sector simulate extreme temperature, altitude, and vibration conditions for aircraft components and satellite hardware.
- Pharmaceutical Testing:This involves stability testing of drugs and medical devices, ensuring product integrity under specific temperature and humidity profiles.
Electronics Testing exhibits the steepest expansion trajectory, driven by continuous innovation in consumer devices.
End User:
Each end-user group approaches environmental testing with a distinct operational focus, influencing chamber design and data acquisition needs.
- Manufacturing Facilities:These users integrate test chambers directly into production lines for in-process validation and batch testing of components. Significant investment in advanced manufacturing within China creates concentrated demand for high-throughput chambers to support local production mandates.
- Quality Control Departments:These departments use chambers for final product validation and adherence to industry standards before market release. They prioritize precise parameter control and detailed data logging for compliance with regulations like the EU's RoHS directive.
- Research Laboratories:These institutions utilize chambers for material science investigations, new product development, and academic studies on environmental stress effects.
- Educational Institutions:Universities and technical schools employ smaller chambers for teaching purposes and student projects related to engineering and material science.
Manufacturing Facilities command the largest share, while Quality Control Departments are rapidly gaining share due to stricter regulatory oversight.
Technology:
The technological segmentation highlights the core functional capabilities that define modern environmental test chambers.
- Refrigeration Technology:This segment encompasses the cooling mechanisms, including compressor-based systems and alternative low-GWP refrigerants. The EU's F-Gas Regulation mandates a significant phasedown of HFCs, forcing re-engineering efforts in this area.
- Control Systems:These advanced platforms manage and automate test parameters, allowing for precise temperature, humidity, and pressure cycling. Integration with IIoT sensors provides continuous data streams for dynamic component lifetime modeling.
- Heating Technology:This involves electric heaters and other methods used to achieve and maintain elevated temperatures within the test chamber.
- Monitoring Systems:These systems track and record chamber conditions and product performance data, often with remote access and data analytics capabilities.
Innovation in Control Systems is accelerating most quickly, driven by the demand for data-centric validation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Global trade routes and advanced manufacturing supply chains underwrite the widespread demand for environmental test chambers. These chambers ensure product reliability across diverse industries. From automotive electronics to advanced telecommunication hardware, rigorous testing is essential for market acceptance and regulatory compliance.
China
Demand for environmental test chambers in China stems from its burgeoning new energy vehicle sector and extensive consumer electronics manufacturing. The country's dual carbon goals drive innovation in sustainable testing practices and energy-efficient chamber designs. Advanced manufacturing clusters in the Yangtze River Delta region create concentrated demand for high-throughput testing solutions.
Germany
Germany's robust automotive R&D and precision industrial machinery sectors generate significant demand for environmental test chambers. The EU's F-Gas Regulation directly influences the re-engineering of refrigeration systems within German-made chambers. Bavaria's automotive and engineering hubs are central to validating components for electric vehicles and industrial automation.
United States
The United States sees strong demand from its aerospace, defense, and semiconductor manufacturing industries. EPA standards for refrigerant management guide equipment design and material selection for test chambers operating in the US. Silicon Valley's electronics and aerospace component validation facilities require precise environmental simulation capabilities.
Japan
Japan's precision electronics and advanced automotive components sectors are key drivers for environmental test chamber adoption. METI guidelines for industrial equipment promote high standards for reliability and performance in Japanese manufacturing. The Kanto region's electronics and automotive testing facilities are crucial for product development and quality assurance.
India
India's expanding automotive production and electronics manufacturing initiatives fuel the demand for environmental test chambers. BIS standards for product quality and safety mandate comprehensive testing across various industrial applications. Pune's automotive and manufacturing clusters demonstrate a growing need for chambers to support local production and export mandates.
Environmental Test Chambers Market Key Industry Players
On the supply side, the industry is moderately consolidated, featuring a mix of global players and niche specialists. Global full-service providers offer broad portfolios, while regional firms focus on specific applications and localized support. Strategic archetypes include comprehensive solution providers, specialized custom chamber manufacturers, and regional automotive testing experts. Dominant competitive moves include strategic partnerships and continuous portfolio diversification to meet evolving industry needs.
Among established industry leaders, ESPEC CORP, a global entity, represents the comprehensive solution providers with extensive manufacturing footprints. Weiss Technik exemplifies specialization in highly customized chamber solutions, particularly for demanding sectors like aerospace and defense. Thermotron Industries maintains a strong position in the North American automotive testing sector, focusing on regional market needs and service excellence.
| Leading Market Players |
|---|
| ESPEC CORP |
| Weiss Technik |
| Thermotron Industries |
| BINDER GmbH |
| Angelantoni Test Technologies |
| Climatic Testing Systems, Inc. (CTS) |
| Hastest Solutions Inc. |
| CM Envirosystems |
| Russells Technical Products |
| Others |
Cost & Logistics Intelligence
Refrigerant supply concentration in specific manufacturing regions directly impacts the cost structure of environmental test chambers, influencing overall market pricing and the profitability of service contracts. This upstream dependency creates a leverage point for component suppliers, shaping downstream margin pools for equipment manufacturers.
Pricing Analysis
Pricing for environmental test chambers is tiered based on customization and volume, reflecting the complexity of simulation requirements. Differentiation stems from advanced control system capabilities, after-sales service agreements, and specialized certifications for demanding applications. Pricing softness reflects high initial capital expenditure requirements for end-users. Smaller research institutions and educational institutions exhibit greater price sensitivity compared to large industrial manufacturers.
Supply Chain Analysis
The upstream feedstock for critical low-GWP refrigerants primarily originates from a limited number of chemical producers in Europe and Asia. Key components like precision sensors and advanced control modules are sourced from specialized electronics manufacturing hubs in China and Germany. Supply chain risk arises from the phasedown mandates of the EU's F-Gas Regulation, creating volatility in refrigerant availability and cost. Distribution runs through a hybrid model, combining direct sales for major clients with specialized third-party distributors for regional market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is poised for a cyclical recovery, driven by renewed investment cycles in automotive electrification and advanced electronics manufacturing across key industrial zones.
For Market Incumbents:
Insulate core market share by deepening service and solution bundling, offering comprehensive long-term maintenance and calibration contracts. Invest strategically in research and development for next-generation low-GWP refrigerants and advanced IIoT-enabled control systems to counter evolving compliance threats. Leverage global manufacturing footprints to optimize regional supply chains against geopolitical shifts.
For New Entrants and Emerging Players:
Southeast Asia's electronics and automotive manufacturing expansion presents a significant geographic underpenetration opportunity for specialized test chamber providers. Focus on niche applications like hydrogen fuel cell testing or grid-scale energy storage systems, which require unique safety protocols. A go-to-market strategy emphasizing highly integrated, data-centric validation systems can capture early adopters in these emerging sectors.
For Investors and Strategic Acquirers:
Capital is best deployed toward manufacturers demonstrating strong intellectual property in advanced control systems, predictive analytics software, or specialized refrigeration technologies. The long-term viability of this market hinges on continuous innovation to meet evolving product validation needs for next-generation technologies. An acceleration in IIoT-enabled predictive reliability engineering platforms serves as a critical inflection signal.
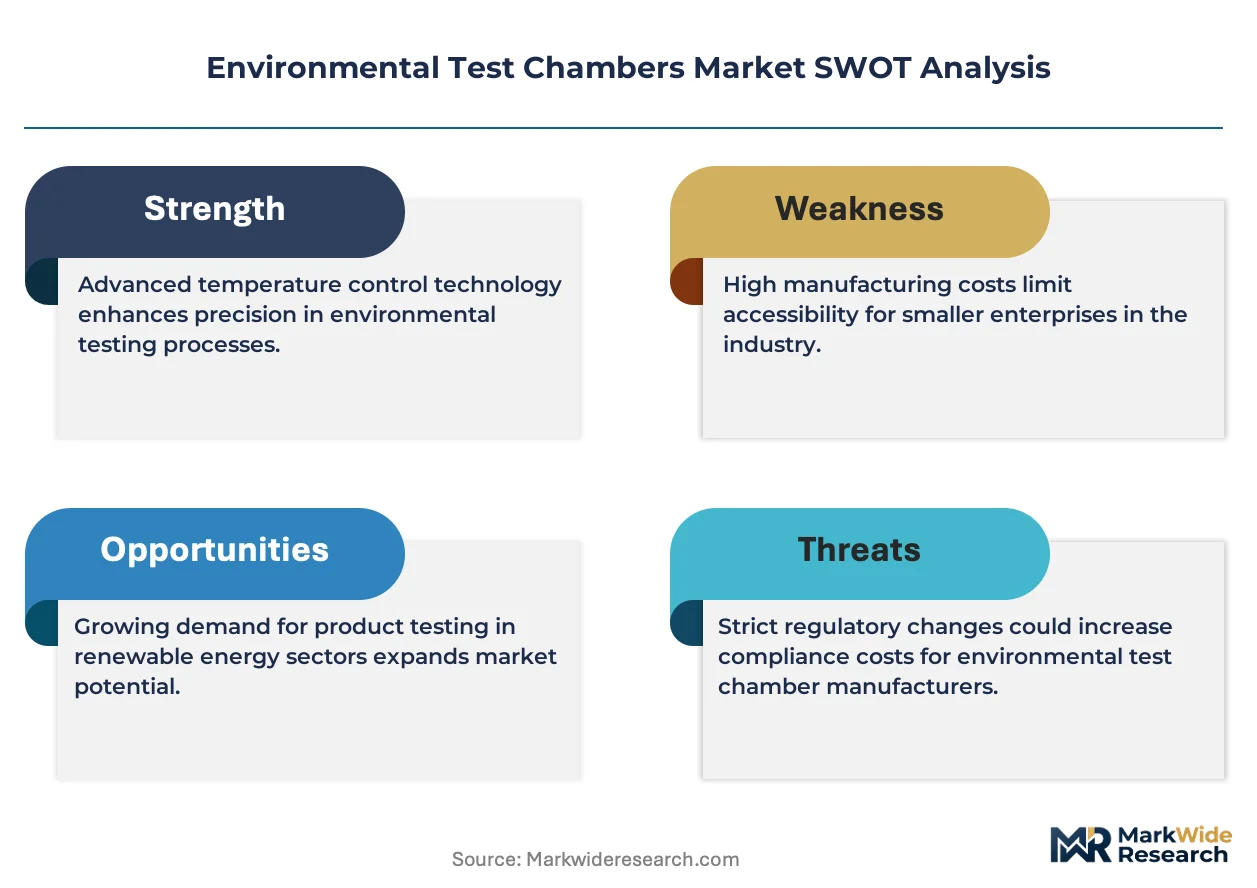
| Strategic Initiative | Industry Significance |
|---|---|
| Solution Bundling Expansion | Deepens customer relationships and generates recurring revenue streams for manufacturers. |
| Low-GWP Refrigerant R&D | Ensures compliance with evolving environmental regulations, particularly in the European market. |
| IIoT Integration Development | Transforms testing from pass-fail validation to predictive reliability engineering. |
| Southeast Asia Market Entry | Captures demand from expanding electronics and automotive manufacturing hubs. |
| Specialized Battery Testing | Addresses critical validation needs for electric vehicle and energy storage technologies. |
Research Approach
Cross-validation between primary interviews with industry stakeholders and secondary validation from company reports anchors the qualitative findings. This study engaged R&D directors, procurement managers, quality control specialists, and sales executives in the automotive and electronics sectors. Secondary data sources included ISO/IEC standards documentation, EU F-Gas regulation texts, national manufacturing statistics, and technology white papers, triangulating bottom-up data aggregation with top-down market sizing.
Market projections calibrate historical data with anticipated technological shifts across the analysis window. The analytical framework modeled segmentation dimensions including product type, application, end-user, technology, and key geographic regions. Compound Annual Growth Rates derive from a weighted assessment of demand drivers and market restraints. Electric vehicle production forecasts and 5G infrastructure deployment rates serve as critical forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in global trade policies and industrial investment cycles would shift the trajectory. Forecasts reflect assumptions regarding refrigerant supply chain stability and the pace of regulatory adoption. Cross-checking against independent industry association reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Permeability Testing Machine Market
Test and Measurement
NIR Moisture Analyzers Sales Market
Test and Measurement
Global Platform Electronic Laboratory Balance Market
Test and Measurement
Asia-Pacific Laser Interferometer Market
Test and Measurement
Automated Ultrasonic Testing Market
Test and Measurement
Drop Weight Testers Market
Test and Measurement
Global Digital Measurement Instruments Market
Test and Measurement
Inline Metrology Market
Test and Measurement
Radiography Test Equipment Market
Test and Measurement
Global Micrometer Market
Test and Measurement
Digital Weighing Terminal Market
Test and Measurement
Anechoic Chamber Market
Test and Measurement
Photometer and Calorimeter Market
Test and Measurement
Data Center Testing Market
Test and Measurement
Active Dosimeter Market
Test and Measurement
Durometer Calibration Service Market