
 Simulation and Test Data Management Market | 2026-2036
Simulation and Test Data Management Market Size, Share, and Industry Trends Forecast 2026-2036
Simulation and Test Data Management Market Outlook
Enterprise software distribution is fragmenting as vendors rebalance direct sales against cloud marketplaces and systems integrator partnerships. Dassault Systèmes leverages its 3DEXPERIENCE platform to anchor aerospace and automotive accounts with integrated simulation lifecycle tools. Siemens Digital Industries Software competes through Teamcenter integration, sustaining pull-through from its broader digital twin portfolio. ANSYS specializes in high-fidelity physics solvers, dominating the pre-simulation data preparation layer that feeds downstream test data pipelines.
Simulation and test data management encompasses the systematic capture, storage, traceability, and governance of engineering datasets generated during virtual modeling and physical validation cycles, typically handling multi-terabyte structured and unstructured files with metadata schemas linking design parameters to test outcomes. The discipline serves primarily to compress product development timelines and ensure reproducibility across distributed engineering teams. Data masking and data virtualization solutions carry expanding margin pools as privacy regulations harden requirements for production-like test environments. Cloud-based deployment is accelerating fastest among mid-tier manufacturers seeking elastic compute for burst simulation workloads, while on-premises installations retain strongholds in defense and classified aerospace programs.
ISO 80001 risk management frameworks for medical device software testing, FDA 21 CFR Part 11 electronic records requirements, and EASA certification standards for simulation-based aircraft qualification all elevate the compliance burden on test data provenance and audit trails. These regulations force platform vendors to embed chain-of-custody logging and tamper-evident archiving as standard features rather than optional modules. Stakeholders must weigh whether to build sovereign data residency capabilities or partner with regional cloud providers as cross-border engineering collaboration intensifies.
Market Dynamics
Cloud-native architectures are fragmenting the vendor landscape as mid-tier manufacturers abandon perpetual licenses for consumption-based simulation platforms, forcing incumbents to rebuild pricing models around elastic compute rather than seat counts.
Growth Catalysts
- ISO 80001 risk management frameworks:Medical device manufacturers in Germany and the United States must maintain complete test data provenance for software validation, creating mandatory platform upgrades.
- Automotive electrification:Battery pack thermal validation requires 10-100x more simulation iterations than internal combustion platforms, driving storage and metadata indexing demand.
- China's MIIT digital twin mandates:State-owned aerospace and rail equipment producers must integrate simulation and physical test data under unified national standards.
Market Restraints
- GPU compute cost volatility:Cloud-based high-fidelity physics solvers face input cost swings tied to NVIDIA supply allocation and energy pricing in data center clusters.
- Defense sector supplier concentration:Classified aerospace programs in the United States require on-premises infrastructure from a shrinking pool of cleared systems integrators.
- Data sovereignty fragmentation:GDPR, China's PIPL, and India's DPDP Act create incompatible residency requirements that prevent unified global deployments.
Strategic Opportunities
- India's PLI scheme for automotive:Domestic EV and component manufacturers lack mature test data infrastructure, creating greenfield platform opportunities.
- Digital thread convergence:Integration of MBSE model repositories with test data lakes enables automated requirement-to-validation traceability.
- EASA AI-based certification pathways:Machine learning surrogate models for aircraft loads analysis require new data governance frameworks not yet codified in vendor products.
Industry Challenges
- Multi-physics workflow orchestration:Coupled thermal-structural-acoustic simulations demand data scientists who understand both solver mathematics and storage tiering economics.
- FDA 21 CFR Part 11 audit readiness:Electronic signatures and tamper-evident archiving for medical device submissions require 12-18 month validation timelines that delay revenue recognition.
- Heterogeneous legacy PLM integration:Decades of proprietary CAD and CAE formats resist standardized metadata extraction without expensive professional services engagements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Simulation and Test Data Management Market |
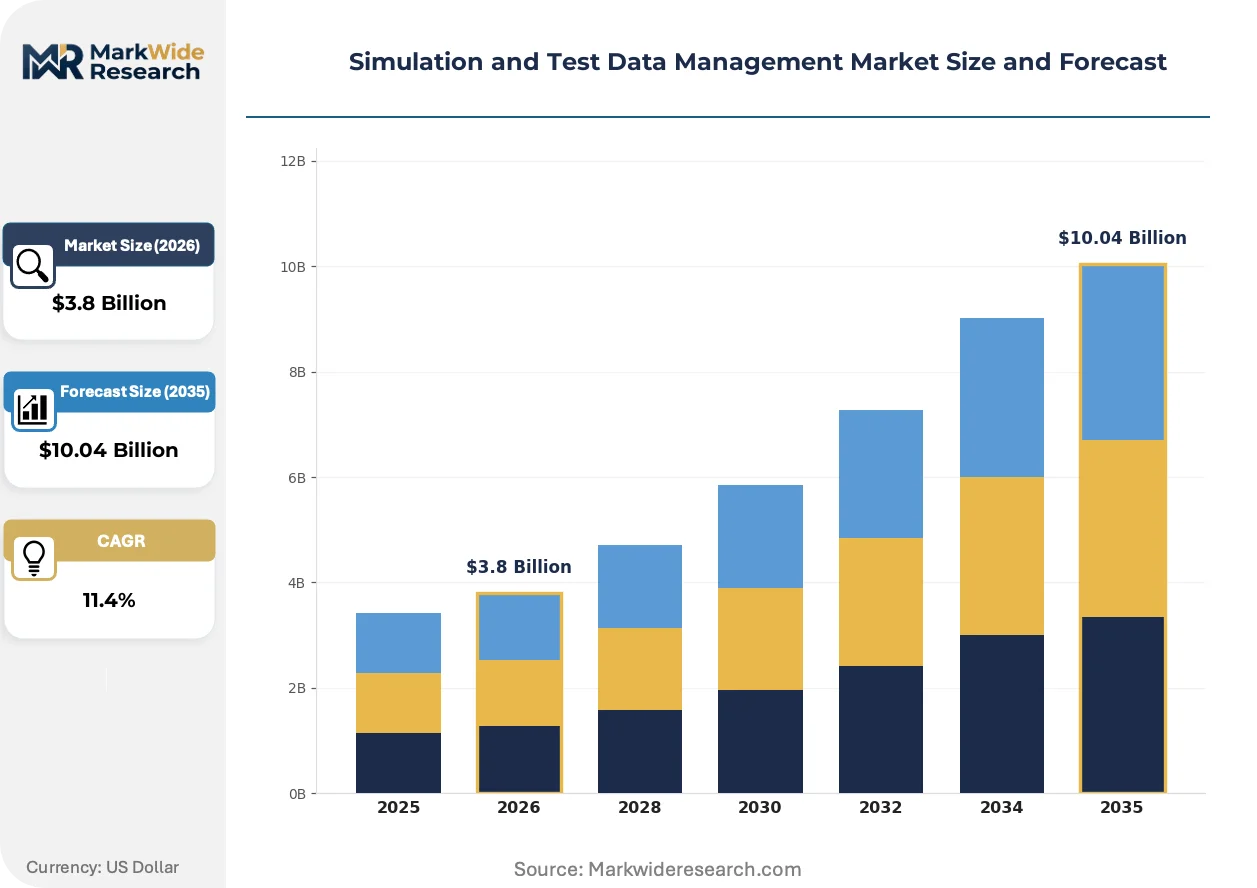
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
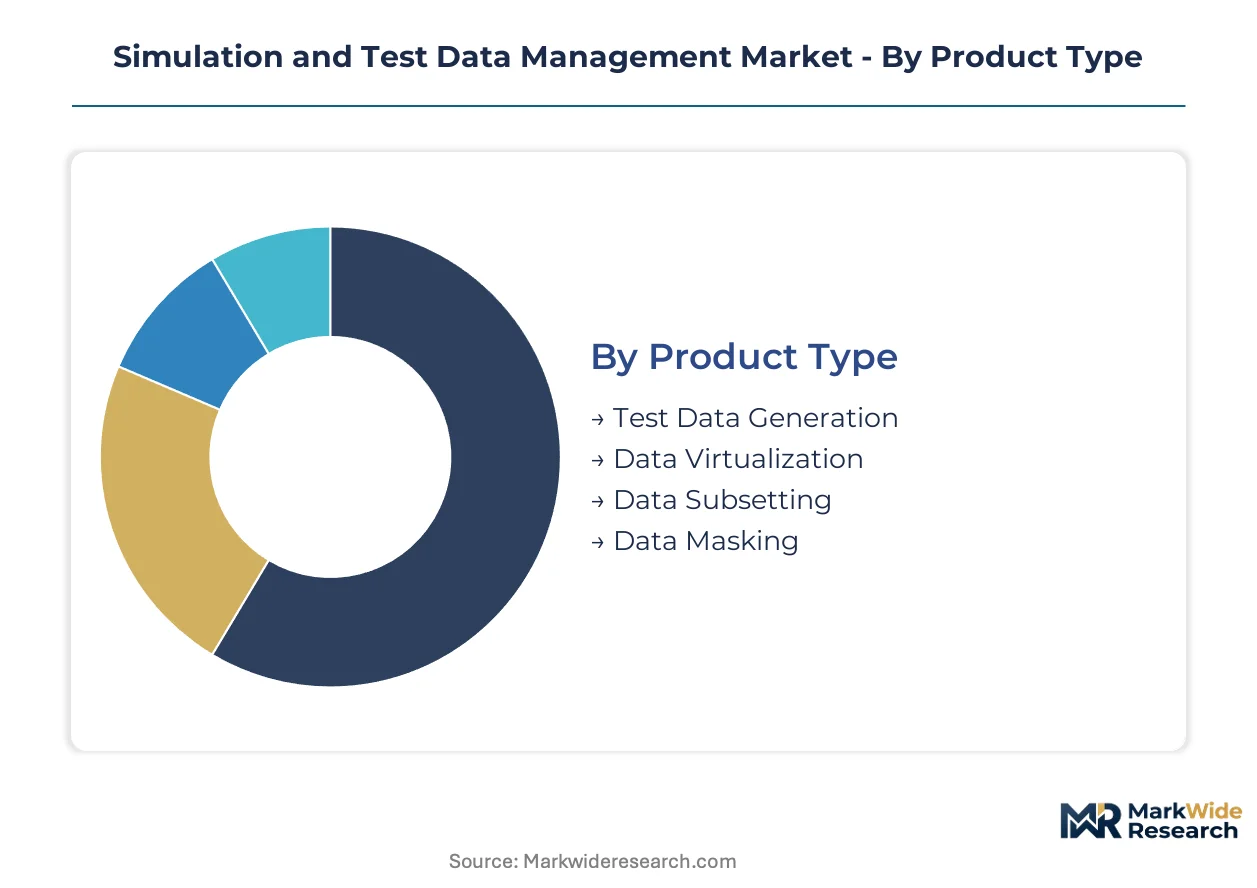
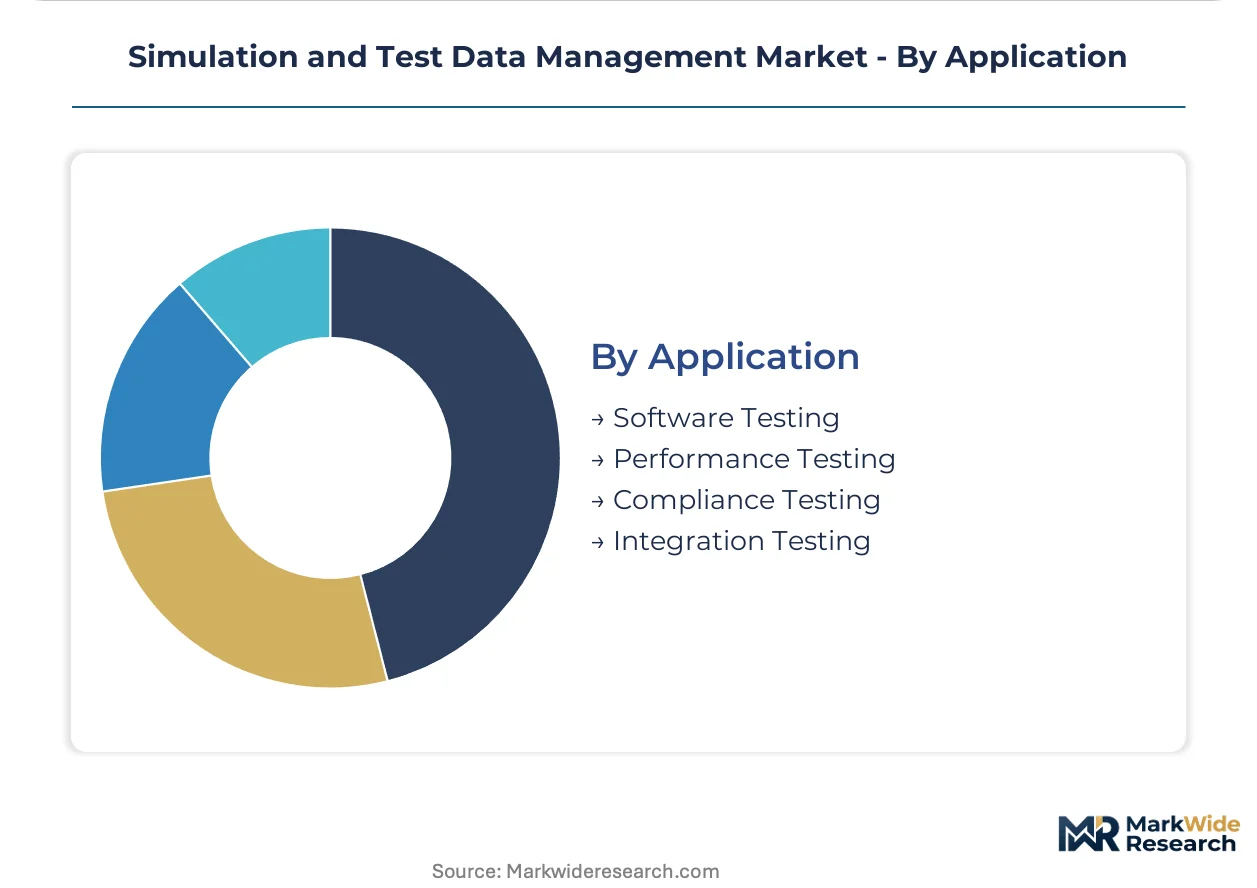
| Segmentation | Product Type: Test Data Generation, Data Virtualization, Data Subsetting, Data Masking End User: Aerospace, Automotive, Telecommunications, Healthcare Deployment: On-premises, Cloud-based, Hybrid, Managed Service Application: Software Testing, Performance Testing, Compliance Testing, Integration Testing |
| Companies Covered | Dassault Systèmes, Autodesk, IBM Corporation, Delphix, MSC Software Corporation, Siemens Digital Industries Software, Informatica, K2View, ANSYS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Simulation and Test Data Management Market Strategic Shifts
Artificial intelligence is compressing the boundary between virtual and physical validation, with generative models now predicting test outcomes before hardware prototypes exist. This shift demands entirely new data architectures that can feed simulation outputs back into training pipelines.
Physics-informed neural networks are migrating from academic research into production vehicle development workflows. Tier 1 automotive suppliers in Stuttgart and Detroit deploy these surrogates to replace 60-70 percent of crash and durability simulations. The technology is migrating from isolated pilot programs toward mandatory inclusion in OEM supplier qualification requirements.
EU AI Act risk classification rules now capture high-stakes engineering AI systems used for aircraft and medical device certification. Manufacturers must document training data provenance, model validation protocols, and human oversight mechanisms. Aerospace suppliers in Toulouse and Hamburg are restructuring simulation governance committees to pre-empt regulatory scrutiny.
Subscription consumption models displace perpetual licensing across mid-market engineering teams. Procurement teams in industrial machinery and consumer electronics now prioritize pay-per-simulation contracts that align software spend with project milestones. This pattern is most visible in South Korea's semiconductor equipment sector, where capital-light fabless designers dominate.
Simulation and Test Data Management Market Segmentation
Engineering organizations select simulation and test data management platforms based on data sovereignty constraints, validation throughput requirements, and integration complexity with legacy PLM systems. Segmentation reveals diverging technology preferences between defense primes bound to on-premises infrastructure and commercial manufacturers pursuing cloud elasticity.
Product Type:
After-sales service intensity varies sharply across product categories, with data masking and virtualization solutions demanding continuous compliance updates as privacy regulations evolve.
- Test Data Generation:Synthetic dataset creation tools produce statistically representative engineering data for scenarios where physical testing remains impractical. Automotive battery manufacturers in Stuttgart and Detroit deploy these platforms to simulate thermal runaway conditions without destroying prototype packs. Demand concentrates among EV programs where physical destruction testing creates 10-100x iteration bottlenecks.
- Data Virtualization:Abstraction layers enable real-time access to distributed simulation repositories without physical data movement. Aerospace suppliers in Toulouse leverage this technology to federate wind tunnel datasets across EASA-regulated national boundaries while maintaining chain-of-custody requirements. The technology addresses data sovereignty fragmentation that prevents unified global deployments.
- Data Subsetting:Extraction tools isolate statistically valid sample sets from multi-terabyte simulation archives for downstream validation workflows.
- Data Masking:Privacy-preserving transformation engines protect sensitive design parameters when sharing test data with external suppliers or regulatory auditors.
Test data generation holds the largest share; momentum sits with data virtualization.
End User:
Cost tier stratification separates defense-aerospace budgets with decade-long procurement cycles from automotive programs operating on compressed 18-24 month vehicle development timelines.
- Aerospace:Airframe and propulsion manufacturers manage petabyte-scale simulation archives spanning decades of certification campaigns. Boeing and Airbus suppliers in Hamburg maintain tamper-evident audit trails for EASA simulation-based qualification pathways. Regulatory pressure from EU AI Act risk classification rules now mandates documented training data provenance for machine learning surrogate models.
- Automotive:OEMs and Tier 1 suppliers generate 60-70 percent more simulation iterations for electrified platforms compared to internal combustion predecessors. Battery thermal validation workflows in Germany and China drive storage and metadata indexing investments. MIIT digital twin mandates for state-owned rail and aerospace producers in China extend to automotive joint ventures.
- Telecommunications:Network equipment vendors simulate RF propagation and base station load testing across heterogeneous geographic conditions.
- Healthcare:Medical device manufacturers maintain FDA 21 CFR Part 11 compliant electronic records for software validation under ISO 80001 risk management frameworks.
Aerospace commands premium pricing; automotive represents the steepest expansion trajectory.
Deployment:
Customer type segmentation distinguishes classified defense programs requiring cleared personnel from commercial manufacturers prioritizing capital efficiency.
- On-premises:Physical infrastructure installations serve classified aerospace programs and medical device manufacturers with strict data residency requirements. United States defense primes face supplier concentration risk as the pool of cleared systems integrators contracts. These deployments sustain perpetual licensing models resistant to cloud migration pressures.
- Cloud-based:Elastic compute platforms enable burst simulation workloads for mid-tier manufacturers without datacenter capital commitments. South Korean semiconductor equipment designers and industrial machinery producers in Japan favor pay-per-simulation contracts aligned with project milestones. GPU compute cost volatility tied to NVIDIA supply allocation creates input cost uncertainty.
- Hybrid:Architectures partition sensitive design data on-premises while pushing non-critical simulation processing to cloud tiers.
- Managed Service:Outsourced platform operations address skill shortages in multi-physics workflow orchestration and storage tiering economics.
On-premises retains the largest installed base; cloud-based deployments are climbing the fastest.
Application:
Application maturity separates established software testing protocols from emerging AI validation frameworks lacking codified vendor support.
- Software Testing:Systematic validation of embedded control algorithms and HMI interfaces across automotive and medical device programs. ISO 80001 and FDA 21 CFR Part 11 requirements force platform vendors to embed chain-of-custody logging as standard features. German automotive suppliers face mandatory platform upgrades to maintain complete test data provenance.
- Performance Testing:Load and stress validation for telecommunications infrastructure and industrial automation systems. India's PLI scheme for automotive creates greenfield demand as domestic EV manufacturers lack mature test data infrastructure.
- Compliance Testing:Regulatory submission packages documenting requirement-to-validation traceability for EASA and FDA certification.
- Integration Testing:Cross-system validation ensuring MBSE model repositories synchronize with physical test data lakes.
Software testing dominates current spend; compliance testing is gaining share fastest as regulatory frameworks harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Frankfurt-Cologne high-speed rail corridor underwrites Germany's central role in European engineering data exchange, connecting automotive OEMs in Stuttgart with aerospace clusters in Hamburg.
United States
Defense primes in Arlington and Bethesda drive classified simulation archive demand for hypersonic vehicle qualification. NHTSA crash test data mandates force Tier 1 suppliers to upgrade chain-of-custody systems. Detroit battery engineering centers consume elastic cloud compute for thermal runaway modeling.
Germany
Stuttgart OEMs generate 60-70 percent more simulation iterations for EV platforms than combustion predecessors. KBA type-approval requirements extend to virtual validation datasets under UN ECE regulations. Munich industrial software vendors anchor EU AI Act compliance tooling for aerospace suppliers.
China
MIIT digital twin mandates compel state-owned rail and aerospace producers to unify simulation and physical test data. Shanghai battery manufacturers face 10-100x iteration volumes for thermal validation workflows. Beijing-Tianjin-Hebei corridor concentrates sovereign cloud infrastructure for defense-adjacent programs.
India
PLI scheme beneficiaries in Tamil Nadu and Gujarat lack mature test data infrastructure for domestic EV component qualification. CDSCO medical device software validation rules mirror FDA 21 CFR Part 11 structures. Bangalore semiconductor equipment designers favor pay-per-simulation contracts aligned with fabless project milestones.
South Korea
Seoul Capital Area semiconductor equipment vendors simulate RF propagation across heterogeneous geographic conditions for 5G base station exports. MFDS medical device software validation frameworks drive ISO 80001 risk management adoption. Busan-Ulsan industrial machinery producers accelerate subscription consumption models for burst simulation workloads.
Simulation and Test Data Management Market Competitive Environment
On the supply side, the industry is consolidating around platform vendors with embedded PLM integration capabilities. Three archetypes dominate: diversified industrial software conglomerates with digital twin portfolios, specialized physics solver vendors with high-fidelity pre-simulation layers, and data infrastructure specialists with masking and virtualization toolchains. Competitive moves concentrate on strategic partnerships with systems integrators and geographic expansion through regional cloud provider alliances.
Among diversified platform vendors, Dassault Systèmes and Siemens Digital Industries Software occupy positions anchored by enterprise PLM integration, while ANSYS exemplifies the specialized physics solver archetype with dominance in pre-simulation data preparation workflows. IBM Corporation and Informatica represent data infrastructure specialists with enterprise-grade masking and virtualization capabilities.
| Leading Market Players |
|---|
| Dassault Systèmes |
| Autodesk |
| IBM Corporation |
| Delphix |
| MSC Software Corporation |
| Siemens Digital Industries Software |
| Informatica |
| K2View |
| ANSYS |
| Others |
Value Chain & Pricing Dynamics
GPU compute cost volatility tied to NVIDIA supply allocation determines both tiered pricing spreads and supply chain configuration across cloud-native and on-premises deployment modes. Defense primes absorb premium infrastructure costs for cleared systems integrator access, while mid-tier manufacturers gravitate toward consumption-based elasticity.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and after-sales service intensity. Premium tiers embed EASA-compliant chain-of-custody logging and FDA 21 CFR Part 11 validation support, commanding sustained margins from aerospace and medical device accounts. Price erosion runs through standard tiers as subscription consumption models displace perpetual licensing among South Korean semiconductor equipment designers and Japanese industrial machinery producers. Automotive OEMs exhibit highest price sensitivity, prioritizing pay-per-simulation contracts aligned with 18-24 month vehicle development cycles.
Supply Chain Analysis
US export-control restrictions on GPU and simulation software technologies limit flows to Chinese state-owned aerospace and rail equipment producers under MIIT digital twin mandates. Supply concentrates in Germany for automotive validation platforms, the United States for defense-aerospace infrastructure, and China for sovereign cloud deployments serving battery thermal validation workflows. Raw material dependencies center on NVIDIA GPU allocation, energy pricing in data center clusters, and cleared personnel pools for classified programs. Single-source vulnerability in GPU supply creates input cost uncertainty. Distribution runs through direct enterprise sales, hyperscaler marketplaces, and systems integrator partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Managed service and compliance-update layers expand faster than perpetual license hardware, creating durable recurring-revenue pools for platform vendors with embedded governance tooling.
For Market Incumbents: Build switching-cost moats through deep PLM integration and proprietary metadata schemas that resist heterogeneous legacy format extraction. Anchor aerospace accounts with EASA-compliant chain-of-custody features as EU AI Act risk classification rules harden. Extend backward integration into sovereign cloud infrastructure partnerships across Germany, China, and India to preempt data sovereignty fragmentation. For New Entrants and Emerging Players: Establish a beachhead in India's PLI scheme automotive segment, where domestic EV manufacturers lack mature test data infrastructure for battery pack qualification. Target data virtualization solutions for aerospace suppliers grappling with cross-border EASA-regulated dataset federation. Pursue OEM supplier qualification requirements as the primary go-to-market channel, positioning physics-informed neural network governance as mandatory inclusion. For Investors and Strategic Acquirers: EU AI Act implementation reshapes the acquisition landscape toward platforms with pre-built training data provenance documentation and human oversight mechanism tooling. Five-to-ten year viability favors data infrastructure specialists with masking and virtualization capabilities over point-solution physics solvers. Target acquisition archetypes include regional cloud providers with sovereign data residency certifications. The signal to watch is EASA codification of machine learning surrogate model governance frameworks.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Deep 3DEXPERIENCE or Teamcenter embedding captures automotive and aerospace switching costs. |
| Strategic Partnership | Systems integrator alliances with cleared personnel pools unlock classified defense program access. |
| Geographic Expansion | Regional cloud provider alliances in China and India address data sovereignty fragmentation. |
| Product Launch | Compliance-as-a-service modules for EU AI Act risk classification preempt regulatory scrutiny. |
| Acquisition of Specialist Firm | Data masking and virtualization tooling captures expanding privacy-regulation margin pools. |
Study Parameters
A standing panel of simulation platform engineering directors, PLM integration specialists, regulatory compliance officers, and defense procurement managers provided ongoing calibration across primary interview rounds. Secondary validation drew from EASA certification bulletins, FDA 510(k) submission databases, MIIT digital twin policy releases, and hyperscaler capex disclosures. Bottom-up segment sizing triangulated against top-down market construction.
Scenario-bracketing anchored projections across conservative, baseline, and accelerated cloud migration pathways. Modeled dimensions span deployment architecture, end-use industry vertical, integration complexity with legacy PLM systems, and regional regulatory cluster. CAGRs derived from elasticity-adjusted adoption curves and GPU supply-constraint scenarios. Forecast inputs include battery EV platform simulation iteration volumes and EASA AI-based certification pathway progression.
Sensitivities concentrate around NVIDIA supply allocation shifts, EU AI Act implementation timing, and defense sector cleared systems integrator pool contraction. Forecasts reflect documented assumptions on cloud migration elasticity and regulatory harmonization. Material shifts in GPU compute cost structures or data sovereignty enforcement patterns would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Digital Thickness Gauge Market
Test and Measurement
Backside Power Delivery Network (BPDN) Analysis Test Equipment Market
Test and Measurement
Digital Oscilloscope Market
Test and Measurement
Latin America Measurement and Test Equipment Market
Test and Measurement
Shock Test Machines Market
Test and Measurement
Europe NDT Equipment Market
Test and Measurement
Ultrasonic Thickness Gauge Market
Test and Measurement
Telescopic Inspection Mirror Market
Test and Measurement
Stress Test Chamber Market
Test and Measurement
Bursting Strength Tester Market
Test and Measurement
Failure Analysis Market
Test and Measurement
Automated Test Equipment Market
Test and Measurement
Electric Vehicle Edrive Test System Market
Test and Measurement
Modular Test Equipment Market
Test and Measurement
Battery CT Inspection Market
Test and Measurement
Over-The-Air (OTA) Testing Market