
 Active Dosimeter Market | 2026-2036
Active Dosimeter Market Size, Share, and Industry Trends Forecast 2026-2036
Active Dosimeter Market Outlook
Modular sensor packaging with swappable probe heads is realigning procurement patterns across nuclear utilities and hospital networks. Mirion Technologies, Inc. leverages its captive semiconductor fabrication to control detector consistency at scale. Thermo Fisher Scientific Inc. anchors its position through deep integration with laboratory informatics platforms. Polimaster Inc differentiates via hardened designs purpose-built for defense and emergency response channels.
An active dosimeter is a self-contained radiation measurement instrument that incorporates a solid-state or gas-filled detector, signal processing electronics, and a real-time display to quantify cumulative or instantaneous dose equivalent in sieverts or rem. The device performs continuous ionization detection or scintillation counting to alert wearers before regulatory exposure thresholds are breached. Personal dosimeters lead the product mix because occupational safety mandates in healthcare and nuclear operations require individual tracking. Electronic dosimeters within the technology category represent the fastest-expanding segment as digital telemetry replaces passive badge systems. Environmental dosimeters carry narrower volume but command premium pricing where perimeter monitoring around particle accelerators and waste facilities demands certified data logging.
The FDA enforces 21 CFR Part 20 performance criteria for medical radiation worker monitoring, while the NRC mandates 10 CFR Part 20 compliance across commercial nuclear licensees. IEC 61526 international standards define electromagnetic immunity and dose measurement uncertainty thresholds that manufacturers must satisfy for CE marking and global market access. Stakeholders should track how EPA radionuclide reporting rules and state-level nuclear emergency preparedness audits reshape replacement cycles for legacy passive systems.
Market Dynamics
Real-time telemetry integration is compressing replacement cycles for passive badge systems across healthcare and nuclear utilities, forcing vendors to restructure hardware-service bundling.
Growth Catalysts
- FDA 21 CFR Part 20 mandates:Medical radiation worker monitoring requirements in the United States are accelerating hospital procurement of electronic dosimeters with auditable data logging.
- IEC 61526 electromagnetic immunity standards:CE marking prerequisites are filtering out uncertified suppliers and consolidating procurement toward validated manufacturers.
- Germany's TÜV-certified calibration networks:Industrial radiography clusters around Munich and Hamburg are standardizing on traceable measurement protocols that favor digital systems.
Market Restraints
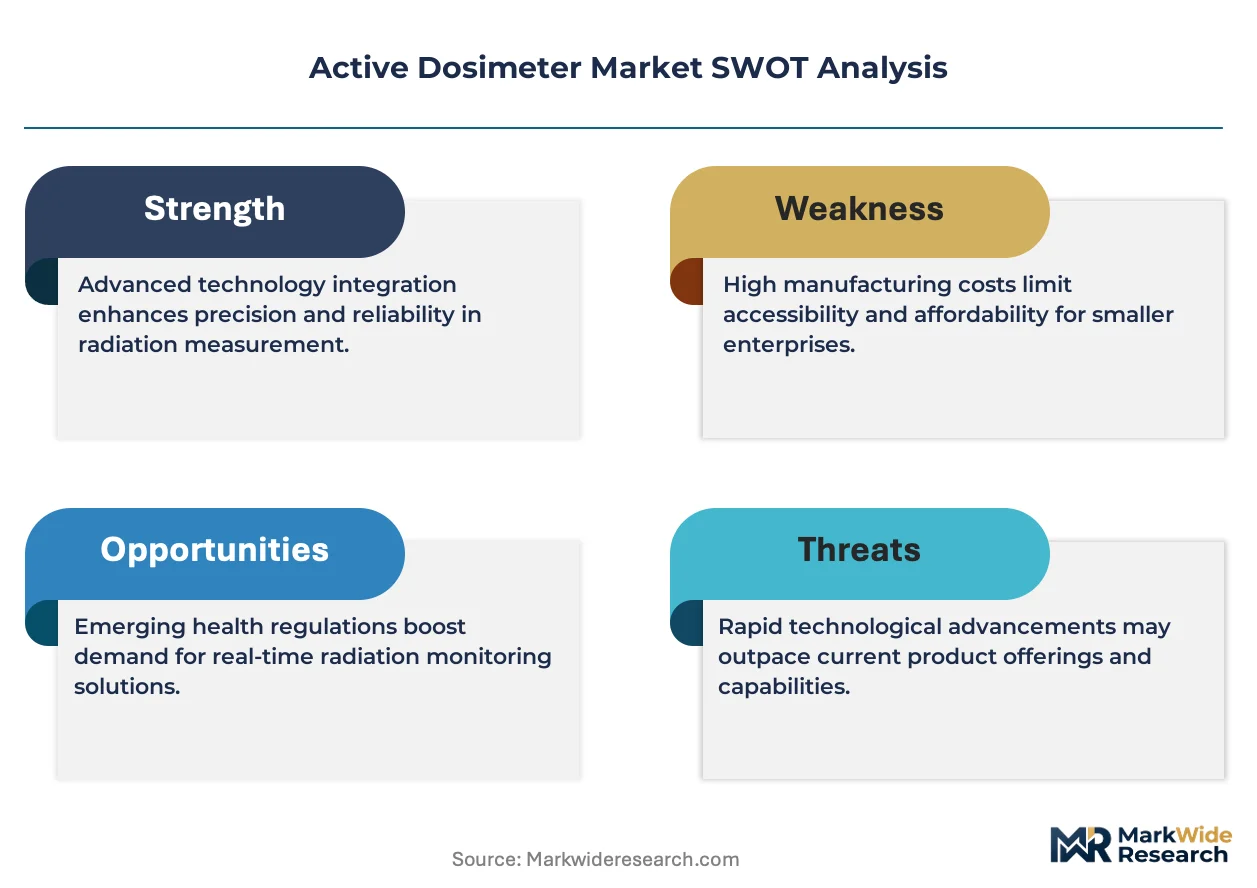
- Semiconductor detector substrate costs:Silicon photomultiplier and PIN diode wafer prices fluctuate with foundry capacity allocation, squeezing hardware margins.
- Single-source scintillator crystal supply:Thallium-doped sodium iodide production concentrates in limited geographies, creating vulnerability for gamma-sensitive probe manufacturers.
- NRC 10 CFR Part 20 compliance complexity:Commercial nuclear licensees face multi-layer approval processes that extend sales cycles and elevate pre-qualification costs.
Strategic Opportunities
- India's expanding radiation oncology infrastructure:Government hospital procurement under the PLI scheme is opening volume contracts for cost-optimized electronic dosimeters.
- Cloud-connected fleet management platforms:Subscription-based dose data analytics are displacing one-time hardware sales in multi-site hospital networks.
- Japan's decommissioning workforce surge:Fukushima-area remediation contracts are generating demand for hardened, high-range dosimeters with satellite telemetry.
Industry Challenges
- Cross-disciplinary firmware engineering:Competent developers who bridge radiation physics, embedded systems, and cybersecurity remain scarce.
- IEC 61526 recertification timelines:Revision cycles for electromagnetic immunity testing create 12-18 month gaps between design updates and market authorization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Active Dosimeter Market |
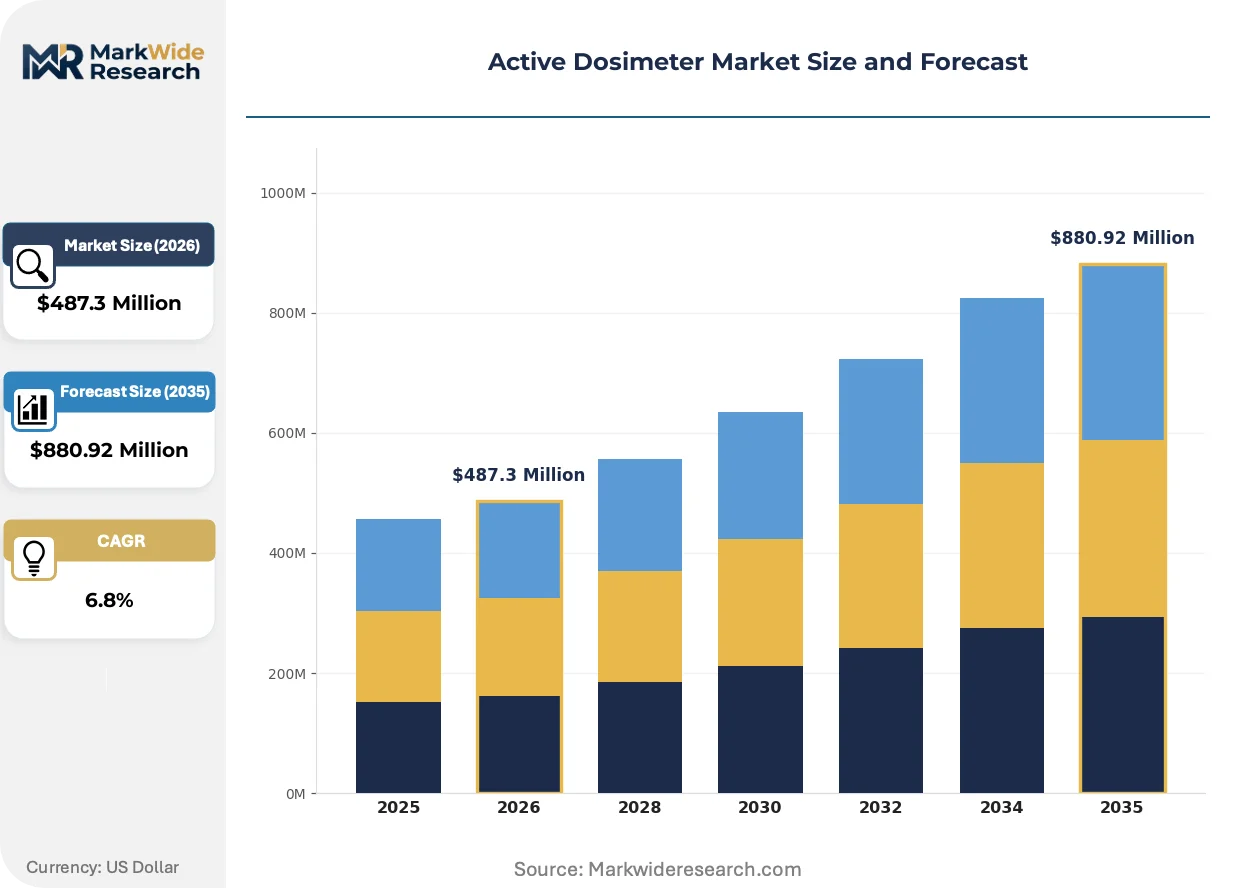
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Personal Dosimeter, Environmental Dosimeter, Area Dosimeter, Surface Dosimeter Technology: Optically Stimulated Luminescence, Electronic Dosimeters, Thermoluminescent Dosimeters, Ionization Chamber End User: Medical Facilities, Nuclear Power Plants, Research Laboratories, Industrial Sites Application: Radiation Protection, Environmental Monitoring, Industrial Safety, Research Applications |
| Companies Covered | Fuji Electric Co., Ltd., Polimaster Inc, Mirion Technologies, Inc., Tracerco Limited, Atomtex, Thermo Fisher Scientific Inc., Ludlum Measurements, Inc., Rotunda Scientific Technologies LLC, Landauer, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Active Dosimeter Market Strategic Shifts
Digital telemetry architectures are displacing passive film-badge infrastructure, while modular hardware platforms enable rapid sensor reconfiguration without full device replacement.
Silicon photomultiplier arrays are expanding into compact personal dosimeter designs, replacing traditional photomultiplier tubes with solid-state alternatives that tolerate magnetic fields and mechanical shock. Nuclear medicine departments in the United States are adopting these devices for technetium-99m and fluorine-18 handling protocols. The technology is expanding into wearable form factors previously dominated by passive systems.
The European Union's Medical Device Regulation (MDR) is tightening post-market surveillance requirements for radiation monitoring equipment sold under CE marking. Manufacturers must now maintain technical documentation and vigilance reporting systems that mirror pharmaceutical traceability standards. Class IIa dosimeter suppliers are responding by embedding unique device identification and software bill of materials into firmware architectures.
Hospital procurement departments are consolidating vendor relationships through multi-year managed service agreements that bundle hardware, calibration, and cloud analytics. Traditional distributor networks face margin compression as original equipment manufacturers build direct field service organizations. This pattern is most visible in Germany's university hospital clusters, where centralized purchasing offices negotiate enterprise-wide dose monitoring contracts.
Active Dosimeter Market Segmentation
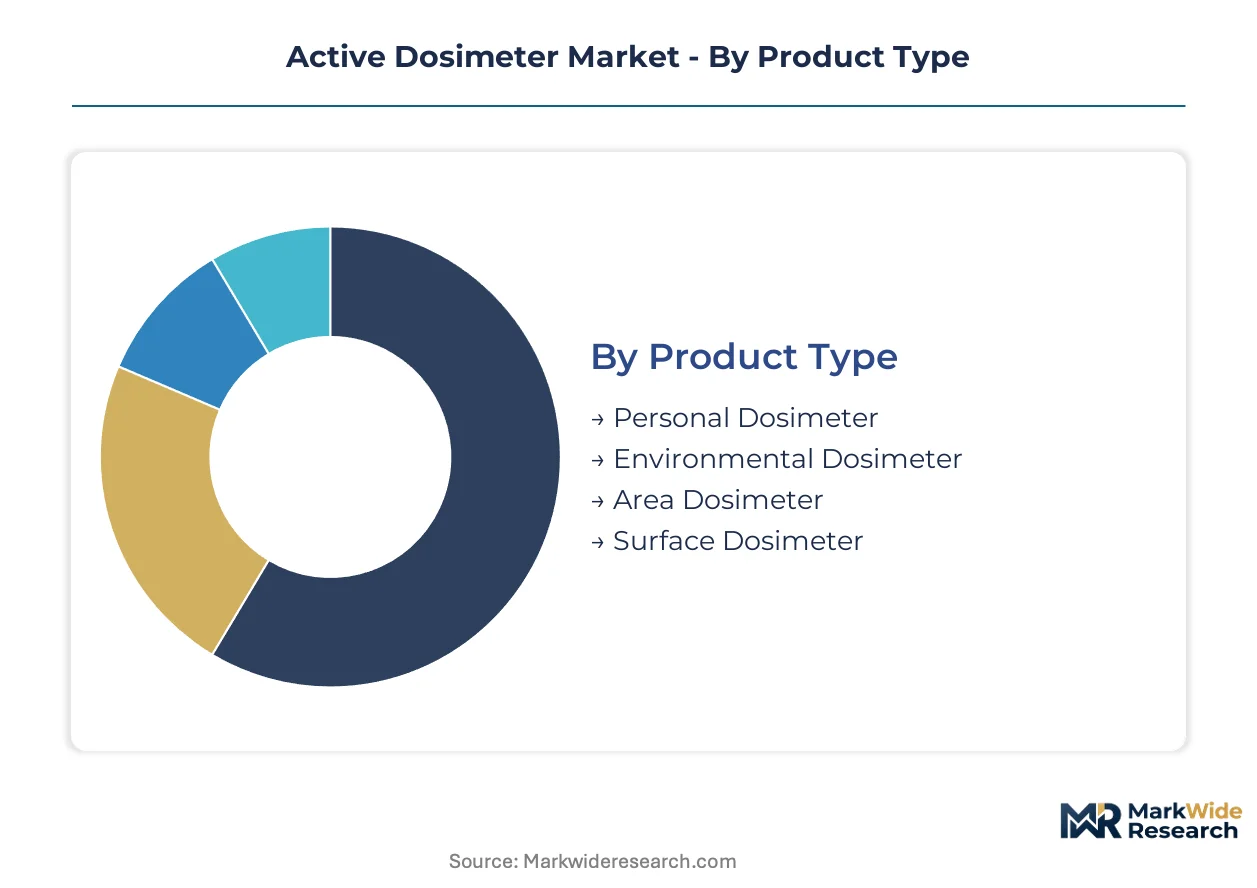
Segmentation in the active dosimeter market reveals how distinct technical specifications, deployment environments, and regulatory exposure levels drive procurement decisions across healthcare, nuclear, and industrial verticals. Understanding these divides helps vendors align detector sensitivity ranges, telemetry capabilities, and calibration protocols with specific operational hazards and compliance frameworks.
Product Type:
Form factor and deployment mobility define how radiation detection hardware integrates with personnel workflows and fixed monitoring infrastructure.
- Personal Dosimeter:Self-contained wearable units with solid-state detectors and real-time displays track cumulative dose equivalent for individual workers. Occupational safety mandates from the FDA and NRC in the United States require these devices across hospital radiology departments and commercial nuclear licensees, compressing replacement cycles for legacy passive badge systems.
- Environmental Dosimeter:Stationary or semi-portable systems with certified data logging capabilities monitor perimeter radiation levels around particle accelerators, waste storage facilities, and decommissioning sites. Perimeter monitoring contracts at Germany's industrial radiography clusters and Japan's Fukushima remediation zones command premium pricing for hardened, high-range configurations.
- Area Dosimeter:Networked detector arrays provide continuous coverage of controlled zones with alarm thresholds tied to facility access systems. These installations dominate nuclear power plant containment buildings and cyclotron vaults where spatial dose mapping replaces individual tracking.
- Surface Dosimeter:Contamination detection probes with swipe or direct measurement modes identify radioactive material deposition on equipment and personnel. Research laboratories handling unsealed sources in the United States and France rely on these for exit monitoring protocols.
Mature deployment sits with personal dosimeters across established healthcare and nuclear workforces. Newer deployment is concentrated in environmental dosimeters as perimeter monitoring requirements expand around particle therapy centers and legacy waste facilities.
Technology:
Detector physics and signal processing architectures determine measurement uncertainty, electromagnetic immunity, and form factor constraints across regulatory compliance tiers.
- Electronic Dosimeters:Digital systems incorporating PIN diodes, silicon photomultipliers, or solid-state scintillators with integrated microprocessors deliver instantaneous dose rate readouts and telemetry connectivity. Hospital networks in Germany's university hospital clusters and nuclear utilities in the United States are displacing passive film-badge infrastructure with these devices under FDA 21 CFR Part 20 and IEC 61526 mandates.
- Optically Stimulated Luminescence:Passive累积 systems using aluminum oxide crystals with laser-stimulated readout provide retrospective dose verification for regulatory audits. These retain relevance where battery-free operation and archival traceability outweigh real-time alerting requirements.
- Thermoluminescent Dosimeters:Lithium fluoride or calcium fluoride crystals heated to release stored light energy continue serving as legal dose-of-record instruments in many jurisdictions. TÜV-certified calibration networks in Germany maintain extensive infrastructure for these systems despite digital displacement pressures.
- Ionization Chamber:Gas-filled detectors with precise energy response characteristics anchor reference-grade measurements and high-range emergency monitoring. These occupy calibration laboratories and post-accident response kits where absolute accuracy overrides portability constraints.
Electronic dosimeters are gaining share fastest as digital telemetry architectures reshape procurement toward connected fleet management. Thermoluminescent systems retain entrenched positions where regulatory acceptance cycles lag technology adoption.
End User:
Operational hazard profiles and regulatory oversight intensity create distinct performance requirements for detector sensitivity, environmental hardening, and data documentation.
- Medical Facilities:Radiation oncology departments, nuclear medicine suites, and interventional radiology labs require compact wearable devices with low-energy photon sensitivity for technetium-99m and fluorine-18 handling. The FDA's 21 CFR Part 20 framework mandates individual monitoring with auditable data logging across United States hospital systems.
- Nuclear Power Plants:Commercial licensees under NRC 10 CFR Part 20 deploy mixed fleets of personal and area monitors across containment, fuel handling, and radioactive waste management zones. Multi-layer approval processes extend sales cycles but create sticky relationships with validated suppliers.
- Research Laboratories:Universities and national laboratories handling diverse radionuclide inventories demand modular platforms with swappable probe heads for alpha, beta, gamma, and neutron discrimination. CERN and comparable facilities drive specifications for electromagnetic immunity in high-field environments.
- Industrial Sites:Non-destructive testing operations, well-logging crews, and mineral processing facilities require cost-optimized devices with mechanical durability and simplified calibration logistics. India's industrial radiography expansion under government procurement programs is opening volume contracts in this tier.
Medical facilities concentrate procurement volume for compact electronic wearables. Research laboratories are expanding fastest as neutron source facilities and radioisotope production centers multiply across Europe and Asia-Pacific.
Application:
Functional purpose shapes whether dosimeters serve compliance documentation, worker protection, environmental surveillance, or scientific measurement objectives.
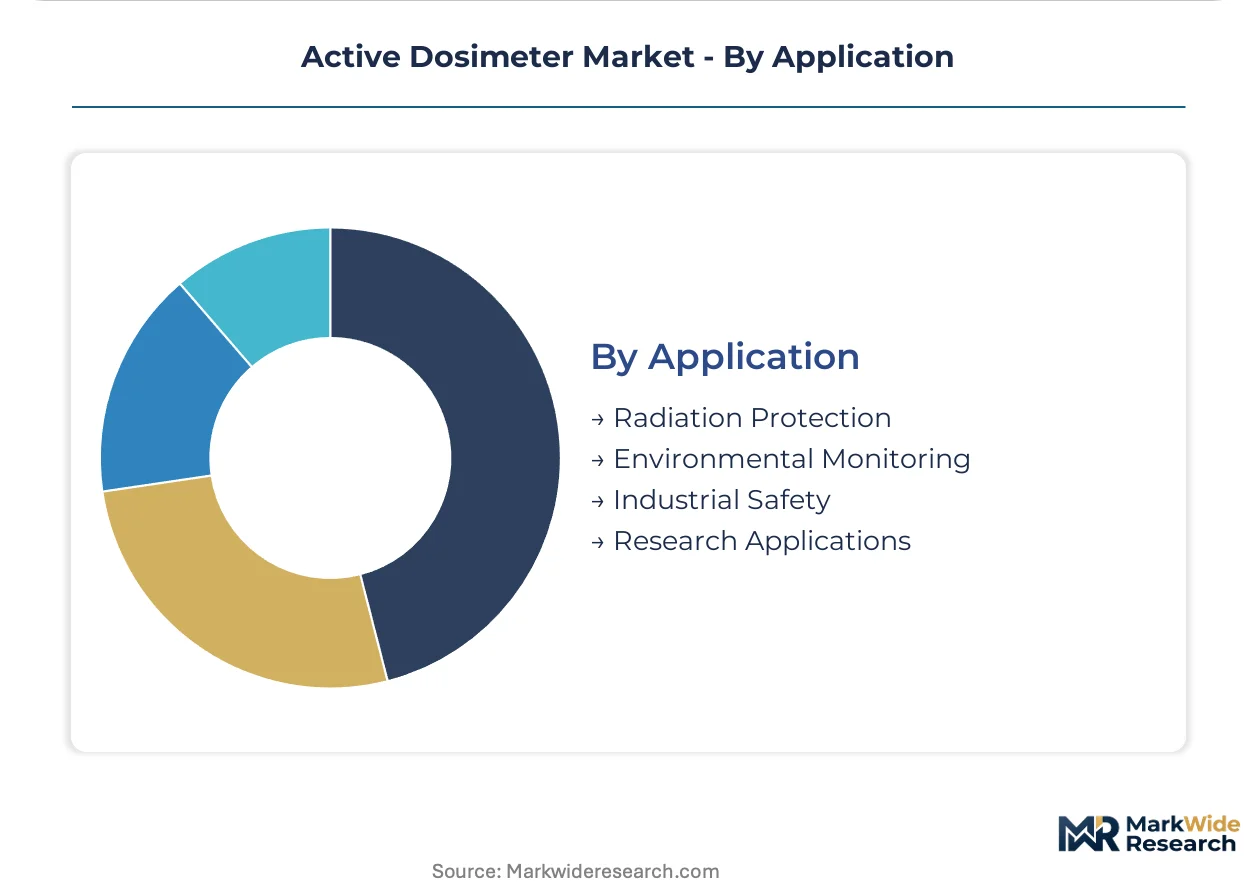
- Radiation Protection:Occupational dose monitoring for regulatory compliance and ALARA program implementation dominates procurement volume across all end-user verticals. These applications prioritize traceable calibration chains and auditable data management systems.
- Environmental Monitoring:Perimeter surveillance and effluent tracking around licensed facilities require networked sensors with meteorological data integration and regulatory reporting automation. EPA radionuclide reporting rules in the United States reshape replacement cycles for legacy passive systems in this category.
- Industrial Safety:Hot work permits, confined space entry, and emergency response protocols demand alarming personal devices with immediate hazard notification. Germany's industrial radiography sector standardizes on TÜV-certified digital systems for these workflows.
- Research Applications:Precise dose mapping for beam characterization, shielding validation, and biological effect studies requires reference-grade instrumentation with energy-resolved spectroscopy capabilities. National metrology institutes and accelerator facilities drive specifications here.
Radiation protection commands the largest installed base across mature healthcare and nuclear workforces. Environmental monitoring is climbing fastest as climate resilience planning and legacy site remediation expand sensor network deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones for radiation technology manufacturing in Malaysia and Vietnam are accelerating component assembly concentration. These zones offer tariff exemptions on semiconductor substrates and scintillator crystals that anchor detector production costs.
United States
Hospital network consolidation is driving enterprise-wide dose monitoring procurement across the Mayo Clinic and Cleveland Clinic systems. FDA 21 CFR Part 20 enforcement actions against non-compliant facilities accelerated electronic dosimeter replacement in 2024. The Department of Energy's national laboratory complex around Oak Ridge and Los Alamos sustains demand for research-grade instrumentation with neutron discrimination capabilities.
Germany
Industrial radiography clusters around Munich and Hamburg are standardizing on TÜV-certified digital systems for non-destructive testing workflows. The EU Medical Device Regulation (MDR) is forcing firmware updates and unique device identification embedding across CE-marked equipment. Siemens Healthineers' manufacturing presence in Erlangen anchors a supplier ecosystem serving university hospital networks across Bavaria and Baden-Württemberg.
Japan
Fukushima-area decommissioning contracts are generating sustained demand for hardened, high-range dosimeters with satellite telemetry integration. METI procurement guidelines favor domestic suppliers for radiation monitoring equipment in nuclear emergency preparedness programs. The Japan Atomic Energy Agency's research campuses in Tokai and Oarai drive specifications for reference-grade ionization chamber systems.
India
Government hospital procurement under the PLI scheme is opening volume contracts for cost-optimized electronic dosimeters in radiation oncology departments. CDSCO medical device registration requirements are filtering out uncertified imports and consolidating procurement toward validated manufacturers. The Tata Memorial Centre in Mumbai and AIIMS Delhi anchor demand concentration for personal monitoring systems in tertiary care networks.
China
Particle therapy center construction in Shanghai and Guangzhou is expanding perimeter monitoring requirements around proton and heavy-ion facilities. NMPA Class II medical device approval timelines are extending market entry for foreign manufacturers while domestic producers capture hospital procurement. The Chinese Academy of Sciences' Institute of High Energy Physics in Beijing drives research applications for precision dose mapping instrumentation.
Active Dosimeter Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across detector fabrication and systems integration tiers. The vendor base separates into three strategic archetypes: captive semiconductor fabricators controlling detector consistency, laboratory informatics integrators anchoring data platform positions, and hardened equipment specialists serving defense and emergency response channels. Consolidation pressure is intensifying as cloud-connected fleet management platforms displace traditional distributor networks. Multi-year managed service agreements bundling hardware, calibration, and analytics are compressing margins for pure hardware vendors.
Among diversified technology conglomerates, Thermo Fisher Scientific Inc. and Fuji Electric Co., Ltd. exemplify scale-driven positions spanning laboratory equipment through industrial instrumentation. Mirion Technologies, Inc. occupies a specialized tier with captive semiconductor fabrication capabilities. Polimaster Inc represents the hardened equipment archetype with purpose-built designs for defense and emergency response deployment. These three anchors illustrate how competitive positioning stratifies across manufacturing depth, software integration, and environmental hardening vectors.
| Leading Market Players |
|---|
| Fuji Electric Co., Ltd. |
| Polimaster Inc |
| Mirion Technologies, Inc. |
| Tracerco Limited |
| Atomtex |
| Thermo Fisher Scientific Inc. |
| Ludlum Measurements, Inc. |
| Rotunda Scientific Technologies LLC |
| Landauer, Inc. |
| Others |
Value Chain & Pricing Dynamics
Hospital procurement committees and nuclear utility fleet managers concentrate buying power through multi-year enterprise contracts, compressing hardware margins while elevating subscription-based telemetry services as the dominant revenue model. This buyer concentration creates asymmetric pricing power where calibration certification tiers and real-time data analytics bundling determine contract winners.
Pricing Analysis
Short lead-time premiums of 15-25% apply to IEC 61526-certified electronic dosimeters needed for emergency NRC compliance deadlines, while spot inventory of thallium-doped sodium iodide crystals trades at volatile premiums. Three-tier pricing structure across premium, standard, and economy levels separates TÜV-certified calibration networks from hospital-grade wearables and industrial radiography cost-optimized units. Pricing pressure stems from semiconductor foundry capacity allocation squeezing silicon photomultiplier substrate costs. Industrial sites and emerging market government tenders exhibit highest price sensitivity, whereas nuclear power plant licensees prioritize certification reliability over unit economics.
Supply Chain Analysis
Dual-sourcing mandates from NRC-licensed nuclear utilities and FDA-regulated hospital networks require qualified suppliers for both silicon photomultiplier arrays and PIN diode substrates. Manufacturing concentrates in Japan, Germany, and the United States for detector fabrication, while thallium-doped sodium iodide crystal growth centers on limited Eastern European and North American facilities. Raw material dependencies include high-purity silicon wafers, rare-earth scintillator dopants, and hermetic packaging ceramics. Single-source vulnerability in thallium-doped crystal supply creates tariff exposure and geopolitical risk. Distribution runs through TÜV-certified calibration laboratories and OEM direct field service organizations, displacing traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scintillator crystal production capacity constraints and qualified semiconductor foundry bottlenecks prop pricing power for manufacturers with captive supply or backward integration into detector substrates.
For Market Incumbents: Acquire certified calibration laboratory networks to lock in recurring revenue streams and defend against cloud-native fleet management entrants. Mirion Technologies' captive semiconductor fabrication demonstrates how upstream control over PIN diode consistency neutralizes substrate cost volatility. Incumbents should embed unique device identification and software bill of materials into firmware architectures ahead of EU MDR enforcement tightening. For New Entrants and Emerging Players: Begin with India's PLI scheme government hospital procurement, where CDSCO registration requirements filter out uncertified imports and volume contracts favor cost-optimized electronic dosimeters. Cloud-connected dose analytics for multi-site hospital networks represents the most penetrable white space, displacing one-time hardware sales with subscription models. A direct field service organization bypassing distributor markups offers the strongest go-to-market angle against entrenched OEMs. For Investors and Strategic Acquirers: The window for entry favors semiconductor fabrication specialists with radiation-hardened process expertise and firmware developers bridging physics simulation with embedded cybersecurity. Long-term viability hinges on regulatory certification moats widening as IEC 61526 recertification timelines extend to 12-18 months. Watch for EPA radionuclide reporting rule revisions as the signal indicating replacement cycle acceleration for legacy passive systems.| Strategic Initiative | Industry Significance |
|---|---|
| IEC 61526 Recertification Investment | CE marking prerequisites filter uncertified suppliers and consolidate procurement toward validated manufacturers. |
| Cloud-Connected Fleet Management Platform | Subscription-based dose analytics displace one-time hardware sales in multi-site hospital networks. |
| TÜV Calibration Laboratory Acquisition | Traceable measurement protocols in Germany's industrial radiography clusters favor integrated service providers. |
| Silicon Photomultiplier Array Development | Solid-state alternatives replace photomultiplier tubes for magnetic field tolerance in nuclear medicine departments. |
| India PLI Scheme Volume Contract | Government hospital procurement under production-linked incentives opens cost-optimized electronic dosimeter markets. |
Study Parameters
Independent corroboration across radiation safety officers at nuclear utilities, biomedical engineers at university hospital networks, and procurement managers at Germany's TÜV-certified calibration laboratories underwrites the qualitative findings. Primary interviews with dosimeter firmware developers, semiconductor foundry specialists, and regulatory affairs consultants combined with secondary validation from FDA 21 CFR Part 20 enforcement records, IEC 61526 certification databases, and NRC 10 CFR Part 20 licensee inspection reports. Bottom-up unit shipment estimates and top-down market value reconstructions triangulate across the analysis window.
Comparable-period anchoring to historical replacement cycles for passive film-badge systems and telemetry adoption curves in hospital informatics platforms structured the projection horizon. Segmentation dimensions modeled include product type, detector technology, end-user vertical, application purpose, and regional regulatory cluster. CAGRs derive from installed base turnover rates and new facility construction pipelines. Forecast inputs incorporate semiconductor foundry capacity allocation schedules and radionuclide therapy procedure volume trajectories.
Foundry capacity reallocation, scintillator crystal supply disruption, and IEC standard revision timing are the dominant revision risks. Deviation in thallium-doped sodium iodide production geography would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Electromagnetic Compatibility Test Equipment and Testing Services Market
Test and Measurement
VXI Testing Equipment Market
Test and Measurement
Non-Destructive Testing (NDT) Service Market
Test and Measurement
Failure Analysis Equipment Market
Test and Measurement
Bursting Strength Tester Market
Test and Measurement
CCTV Tester Market
Test and Measurement
Brightness Meter Market
Test and Measurement
Wafer Testing Services Market
Test and Measurement
Oscilloscope Market
Test and Measurement
Non Destructive Testers (NDT) Equipment Market
Test and Measurement
Tensile Testing Machine Market
Test and Measurement
India Electrical Testing Services Market
Test and Measurement
Ultrasonic Flaw Detector Market
Test and Measurement
Heat Deformation Tester Market
Test and Measurement
X-Ray Inspection System Market
Test and Measurement
Psophometer Market