
 Asia-Pacific Laser Interferometer Market | 2026-2036
Asia-Pacific Laser Interferometer Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Laser Interferometer Market Insights
The gap between premium interferometric systems and commodity displacement sensors is rebalancing as foundries demand sub-nanometer repeatability for EUV mask inspection. Renishaw plc leverages its encoder-interferometer hybrid architecture to dominate high-end semiconductor metrology. Keyence Corporation competes through compact, shop-floor-ready units that reduce calibration overhead for tier-two automotive suppliers. Nikon Corporation anchors its position in optical testing through deep ultraviolet wavefront systems refined for lithography lens qualification.
A laser interferometer measures displacement, surface form, or refractive index variation by detecting phase shifts between a reference beam and a measurement beam, typically achieving resolution below one nanometer through heterodyne or homodyne detection schemes. Frequency domain interferometers lead the product type landscape due to their superior signal-to-noise ratio in vibration-prone factory environments, while fiber optic variants represent the fastest-expanding category as they enable remote sensing in vacuum chambers and cleanrooms. Semiconductor industry end users command the largest margin pool, though aerospace applications in Japan and India are gaining share as turbine blade inspection protocols tighten.
Japan's METI administers JIS standards that mandate periodic interferometric calibration for precision machine tools, while China's SAMR enforces GB national metrology standards that shape procurement criteria for domestic fabs. South Korea's MFDS alignment with ISO 17025 accreditation requirements influences supplier qualification for medical device manufacturing. Stakeholders must monitor how China's dual carbon goals reshape energy intensity standards for metrology equipment production facilities across the region.
Market Dynamics
EUV lithography node advancement below 3nm is compressing metrology tolerance windows across Taiwan and South Korean semiconductor fabs, forcing interferometer suppliers to recalibrate product architectures around sub-nanometer repeatability rather than incremental precision gains.
Growth Catalysts
- GB Calibration Mandates:China's SAMR enforcement of national metrology standards for domestic fabs is mandating interferometric traceability, creating procurement pull for certified systems in the Yangtze River Delta corridor.
- EUV Mask Inspection:Semiconductor foundries in Taiwan and South Korea require phase-shifting interferometry for multi-patterning overlay verification at sub-2nm nodes.
- JIS Periodic Recalibration:Japan's METI-administered standards mandate interferometric verification cycles for precision machine tools, sustaining replacement demand.
Market Restraints
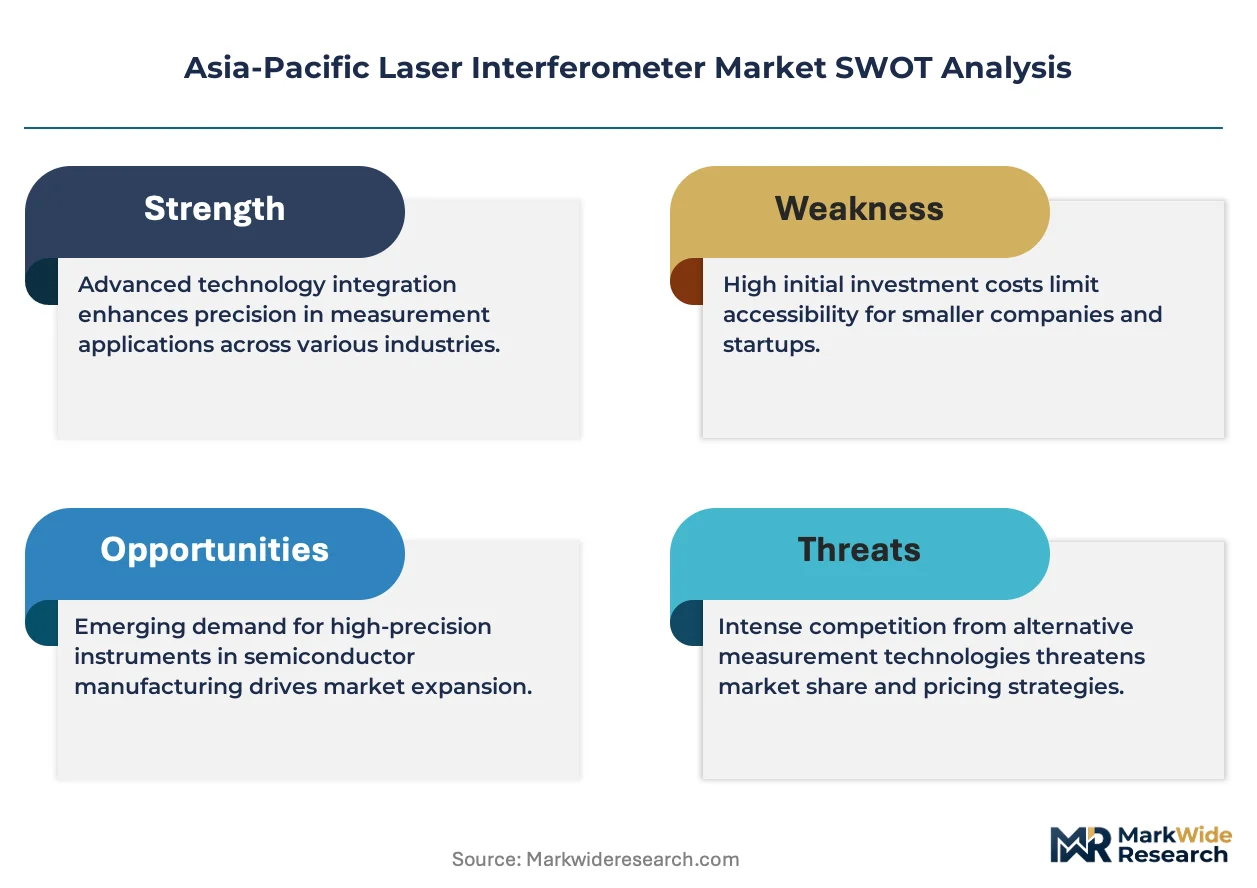
- He-Ne Laser Supply Concentration:Gas laser tube manufacturing clusters in Japan and Germany, exposing buyers to extended lead times during supply disruptions.
- Vacuum-Compatible Enclosure Costs:Stainless steel chamber fabrication and ion pump integration add 40-60% cost premiums over ambient-environment systems.
- Optical Encoder Substitution:Grating-based displacement sensors from Renishaw and Heidenhain capture mid-precision applications below 0.5 nanometer requirements.
Strategic Opportunities
- India Aerospace Metrology:Hindustan Aeronautics and DRDO laboratories are establishing turbine blade inspection protocols requiring non-contact profilometry.
- Fiber-Optic Remote Sensing:Vacuum chamber and cleanroom installations favor fiber-coupled interferometers that separate optical heads from electronics.
- Dual Carbon Alignment:China's energy intensity standards for production facilities favor suppliers with localized manufacturing and renewable power sourcing.
Industry Challenges
- Heterodyne Detection Expertise Gap:Fewer than twelve Asia-Pacific universities maintain active programs in precision interferometry, constraining field service engineer recruitment.
- ISO 17025 Accreditation Timelines:South Korean medical device suppliers face 14-18 month calibration laboratory certification cycles through MFDS alignment requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Laser Interferometer Market |
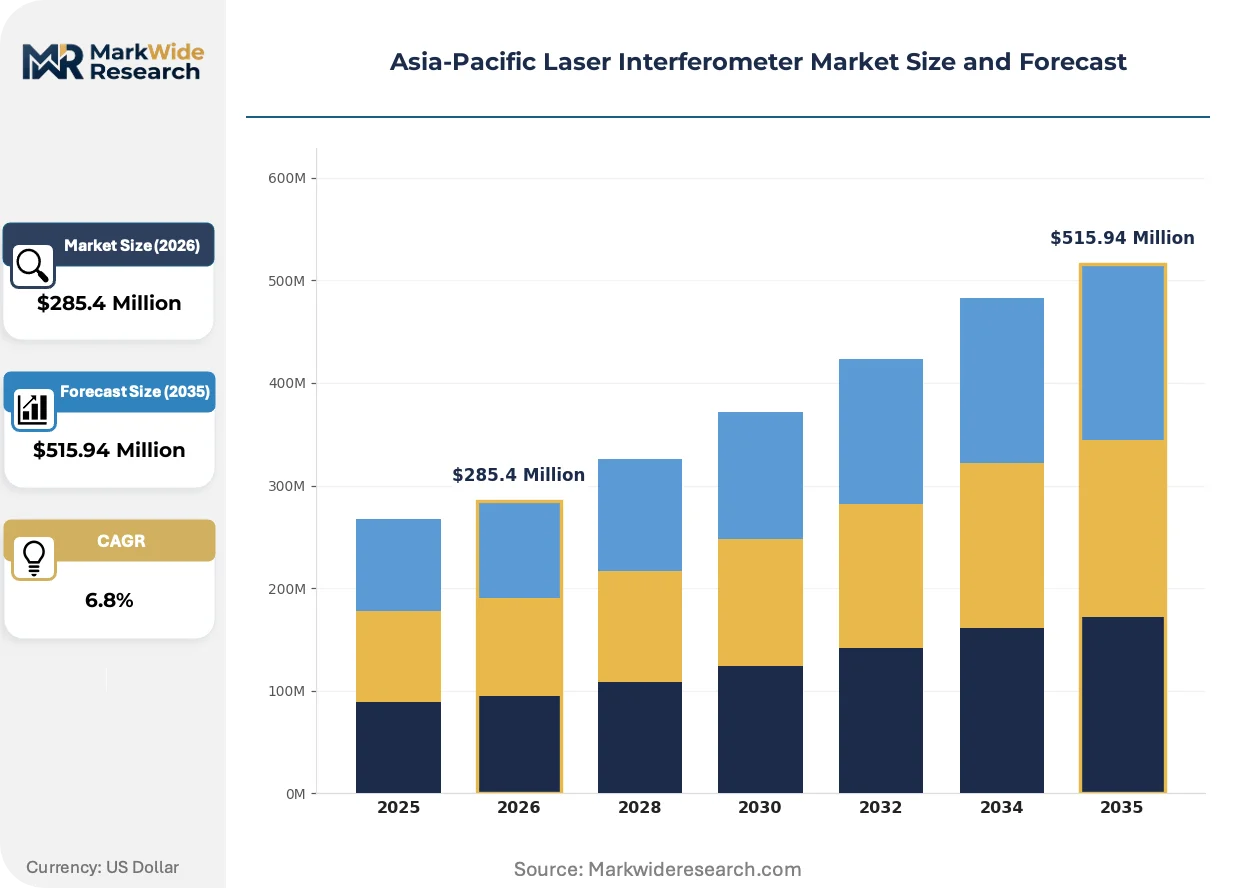
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $515.94 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Time-of-Flight, Frequency Domain, Compact, Fiber Optic Application: Optical Testing, Surface Metrology, Industrial Measurements, Microelectronic Manufacturing End User: Semiconductor Industry, Aerospace, Automotive, Research Institutions Technology: Interferometric Techniques, Digital Signal Processing, Fiber Coupling, Wavefront Sensing |
| Companies Covered | Renishaw plc, Zygo Corporation, Keyence Corporation, Nikon Corporation, Mitutoyo Corporation, Keysight Technologies, Tosei Engineering Corp., Mahr GmbH, QED Technologies International, Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Laser Interferometer Market Trends and Innovations
Frequency-domain signal processing architectures are displacing homodyne detection in vibration-prone factory floors, while fiber-optic beam delivery is decoupling measurement heads from control electronics to enable remote sensing in sealed environments.
Multi-axis simultaneous measurement systems is expanding into lithography stage qualification workflows, capturing X-Y-Z displacement and angular error motion in single acquisition cycles. Taiwan Semiconductor Manufacturing and Samsung Foundry deploy these configurations for EUV scanner baseline establishment. The technology is expanding into mask blank flatness verification, compressing inspection cycle times from sequential single-axis builds to parallel capture.
METI's 2024 precision manufacturing roadmap tightens JIS B 6190 tolerance bands for CNC machine tools, mandating interferometric verification of positioning accuracy below 100 nanometers over full travel. Japanese machine tool builders retrofit existing platforms with laser calibration systems to maintain export eligibility. Small and mid-tier suppliers face capital equipment decisions between outsourced metrology services and in-house system acquisition.
Semiconductor fabs consolidate interferometer procurement under centralized metrology engineering functions, displacing distributed purchasing by individual process modules. Equipment engineers in Hsinchu and Pyeongtaek negotiate enterprise service agreements spanning calibration, spare optics, and software maintenance. This concentration shifts vendor relationships from transactional hardware sales to multi-year performance contracts with uptime guarantees.
Asia-Pacific Laser Interferometer Market Segmentation
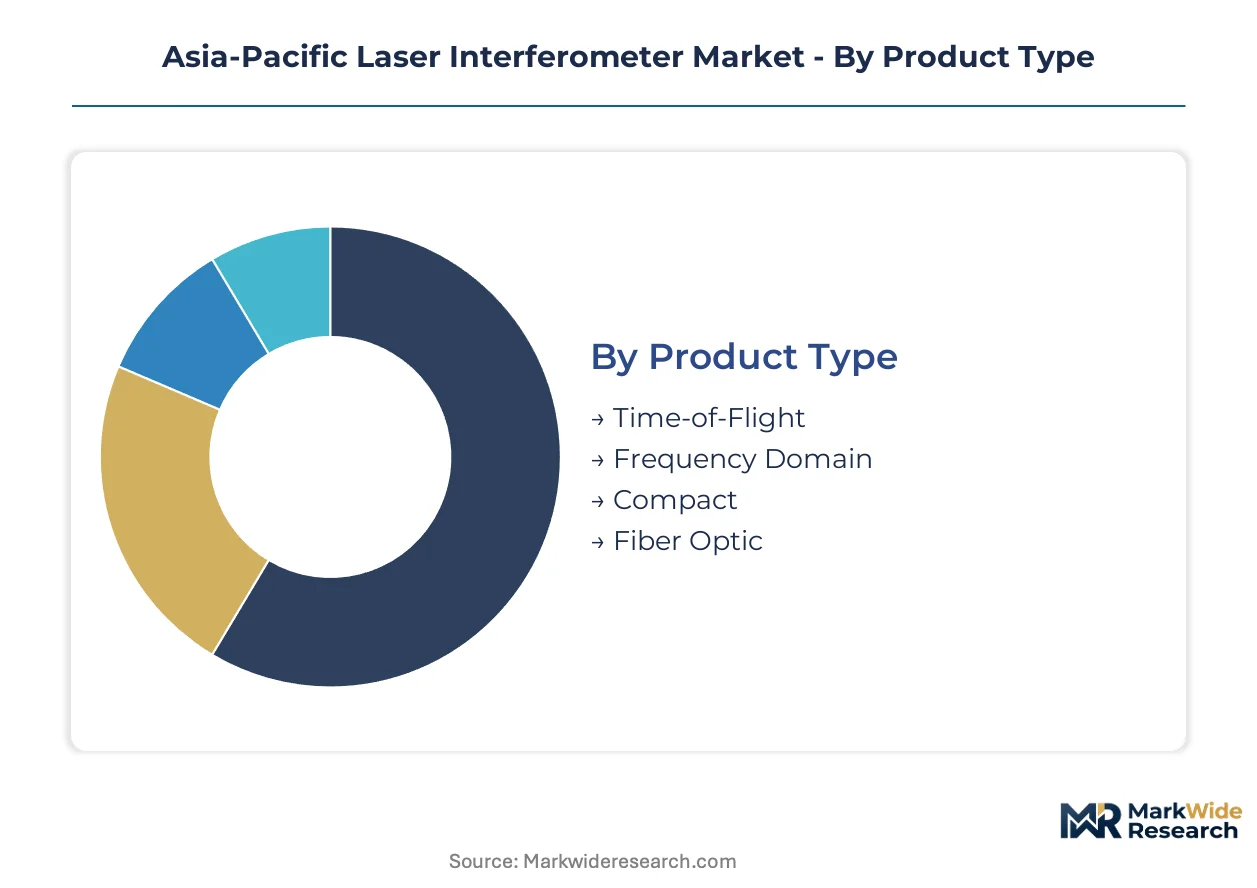
Segmentation reveals how interferometer architectures map to distinct precision requirements and integration depths across Asia-Pacific semiconductor fabs, aerospace test facilities, and automotive production lines. Understanding these boundaries clarifies where standalone metrology systems command premium pricing versus embedded sensor configurations.
Product Type:
Frequency-domain and fiber-optic architectures increasingly embed directly into lithography scanners and precision motion stages, while time-of-flight and compact units remain predominantly standalone instruments for shop-floor deployment.
- Frequency Domain:Heterodyne detection schemes achieve superior signal-to-noise ratios in vibration-prone factory environments through phase-locked loop demodulation. Taiwan Semiconductor Manufacturing and Samsung Foundry specify these systems for EUV scanner baseline establishment, with sub-nanometer repeatability now mandatory below 3nm nodes.
- Fiber Optic:Beam delivery through single-mode fiber decouples optical heads from control electronics, enabling remote sensing inside vacuum chambers and cleanrooms. China's Yangtze River Delta fabs favor this architecture for EUV mask inspection where electronics must remain outside process environments.
- Time-of-Flight:Pulsed laser architectures measure absolute distance without continuous wave reference beams, serving large-scale coordinate measurement machines in Japanese automotive stamping facilities.
- Compact:Reduced-form-factor units with integrated signal processing target tier-two automotive suppliers in South Korea's Gyeonggi Province seeking minimal calibration overhead.
Frequency domain leads volumes today; fiber optic is gaining share fastest.
Application:
Cost tiers separate qualification-grade metrology from production-line monitoring, with optical testing and microelectronic manufacturing commanding 3-5x pricing premiums over industrial measurement applications.
- Microelectronic Manufacturing:Multi-patterning overlay verification at sub-2nm nodes demands phase-shifting interferometry for mask blank flatness measurement. Hsinchu and Pyeongtaek foundries compress inspection cycles through parallel X-Y-Z capture replacing sequential single-axis builds.
- Optical Testing:Deep ultraviolet wavefront systems qualify lithography lens assemblies through Zernike polynomial decomposition of aberration signatures. Nikon Corporation dominates this segment for scanner objective qualification.
- Surface Metrology:Non-contact profilometry measures turbine blade surface finish for Hindustan Aeronautics and DRDO laboratories establishing new aerospace protocols in India.
- Industrial Measurements:Displacement monitoring for precision machine tool positioning accuracy verification falls under Japan's METI-administered JIS B 6190 tolerance mandates.
Microelectronic manufacturing commands the highest margins; surface metrology shows the steepest expansion trajectory.
End User:
Customer concentration patterns diverge sharply, with semiconductor procurement consolidating under centralized metrology engineering functions while aerospace and automotive remain fragmented across individual facilities.
- Semiconductor Industry:Enterprise service agreements now span calibration, spare optics, and software maintenance with uptime guarantees, displacing transactional hardware sales. Foundries in Taiwan and South Korea negotiate multi-year performance contracts covering entire fab footprints.
- Aerospace:Turbine blade inspection protocols in Japan and India specify non-contact profilometry for cooling hole geometry verification, with ISO 17025 accreditation timelines of 14-18 months constraining supplier qualification.
- Automotive:Tier-one suppliers in Japan's Aichi Prefecture deploy interferometric systems for powertrain component dimensional verification, while tier-two shops prioritize compact units with reduced calibration intervals.
- Research Institutions:University laboratories across the region maintain heterodyne detection expertise programs, though fewer than twelve Asia-Pacific institutions sustain active precision interferometry curricula limiting field service engineer recruitment.
Semiconductor industry leads absolute spending; aerospace is climbing the fastest.
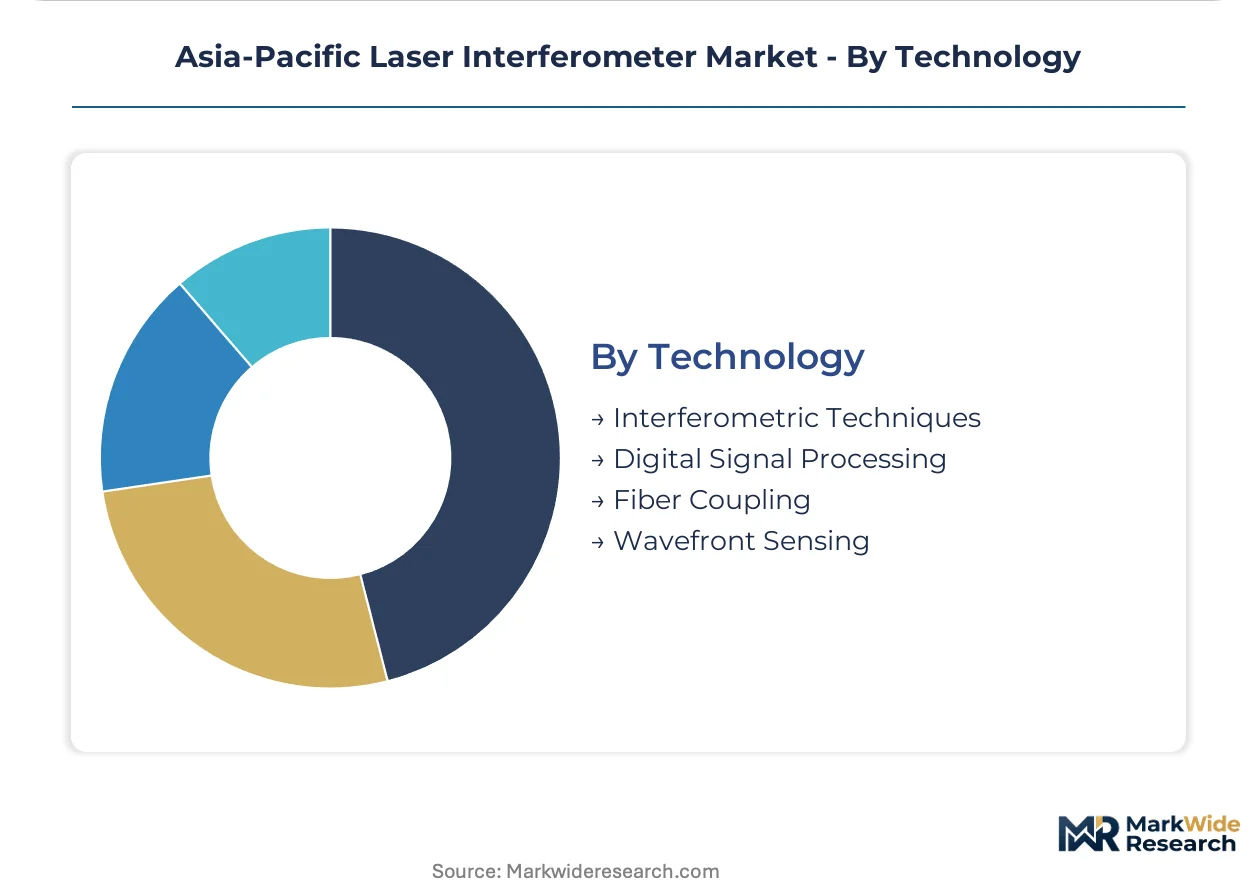
Technology:
Technology maturity curves separate established interferometric techniques from emerging digital architectures, with fiber coupling and wavefront sensing representing the frontier of embedded system integration.
- Interferometric Techniques:Homodyne and heterodyne detection schemes form the measurement foundation, with heterodyne architectures preferred for vibration immunity in production environments. Japan's precision machine tool builders retrofit existing platforms to maintain METI export eligibility.
- Digital Signal Processing:FPGA-based real-time demodulation enables multi-axis simultaneous measurement systems capturing displacement and angular error motion in single acquisition cycles.
- Fiber Coupling:Vacuum-compatible fiber feedthroughs separate optical heads from electronics, addressing China's GB calibration mandates for sealed environment traceability.
- Wavefront Sensing:Hartmann-Shack and lateral shearing interferometer configurations qualify lithography lens assemblies through pupil plane aberration mapping.
Interferometric techniques anchor current installed base; fiber coupling is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta corridor outpaces Japan's precision manufacturing belt in absolute interferometer procurement volume, though Japanese vendors maintain tighter specification control over sub-nanometer qualification systems.
China
Domestic semiconductor fabs in Shanghai and Wuxi expand metrology budgets as EUV lithography nodes advance below 7nm. SAMR enforcement of GB national metrology standards mandates interferometric traceability for equipment qualification. The Yangtze River Delta semiconductor corridor concentrates demand clusters around SMIC and Hua Hong facilities.
Japan
Machine tool builders in Nagoya and Tokyo retrofit existing platforms to maintain export eligibility under tightening tolerance bands. METI-administered JIS B 6190 standards mandate interferometric verification cycles for positioning accuracy below 100 nanometers. Chubu region precision manufacturers sustain replacement demand through periodic recalibration requirements.
South Korea
Samsung Foundry and SK Hynix facilities in Pyeongtaek and Icheon compress inspection cycles through multi-axis simultaneous measurement systems. MFDS alignment with ISO 17025 accreditation requirements shapes supplier qualification for medical device manufacturing. Gyeonggi Province tier-two automotive suppliers prioritize compact units with reduced calibration overhead.
Taiwan
TSMC and United Microelectronics in Hsinchu negotiate enterprise service agreements spanning calibration, spare optics, and software maintenance. Centralized metrology engineering functions displace distributed purchasing by individual process modules. The Hsinchu Science Park anchors procurement concentration for EUV scanner baseline establishment.
India
Hindustan Aeronautics and DRDO laboratories establish turbine blade inspection protocols requiring non-contact profilometry. The country's national aerospace regulator tightens cooling hole geometry verification standards for indigenous engine programs. Bangalore and Hyderabad defense research clusters drive initial system deployments.
Asia-Pacific Laser Interferometer Market Competitive Landscape
Top-tier vendors anchor premium semiconductor metrology, while mid-tier specialists capture shop-floor displacement monitoring. The vendor base stratifies across three functional tiers: encoder-interferometer hybrid architects, compact standalone unit fabricators, and optical testing system houses. Consolidation pressures intensify as foundries demand sub-nanometer repeatability with multi-year performance contracts. Strategic moves center on geographic manufacturing localization and fiber-coupled architecture licensing.
Within the premium-tier vector, Renishaw plc and Nikon Corporation exemplify divergent specialization models. Renishaw occupies a position among encoder-interferometer hybrid architects serving high-end semiconductor stage qualification. Nikon sits within optical testing system houses refined for lithography lens aberration mapping. Keyence Corporation represents the compact standalone unit fabricators targeting tier-two automotive suppliers with reduced-form-factor designs. These three anchors illustrate how technical architecture choices map to distinct customer concentration patterns across the region.
| Leading Market Players |
|---|
| Renishaw plc |
| Zygo Corporation |
| Keyence Corporation |
| Nikon Corporation |
| Mitutoyo Corporation |
| Keysight Technologies |
| Tosei Engineering Corp. |
| Mahr GmbH |
| QED Technologies International, Inc. |
| Others |
Pricing and Supply Chain Analysis
He-Ne laser tube fabrication costs in Japan and Germany cascade through three pricing strata, with gas laser sourcing premiums of 40-60% over solid-state alternatives compressing margins for vacuum-compatible system builders serving Taiwan and South Korean foundries.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for compact interferometric units while premium-grade systems retain pricing power through ISO 17025 certification tiers. Three-tier pricing structure across premium, standard, and economy levels separates EUV-qualified metrology from shop-floor displacement sensors, with semiconductor fabs showing least price sensitivity and tier-two automotive suppliers driving cost compression. Price differentiation hinges on traceability documentation and after-sales service bundling, with Renishaw and Nikon commanding brand premiums in lithography lens qualification workflows.
Supply Chain Analysis
Single-source vulnerability sits with Japanese and German He-Ne laser tube manufacturers, exposing buyers to extended lead times during supply disruptions. Optical component fabrication draws from Japan, Germany, and the United States, while precision motion stages feed from Taiwan and South Korea. Tariff exposure runs through specialty glass and laser gas imports, with distribution running through direct OEM partnerships for high-end systems and regional distributors for compact units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through fiber-coupled architecture substitution, which eliminates vacuum chamber fabrication premiums while opening cleanroom deployment opportunities.
For Market Incumbents: Anchor market position through backward integration into He-Ne laser tube supply and captive calibration laboratory networks in the Yangtze River Delta. Defensive investments should target fiber-optic intellectual property licensing to preempt optical encoder substitution in mid-precision applications. Renishaw's encoder-interferometer hybrid architecture demonstrates how vertical control over measurement standards sustains pricing power against grating-based displacement sensors. For New Entrants and Emerging Players: The 40-60% price gap between vacuum-compatible premium systems and ambient-environment compact units creates entry space for fiber-coupled architectures that bridge performance tiers. India's aerospace metrology protocols represent the most penetrable white-space, with Hindustan Aeronautics turbine blade inspection requirements favoring non-contact profilometry newcomers. A calibration-service-first go-to-market angle bypasses capital-intensive system manufacturing while building customer relationships. For Investors and Strategic Acquirers: Consolidation pressure builds where heterodyne detection expertise scarcity constrains field service engineer recruitment across fewer than twelve Asia-Pacific university programs. Long-term viability favors acquisition targets with fiber-optic patent portfolios and established SAMR GB calibration certification pathways. The signal to monitor is China's dual carbon goal implementation, which will reshape energy intensity standards for metrology equipment production facilities and favor localized manufacturing assets.| Strategic Initiative | Industry Significance |
|---|---|
| Fiber-Optic Architecture Licensing | Enables remote sensing in EUV vacuum chambers without stainless steel enclosure premiums. |
| GB Calibration Certification Investment | Satisfies SAMR traceability mandates for Yangtze River Delta semiconductor fabs. |
| India Aerospace Partnership Formation | Positions suppliers for Hindustan Aeronautics turbine blade inspection protocol adoption. |
| He-Ne Laser Tube Supply Agreement | Secures gas laser sourcing against Japanese and German manufacturing concentration risk. |
| Multi-Axis Measurement System Launch | Captures TSMC and Samsung Foundry EUV scanner baseline establishment demand. |
Research Methodology
Multiple input streams — equipment procurement managers at Taiwan and South Korean foundries, metrology engineering directors in Japan's Chubu region, and calibration laboratory operators across China's Yangtze River Delta — were reconciled against METI JIS standard documentation, SAMR GB mandate filings, and semiconductor capital expenditure disclosures. Secondary validation drew from patent filings in fiber-optic interferometry, trade customs data for He-Ne laser tube imports, and university precision engineering program curricula. Bottom-up unit demand estimates and top-down market sizing were triangulated to constrain forecast variance.
Data-stream reconciliation across product type, application, end user, and technology dimensions produced volume and value outputs through the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against macroeconomic indicators and industry-specific demand drivers including EUV lithography node advancement timelines and JIS B 6190 tolerance band tightening. Forecast inputs incorporated semiconductor fab metrology budget trajectories, aerospace protocol establishment schedules, and automotive supplier tier stratification.
The model assumes a particular technology adoption path; alternative pathways for fiber-coupled versus free-beam architectures would alter the outlook. Forecasts reflect assumptions about SAMR enforcement consistency, METI standard revision cadence, and He-Ne laser supply stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Electrical Conductivity Meters Market
Test and Measurement
VXI Test Equipment Market
Test and Measurement
Calorimeters Market
Test and Measurement
Inline Metrology Market
Test and Measurement
EMC Shielding and Test Equipment Market
Test and Measurement
Air Measuring Equipment Market
Test and Measurement
Ethernet Test Equipment Market
Test and Measurement
Leak Testing Machine Market
Test and Measurement
Electric Vehicle Edrive Test System Market
Test and Measurement
Fiber Optic Tester Market
Test and Measurement
Resonant Testing Machines Market
Test and Measurement
PXI Source Measure Unit Market
Test and Measurement
Insulation Testing Instrument Market
Test and Measurement
Continuous Methane Monitoring and Leak Detection Test Equipment Market
Test and Measurement
Radiation Effects Testing Market
Test and Measurement
Lithium Metal Anode Dendrite Growth Visualization Test Platforms Market