
 Permeability Testing Machine Market | 2026-2036
Permeability Testing Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Permeability Testing Machine Market Analytics
Buyer concentration among geotechnical service providers is realigning as mid-sized engineering firms consolidate testing capabilities in-house rather than outsourcing to third-party laboratories. Labthink Instruments Co., Ltd leverages its digital platform integration to capture recurring calibration revenue from centralized lab networks. AMETEK MOCON sustains premium positioning through automated gas permeability systems that reduce operator variability in high-throughput environments. Asian Test Equipments anchors emerging market penetration with manual and hybrid units priced for budget-constrained municipal soil programs.
A permeability testing machine quantifies the rate at which fluids migrate through porous media such as soil, rock, or construction composites, typically expressing results in coefficients ranging from 10⁻² to 10⁻¹¹ cm/s depending on material class. These instruments serve civil engineers, environmental consultants, and petroleum geologists who require standardized hydraulic characterization for foundation design, landfill liner verification, and reservoir simulation. Digital technology segments command margin premiums where automated data logging and cloud-connected reporting reduce field-to-office latency, while constant head configurations dominate mature construction markets with established ASTM D2434 workflows. Gas permeability applications in unconventional oil and gas represent the fastest-expanding technology-end use intersection as operators tighten wellbore integrity protocols.
ASTM International, ISO, and the US EPA collectively shape equipment specifications through methods D2434, D5084, and 9100-series groundwater monitoring standards that mandate traceable calibration chains and documented uncertainty budgets. The EPA's landfill liner assessment rules and state-level DOT material certification programs create compliance-driven replacement cycles for aging analog instruments. Stakeholders should monitor evolving interoperability requirements between field data acquisition systems and building information modeling platforms as infrastructure digitalization mandates permeate procurement specifications.
Market Dynamics
ASTM D2434 and ISO 17892 standard updates are compressing replacement cycles for analog permeability testing equipment as geotechnical firms face mandatory digital traceability requirements for federal highway project submissions.
Growth Catalysts
- Federal highway rehabilitation mandates:US DOT material certification programs require subsurface permeability verification before project approval, forcing engineering firms to expand testing fleets or upgrade to compliant digital systems.
- Landfill liner integrity protocols:EPA groundwater monitoring rules under the 9100-series standards mandate documented uncertainty budgets and traceable calibration chains for liner assessment equipment.
- Unconventional oil and gas wellbore testing:Tightening integrity protocols in shale formations drive demand for automated gas permeability systems that reduce operator variability in high-throughput environments.
Market Restraints
- Precision sensor supply concentration:High-accuracy pressure transducers and flow meters concentrate among German and Japanese component suppliers, exposing equipment manufacturers to input cost volatility and extended lead times.
- Capital intensity of automated systems:Fully digital permeability testing platforms require substantial upfront investment in cloud infrastructure and calibration networks, limiting adoption among municipal soil programs with constrained budgets.
- ASTM-ISO protocol divergence:Differences between ASTM D5084 constant head methods and ISO 17892 variable head specifications force manufacturers to maintain dual product lines or sacrifice market access.
Strategic Opportunities
- Building information modeling integration:Interoperability mandates between field data acquisition systems and BIM platforms create demand for API-connected permeability testing equipment that streams results directly to project management software.
- Municipal soil program digitization:Budget-constrained city and county engineering departments in secondary US markets present conversion opportunity from manual to hybrid testing units with staged automation upgrades.
- Carbon capture reservoir characterization:Geologic sequestration site assessment requires specialized gas permeability testing for caprock integrity verification, opening adjacent application beyond traditional civil engineering.
Industry Challenges
- Calibration technician scarcity:Traceable calibration chains under EPA and ASTM protocols require certified personnel with hydraulic testing expertise that outstrips current vocational training pipeline output.
- Legacy system integration friction:Field-to-office data latency reduction demands retrofitting analog permeability testing machines with digital logging modules, complicating warranty and performance guarantees.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Permeability Testing Machine Market |
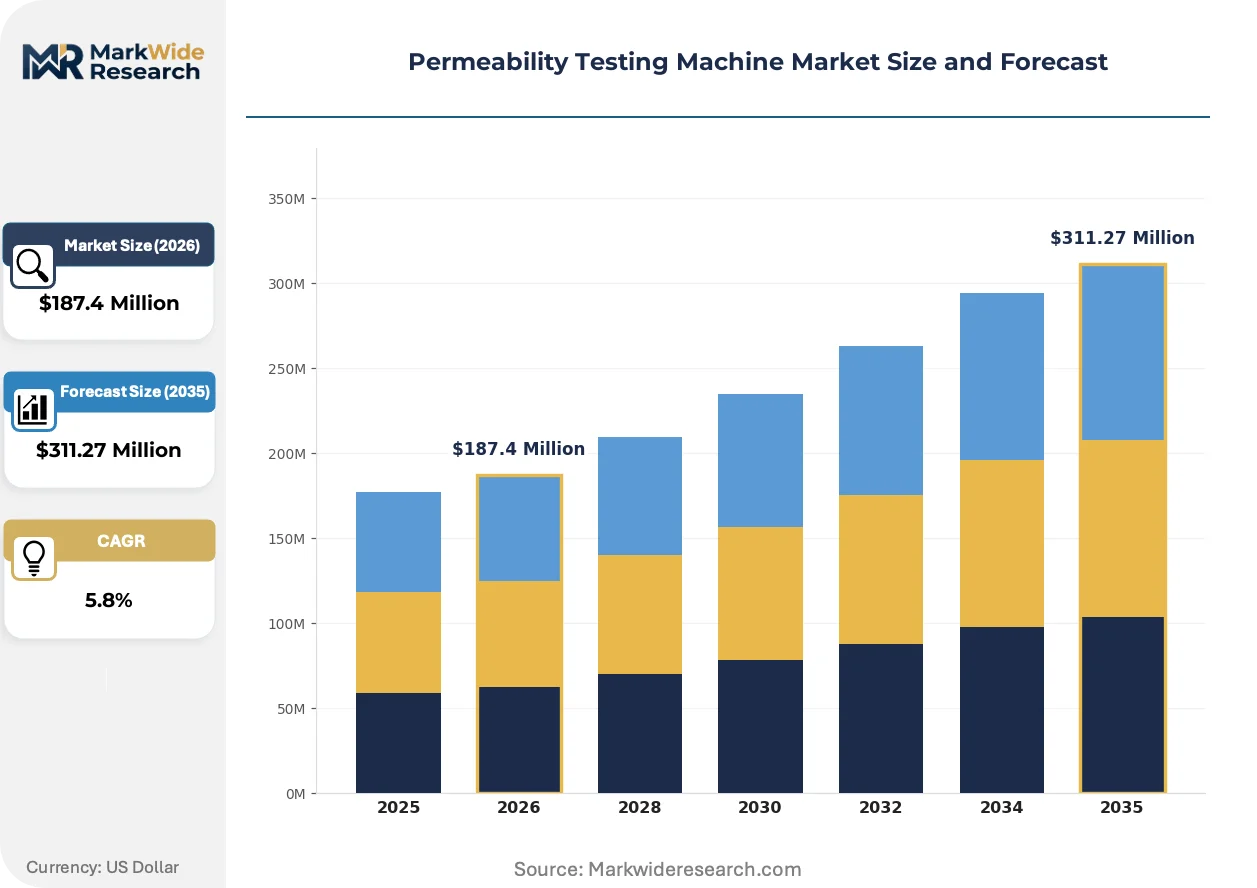
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Constant Head, Falling Head, Packer Test, Gas Permeability Technology: Digital, Manual, Automated, Hybrid End User: Construction, Environmental, Oil & Gas, Academic Application: Soil Testing, Rock Testing, Concrete Analysis, Groundwater Assessment |
| Companies Covered | Labthink Instruments Co., Ltd, Asian Test Equipments, OFI Testing Equipment, Testing Machines, Inc, Texcare Instruments Limited, Versatile Equipments Pvt. Ltd, Zhejiang Tugong Instrument Co., Ltd, Qualitest, AMETEK MOCON, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Permeability Testing Machine Market Evolving Landscape
Digital automation and cloud connectivity are restructuring how permeability data moves from field instrumentation to engineering decision systems, compressing project timelines while raising compliance documentation standards.
Automated constant head permeability testing systems with integrated data logging are overtaking manual falling head configurations in US commercial construction markets. Mid-sized geotechnical engineering firms deploying these platforms reduce field-to-report turnaround from days to hours. The technology is compressing competitive differentiation around speed rather than raw measurement accuracy alone.
EPA's evolving landfill liner assessment rules now explicitly require electronic data integrity safeguards that mirror FDA 21 CFR Part 11 pharmaceutical standards. Equipment manufacturers must embed audit trails and user access controls into firmware architectures originally designed for mechanical operation. Gas permeability testing segments serving environmental consulting are responding fastest, with ASTM D5084-compliant automated systems commanding procurement preference in federal Superfund site characterization.
Consolidation among third-party testing laboratories is driving equipment purchasing toward centralized fleet standardization rather than distributed site-specific procurement. Engineering firms with multi-state operations now mandate interoperable data formats and shared calibration schedules across locations. The Southwest and Mountain West US regions exhibit this pattern most acutely, where regional geotechnical service provider mergers have eliminated heterogeneous equipment policies in favor of single-vendor relationships with integrated service contracts.
Permeability Testing Machine Market Segmentation
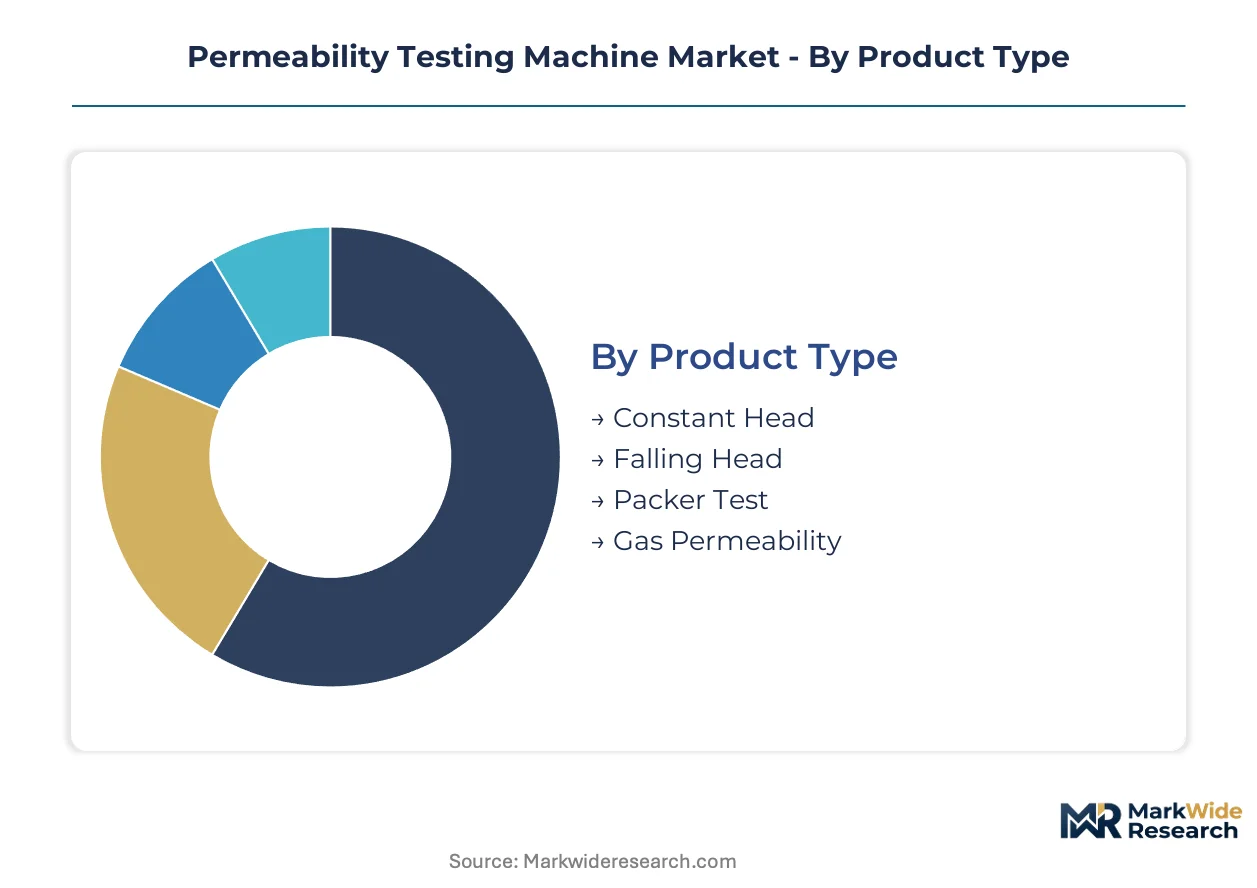
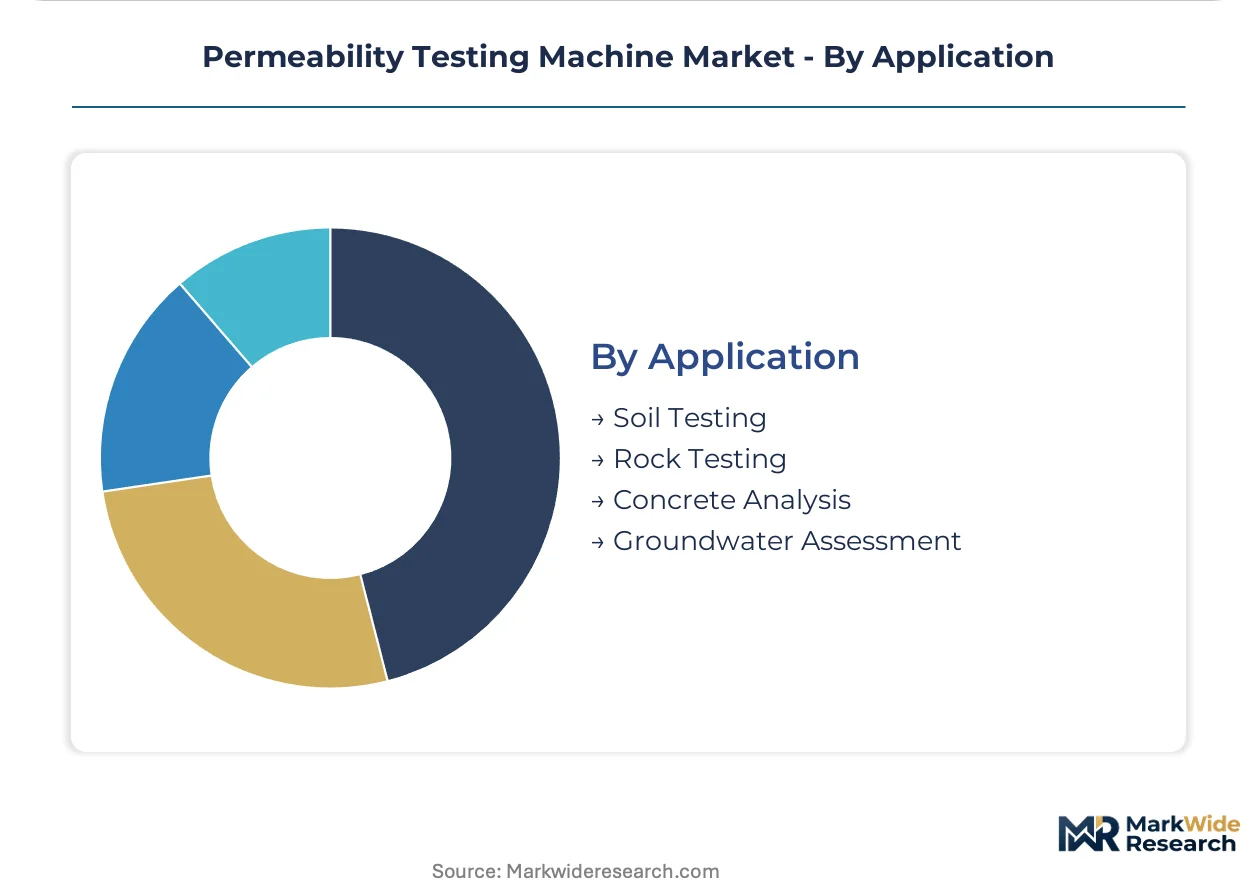
Permeability testing machine segmentation reveals distinct procurement patterns across integration depths, from standalone field units to laboratory-embedded systems with building information modeling connectivity. Understanding these structural divides enables vendors to align product architectures with customer technical maturity and compliance requirements.
Product Type:
Constant head and falling head configurations dominate embedded laboratory workflows, while packer test and gas permeability units serve standalone field deployment where portability overrides automation depth.
- Constant Head:Maintains fixed hydraulic gradient across soil specimens per ASTM D2434 protocols, enabling standardized coefficient determination for foundation design. Demand concentrates among US geotechnical engineering firms serving federal highway rehabilitation programs where digital traceability mandates compress replacement cycles for aging analog systems.
- Falling Head:Measures permeability through declining head pressure in fine-grained soils, offering simpler mechanical construction suited to budget-constrained municipal soil programs. Academic laboratories and secondary market engineering departments in the Mountain West US favor this configuration for introductory training and low-throughput characterization.
- Packer Test:Borehole-based rock permeability assessment for dam foundation and tunnel projects.
- Gas Permeability:Unconventional oil and gas wellbore integrity verification and carbon capture reservoir characterization.
Constant head leads volumes today; gas permeability is gaining share fastest.
Technology:
Cost tier stratification separates premium automated platforms from economy manual units, with hybrid systems capturing mid-market conversion opportunities.
- Digital:Integrated data logging with cloud-connected reporting and API interoperability for building information modeling platforms. Federal contractors and multi-state geotechnical service providers mandate these systems to satisfy EPA electronic data integrity requirements mirroring FDA 21 CFR Part 11 standards.
- Automated:Reduces operator variability through programmable pressure control and unattended test execution. High-throughput commercial laboratories and environmental consulting firms serving Superfund site characterization specify ASTM D5084-compliant automated configurations.
- Manual:Mechanical head control with visual reading requirements, priced for developing market entry.
- Hybrid:Staged automation upgrade path from manual base units through modular digital retrofit kits.
Manual systems retain installed base dominance; hybrid configurations are climbing the fastest among municipal conversion programs.
End User:
Application maturity varies sharply across customer types, with oil and gas operators demanding highest automation depth and academic users prioritizing pedagogical transparency over throughput.
- Construction:Civil engineering firms require ASTM and ISO protocol compliance for subsurface verification before project approval. US commercial building codes and DOT material certification programs drive fleet standardization among consolidated regional service providers.
- Oil & Gas:Shale formation operators and carbon capture developers specify gas permeability systems with automated pressure cycling and audit trail documentation. Wellbore integrity protocols tightening across unconventional basins favor vendors with integrated calibration networks.
- Environmental:Groundwater monitoring and landfill liner assessment under EPA 9100-series standards.
- Academic:Teaching laboratories and research programs prioritizing operator visibility into measurement mechanics.
Construction commands current revenue concentration; oil and gas exhibits steepest expansion trajectory.
Application:
Volume scale separates high-frequency soil testing from specialized rock and concrete characterization where test complexity extends project timelines.
- Soil Testing:Foundation design, embankment stability, and agricultural drainage assessment across ASTM D2434 and ISO 17892 workflows. US federal highway rehabilitation programs and commercial development projects sustain repetitive demand for standardized hydraulic characterization.
- Groundwater Assessment:Aquifer property determination and contaminant transport modeling for environmental compliance. EPA landfill liner rules and state-level groundwater protection programs mandate documented uncertainty budgets that favor digital permeability platforms.
- Rock Testing:Fractured media characterization for tunneling, mining, and reservoir engineering.
- Concrete Analysis:Permeability-based durability prediction for infrastructure lifecycle assessment.
Soil testing anchors current volumes; groundwater assessment shows strongest share gain among environmental consulting segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands premium equipment procurement while China scales manufacturing output for cost-sensitive segments. Germany anchors European standardization through DIN and ISO protocol alignment. India and Brazil represent conversion markets where municipal infrastructure programs drive manual-to-hybrid upgrade cycles.
United States
Federal highway rehabilitation programs and commercial building codes mandate subsurface permeability verification before project approval. The US EPA's landfill liner assessment rules under 9100-series standards require documented uncertainty budgets and traceable calibration chains. Engineering firms in Texas and California are consolidating testing capabilities in-house rather than outsourcing to third-party laboratories.
Germany
Precision sensor supply concentration among German component suppliers exposes equipment manufacturers to input cost volatility. The country's national standards body enforces DIN 18130 protocols that align with ISO 17892 specifications for geotechnical testing. Industrial clusters in Bavaria and North Rhine-Westphalia host calibration service providers serving centralized lab networks across Central Europe.
China
Municipal soil programs with constrained budgets drive demand for manual and hybrid units priced for developing market entry. The Ministry of Ecology and Environment enforces groundwater monitoring standards that increasingly reference international protocol harmonization. Manufacturing concentrations in Zhejiang province supply budget-constrained municipal engineering departments throughout Asia-Pacific.
India
Budget-constrained city and county engineering departments present conversion opportunity from manual to hybrid testing units with staged automation upgrades. The Bureau of Indian Standards coordinates with ISO working groups to align national geotechnical test methods. Engineering service providers in Maharashtra and Gujarat are expanding testing fleets as infrastructure resilience standards tighten.
Brazil
Unconventional oil and gas wellbore integrity protocols tightening across shale formations favor automated gas permeability systems. The national petroleum regulator mandates traceable calibration chains for reservoir characterization equipment. Environmental consulting firms in São Paulo state are retrofitting analog permeability testing machines with digital logging modules to reduce field-to-office data latency.
Permeability Testing Machine Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the permeability testing machine market. The vendor base stratifies into three tiers: premium automated platforms serving federal contractors, mid-market hybrid systems targeting municipal conversion programs, and economy manual units for developing market entry. Two dominant competitive moves are reshaping positioning: digital platform integration to capture recurring calibration revenue, and API-connected equipment development for building information modeling interoperability.
Within the digital automation tier, Labthink Instruments Co., Ltd and AMETEK MOCON exemplify contrasting geographic anchoring strategies. Labthink Instruments Co., Ltd occupies a position among Asia-Pacific platform integrators, while AMETEK MOCON represents North American premium-system positioning. Asian Test Equipments sits within the budget-tier specialist archetype, serving manual and hybrid demand across emerging markets.
| Leading Market Players |
|---|
| Labthink Instruments Co., Ltd |
| Asian Test Equipments |
| OFI Testing Equipment |
| Testing Machines, Inc |
| Texcare Instruments Limited |
| Versatile Equipments Pvt. Ltd |
| Zhejiang Tugong Instrument Co., Ltd |
| Qualitest |
| AMETEK MOCON |
| Others |
Value Network & Pricing Analysis
Calibration technician scarcity in Germany and Japan creates labor-cost differentials that widen pricing-tier spreads between premium automated platforms and economy manual units, as certified hydraulic testing expertise commands wage premiums that concentrate in precision-sensor manufacturing clusters.
Pricing Analysis
Capacity additions in Zhejiang province are reshaping price floors for manual and hybrid permeability testing units, compressing margins for mid-tier manufacturers while premium automated systems retain pricing power through ASTM D5084 compliance bundling. Three-tier pricing structure across premium, standard, and economy levels separates API-connected digital platforms from automated constant head configurations and basic falling head instruments. Price differentiation rests on certification grade and after-sales calibration network density. Cost compression in economy tiers is intensifying because municipal soil programs in India and Brazil prioritize upfront capital savings over lifecycle service contracts. Municipal engineering departments exhibit highest price sensitivity; federal contractors and multi-state geotechnical service providers show least.
Supply Chain Analysis
Refurbishment flows for analog permeability testing machines create secondary supply channels that extend equipment lifecycles and delay replacement demand in budget-constrained markets. Manufacturing concentrates in China, Germany, and the United States, with precision pressure transducers and flow meters drawing from Japanese and German component suppliers. Raw material dependencies include high-grade aluminum for test cell construction, borosilicate glass for permeameter tubes, and specialized elastomers for packer seals. Single-source vulnerability in precision sensor supply exposes equipment manufacturers to input cost volatility. Distribution runs through authorized calibration service networks that anchor customer stickiness in centralized laboratory procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Permeability testing machine margins are expanding as digital platform integration captures recurring calibration revenue and API-connected equipment commands procurement preference in federal contracting, offsetting capital intensity through service-contract bundling.
For Market Incumbents: Deploy calibration network densification to defend installed base against emerging platform integrators. Incumbents should deepen backward integration into precision sensor supply through captive production partnerships with German and Japanese component specialists, reducing exposure to lead time volatility. Certification pre-emption in carbon capture reservoir characterization creates defensive moats as geologic sequestration site assessment protocols mature. For New Entrants and Emerging Players: Direct-to-municipal digital sales channels bypass incumbent distributor relationships that dominate federal contractor procurement. New entrants should target budget-constrained city and county engineering departments in secondary US markets with staged hybrid upgrade paths from manual base units. White-space penetration runs fastest through API interoperability demonstrations that stream permeability data directly to building information modeling platforms, addressing interoperability mandates without incumbent legacy system retrofit friction. For Investors and Strategic Acquirers: Valuations sit cheapest among manual-equipment manufacturers with underutilized hybrid conversion IP and dormant calibration service networks. Acquisition targets with established municipal customer relationships in India and Brazil offer platform integration upside as infrastructure resilience standards tighten. Long-term viability centers on vendors that control both equipment manufacturing and traceable calibration chain certification, as EPA electronic data integrity requirements mirror FDA 21 CFR Part 11 standards. Monitor ASTM-ISO protocol harmonization progress as inflection indicator for dual-product-line consolidation opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Network Expansion | Recurring revenue capture from centralized lab networks reduces customer churn under ASTM traceability mandates. |
| API Platform Integration | Direct BIM connectivity satisfies federal contractor interoperability requirements that compress field-to-report timelines. |
| Backward Integration into Sensors | In-house production of pressure transducers mitigates German and Japanese supplier concentration risk. |
| Hybrid Conversion Kit Development | Staged automation upgrades unlock municipal budget cycles without full platform replacement capital burden. |
| Carbon Capture Application Extension | Caprock integrity verification opens adjacent demand beyond traditional civil engineering customer base. |
Research Methodology
Multiple input streams — primary interviews with geotechnical engineering directors, EPA compliance officers, and calibration service technicians; secondary validation through ASTM and ISO standard documentation, federal highway procurement databases, and equipment manufacturer technical specifications — were reconciled through bottom-up and top-down triangulation. Primary fieldwork captured procurement decision criteria across construction, oil and gas, and environmental consulting verticals. Secondary sources included US DOT material certification program records, EPA 9100-series enforcement guidance, and customs trade data for precision sensor import flows.
Historical shipment patterns were cross-referenced against expert panel assessments of replacement cycle compression and digital adoption trajectories across the projection horizon. Segmentation modeling incorporated product type, technology tier, end-use industry, and application workflow dimensions. CAGRs were derived from equipment fleet expansion rates tied to federal highway rehabilitation program allocations and state-level DOT certification requirements. Industry-specific forecast inputs included ASTM D2434 and ISO 17892 protocol update timelines, plus municipal soil program digitization budget appropriations in target geographies.
Regulatory enforcement intensity shifts, precision sensor supply disruption events, and protocol harmonization delays are the dominant revision risks that could compress or extend replacement demand timing. Forecasts reflect assumptions about calibration technician training pipeline output and BIM interoperability mandate adoption schedules. Practitioners should monitor EPA electronic data integrity rulemaking and ASTM-ISO working group convergence for early signals of compliance-driven procurement acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
AI Inference Hardware Performance Benchmarking Test Systems Market
Test and Measurement
Optical Critical Dimension (OCD) Measurements System Market
Test and Measurement
Force Gauge Market
Test and Measurement
Digital Weighing Machine Market
Test and Measurement
Sound Level Measurement Meter Market
Test and Measurement
United States Signal Generator Market
Test and Measurement
Wi-Fi Test Equipment Market
Test and Measurement
Capacitance Meter Market
Test and Measurement
Curve Tracer Market
Test and Measurement
Micro Ohmmeter Market
Test and Measurement
NIR Moisture Analyzers Sales Market
Test and Measurement
Semiconductor Chip Test Probes Market
Test and Measurement
Duct Integrity Tester (DIT) Market
Test and Measurement
Shape Measuring Devices Market
Test and Measurement
Ultrasonic Flaw Detector Market
Test and Measurement
Electronic Measuring Device Market