
 Global Digital Measurement Instruments Market | 2026-2036
Global Digital Measurement Instruments Market Size, Share, and Industry Trends Forecast 2026-2036
Global Digital Measurement Instruments Market Intelligence
The upgrade to higher-precision, multi-channel oscilloscopes is rotating the market towards higher-value instrumentation. This shift favors vendors with deep expertise in high-frequency signal analysis. Keysight Technologies leverages its extensive portfolio in electronics testing to capture this demand. Rohde & Schwarz competes on the strength of its specialized solutions for the aerospace and telecommunications sectors, while Fortive Corporation sustains its position through its Fluke Corporation subsidiary.
Digital measurement instruments are electronic devices that capture and convert physical or electrical signals into digital values for precise analysis. These tools are defined by technical parameters like sampling rate, bandwidth, and bit resolution, enabling detailed examination of waveforms. Oscilloscopes and analyzers represent the core product segments, driven by complex electronics testing. Demand from telecommunications and aerospace systems applications commands higher margins due to stringent performance and reliability requirements.
Regulatory compliance is a critical barrier to entry, governed by frameworks like the EU's CE marking for safety and the US FCC's rules on electromagnetic interference. In China, adherence to national GB standards is mandatory for market access. These regulations dictate design specifications and component choices for all manufacturers. Vendor success will depend on integrating modular, software-defined architectures to adapt to evolving test requirements across different end-user segments.
Market Dynamics
The transition toward complex, high-frequency communication systems is the central force shaping the digital measurement instruments market. The technical demands of 5G, satellite communications, and advanced radar systems compel investment in new, more capable instrumentation for design, validation, and production.
Growth Catalysts
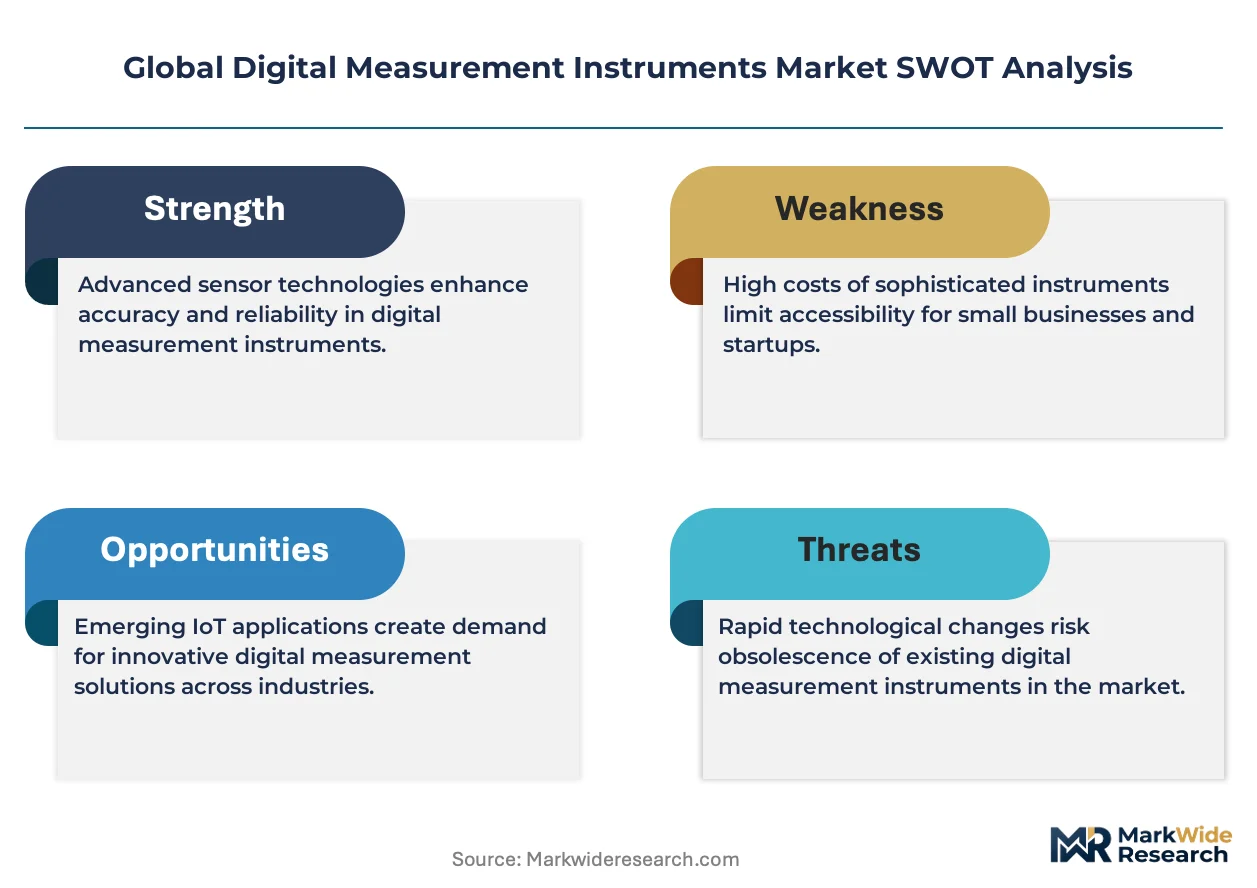
- 5G Infrastructure Rollout:The deployment of 5G networks necessitates instruments with wider bandwidth and advanced modulation analysis capabilities to test base stations and user equipment, especially within East Asian telecommunications manufacturing hubs.
- Automotive Electrification:Demand for high-power, multi-channel oscilloscopes and analyzers is rising to test battery management systems, inverters, and charging infrastructure for electric vehicles, driven by automotive clusters in Europe and North America.
- Aerospace and Defense Modernization:Government programs focused on upgrading radar, electronic warfare, and satellite communications systems create sustained demand for high-performance, ruggedized measurement tools that meet stringent reliability standards.
Market Restraints
- High Calibration and Maintenance Costs:The precision required for high-frequency applications mandates frequent, expensive calibration services, increasing the total cost of ownership and acting as a brake on adoption for smaller enterprises.
- Specialized Semiconductor Scarcity:The industry's reliance on a concentrated supply chain for high-speed analog-to-digital converters (ADCs) and FPGAs, primarily from Taiwan and South Korea, creates vulnerability to production delays and price volatility.
- Signal Integrity at Terahertz Frequencies:As research pushes toward 6G technologies, current instrument architectures face fundamental physical limits in maintaining signal fidelity and minimizing noise, creating a significant technical barrier.
Strategic Opportunities
- Quantum Computing Development:The nascent field of quantum computing requires ultra-low noise, high-channel-count signal generators and analyzers to control and measure qubits, representing a new, high-value application frontier.
- Software-Defined Instrumentation:Modular hardware platforms combined with open-source software offer end-users greater flexibility to create customized test solutions, lowering the entry barrier for academic research and startups.
- Medical Device Connectivity Testing:Stricter regulations, such as the EU's Medical Device Regulation (MDR), mandate rigorous testing for wireless performance and cybersecurity in connected medical devices, opening a new compliance-driven market.
Industry Challenges
- RF Engineering Talent Scarcity:A persistent shortage of engineers with specialized skills in radio frequency, microwave, and high-speed digital design hampers product development and the ability to provide expert application support.
- Divergent Global Compliance:Manufacturers face significant overhead in designing instruments that simultaneously satisfy the EU's CE marking, US FCC rules on interference, and China's distinct GB standards for market access.
- Legacy System Integration:Integrating new, high-speed instruments into established automated test equipment (ATE) systems on manufacturing floors presents a major challenge, risking production downtime and requiring complex software adaptation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Digital Measurement Instruments Market |
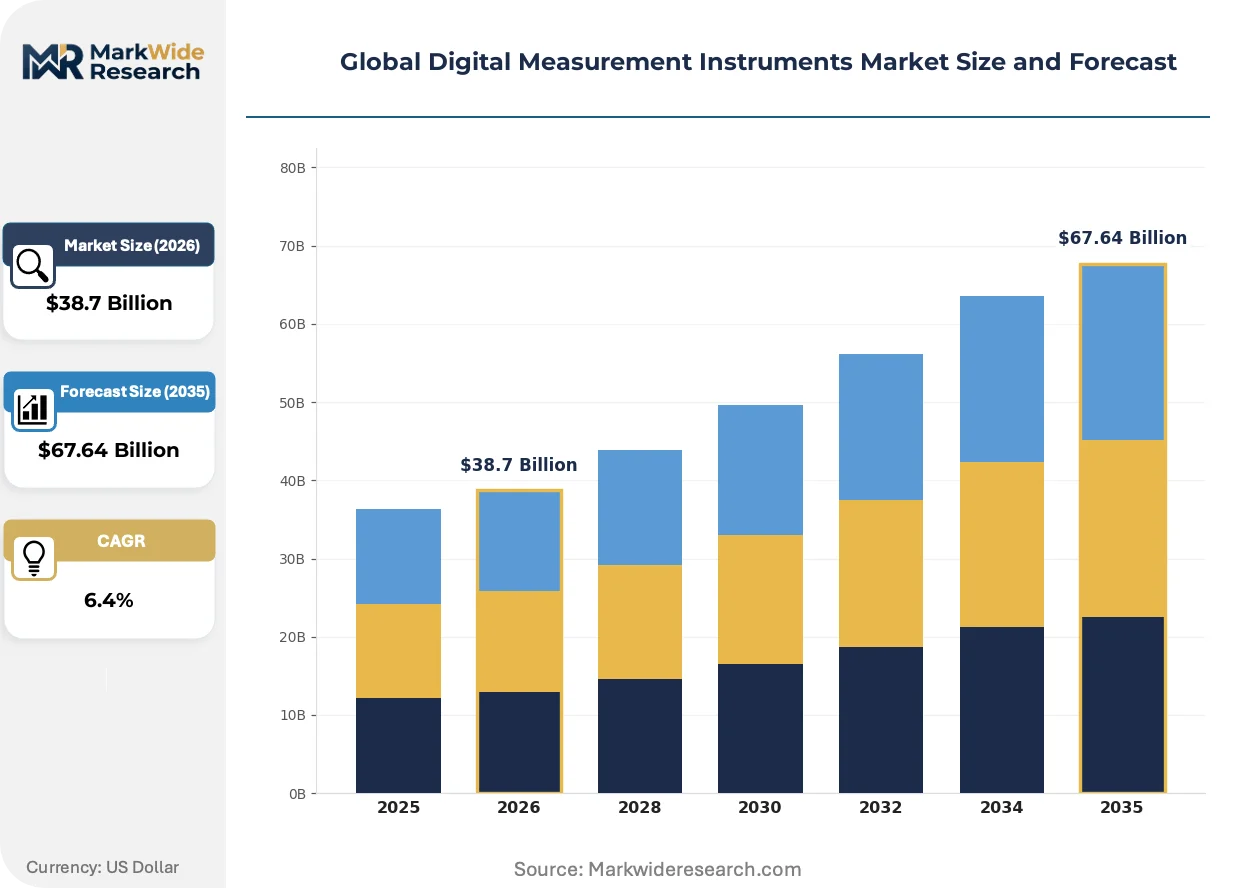
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $67.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Multimeters, Oscilloscopes, Analyzers, Calibrators, Signal Generators Technology: Portable, Laboratory, Benchtop, Handheld, Wireless Application: Electronics Testing, Telecommunications, Aerospace Systems, Environmental Monitoring, Energy Auditing End User: Manufacturing Plants, Research Institutes, Quality Assurance Labs, Maintenance Services |
| Companies Covered | Yokogawa Electric Corporation, Advantest Corporation, Keysight Technologies, AMETEK Inc., Teledyne Technologies, Rohde & Schwarz, National Instruments, Fortive Corporation, Fluke Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Digital Measurement Instruments Market Strategic Shifts & Innovations
The market's evolution is defined by a pivot from fixed-function hardware toward flexible, data-centric architectures. This transition enables more sophisticated analysis of complex signals across diverse industries, from telecommunications to life sciences, accelerating design and validation cycles.
Artificial intelligence and machine learning integration into analysis software is a key development. This technology automates complex tasks like anomaly detection and signal classification. R&D labs in the semiconductor and aerospace sectors are the primary adopters, while this integration is bifurcating the market into intelligent systems for discovery and traditional instruments for standardized production.
The European Union's updated Radio Equipment Directive (RED) introduces stricter cybersecurity requirements. The directive now mandates that manufacturers of connected devices demonstrate resilience against network-based threats, expanding the scope beyond simple radio performance. This shift most directly impacts the vast Internet of Things (IoT) device segment, forcing vendors to acquire new measurement capabilities for security testing.
A shift away from outright capital expenditure purchases toward subscription-based access and rental models is gaining traction. This trend disrupts the traditional direct sales channel, empowering specialized rental companies and manufacturers' own service divisions. This model is most visible among startups and project-based R&D teams in North America and Europe needing access to high-end equipment without a large upfront investment.
Global Digital Measurement Instruments Market Segmentation
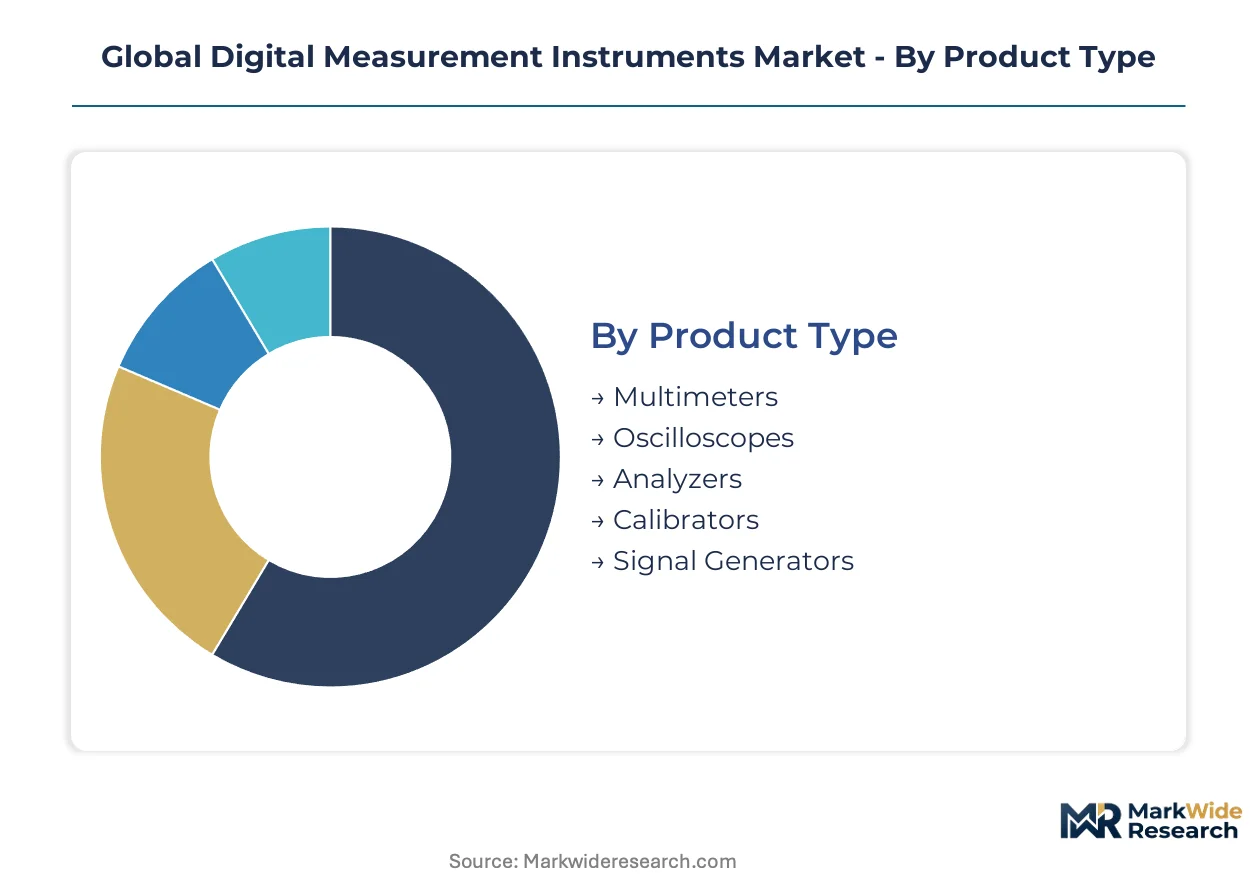
Market segmentation provides a critical lens to understand the diverse technical requirements and economic drivers within the digital measurement instruments sector. Each segment reflects distinct user needs, ranging from fundamental electrical testing to highly specialized applications in advanced research and development. This granular view highlights where innovation and investment are concentrating across the industry value chain.
Product Type:
Substitution pressure is most pronounced for basic instruments, where simpler, multi-functional devices can sometimes replace dedicated tools for routine tasks.
- Multimeters:These instruments perform basic electrical measurements like voltage, current, and resistance, serving as foundational tools across diverse industries. Widespread adoption occurs in general electronics repair and educational settings globally.
- Oscilloscopes:High-precision, multi-channel oscilloscopes capture and analyze complex waveforms, essential for design and validation of high-frequency circuits. Demand concentrates in telecommunications for 5G infrastructure and automotive electrification projects in Europe and North America.
- Analyzers:These tools provide detailed examination of signals, encompassing spectrum, network, and logic analysis for complex electronic systems. R&D labs in the semiconductor sector and aerospace systems developers drive demand for advanced analysis capabilities.
- Calibrators:Instruments used to verify and adjust the accuracy of other measurement devices, ensuring compliance and precision in industrial operations.
- Signal Generators:Devices producing precise electronic signals for testing components and systems during development and production cycles.
Multimeters anchor the volume base while Oscilloscopes gain share at the steepest rate.
Technology:
The deployment context significantly influences technology choices, with mobility and connectivity driving specific instrument designs.
- Portable:Designed for field use and on-site diagnostics, these instruments offer flexibility for maintenance and installation teams in remote locations. Demand for portable solutions rises with distributed infrastructure deployment, particularly in telecommunications.
- Laboratory:Fixed, high-precision instruments providing extensive capabilities for fundamental research and advanced development environments. These are critical in semiconductor fabrication facilities and academic research labs.
- Benchtop:Versatile instruments offering a balance of performance and footprint for general electronics design and testing in various engineering workplaces.
- Handheld:Compact, battery-powered devices emphasizing ease of use for quick checks and basic troubleshooting tasks in industrial maintenance.
- Wireless:Instruments integrating wireless communication for remote control and data transfer, enhancing safety and accessibility in hazardous environments.
The market for Portable instruments continues to expand, driven by field service needs, while Laboratory technology finds specialized utility for high-precision R&D.
Application:
Margin profiles vary significantly across applications, with highly regulated and technically demanding sectors commanding premium pricing.
- Electronics Testing:A broad category encompassing design validation, characterization, and production quality control for a wide array of electronic devices and components. This forms a foundational demand segment across manufacturing.
- Telecommunications:Instruments critical for validating 5G network infrastructure, high-frequency components, and complex modulation schemes. Demand is particularly high in East Asian manufacturing hubs like South Korea.
- Aerospace Systems:Measurement tools required for rigorous testing of radar, electronic warfare, and satellite communication systems, adhering to stringent performance standards. Government modernization programs in the US and Europe drive this demand.
- Environmental Monitoring:Instruments used to measure air quality, water parameters, and other ecological factors for regulatory compliance and scientific research.
- Energy Auditing:Tools for assessing power consumption and efficiency in industrial and commercial settings to optimize energy usage and reduce operational costs.
High-performance Telecommunications applications drive significant investment, contrasting with the broader utility of Electronics Testing.
End User:
The operational scale and precision requirements of end-users dictate the type and sophistication of digital measurement instruments deployed.
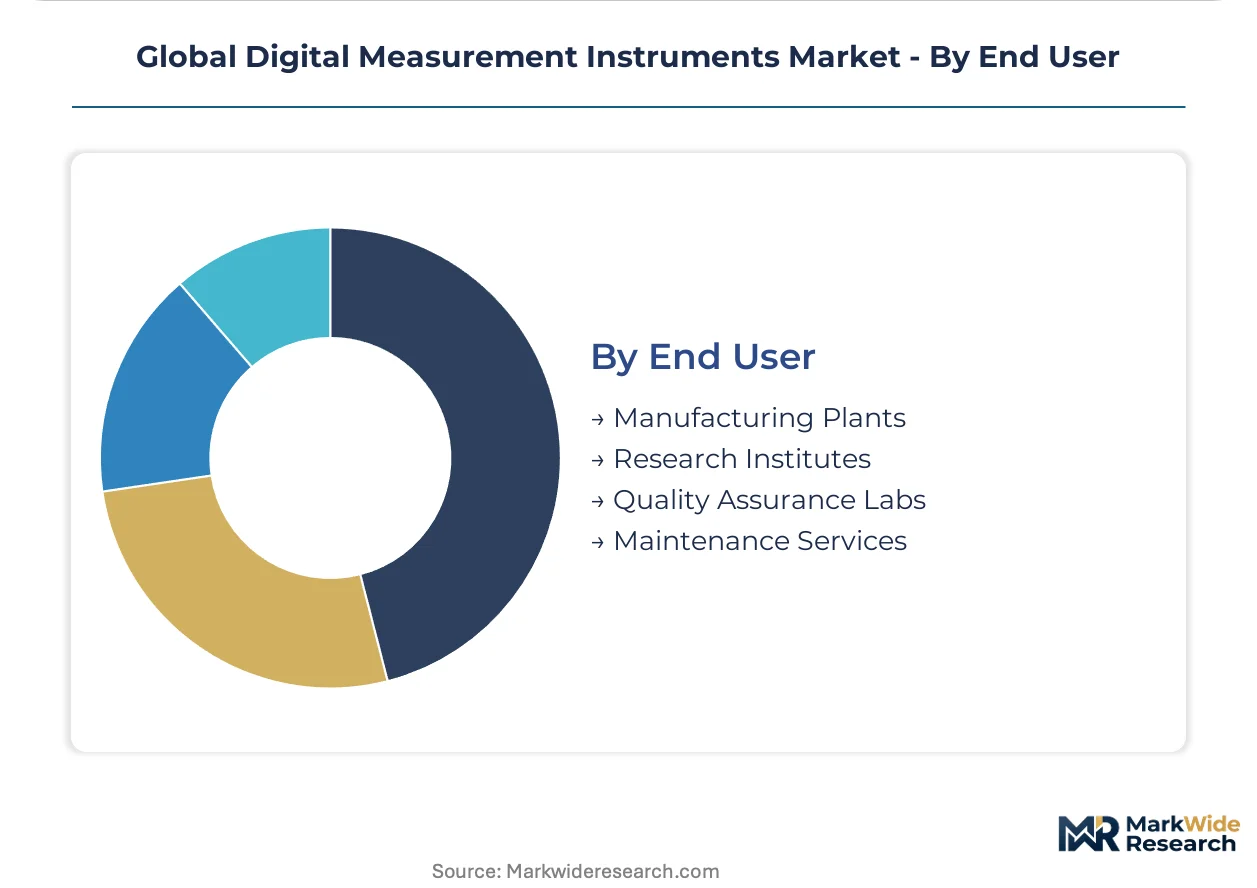
- Manufacturing Plants:These facilities utilize digital measurement instruments for automated test equipment (ATE) and quality control during high-volume production processes. Integration challenges exist with legacy systems on factory floors.
- Research Institutes:Require cutting-edge, high-precision instruments for developing new technologies, including quantum computing and advanced material science. These labs often drive demand for software-defined solutions.
- Quality Assurance Labs:Focus on calibration, verification, and compliance testing to ensure products meet industry standards and regulatory requirements.
- Maintenance Services:Deploy portable and handheld instruments for field diagnostics, troubleshooting, and preventive maintenance of complex systems.
The demand from Manufacturing Plants underpins consistent market activity, while Maintenance Services represents a growing segment for specialized diagnostics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The digital measurement instruments market exhibits significant supply-side concentration, particularly in regions with advanced electronics manufacturing capabilities. These specialized instruments are critical for validating high-frequency communication systems and complex electronic components. East Asian technology hubs and established Western industrial centers drive much of this specialized demand.
South Korea
South Korea drives demand for high-precision digital measurement instruments through its extensive 5G infrastructure rollout and advanced semiconductor fabrication. The government's strong support for domestic technology development underpins significant investment. Electronics manufacturing in the Seoul Capital Area necessitates continuous innovation in measurement capabilities.
United States
The United States market sees robust demand from aerospace and defense modernization programs, alongside burgeoning quantum computing initiatives. FCC regulations on electromagnetic interference dictate stringent testing for communication systems. Silicon Valley's research institutions and defense contractors in states like California drive innovation in high-performance measurement tools.
Germany
Germany's automotive electrification efforts and advanced industrial automation sectors create substantial demand for multi-channel oscilloscopes and analyzers. Adherence to EU's CE marking ensures safety and performance across product categories. Automotive clusters in Bavaria and Baden-Württemberg lead in developing new testing methodologies for electric vehicle components.
China
China's vast telecommunications network expansion and electronics manufacturing prowess generate significant demand for digital measurement instruments. Compliance with national GB standards is mandatory for all market participants. The Yangtze River Delta region, particularly around Shanghai, features extensive electronics production requiring sophisticated testing solutions.
Japan
Japan's focus on advanced robotics and cutting-edge semiconductor research fuels demand for high-precision signal generators and analyzers. Adherence to strict JIS standards ensures product quality and reliability in all applications. The Kanto region, encompassing Tokyo, hosts numerous electronics firms and academic institutions driving instrument development.
Global Digital Measurement Instruments Market Key Industry Players
Concentration sits with established global players offering comprehensive portfolios across diverse applications, particularly in high-frequency and complex signal analysis. The market structure is tiered, featuring a few dominant multinational corporations alongside numerous specialized niche providers. These larger entities leverage extensive R&D capabilities, global distribution networks, and deep customer relationships. Key competitive moves include strategic partnerships for technology co-development and continuous portfolio diversification into emerging high-value segments like quantum computing.
On the premium-tier vector, Keysight Technologies exemplifies leadership in high-frequency signal analysis, leveraging its deep expertise in electronics testing for telecommunications and aerospace. Rohde & Schwarz occupies a strong position through specialized solutions tailored for stringent performance requirements in the aerospace and defense sectors, as well as advanced telecommunications. Fortive Corporation, through its Fluke Corporation subsidiary, anchors the market for industrial calibration and field service instruments, providing essential tools for maintenance and quality assurance. These firms represent the archetypes of integrated solutions providers and specialized technology innovators within the industry, driving advancements in measurement precision.
| Leading Market Players |
|---|
| Yokogawa Electric Corporation |
| Advantest Corporation |
| Keysight Technologies |
| AMETEK Inc. |
| Teledyne Technologies |
| Rohde & Schwarz |
| National Instruments |
| Fortive Corporation |
| Fluke Corporation |
| Others |
Cost & Logistics Intelligence
The shift from fixed-function hardware to software-defined architectures reshapes both the supply geography and pricing economics in digital measurement instruments. This transition reduces reliance on specialized component manufacturing and enables subscription-based access models.
Pricing Analysis
EU's CE marking dictates the pricing tier structure for digital measurement instruments, particularly for safety-critical applications. Pricing stratifies across premium, standard, and economy tiers, driven by instrument performance and included after-sales calibration services. Pricing softness runs through the standard segment due to increased modularity and software-defined options. Academic research and startups exhibit higher price sensitivity compared to aerospace and telecommunications end-users.
Supply Chain Analysis
Taiwan and South Korea anchor the production of specialized semiconductors, particularly high-speed analog-to-digital converters and FPGAs, crucial for digital measurement instruments. The industry draws from a concentrated supply of these critical components, creating vulnerability to production delays and price volatility. China provides extensive electronics manufacturing capabilities for instrument assembly. Distribution runs through direct sales channels for high-end equipment and specialized rental companies for project-based access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The digital measurement instruments market represents an early-cycle expansion story, driven by the global 5G infrastructure rollout. This deployment necessitates advanced testing capabilities, fueling demand across diverse technology hubs.
For Market Incumbents:Fortify existing market positions by deepening expertise in high-frequency signal analysis, especially for 6G research. Strategic partnerships for technology co-development can mitigate the RF engineering talent scarcity. Diversify portfolios into nascent, high-value segments like quantum computing instrumentation. Investing in modular, software-defined architectures offers a lever against evolving test requirements.
For New Entrants and Emerging Players:Customized test solutions for academic research and startups represent a service-layer gap where incumbents under-serve. Target software-defined instrumentation platforms with open-source interfaces to lower entry barriers. Focus on medical device connectivity testing in Europe, driven by stringent MDR regulations. A subscription-based access model offers a compelling go-to-market angle for project-based R&D teams.
For Investors and Strategic Acquirers:The market sits at a growth phase that favors specialized technology innovators capable of addressing emerging high-frequency challenges. Long-term viability remains strong, driven by continuous technological evolution in telecommunications and advanced computing. Target niche providers with proprietary intellectual property in ultra-low noise signal generation or terahertz frequency analysis. The signal to watch is the commercialization of 6G testbeds and quantum computing research breakthroughs.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in 6G Research Partnerships | Accelerates development of next-generation measurement tools for future telecommunications standards. |
| Expand Software-Defined Offerings | Enhances instrument flexibility and customization for diverse end-user segments like academic research. |
| Acquire RF Talent Pool | Addresses the critical RF engineering talent scarcity, bolstering product development capabilities. |
| Certify for Medical Device Connectivity | Unlocks new compliance-driven market opportunities in connected medical devices under EU MDR. |
| Secure ADC/FPGA Supply Agreements | Mitigates supply chain vulnerability stemming from specialized semiconductor scarcity in Taiwan. |
Research Approach
Desk research of industry reports, company filings, and academic publications preceded structured interviews with R&D directors, test engineers, procurement managers, and regulatory compliance officers. This approach combined primary insights with secondary validation from sources like SEC filings, IEEE journals, and government technology roadmaps. Bottom-up data collection and top-down market sizing ensured comprehensive analysis and data integrity.
Variance decomposition isolated the impact of key drivers on market growth across the analysis window. The quantitative modeling framework segmented the market by product type, technology, application, end-user, and frequency band. Compound annual growth rates were derived through regression analysis and expert consensus. Industry-specific inputs included 5G deployment rates and electric vehicle production forecasts.
Underlying assumptions cover technological advancements and regulatory stability, with deviation risk concentrated in geopolitical supply chain disruptions and rapid shifts in communication standards. Forecasts reflect these documented assumptions. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Production Testing Market
Test and Measurement
Environmental Test Chambers Market
Test and Measurement
Semiconductor Test Socket Market
Test and Measurement
Fogging Tester Market
Test and Measurement
Automated Optical Inspection (AOI) System Market
Test and Measurement
Sample Rate Converters Market
Test and Measurement
Battery Testing Market
Test and Measurement
LCR Meter Market
Test and Measurement
Solar Clamp Meter Market
Test and Measurement
Duct Integrity Tester (DIT) Market
Test and Measurement
Global 5G Test Equipment Market
Test and Measurement
Continuous Friction Tester Market
Test and Measurement
LTE Testing Equipment Market
Test and Measurement
Ultrasonic Thickness Gauge Market
Test and Measurement
Tribometer Market
Test and Measurement
High-Throughput Liquid Handling Robot Performance Test Equipment Market