
 Battery Power Tools Market | 2026-2036
Battery Power Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Battery Power Tools Market Outlook
Aftermarket battery pack refurbishment and platform-agnostic charging ecosystems are reshaping margin distribution across the value chain. Techtronic Industries leverages its Milwaukee brand to dominate premium cordless platforms in North American professional channels. Stanley Black & Decker sustains broad retail penetration through multi-brand portfolio density across DIY and contractor segments. Robert Bosch anchors European demand with integrated battery systems that span automotive and construction tool applications.
Battery power tools are portable electromechanical devices driven by rechargeable cells, typically lithium-ion packs operating between 18V and 40V, designed for cutting, fastening, grinding, or drilling in environments without grid power access. Their primary purpose is to deliver corded-equivalent torque and runtime while eliminating trip hazards and mobility constraints on job sites. Drills and impact drivers occupy the largest revenue pool due to universal adoption across construction and automotive maintenance workflows, while grinders represent the fastest-expanding category as brushless motor technology extends cordless viability into high-load metalworking tasks. The Li-ion battery technology segment commands structural priority because energy density improvements directly enable tool class expansion and platform standardization strategies.
The US EPA governs battery disposal and recycling mandates that affect end-of-life costs and design-for-disassembly requirements, while the EU REACH regulation restricts hazardous substances in battery formulations and chargers sold across member states. OSHA workplace safety standards in the US additionally shape demand for cordless alternatives that reduce electrical hazard exposure on active construction sites. Stakeholders must monitor evolving battery chemistry regulations and platform interoperability standards as determinants of product roadmap investment and geographic market access.
Market Dynamics
Brushless motor platforms and high-density lithium-ion cell architectures are compressing the performance gap between cordless and corded tools, forcing incumbent manufacturers to accelerate platform standardization investments or surrender professional-grade segments to specialized competitors.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon refrigerants in battery thermal management systems is accelerating adoption of solid-state cooling architectures and silicon carbide power electronics in premium tool platforms.
- Residential renovation spending:DIY homeowners in the United States are converting garages into dedicated workshop spaces, driving 18V-20V platform lock-in through ecosystem purchases of drills, impact drivers, and oscillating multi-tools.
- Brushless motor adoption:Permanent magnet synchronous motors with Hall-effect position sensing are extending cordless runtime by 40-50% in grinding and cutting applications previously restricted to corded alternatives.
Market Restraints
- Cobalt supply concentration:Over 70% of refined cobalt originates from the Democratic Republic of Congo, exposing lithium-ion cell manufacturers to price volatility and ethical sourcing audit requirements.
- REACH substance restrictions:The European Chemicals Agency's evolving candidate list of Substances of Very High Concern is forcing reformulation of electrolyte solvents and separator coatings, extending new product qualification timelines.
- Pneumatic tool substitution:Compressed air systems retain total cost advantages in fixed automotive assembly lines, limiting cordless penetration in high-volume manufacturing environments.
Strategic Opportunities
- Platform-agnostic charging infrastructure:Third-party manufacturers are developing universal battery docks compatible across multiple OEM voltage architectures, creating aftermarket revenue pools independent of original tool sales.
- India construction electrification:The country's Smart Cities Mission and urban housing targets are generating first-time demand for cordless tools among informal sector contractors previously dependent on manual labor.
- Battery pack refurbishment services:Cell replacement and BMS reprogramming for end-of-life packs is emerging as a margin-rich service layer, particularly for 40V commercial landscaping platforms.
Industry Challenges
- Power electronics engineering scarcity:The intersection of motor control firmware, thermal management, and electromagnetic compatibility expertise is concentrating in automotive and aerospace sectors, constraining tool OEM hiring pipelines.
- Interoperability certification delays:UL 2595 and IEC 62841-1 testing backlogs at accredited laboratories are extending product launch windows by 4-6 months for new battery platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Battery Power Tools Market |
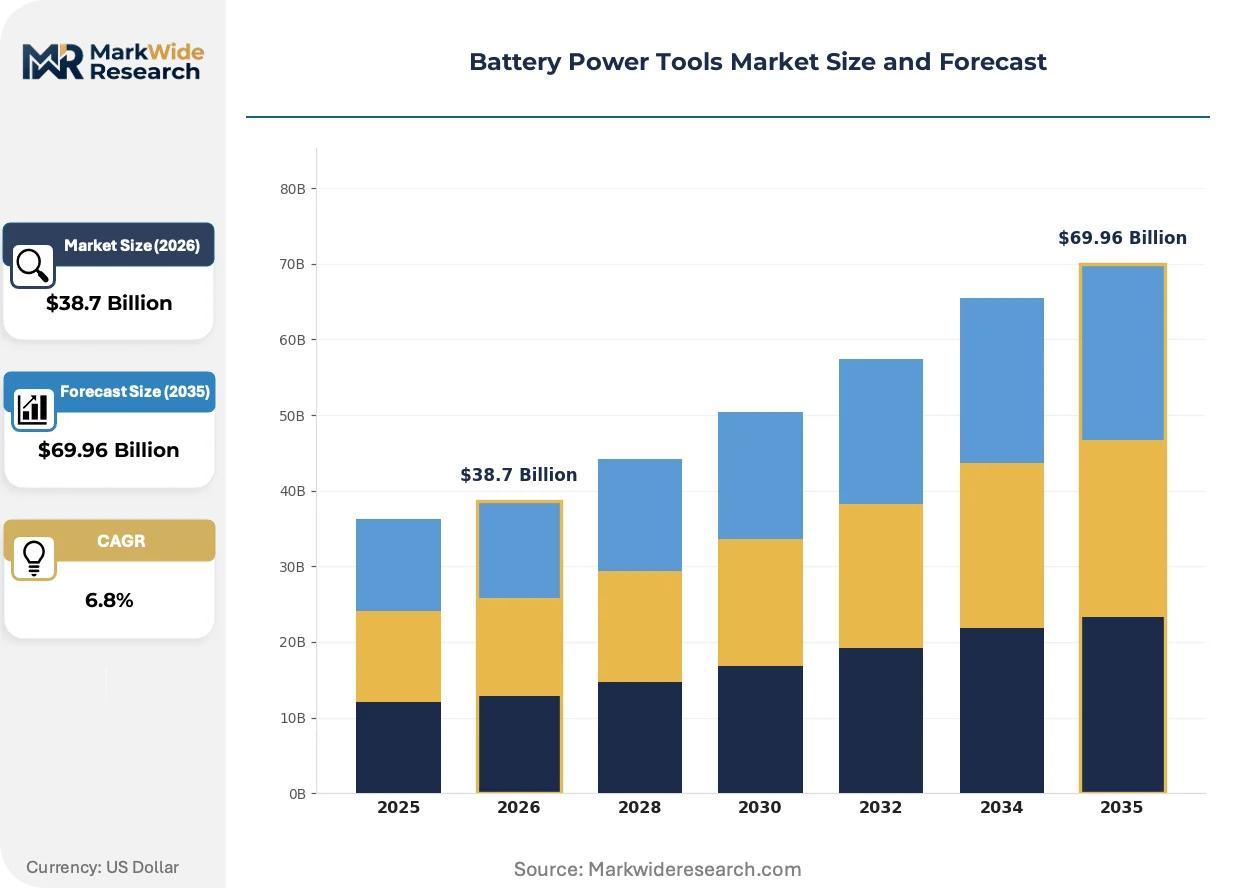
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drills, Saws, Sanders, Grinders Application: Construction, Automotive, Landscaping, DIY User Type: Professionals, Hobbyists, Contractors, Maintenance Battery Technology: Li-ion, NiMH, NiCd, Others |
| Companies Covered | Techtronic Industries, Hilti, Stanley Black & Decker, Atlas Copco, Ingersoll Rand, Robert Bosch, Milwaukee, Panasonic, Makita, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Battery Power Tools Market Strategic Shifts
Gallium nitride power semiconductors, predictive battery health algorithms, and direct-to-contractor distribution models are compressing traditional technology adoption cycles and reshaping how professional users acquire and maintain cordless platforms.
GaN-based inverter circuits in 40V-80V battery chargers are rendering obsolete silicon MOSFET architectures that dominated the previous decade. Commercial landscaping contractors operating fleet-scale equipment are adopting these chargers to cut recharge intervals from 90 minutes to under 45 minutes. The technology is enabling same-shift continuous operation for zero-turn mowers and backpack blowers, compressing the total cost of ownership advantage previously held by gasoline alternatives.
REACH substance restrictions on nickel, cobalt, and certain electrolyte additives are compelling cell manufacturers to accelerate sodium-ion and lithium iron phosphate chemistry development for mid-voltage tool applications. The industrial consequence is a bifurcation in platform strategies: premium lines retain nickel-rich cells for energy density, while standard-tier tools migrate to cobalt-free formulations. European professional channels are most affected, with German and French distributors now requiring full material composition disclosure for municipal procurement contracts.
Aftermarket battery pack refurbishment is displacing traditional replacement purchasing patterns among cost-sensitive commercial users. Independent service providers in the United States are capturing share from OEM channels by offering cell-grade replacement with warranty terms matching factory packs. The model is most visible in construction and facilities maintenance verticals, where fleet managers prioritize uptime over brand loyalty and standardized voltage platforms enable cross-manufacturer compatibility.
Battery Power Tools Market Segmentation
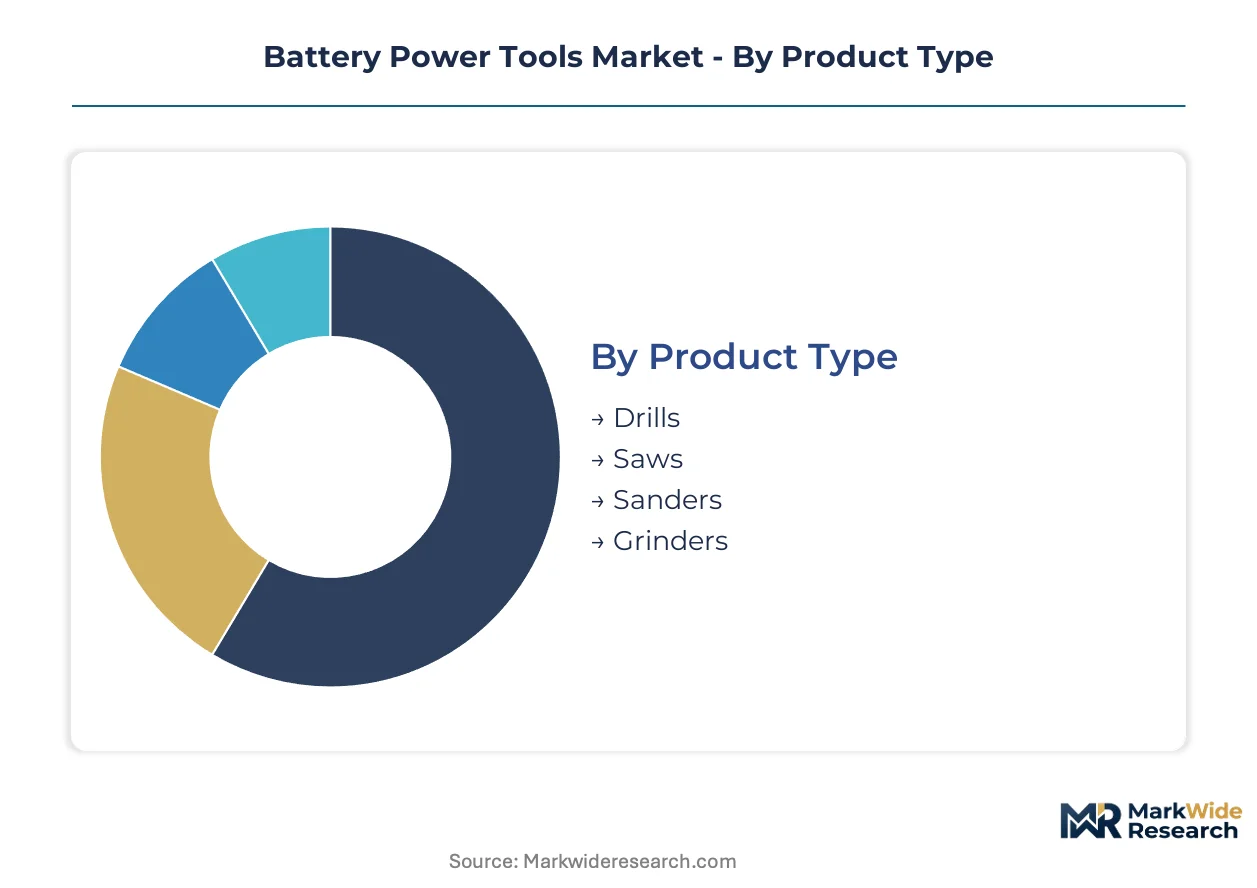
Segmentation in battery power tools reveals how voltage platforms, user workflows, and chemistry choices create distinct margin pools. Manufacturers configure R&D allocation and distribution partnerships around these fault lines rather than pursuing undifferentiated coverage.
Product Type:
Application intensity and torque requirements divide the product landscape into four equipment classes with diverging motor and battery specifications.
- Drills:Brushless motor variants operating at 18V-20V deliver corded-equivalent torque for metal and masonry penetration. Residential renovation in the United States drives platform lock-in through ecosystem purchases of compatible impact drivers and multi-tools.
- Saws:Reciprocating and circular configurations at 40V-60V extend cordless viability into framing and demolition tasks. Demand concentrates among professional contractors in Germany where REACH-compliant battery systems are mandatory for municipal infrastructure tenders.
- Sanders:Random orbital and belt formats prioritize vibration dampening and dust extraction integration over raw power density.
- Grinders:Angle grinder architectures with active thermal management enable sustained metal cutting without grid tethering.
Drills command the established base. The steepest expansion runs through grinders as brushless thermal handling improves.
Application:
End-use environments shape duty cycles, durability certifications, and fleet replacement rhythms across four verticals.
- Construction:Commercial building and infrastructure projects demand IP-rated housings and drop-resistant chassis for daily site abuse. OSHA workplace safety standards in the United States accelerate cordless substitution to reduce electrical hazard exposure on active job sites.
- Automotive:Assembly line and aftermarket maintenance operations require precision torque control and compact form factors for under-vehicle access.
- Landscaping:Seasonal commercial operators prioritize battery interchangeability across mowers, blowers, and trimmers to maximize fleet uptime.
- DIY:Home workshop users in China and the United States respond to 18V platform marketing and bundled starter kits.
Construction holds the revenue concentration. Landscaping is climbing the fastest as commercial fleet electrification accelerates.
User Type:
Procurement authority and total cost sensitivity separate four customer archetypes with distinct channel preferences.
- Professionals:Electricians, plumbers, and HVAC technicians purchase through specialized distributors and demand multi-year platform commitments. German and French professional channels now require full material composition disclosure for municipal contracts under evolving REACH substance restrictions.
- Hobbyists:Enthusiast woodworkers and home mechanics research specifications online and prioritize expandability over initial price.
- Contractors:General construction firms negotiate volume pricing and standardized fleet voltage to simplify inventory management.
- Maintenance:Facilities management departments at hospitals, universities, and corporate campuses favor interoperability across building systems.
Professionals anchor premium pricing power. Contractors are gaining share fastest as informal labor formalizes in India and Southeast Asia.
Battery Technology:
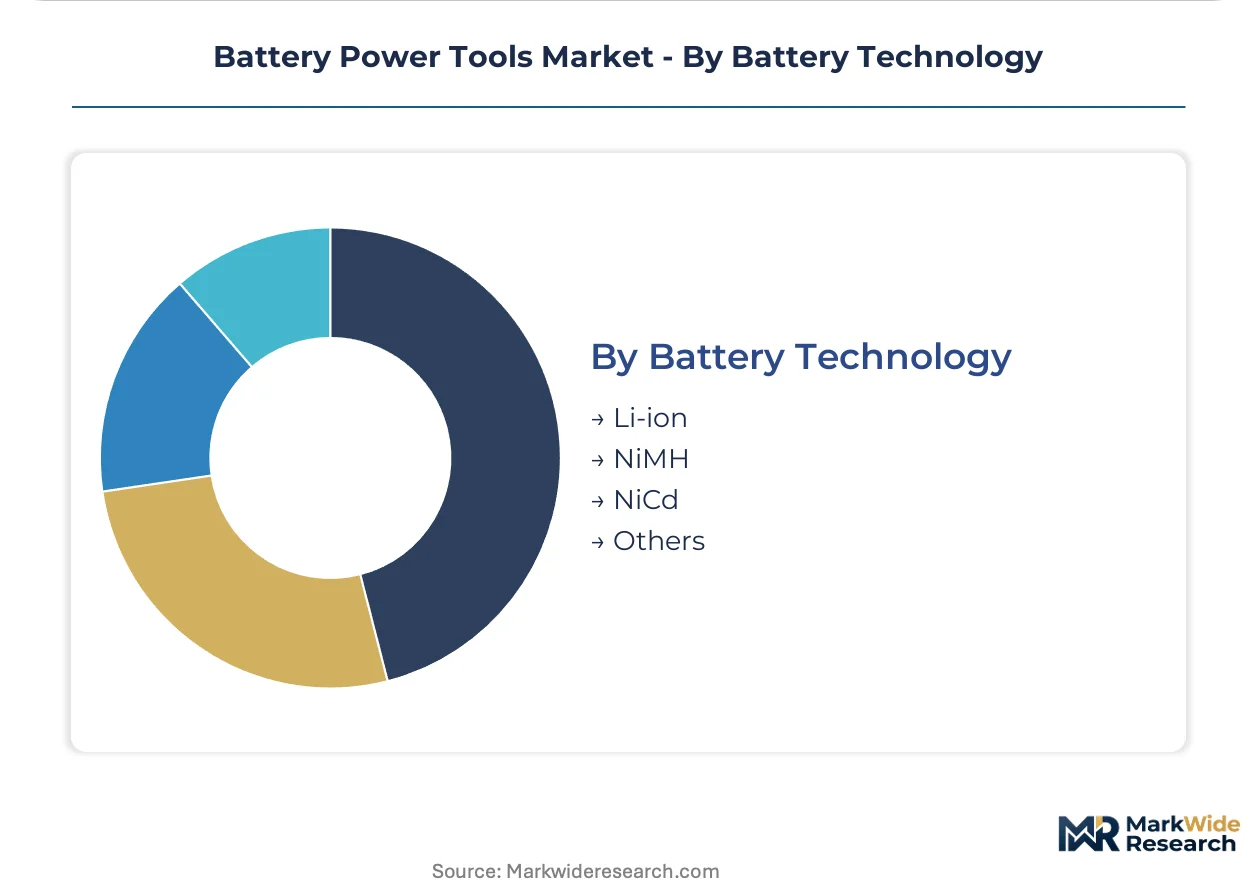
Chemistry selection determines energy density, cycle life, and regulatory compliance exposure across four technological trajectories.
- Li-ion:Nickel-manganese-cobalt and lithium iron phosphate cells dominate 18V-80V platforms with 500-1500 cycle ratings. EU F-Gas Regulation and REACH compliance are pushing manufacturers toward cobalt-free formulations for mid-voltage applications.
- NiMH:Nickel-metal hydride packs persist in legacy 12V-14.4V tools and price-sensitive replacement markets.
- NiCd:Nickel-cadmium chemistry faces disposal restrictions under US EPA battery recycling mandates and declining production economics.
- Others:Sodium-ion prototypes and solid-state research programs target cobalt elimination and thermal runaway elimination.
Li-ion holds the installed base. Sodium-ion and solid-state alternatives are expanding most quickly in European professional channels seeking cobalt-free supply chains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across geographies. German professional contractors absorb premium pricing for REACH-compliant battery systems, while Indian informal sector buyers prioritize entry-level 18V platforms. Chinese procurement concentrates on brushless motor density for domestic construction scale.
United States
Residential renovation spending by DIY homeowners drives 18V-20V platform lock-in through ecosystem purchases. OSHA workplace safety standards accelerate cordless substitution to reduce electrical hazard exposure on active construction sites. Tool demand clusters in Texas and Florida where housing starts and storm recovery projects sustain contractor fleet replacement cycles.
Germany
Professional channels mandate full material composition disclosure for municipal infrastructure tenders under evolving REACH substance restrictions. The EU F-Gas Regulation phases down hydrofluorocarbon refrigerants in battery thermal management systems. Industrial procurement concentrates in Baden-Württemberg where automotive supplier networks extend tool specifications into metalworking applications.
China
Domestic construction and manufacturing scale create outsized procurement volumes for brushless motor platforms. MIIT efficiency standards and dual carbon goals push manufacturers toward cobalt-free battery chemistries. Production gravity centers on the Yangtze River Delta where cell manufacturing clusters supply both automotive and power tool OEMs.
India
The Smart Cities Mission and urban housing targets generate first-time demand for cordless tools among informal sector contractors. BIS certification requirements and PLI scheme incentives for domestic manufacturing reshape import dependency. Demand concentrates in Maharashtra and Gujarat where commercial construction formalization accelerates fleet electrification.
Japan
Precision torque control requirements in automotive assembly sustain demand for compact 14.4V-18V platforms. METI battery recycling directives and JIS standards enforce design-for-disassembly protocols. Manufacturing tool procurement clusters in the Chubu region around Nagoya-based automotive OEM supplier networks.
Battery Power Tools Market Competitive Environment
Capability concentration sits with specialized motor control and battery management tiers; scale advantage sits with diversified industrial conglomerates. The vendor base stratifies into three layers: premium platform architects with proprietary battery ecosystems, mid-tier regional assemblers with licensed motor designs, and aftermarket refurbishment specialists capturing end-of-life value. Dominant competitive moves include platform standardization investments to lock professional users into voltage-architecture ecosystems, and backward integration into cell procurement to secure cobalt-free supply chains.
Within the premium platform tier, Techtronic Industries and Stanley Black & Decker occupy positions defined by multi-brand portfolio density across DIY and contractor segments. Robert Bosch exemplifies the integrated industrial archetype, anchoring European demand with battery systems that span automotive and construction tool applications. These three entities represent contrasting geographic anchors: Hong Kong-listed, US-heritage, and German-engineered respectively.
| Leading Market Players |
|---|
| Techtronic Industries |
| Hilti |
| Stanley Black & Decker |
| Atlas Copco |
| Ingersoll Rand |
| Robert Bosch |
| Milwaukee |
| Panasonic |
| Makita |
| Others |
Value Chain & Pricing Dynamics
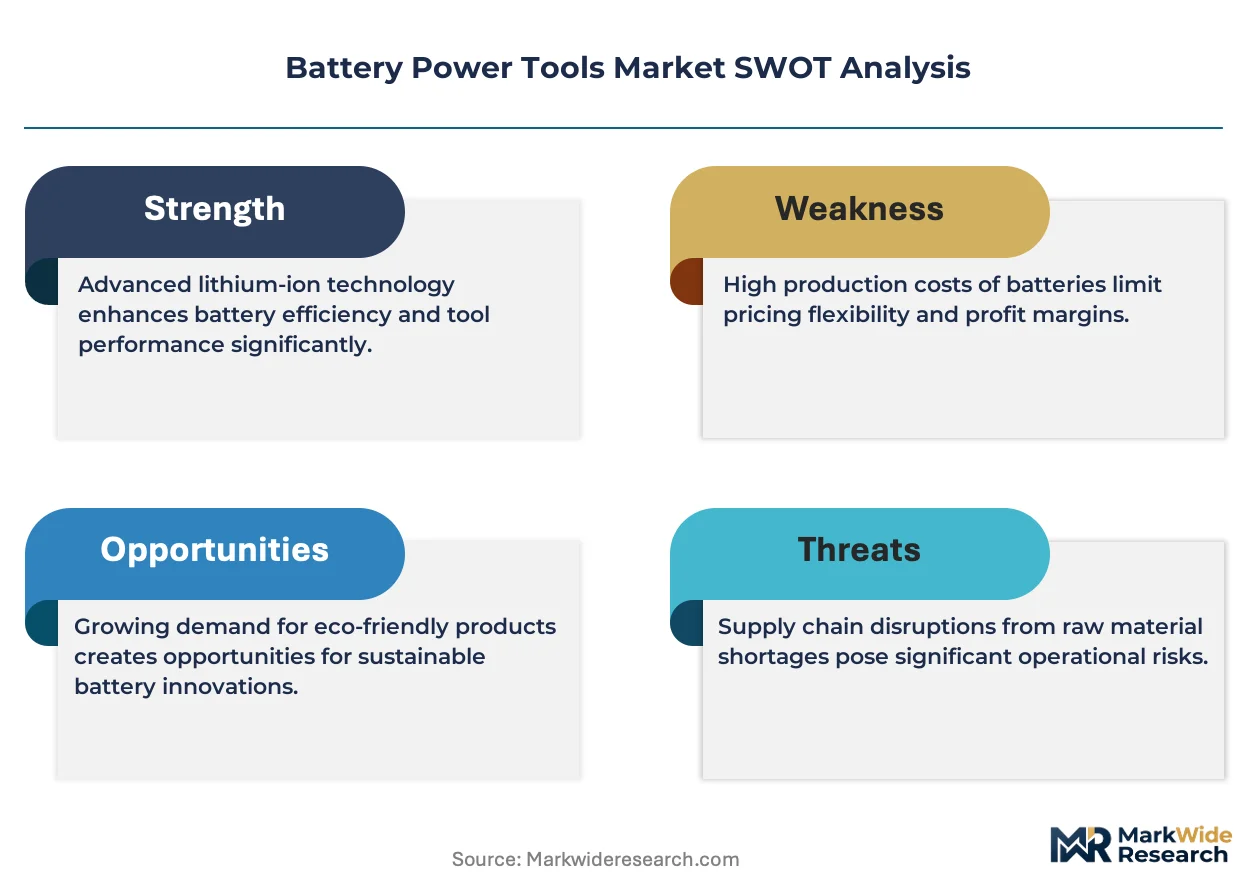
Cobalt refining concentration in the Democratic Republic of Congo anchors lithium-ion cell cost structures and transfers pricing power downstream to battery pack integrators rather than tool OEMs. Margin pools concentrate in aftermarket refurbishment services and platform-agnostic charging infrastructure where cell replacement economics undercut factory-new pricing.
Pricing Analysis
Aftermarket battery pack refurbishment drives lifetime value capture for commercial fleet operators seeking uptime over brand loyalty. Three-tier pricing structure across premium brushless platforms, standard brushed-motor tools, and entry-level DIY equipment reflects certification grade and thermal management sophistication. Cost compression in mid-voltage tiers intensifies as sodium-ion chemistry matures and cobalt-free formulations reach scale. Contractors operating standardized fleet voltages exhibit lowest price sensitivity; informal sector buyers in India and Southeast Asia remain most responsive to entry-level positioning.
Supply Chain Analysis
Contract manufacturing for battery packs concentrates among specialized electronics manufacturing services in China, South Korea, and Vietnam with dedicated lithium-ion assembly lines. Cell procurement draws from nickel-manganese-cobalt and lithium iron phosphate supply chains anchored in Chinese Yangtze River Delta clusters and South Korean chemical complexes. Single-source vulnerability persists in refined cobalt and silicon carbide power semiconductors for brushless motor controllers. Distribution runs through specialized industrial distributors for professional channels and big-box retail for DIY segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Battery power tools have crossed into platform-economics territory where voltage-architecture lock-in determines lifetime customer value. Interoperability standards and charging ecosystem unification are accelerating this shift.
For Market Incumbents: Entrench professional users through multi-year platform commitments and backward integration into cobalt-free cell procurement. Defend against independent refurbishment specialists by extending warranty terms and enabling certified cell replacement programs. Prioritize thermal management R&D to maintain performance differentiation as sodium-ion chemistry commoditizes mid-voltage tiers.
For New Entrants and Emerging Players: India's informal construction sector offers first-mover opportunity as Smart Cities Mission formalizes contractor fleets. Target platform-agnostic charging infrastructure and cross-manufacturer battery compatibility as entry vectors. Pursue direct-to-contractor distribution partnerships bypassing established distributor relationships.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed aftermarket refurbishment specialists and regional battery pack assemblers lacking brand equity. Long-term viability hinges on cobalt-free chemistry transitions and solid-state thermal management patents. Monitor REACH substance restriction expansions and EU F-Gas Regulation enforcement as inflection signals for chemistry migration timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization Investment | Voltage-architecture lock-in secures multi-tool ecosystem purchases and recurring battery replacement revenue. |
| Backward Integration into Cell Procurement | Captive cobalt-free supply chains insulate margins from DRC price volatility and ethical sourcing audits. |
| Aftermarket Refurbishment Network Buildout | Cell replacement services capture margin pools from cost-sensitive commercial fleet operators. |
| GaN-Based Fast-Charging Infrastructure | Silicon carbide power electronics compress recharge intervals for commercial landscaping fleet uptime. |
| REACH-Compliant Chemistry Reformulation | Material composition disclosure satisfies German and French municipal procurement mandates. |
Study Parameters
Initial hypotheses were tested against primary input from power tool product managers, battery pack procurement leads at commercial landscaping fleets, industrial distributor category buyers, and brushless motor control engineers and refined through secondary validation. Primary fieldwork encompassed structured interviews across OEM engineering divisions, aftermarket service providers, and municipal procurement officers in Germany and France. Secondary sources included EU REACH candidate list updates, EPA battery recycling mandate filings, UL 2595 certification databases, and customs trade data for lithium-ion cell imports. Bottom-up demand modeling triangulated against top-down manufacturer revenue aggregation.
Demand-supply-balance framing anchored the analytical framework across the analysis window. Segmentation dimensions encompassed voltage platform tier, end-use application intensity, user procurement authority, and battery chemistry compliance status. CAGRs derived from normalized historical shipment data and forward-projected replacement cycles. Industry-specific inputs included brushless motor adoption curves, REACH substance restriction phase-in schedules, and cobalt price elasticity coefficients.
Practitioners should monitor cobalt price volatility, REACH SVHC list expansions, and solid-state battery pilot production announcements for early signals of chemistry migration timing. Quarterly review of UL and IEC certification backlogs, municipal tender material disclosure requirements, and third-party charging infrastructure deployment rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Micro Motor Market
Industrial Equipment
Sorter Machines Market
Industrial Equipment
Europe Vacuum Pump Market
Industrial Equipment
Global Cryostat Market
Industrial Equipment
ROV Tether Management System Market
Industrial Equipment
Vacuum Concentrators Market
Industrial Equipment
Pin Marking Machine Market
Industrial Equipment
Long-Range Acoustic Device Market
Industrial Equipment
Air Bearings Market
Industrial Equipment
Seismic Data Acquisition Equipment Market
Industrial Equipment
Linear Shaft Motor Market
Industrial Equipment
Europe Fans and Blowers Market
Industrial Equipment
Global Servo Motor Market
Industrial Equipment
Laser Marking Machine Market
Industrial Equipment
Dry Block Heaters Market
Industrial Equipment
Magnetic Chip Conveyors Market