
 Drop Weight Testers Market | 2026-2036
Drop Weight Testers Market Size, Share, and Industry Trends Forecast 2026-2036
Drop Weight Testers Market Insights
Aftermarket calibration and certification revenue is fragmenting across regional service networks as equipment owners seek faster turnaround times. Instron leverages its North American service infrastructure to capture recurring revenue from installed bases. ZwickRoell anchors European demand through German-accredited testing protocols. Shimadzu Corporation dominates Asia-Pacific with localized technical support and JIS-compliant validation services.
Drop weight testers are mechanical instruments that accelerate a defined striker mass through a guided column onto a specimen to measure fracture energy, ductile-to-brittle transition, and impact resistance per ASTM E208 or ISO 148 standards. Automatic drop weight testers command premium positioning due to programmable multi-drop sequences and integrated data acquisition, while digital sensor-based technology segments attract R&D investment for real-time strain mapping. Pneumatic systems retain cost advantages in emerging material testing laboratories with lower throughput requirements.
FDA device-material qualification rules, FAA composite airworthiness directives, and ASTM International impact-test protocols collectively mandate documented traceability for aerospace and medical device supply chains. ISO 17025 accreditation requirements force laboratories to upgrade legacy manual systems with calibrated digital instrumentation. Stakeholders must weigh capital deployment between electromechanical precision and pneumatic cost efficiency as regulatory audit frequencies intensify.
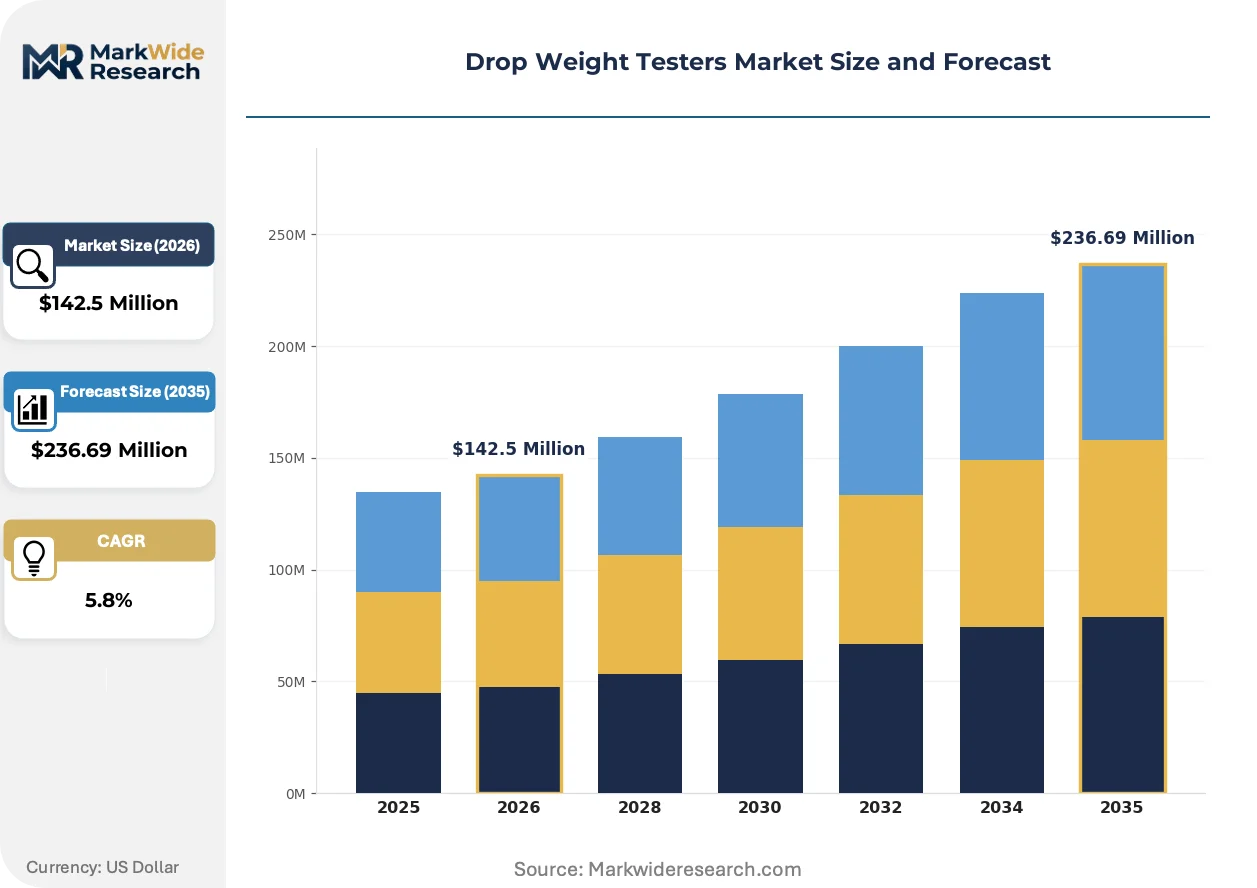
Market Dynamics
Automated impact testing systems are displacing manual drop weight configurations as aerospace and automotive certification pipelines demand traceable, repeatable fracture energy data under tightening ASTM and ISO protocols.
Growth Catalysts
- FAA composite airworthiness directives:Mandated documented impact resistance for carbon-fiber primary structures is accelerating replacement of legacy manual testers at US Gulf Coast aerospace suppliers.
- Germany's automotive testing corridor:OEM qualification laboratories in Stuttgart and Munich are procuring multi-axis automated systems to meet accelerated material validation cycles for electric vehicle platforms.
- Digital sensor integration:Real-time strain mapping capabilities embedded in striker assemblies are enabling ductile-to-brittle transition analysis that pneumatic systems cannot replicate.
Market Restraints
- Capital intensity of electromechanical precision:Servo-controlled striker positioning and calibrated load cells impose equipment costs that strain emerging laboratory budgets in Southeast Asia.
- Helium supply concentration:Pneumatic system dependency on refined gas supplies from Qatar and Algeria creates input cost volatility for cost-sensitive testing facilities.
- ISO 17025 accreditation timelines:Eighteen-month validation cycles for digital instrumentation retrofits delay revenue recognition for equipment owners upgrading legacy manual columns.
Strategic Opportunities
- India's PLI scheme for advanced materials:Domestic carbon-fiber manufacturing incentives are creating demand for localized impact testing capacity outside traditional import channels.
- Battery enclosure qualification:Electric vehicle thermal runaway containment standards are opening new application scope for high-energy drop weight protocols previously confined to aerospace.
- Subscription-based calibration networks:Remote sensor validation and cloud-based certification documentation are reducing downtime for distributed testing operations.
Industry Challenges
- Metrology technician scarcity:Specialized expertise in striker mass calibration and velocity verification is concentrating among German-accredited training programs.
- Legacy data format incompatibility:Analog chart recorders from 1990s-era equipment cannot interface with modern LIMS platforms, forcing parallel documentation systems during transition periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drop Weight Testers Market |
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $236.69 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic Drop Weight Testers, Manual Drop Weight Testers, Digital Drop Weight Testers, Hydraulic Drop Weight Testers Technology: Electromechanical, Pneumatic, Hydraulic, Digital Sensor-Based, Laser Measurement Application: Metal Impact Testing, Coal Hardness Testing, Composite Material Assessment, Glass Durability Analysis, Aerospace Material Testing End User: Material Testing Laboratories, Research Institutes, Quality Assurance Departments, Aerospace Manufacturers, Construction Material Companies |
| Companies Covered | Instron, ZwickRoell, Shimadzu Corporation, Tinius Olsen, MTS Systems Corporation, ADMET, Inc., Hegewald & Peschke, Labthink Instruments, Riechert Testing Machines, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drop Weight Testers Market Trends and Innovations
Real-time data acquisition architectures are compressing the gap between mechanical impact events and analytical insight, reshaping how laboratories validate material qualification protocols.
Programmable multi-drop sequences with integrated high-speed videography are collapsing the distinction between single-impact characterization and fatigue-like progressive damage assessment. Aerospace tier-one suppliers in Japan and Germany are deploying these systems for carbon-fiber laminate qualification. The technology is collapsing traditional testing timelines by embedding fracture mechanics analysis directly into the impact event rather than post-processing.
ASTM International's revised E436 annex on instrumented striker calibration is forcing laboratories to document traceability chains for piezoelectric load cell drift. The regulation compresses permissible recertification intervals from twenty-four to twelve months. European notified bodies are prioritizing audit resources toward polymer composite laboratories, pushing facilities toward automated calibration routines.
Testing service unbundling is fragmenting long-term equipment ownership models. Automotive OEMs in Stuttgart and Wolfsburg are contracting impact validation as discrete service events rather than captive laboratory investment. The pattern concentrates equipment utilization at regional service hubs with ISO 17025 scope expansion, marginalizing standalone laboratory capital deployment.
Drop Weight Testers Market Segmentation
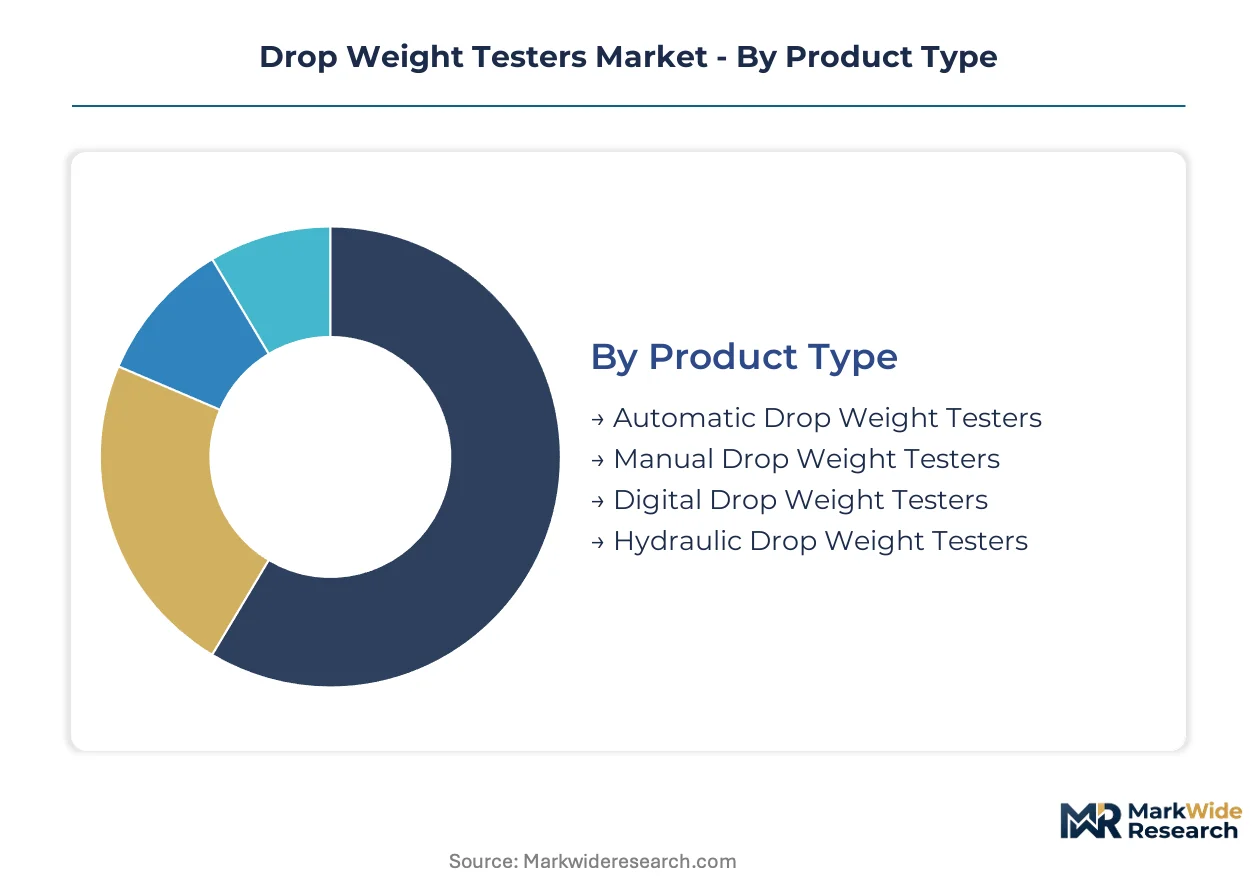
Drop weight tester procurement patterns diverge sharply across operational scales and certification requirements. Laboratories serving FAA composite directives demand instrumented precision, while emerging facilities prioritize capital efficiency. Understanding these segment boundaries clarifies where technology premiums command pricing power versus where pneumatic simplicity sustains margin.
Product Type:
Equipment selection across cost tiers reflects the tension between throughput demands and capital constraints facing testing facilities.
- Automatic Drop Weight Testers:Programmable multi-drop sequences with integrated data acquisition enable unattended operation for high-volume composite qualification pipelines. Stuttgart automotive laboratories and US Gulf Coast aerospace suppliers specify these systems to compress ASTM E436 validation cycles.
- Manual Drop Weight Testers:Hand-operated striker release mechanisms with basic energy calculation remain prevalent in educational institutions and emerging market facilities with intermittent testing schedules. Operators in Southeast Asia cite lower maintenance burden and simpler calibration protocols as decisive factors.
- Digital Drop Weight Testers:Real-time velocity monitoring and automated fracture energy computation bridge the gap between manual economy and full automation. Japanese precision instrument clusters favor these units for JIS-compliant validation services.
- Hydraulic Drop Weight Testers:High-energy configurations exceeding 50,000 joules serve specialized applications in pipeline steel and heavy construction material assessment. German-accredited protocols for offshore wind tower foundations specify hydraulic actuation for reproducible high-mass impacts.
Automatic configurations command the established base. The steepest expansion runs through digital sensor-equipped intermediate systems.
Technology:
Underlying actuation and measurement architectures determine which laboratories can meet tightening ISO 17025 instrumentation requirements.
- Electromechanical:Servo-controlled striker positioning with calibrated load cells delivers velocity precision within 0.5% for ductile-to-brittle transition analysis. FAA airworthiness directives for carbon-fiber primary structures mandate this technology tier for documented traceability.
- Pneumatic:Compressed gas acceleration systems from Qatar and Algerian helium supply chains retain cost advantages in facilities with lower throughput requirements. Capital constraints in Southeast Asian emerging laboratories sustain demand despite velocity consistency limitations.
- Hydraulic:Fluid-power actuation dominates ultra-high-energy applications where striker masses exceed 500 kilograms. Offshore wind foundation testing in the North Sea relies on hydraulic systems for reproducible impact characterization.
- Digital Sensor-Based:Piezoelectric load cells and high-speed data acquisition enable real-time strain mapping during impact events. Japan's METI-funded R&D programs prioritize this technology for next-generation composite qualification protocols.
- Laser Measurement:Non-contact velocity verification and displacement tracking supplement mechanical instrumentation for audit-grade documentation. European notified bodies increasingly specify laser-based verification for polymer composite laboratory accreditation.
Electromechanical systems anchor premium positioning. Digital sensor integration represents the most rapid technology transition.
Application:
End-use specialization dictates energy range requirements and the regulatory frameworks governing test protocol selection.
- Composite Material Assessment:Carbon-fiber laminate qualification for aerospace primary structures requires instrumented strikers with force-time history capture. Boeing and Airbus tier-one suppliers in Germany and Japan deploy automated systems for BVID (barely visible impact damage) characterization.
- Metal Impact Testing:Steel and aluminum ductile-to-brittle transition analysis per ASTM E208 serves pipeline and pressure vessel certification. US Gulf Coast energy infrastructure suppliers specify Charpy-correlated drop weight protocols for offshore platform materials.
- Aerospace Material Testing:FAA-directed composite airworthiness validation concentrates demand at specialized laboratories with ISO 17025 scope expansion. Regulatory audit frequencies intensify equipment upgrade cycles.
- Glass Durability Analysis:Architectural and automotive glazing impact resistance testing follows regional building codes and ECE R43 automotive safety regulations. German automotive OEMs specify standardized drop weight protocols for windshield qualification.
- Coal Hardness Testing:Mining sector applications measure friability and grindability indices for processing optimization. Australian and South African coal operations utilize drop weight indices for mill design specifications.
Composite assessment holds the largest installed base. Battery enclosure qualification for electric vehicle thermal runaway containment is climbing the fastest.
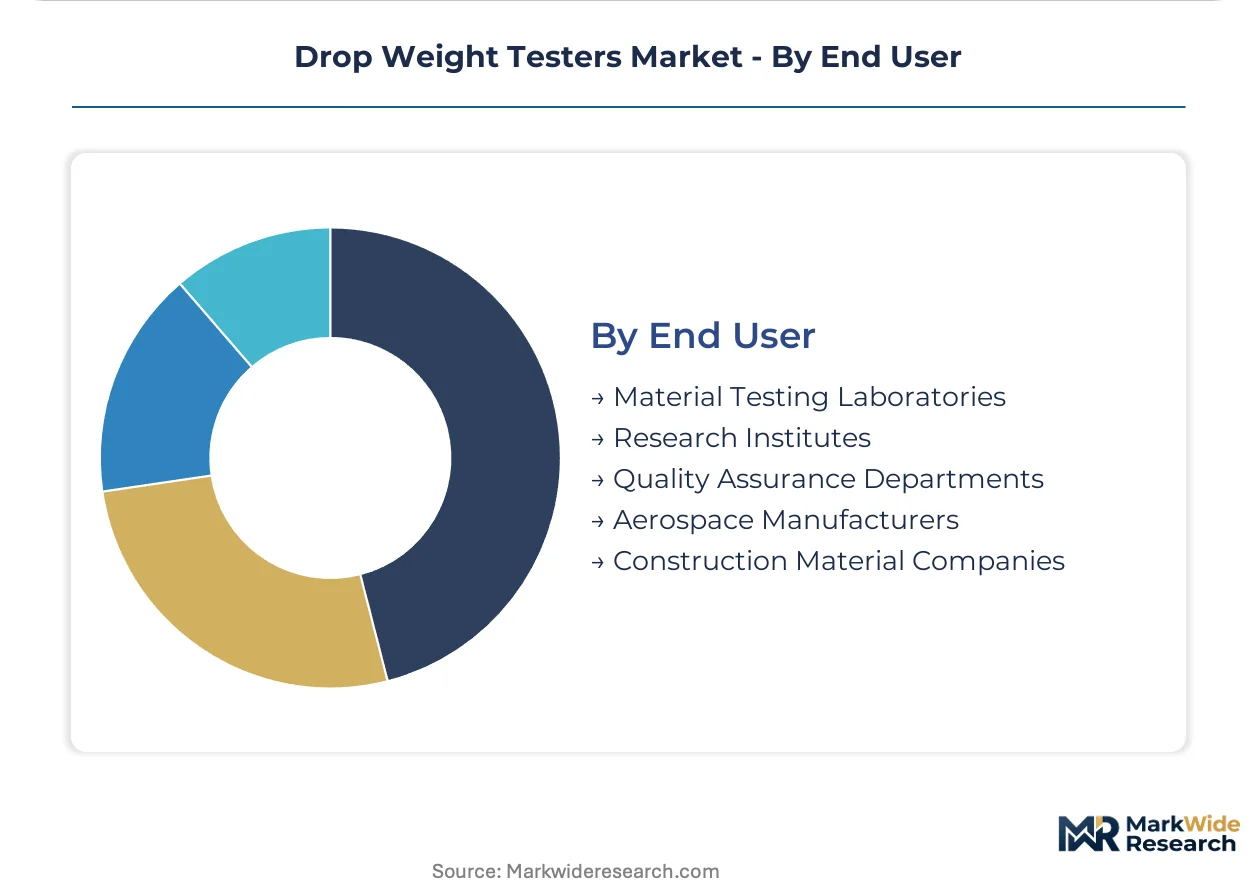
End User:
Customer type determines procurement authority, service contract structures, and the balance between captive capacity and outsourced validation.
- Material Testing Laboratories:Independent ISO 17025-accredited facilities serving multiple industries face the steepest instrumentation upgrade pressure. European notified body audit prioritization accelerates digital retrofit timelines.
- Aerospace Manufacturers:Boeing, Airbus, and Gulf Coast suppliers maintain captive testing capacity for proprietary composite formulations. FAA directive compliance mandates documented traceability chains.
- Research Institutes:University and government laboratory procurement emphasizes flexibility for protocol development over production throughput. Japan's METI and Germany's Fraunhofer networks prioritize multi-axis automated systems.
- Quality Assurance Departments:Captive manufacturing laboratory investment is fragmenting as automotive OEMs unbundle testing services. Stuttgart and Wolfsburg operations increasingly contract discrete validation events.
- Construction Material Companies:Cement, aggregate, and precast concrete producers utilize drop weight protocols for toughness and abrasion resistance. Indian infrastructure expansion under PLI scheme incentives is creating localized demand.
Independent material testing laboratories retain the deepest installed base. Aerospace manufacturer captive capacity is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive laboratories deploy automated drop weight systems for electric vehicle composite validation, while Japanese precision clusters prioritize digital sensor integration for aerospace certification pipelines. This consumption-mix differential separates high-throughput automation demand from R&D-focused instrumentation investment.
United States
FAA composite airworthiness directives mandate documented impact resistance for carbon-fiber primary structures. Gulf Coast aerospace suppliers in Texas and Louisiana accelerate replacement of legacy manual testers. Boeing tier-one contractors in Seattle and Charleston deploy multi-axis automated systems for BVID characterization.
Germany
OEM qualification laboratories in Stuttgart and Munich procure electromechanical precision systems for accelerated material validation cycles. KBA automotive safety protocols tighten certification requirements for battery enclosure impact testing. Fraunhofer research networks anchor demand in Bavaria and Baden-Württemberg for next-generation composite protocols.
Japan
METI-funded R&D programs prioritize digital sensor-based technology for real-time strain mapping capabilities. JIS-compliant validation services concentrate in Nagoya and Osaka precision instrument clusters. Shimadzu Corporation's localized technical support infrastructure dominates aftermarket calibration revenue across the archipelago.
India
PLI scheme incentives for domestic carbon-fiber manufacturing create demand for localized impact testing capacity outside traditional import channels. BIS standards adoption accelerates laboratory accreditation timelines in Maharashtra and Gujarat. Construction material companies in Delhi-NCR and Chennai invest in drop weight protocols for infrastructure expansion projects.
China
GB standards alignment with ISO 6603 protocols forces material testing laboratory upgrades in Yangtze River Delta manufacturing corridors. MIIT industrial policy prioritizes composite qualification for electric vehicle battery enclosures. Shenzhen and Shanghai testing hubs expand instrumented striker procurement for aerospace supplier certification.
Drop Weight Testers Market Competitive Landscape
Capability concentration sits with electromechanical precision specialists; scale advantage sits with diversified instrumentation conglomerates. The vendor base organizes around three strategic archetypes: German-accredited protocol anchors, Asia-Pacific technical service networks, and North American aftermarket calibration platforms. Competitive moves concentrate on geographic service infrastructure expansion and digital sensor technology licensing arrangements.
Among German-based precision engineering houses, ZwickRoell GmbH and Hegewald & Peschke occupy positions within the protocol-anchored tier, exemplifying how European accreditation requirements translate into sustained equipment specification authority. Shimadzu Corporation represents the Asia-Pacific service-network archetype, with its Co., Ltd. structure supporting localized validation infrastructure. Instron anchors North American aftermarket revenue capture through installed base service contracts.
| Leading Market Players |
|---|
| Instron |
| ZwickRoell |
| Shimadzu Corporation |
| Tinius Olsen |
| MTS Systems Corporation |
| ADMET, Inc. |
| Hegewald & Peschke |
| Labthink Instruments |
| Riechert Testing Machines |
| Others |
Pricing and Supply Chain Analysis
Helium supply concentration in Qatar and Algeria anchors pneumatic system cost structures, funneling margin pools toward electromechanical precision vendors with captive servo-motor supply chains. Equipment buyers face divergent total-cost-of-ownership profiles depending on which actuation technology they specify.
Pricing Analysis
Long-term service contracts dominate procurement for high-throughput laboratories, while spot purchases persist in educational and emerging-market facilities. Three-tier pricing structure across instrumented precision, digital intermediate, and pneumatic economy levels reflects certification grade and after-sales bundling intensity. Cost compression in pneumatic tiers is intensifying because refined gas supply volatility feeds into maintenance contract pricing. Emerging laboratories in Southeast Asia exhibit the highest price sensitivity, whereas FAA-compliant aerospace suppliers prioritize traceability over capital outlay.
Supply Chain Analysis
Tariff exposure between Germany and China for piezoelectric load cell components dominates supply chain risk planning for instrumented striker manufacturers. Precision machining capacity concentrates in Germany, Japan, and Switzerland, drawing from rare-earth magnet supplies for servo motors and high-purity aluminum for striker masses. Single-source vulnerability in helium refining creates input cost volatility for pneumatic system vendors. Distribution runs through regional service hubs with ISO 17025 accreditation rather than direct equipment sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Drop weight tester penetration sits at early-cycle expansion, with battery enclosure qualification for electric vehicle thermal runaway containment opening application scope beyond traditional aerospace and automotive boundaries.
For Market Incumbents: Entrench position by deepening backward integration into piezoelectric load cell calibration infrastructure and expanding German-accredited training programs to address metrology technician scarcity. Certification investment in ISO 17025 scope expansion for regional service hubs counters testing-service unbundling threats from automotive OEMs. For New Entrants and Emerging Players: India's PLI scheme for advanced materials offers the most penetrable geographic entry point, with domestic carbon-fiber manufacturing incentives creating demand for localized impact testing capacity outside established import channels. Battery enclosure qualification protocols present a white-space application with less entrenched incumbent specification authority. A calibration-network partnership model with existing ISO 17025 laboratories accelerates market access without captive capital deployment. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed testing service platforms consolidating regional laboratory networks. Long-term viability hinges on recurring calibration revenue density rather than equipment shipment volume. The signal to monitor is FAA audit frequency acceleration, which compresses replacement cycles for legacy manual systems.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Load Cell Manufacturing | Captive calibration infrastructure secures margin pools from piezoelectric component suppliers in Germany and Japan. |
| Regional Service Hub Accreditation Expansion | ISO 17025 scope expansion in Stuttgart and Nagoya captures testing-service unbundling revenue from automotive OEMs. |
| Digital Sensor Technology Licensing | Real-time strain mapping IP partnerships with METI-funded R&D programs accelerate JIS-compliant product development. |
| Battery Enclosure Protocol Development | Thermal runaway containment standards for electric vehicles open new application scope beyond aerospace certification pipelines. |
| Subscription-Based Calibration Networks | Remote sensor validation and cloud-based certification documentation reduce downtime for distributed testing operations. |
Research Methodology
Operator-level perspectives from laboratory directors, metrology technicians, OEM procurement managers, and aftermarket service heads anchored the qualitative base. Primary interviews combined with secondary validation from ASTM International protocol documentation, ISO 17025 accreditation records, FAA airworthiness directive filings, and customs trade data for precision instrumentation imports. Bottom-up equipment shipment analysis triangulated against top-down spending estimates from aerospace and automotive R&D budget disclosures.
Scenario-bracketing around helium supply volatility and FAA audit frequency acceleration shaped the analytical framework across the analysis window. Segmentation dimensions modeled include product type tier, actuation technology, end-use application, and customer archetype. CAGRs derived from fitted growth curves against historical qualification pipeline volumes, with composite airworthiness certification timelines and electric vehicle platform launch schedules as key industry-specific inputs.
Practitioners should monitor helium supply chain disruptions and ASTM E436 recertification interval compressions for early signals requiring forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Flying Probe Testing for PCB Assembly Market
Test and Measurement
Impact Testing Machine Market
Test and Measurement
Chiplet-Based System Thermal Cycling and Interconnect Fatigue Test Systems Market
Test and Measurement
Semiconductor Chip Test Probes Market
Test and Measurement
X-Ray Inspection System for Secondary Battery Market
Test and Measurement
State Transition Testing Market
Test and Measurement
Solid-State Battery Fast-Charge Degradation Test Systems Market
Test and Measurement
Marine Electronics Tester Market
Test and Measurement
Global Nondestructive Testing Equipment Market
Test and Measurement
Manufacturing Test Systems Market
Test and Measurement
Continuous Friction Tester Market
Test and Measurement
Miniature Atomic Clock Market
Test and Measurement
AI-Enabled Testing Market
Test and Measurement
Video Test Equipment Market
Test and Measurement
Inline Metrology Market
Test and Measurement
APAC NDT Equipment Market