
 Hydrogen Monitor Market | 2026-2036
Hydrogen Monitor Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrogen Monitor Market Insights
Multi-source procurement for sensor components is rebalancing as manufacturers seek supply resilience against semiconductor shortages. Honeywell International Inc. leverages its distributed sensing architecture to serve large refinery deployments. Teledyne Technologies anchors its position through deep R&D intensity in optical detection pathways. H2Scan Corporation specializes in solid-state palladium-based sensors that dominate niche high-purity hydrogen applications.
A hydrogen monitor detects hydrogen gas concentration through electrochemical, thermal conductivity, semiconductor, or optical sensing principles, typically measuring from parts-per-million to percentage levels to prevent explosive mixtures forming in air. These instruments serve critical safety and process control functions across facilities where hydrogen generation, storage, or consumption occurs. Fixed monitors command the largest installed base due to permanent infrastructure integration in refineries and chemical plants, while portable units represent the fastest-growing category as field maintenance teams adopt personal protective protocols. Electrochemical technology sustains broad commercial traction for its cost-performance balance, though optical methods are gaining ground where false-alarm immunity matters most.
The EPA enforces hydrogen sulfide and flammable gas monitoring requirements at US refineries under Clean Air Act provisions, while the EU's ATEX directives mandate intrinsically safe equipment certification for hazardous zone installations. Germany's Federal Institute for Materials Research and Testing (BAM) shapes national hydrogen infrastructure standards that directly influence monitor specification thresholds. Stakeholders must track evolving certification timelines as hydrogen blending into natural gas networks triggers new measurement accuracy requirements across multiple jurisdictions.
Market Dynamics
Refinery process safety mandates are compressing replacement cycles for hydrogen detection infrastructure, forcing operators to retire legacy electrochemical units ahead of depreciation schedules.
Growth Catalysts
- EU F-Gas Regulation:Equipment replacement mandates across German, Dutch, and Belgian industrial zones are accelerating procurement of next-generation optical detection systems.
- Green hydrogen production hubs:Electrolyzer installations in Denmark and Spain are generating dedicated demand for high-purity hydrogen monitors at gigawatt-scale facilities.
- Solid-state palladium sensors:Semiconductor fabrication and aerospace ground operations are adopting these for immunity to cross-gas interference.
Market Restraints
- Palladium supply concentration:Russian and South African mining operations control critical feedstock for solid-state sensor membranes.
- ATEX certification timelines:Intrinsically safe equipment approvals in EU member states extend lead times by 8-14 months for new product introductions.
- Electrochemical cross-sensitivity:Hydrogen sulfide and carbon monoxide interference limits deployment in sour gas processing environments.
Strategic Opportunities
- Hydrogen blending into natural gas networks:Italy and the United Kingdom are piloting 20% hydrogen injection requiring distributed pipeline monitoring.
- Portable personal protective protocols:Field maintenance teams in North Sea offshore platforms are driving unit-level procurement outside capital budgets.
- Optical-Raman convergence:Integration with process analytical technology suites opens chemical plant retrofit contracts.
Industry Challenges
- Calibration technician scarcity:Electrochemical sensor maintenance requires specialized training that outpaces vocational pipeline output.
- Legacy 4-20mA integration:Digital Modbus and HART protocol upgrades demand parallel wiring runs in brownfield installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrogen Monitor Market |
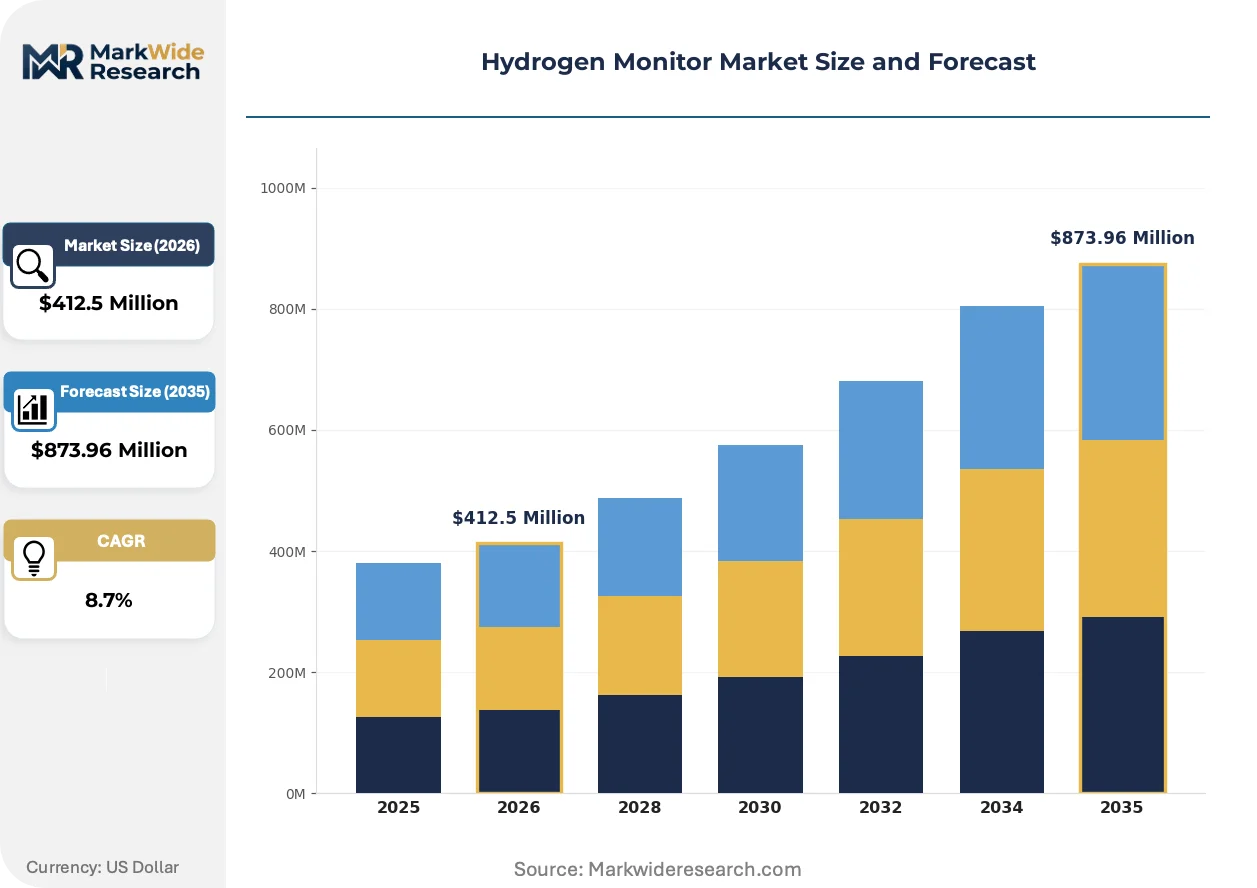
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $873.96 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Monitors, Fixed Monitors, Transmitters, Analyzers Technology: Electrochemical, Thermal Conductivity, Semiconductor, Optical End User: Industrial Manufacturing, Oil & Gas, Renewable Energy, Chemical Processing Application: Leak Detection, Process Monitoring, Safe Storage, Environmental Compliance |
| Companies Covered | Honeywell International Inc., Teledyne Technologies, Figaro Engineering, MSA Safety Incorporated, Drägerwerk AG & Co. KGaA, H2Scan Corporation, Emerson Electric Co., RKI Instruments, Inc., Industrial Scientific Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrogen Monitor Market Trends and Innovations
Detection modality boundaries are dissolving as multi-sensor fusion architectures displace single-technology units. Vendors are bundling hydrogen, oxygen, and pressure sensing into unified safety nodes.
Tunable diode laser absorption spectroscopy is converging with refinery distributed control systems. Honeywell and Teledyne are embedding these units directly into hydrocracker and reformer process loops. Real-time concentration feedback is converging with automated emergency shutdown logic, compressing incident response windows from minutes to seconds.
REACH substance restrictions are phasing out lead-based sensor components across EU manufacturing. Equipment suppliers are reformulating electrochemical cell electrolytes to eliminate cadmium and mercury salts. German chemical operators are front-loading replacement purchases to avoid supply interruptions during the 2026-2027 transition window.
Maintenance teams are unbundling sensor replacement from original manufacturer service contracts. Third-party calibration laboratories in Texas and Rotterdam are capturing recurring revenue through subscription-based certification programs. This channel shift is most visible in downstream oil and gas, where procurement autonomy has devolved to site-level reliability engineers.
Hydrogen Monitor Market Segmentation
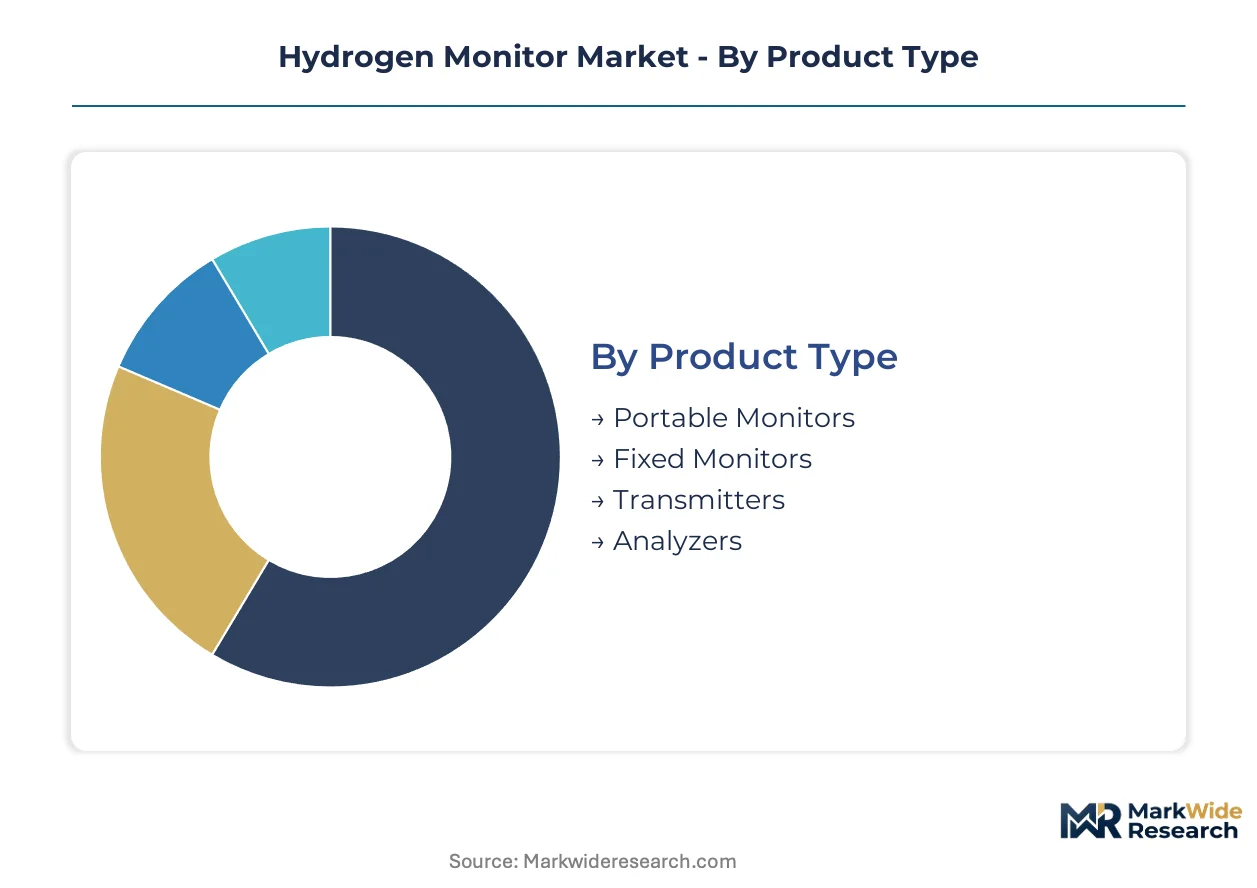
Hydrogen monitor procurement patterns diverge sharply across product configurations, sensing technologies, and operational contexts. Certification requirements from ATEX, IECEx, and national hazardous area regulators segment the addressable market by installation environment and safety integrity level.
Product Type:
Fixed monitors carry the heaviest certification burden under EU ATEX directives and US OSHA process safety mandates, while portable units navigate simpler electromagnetic compliance pathways. Transmitters and analyzers face additional metrology approvals for custody-transfer accuracy.
- Fixed Monitors:Permanent installations integrate with refinery distributed control systems through 4-20mA or digital HART protocols. German chemical parks and Dutch hydrogen pipeline hubs command the largest procurement volumes for zone-rated fixed systems. Replacement cycles compress as REACH substance restrictions phase out legacy electrochemical cell formulations.
- Portable Monitors:Handheld units serve field maintenance teams on North Sea offshore platforms and Texas refinery turnarounds. Personal protective protocols outside capital budgets accelerate unit-level procurement faster than infrastructure-linked categories. Battery life and wireless connectivity specifications dominate competitive differentiation.
- Transmitters:Compact sensor heads with standardized output signals embed directly into electrolyzer skids and hydrogen fueling stations.
- Analyzers:Laboratory-grade and inline process analytical instruments deliver part-per-billion detection thresholds for semiconductor fabrication and aerospace ground operations.
Leading the category by volume: Fixed Monitors. Growing fastest: Portable Monitors.
Technology:
Cost tiers separate mature electrochemical platforms from emerging optical systems, with thermal conductivity and semiconductor modalities occupying intermediate price-performance positions.
- Optical:Tunable diode laser absorption spectroscopy eliminates cross-gas interference that plagues electrochemical cells in sour gas environments. Honeywell and Teledyne embed these directly into hydrocracker process loops for real-time concentration feedback. Italian and UK hydrogen blending pilots specify optical methods for pipeline custody measurement.
- Electrochemical:Amperometric cells with proprietary electrolyte formulations dominate installed base economics. Calibration technician scarcity and REACH-mandated component reformulation compress service contract margins. Cross-sensitivity to hydrogen sulfide limits deployment in refinery sulfur recovery units.
- Thermal Conductivity:Bulk property measurement suits high-concentration hydrogen streams in ammonia synthesis and methanol production loops.
- Semiconductor:Metal oxide sensors serve cost-constrained ambient leak detection in warehouse and vehicle maintenance facilities.
Highest average selling prices: Optical. Steepest expansion trajectory: Optical-Raman convergence for process analytical technology integration.
End User:
Customer type determines procurement autonomy, with oil and gas operators centralizing decisions through corporate engineering standards while renewable energy developers delegate to EPC contractors.
- Oil & Gas:Refinery process safety mandates under EPA Clean Air Act provisions compress replacement cycles for legacy detection infrastructure. US Gulf Coast and Rotterdam-Antwerp refining clusters sustain concentrated demand for fixed multi-sensor nodes.
- Renewable Energy:Gigawatt-scale electrolyzer installations in Denmark and Spain generate dedicated demand for high-purity hydrogen monitors. Green hydrogen production hubs specify solid-state palladium sensors for immunity to cross-gas interference.
- Industrial Manufacturing:Steel and glass producers adopt hydrogen monitors for fuel-switching safety as blast furnace injection trials expand.
- Chemical Processing:Ammonia and methanol synthesis loops require continuous hydrogen measurement for stoichiometric control and catalyst protection.
Dominant procurement volume: Oil & Gas. Gaining share fastest: Renewable Energy.
Application:
Maturity curves separate established leak detection from emerging process monitoring and environmental compliance use cases.
- Process Monitoring:Integration with automated emergency shutdown logic compresses incident response windows from minutes to seconds. Honeywell and Teledyne anchor positions through direct DCS embedding in hydrocracker and reformer units. Real-time concentration feedback enables predictive catalyst management.
- Leak Detection:Ambient air monitoring for explosive mixture prevention represents the most penetrated application. Fixed point detectors and open-path infrared systems cover refinery process units and hydrogen fueling station canopy spaces.
- Safe Storage:Cryogenic liquid hydrogen and compressed gas facility monitoring requires cryogenic-rated sensors and vapor cloud detection arrays.
- Environmental Compliance:Fugitive emission quantification and greenhouse gas reporting protocols drive new procurement in hydrogen blending pilot zones.
Most mature penetration: Leak Detection. Climbing the fastest: Process Monitoring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German hydrogen pipeline infrastructure and green hydrogen production hubs concentrate procurement volumes at scale, while US refinery clusters and Dutch industrial zones sustain concentrated demand for fixed detection systems.
United States
EPA Clean Air Act enforcement compresses replacement cycles for legacy electrochemical units across Gulf Coast refining clusters. OSHA process safety mandates require intrinsically safe equipment certification for hazardous zone installations. Houston and Port Arthur facilities sustain the largest procurement volumes for multi-sensor fixed nodes.
Germany
Federal Institute for Materials Research and Testing standards directly influence monitor specification thresholds for hydrogen blending infrastructure. EU F-Gas Regulation accelerates equipment replacement cycles across industrial zones in North Rhine-Westphalia. Ruhr chemical parks and Hamburg hydrogen hubs command concentrated procurement for next-generation optical detection systems.
Netherlands
Rotterdam-Antwerp refining corridor sustains demand for zone-rated fixed systems integrated with distributed control architectures. ATEX directives mandate intrinsically safe equipment certification extending lead times for new product introductions. Port of Rotterdam hydrogen import terminal projects drive specialized procurement for cryogenic vapor detection arrays.
United Kingdom
Twenty percent hydrogen injection pilots into natural gas networks require distributed pipeline monitoring with custody-transfer accuracy specifications. Health and Safety Executive regulations govern hazardous area installations for electrolyzer facilities. Teesside and Humber industrial clusters anchor procurement for high-purity hydrogen monitors at gigawatt-scale production sites.
Denmark
Gigawatt-scale electrolyzer installations generate dedicated demand for solid-state palladium sensors with immunity to cross-gas interference. National hydrogen strategy implementation accelerates green hydrogen production hub development. Esbjerg port infrastructure expansion concentrates procurement for process analytical technology integration.
Hydrogen Monitor Market Competitive Landscape
Strategic partnerships dominate the current landscape as vendors bundle multi-sensor fusion architectures into unified safety nodes. The vendor base organizes around three distinct tiers: diversified industrial conglomerates with distributed sensing portfolios, specialized sensor technology developers with deep R&D intensity, and regional safety equipment fabricators with cost-optimized offerings. Two competitive moves define current positioning: technology licensing agreements for optical detection pathways, and backward integration into semiconductor component supply to mitigate palladium feedstock concentration risks.
Among diversified industrial conglomerates, Honeywell International Inc. and Teledyne Technologies occupy positions exemplifying scale-driven platform strategies, while H2Scan Corporation represents the specialized sensor archetype with focused expertise in solid-state detection methodologies. These three anchors illustrate the competitive spectrum from broad industrial automation integration to narrow technology depth.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Teledyne Technologies |
| Figaro Engineering |
| MSA Safety Incorporated |
| Drägerwerk AG & Co. KGaA |
| H2Scan Corporation |
| Emerson Electric Co. |
| RKI Instruments, Inc. |
| Industrial Scientific Corporation |
| Others |
Pricing and Supply Chain Analysis
REACH substance restrictions on lead-based sensor components gate qualified supply and premium-tier pricing access, as German chemical operators front-load replacement purchases to avoid supply interruptions during the mandated transition window. This environmental mandate compresses service contract margins for electrochemical cell manufacturers while elevating optical detection systems to premium pricing tiers.
Pricing Analysis
Volume concentrates in fixed multi-sensor nodes for refinery distributed control systems, while margins accrue to portable units with wireless connectivity specifications. Three-tier pricing structure across ATEX-certified premium, standard industrial, and economy ambient-leak tiers differentiates on certification grade and after-sales bundling. Pricing pressure stems from third-party calibration laboratories capturing recurring revenue through subscription-based certification programs. Renewable energy developers delegate procurement to EPC contractors and exhibit highest price sensitivity, whereas semiconductor fabrication buyers prioritize detection threshold accuracy over unit cost.
Supply Chain Analysis
Dual-sourcing requirements for palladium feedstock mandate multi-supplier qualification as buyers hedge against Russian and South African mining concentration. Semiconductor fabrication draws from Taiwan, South Korea, and Germany for sensor component supply, with palladium membranes, laser diodes, and electrochemical electrolytes anchoring bill-of-materials costs. Single-source vulnerability in solid-state sensor membranes exposes manufacturers to commodity price volatility. Distribution runs through original equipment manufacturer service contracts and third-party calibration laboratories in Texas and Rotterdam.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU F-Gas Regulation creates a barrier-to-entry moat for compliant players, transforming this market into a cost-of-compliance story where ATEX certification investments separate viable competitors from marginal entrants.
For Market Incumbents: Lock in long-term palladium supply agreements before feedstock concentration intensifies. Backward integration into semiconductor component production mitigates Honeywell and Teledyne's captive supply advantages. Capacity addition in German chemical parks captures front-loaded replacement demand ahead of REACH transition deadlines. For New Entrants and Emerging Players: Enter via portable personal protective protocols for North Sea offshore platforms, where procurement autonomy outside capital budgets enables unit-level sales. Target field maintenance teams with battery life and wireless connectivity specifications as the most penetrable buyer archetype. Pursue direct channel relationships with site-level reliability engineers rather than corporate engineering standards. For Investors and Strategic Acquirers: Italian and UK hydrogen blending pilot announcements are the leading indicator that custody-transfer accuracy specifications will reshape procurement criteria. Solid-state palladium sensor specialists with BAM certification represent the highest-value acquisition targets. Watch for F-Gas Regulation enforcement actions as the signal that replacement cycle compression is accelerating.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Palladium Supply | Captive membrane production insulates H2Scan and specialized sensor developers from Russian and South African mining concentration. |
| Optical-Raman Technology Licensing | Process analytical technology integration opens Honeywell and Teledyne to chemical plant retrofit contracts in German Ruhr clusters. |
| Third-Party Calibration Laboratory Acquisition | Rotterdam and Texas certification facilities capture recurring revenue from downstream oil and gas procurement autonomy shifts. |
| ATEX Certification Fast-Track Investment | Eight-to-fourteen-month approval compression enables first-mover positioning in EU hydrogen blending infrastructure tenders. |
| Multi-Sensor Fusion Architecture Development | Unified safety nodes bundling hydrogen, oxygen, and pressure sensing displace single-technology units in refinery deployments. |
Research Methodology
Trade data from Eurostat, EIA refinery safety filings, and BAM hydrogen infrastructure standards formed the secondary backbone, supplemented by customs records for palladium feedstock flows. Primary interviews with refinery process safety officers, EPC contractor procurement leads, and third-party calibration laboratory operators combined with this secondary validation. Bottom-up unit economics for fixed, portable, transmitter, and analyzer configurations triangulated against top-down market sizing from regulatory mandate compliance schedules.
Historical trendline analysis for electrochemical and optical detection modalities established baseline penetration curves across the projection horizon. Segmentation dimensions modeled include product type, sensing technology, end-user industry, and application context, with additional granularity on ATEX certification tier and hydrogen purity specification. CAGRs derived from replacement cycle compression rates and green hydrogen production hub development pipelines. Forecast inputs incorporated F-Gas Regulation enforcement timelines and REACH substance restriction phase-out schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under palladium supply disruption or ATEX certification timeline extension scenarios. Deviation in German hydrogen pipeline infrastructure deployment schedules would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Multi-Axis Sensor Market
Sensors and Controls
Magnetic Absorption Data Line Market
Sensors and Controls
Signal Calibrators Market
Sensors and Controls
Global Color Detection Sensors Market
Sensors and Controls
Japan Sensor Market
Sensors and Controls
Specialty Control Plasma Market
Sensors and Controls
Thermography Condition Monitoring Equipment Market
Sensors and Controls
High-Performance IMU Market
Sensors and Controls
IR Emitter and Receiver Market
Sensors and Controls
Optical Chemical Sensor Market
Sensors and Controls
Anti-Collision Sensor Market
Sensors and Controls
Speed Sensor Market
Sensors and Controls
Motion Control Encoders Market
Sensors and Controls
Vibration Sensor Market
Sensors and Controls
Calibrator Market
Sensors and Controls
Insulation Monitoring Devices (IMD) Market