
 Global Platform Electronic Laboratory Balance Market | 2026-2036
Global Platform Electronic Laboratory Balance Market Size, Share, and Industry Trends Forecast 2026-2036
Global Platform Electronic Laboratory Balance Market Outlook
Metrology-grade calibration specifications is reorganizing procurement criteria across pharmaceutical and semiconductor quality-control labs. METTLER TOLEDO leverages its Swiss manufacturing base and captive sensor production to dominate high-precision analytical balances. Sartorius AG anchors European demand through specialized contamination-resistant designs for biopharma cleanroom environments. Shimadzu Corporation competes in Asia-Pacific markets with integrated chromatography-balance data systems.
A platform electronic laboratory balance is a precision weighing instrument utilizing electromagnetic force restoration or strain-gauge load cells, typically achieving readability from 0.1 milligram to 0.1 gram, designed for quantitative analysis, formulation, and compliance documentation in regulated environments. The device serves primary industrial purposes in gravimetric analysis, batch consistency verification, and traceable measurement chain maintenance under ISO 17025 frameworks. Analytical balances command the deepest margin pools where pharmaceutical labs require sub-milligram resolution for API characterization. Cloud-connected technology segments are displacing mechanical and basic digital categories as laboratories in Germany and Japan mandate audit-trail automation for ALCOA+ data-integrity standards. Precision balances occupy the broadest volume tier across academic institutions where capital constraints favor mid-range specifications over metrology-grade investments.
FDA 21 CFR Part 11 and EMA Annex 11 data-integrity requirements are forcing replacement of legacy mechanical balances with automated audit-trail systems in United States and European pharmaceutical facilities. ISO 8655 and OIML R76 calibration standards shape product design and service revenue models, particularly in Japan where METI enforces mandatory periodic verification. China's NMPA and GB standards are tightening import requirements for foreign balance manufacturers seeking hospital-laboratory access. Stakeholders must monitor divergence between FDA electronic-signature rules and China's evolving medical-device classification system for laboratory equipment.
Market Dynamics
Cloud-connected calibration infrastructure is reorganizing procurement criteria across pharmaceutical and semiconductor quality-control labs, compressing replacement cycles for legacy mechanical balances that lack automated audit-trail capabilities. This structural shift favors vendors with captive sensor production and integrated software stacks over component assemblers.
Growth Catalysts
- FDA 21 CFR Part 11 mandates:United States pharmaceutical facilities must replace manual data-recording balances with automated audit-trail systems, accelerating hardware refresh cycles in API characterization labs.
- Semiconductor metrology expansion:Taiwan and South Korea foundries are procuring sub-milligram analytical balances for wafer-thickness verification under tightening process-node tolerances.
- ISO 17025 accreditation proliferation:Contract research organizations in Germany and Switzerland require traceable measurement chains, driving demand for balances with embedded calibration certificates.
Market Restraints
- Strain-gauge load cell supply concentration:Japanese and German sensor manufacturers control premium electromagnetic force restoration component supply, creating input bottlenecks for mid-tier assemblers.
- EMA Annex 11 compliance friction:European biopharma labs face extended validation timelines for cloud-connected balances, delaying purchase approvals by six to twelve months.
- Portable field balances:Battery-powered precision units with Bluetooth data transmission threaten fixed-platform balance demand in environmental monitoring and mobile testing applications.
Strategic Opportunities
- India's PLI scheme for medical devices:Domestic manufacturing incentives are creating localized assembly opportunities for foreign balance vendors seeking hospital-laboratory market access.
- Chromatography-balance integration:Converged data systems that auto-populate analytical results from weighing stations into LIMS platforms represent unmet demand in high-throughput screening facilities.
- Subscription calibration services:Remote monitoring and predictive maintenance contracts offer recurring revenue streams beyond hardware sales, particularly attractive to capital-constrained academic institutions.
Industry Challenges
- ALCOA+ data-integrity skill scarcity:Pharmaceutical labs struggle to hire technicians proficient in attributable, legible, contemporaneous, original, and accurate record-keeping standards for automated balance systems.
- Legacy LIMS integration complexity:Cloud-connected balances must interface with decades-old laboratory information management systems, requiring costly middleware development and extended deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Platform Electronic Laboratory Balance Market |
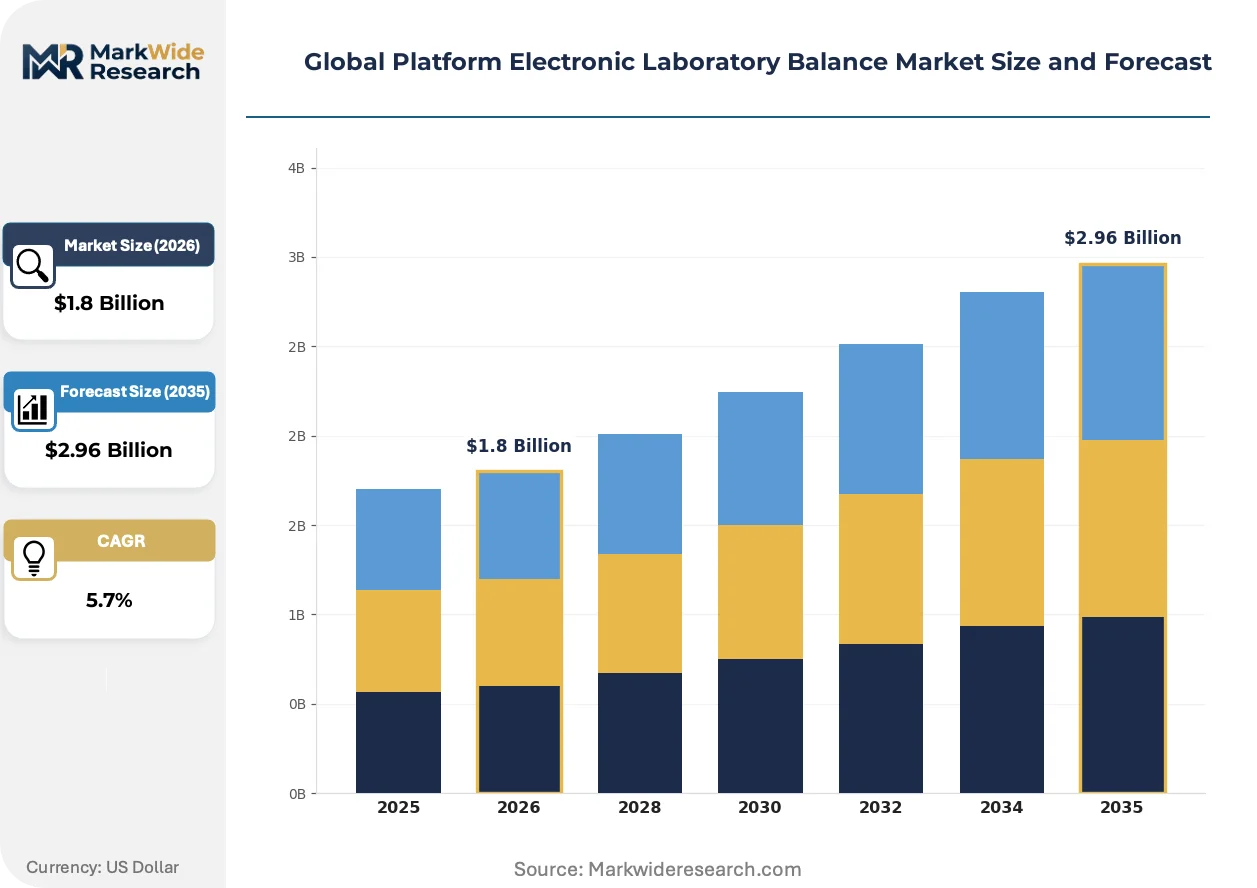
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analytical Balances, Precision Balances, Top-Loading Balances, Microbalances End User: Pharmaceutical Labs, Academic Institutions, Research Facilities, Quality Control Labs Capacity: Up to 1 kg, 1 kg to 5 kg, 5 kg to 10 kg, Above 10 kg Technology: Digital, Mechanical, Automated, Cloud-Connected |
| Companies Covered | METTLER TOLEDO, A&D Company Limited, Shimadzu Corporation, Sartorius AG, OHAUS Corporation, Adam Equipment, Fairbanks, Essae-Teraoka Pvt. Ltd, Contech Instruments Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Platform Electronic Laboratory Balance Market Strategic Shifts
Electromagnetic force restoration technology is advancing readability thresholds while software-defined measurement workflows are compressing the boundary between instrument and data platform. These developments are elevating service revenue relative to hardware margin in vendor economics.
Electromagnetic force restoration with automatic internal calibration is supplanting strain-gauge load cells in pharmaceutical quality-control environments. API characterization labs in Germany and the United States are adopting these systems to eliminate manual calibration drift errors. This technology is supplanting basic digital balances in regulated settings by embedding temperature compensation and real-time linearity correction that satisfies FDA data-integrity requirements without external reference weights.
REACH restrictions on mercury-containing components are forcing redesign of traditional electromagnetic balance mechanisms across European manufacturing. Vendors are accelerating development of inductive position sensors to replace mercury-based damping systems in high-precision models. Analytical balance categories destined for EMA-regulated laboratories face the steepest compliance redesign costs and shortest implementation deadlines.
Consolidated procurement through group purchasing organizations is compressing vendor-direct sales relationships in United States academic and hospital laboratory sectors. Large research universities and health systems are mandating centralized balance standardization to reduce calibration contract fragmentation. This pattern is most visible in California and Massachusetts where multi-site research consortia negotiate enterprise-wide instrument and service agreements.
Global Platform Electronic Laboratory Balance Market Segmentation
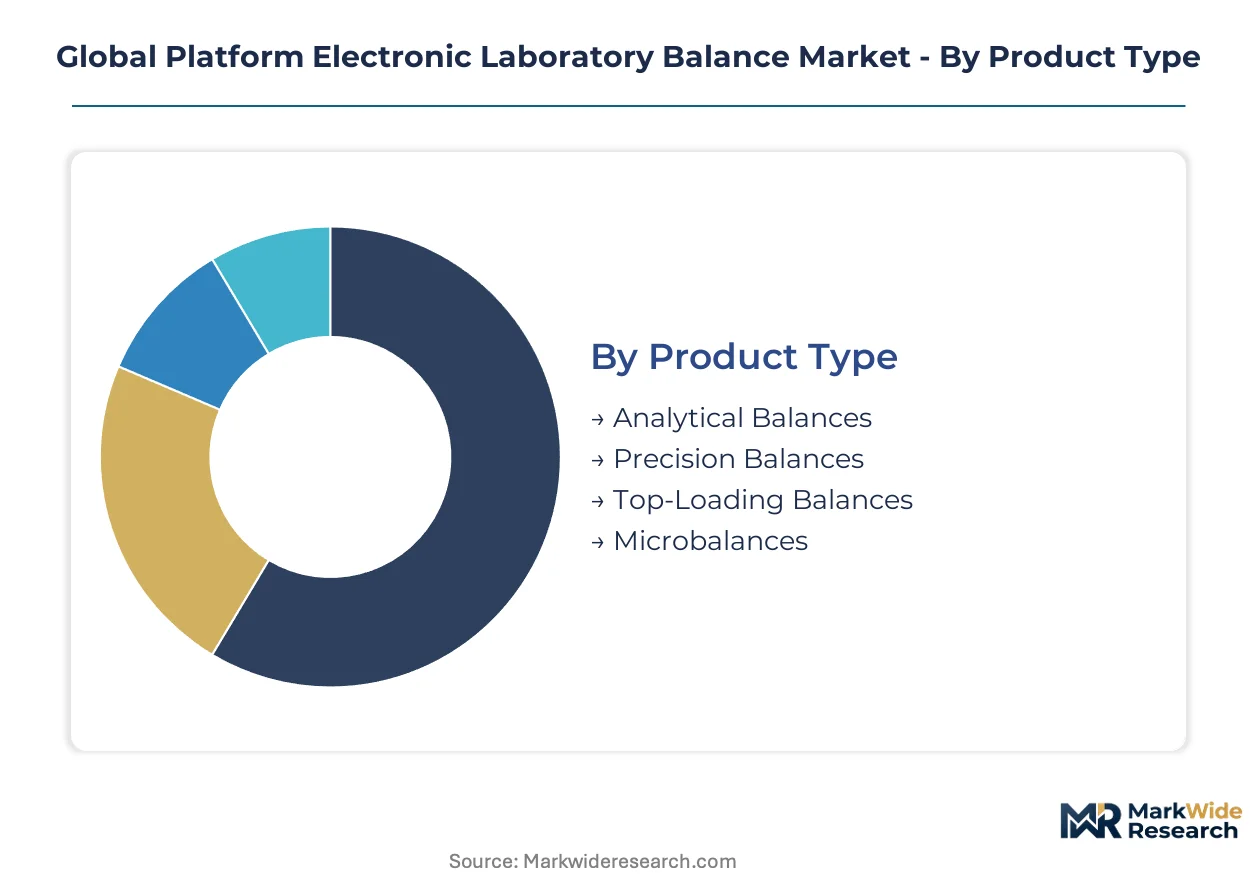
Segmentation in the platform electronic laboratory balance market reveals how procurement patterns diverge across precision requirements, regulatory environments, and capital constraints. Pharmaceutical quality-control labs in Germany and the United States drive premium-tier specifications, while academic institutions in India and Brazil prioritize cost efficiency over metrology-grade features.
Product Type:
Domestic production concentrates analytical and microbalance categories in Switzerland and Germany for European pharmaceutical demand, while precision and top-loading balances flow from Japanese and Chinese assembly lines to Asia-Pacific academic markets.
- Analytical Balances:Electromagnetic force restoration systems achieve 0.1 milligram readability with automatic internal calibration. German and United States pharmaceutical laboratories under FDA 21 CFR Part 11 mandates are replacing legacy units to eliminate manual data-recording errors.
- Precision Balances:Strain-gauge load cell platforms deliver 1 milligram to 0.1 gram resolution for routine quantitative work. Academic institutions across India and Southeast Asia favor these units where capital budgets constrain metrology-grade investments.
- Top-Loading Balances:Higher-capacity units serve industrial formulation and batch consistency verification in chemical manufacturing.
- Microbalances:Sub-microgram resolution instruments support semiconductor wafer metrology and nanomaterial characterization in Taiwan and South Korea foundries.
Analytical balances hold the largest share; momentum sits with cloud-connected precision units gaining share fastest in contract research organizations.
End User:
Cost tier stratification separates regulated pharmaceutical environments requiring audit-trail automation from budget-constrained academic settings accepting basic digital specifications.
- Pharmaceutical Labs:API characterization and quality-control workflows demand electromagnetic force restoration with embedded calibration certificates under ISO 17025 frameworks. United States and German facilities face the steepest replacement pressure from FDA and EMA data-integrity mandates.
- Academic Institutions:Teaching laboratories and basic research groups prioritize capital efficiency over precision extremes. Indian and Brazilian universities are expanding procurement through group purchasing organizations to reduce per-unit calibration costs.
- Research Facilities:Government and private R&D centers require flexible capacity ranges across multiple project types.
- Quality Control Labs:Industrial testing environments need durable platforms for high-throughput batch verification in food and chemical sectors.
Pharmaceutical labs dominate value capture; academic institutions represent the steepest expansion trajectory as research funding diversifies beyond traditional hubs.
Capacity:
Volume distribution follows application-specific gravimetric requirements, with sub-kilogram ranges anchoring pharmaceutical analysis and higher capacities serving industrial formulation.
- Up to 1 kg:Analytical and microbalance categories concentrate here for pharmaceutical API weighing and chromatography sample preparation. Japanese and German manufacturers control premium supply for this range.
- 1 kg to 5 kg:Precision balances in this band serve dual-purpose academic and industrial quality-control applications.
- 5 kg to 10 kg:Top-loading configurations support chemical formulation and materials testing where moderate precision suffices.
- Above 10 kg:Heavy-duty platforms address bulk material handling in environmental monitoring and industrial process control.
Sub-kilogram capacities command the deepest margins; above-10 kg segments are climbing fastest as industrial automation expands quality-control sampling.
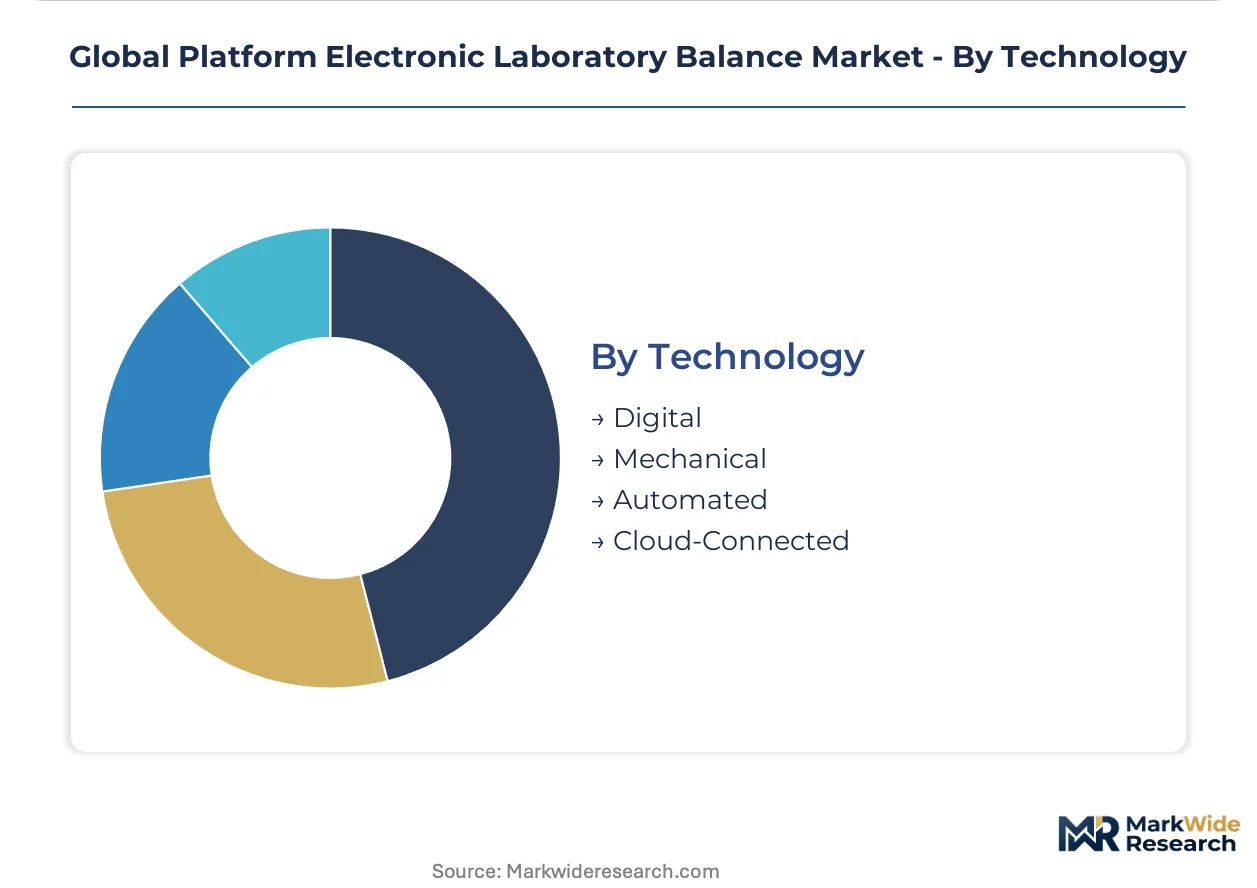
Technology:
Customer type bifurcation separates regulated pharmaceutical demand for cloud-connected audit trails from legacy mechanical holdouts in cost-sensitive emerging markets.
- Cloud-Connected:Integrated calibration monitoring and automated data logging satisfy ALCOA+ standards for pharmaceutical laboratories in Germany, the United States, and Japan. These systems compress replacement cycles by embedding predictive maintenance alerts.
- Digital:Basic electronic displays without connectivity serve academic and industrial applications where regulatory documentation requirements remain minimal.
- Automated:Robotic sample handling and LIMS integration target high-throughput screening facilities in contract research organizations.
- Mechanical:Legacy spring and lever systems persist in resource-constrained settings and educational demonstrations where electronic failure modes pose unacceptable risks.
Cloud-connected platforms command premium positioning; automated segments are expanding most quickly as chromatography-balance integration demand rises.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Swiss and German sensor manufacturers control electromagnetic force restoration component supply, creating geographic chokepoints for precision balance production. Pharmaceutical demand clusters in three regulatory jurisdictions with divergent compliance timelines.
United States
FDA 21 CFR Part 11 mandates are accelerating replacement cycles in API characterization labs across Massachusetts and North Carolina. The agency's data-integrity enforcement is eliminating manual data-recording balances from contract manufacturing organizations. Boston's biotech corridor is standardizing on cloud-connected audit-trail systems to preempt regulatory inspection findings.
Germany
EMA Annex 11 compliance requirements are reshaping procurement in Baden-Württemberg's pharmaceutical manufacturing belt. The country's national pharmaceutical regulator enforces ALCOA+ standards through unannounced laboratory inspections. Stuttgart and Heidelberg clusters are consolidating vendor relationships to reduce calibration contract fragmentation across multi-site operations.
Japan
METI-mandated periodic verification under OIML R76 standards sustains replacement demand in Osaka and Tokyo precision manufacturing zones. The ministry's metrology framework requires embedded calibration certificates for ISO 17025-accredited facilities. Chubu region semiconductor foundries are procuring sub-milligram analytical balances for wafer-thickness verification.
China
NMPA and GB standards are tightening import requirements for foreign balance manufacturers seeking hospital-laboratory access in Shanghai and Beijing. The regulator's evolving medical-device classification system creates compliance friction for cloud-connected systems. Yangtze River Delta contract research organizations are expanding procurement of traceable measurement chains.
India
PLI scheme incentives for medical devices are attracting localized assembly investment from foreign vendors targeting hospital-laboratory markets in Maharashtra and Karnataka. CDSCO import regulations favor domestic manufacturing for public procurement tenders. Hyderabad's pharmaceutical R&D cluster is expanding analytical balance procurement through group purchasing organizations.
Global Platform Electronic Laboratory Balance Market Competitive Environment
Concentration sits with Swiss and German manufacturers controlling captive sensor production and integrated software stacks. Three tiers structure competitive positioning: metrology-grade specialists with electromagnetic force restoration capabilities, mid-range precision assemblers sourcing Japanese load cells, and emerging Asian fabricators competing on capital efficiency. Strategic moves center on backward integration into load cell manufacturing and subscription calibration service bundling to capture recurring revenue.
Within the premium-tier electromagnetic force restoration segment, METTLER TOLEDO and Sartorius AG exemplify the Swiss-German manufacturing archetype with in-house sensor production. Shimadzu Corporation occupies a distinct position among Japanese precision instrument specialists competing through chromatography-balance integration. These three anchors illustrate how geographic manufacturing bases align with regulatory jurisdiction expertise—Swiss and German vendors dominating EMA-regulated European demand, Japanese manufacturers capturing METI-enforced domestic replacement cycles.
| Leading Market Players |
|---|
| METTLER TOLEDO |
| A&D Company Limited |
| Shimadzu Corporation |
| Sartorius AG |
| OHAUS Corporation |
| Adam Equipment |
| Fairbanks |
| Essae-Teraoka Pvt. Ltd |
| Contech Instruments Ltd |
| Others |
Value Chain & Pricing Dynamics
Electromagnetic force restoration mechanisms displacing strain-gauge load cells in pharmaceutical quality-control environments are redrawing manufacturing geography toward Swiss and German sensor specialists while compressing margins for mid-tier assemblers dependent on Japanese component imports. This substitution dynamic concentrates pricing power with vendors controlling captive production of metrology-grade load cells and integrated calibration software stacks.
Pricing Analysis
FDA 21 CFR Part 11 dictates the pricing tier structure across pharmaceutical procurement, separating cloud-connected audit-trail systems from basic digital platforms. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and embedded software capabilities rather than hardware resolution alone. Cost compression in precision balance segments is intensifying because Indian and Brazilian academic buyers prioritize capital efficiency over metrology-grade specifications. Academic institutions exhibit highest price sensitivity; API characterization labs in Germany and the United States demonstrate lowest sensitivity due to regulatory compliance mandates.
Supply Chain Analysis
Switzerland and Germany anchor electromagnetic force restoration sensor production for analytical and microbalance categories serving EMA-regulated European demand. Component supply draws from Japanese manufacturers for strain-gauge load cells and Chinese fabricators for precision-machined platforms and electronic assemblies. Single-source vulnerability concentrates in Swiss-German electromagnetic sensor supply for sub-milligram resolution instruments. Distribution runs through authorized distributor networks and direct enterprise contracts with multi-site pharmaceutical and semiconductor foundry customers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
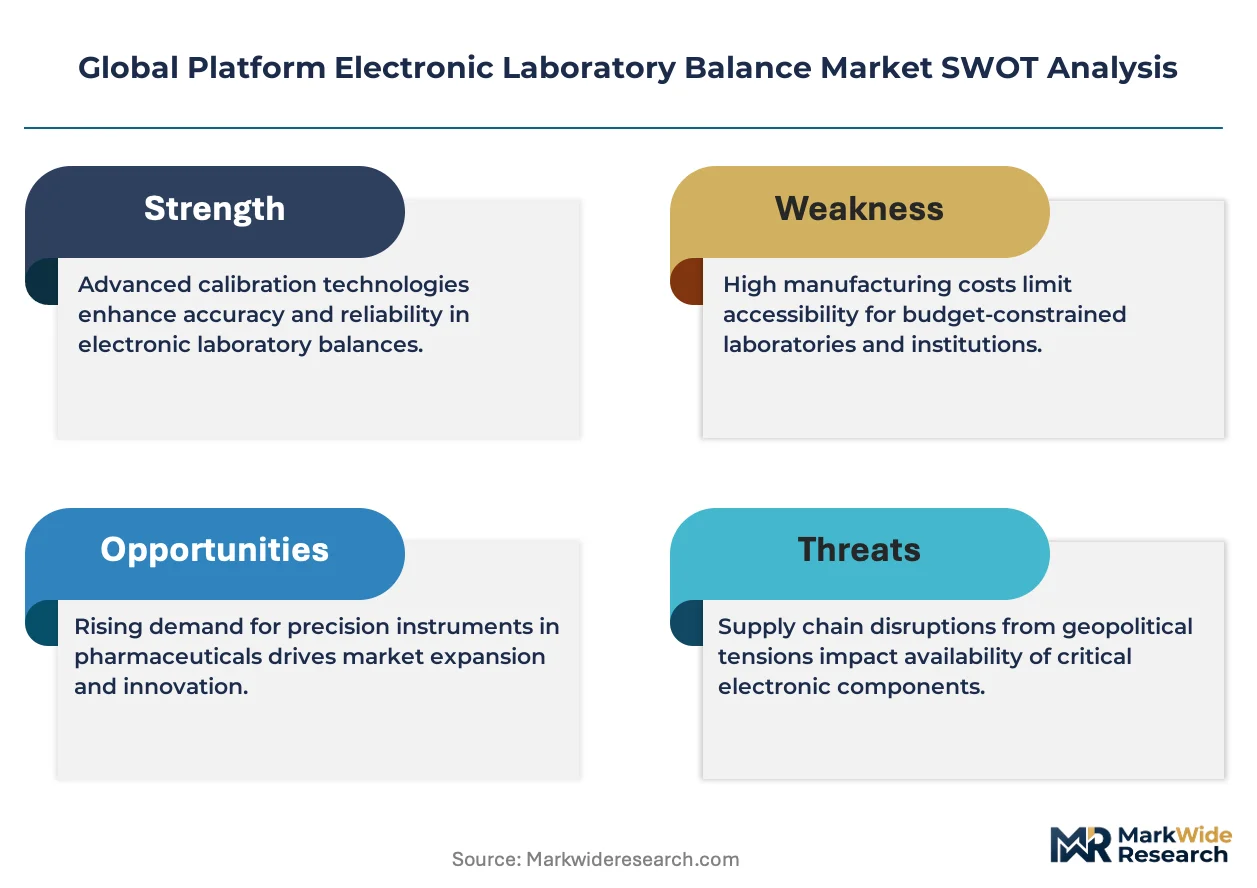
Incumbents face a substitution defense against portable field balances with Bluetooth data transmission threatening fixed-platform demand in environmental monitoring and mobile testing applications.
For Market Incumbents: Fortify backward integration into electromagnetic force restoration sensor manufacturing to escape Japanese and German component bottlenecks. Deepen software stack development for automated LIMS integration to preempt middleware competitors. Cloud-connected calibration service bundling represents the critical defensive lever against capital-efficient Asian assemblers.
For New Entrants and Emerging Players: ISO 17025 certification fast-track through partnership with German or Swiss accreditation bodies unlocks European pharmaceutical procurement channels. India's PLI scheme for medical devices offers the most penetrable geography for localized assembly targeting hospital-laboratory markets. Chromatography-balance integration for high-throughput screening facilities provides a differentiated go-to-market angle against established hardware vendors.
For Investors and Strategic Acquirers: The market sits at a compliance-driven replacement phase that favors vendors with integrated software-hardware stacks over component assemblers. Long-term viability centers on recurring calibration service revenue rather than transactional hardware margins. Acquisition target archetype: mid-tier precision balance manufacturers with established distributor relationships but lacking cloud connectivity capabilities. Signal to watch: EMA Annex 11 enforcement intensity accelerating European replacement timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Manufacturing | Captive electromagnetic force restoration production insulates margin pressure from Japanese component supply constraints. |
| Cloud-Connected Calibration Service Launch | Recurring revenue contracts with pharmaceutical labs satisfy FDA 21 CFR Part 11 audit-trail automation requirements. |
| Chromatography-Balance Integration Development | Auto-populated LIMS data streams capture unmet demand in contract research organization high-throughput screening facilities. |
| ISO 17025 Accreditation Investment | Embedded calibration certificates unlock German and Swiss pharmaceutical quality-control procurement channels. |
| India PLI Scheme Manufacturing Localization | Domestic assembly qualification bypasses CDSCO import friction for public hospital-laboratory tenders. |
Study Parameters
The analysis maps analytical balances, precision balances, microbalances, and top-loading configurations, each validated through laboratory procurement managers, pharmaceutical quality-control directors, academic research officers, and calibration service technicians. Primary interviews with these stakeholders combined with secondary validation from FDA 21 CFR Part 11 guidance documents, EMA Annex 11 inspection reports, ISO 17025 accreditation databases, and METI OIML R76 verification records. Bottom-up segment sizing and top-down market triangulation cross-validated volume and value estimates across the analysis window.
Consistency checks against external benchmarks validated forecast outputs against historical replacement cycle patterns in pharmaceutical and semiconductor quality-control environments. Segmentation dimensions modeled include product type, end-user category, capacity range, and technology connectivity level across the projection horizon. CAGRs derived from regression analysis of procurement volume trends, regulatory compliance timelines, and technology substitution rates. Industry-specific inputs encompassed ALCOA+ data-integrity mandate enforcement intensity and semiconductor process-node tolerance tightening in Taiwan and South Korea foundries.
Underlying assumptions cover sustained FDA and EMA data-integrity enforcement, stable electromagnetic sensor supply from Swiss-German manufacturing bases, and continued semiconductor metrology expansion, with deviation risk concentrated in EMA Annex 11 validation timeline extensions and REACH restriction implementation deadlines for mercury-free damping systems. Recalibration cycles align with material shifts in regulatory enforcement patterns and sensor technology substitution thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Ultrasonic Flaw Detector Market
Test and Measurement
Wafer Inspection Market
Test and Measurement
Flow Meter Calibration Market
Test and Measurement
Distortion Meter Market
Test and Measurement
Test and Measurement Equipment Market
Test and Measurement
Height Measurement Devices Market
Test and Measurement
Global Inspection Machines Market
Test and Measurement
Heat Deformation Tester Market
Test and Measurement
Voltage Tester Market
Test and Measurement
Global Non-Destructive Testing and Inspection Market
Test and Measurement
Global in Circuit Tester Market
Test and Measurement
Noise Vibration Harshness (NVH) Testing Market
Test and Measurement
Smart Contact Lens Optical and Telemetry Test Equipment Market
Test and Measurement
Fluorometers Market
Test and Measurement
LCR Meter Market
Test and Measurement
Structure Tester Market