
 Global Micrometer Market | 2026-2036
Global Micrometer Market Size, Share, and Industry Trends Forecast 2026-2036
Global Micrometer Market Outlook
Buyer concentration among tier-one automotive and aerospace OEMs is shifting toward consolidated metrology procurement frameworks that favor multi-year calibration contracts. Mitutoyo Corporation leverages its Japan-centric manufacturing scale to sustain pricing discipline across digital micrometer lines. Starrett anchors North American distribution through dedicated industrial distributor networks. Mahr GmbH differentiates via European-centric ISO 17025 accreditation density.
A micrometer is a precision length measurement instrument employing a calibrated screw mechanism to resolve dimensions typically from 0.01 mm down to 0.001 mm, with spindle travel constrained by hardened anvil and sleeve assemblies ground to sub-micron parallelism. Its primary industrial purpose is dimensional verification of machined components, ground shafts, and precision-bore assemblies against engineering tolerances. Digital micrometers command expanding share as shop-floor data logging demands rise, while analog variants retain cost-sensitive maintenance and education segments. Aerospace industry verticals concentrate margin pools due to AS9100 traceability requirements and NADCAP audit frequency. Outside micrometers dominate unit volume across general manufacturing, whereas inside micrometers capture premium positioning in hydraulic cylinder and bearing applications.
ISO 17025 governs calibration laboratory competence and directly shapes supplier qualification for defense and medical device OEMs. The EU AI Act and FDA's computer system validation guidance increasingly intersect with automated digital micrometer data collection systems. ASTM E2309 and JIS B 7502 establish thread and flatness standards that determine product interoperability across export markets. Stakeholders must monitor evolving cybersecurity requirements for networked measurement devices as factory digitization accelerates.
Market Dynamics
Consolidated metrology procurement frameworks among tier-one aerospace and automotive OEMs are compressing supplier margins while privileging multi-year calibration service contracts over discrete instrument sales.
Growth Catalysts
- EU Green Deal embodied carbon tracking:Traceable dimensional verification mandates across supplier tiers are mandating calibrated micrometer deployment for emissions-accounting documentation.
- Composite airframe tolerance tightening:Aerospace component manufacturers in Germany's Stuttgart-Erlangen precision engineering cluster are expanding metrology budgets to certify sub-10-micron tolerances on carbon fiber assemblies.
- Digital thread integration:Shop-floor data logging requirements from AS9100-certified manufacturers are pulling digital micrometer adoption ahead of analog alternatives.
Market Restraints
- Hardened anvil material cost volatility:Tungsten carbide and ceramic spindle tip feedstock prices fluctuate with rare earth export controls, squeezing margin on precision-ground assemblies.
- Japan-centric manufacturing concentration:Digital micrometer spindle motor and encoder supply concentrates in a single geography, exposing procurement timelines to freight and customs friction.
- Optical comparator substitution:Non-contact vision systems are capturing dimensional verification workflows above 25mm measurement range, compressing outside micrometer addressable applications.
Strategic Opportunities
- India PLI scheme precision manufacturing:Domestic aerospace and defense component fabrication incentives are seeding greenfield metrology infrastructure demand in Bangalore and Hyderabad clusters.
- EU AI Act automated measurement validation:Computer system validation requirements for networked digital micrometers create accredited software integration service revenue pools.
- Maintenance technician channel bypass:Direct-to-factory calibration subscription models are disintermediating industrial distributors in North American job shop segments.
Industry Challenges
- ISO 17025 assessor capacity shortage:Accreditation backlog for calibration laboratories stretches 14-18 months in high-demand aerospace corridors, delaying supplier qualification.
- NADCAP special process audit frequency:Heat-treat and chemical processing subcontractors face recurring dimensional verification re-qualification cycles that strain metrology asset utilization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Micrometer Market |
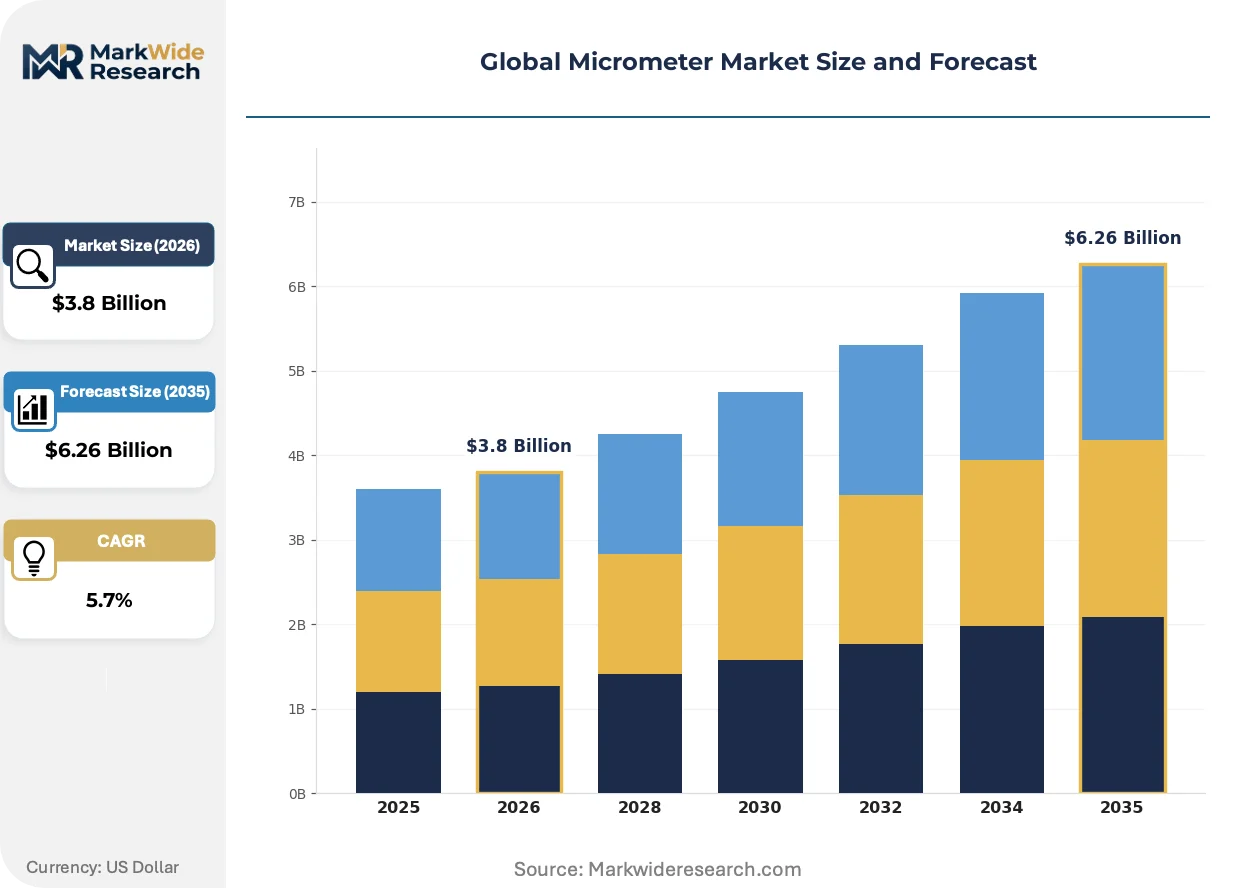
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog Micrometer, Digital Micrometer, Outside Micrometer, Inside Micrometer Industry Vertical: Aerospace, Automotive, Manufacturing, Electronics Measurement Range: 0-25 mm, 25-50 mm, 50-75 mm, 75-100 mm Calibration Standard: ISO, ASTM, DIN, JIS |
| Companies Covered | Mitutoyo Corporation, Starrett, Hexagon, TESA Technology, Snap-on, Mahr GmbH, MICROTECH, Fowler High Precision, Bowers Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Micrometer Market Strategic Shifts
Wireless data transmission and edge computing are embedding intelligence directly into handheld measurement instruments, collapsing the latency between dimensional capture and quality system documentation.
Bluetooth-enabled digital micrometers with SPC software integration are overtaking standalone USB-cable models in high-volume automotive stamping plants. Tier-one suppliers in Germany and the US Midwest are mandating real-time gauge R&R data feeds into MES platforms. This connectivity is compressing the market for analog and basic digital variants without native networking capability.
REACH restrictions on hexavalent chromium plating are forcing spindle and anvil surface treatment migrations to trivalent chrome and PVD coatings. European micrometer manufacturers face reformulation costs and re-qualification testing for existing product lines. Medical device OEMs in Switzerland and Germany are accelerating supplier audits to verify coating chemistry compliance ahead of enforcement deadlines.
Buyer concentration among consolidated aerospace primes is unbundling calibration services from instrument purchase. Long-term service agreements with guaranteed turnaround times are displacing transactional recalibration orders. This pattern is most visible in France and the UK, where Safran and Rolls-Royce procurement teams have standardized on framework contracts covering multi-site instrument fleets.
Global Micrometer Market Segmentation
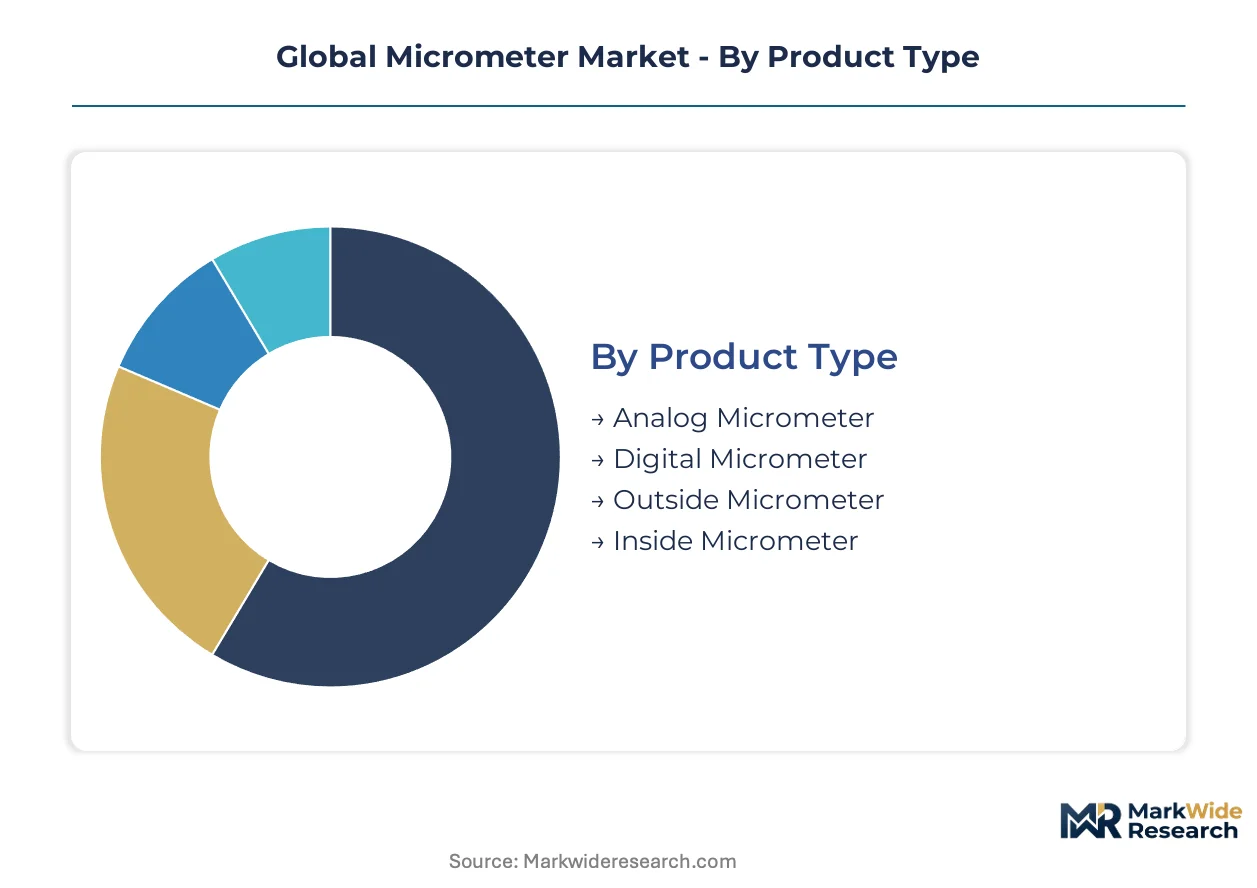
Micrometer procurement patterns diverge sharply across product architectures, end-use tolerances, and traceability regimes. Segment-specific supply chain configurations determine margin capture and qualification barriers for instrument vendors.
Product Type:
Spindle motor and encoder manufacturing concentrates in Japan, shaping availability and lead times across all product architectures.
- Digital Micrometer:Integrated rotary encoders and LCD displays enable direct data logging into SPC systems. AS9100-certified aerospace manufacturers in Germany's Stuttgart-Erlangen cluster mandate these for real-time gauge R&R documentation.
- Outside Micrometer:The classic C-frame design with hardened anvil and spindle dominates general manufacturing volume. Machine shops across the US Midwest deploy these for shaft diameter verification on turned components.
- Analog Micrometer:Vernier scale variants persist in cost-sensitive maintenance operations and vocational training programs. Technical colleges in India retain these for metrology curriculum standardization.
- Inside Micrometer:Telescoping and tubular designs access internal diameters in hydraulic cylinders and bearing housings. Premium positioning reflects complex calibration requirements for bore measurement accuracy.
Outside micrometers absorb the bulk of installed capacity; digital micrometers are expanding most quickly.
Industry Vertical:
End-use tolerance specifications and audit frequency create tiered pricing power across customer segments.
- Aerospace:NADCAP special process audits and AS9100 traceability mandates drive multi-year calibration contracts. Composite airframe manufacturers face sub-10-micron tolerance verification requirements on carbon fiber assemblies.
- Automotive:Stamping plants mandate Bluetooth-enabled SPC integration for real-time dimensional feedback. Tier-one suppliers in France and the UK have consolidated procurement under framework contracts.
- Manufacturing:General job shops span maintenance, toolroom, and quality control applications. Direct-to-factory calibration subscriptions are disintermediating industrial distributors in North America.
- Electronics:Miniaturized component measurement demands specialized anvil configurations and reduced measuring force. Swiss and German medical device OEMs accelerate coating chemistry audits ahead of REACH enforcement.
Aerospace commands premium margin pools; automotive is gaining share fastest through consolidated fleet procurement.
Measurement Range:
Frame size and thermal stability requirements scale non-linearly with measurement span, concentrating production expertise.
- 0-25 mm:The most common frame size handles precision shaft and pin measurements. Optical comparator substitution above 25mm compresses addressable applications for larger instruments.
- 25-50 mm:Mid-range applications include bearing outer races and medium-diameter bores. Machine tool spindle verification drives demand in Germany's precision engineering corridor.
- 50-75 mm:Larger frame constructions require enhanced thermal compensation mechanisms. Hydraulic cylinder manufacturers specify these for rod diameter certification.
- 75-100 mm:Extended range instruments face specialized calibration challenges and lower unit volumes. Custom anvil configurations serve heavy equipment and energy sector applications.
The 0-25 mm range holds the largest installed base; 25-50 mm is climbing the fastest through automotive bearing demand.
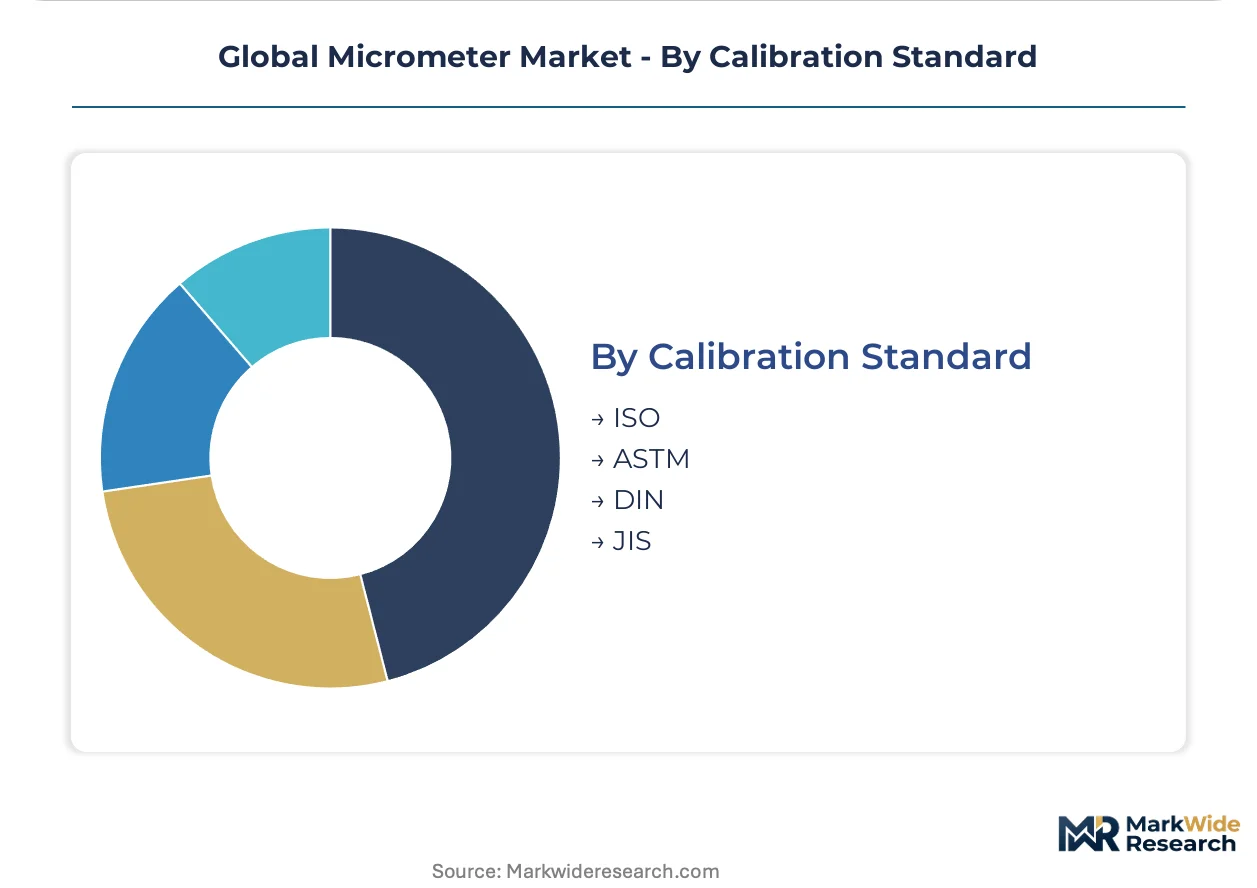
Calibration Standard:
Accreditation density and mutual recognition agreements determine laboratory qualification barriers across export markets.
- ISO:ISO 17025 governs calibration laboratory competence and shapes supplier qualification for defense and medical device OEMs. Accreditation backlog stretches 14-18 months in high-demand aerospace corridors.
- ASTM:ASTM E2309 establishes thread and flatness standards for North American interoperability. US-based primes require ASTM-traceable certificates for supplier onboarding.
- DIN:German standardization underpins European-centric metrology infrastructure. Mahr GmbH leverages DIN accreditation density for regional differentiation.
- JIS:Japanese Industrial Standards anchor domestic manufacturing quality systems. Mitutoyo Corporation sustains pricing discipline through JIS-compliant Japan-centric production scale.
ISO absorbs the bulk of cross-border accreditation activity; ASTM is expanding most quickly through US defense supply chain localization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for precision micrometers concentrates in aerospace and automotive manufacturing corridors where sub-10-micron tolerances drive metrology investment. Germany's Stuttgart-Erlangen cluster anchors European procurement, while Japan-centric spindle motor supply shapes Asia-Pacific availability.
Germany
Composite airframe manufacturers in Stuttgart and Erlangen are expanding calibration budgets to certify carbon fiber assemblies. The EU Green Deal's embodied carbon tracking mandates traceable dimensional verification across supplier tiers. Mahr GmbH leverages ISO 17025 accreditation density to capture multi-year service contracts from Safran and Rolls-Royce procurement teams.
United States
Tier-one automotive stamping plants in the Midwest mandate Bluetooth-enabled SPC integration for real-time dimensional feedback. ASTM E2309 thread and flatness standards govern supplier onboarding for defense primes. Starrett anchors North American distribution through dedicated industrial distributor networks serving job shops across Michigan and Ohio.
Japan
Digital micrometer spindle motor and encoder manufacturing concentrates domestically, exposing procurement timelines to freight friction. METI oversees JIS B 7502 compliance that underpins export quality systems. Mitutoyo Corporation sustains pricing discipline through captive production scale and Japan-centric supply chain control.
India
Domestic aerospace and defense component fabrication is accelerating under the PLI scheme, seeding greenfield metrology infrastructure. BIS standards alignment pressures calibration laboratory capacity in Bangalore and Hyderabad clusters. Technical colleges retain analog micrometer deployments for vocational metrology curriculum standardization.
France
Safran procurement teams have standardized on framework contracts covering multi-site instrument fleets with guaranteed calibration turnaround. The EU AI Act's computer system validation requirements intersect with automated digital micrometer data collection. Paris-region aerospace subcontractors face ISO 17025 assessor capacity shortages stretching 14-18 months.
Global Micrometer Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue wireless connectivity and edge computing integration. The vendor base separates into three archetypes: Japan-centric scale manufacturers, European accreditation-dense service integrators, and North American distribution-anchored specialists. Competitive positioning hardens around multi-year calibration contract capture and direct-to-factory subscription models that disintermediate industrial distributors.
Among Japan-centric manufacturers, Mitutoyo Corporation exemplifies scale-driven pricing discipline through domestic spindle motor and encoder production. Starrett anchors North American positioning through dedicated industrial distributor networks. Mahr GmbH occupies the European service-integration tier, leveraging ISO 17025 accreditation density for regional differentiation. Hexagon and TESA Technology represent metrology conglomerates with broader dimensional measurement portfolios that encompass micrometer lines within integrated quality systems.
| Leading Market Players |
|---|
| Mitutoyo Corporation |
| Starrett |
| Hexagon |
| TESA Technology |
| Snap-on |
| Mahr GmbH |
| MICROTECH |
| Fowler High Precision |
| Bowers Group |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal embodied carbon tracking mandates gate qualified supply and premium-tier pricing access, as traceable dimensional verification requirements disqualify non-accredited vendors from aerospace and automotive procurement frameworks while commanding calibration-inclusive contract premiums.
Pricing Analysis
Volume concentrates in standard outside micrometers while margin pools concentrate in digital variants with SPC integration. Three-tier pricing structure across premium, standard, and economy levels separates AS9100-certified aerospace instruments from general manufacturing analog units and vocational training verniers. Price differentiation hinges on ISO 17025 accreditation density and Bluetooth-enabled data logging capability. Pricing pressure stems from optical comparator substitution above 25mm measurement range, squeezing mid-range outside micrometer margins. Automotive tier-one suppliers exhibit lowest price sensitivity due to consolidated framework contracts; Indian technical colleges and North American job shops show highest sensitivity.
Supply Chain Analysis
ISO 17025 accreditation gating restricts qualified spindle and anvil suppliers to Japan, Germany, and Switzerland for aerospace-grade instruments. Tungsten carbide feedstock draws from Chinese rare earth processing and Japanese powder metallurgy, while ceramic spindle tips source from German and Japanese technical ceramics specialists. Single-source vulnerability concentrates in Japan-centric spindle motor and encoder manufacturing, exposing lead times to freight friction. Distribution runs through dedicated industrial distributor networks in North America, direct factory calibration subscriptions in European aerospace corridors, and technical college procurement channels in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race, with spindle motor and encoder manufacturing emerging as the critical upstream lever that determines pricing discipline and supply security.
For Market Incumbents: Extend calibration service contract coverage to capture multi-year framework agreements from Safran and Rolls-Royce procurement teams before ISO 17025 assessor capacity shortages ease. Deepen captive production of spindle motors and rotary encoders to offset Japan-centric supply concentration risk. Defend against optical comparator substitution by embedding edge computing and wireless data transmission into handheld instrument lines. For New Entrants and Emerging Players: Capture greenfield metrology infrastructure demand seeded by India's PLI scheme in Bangalore and Hyderabad aerospace clusters. Exploit the 14-18 month ISO 17025 accreditation backlog in European aerospace corridors by offering expedited calibration partnerships with existing accredited laboratories. Target direct-to-factory subscription models to disintermediate industrial distributors in North American job shop segments. For Investors and Strategic Acquirers: EU AI Act computer system validation enforcement is the leading indicator that accredited software integration services will command premium multiples. Long-term viability favors calibration laboratory networks with dense ISO 17025 accreditation and embedded SPC software capabilities. Watch for NADCAP special process audit frequency increases as the signal for accelerated metrology asset utilization and recurring service revenue expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Spindle Motors | Mitutoyo's Japan-centric production scale anchors pricing discipline across digital micrometer lines. |
| Calibration Laboratory Accreditation Expansion | Mahr GmbH leverages ISO 17025 density to capture multi-year service contracts from European aerospace primes. |
| Bluetooth-Enabled SPC Integration | Tier-one automotive suppliers in Germany and the US Midwest mandate real-time gauge R&R data feeds. |
| Direct-to-Factory Subscription Launch | Calibration subscriptions disintermediate industrial distributors in North American job shop segments. |
| REACH-Compliant Coating Migration | Swiss and German medical device OEMs accelerate supplier audits ahead of hexavalent chromium restrictions. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, triangulated with primary interviews across metrology equipment manufacturers, calibration laboratory operators, aerospace quality engineers, automotive procurement leads, and technical college curriculum directors. FDA computer system validation guidance, EU AI Act implementation documents, and METI JIS compliance filings supplemented customs records and ISO 17025 accreditation databases. Bottom-up instrument shipment analysis and top-down metrology budget surveys were cross-validated.
Granularity-level modeling disaggregated volume and value across product type, industry vertical, measurement range, and calibration standard dimensions throughout the forecast period. CAGRs were derived from segment-specific demand elasticity modeling calibrated to composite airframe tolerance tightening and EU Green Deal verification mandates. Aerospace NADCAP audit frequency and automotive stamping plant SPC integration timelines served as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to rare earth export control volatility and optical comparator substitution rates. Forecasts reflect documented assumptions regarding accreditation backlog resolution and REACH coating enforcement timelines. A model refresh is warranted upon material change in EU AI Act automated measurement validation implementation schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Metrology and Inspection Equipment Market
Test and Measurement
Automatic Impact Testing Machine Market
Test and Measurement
Four-Quadrant Battery Simulator Market
Test and Measurement
Resonant Testing Machines Market
Test and Measurement
Receptacle Tester Market
Test and Measurement
Moisture Analyzer Market
Test and Measurement
Melt Flow Tester Market
Test and Measurement
Gauss Meter Market
Test and Measurement
Photometer and Calorimeter Market
Test and Measurement
Global Non-Destructive Testing and Inspection Market
Test and Measurement
PXI Source Measure Unit Market
Test and Measurement
Hearing Aid and True Wireless Earbud Acoustic Performance Test Systems Market
Test and Measurement
Additively Manufactured Lattice Structure Mechanical Test Systems Market
Test and Measurement
Burst Strength Tester Market
Test and Measurement
Crock Meter Market
Test and Measurement
Flying Probe Testing for PCB Assembly Market