
 Anechoic Chamber Market | 2026-2036
Anechoic Chamber Market Size, Share, and Industry Trends Forecast 2026-2036
Anechoic Chamber Market Intelligence
Automotive component testing is hardening as the dominant demand vertical, displacing traditional consumer electronics qualification volumes. TDK Corporation leverages its absorber foam technology leadership to anchor supply relationships with Asian EV platforms. ETS-Lindgren sustains geographic dominance across North American certification infrastructure. Eckel Industries specializes in custom architectural acoustic solutions for aerospace manufacturers.
An anechoic chamber is an enclosed space lined with radiation-absorbent material that suppresses electromagnetic wave reflections or sound reverberations, typically achieving reflectivity levels below -40 dB across target frequency bands. These structures enable precise measurement of antenna radiation patterns, acoustic signatures, and electromagnetic emissions without environmental interference. Semi-anechoic chambers occupy the largest installed base due to their versatility for automotive and military EMC compliance workflows. Fully anechoic chambers represent the fastest-growing product category, driven by millimeter-wave 5G antenna characterization and satellite payload validation where complete reflection suppression is mandatory.
The FCC in the United States and ETSI in Europe enforce divergent EMC emission limits that compel chamber operators to maintain dual-standard test capability, inflating capital intensity for independent laboratories. China's MIIT mandates domestic 5G equipment certification through GB-standard test protocols, redirecting chamber procurement toward locally qualified installation partners. Stakeholders must monitor how evolving O-RAN specifications and satellite constellation deployment timelines reshape absorber performance requirements and chamber footprint demands.
Market Dynamics
Automotive OEM validation programs are compressing test cycles for EV antenna systems, forcing chamber operators to expand throughput capacity while maintaining dual-standard EMC compliance for divergent FCC and ETSI emission limits.
Growth Catalysts
- 5G Millimeter-Wave Deployment:China's MIIT mandates domestic equipment certification through GB-standard protocols, redirecting procurement toward qualified local installation partners.
- EV Platform Validation Surge:Antenna characterization for electric vehicle connectivity modules now consumes majority capacity at Asian test facilities.
- FCC EMC Mandate Tightening:United States certification throughput requirements intensify as emission limits narrow for automotive electronics.
Market Restraints
- Absorber Material Concentration:Pyramidal foam supply chains cluster among Japanese and German specialty chemical producers, exposing procurement to regional logistics disruptions.
- Capital Intensity Barrier:Fully anechoic chambers for satellite payload validation require specialized ferrite tile installations exceeding standard semi-anechoic configurations.
- Dual-Standard Compliance Burden:Independent laboratories must maintain parallel FCC Part 15 and ETSI EN 55032 test capability, inflating equipment depreciation schedules.
Strategic Opportunities
- Satellite Constellation Expansion:Low-earth orbit payload manufacturers in Germany and the United States seek dedicated compact chambers for rapid iteration cycles.
- O-RAN Specification Evolution:Open radio access network interoperability testing creates demand for multi-antenna measurement configurations.
- India Telecom Infrastructure:TRAI spectrum auctions for 5G mid-band drive certification laboratory buildout in Bangalore and Hyderabad clusters.
Industry Challenges
- Electromagnetic Simulation Talent Scarcity:Chamber design engineers proficient in CST Studio and HFSS modeling command premium compensation, constraining facility expansion timelines.
- Legacy Facility Retrofit Complexity:Existing semi-anechoic installations require structural reinforcement to accommodate millimeter-wave ferrite absorber loads without foundation reconstruction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anechoic Chamber Market |
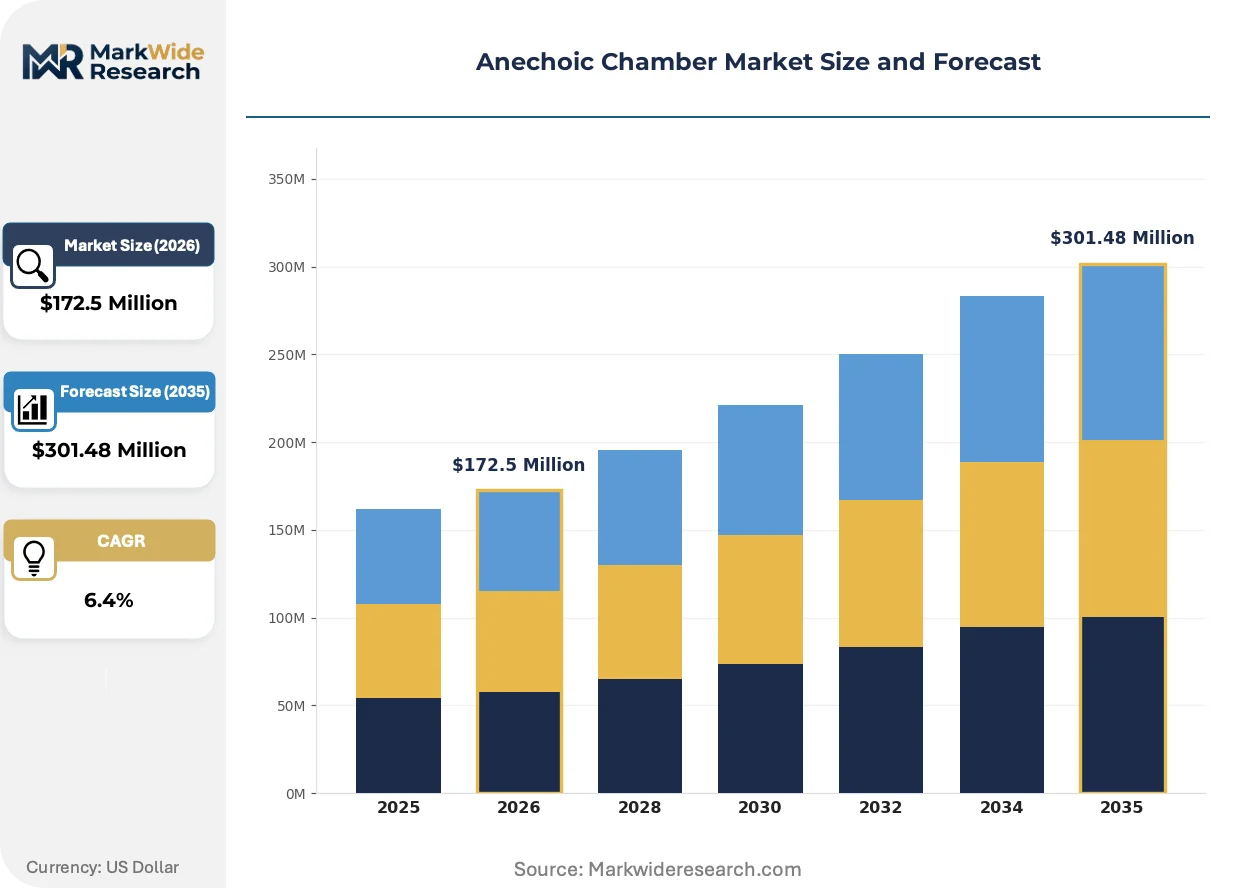
| Market Size in 2026 | $172.5 Million |
| Market Size in 2035 | $301.48 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Semi-Anechoic Chambers, Fully Anechoic Chambers, Reverberation Chambers, Hybrid Anechoic Chambers Technology: Absorber Foam, Electromagnetic Shielding, Soundproof Materials, Vibration Isolation, Acoustic Panels Application: Electromagnetic Compatibility Testing, Acoustic Measurement, Antenna Testing, Automotive Component Testing End User: Telecommunications Companies, Aerospace Manufacturers, Consumer Electronics Firms, Research Laboratories |
| Companies Covered | ETS-Lindgren, TDK Corporation, Eckel Industries, MVG, Albatross Projects GmbH, ESCO Technologies, Brüel & Kjær, Frankonia Group, Comtest Engineering, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anechoic Chamber Market Strategic Shifts & Innovations
Metamaterial absorber surfaces and software-defined measurement architectures are compressing chamber footprints while expanding testable frequency ranges, fundamentally altering facility economics and geographic deployment patterns.
Frequency-selective surface metamaterials are rewriting absorber performance benchmarks by achieving broadband suppression in physically thinner layers than conventional pyramidal foam. Satellite manufacturers in the United States and Germany are specifying these surfaces for compact payload validation cells. The technology is rewriting footprint requirements for urban test facilities where real estate constraints previously excluded full-chamber installations.
ETSI's updated EMC emission standards for automotive radar systems in Europe are compelling chamber operators to extend quiet-zone validation above 79 GHz. Test laboratories in Stuttgart and Munich are retrofitting existing semi-anechoic configurations with specialized millimeter-wave absorber arrays. German OEM validation programs now require documented reflection coefficients below -50 dB across 76-81 GHz bands, forcing capital allocation toward absorber replacement cycles.
Automotive procurement teams are consolidating supplier relationships around turnkey chamber-plus-service contracts rather than discrete equipment purchases. Tier-1 antenna module vendors now demand bundled installation, calibration, and ongoing maintenance from single providers. This consolidation pattern is most visible in China's Yangtze River Delta, where MIIT-certified facilities compete on total cost-of-ownership rather than equipment pricing alone.
Anechoic Chamber Market Segmentation
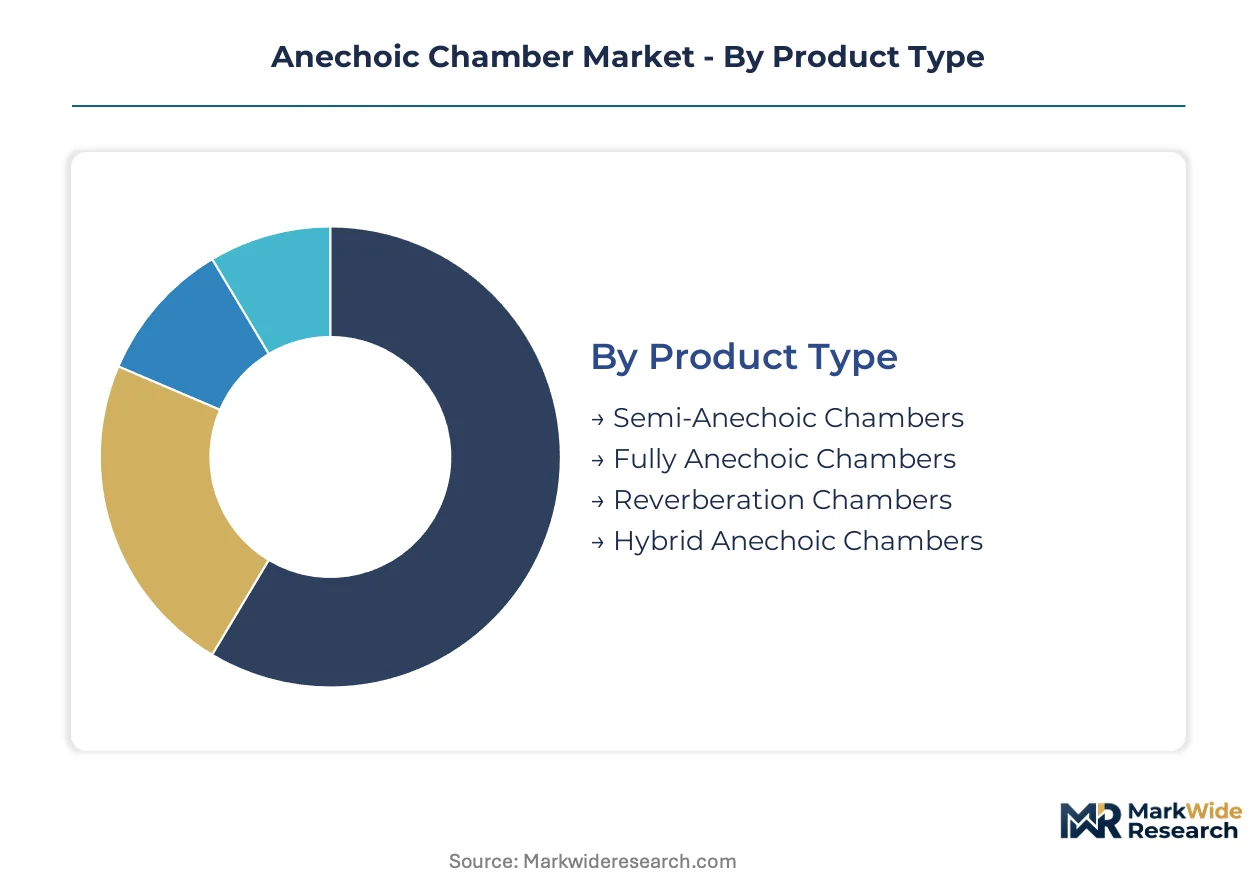
Segmentation in the anechoic chamber market reflects divergent capital deployment strategies across validation workflows. Product architecture determines whether facilities operate as standalone certification centers or embed within OEM manufacturing footprints. Technology choices and application focus further stratify procurement patterns between compliance-driven volume buyers and precision-focused satellite or automotive specialists.
Product Type:
Semi-anechoic chambers function as integrated test cells within broader EMC validation workflows, while fully anechoic configurations demand standalone architectural footprints with complete electromagnetic isolation.
- Semi-Anechoic Chambers:These retain a conductive ground plane with absorber-lined walls and ceiling, enabling automotive and military EMC compliance testing where radiated emission measurements reference ground-bounce effects. Installations cluster at independent laboratories serving United States FCC Part 15 and ETSI EN 55032 dual-standard workflows. Volume placements concentrate in legacy facilities retrofitting for 5G mid-band validation.
- Fully Anechoic Chambers:Six-sided absorber coverage eliminates all internal reflections, achieving the -50 dB performance thresholds mandatory for millimeter-wave antenna characterization and satellite payload validation. Germany's aerospace corridor and China's EV platform test centers drive procurement. The faster expansion belongs to compact configurations for low-earth orbit satellite iteration cycles.
- Reverberation Chambers:Mode-stirred aluminum cavities generate statistically uniform electromagnetic fields for high-power immunity testing and mass-production sampling.
- Hybrid Anechoic Chambers:Modular architectures combine semi-anechoic and reverberation modes within single enclosures, serving multi-protocol telecommunications certification houses.
Volume placements concentrate in semi-anechoic configurations; the faster expansion belongs to fully anechoic chambers.
Technology:
Absorber material selection governs frequency range coverage and installation logistics, with foam-based systems embedding directly into chamber walls while ferrite tile arrays require dedicated structural foundations.
- Absorber Foam:Pyramidal polyurethane and polystyrene formulations dominate sub-6 GHz applications, with Japanese and German specialty chemical producers controlling supply. TDK Corporation anchors relationships with Asian EV platforms through customized foam geometries. Demand concentrates in high-volume automotive EMC facilities where rapid absorber replacement cycles sustain recurring revenue streams.
- Electromagnetic Shielding:Copper and galvanized steel panel systems block external interference, with panel joint quality determining isolation performance above 100 dB. Installations concentrate at satellite payload validation centers requiring hermetic electromagnetic seals.
- Soundproof Materials:Mineral wool and mass-loaded vinyl layers address acoustic anechoic requirements for aerospace signature measurement.
- Vibration Isolation:Pneumatic and spring-damper foundations decouple chambers from building structural noise, critical for precision antenna pattern measurement.
- Acoustic Panels:Perforated metal-faced absorbers tune broadband acoustic suppression for jet engine and rotorcraft testing applications.
Procurement volumes cluster around absorber foam and electromagnetic shielding as paired purchases; acoustic-focused technologies gain share fastest in aerospace retrofit programs.
Application:
Application segmentation tracks the migration from generic electronics qualification toward automotive and telecommunications-specific validation protocols with divergent throughput and precision requirements.
- Electromagnetic Compatibility Testing:Regulatory-mandated emission and immunity verification consumes the majority of installed chamber hours across FCC, ETSI, and MIIT certification pathways. United States test laboratories face throughput compression as automotive electronics emission limits tighten. Volume concentrates in independent laboratories serving multi-industry client portfolios.
- Antenna Testing:5G millimeter-wave and satellite phased-array characterization demands fully anechoic quiet zones with positioner systems for three-dimensional radiation pattern mapping. China's MIIT-mandated domestic equipment certification redirects procurement toward GB-standard qualified installation partners. The steepest expansion trajectory sits here.
- Automotive Component Testing:EV connectivity module and radar system validation now dominates Asian facility capacity allocation.
- Acoustic Measurement:Jet engine noise signature and electric vehicle NVH testing sustains demand in aerospace and automotive R&D centers.
EMC testing retains the largest installed base; antenna testing climbs fastest on 5G and satellite constellation deployment timelines.
End User:
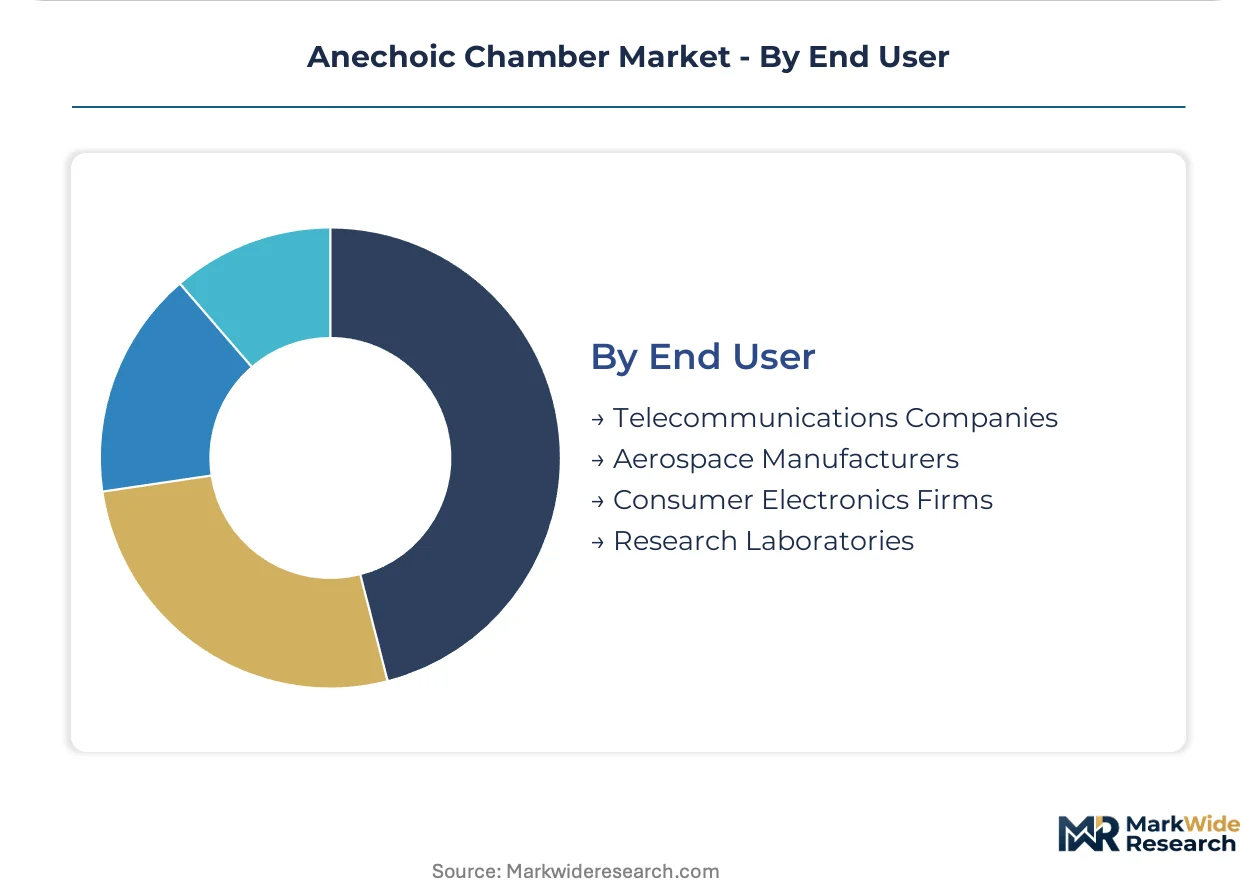
End user segmentation distinguishes between capital-intensive captive facilities and service-oriented independent laboratories with divergent procurement rhythms and technical specifications.
- Telecommunications Companies:5G equipment vendors and network operators maintain captive chambers for pre-certification validation and base station antenna optimization. China's Huawei and ZTE anchor substantial installed capacity in Shenzhen and Shanghai corridors. Procurement emphasizes turnkey installation with ongoing calibration service contracts.
- Aerospace Manufacturers:Satellite payload producers in Germany and the United States specify compact chambers for rapid design iteration, driving demand for metamaterial absorber surfaces that compress urban facility footprints. Boeing and Airbus validation networks sustain premium pricing for custom architectural solutions.
- Consumer Electronics Firms:Smartphone and IoT device makers increasingly outsource EMC validation to independent laboratories rather than maintaining captive capacity.
- Research Laboratories:University and government facilities support fundamental electromagnetic and acoustic research with specialized configurations.
Telecommunications companies deploy the most chamber units; aerospace manufacturers expand capacity fastest on satellite constellation buildout.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany manufactures the majority of precision absorber materials and ferrite substrates, while China and the United States consume the greatest installed chamber capacity for 5G and automotive validation programs.
United States
FCC EMC certification mandates for automotive electronics narrow emission limits and compress test-lab throughput requirements. The FCC Part 15 framework governs radiated emission standards for connected vehicle components. Greater Detroit and Austin tech corridors host the densest concentrations of EV antenna validation facilities.
Germany
ETSI automotive radar standards above 79 GHz drive chamber retrofit cycles for OEM validation programs. The KBA enforces type-approval protocols that synchronize with ETSI emission benchmarks. Stuttgart and Munich clusters specialize in millimeter-wave quiet-zone installations for premium automotive suppliers.
China
MIIT-mandated GB-standard 5G equipment certification redirects procurement toward domestic installation partners. The MIIT domestic certification pathway requires qualified local partners for chamber deployment. Yangtze River Delta facilities in Shanghai and Suzhou dominate EV platform antenna testing capacity.
Japan
METI industrial standards support specialty chemical production of pyramidal absorber foams for sub-6 GHz applications. METI technology roadmaps prioritize electromagnetic measurement infrastructure for automotive export compliance. Osaka-Kobe manufacturing belt concentrates foam formulation expertise for Asian EV supply chains.
India
TRAI 5G mid-band spectrum auctions accelerate certification laboratory buildout in southern technology corridors. TRAI spectrum allocation frameworks mandate domestic testing infrastructure for equipment authorization. Bangalore and Hyderabad clusters attract turnkey chamber installations for telecommunications equipment vendors.
Anechoic Chamber Market Key Industry Players
Top-tier vendors anchor integrated absorber-and-shielding supply, while mid-tier fabricators compete on regional installation speed and maintenance contracts. Market structure tilts toward consolidated absorber material supply with fragmented chamber assembly and calibration services. Three archetypes dominate: Japanese-German chemical specialists controlling foam formulations, North American shielding engineers with FCC certification relationships, and European custom architectural acoustic designers. Competitive moves concentrate on absorber technology licensing partnerships and captive installation capacity expansion in high-growth certification corridors.
Among Japanese and German material specialists, TDK Corporation and Frankonia Group exemplify the absorber technology archetype that anchors relationships with Asian EV platforms. ETS-Lindgren occupies a position within the North American certification infrastructure tier, representing the shielding-and-test-system integrator model. These three entities illustrate how geographic specialization in materials, regulatory relationships, and custom fabrication stratifies competitive positioning across the value chain.
| Leading Market Players |
|---|
| ETS-Lindgren |
| TDK Corporation |
| Eckel Industries |
| MVG |
| Albatross Projects GmbH |
| ESCO Technologies |
| Brüel & Kjær |
| Frankonia Group |
| Comtest Engineering |
| Others |
Cost & Logistics Intelligence
Electromagnetic simulation engineers concentrated in Stuttgart and Munich command compensation premiums that widen pricing spreads between premium custom chambers and economy-tier installations. Labor-cost differentials between German design specialists and Asian assembly technicians stratify the market into three distinct procurement tiers.
Pricing Analysis
Margin tightening in economy-tier semi-anechoic chambers reflects pyramidal foam commoditization among Japanese and German chemical suppliers. Three-tier pricing structure across premium, standard, and economy levels differentiates by certification grade and after-sales service bundling. Pricing pressure intensifies in standard-tier configurations as Chinese installation partners compete on total cost-of-ownership. Telecommunications companies demonstrate lowest price sensitivity due to captive validation requirements, while independent laboratories face acute budget constraints.
Supply Chain Analysis
Dual-sourcing mandates from aerospace manufacturers in Germany and the United States require qualified backup suppliers for ferrite tile arrays and copper shielding panels. Supply concentrates in Japan for specialty polyurethane foam formulations, Germany for precision ferrite substrates, and China for galvanized steel panel fabrication. Raw material dependencies include rare-earth ferrite powders, conductive copper sheeting, and fire-retardant foam precursors. Single-source vulnerability persists in sub-6 GHz pyramidal foam geometries patented by incumbent chemical specialists. Distribution runs through turnkey installation contractors rather than direct equipment sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into absorber material production represents the critical competitive race, with chamber vendors pursuing captive foam formulation capabilities to escape specialty chemical supplier pricing power.
For Market Incumbents: Anticipate margin compression from metamaterial absorber startups by securing exclusive licensing partnerships with university electromagnetic research programs. Defensive consolidation through acquisition of regional installation specialists in China's Yangtze River Delta preserves channel control against domestic competitors. For New Entrants and Emerging Players: Independent satellite payload developers in Germany and the United States present an underserved buyer archetype seeking compact iteration chambers with rapid delivery timelines. White-space penetration targets include O-RAN interoperability test houses requiring multi-antenna configurations and Indian telecommunications laboratories building post-TRAI auction capacity. Go-to-market positioning as metamaterial surface specialists bypasses incumbent foam supply relationships. For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated chamber-assemblers who control both ferrite tile production and electromagnetic shielding fabrication, given satellite constellation deployment acceleration. Long-term viability favors acquisition targets with MIIT certification relationships in China and FCC test-lab partnerships in the United States. Watch O-RAN specification finalization as inflection indicator for multi-antenna chamber demand.| Strategic Initiative | Industry Significance |
|---|---|
| Absorber Material Backward Integration | Captive ferrite tile production insulates margins from Japanese chemical supplier pricing power. |
| Metamaterial Surface Licensing | Frequency-selective absorber partnerships with Stuttgart technical universities compress urban facility footprints. |
| MIIT Certification Partnership | GB-standard qualification in China unlocks domestic 5G equipment testing procurement. |
| Turnkey Service Contract Expansion | Bundled calibration and maintenance agreements with Asian EV platforms secure recurring revenue. |
| Satellite Payload Chamber Miniaturization | Compact low-earth orbit validation cells address German and US aerospace manufacturer iteration cycles. |
Research Approach
Multi-period observation of chamber installation volumes, absorber material pricing indices, and certification throughput rates anchored the trend analysis, supplemented by interviews with electromagnetic test laboratory directors, OEM validation program managers, absorber foam procurement leads, and satellite payload engineering heads. Secondary validation drew from FCC equipment authorization databases, MIIT certification registries, ETSI standards documentation, and customs trade records for ferrite and copper shielding materials. Bottom-up facility counts triangulated against top-down market sizing from capital expenditure disclosures.
Input-output matrices modeled chamber demand across product architecture, absorber technology, application protocol, and end-user procurement type. Segmentation dimensions included semi-anechoic versus fully anechoic configurations, foam-based versus ferrite tile absorber systems, automotive versus telecommunications versus aerospace validation workflows, and captive versus independent laboratory ownership structures. CAGRs were derived from regression analysis of historical installation patterns against 5G deployment schedules and EV platform launch timelines. Forecast inputs incorporated MIIT spectrum allocation announcements and FCC Part 15 rulemaking proceedings.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to O-RAN specification evolution and low-earth orbit satellite constellation deployment cadence. Deviation in metamaterial absorber commercialization timelines or pyramidal foam supply disruptions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Radiography Test Equipment Market
Test and Measurement
CCTV Tester Market
Test and Measurement
Wi-Fi Test Equipment Market
Test and Measurement
Tensile Testing Machine Market
Test and Measurement
Additively Manufactured Lattice Structure Mechanical Test Systems Market
Test and Measurement
Non-Destructive Testing (NDT) Software Market
Test and Measurement
Asia-Pacific Semiconductor Metrology and Inspection Market
Test and Measurement
Ohm Meter Market
Test and Measurement
United States Signal Generator Market
Test and Measurement
Receptacle Tester Market
Test and Measurement
Universal Testing Machine Market
Test and Measurement
Pump Testers Market
Test and Measurement
North America Electronic Test and Measurement Market
Test and Measurement
Solid-State Battery Fast-Charge Degradation Test Systems Market
Test and Measurement
Test and Measurement Sensors Market
Test and Measurement
Electrolyzer Test System Market