
 Photometer and Calorimeter Market | 2026-2036
Photometer and Calorimeter Market Size, Share, and Industry Trends Forecast 2026-2036
Photometer and Calorimeter Market Analytics
Environmental monitoring agencies are redrawing procurement patterns for photometric water quality instruments, displacing traditional laboratory-centric buying. Shimadzu Corp. leverages its optical engineering heritage to dominate UV-Vis spectrophotometry for pharmaceutical applications. TA Instruments Inc. anchors North American demand for differential scanning calorimetry through its specialized thermal analysis portfolio. Hanna Instruments competes aggressively in portable colorimetry for field-deployed environmental testing, extending its channel reach through water utility distributors.
Photometers and calorimeters comprise analytical instruments that quantify light absorption, emission, or thermal energy changes in samples, typically operating across wavelength ranges from 190 nm to 1100 nm or temperature ramps from -180°C to 700°C for thermal analysis. These devices serve as foundational measurement tools for quality control, reaction kinetics studies, and material stability assessment across process industries. Spectrophotometer demand leads product type revenue due to its ubiquity in pharmaceutical quality assurance workflows, while fluorometer adoption accelerates fastest in biopharma R&D for protein conformation studies. Microprocessor-based technology commands premium positioning through automated calibration and data integrity features that satisfy regulatory audit requirements, whereas analog systems retain share in cost-sensitive educational markets where precision thresholds remain modest.
The FDA enforces 21 CFR Part 11 compliance for electronic records in pharmaceutical analytical workflows, directly shaping instrument software architecture and validation documentation requirements. Europe's MDR and REACH frameworks impose substance characterization obligations that expand calorimetry deployment for polymer and medical device material certification. ISO 17025 accreditation standards for testing laboratories create recurring demand for photometer recalibration services and traceable reference standards. Stakeholders must monitor evolving data integrity enforcement patterns and position service capabilities ahead of regulatory inspection intensity cycles.
Market Dynamics
Pharmaceutical laboratories are consolidating thermal analysis workflows around microprocessor-based calorimeters to meet FDA 21 CFR Part 11 data integrity mandates, compressing replacement cycles for legacy analog systems and reshaping vendor service revenue models.
Growth Catalysts
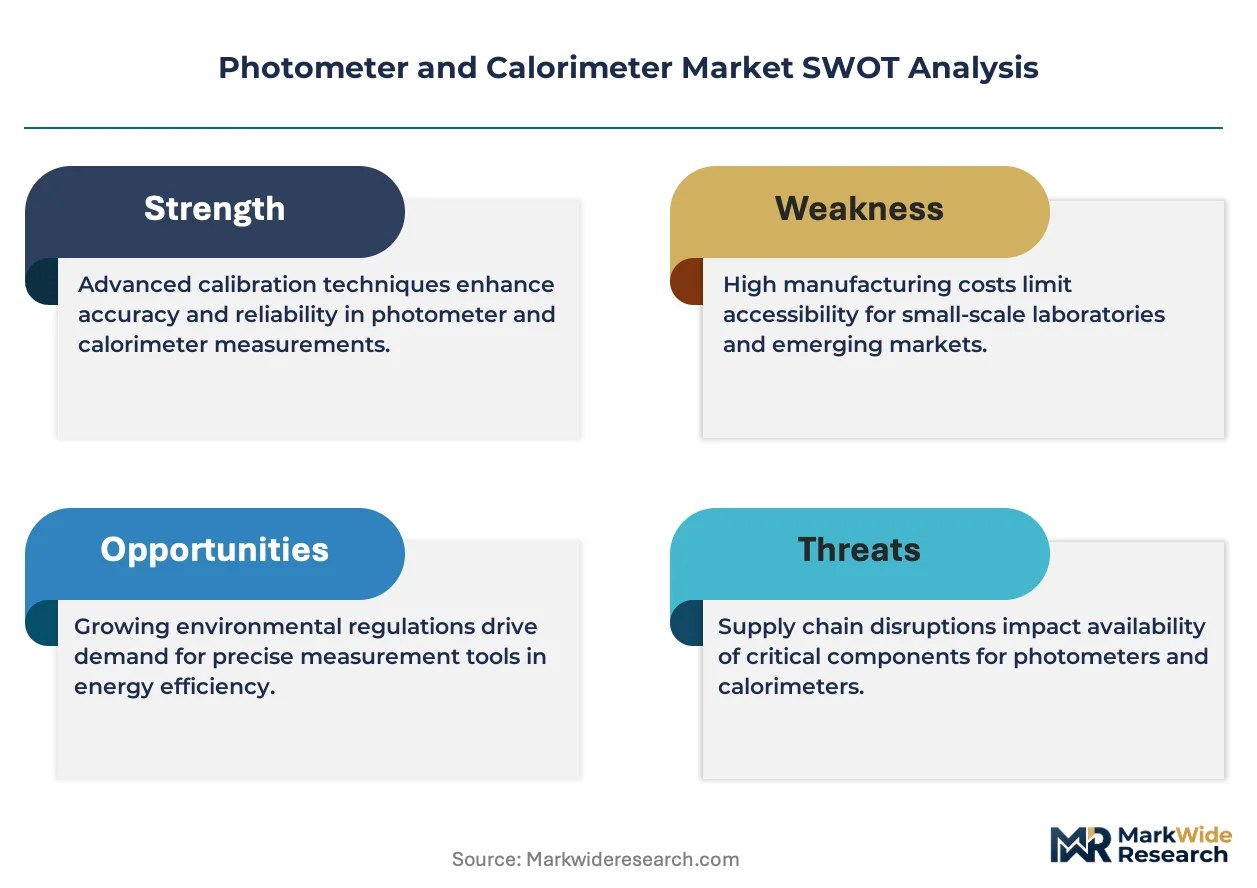
- Biologics characterization demand:Pharmaceutical R&D pipelines require differential scanning calorimetry for protein stability assessment, pulling instrument procurement toward high-sensitivity thermal analysis systems.
- Europe's MDR framework:Medical device material certification obligations expand calorimetry deployment for polymer characterization and thermal property documentation.
- Heidelberg-Munich instrument cluster:Precision optics manufacturing concentration in southern Germany anchors supply chain reliability for UV-Vis photometer component sourcing.
Market Restraints
- High-purity optical component costs:Germanium and silicon photodetector wafer prices fluctuate with semiconductor foundry capacity allocation, squeezing gross margins on mid-range spectrophotometers.
- Specialized service technician scarcity:Thermal analysis instrument calibration requires certified engineers whose training pipelines lag equipment complexity advances.
- Portable colorimeter performance ceiling:Field-deployed environmental testing units cannot match laboratory-grade resolution, limiting substitution potential for regulatory-grade water quality monitoring.
Strategic Opportunities
- India's CDSCO biologics pathway:Biosimilar approval acceleration creates demand for calorimetry-equipped contract research organizations serving domestic pharmaceutical development.
- Cloud-connected instrument platforms:Remote diagnostics and predictive maintenance capabilities differentiate vendor offerings in distributed pharmaceutical manufacturing networks.
- Water utility distributor channels:Environmental monitoring procurement bypasses traditional laboratory supply houses through specialized infrastructure service contracts.
Industry Challenges
- ISO 17025 accreditation timelines:Testing laboratory certification delays instrument revenue recognition and extends sales cycles for photometer recalibration service contracts.
- Legacy system integration complexity:Pharmaceutical quality control networks require seamless data handoff between microprocessor-based calorimeters and existing LIMS architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Photometer and Calorimeter Market |
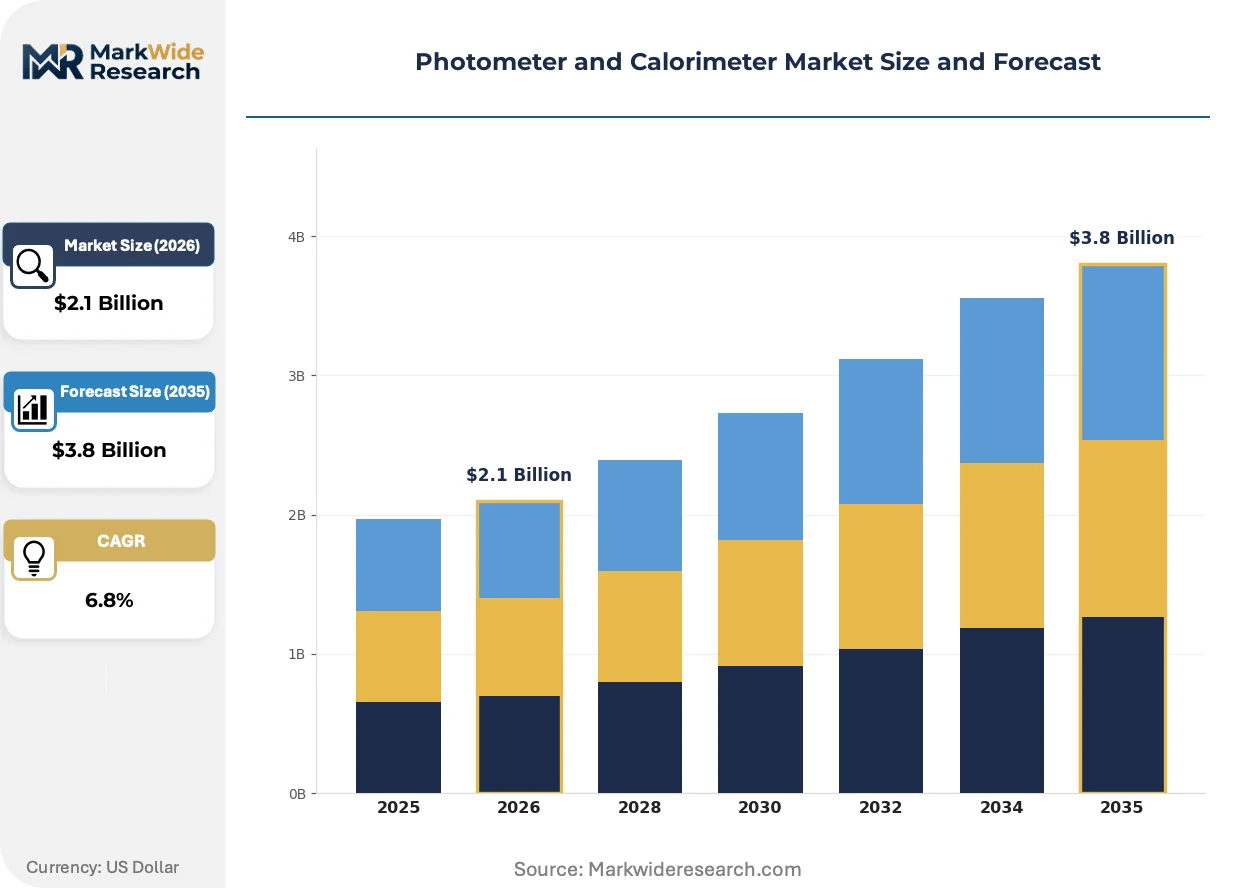
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spectrophotometer, Colorimeter, Fluorometer, Dual-Beam Photometer End User: Laboratories, Industrial, Educational Institutions, Environmental Monitoring Technology: Optical, Digital, Microprocessor-Based, Analog Application: Water Quality Analysis, Food Testing, Pharmaceutical Research, Chemical Analysis |
| Companies Covered | Calorimetry Sciences Corp., Swan Analytical Instruments AG, MicroCal LLC, ABB Ltd, Yokogawa Electric Corporation, Shimadzu Corp., Mettler-Toledo International Inc, TA Instruments Inc., Hanna Instruments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Photometer and Calorimeter Market Evolving Landscape
Instrument architecture is pivoting toward embedded compliance automation as regulatory audit intensity tightens across pharmaceutical and environmental monitoring verticals, compressing competitive differentiation around software validation capabilities rather than hardware specifications alone.
Microprocessor-based photometer platforms are displacing analog detection systems in pharmaceutical quality assurance workflows. Biologics manufacturers in Germany and Switzerland adopt these units for automated wavelength calibration and electronic signature capture. The shift compresses demand for manual calibration services while elevating software validation documentation to primary procurement criteria.
Europe's REACH substance characterization obligations now require thermal analysis data for polymer import certification. Calorimeter manufacturers must pre-configure temperature ramp protocols matching ECHA guidance templates. Medical device material suppliers in Italy and France face the steepest compliance burden, driving differential scanning calorimetry specification into standard procurement tenders.
Environmental monitoring agencies now contract directly with water utility infrastructure providers rather than centralized laboratory procurement departments. Field-deployed colorimetry instruments with cellular data transmission replace sample collection and transport logistics. This pattern concentrates most visibly in Germany's river basin management districts, where real-time phosphate and nitrate monitoring mandates accelerate portable instrument refresh cycles.
Photometer and Calorimeter Market Segmentation
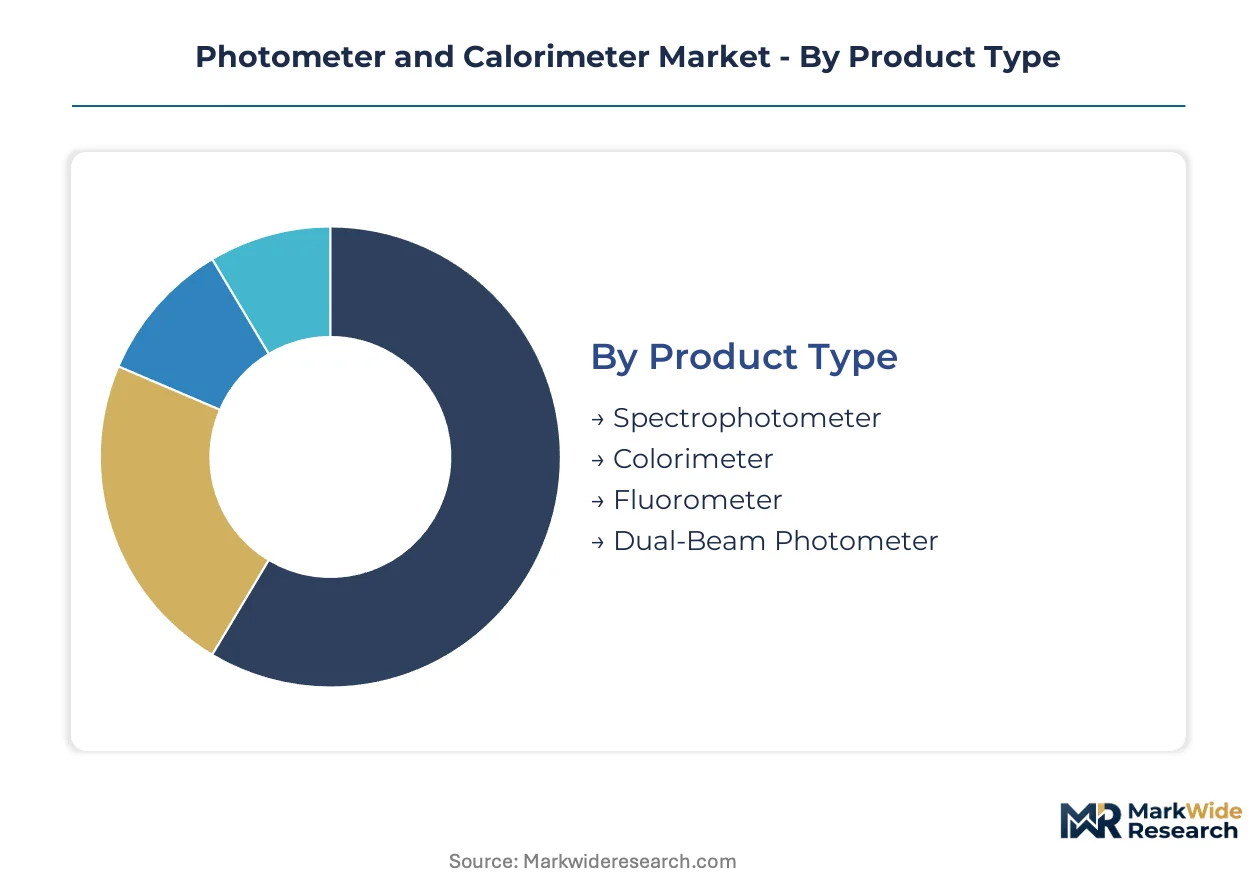
Photometer and calorimeter procurement patterns fragment sharply across end-use contexts, with regulatory compliance intensity and precision thresholds dictating technology choices. Vendors must align product architectures to distinct validation requirements rather than pursuing universal platform strategies.
Product Type:
Substitution pressure concentrates on dual-beam photometers as single-beam alternatives close the precision gap at lower price points, forcing incumbents to defend through software differentiation.
- Spectrophotometer:These instruments measure light absorption across ultraviolet, visible, and near-infrared wavelengths using monochromator-based optical benches. Pharmaceutical quality assurance workflows in Germany and Switzerland anchor demand, where automated wavelength calibration satisfies FDA 21 CFR Part 11 mandates. Compliance documentation requirements compress replacement cycles for legacy units.
- Fluorometer:Fluorometers detect molecular fluorescence emission with sensitivity thresholds reaching picomolar concentrations. Biopharma R&D facilities prioritize these systems for protein conformation and binding affinity studies, pulling procurement toward high-sensitivity photomultiplier tube configurations.
- Colorimeter:Portable colorimeters serve field-deployed environmental testing with simplified optical paths and battery-powered operation. Water utility distributors in Germany's river basin management districts specify cellular data transmission capabilities.
- Dual-Beam Photometer:These systems split incident light between sample and reference cuvettes to compensate for source intensity drift. Cost-conscious industrial laboratories favor the design for routine quality control where absolute precision remains secondary to measurement stability.
Spectrophotometer retains volume leadership; fluorometer holds the steepest expansion curve.
End User:
Laboratory procurement dominates revenue contribution, though environmental monitoring agencies are redirecting spend toward field-deployable instrumentation.
- Laboratories:Pharmaceutical research laboratories command premium instrument specifications with embedded compliance automation. ISO 17025 accreditation requirements create recurring demand for traceable recalibration services and reference standard replacements.
- Environmental Monitoring:Agencies now contract directly with water utility infrastructure providers, bypassing traditional laboratory supply channels. Real-time phosphate and nitrate monitoring mandates in Germany accelerate portable colorimeter refresh cycles.
- Industrial:Process industries deploy photometers for inline quality control with simplified operator interfaces. Chemical manufacturers prioritize ruggedized enclosures over analytical sensitivity.
- Educational Institutions:Universities and technical colleges procure analog detection systems where precision thresholds remain modest. Cost sensitivity dominates procurement criteria with minimal software validation requirements.
Laboratories retain volume leadership; environmental monitoring holds the steepest expansion curve.
Technology:
Microprocessor-based platforms command margin concentration as analog systems retreat to price-sensitive niches.
- Microprocessor-Based:These platforms integrate automated calibration routines, electronic signature capture, and audit trail generation. Pharmaceutical manufacturers adopt these units exclusively to satisfy FDA data integrity enforcement patterns.
- Digital:Digital detection systems offer intermediate positioning with solid-state photodiode arrays and software-controlled wavelength selection. Contract research organizations favor the balance of capability and capital efficiency.
- Optical:Conventional optical architectures with discrete component benches persist in high-end research applications requiring customizable light path configurations.
- Analog:Analog systems retain share in educational markets and developing economy laboratories where regulatory audit intensity remains minimal.
Microprocessor-based retains volume leadership; digital holds the steepest expansion curve.
Application:
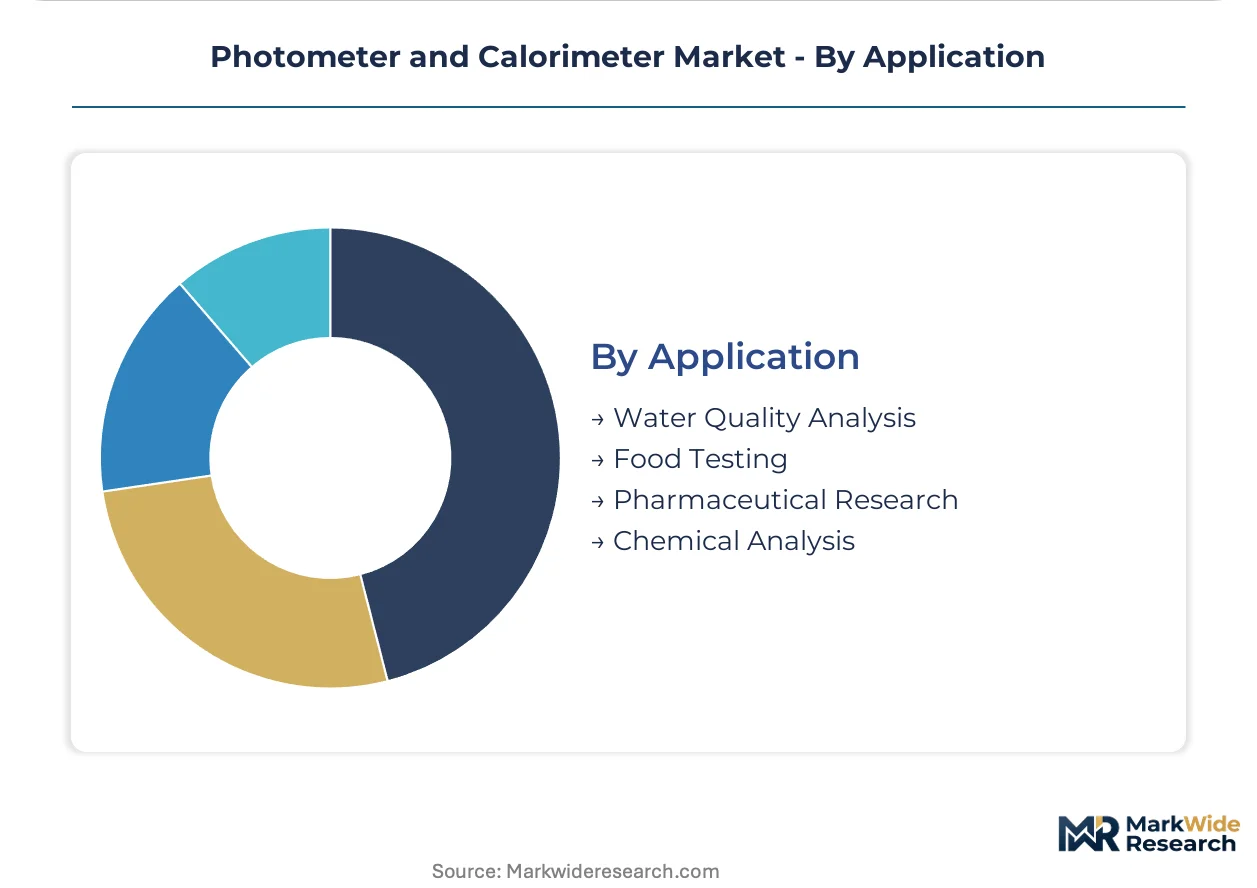
Pharmaceutical research concentrates the highest per-unit spend, while food testing faces margin compression from standardized method requirements.
- Pharmaceutical Research:Biologics characterization workflows require differential scanning calorimetry for protein stability assessment. CDSCO's biosimilar approval acceleration in India expands demand for calorimetry-equipped contract research organizations.
- Water Quality Analysis:Field-deployed colorimetry with cellular data transmission replaces sample collection logistics. Germany's river basin management districts mandate real-time monitoring for nutrient discharge compliance.
- Food Testing:Spectrophotometric methods for contaminant detection and nutritional labeling face standardization pressure from EU reference method harmonization.
- Chemical Analysis:Industrial process control applications prioritize measurement speed over analytical sophistication, favoring simplified optical configurations.
Pharmaceutical research retains volume leadership; water quality analysis holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision instrument manufacturing clusters in southern Germany and Switzerland anchor component supply chains for optical photometry systems. Heidelberg and Munich host dense networks of optical engineering specialists serving pharmaceutical quality assurance workflows. Regulatory frameworks in multiple jurisdictions reshape procurement patterns for thermal analysis equipment.
Germany
Pharmaceutical manufacturers in Baden-Württemberg and Bavaria drive demand for microprocessor-based calorimeters with automated compliance documentation. The country's MDR implementation tightens medical device material certification requirements for polymer thermal characterization. The Heidelberg-Munich corridor concentrates UV-Vis photometer component sourcing through specialized optics fabricators.
United States
FDA enforcement of 21 CFR Part 11 data integrity mandates compresses replacement cycles for legacy thermal analysis systems in pharmaceutical laboratories. The agency's updated analytical instrument validation guidelines reshape software architecture requirements across quality control networks. Boston and San Diego biotech clusters anchor differential scanning calorimetry procurement for protein stability assessment.
Switzerland
Biologics manufacturers in Basel and Zurich prioritize fluorometer configurations for protein conformation studies. Swissmedic oversight of biosimilar development pathways elevates instrument validation documentation to primary procurement criteria. The country's precision engineering heritage supports specialized photodetector assembly for high-sensitivity applications.
India
CDSCO's accelerated biosimilar approval pathway expands demand for calorimetry-equipped contract research organizations in Hyderabad and Bangalore. The regulator's biologics characterization requirements pull procurement toward thermal analysis systems with automated data integrity features. Domestic pharmaceutical development clusters in Maharashtra and Telangana anchor instrument service network expansion.
Japan
PMDA guidelines for biologics stability testing drive differential scanning calorimetry adoption in Osaka and Tokyo pharmaceutical R&D facilities. The country's industrial standards framework imposes traceable calibration requirements on photometric water quality instruments. Kansai region precision manufacturers supply optical benches for UV-Vis spectrophotometry platforms.
Photometer and Calorimeter Market Competitive Landscape
Concentration sits with diversified analytical instrument conglomerates and specialized thermal analysis providers. The market structure spans three tiers: precision optics specialists with pharmaceutical heritage, diversified measurement technology conglomerates with broad industrial reach, and portable instrumentation specialists serving environmental monitoring channels. Strategic moves center on cloud-connected platform development and predictive maintenance service capabilities.
Among diversified analytical instrument providers, Shimadzu Corp., Mettler-Toledo International Inc, and TA Instruments Inc occupy positions spanning spectrophotometry and thermal analysis domains. These entities exemplify archetypes ranging from optical engineering heritage to precision measurement scale. Hanna Instruments represents the portable instrumentation specialist tier focused on field-deployed environmental testing channels. Swan Analytical Instruments AG and Yokogawa Electric Corporation anchor process analytics and industrial automation vectors respectively.
| Leading Market Players |
|---|
| Calorimetry Sciences Corp. |
| Swan Analytical Instruments AG |
| MicroCal LLC |
| ABB Ltd |
| Yokogawa Electric Corporation |
| Shimadzu Corp. |
| Mettler-Toledo International Inc |
| TA Instruments Inc. |
| Hanna Instruments |
| Others |
Value Network & Pricing Analysis
FDA 21 CFR Part 11 compliance gates both vendor qualification and price tier separation in pharmaceutical procurement workflows. The regulation mandates electronic signature capture and audit trail generation, forcing buyers to discriminate between certified and uncertified instrument platforms regardless of hardware specifications. This dual gating mechanism concentrates pricing power with vendors who pre-validate software architectures.
Pricing Analysis
FDA 21 CFR Part 11 dictates the pricing tier structure across the photometer and calorimeter market. Three-tier pricing structure across premium, standard, and economy levels separates microprocessor-based platforms with embedded compliance automation from digital systems with partial validation support and analog units for educational markets. Price differentiation hinges on ISO 17025 calibration certification tier and after-sales service bundling intensity. Cost compression in the economy tier is intensifying because educational institutions face budget constraints without regulatory audit pressure. Environmental monitoring agencies show highest price sensitivity due to volume procurement mandates, while pharmaceutical manufacturers demonstrate lowest sensitivity given compliance failure costs.
Supply Chain Analysis
Inventory cycles for germanium photodetector wafers stretch lead times during semiconductor foundry capacity crunches. Optical component sourcing concentrates in Germany, Japan, and Switzerland, where precision engineering clusters maintain photodetector assembly capabilities. Supply chains draw from silicon wafer foundries, optical glass fabricators, and microprocessor semiconductor vendors. Single-source vulnerability sits with specialized monochromator grating manufacturers in southern Germany. Distribution runs through laboratory supply houses, water utility infrastructure contractors, and direct pharmaceutical procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The photometer and calorimeter market sits in early-cycle expansion as biologics characterization workflows penetrate contract research organizations beyond traditional pharmaceutical headquarters. Biosimilar approval acceleration across multiple regulatory jurisdictions extends instrument demand into mid-tier service providers previously priced out of thermal analysis procurement.
For Market Incumbents: Fortify software validation documentation capabilities ahead of intensifying FDA audit patterns. Incumbent vendors must deepen backward integration into optical component sourcing to defend margin position against germanium wafer price volatility. Channel control through exclusive water utility distributor relationships protects portable colorimeter revenue streams from emerging environmental monitoring specialists.
For New Entrants and Emerging Players: CDSCO's accelerated biosimilar approval pathway offers certification fast-track entry into India's contract research organization segment. New entrants should target Hyderabad and Bangalore instrument service networks where incumbent presence remains thin. A go-to-market angle anchored in cloud-connected predictive maintenance capabilities differentiates against legacy vendor service models.
For Investors and Strategic Acquirers: Europe's MDR implementation reshapes the acquisition landscape toward thermal analysis providers with pre-configured polymer characterization protocols. Long-term viability favors precision optics specialists with captive photodetector assembly capabilities. The signal to watch is ISO 17025 accreditation timeline compression in testing laboratory certification, indicating service revenue inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Connected Platform Development | Remote diagnostics capabilities differentiate vendor offerings in distributed pharmaceutical manufacturing networks. |
| Backward Integration into Optical Components | Captive photodetector wafer supply insulates margins from semiconductor foundry capacity allocation volatility. |
| Water Utility Channel Expansion | Infrastructure service contracts bypass traditional laboratory supply houses in environmental monitoring procurement. |
| ISO 17025 Service Network Buildout | Traceable recalibration capabilities capture recurring revenue from accredited testing laboratories. |
| Biologics Characterization Protocol Pre-Configuration | ECHA-aligned temperature ramp templates accelerate polymer certification workflows for medical device suppliers. |
Research Methodology
Desk research of regulatory filing databases, trade customs records, and instrument certification registries preceded structured interviews with pharmaceutical quality control directors, thermal analysis service engineers, water utility procurement managers, and optical component sourcing specialists. Primary fieldwork with laboratory instrumentation vendors and contract research organization executives combined with secondary validation against FDA 21 CFR Part 11 guidance documents, ECHA substance characterization protocols, and ISO 17025 accreditation standards. Bottom-up demand modeling across end-use segments triangulated against top-down market sizing from precision instrument trade associations.
Variance decomposition across product type, technology tier, end-user category, and geographic regulatory cluster shaped the analytical framework over the projection horizon. CAGRs derived from instrument replacement cycle analysis, biologics pipeline expansion rates, and environmental monitoring mandate implementation timelines. Modeled inputs included differential scanning calorimetry adoption curves in biosimilar development, portable colorimeter refresh cycles in German river basin districts, and microprocessor-based platform penetration in pharmaceutical quality assurance.
The analysis sits within stated boundaries; outcomes outside sustained biologics investment levels or accelerated MDR enforcement timelines would require recalibration. Forecasts reflect documented assumptions regarding regulatory audit intensity patterns and semiconductor foundry capacity allocation. Supply chain disruption from optical component trade restrictions or calibration technician training pipeline failures represents specific revision triggers. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Hearing Aid and True Wireless Earbud Acoustic Performance Test Systems Market
Test and Measurement
Optical Wafer Inspection Systems Market
Test and Measurement
Video Test Equipment Market
Test and Measurement
Non-Destructive Testing (NDT) Service Market
Test and Measurement
Global General Purpose Test Equipment (GPTE) Market
Test and Measurement
Calibration Management Software Market
Test and Measurement
Battery CT Inspection Market
Test and Measurement
Battery Test Equipment Market
Test and Measurement
Stress Test Chamber Market
Test and Measurement
Europe Signal Generator Market
Test and Measurement
Solar Clamp Meter Market
Test and Measurement
Coaxial Profile Projectors Market
Test and Measurement
Global Micrometer Market
Test and Measurement
Microwave Power Meters Market
Test and Measurement
Anechoic Chamber Market
Test and Measurement
Ultrasonic Wall Thickness Gauges Market