
 Data Center Testing Market | 2026-2036
Data Center Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Data Center Testing Market Outlook
Hyperscale cloud providers are gaining share as the buyer base is bifurcating away from traditional enterprise data center operators. NTT Data dominates integrated commissioning and validation programs across Asia-Pacific facilities. Equinix anchors interconnection testing standards at its global platform sites. Google sustains in-house thermal stress-testing protocols for its custom server deployments.
Data center testing encompasses systematic validation of power distribution, cooling efficiency, network latency, and failover resilience prior to commercial operation, typically executed through simulated load injection and continuous monitoring over 72-hour burn-in cycles. Performance testing leads service-type revenue as AI clusters push thermal design power beyond traditional validation thresholds, while edge deployment models represent the fastest-growing structural segment due to distributed latency requirements. Cloud testing technology occupies mature margin pools, whereas security testing commands premium pricing amid rising cyber-physical convergence risks.
EU AI Act classification rules and NIS2 resilience mandates are reshaping certification scope for facilities hosting high-risk automated systems. Uptime Institute Tier certification and ISO 22237 standards govern thermal and power quality benchmarks across European and North American markets. Stakeholders must monitor regulatory divergence between EU operational resilience frameworks and emerging US EPA efficiency guidelines for data center power usage effectiveness thresholds.
Market Dynamics
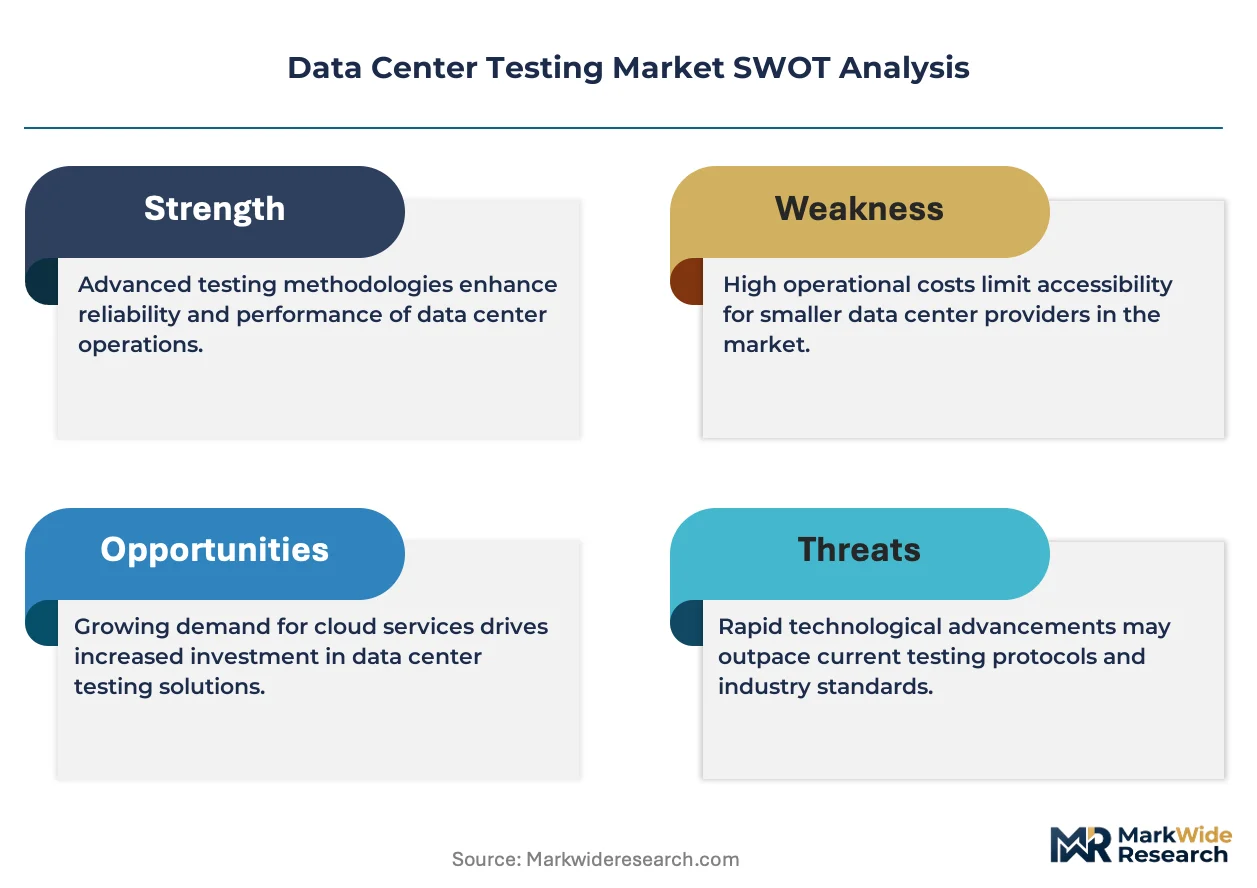
Hyperscale cloud providers are bifurcating the buyer base away from traditional enterprise operators, concentrating commissioning demand among fewer accounts with specialized AI-ready validation protocols and compressed acceptance timelines.
Growth Catalysts
- EU AI Act Classification Rules:Facilities hosting high-risk automated systems in Germany, France, and the Netherlands now face mandatory resilience certification, expanding testing scope beyond traditional Tier standards.
- Thermal Design Power Thresholds:AI clusters from NVIDIA and AMD are pushing power densities past 100kW per rack, forcing new liquid-cooled validation methodologies and extended burn-in cycles.
- Frankfurt Cluster Density:Germany's concentration of hyperscale facilities generates specialized demand for integrated thermal and power quality validation services that smaller markets cannot replicate.
Market Restraints
- Specialized Engineering Talent Scarcity:The pool of certified commissioning engineers with AI facility experience remains concentrated in Northern Europe and the US West Coast, creating geographic supply bottlenecks.
- Copper and Electrical Component Volatility:Power distribution testing equipment relies on copper busbars and precision switchgear subject to commodity price swings and extended lead times.
- NIS2 Implementation Friction:EU member states are interpreting resilience mandates inconsistently, forcing testing providers to maintain multiple compliance playbooks and delaying contract finalization.
Strategic Opportunities
- India Data Center Build-Out:Mumbai and Hyderabad are attracting hyperscale investment under the country's digital infrastructure incentives, creating first-mover openings for integrated commissioning services.
- Digital Twin Convergence:Physics-based simulation platforms are merging with live sensor networks, enabling predictive validation that reduces physical burn-in duration and facility downtime.
- Edge Micro-Facility Certification:Distributed latency requirements are spawning standardized validation protocols for sub-500kW deployments that lack traditional Tier certification pathways.
Industry Challenges
- ISO 22237 and Tier Standard Harmonization:Testing providers must navigate overlapping but non-identical thermal and power quality benchmarks across European and North American certification bodies, complicating multi-site programs.
- Legacy DCIM Integration Complexity:New AI-optimized monitoring platforms must interface with decade-old building management systems, extending commissioning timelines and requiring custom protocol bridges.
- Cyber-Physical Security Convergence:Testing teams now require cleared personnel to validate failover resilience in facilities handling classified or critical infrastructure workloads, narrowing the available talent pool.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Data Center Testing Market |
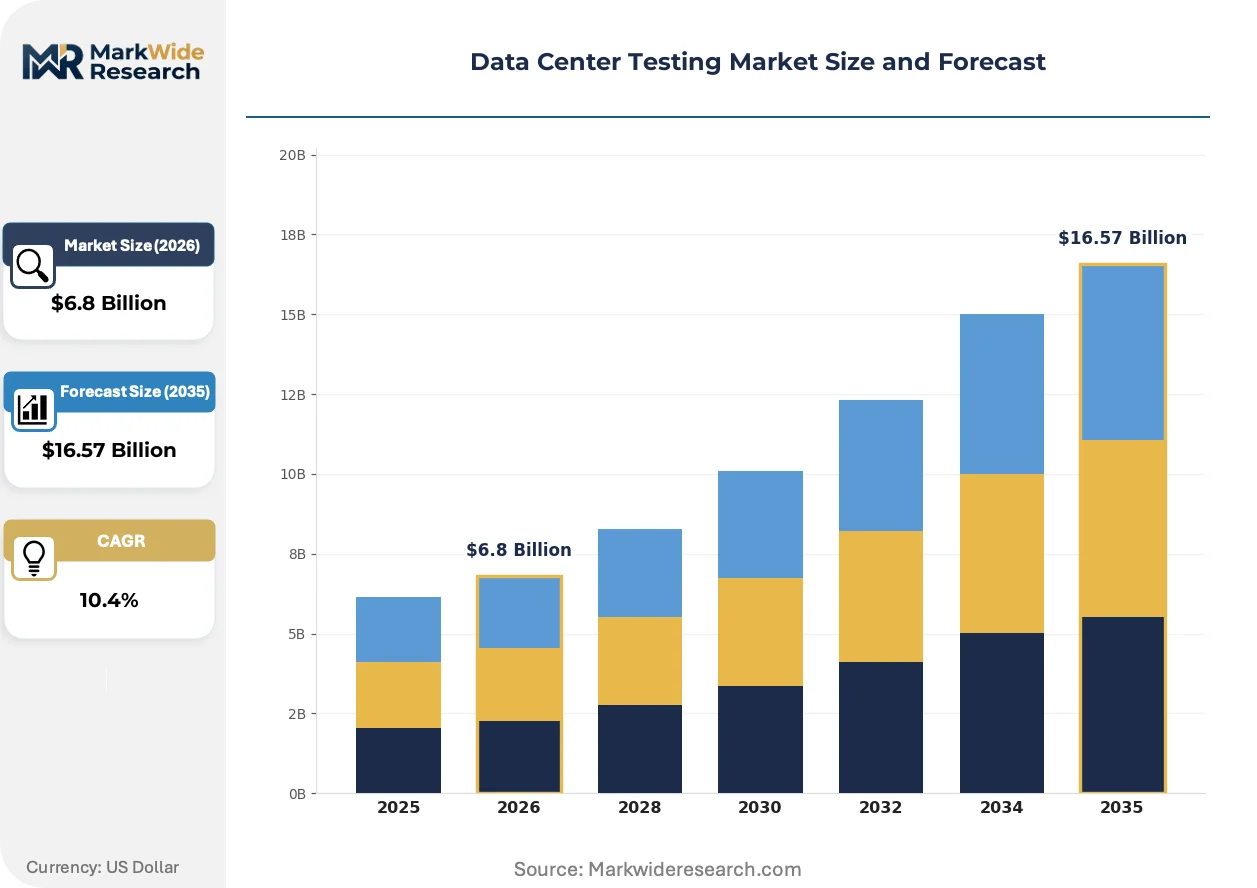
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $16.57 Billion |
| CAGR (2026 – 2036) | 10.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Performance Testing, Compliance Testing, Security Testing, Load Testing Technology: Cloud Testing, Virtualization Testing, Network Testing, Hardware Testing End User: Telecommunications, Cloud Providers, Managed Service Providers, Enterprises Deployment Model: On-Premises, Hybrid, Cloud, Edge |
| Companies Covered | NTT Data, Flexential, Equinix, Google, MSH, Digital Realty, Rackspace Technology, Meta, Kyndryl, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Data Center Testing Market Strategic Shifts
Systematic validation methodologies are compressing from multi-week commissioning cycles toward continuous automated verification, driven by software-defined infrastructure and real-time thermal telemetry.
Physics-based digital twin platforms are supplanting static load-bank testing for thermal validation. Hyperscale operators in Ireland and Singapore are deploying these systems at greenfield sites, reducing physical burn-in from 72 hours to 24 hours while maintaining ISO 22237 compliance. The technology is compressing project timelines and reallocating engineering resources toward predictive failure analysis.
The EU AI Act's operational resilience mandates are forcing testing scope expansion into automated decision-system failover scenarios. Facilities hosting high-risk AI applications in Frankfurt and Amsterdam must now demonstrate sub-second workload migration under simulated cyber-physical attack conditions. Commissioning providers are responding by hiring cleared security engineers and partnering with national cyber agencies for attack simulation protocols.
Buyer concentration among hyperscale cloud providers is consolidating procurement authority into centralized technical standards teams. Traditional enterprise data center operators in secondary US markets are losing negotiating leverage and accepting bundled validation packages from construction-integrated providers rather than independent commissioning specialists. This shift is visible most acutely in Phoenix and Northern Virginia, where Amazon, Microsoft, and Google procurement teams dictate testing protocols and pricing benchmarks.
Data Center Testing Market Segmentation
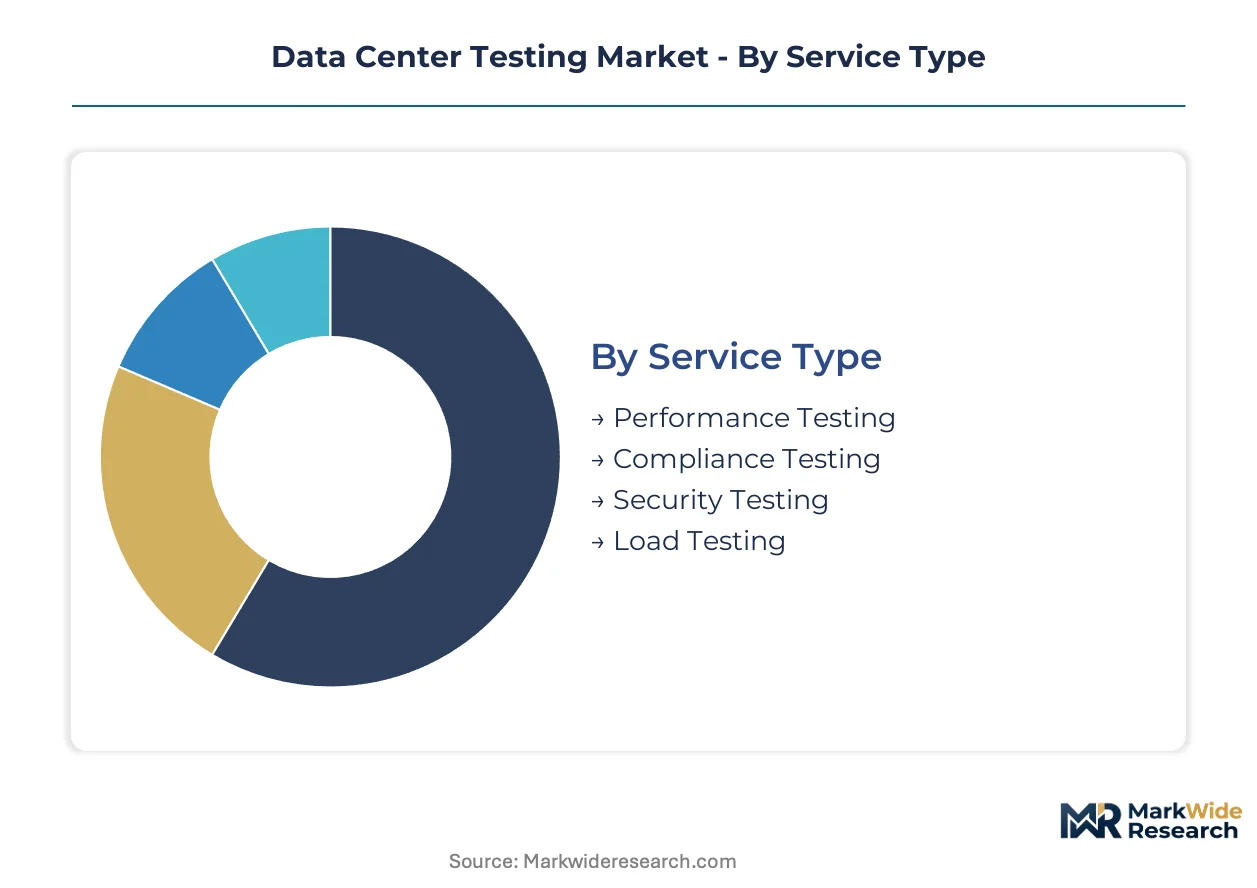
Data center testing procurement channels fragment sharply between hyperscale direct contracting and enterprise bundled services. Channel selection determines validation depth, certification authority, and pricing leverage for testing providers.
Service Type:
Performance testing flows through hyperscale technical standards teams with compressed timelines. Compliance testing routes through facility construction integrators. Security testing channels through cleared personnel networks.
- Performance Testing:Thermal stress validation, power quality measurement, and network latency benchmarking under simulated AI cluster loads. Hyperscale operators in Germany and Singapore are extending burn-in cycles beyond 72 hours for liquid-cooled racks exceeding 100kW density.
- Compliance Testing:EU AI Act resilience certification, Uptime Institute Tier validation, and ISO 22237 thermal benchmarking. Facilities in Frankfurt and Amsterdam face mandatory sub-second failover demonstration for high-risk automated systems.
- Security Testing:Cyber-physical convergence validation requiring cleared personnel for classified infrastructure workloads.
- Load Testing:Simulated demand injection for power distribution and cooling redundancy verification.
Performance testing dominates installed base. Compliance testing is where expansion concentrates.
Technology:
Cloud testing commands mature margin pools through standardized automation frameworks. Hardware testing absorbs premium engineering costs from copper component volatility.
- Cloud Testing:Automated orchestration of distributed validation workloads across virtualized infrastructure. Hyperscale providers deploy continuous verification pipelines that compress commissioning from weeks to days.
- Hardware Testing:Physical power distribution, server thermal, and storage subsystem validation. Copper busbar price swings and precision switchgear lead times are squeezing equipment procurement cycles in Northern Europe.
- Virtualization Testing:Hypervisor resilience and container orchestration failover protocols.
- Network Testing:Latency, bandwidth, and interconnection redundancy validation.
Hardware testing anchors revenue concentration. Cloud testing is climbing the fastest.
End User:
Cloud providers concentrate procurement authority into centralized technical standards teams. Enterprises accept bundled validation from construction-integrated providers with diminished negotiating leverage.
- Cloud Providers:Hyperscale operators dictating custom thermal protocols and compressed acceptance timelines. Amazon, Microsoft, and Google procurement teams in Phoenix and Northern Virginia set pricing benchmarks and validation scope.
- Telecommunications:5G edge facility validation with distributed latency requirements driving sub-500kW deployment certification.
- Managed Service Providers:Multi-tenant facility commissioning with shared infrastructure risk allocation.
- Enterprises:Secondary market operators losing procurement leverage to bundled construction packages.
Cloud providers dominate contract value. Telecommunications is gaining share fastest.
Deployment Model:
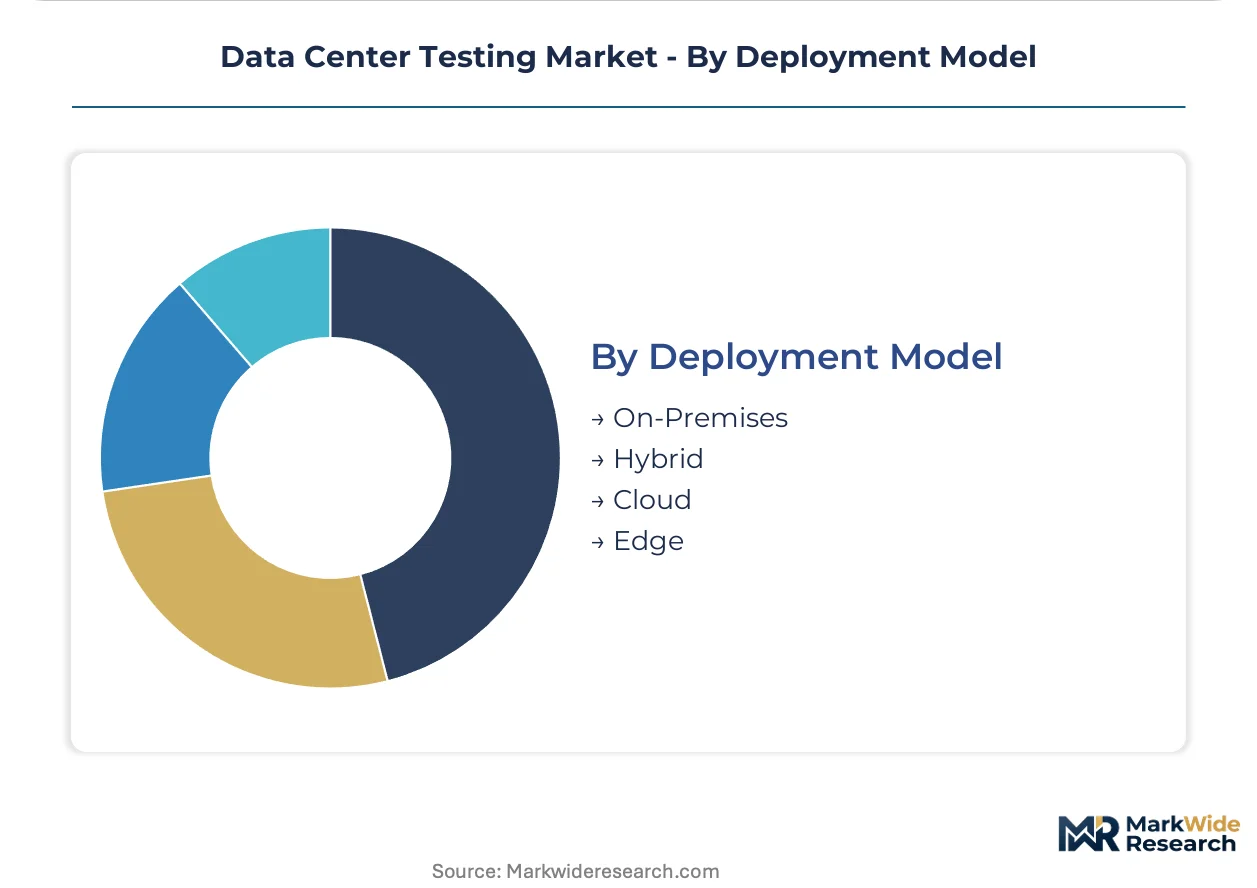
Edge deployments lack established Tier certification pathways, creating standardization gaps. On-premises retains premium pricing for custom resilience protocols.
- Edge:Sub-500kW micro-facility validation for distributed latency requirements. Physics-based digital twin platforms in Ireland and Singapore are reducing physical burn-in from 72 hours to 24 hours.
- On-Premises:Dedicated facility commissioning with full custom protocol development and extended acceptance cycles.
- Hybrid:Split workload validation across owned and colocated infrastructure.
- Cloud:Shared facility testing through provider-managed certification programs.
On-premises dominates validation spend. Edge is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The submarine cable landing stations at Cork and Dublin anchor Ireland's role as a transatlantic data hub, while the Amsterdam Internet Exchange underwrites Dutch interconnection density. These infrastructure assets concentrate commissioning demand across Northern European facilities.
Germany
Frankfurt's cluster density generates specialized thermal and power validation services that smaller markets cannot replicate. The EU AI Act and NIS2 Directive are tightening resilience certification requirements for facilities hosting high-risk automated systems. Hyperscale operators in the Rhine-Main region are extending burn-in cycles beyond 72 hours for liquid-cooled racks exceeding 100kW density.
United States
Hyperscale procurement teams in Phoenix and Northern Virginia are dictating testing protocols and pricing benchmarks. The EPA is developing efficiency guidelines for data center power usage effectiveness thresholds. Amazon, Microsoft, and Google technical standards teams in Loudoun County and Maricopa County are compressing acceptance timelines for AI-ready facilities.
Singapore
Physics-based digital twin platforms are reducing physical burn-in from 72 hours to 24 hours at greenfield sites. The Infocomm Media Development Authority governs data center sustainability standards through its Green Data Centre Roadmap. Hyperscale operators in the Jurong West and Loyang industrial estates are deploying predictive validation systems that reallocate engineering resources toward failure analysis.
India
Mumbai and Hyderabad are attracting hyperscale investment under the country's digital infrastructure incentives. The Ministry of Electronics and Information Technology administers data center certification through the India Data Centre Policy. First-mover openings for integrated commissioning services are concentrating in Maharashtra's Navi Mumbai cluster and Telangana's HITEC City corridor.
Data Center Testing Market Competitive Environment
Listed leaders compete with private specialists across certification authority and geographic coverage. The vendor base fragments between construction-integrated providers and independent commissioning specialists, with procurement authority concentrating among hyperscale technical standards teams. Three archetypes dominate: integrated facility operators with captive testing capabilities, pure-play validation specialists with ISO 22237 accreditation, and hyperscale cloud providers with in-house thermal stress-testing protocols. Competitive moves center on strategic partnerships with national cyber agencies and geographic expansion into emerging build-out markets.
Within the integrated operator tier, NTT Data and Equinix exemplify archetypes with differentiated positioning. NTT Data represents the Asia-Pacific-anchored commissioning specialist with integrated validation programs, while Equinix occupies a position as the interconnection testing standard-setter at global platform sites. Among hyperscale operators with in-house capabilities, Google sits within the tier of cloud providers maintaining proprietary thermal protocols for custom server deployments.
| Leading Market Players |
|---|
| NTT Data |
| Flexential |
| Equinix |
| MSH |
| Digital Realty |
| Rackspace Technology |
| Meta |
| Kyndryl |
| Others |
Value Chain & Pricing Dynamics
Digital twin simulation platforms displacing static load-bank testing are redrawing supply geography toward software engineering hubs while compressing pricing premiums previously anchored in physical equipment deployment cycles. This substitution simultaneously erodes hardware-dependent margins in Northern Europe and elevates recurring-revenue capture for predictive analytics providers in Ireland and Singapore.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs commissioning services. Premium tiers attach to EU AI Act resilience certification with cleared personnel requirements, while economy tiers serve bundled construction packages for secondary US markets. Price differentiation hinges on certification authority and geographic delivery cost. Cost compression in standard tiers is intensifying because hyperscale procurement teams in Phoenix and Northern Virginia are consolidating contract value. Enterprises exhibit highest price sensitivity; cloud providers with captive technical standards teams demonstrate lowest.
Supply Chain Analysis
Copper refining capacity in Chile, Germany, and China anchors power distribution testing equipment manufacturing. Precision switchgear production draws from German and Japanese component ecosystems. Raw material dependencies center on copper busbars, electrical steel, and semiconductor-based power monitoring sensors. Single-source vulnerability concentrates in precision thermal sensors sourced from Japanese suppliers. Distribution runs through construction-integrated providers and independent commissioning specialists serving hyperscale direct contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Data center testing functions as a service-attach opportunity where predictive maintenance and continuous monitoring subscriptions expand faster than one-time commissioning hardware sales. Recurring-revenue layers around digital twin platforms and automated verification pipelines are displacing project-based pricing.
For Market Incumbents: Secure ISO 22237 accreditation expansion into India before hyperscale construction peaks in Mumbai and Hyderabad. Defend margin position by deepening backward integration into copper busbar fabrication to offset commodity volatility. Channel control through exclusive partnerships with national cyber agencies for EU AI Act attack simulation protocols represents the critical lever against construction-integrated providers bundling validation services.
For New Entrants and Emerging Players: Differentiate on edge micro-facility certification protocols where standardized validation pathways for sub-500kW deployments remain undefined. Target telecommunications 5G infrastructure build-outs requiring distributed latency validation across secondary European markets. A go-to-market angle anchored in physics-based simulation platforms reduces physical burn-in duration and accelerates customer acceptance timelines.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors pure-play validation specialists with cleared personnel networks and multi-country accreditation. Long-term viability over the next decade rests on regulatory divergence between EU operational resilience frameworks and emerging US EPA efficiency guidelines creating persistent compliance demand. Acquisition target archetypes include commissioning providers with existing cyber agency partnerships. The signal to watch is NIS2 implementation friction forcing multiple compliance playbooks and delaying contract finalization.
| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Platform Deployment | Physics-based simulation reduces physical burn-in from 72 hours to 24 hours at greenfield sites. |
| Cleared Personnel Network Expansion | EU AI Act mandates sub-second failover demonstration requiring security-cleared commissioning engineers. |
| India Market Entry | Maharashtra's Navi Mumbai cluster offers first-mover positioning under digital infrastructure incentives. |
| Cyber Agency Partnership | National attack simulation protocols differentiate providers for high-risk automated system certification. |
| Copper Component Backward Integration | In-house busbar fabrication hedges commodity price swings squeezing Northern European equipment procurement. |
Study Parameters
Two parallel data streams informed the analysis: primary field engagement with commissioning engineers, hyperscale facility procurement directors, and construction-integrated provider executives; and secondary validation through Uptime Institute Tier certification databases, EU regulatory filings under NIS2 and AI Act frameworks, and hyperscaler capital expenditure disclosures. Bottom-up triangulation across service-type revenue segmentation and top-down demand modeling across deployment models ensured cross-verification.
Across the analysis window, the forecasting framework modeled service type, technology, end user, and deployment model dimensions alongside regional regulatory cluster variations. CAGRs were derived from installed base expansion rates and replacement cycle compression. Forecast inputs incorporated AI cluster thermal design power trajectories and liquid-cooled validation methodology adoption curves.
The analysis sits within stated boundaries; outcomes outside sustained hyperscale construction investment and stable copper commodity pricing would require recalibration. Forecasts reflect assumptions around EU member state harmonization of NIS2 resilience mandates and EPA efficiency guideline finalization. Practitioners should keep alternative scenarios live as regulatory divergence and commodity volatility evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Anechoic Chamber Market
Test and Measurement
Automated Optical Inspection (AOI) Equipment Market
Test and Measurement
Ultrasonic NDT Equipment Market
Test and Measurement
Insulation Testing Instrument Market
Test and Measurement
5G Testing Devices Market
Test and Measurement
Pump Testers Market
Test and Measurement
Ultrasonic Testing Equipment Market
Test and Measurement
Digital Oscilloscope Market
Test and Measurement
Automated Calibration-as-a-Service Platforms for Test and Measurement Assets Market
Test and Measurement
Global Nondestructive Testing Equipment Market
Test and Measurement
Digital Multimeter Market
Test and Measurement
Asia-Pacific Semiconductor Metrology and Inspection Market
Test and Measurement
Silicon Photonics and Optical I/O Test and Measurement Systems Market
Test and Measurement
AI-Enabled Semiconductor Defect Classification and Review Systems Market
Test and Measurement
Miniature Atomic Clock Market
Test and Measurement
Electromagnetic NDT Market