
 Automated Ultrasonic Testing Market | 2026-2036
Automated Ultrasonic Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Automated Ultrasonic Testing Market Outlook
North American inspection service providers is shifting capacity toward automated platforms capable of continuous pipeline monitoring. MISTRAS Group Inc. leverages its integrated asset protection model to bundle hardware with long-term service contracts. Baker Hughes Company anchors its position through proprietary ultrasonic array technologies purpose-built for energy infrastructure. SGS Société Générale de Surveillance SA competes on geographic reach, operating accredited laboratories across multiple continents.
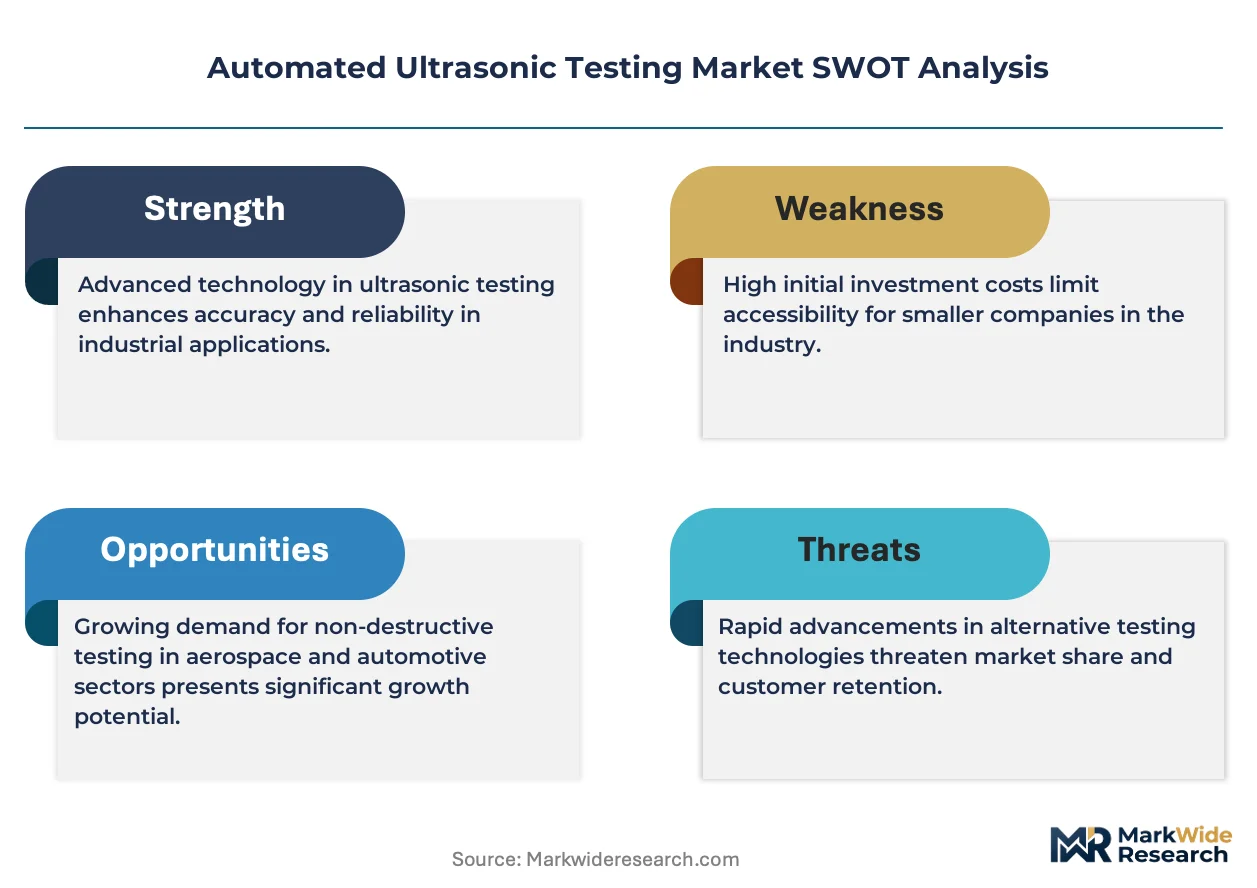
Automated ultrasonic testing deploys piezoelectric transducers emitting high-frequency mechanical waves to detect internal discontinuities in metals and composites, with typical operating frequencies ranging from 0.5 MHz to 25 MHz depending on material thickness and defect resolution requirements. The technique serves critical quality assurance functions in welding, casting, and additive manufacturing processes where structural failure carries catastrophic liability. Phased array technology commands the fastest expansion trajectory due to its electronic beam steering capability and reduced inspection cycle times. Weld inspection applications generate the largest revenue pool, though corrosion detection in aging energy infrastructure presents the most acute replacement demand. Data interpretation software represents an emerging margin concentration point as operators seek to reduce dependence on certified technician labor.
ASME Section V and ASTM E317 standards govern equipment calibration and operator qualification in the United States, while the EU Pressure Equipment Directive mandates periodic integrity verification for classified installations. The FAA's airworthiness directives for commercial aircraft impose recurring non-destructive testing obligations that automated systems increasingly satisfy. Stakeholders must evaluate how evolving AI-enabled defect recognition algorithms will reshape technician certification requirements and equipment procurement criteria.
Market Dynamics
Phased array ultrasonic technology is compressing inspection cycle times by 60-70% versus conventional methods, forcing asset operators to retire legacy equipment before full depreciation and triggering replacement demand across energy infrastructure and aerospace manufacturing.
Growth Catalysts
- ASME Boiler and Pressure Vessel Code:Tighter weld quality mandates under Section V standards compel oil and gas operators to replace manual inspection methods with automated systems capable of continuous monitoring and documented traceability.
- Composite airframe manufacturing:Aerospace OEMs in Germany and France are accelerating procurement of automated phased array systems to inspect carbon fiber layups and adhesive bonds in next-generation aircraft programs.
- Aging pipeline infrastructure:Corrosion detection requirements in North American and European energy corridors drive replacement cycles for legacy manual ultrasonic equipment with automated crawler-mounted systems.
Market Restraints
- Piezoelectric crystal supply concentration:Specialized transducer materials depend on limited suppliers in Japan and Germany, creating input cost volatility and lead time risk for equipment manufacturers.
- Technician certification bottlenecks:ASNT Level III and EN ISO 9712 qualification requirements extend deployment timelines by 12-18 months, constraining service provider capacity expansion.
- Radiographic testing substitution:Digital radiography retains preference for certain thick-section weld inspections where ultrasonic beam attenuation limits defect resolution in austenitic stainless steels.
Strategic Opportunities
- AI-enabled defect recognition:Machine learning algorithms trained on labeled discontinuity datasets are unifying data interpretation with hardware sales, reducing operator dependence and opening recurring software revenue streams.
- Additive manufacturing quality assurance:In-process automated ultrasonic monitoring of metal powder bed fusion builds represents an emerging application with limited incumbent competition.
- India infrastructure buildout:Pipeline construction and refinery expansion under the Petroleum and Natural Gas Regulatory Board create underpenetrated demand for automated inspection services.
Industry Challenges
- Multi-modal system integration:Combining ultrasonic arrays with eddy current and thermographic modules requires complex data fusion engineering that extends development cycles and strains R&D budgets.
- Legacy equipment interoperability:Retrofitting automated scanning systems onto existing manual inspection rigs demands customized mechanical interfaces that fragment production economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automated Ultrasonic Testing Market |
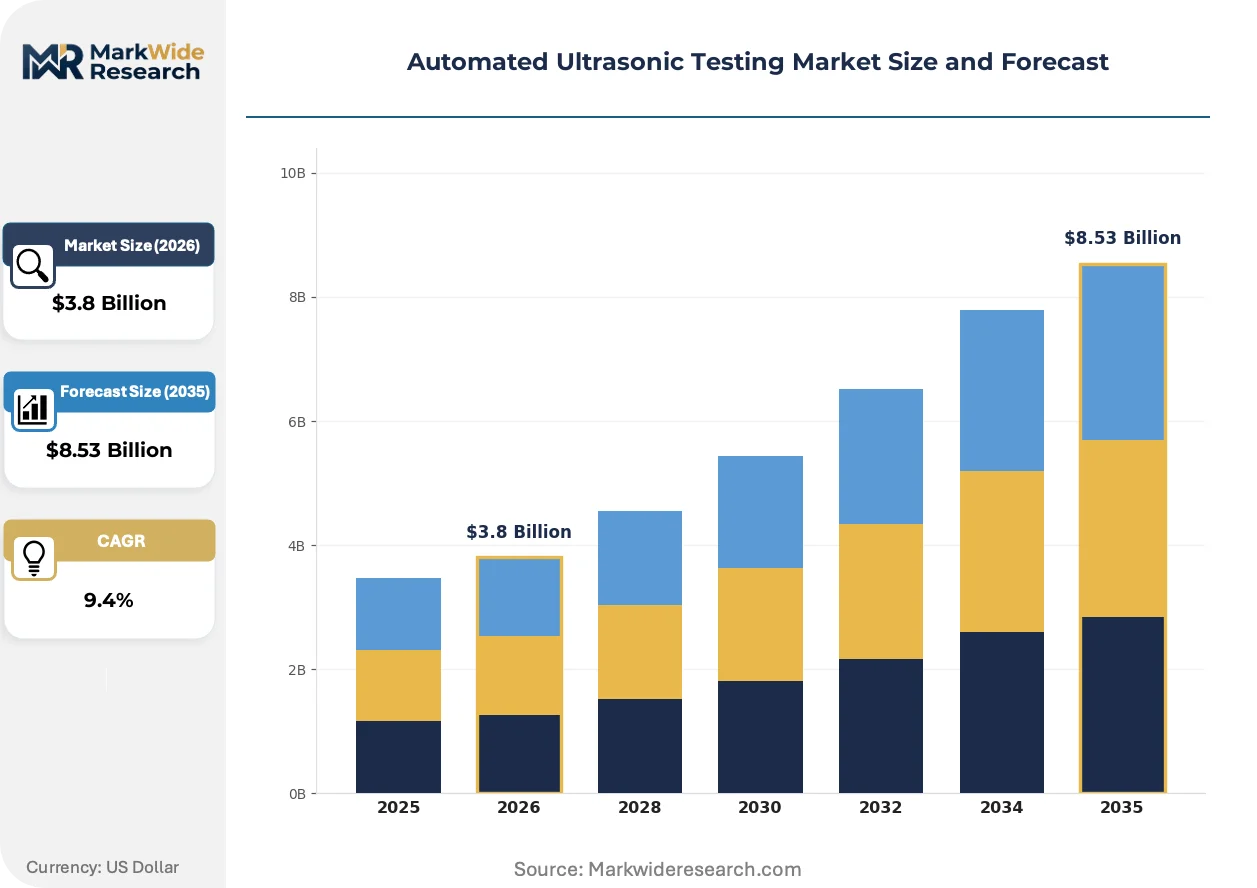
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultrasonic Flaw Detectors, Thickness Gauges, Imaging Systems, Data Interpretation Software Technology: Pulsed Echography, Time-of-Flight Diffraction, Phased Array, Ultrasonic Array End User: Aerospace, Automotive Manufacturers, Oil & Gas Companies, Power Generation Application: Weld Inspection, Corrosion Detection, Composite Material Testing, Structural Integrity Assessment |
| Companies Covered | MISTRAS Group Inc., Baker Hughes Company, SGS Société Générale de Surveillance SA, Applus+, DEKRA SE, Bureau Veritas SA, Eddyfi Technologies, Acuren, Intertek Group plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automated Ultrasonic Testing Market Strategic Shifts
Automated ultrasonic testing is converging with artificial intelligence and robotics to transform inspection from a periodic compliance activity into a continuous asset intelligence function. Three developments are compressing technology adoption cycles and reshaping competitive positioning.
Full-matrix capture with total focusing method is unifying high-resolution defect imaging with real-time processing capability. Offshore wind turbine manufacturers in Denmark and the UK are deploying these systems for full-volume blade inspection. The technology is compressing the trade-off between inspection speed and spatial resolution that previously forced operators to choose one or the other.
REACH regulation amendments restricting hexavalent chromium in corrosion protection coatings are extending inspection intervals for coated pressure vessels. European chemical operators must verify coating integrity more frequently, accelerating replacement of manual spot-checks with automated scanning protocols. German TÜV inspection bodies are certifying automated systems for these extended verification cycles.
Service contract unbundling is fragmenting the traditional hardware-plus-technician bundle. North American pipeline operators now procure automated crawler systems separately from data interpretation services, pressuring integrated vendors to compete on individual component pricing. This pattern is most visible in Texas and Alberta shale corridors where operator consolidation has concentrated buying power.
Automated Ultrasonic Testing Market Segmentation
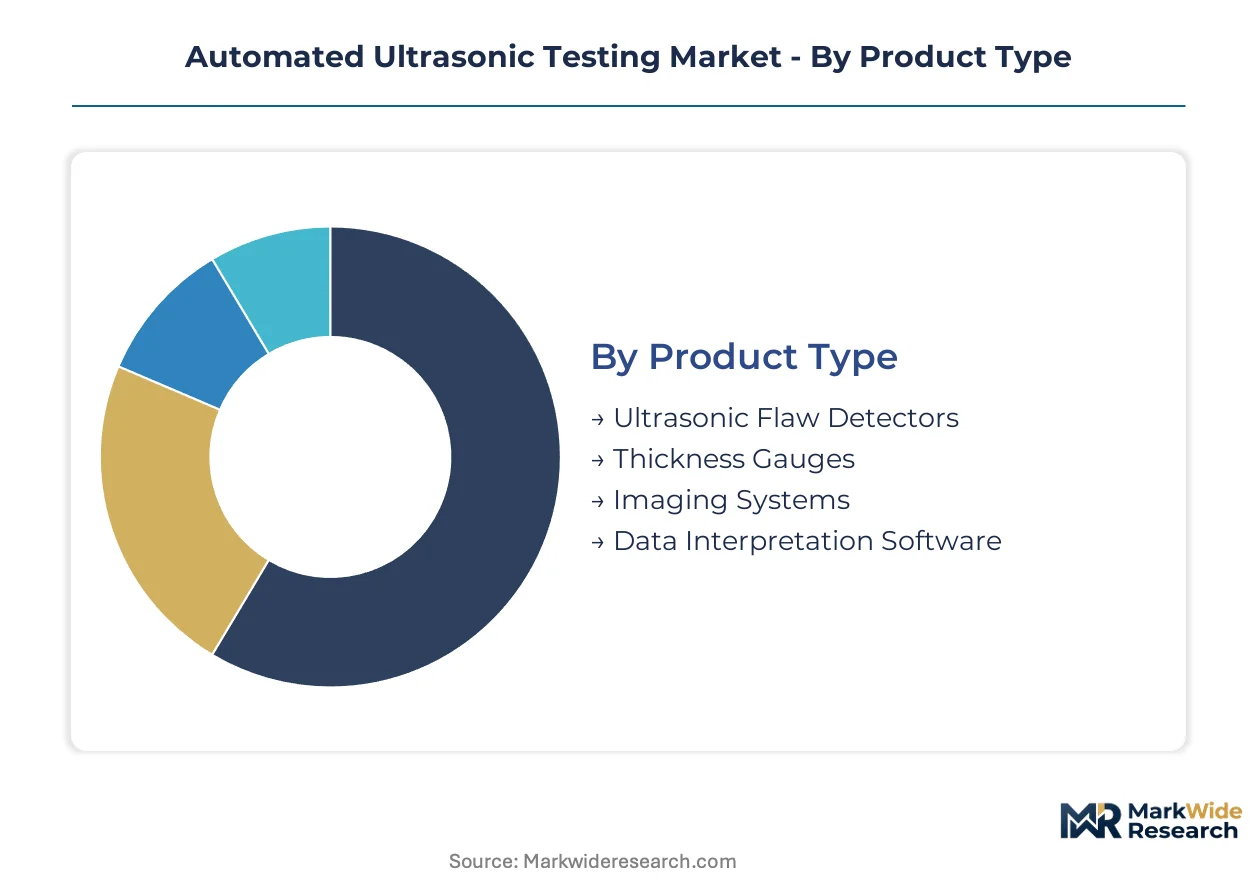
Segmentation in automated ultrasonic testing reveals divergent capital requirements across hardware, software, and service layers. Procurement patterns split between asset-intensive equipment buyers and software-centric operators seeking to reduce technician dependence.
Product Type:
Capital intensity peaks in imaging hardware, where phased array transducer arrays and scanning mechanics demand substantial upfront investment. Software segments require lower fixed costs but incur ongoing development expenditure for algorithm training and regulatory validation.
- Ultrasonic Flaw Detectors:Portable units emitting pulsed ultrasonic waves to identify cracks, voids, and inclusions in metallic structures. Demand concentrates in German automotive OEMs and pipeline operators replacing legacy manual equipment under tighter ASME weld quality mandates.
- Thickness Gauges:Single-purpose instruments measuring wall thickness loss from corrosion or erosion in pressure vessels and storage tanks. Oil and gas operators in the Permian Basin and North Sea deploy these for continuous monitoring of aging infrastructure where structural failure carries catastrophic liability.
- Imaging Systems:Advanced platforms integrating multiple transducer arrays with real-time visualization for complex geometries.
- Data Interpretation Software:Machine learning-enabled platforms automating defect classification and reducing dependence on certified technician labor.
Most installed capacity flows through Ultrasonic Flaw Detectors. Expansion is steepest in Data Interpretation Software.
Technology:
Technology selection determines inspection cycle economics, with electronic beam steering capabilities commanding premium positioning against conventional single-element approaches.
- Phased Array:Electronically controlled multi-element transducer systems enabling dynamic beam steering without mechanical movement. Aerospace manufacturers in France and Germany accelerate procurement for composite airframe inspection where reduced cycle times justify equipment premiums.
- Time-of-Flight Diffraction:Specialized technique detecting and sizing crack-like defects through diffracted wave analysis. Critical for thick-section weld inspections in nuclear power generation where precise defect sizing determines structural acceptance.
- Pulsed Echography:Conventional single-transducer approach measuring echo return time for defect location and thickness determination.
- Ultrasonic Array:Fixed-configuration multi-element systems offering simplified electronic scanning for repetitive inspection tasks.
Phased Array dominates current procurement volumes. Time-of-Flight Diffraction is gaining share fastest in safety-critical energy infrastructure.
End User:
End-user concentration varies by regulatory exposure, with aviation and energy sectors facing mandatory inspection intervals that automate procurement decisions.
- Oil & Gas Companies:Pipeline operators and refinery owners conducting continuous corrosion monitoring and weld verification. North American shale corridor consolidation concentrates buying power in Texas and Alberta, where operators unbundle hardware from service contracts to optimize component pricing.
- Aerospace:Airframe manufacturers and maintenance, repair, and overhaul facilities inspecting composite laminates and adhesive bonds. FAA airworthiness directives impose recurring non-destructive testing obligations that automated systems increasingly satisfy.
- Automotive Manufacturers:OEMs and tier suppliers validating weld quality in high-strength steel and aluminum structures.
- Power Generation:Nuclear, fossil, and renewable asset operators verifying pressure boundary integrity under ASME Boiler and Pressure Vessel Code.
Oil & Gas Companies account for the largest installed base. Aerospace is expanding most quickly as composite airframe production scales.
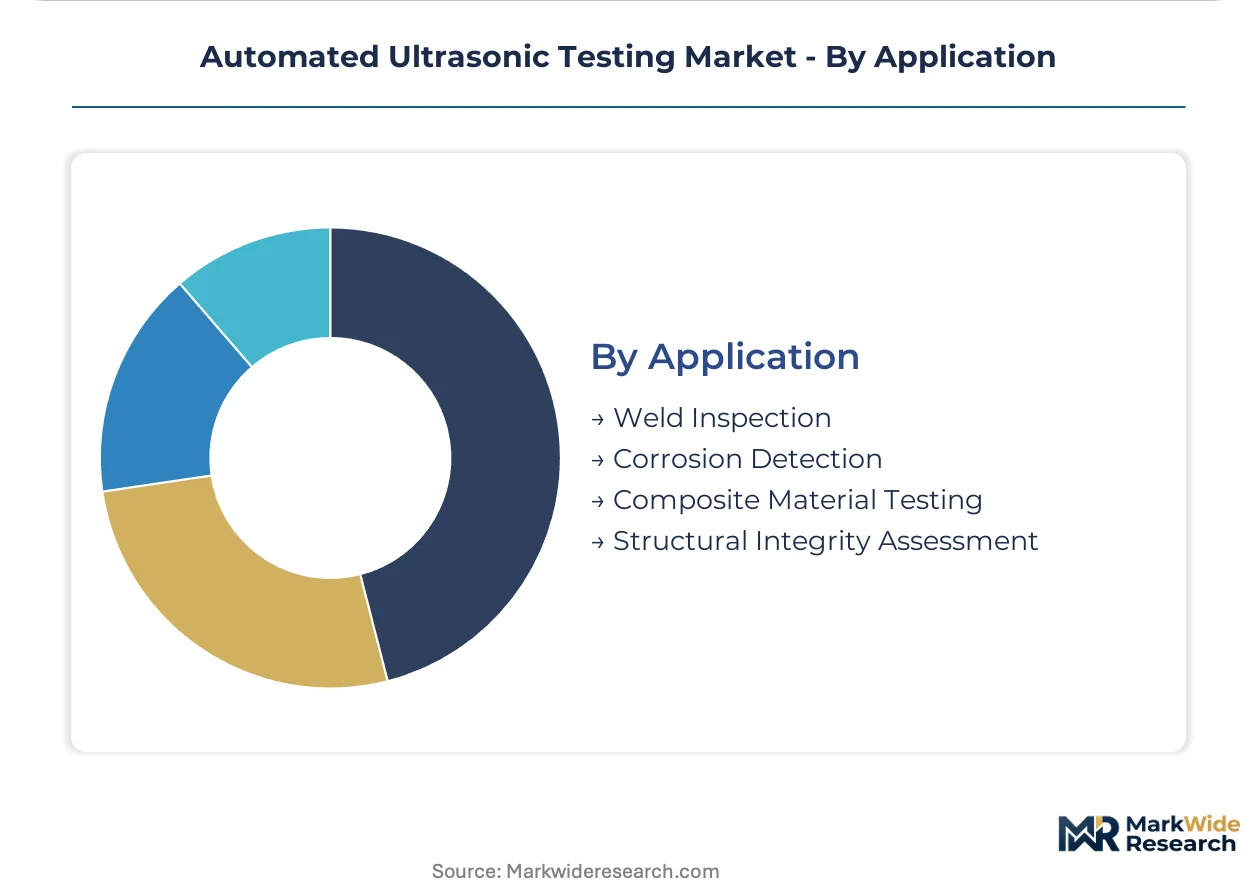
Application:
Application segmentation tracks liability exposure, with weld inspection generating consistent demand while corrosion detection presents acute replacement cycles in aging infrastructure.
- Weld Inspection:Quality assurance for fusion and solid-state welds in pressure vessels, pipelines, and structural components. ASME Section V standards compel documented traceability that automated systems provide, driving replacement of manual methods across energy infrastructure.
- Corrosion Detection:Monitoring wall thickness loss in pipelines, storage tanks, and process equipment. Aging North American and European energy corridors trigger replacement demand for legacy manual equipment with automated crawler-mounted systems.
- Composite Material Testing:Delamination and void detection in carbon fiber reinforced polymers for aerospace and wind energy.
- Structural Integrity Assessment:Comprehensive evaluation of bridges, offshore platforms, and civil infrastructure.
Weld Inspection represents the largest revenue pool. Corrosion Detection is climbing the fastest as infrastructure age profiles deteriorate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping equipment procurement patterns as asset operators migrate inspection budgets toward jurisdictions with harmonized certification standards and concentrated infrastructure replacement cycles. Compliance cost differentials between ASME-governed North American markets and EU Pressure Equipment Directive jurisdictions are compressing as both regions tighten weld quality mandates.
United States
FAA airworthiness directives and ASME Section V standards drive automated system deployment across aerospace manufacturing clusters and energy infrastructure corridors. Pipeline operators in Texas and the Permian Basin unbundle hardware procurement from service contracts, concentrating buying power among consolidated shale producers. Houston-based inspection service providers are shifting capacity toward automated crawler systems for continuous corrosion monitoring.
Germany
Automotive OEMs and pipeline operators jointly accelerate replacement cycles for legacy manual equipment under REACH-regulated coating inspection protocols. TÜV inspection bodies certify automated phased array systems for extended verification cycles mandated by amended corrosion protection standards. Bavarian aerospace suppliers and Ruhr industrial corridor operators represent the densest concentration of procurement activity.
China
MIIT industrial upgrading directives and GB standards for pressure equipment integrity are compelling state-owned pipeline operators to replace manual inspection methods. Yangtze River Delta manufacturing clusters deploy automated ultrasonic systems for weld quality assurance in high-speed rail and shipbuilding production. Shanghai and Jiangsu province house the primary concentration of domestic equipment fabrication capacity.
France
ANSM-equivalent pressure equipment regulators and aerospace manufacturing standards under EASA frameworks mandate recurring non-destructive testing obligations. Toulouse and Bordeaux aerospace clusters accelerate procurement of automated phased array systems for composite airframe inspection. EDF nuclear fleet operators deploy time-of-flight diffraction systems for thick-section weld verification under ASN safety requirements.
United Kingdom
North Sea energy infrastructure aging and offshore wind turbine manufacturing are driving automated crawler system deployment for corrosion detection. HSE pressure systems regulations and BEIS energy transition programs fund inspection equipment modernization. Aberdeen energy service providers and Hull offshore wind manufacturing facilities concentrate procurement demand.
Automated Ultrasonic Testing Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue AI-enabled software unbundling and additive manufacturing quality assurance applications. The market structure splits between integrated asset protection vendors bundling hardware with long-term service contracts, and specialized equipment manufacturers competing on transducer array performance. Three archetypes dominate: inspection service conglomerates leveraging geographic reach, energy-focused technology developers anchoring through proprietary array designs, and software-centric entrants reducing operator dependence through machine learning. Consolidation pressure is intensifying as operators unbundle procurement, while technology licensing agreements proliferate between hardware manufacturers and algorithm developers.
Within the integrated service tier, MISTRAS Group Inc. and Baker Hughes Company exemplify divergent strategic positioning. MISTRAS represents the bundled asset protection model combining equipment deployment with multi-year service contracts. Baker Hughes anchors the energy infrastructure specialization vector through its Houston-based technology development focus. SGS Société Générale de Surveillance SA occupies the geographic reach archetype, with its Geneva-based structure supporting accredited laboratory networks across multiple continents. These three patterns illustrate how competitive positioning fragments across service integration, technology specialization, and geographic scale vectors.
| Leading Market Players |
|---|
| MISTRAS Group Inc. |
| Baker Hughes Company |
| SGS Société Générale de Surveillance SA |
| Applus+ |
| DEKRA SE |
| Bureau Veritas SA |
| Eddyfi Technologies |
| Acuren |
| Intertek Group plc |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up inspection service specialists concentrate equipment procurement power across Texas and Alberta shale corridors, compressing hardware margins while elevating long-term service contract premiums. This ownership pattern tightens pricing discipline for phased array transducer arrays and scanning mechanics, as consolidated buyers unbundle component sourcing from data interpretation services.
Pricing Analysis
Distributor margin compression runs through the automated ultrasonic testing equipment channel, with direct-to-OEM volume discounts reaching 15-25 points below list for multi-unit pipeline crawler deployments. Three-tier pricing structure across premium, standard, and economy levels separates FAA-certified aerospace systems from uncertified industrial units, with ASME Section V compliance tiers commanding mid-market positioning. Cost compression in standard-grade flaw detectors is intensifying because Japanese piezoelectric crystal supply constraints feed input volatility into transducer manufacturing. Oil and gas operators in the Permian Basin exhibit highest price sensitivity, while German automotive OEMs prioritize inspection cycle time over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with specialized piezoelectric crystal suppliers concentrated in Japan and Germany, where Murata Manufacturing and CeramTec anchor global transducer material flows. Manufacturing capacity for phased array electronics clusters in the United States, China, and Germany, with final assembly drawing from precision machining networks in Switzerland and South Korea. Logistics chokepoint risk concentrates in semiconductor-grade analog-to-digital converters sourced from Taiwanese foundries. Distribution runs through authorized equipment distributors serving North American energy corridors and direct sales forces penetrating German automotive and French aerospace manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automated ultrasonic testing equipment procurement arbitrage opportunities emerge between ASME-governed North American markets and EU Pressure Equipment Directive jurisdictions, where certification cost differentials compress as both regions tighten weld quality mandates but diverge in technician qualification timelines.
For Market Incumbents: Deepen backward integration into piezoelectric crystal supply through captive sourcing agreements with Japanese specialty ceramics producers, insulating margin structures from input volatility. Expand ASNT Level III certification pipeline capacity in Houston and Calgary to reduce technician deployment bottlenecks that constrain service contract fulfillment. Defend against AI-enabled software entrants by bundling hardware with proprietary defect recognition algorithms trained on proprietary discontinuity datasets. For New Entrants and Emerging Players: Enter via additive manufacturing quality assurance applications, where in-process monitoring of metal powder bed fusion builds presents white-space demand with limited incumbent competition. Target Indian pipeline construction and refinery expansion under Petroleum and Natural Gas Regulatory Board mandates, where domestic equipment fabrication capacity lags infrastructure buildout timelines. Pursue software-first go-to-market positioning, licensing machine learning defect classification to established hardware vendors rather than competing on transducer array manufacturing. For Investors and Strategic Acquirers: Energy infrastructure technology developers represent the most active acquirer in this space, seeking automated inspection capabilities to bundle with existing asset protection service portfolios. Long-term viability hinges on regulatory enforcement durability for continuous monitoring mandates across aging pipeline networks and composite airframe production scaling. Acquisition target archetype: software-centric defect recognition platforms with validated training datasets and regulatory approval pathways. Watch for FAA airworthiness directive amendments mandating AI-assisted inspection as inflection indicator for technician certification requirement displacement.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Enabled Defect Recognition Development | Machine learning algorithms trained on labeled discontinuity datasets reduce operator dependence and open recurring software revenue streams. |
| Phased Array Transducer Manufacturing Scale-Up | Domestic production capacity expansion in China and Germany addresses lead time risk from Japanese piezoelectric crystal supply concentration. |
| ASNT Level III Certification Pipeline Investment | Accelerated technician qualification programs in Houston and Calgary compress deployment bottlenecks constraining service provider capacity. |
| Additive Manufacturing Quality Assurance Partnership | In-process monitoring collaborations with metal powder bed fusion equipment OEMs capture emerging application demand. |
| Long-Term Service Contract Unbundling | Separate hardware procurement from data interpretation services to align with North American pipeline operator buying power consolidation. |
Study Parameters
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region's energy infrastructure corridors and aerospace manufacturing clusters. The approach combines structured interviews with NDT service company executives, plant engineers at oil and gas operators, procurement leads at German automotive OEMs, and FAA certification specialists, validated against secondary sources including ASME Boiler and Pressure Vessel Code filings, FAA airworthiness directive databases, EASA certification records, and EU Pressure Equipment Directive implementation reports. Bottom-up equipment shipment data triangulates with top-down inspection service revenue estimates.
Granularity-level modeling disaggregates revenue across hardware, software, and service layers, with technology segmentation distinguishing phased array, time-of-flight diffraction, and conventional pulsed echography approaches. End-user demand is projected across oil and gas, aerospace, automotive, and power generation verticals, incorporating application-specific inspection cycle economics for weld verification and corrosion detection. CAGRs derive from equipment replacement timelines tied to regulatory mandate enforcement and infrastructure age profiles. Forecast inputs include pipeline mileage under ASME jurisdiction, composite airframe production scaling at Airbus and Boeing suppliers, and REACH-regulated coating inspection interval extensions.
Inputs from equipment manufacturers and inspection service providers were available through the study window; gaps in real-time procurement transaction data introduce uncertainty bands around hardware pricing trajectories. Forecasts reflect assumptions regarding regulatory enforcement continuity for continuous monitoring mandates and technician certification requirement evolution under AI-enabled defect recognition adoption. Specific risk factors that could revise projections include piezoelectric crystal supply disruption, radiographic testing technology substitution in thick-section austenitic steel applications, and multi-modal system integration delays. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Force Gauge Market
Test and Measurement
Compression Testers Market
Test and Measurement
Burn-In and System-Level Test (SLT) Platforms for AI Accelerators Market
Test and Measurement
VXI Testing Equipment Market
Test and Measurement
EMC Shielding and Test Equipment Market
Test and Measurement
Photometer and Calorimeter Market
Test and Measurement
Non-Destructive Testing (NDT) Software Market
Test and Measurement
Asia-Pacific Electronic Test and Measurement Market
Test and Measurement
Moisture Analyzer Market
Test and Measurement
Semiconductor Metrology and Inspection Market
Test and Measurement
Density Tester Market
Test and Measurement
Product Design Verification and Validation Solution Market
Test and Measurement
Network Tester Market
Test and Measurement
Nanomechanical Testing Market
Test and Measurement
Global Arbitrary Waveform Generator Market
Test and Measurement
Psophometer Market