
 Digital Moisture Meters Market | 2026-2036
Digital Moisture Meters Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Moisture Meters Market Insights
Polymer sensor housings are shifting toward bio-based alternatives as manufacturers seek to reduce unit costs and meet sustainability procurement criteria. Delmhorst Instrument Co. leverages its vertically integrated production in North America to control component quality across its portable device lines. Wagner Meters differentiates through proprietary electromagnetic wave technology that eliminates surface damage during wood moisture assessment. Testo SE & Co. KGaA anchors its position in European building inspection channels with integrated data-logging capabilities.
Digital moisture meters are electronic instruments that measure the percentage of water content in solids, liquids, or gases using electrical resistance, capacitance, or radio frequency detection, typically displaying readings on LCD or LED screens with accuracy ranges of 0.1% to 1% depending on substrate. These devices serve critical quality-control functions across agriculture, construction, and food manufacturing where moisture deviations compromise structural integrity, spoilage rates, or crop yield optimization. Capacitive meters dominate the product landscape for non-destructive testing in woodworking and building inspection, while wireless connectivity represents the fastest-expanding technology segment as contractors and agricultural professionals demand real-time data transmission to cloud-based farm management platforms. Smart sensors command premium positioning due to embedded calibration algorithms and IoT integration, though portable devices retain volume leadership among homeowner and small-contractor segments where cost sensitivity shapes procurement decisions.
The U.S. EPA and FDA jointly influence moisture meter specifications through environmental testing protocols and food safety moisture-content thresholds that manufacturers must certify against for commercial viability. The EU Green Deal and REACH chemical restrictions are reshaping material compositions in sensor manufacturing, particularly affecting RF meter production lines that rely on specialized coatings and substrates. Stakeholders should monitor evolving interoperability standards between smart sensor platforms and enterprise agricultural software systems, as ecosystem compatibility will determine which technology vendors capture recurring service revenue beyond hardware sales.
Market Dynamics
Wireless connectivity standards are fragmenting procurement patterns across agricultural and construction end-uses, forcing manufacturers to prioritize interoperability certifications over hardware differentiation.
Growth Catalysts
- EU Green Deal sustainability mandates:Food processing facilities across Germany and France must install precision moisture-control systems to meet waste-reduction targets, tightening equipment specifications.
- Capacitive non-destructive testing:Woodworking and building inspection segments favor electromagnetic wave methods that eliminate surface damage during quality assessment.
- Central European precision agriculture corridor:Soil monitoring adoption concentrates in Germany's Rhine-Ruhr and adjacent Dutch-German border regions where large-scale farming cooperatives dominate.
Market Restraints
- Specialized polymer substrate costs:REACH chemical restrictions on conventional sensor housings force bio-based material transitions that raise unit production expenses.
- RF component supply concentration:Electromagnetic wave meter production depends on Asian substrate coating suppliers, creating input vulnerability.
- Calibration algorithm limitations:Embedded smart sensors require substrate-specific training datasets that constrain multi-material versatility.
Strategic Opportunities
- Eastern European agricultural modernization:Poland and Romania present underpenetrated demand for wireless-enabled soil monitoring among emerging large-scale farming operations.
- IoT-cloud convergence:Real-time data transmission to farm management platforms creates recurring service revenue streams beyond hardware margins.
- Building energy efficiency retrofits:Germany's federal building codes now mandate moisture inspection prior to insulation upgrades, expanding inspection service demand.
Industry Challenges
- Electromagnetic compatibility certification:Multi-frequency RF meters face prolonged FCC and CE marking timelines that delay product launches.
- Legacy equipment integration:Agricultural software platforms lack standardized APIs, complicating smart sensor deployment for mixed-fleet operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Moisture Meters Market |
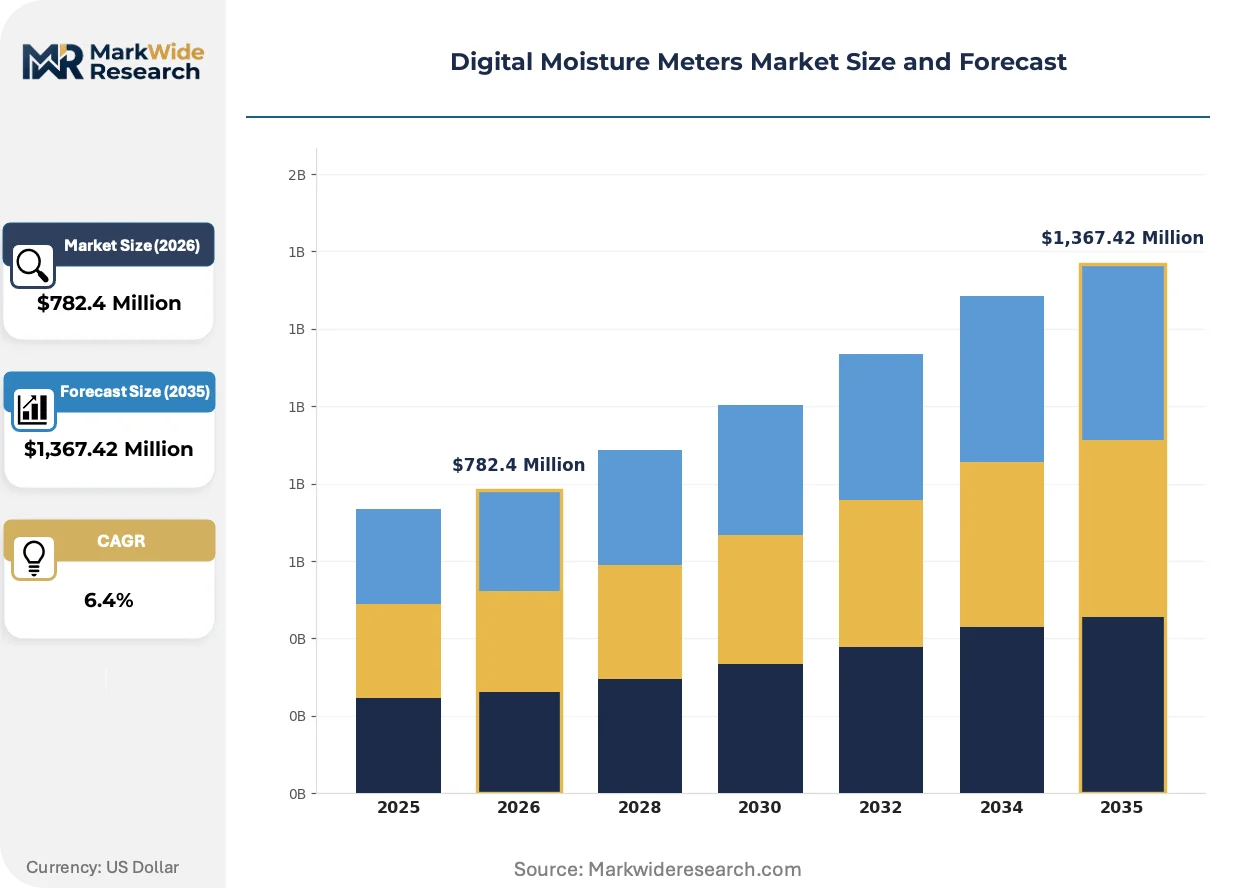
| Market Size in 2026 | $782.4 Million |
| Market Size in 2035 | $1,367.42 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capacitive Meters, Resistive Meters, RF Meters, Laser Meters Application: Agriculture, Building Inspection, Food Processing, Woodworking Technology: Digital Display, Wireless Connectivity, Portable Devices, Smart Sensors End User: Agricultural Professionals, Contractors, Food Manufacturers, Homeowners |
| Companies Covered | Delmhorst Instrument Co., General Tools & Instruments LLC, Extech Instruments, Protimeter, Tramex Ltd., Wagner Meters, Testo SE & Co. KGaA, PCE Instruments, Mettler-Toledo International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Moisture Meters Market Trends and Innovations
Sensor miniaturization and cloud architecture are compressing the value chain, shifting competitive advantage from hardware precision to data-platform stickiness.
Mesh-networked soil sensors is decentralizing farm-level moisture monitoring by enabling peer-to-peer data relay without cellular infrastructure. Agricultural cooperatives in Germany's Lower Saxony region are deploying these systems across fragmented land holdings. This topology is decentralizing equipment procurement decisions from centralized farm managers to individual plot operators.
REACH chemical restrictions are forcing reformulation of RF meter substrate coatings and polymer sensor housings. Manufacturers must certify alternative bio-based materials against electromagnetic performance benchmarks. Wood moisture assessment equipment faces the tightest compliance timeline, with German producers accelerating R&D spending.
Buyer consolidation among European food processing conglomerates is compressing vendor negotiation cycles and demanding outcome-based equipment performance guarantees. Mid-sized moisture meter distributors are losing share to direct manufacturer relationships. This pattern is most visible in France's dairy processing belt and northern Italy's pasta manufacturing clusters.
Digital Moisture Meters Market Segmentation
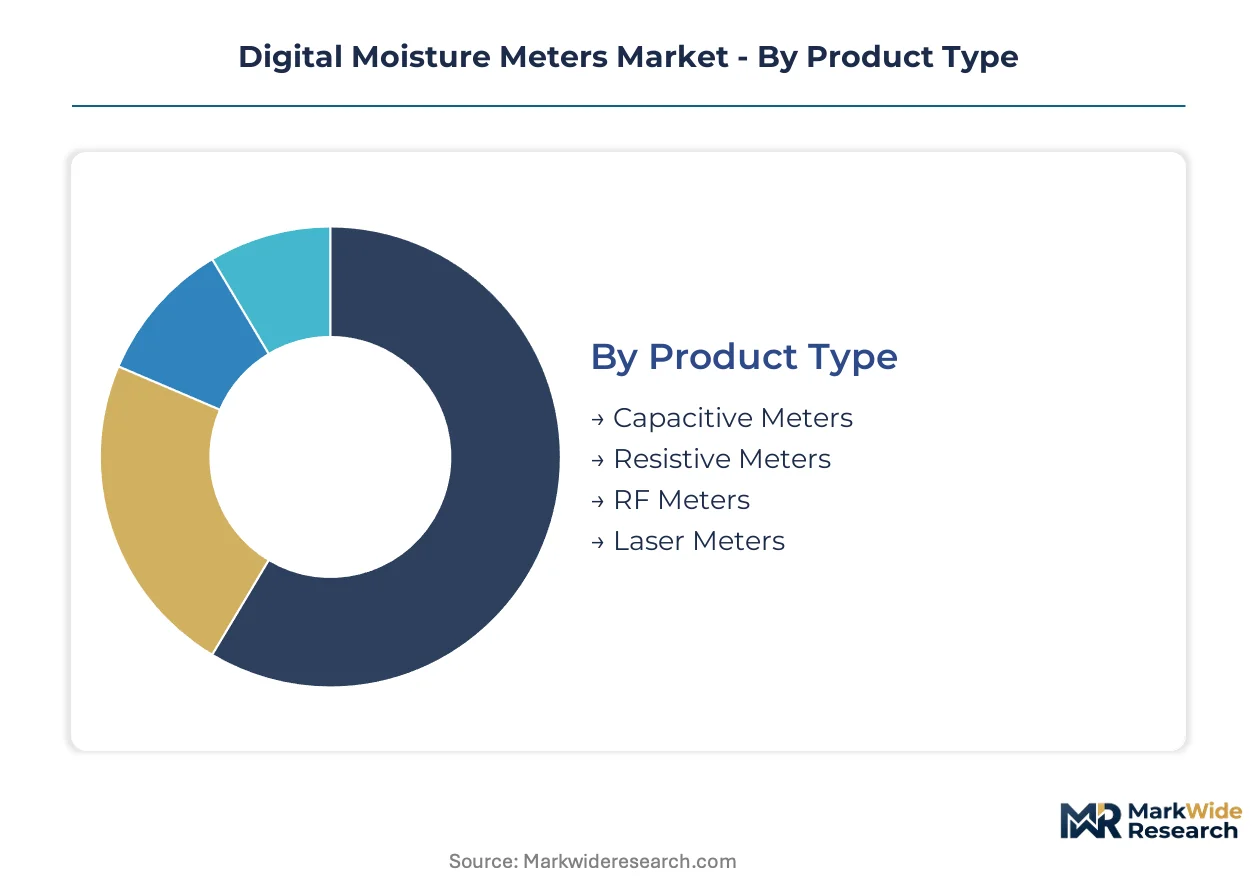
Buyer procurement patterns in digital moisture meters diverge sharply across end-use contexts, with agricultural cooperatives prioritizing wireless telemetry while woodworking specialists demand electromagnetic precision. Understanding these segment-specific decision drivers reveals where technology investments concentrate and where margin compression threatens hardware-only vendors.
Product Type:
Cost tier shapes procurement volume, with premium electromagnetic units commanding agricultural budgets while economy resistive models serve intermittent home use.
- Capacitive Meters:Electromagnetic wave detection enables non-destructive substrate assessment without surface penetration. Woodworking shops in Germany's Black Forest region and building inspection services across the Rhine-Ruhr corridor specify these units for finished material evaluation where cosmetic damage voids commercial value.
- Resistive Meters:Pin-based electrical resistance measurement provides economical moisture quantification for rough lumber and raw agricultural commodities. Small-scale French vineyard operators and Polish grain cooperatives favor these units for pre-drying moisture checks where surface marking carries no commercial penalty.
- RF Meters:Radio frequency detection penetrates dense substrates for deep moisture profiling in structural timber and bulk grain storage.
- Laser Meters:Optical absorption spectroscopy targets specialized pharmaceutical and precision electronics manufacturing environments.
Volume sits with Resistive Meters; growth tilts toward Capacitive Meters.
Application:
Application maturity determines pricing elasticity, with established building inspection segments accepting premium hardware while emerging precision agriculture deployments demand bundled service models.
- Agriculture:Soil moisture monitoring and post-harvest grain conditioning drive demand for wireless-enabled units with cellular data transmission. Germany's Lower Saxony farming cooperatives and Dutch-German border operations deploy mesh-networked sensor arrays across fragmented land holdings to optimize irrigation scheduling and reduce spoilage.
- Building Inspection:Pre-renovation moisture assessment and energy retrofit compliance inspections concentrate demand in Germany's federal building code enforcement zones. Inspectors in Berlin and Munich metropolitan areas require electromagnetic non-destructive units to evaluate historic timber structures and pre-insulation substrate conditions.
- Food Processing:Inline moisture control for pasta manufacturing and dairy powder production operates under EU Green Deal waste-reduction mandates.
- Woodworking:Kiln-drying optimization and finished product quality assurance sustain steady replacement demand among Central European furniture producers.
Revenue concentrates in Building Inspection; steepest expansion trajectory belongs to Agriculture.
Technology:
Customer type dictates connectivity requirements, with enterprise agricultural operators demanding cloud integration while residential buyers prioritize standalone simplicity.
- Wireless Connectivity:Real-time data transmission to farm management platforms enables predictive irrigation algorithms and automated drying cycle adjustments. Large-scale farming operations in Germany's precision agriculture corridor specify these units for integration with existing enterprise software ecosystems.
- Smart Sensors:Embedded calibration algorithms and substrate-specific training datasets automate measurement accuracy across varying material densities. Food processing conglomerates in France's dairy belt and northern Italy's pasta manufacturing clusters specify these units for outcome-based performance guarantees.
- Digital Display:LCD and LED readout interfaces dominate economy-tier portable devices for cost-sensitive contractor segments.
- Portable Devices:Battery-powered handheld units serve homeowner and small-contractor segments where mobility outweighs connectivity requirements.
Unit shipments favor Portable Devices; margin expansion concentrates in Wireless Connectivity.
End User:
Supply concentration aligns with procurement scale, with consolidated food manufacturers negotiating direct manufacturer relationships while fragmented contractor bases sustain distributor networks.
- Agricultural Professionals:Large-scale cooperatives and commercial farming operations in Germany, the Netherlands, and emerging Polish markets drive demand for wireless soil monitoring infrastructure. These buyers specify interoperability certifications with existing farm management platforms and prioritize recurring service revenue models over hardware transactions.
- Food Manufacturers:Consolidated European dairy and pasta processing conglomerates demand precision inline moisture control systems to meet EU Green Deal sustainability targets. These buyers compress vendor negotiation cycles and require outcome-based equipment performance guarantees that shift operational risk to suppliers.
- Contractors:Building inspection and renovation specialists across German cities sustain mid-tier equipment replacement cycles.
- Homeowners:DIY woodworking and residential moisture assessment generates economy-tier portable device demand.
Procurement volume aggregates with Contractors; value capture tilts toward Agricultural Professionals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Germany's precision agriculture corridor and adjacent Central European markets, with agricultural cooperatives driving wireless-enabled soil monitoring adoption. The EU Green Deal's sustainability mandates are tightening moisture-control requirements across food processing facilities. Regulatory fragmentation between CE marking and FCC certification timelines creates divergent product launch strategies.
Germany
Large-scale farming cooperatives in Lower Saxony and the Rhine-Ruhr corridor deploy mesh-networked sensor arrays for irrigation optimization. REACH chemical restrictions force reformulation of RF meter substrate coatings, accelerating R&D spending among domestic producers. Berlin and Munich metropolitan areas sustain building inspection demand for electromagnetic non-destructive units under federal energy retrofit codes.
France
Dairy processing conglomerates in the northern dairy belt demand precision inline moisture control systems to meet EU Green Deal waste-reduction targets. ECHA compliance timelines pressure manufacturers to certify alternative bio-based sensor housings. The pasta manufacturing clusters of northern Italy's proximity influences cross-border procurement patterns for outcome-based equipment guarantees.
Poland
Emerging large-scale farming operations present underpenetrated demand for wireless-enabled soil monitoring infrastructure. EU structural funds support agricultural modernization programs accelerating technology adoption. Grain cooperatives favor resistive meters for pre-drying moisture checks where surface marking carries minimal commercial penalty.
Netherlands
Dutch-German border operations integrate moisture monitoring with existing enterprise farm management platforms requiring interoperability certifications. Wageningen University's agricultural research ecosystem influences early adoption of predictive irrigation algorithms. Glasshouse horticulture clusters specify smart sensors with embedded calibration for substrate-specific growing media.
United States
The EPA and FDA jointly influence moisture meter specifications through environmental testing protocols and food safety moisture-content thresholds. FCC electromagnetic compatibility certification timelines delay multi-frequency RF meter product launches. Pacific Northwest timber operations and Southeast agricultural belts sustain divergent demand patterns for portable versus connected devices.
Digital Moisture Meters Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium electromagnetic specialists commanding agricultural budgets while economy resistive assemblers serve intermittent home use. The vendor base organizes around three archetypes: vertically integrated North American producers controlling component quality, European technology licensors with proprietary wave detection methods, and Asian scale fabricators supplying RF substrate coatings. Capacity expansion and strategic partnerships represent the dominant competitive moves as manufacturers seek to secure constrained polymer sensor housing supply.
Within the branded specialist tier, Delmhorst Instrument Co. and Wagner Meters occupy positions exemplifying divergent integration strategies, while Testo SE & Co. KGaA anchors European building inspection channels through integrated data-logging capabilities. These companies represent archetypes of geographic production control, proprietary technology licensing, and software-platform integration respectively. PCE Instruments and Mettler-Toledo International Inc. sit within the precision instrumentation segment where calibration algorithm sophistication determines competitive positioning. General Tools & Instruments LLC and Extech Instruments exemplify the mid-tier portable device segment where cost sensitivity shapes procurement decisions among contractor and homeowner end users.
| Leading Market Players |
|---|
| Delmhorst Instrument Co. |
| General Tools & Instruments LLC |
| Extech Instruments |
| Protimeter |
| Tramex Ltd. |
| Wagner Meters |
| Testo SE & Co. KGaA |
| PCE Instruments |
| Mettler-Toledo International Inc. |
| Others |
Pricing and Supply Chain Analysis
RF substrate coating costs from Asian suppliers cascade through electromagnetic meter production lines into premium-tier agricultural equipment pricing, while REACH-mandated bio-based polymer transitions compress margins across mid-market portable device segments serving European contractor demand.
Pricing Analysis
Volume concentrates in resistive pin-based units where Polish grain cooperatives and French vineyard operators drive procurement, while margin capture tilts toward smart sensor platforms with embedded calibration algorithms that German agricultural cooperatives specify for mesh-networked deployments. Three-tier pricing structure across premium electromagnetic, standard capacitive, and economy resistive levels separates buyers by certification requirements and interoperability specifications. Pricing pressure stems from bio-based material cost premiums forced by ECHA compliance timelines, with food processing conglomerates in France's dairy belt least sensitive due to outcome-based performance guarantees while homeowner segments face acute cost compression.
Supply Chain Analysis
Regional distribution centers in Germany's Rhine-Ruhr corridor and Rotterdam port zones anchor hub-and-spoke patterns for Central European agricultural equipment deployment. Manufacturing concentrates in Germany for precision electromagnetic units, China for RF substrate coatings, and Taiwan for specialized sensor components. Supply chain risk centers on single-source vulnerability for Asian substrate coating suppliers that electromagnetic wave meter production draws from. Distribution runs through direct manufacturer relationships with consolidated food processing conglomerates and specialized agricultural distributors serving fragmented farming cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bio-based polymer sensor housing capacity constraints prop pricing power for manufacturers with certified alternative material pipelines, creating supply-constrained conditions that favor incumbents with upstream R&D investments.
For Market Incumbents: Anchor market position through captive supply of REACH-compliant bio-based sensor housings and proprietary electromagnetic wave calibration datasets that emerging Asian competitors cannot replicate. Defend against mid-tier portable device margin erosion by consolidating distributor relationships in Germany's building inspection channels and accelerating FCC certification timelines for multi-frequency RF meter launches.
For New Entrants and Emerging Players: Capture white-space opportunity in Poland's emerging large-scale farming operations where wireless-enabled soil monitoring infrastructure remains underdeployed relative to German precision agriculture corridors. Target Romanian agricultural modernization programs with resistive meter offerings for grain cooperatives before incumbent smart sensor platforms establish interoperability standards. Pursue direct relationships with Eastern European farming cooperatives bypassing established distributor networks.
For Investors and Strategic Acquirers: ECHA's accelerated bio-based material compliance timelines are the leading indicator that sensor housing manufacturing capabilities will command acquisition premiums across the medium-term horizon. Target vertically integrated producers with in-house polymer formulation expertise and established CE marking pathways. Monitor FCC electromagnetic compatibility certification backlogs as a signal for which technology licensors face product launch delays that create distressed asset opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Bio-Based Material Certification | ECHA compliance timelines force accelerated R&D spending among German producers to secure housing supply. |
| Mesh Network Platform Integration | Interoperability certifications with Wageningen-influenced farm management software ecosystems capture recurring revenue. |
| Direct Channel Consolidation | Bypassing mid-sized distributors for France-Italy food processing conglomerates compresses negotiation cycles. |
| RF Component Supply Security | Alternative substrate coating supplier qualification reduces Asian single-source vulnerability for electromagnetic meters. |
| Smart Sensor Algorithm Development | Substrate-specific training datasets automate measurement accuracy across varying agricultural material densities. |
Research Methodology
Trade association publications, ECHA regulatory filings, and agricultural equipment customs records formed the secondary backbone, supplemented by primary interviews with precision agriculture technology directors, food processing plant engineers, building inspection service operators, and polymer sensor housing procurement leads at tier-one manufacturers. Bottom-up and top-down triangulation validated segment-level demand estimates against equipment shipment data and farm management platform integration disclosures.
Bottom-up modeling anchored volume projections in installed base replacement cycles and agricultural cooperative technology adoption surveys, while top-down analysis cross-checked against EU structural fund allocations for Eastern European modernization programs. Segmentation dimensions included product type, application context, connectivity technology, and end-user procurement scale. CAGRs were derived from regression analysis of historical equipment pricing trajectories and bio-based material cost curves across the projection horizon.
The model holds under stable REACH enforcement timelines and continued EU Green Deal waste-reduction mandate expansion; deviation in ECHA compliance acceleration or agricultural subsidy program suspensions would shift trajectory. Forecasts reflect documented assumptions about interoperability standard convergence and RF component supply continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Failure Analysis Equipment Market
Test and Measurement
Sound Level Meter Market
Test and Measurement
Durometer Calibration Service Market
Test and Measurement
Wi-Fi Test Equipment Market
Test and Measurement
High-Aspect-Ratio 3D NAND Metrology Equipment Market
Test and Measurement
Liquid Immersion Cooling Fluid Compatibility Test Equipment Market
Test and Measurement
Hour Meter Market
Test and Measurement
Chiplet Integration and Die-to-Die Interconnect Test Solutions Market
Test and Measurement
Eddy Current Testing Market
Test and Measurement
Europe Signal Generator Market
Test and Measurement
Permeation Testing Machines Market
Test and Measurement
Hybrid Supercapacitor Lifetime and Safety Test Equipment Market
Test and Measurement
Rohs Tester Market
Test and Measurement
Fiber Optic Tester Market
Test and Measurement
Wafer Testing Services Market
Test and Measurement
Nanomechanical Testing Market