
 Enterprise Server Market | 2026-2036
Enterprise Server Market Size, Share, and Industry Trends Forecast 2026-2036
Enterprise Server Market Intelligence
Cloud service provider procurement is decoupling from traditional enterprise server refresh cycles as AI training workloads reshape capacity planning. Dell Technologies dominates rack server manufacturing scale across North American supply chains. Nvidia Corporation leads accelerated computing architectures for generative AI inference. HPE sustains blade server specialization in financial services verticals.
An enterprise server is a high-availability computing system engineered with redundant power supplies, error-correcting memory, and multi-socket processor architectures designed for continuous 24/7 operation in centralized data environments. Rack servers occupy the largest installed base due to standardization and density economics, while density-optimized servers represent the fastest-expanding category as liquid-cooled designs address thermal constraints in AI clusters. Blade servers retain margin concentration in regulated industries requiring chassis-level management and physical security isolation.
EPA ENERGY STAR specifications and EU Ecodesign requirements constrain idle power thresholds, while FCC electromagnetic emissions standards govern chassis shielding for US deployments. NIST cybersecurity frameworks increasingly mandate hardware root-of-trust implementations, altering motherboard firmware architectures. Stakeholders must monitor how sovereign cloud regulations fragment certification requirements across national procurement regimes.
Market Dynamics
AI training clusters are compressing server refresh cycles from five-year enterprise norms to eighteen-month replacement schedules as thermal density requirements outstrip air-cooled chassis capacity.
Growth Catalysts
- EU Green Deal mandates:Ecodesign requirements for idle power thresholds are forcing hardware redesigns that favor modular, upgradeable architectures over monolithic systems.
- Hyperscale procurement decoupling:Cloud service providers now plan capacity independently from traditional enterprise refresh cycles, creating dual-track demand patterns.
- Financial services verticals:Regulated institutions require chassis-level physical isolation and hardware root-of-trust implementations that blade server architectures uniquely satisfy.
Market Restraints
- Advanced packaging substrate shortage:CoWoS and HBM interposer capacity constraints at TSMC and Samsung Foundry limit AI server GPU attach rates.
- NIST cybersecurity framework compliance:Hardware root-of-trust mandates extend motherboard firmware development timelines by eight to fourteen months.
- Liquid cooling infrastructure capital:Direct-to-chip and immersion systems require facility-level plumbing retrofits that hyperscalers absorb but mid-market data centers defer.
Strategic Opportunities
- Sovereign cloud procurement regimes:National data localization laws in Germany, France, and Saudi Arabia are fragmenting certification requirements and creating region-specific supplier slots.
- AI inference edge deployment:Telco central offices and manufacturing floors require compact accelerated servers outside hyperscale footprints.
- ISO/IEC 27001 hardware attestation:Convergence of cybersecurity frameworks with supply chain transparency standards favors vendors with vertically integrated manufacturing.
Industry Challenges
- Thermal design power escalation:700W CPU and 1000W GPU packages exceed air-cooled rack density limits, forcing immediate liquid cooling adoption or facility abandonment.
- Firmware supply chain attestation:Baseboard management controller vulnerabilities require continuous patch validation across multi-vendor motherboard ecosystems.
- Intergenerational socket compatibility:Rapid platform turnover strands DDR4 and PCIe 4.0 investments before depreciation schedules complete.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Enterprise Server Market |
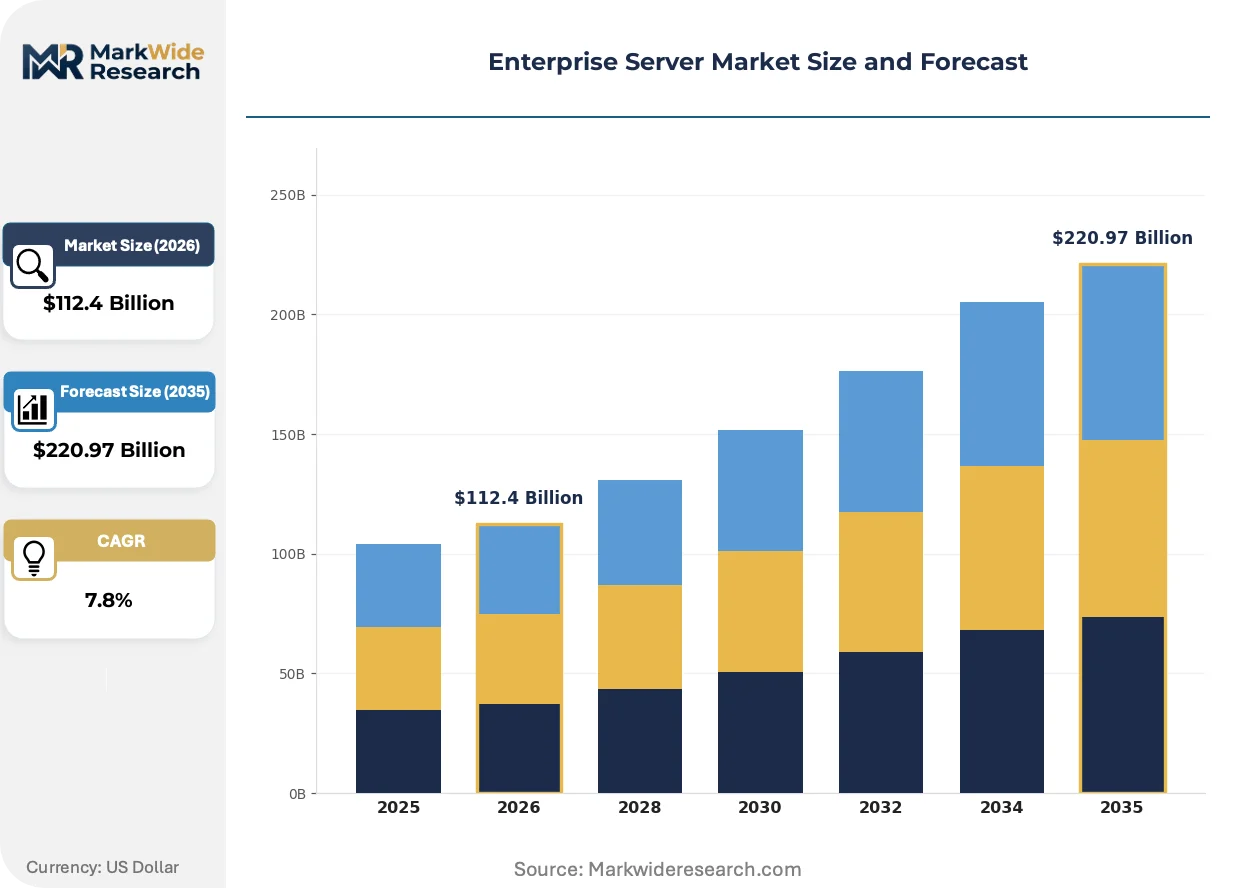
| Market Size in 2026 | $112.4 Billion |
| Market Size in 2035 | $220.97 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blade Server, Rack Server, Tower Server, Density-Optimized Server End User: Large Enterprises, SMEs, Cloud Service Providers, Managed Service Providers Operating System: Linux, Windows Server, Unix, VMware Deployment Model: On-Premise, Hybrid Cloud, Multi-Cloud, Private Cloud |
| Companies Covered | Lenovo, IBM Corporation, Dell Technologies, Nvidia Corporation, Foxconn, Hewlett Packard Enterprise, Inspur Group, Cisco Systems, Super Micro Computer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Enterprise Server Market Strategic Shifts & Innovations
Server architecture is bifurcating between density-optimized AI training platforms and efficiency-focused general-purpose systems as thermal constraints and workload specialization diverge.
Direct liquid cooling is converging with high-bandwidth memory packaging to enable 100kW-per-rack deployments. Hyperscale operators in the United States and China are retrofitting existing facilities with coolant distribution units while new builds specify immersion-ready concrete slabs. This convergence is compressing the viable lifecycle of air-cooled designs to sub-36-month windows.
EPA ENERGY STAR 3.0 specifications and EU F-Gas Regulation phase-down schedules are jointly constraining refrigerant choices for facility-level cooling. Server OEMs must now certify chassis across dual regulatory regimes with incompatible test protocols. European deployments face particular friction as F-Gas quotas tighten ahead of ENERGY STAR harmonization timelines.
Buying committees at enterprise accounts now separate AI infrastructure procurement from general-purpose server refresh decisions. Traditional VAR channels lose attach rates on accelerated computing orders as hyperscale-direct pricing benchmarks reset expectations. This bifurcation is most pronounced in Germany and Japan where procurement centralization meets stringent domestic certification requirements.
Enterprise Server Market Segmentation
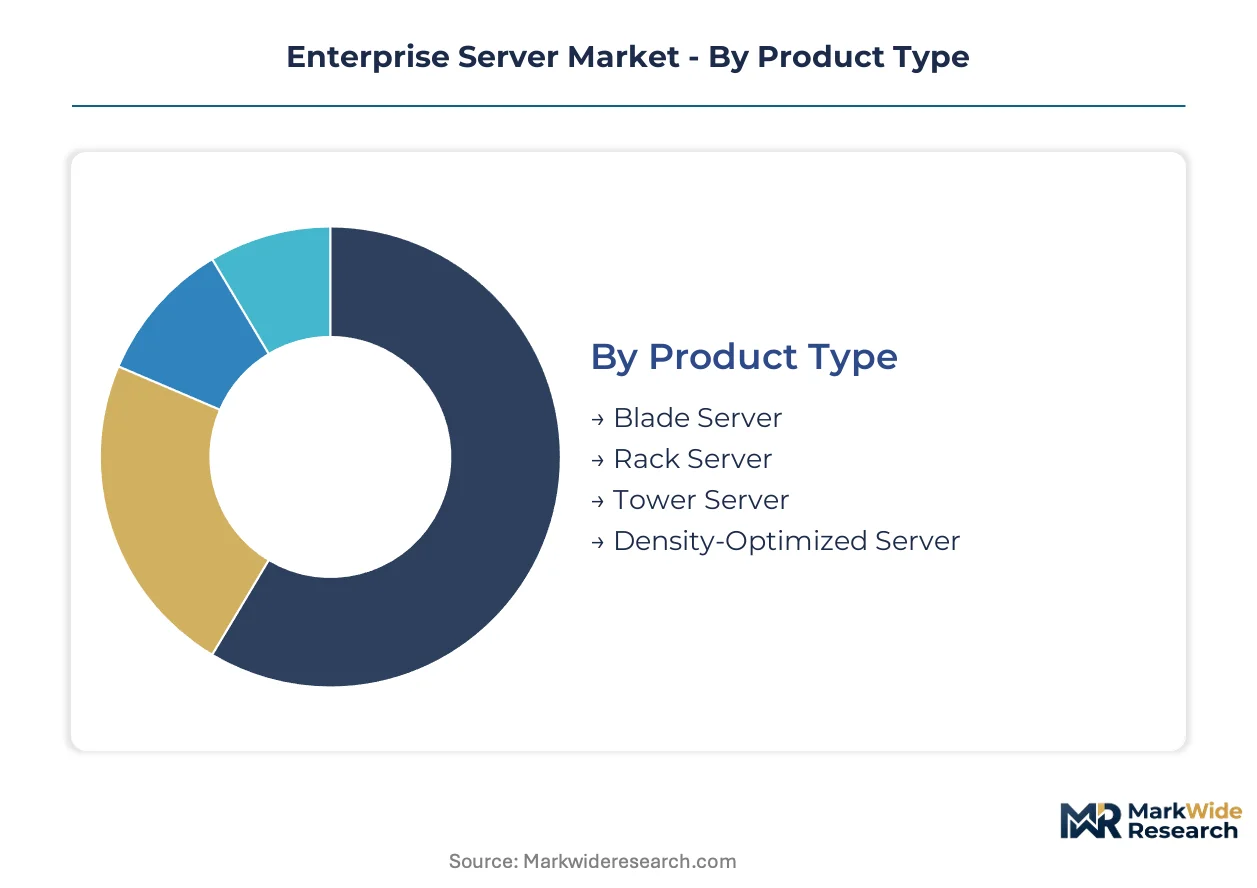
Server procurement patterns diverge sharply between capital-intensive hyperscale deployments and depreciation-driven enterprise refresh cycles. Segmentation reveals how thermal constraints, compliance mandates, and workload specialization reshape hardware specifications across customer tiers.
Product Type:
Volume concentration favors standardized form factors with established supply chains, while premium capture clusters around thermal-dense configurations requiring liquid cooling infrastructure.
- Rack Server:Standardized 19-inch chassis dominate installed base economics with multi-socket x86 architectures and hot-swappable power supplies. Demand concentrates among cloud service providers in the United States and China as these operators prioritize density standardization across megawatt-scale facilities.
- Density-Optimized Server:Liquid-cooled designs with 100kW-per-rack thermal envelopes accommodate GPU-intensive AI training clusters. Procurement is accelerating fastest among hyperscalers retrofitting existing data centers in Germany and Saudi Arabia where energy efficiency mandates under the EU Green Deal and domestic localization laws force rapid infrastructure overhaul.
- Blade Server:Chassis-level management and physical security isolation serve regulated financial services in Frankfurt and Tokyo.
- Tower Server:Standalone units persist in remote office and small data center deployments with limited rack infrastructure.
Mature deployment sits with rack servers. Newer deployment is concentrated in density-optimized servers.
End User:
Procurement authority separates between centralized infrastructure teams managing depreciation schedules and distributed cloud engineering organizations planning capacity independently.
- Cloud Service Providers:Hyperscale operators decouple server procurement from traditional enterprise refresh cycles, compressing replacement schedules to eighteen months as AI training workloads outstrip thermal capacity. These buyers dominate GPU attach rates and drive CoWoS packaging demand at TSMC and Samsung Foundry.
- Large Enterprises:Centralized IT organizations maintain five-year depreciation schedules for general-purpose workloads while establishing separate AI infrastructure budgets. Compliance with NIST cybersecurity frameworks and hardware root-of-trust mandates extends procurement timelines in United States federal contracting and German automotive manufacturing.
- Managed Service Providers:Multi-tenant hosting operations standardize on rack configurations with remote management capabilities across distributed edge locations.
- SMEs:Constrained capital budgets favor refurbished equipment and extended support contracts over new server acquisition.
Procurement volume concentrates with cloud service providers. Margin capture remains strongest among large enterprises.
Operating System:
License economics and container orchestration compatibility determine OS selection across workload types, with open-source alternatives displacing proprietary platforms in cloud-native deployments.
- Linux:Open-source distributions dominate cloud service provider and AI training environments where kernel customization supports specialized GPU drivers and container runtimes. Red Hat Enterprise Linux and Ubuntu Server capture premium support revenue in United States financial services and German industrial automation.
- Windows Server:Active Directory integration and legacy application compatibility sustain demand among United States healthcare systems and government contractors maintaining HIPAA and FISMA compliance.
- VMware:Virtualization licensing constrains bare-metal AI deployments but persists in enterprise private cloud consolidation projects.
- Unix:IBM AIX and Oracle Solaris retain mission-critical database workloads in banking core systems requiring binary compatibility guarantees.
Expansion is fastest in Linux. Legacy maintenance concentrates with Unix.
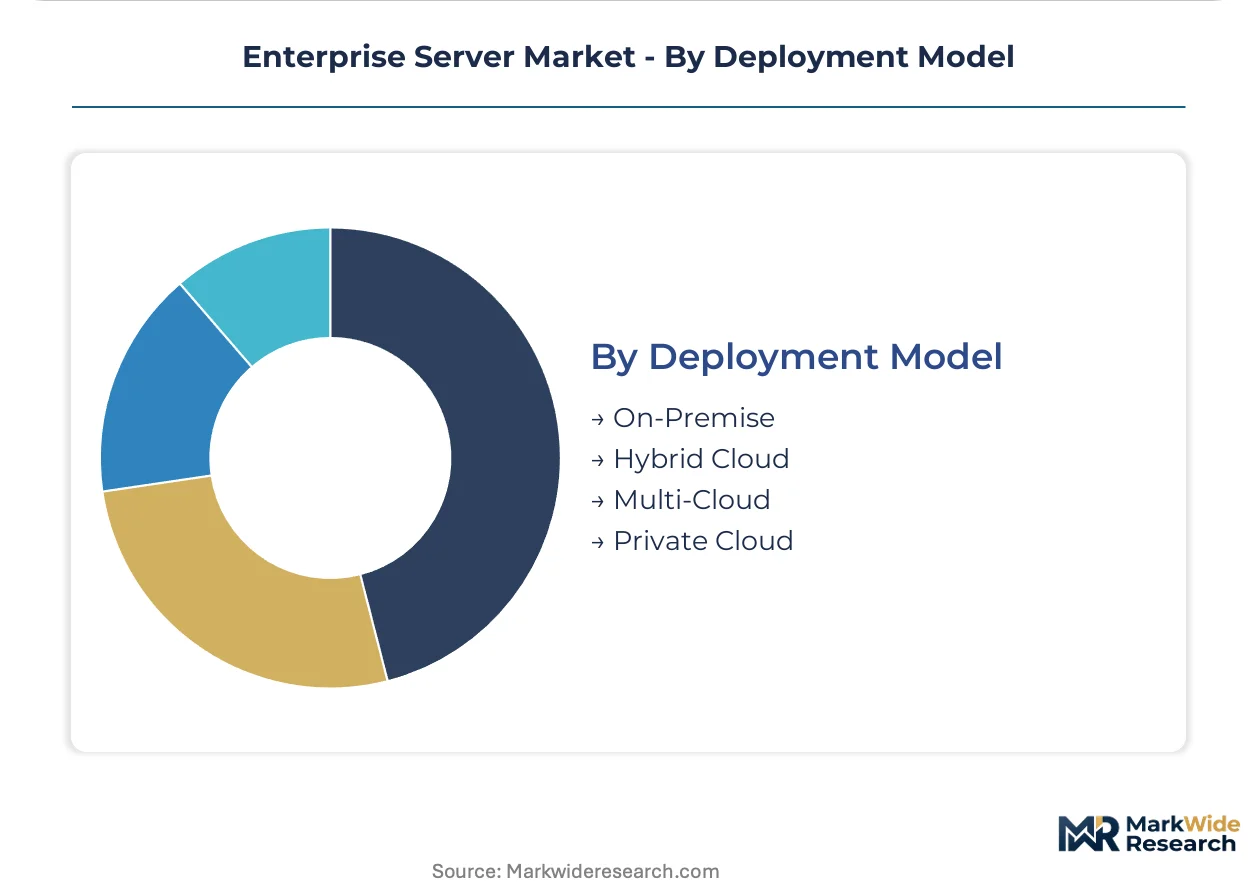
Deployment Model:
Data sovereignty requirements and latency constraints fragment infrastructure location decisions, with regulatory mandates in Europe and the Middle East forcing multi-cloud architectural complexity.
- Hybrid Cloud:Workload portability between on-premise and public cloud infrastructure dominates enterprise architecture planning. German automotive manufacturers and Japanese electronics conglomerates deploy hybrid configurations to satisfy domestic data residency requirements while accessing elastic compute for burst workloads.
- Private Cloud:Dedicated infrastructure meets stringent compliance mandates in United States defense contracting and Saudi Arabia government cloud initiatives where sovereign cloud regulations prohibit multi-tenant foreign ownership.
- Multi-Cloud:Vendor diversification strategies spread risk across AWS, Azure, and GCP footprints among United States technology firms avoiding single-provider concentration.
- On-Premise:Latency-sensitive manufacturing control systems and air-gapped security environments persist in critical infrastructure operators.
Established architecture sits with on-premise. Strategic investment is concentrating in hybrid cloud.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Data center investment zones in Northern Virginia, Frankfurt, and Singapore anchor server procurement concentration. Tax incentives and energy subsidies in these jurisdictions accelerate facility buildouts. Sovereign cloud mandates fragment certification requirements across national procurement regimes.
United States
Hyperscale operators in Northern Virginia and Dallas-Fort Worth drive rack server volume through megawatt-scale facility expansions. NIST cybersecurity frameworks mandate hardware root-of-trust implementations for federal contracting. Microsoft and Amazon Web Services compress refresh cycles to eighteen months in Phoenix and Atlanta data center clusters.
Germany
EU Green Deal Ecodesign requirements enforce idle power thresholds that favor modular server architectures. Frankfurt and Munich data centers retrofit liquid cooling infrastructure to accommodate 100kW-per-rack AI training densities. Domestic automotive manufacturers establish separate AI infrastructure budgets independent of general-purpose refresh cycles.
China
Dual carbon goals under MIIT supervision constrain data center power usage effectiveness ratios in Beijing and Shanghai. Hyperscale operators in Guizhou and Inner Mongolia exploit renewable energy zones for training cluster expansion. Government cloud initiatives mandate domestic silicon preferences in state procurement.
Saudi Arabia
Sovereign cloud regulations under Vision 2030 prohibit multi-tenant foreign ownership in Riyadh and Jeddah data center zones. NEOM infrastructure projects specify immersion-ready concrete slabs for liquid-cooled deployments. Domestic localization laws create region-specific supplier slots for server OEMs.
Japan
METI efficiency standards govern facility-level cooling in Tokyo and Osaka data center corridors. Financial services in the Kanto region require blade server chassis-level physical isolation for core banking systems. Hybrid cloud architectures satisfy domestic data residency requirements while accessing burst compute.
Enterprise Server Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with rack server volume concentrating among scale operators and blade systems retaining margin in regulated verticals. The vendor base organizes around three strategic archetypes: full-stack systems integrators, component-specialized accelerators, and contract manufacturing platforms. Competitive positioning hardens through M&A activity targeting liquid cooling IP and strategic partnerships securing CoWoS packaging allocation.
Among systems integrators, Dell Technologies and Hewlett Packard Enterprise occupy positions spanning enterprise and hyperscale procurement channels. Nvidia Corporation exemplifies the accelerator-specialized archetype with GPU-dominant server architectures. Foxconn represents contract manufacturing scale with vertically integrated motherboard and chassis production capabilities.
| Leading Market Players |
|---|
| Lenovo |
| IBM Corporation |
| Dell Technologies |
| Nvidia Corporation |
| Foxconn |
| Hewlett Packard Enterprise |
| Inspur Group |
| Cisco Systems |
| Super Micro Computer |
| Others |
Cost & Logistics Intelligence
Direct liquid cooling adoption is compressing server lifecycle economics while simultaneously concentrating procurement leverage among hyperscale operators capable of absorbing facility-level infrastructure retrofits. This technology transition fragments pricing power between legacy air-cooled chassis suppliers facing margin compression and liquid-cooled system integrators capturing premium positioning in AI training clusters.
Pricing Analysis
Short lead-time premiums command substantial markups as CoWoS packaging constraints at TSMC and Samsung Foundry extend GPU server delivery windows to twelve months. Contract-based long-term offtake agreements dominate hyperscale procurement, with spot inventory trading at discounts among distressed Tier 2 data center operators. Price differentiation hinges on hardware root-of-trust certification tier and liquid cooling infrastructure bundling. Cost compression in general-purpose rack configurations is intensifying because enterprise buyers benchmark against hyperscale-direct pricing. SMEs exhibit highest price sensitivity, while sovereign cloud procurement regimes in Germany and Saudi Arabia demonstrate lowest sensitivity due to compliance-driven specification rigidity.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan for CoWoS advanced packaging and South Korea for HBM memory interposers. Server motherboard production draws from China, Mexico, and Malaysia for chassis fabrication, with x86 CPU supply anchored in United States and Ireland. Raw material dependencies include high-purity copper for thermal interfaces, specialized substrate laminates for GPU modules, and fluorinated coolants constrained by EU F-Gas Regulation phase-down schedules. Tariff exposure on Chinese-manufactured power supplies threatens margin structures for mid-market OEMs. Distribution runs through direct hyperscale procurement channels, VAR networks for enterprise accounts, and systems integrators for sovereign cloud deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The enterprise server market occupies a technology-transition phase where liquid-cooled AI infrastructure displaces air-cooled legacy systems before depreciation schedules complete. This compression creates asymmetric opportunity for vendors with thermal management IP and hyperscale channel access.
For Market Incumbents: Lock in CoWoS packaging allocation through multi-year foundry commitments before substrate capacity constraints worsen. Defend blade server margin concentration in Frankfurt and Tokyo financial services by accelerating hardware root-of-trust certification timelines ahead of NIST framework updates. Prioritize backward integration into liquid cooling component manufacturing to capture infrastructure retrofit spending.
For New Entrants and Emerging Players: Launch via sovereign cloud certification partnerships in Riyadh and Jeddah where domestic localization laws create region-specific supplier slots. Target AI inference edge deployment in telco central offices and manufacturing floors outside hyperscale footprints. Pursue ISO/IEC 27001 hardware attestation as the primary go-to-market credential to bypass entrenched vendor relationships.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by full-stack systems integrators seeking liquid cooling IP. Long-term viability favors vendors with vertically integrated motherboard production and captive supply of thermal management components. Watch hyperscaler capex commitment timing as the inflection signal for capacity expansion cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| CoWoS Packaging Allocation Securement | TSMC and Samsung Foundry capacity constraints limit GPU attach rates for AI server builds. |
| Liquid Cooling Infrastructure Retrofit | German and Saudi Arabian data centers require facility-level plumbing to accommodate 100kW-per-rack densities. |
| Hardware Root-of-Trust Certification | NIST cybersecurity framework mandates extend procurement timelines for United States federal contracting. |
| Sovereign Cloud Localization Partnership | Vision 2030 regulations in Saudi Arabia prohibit multi-tenant foreign ownership in Riyadh data center zones. |
| AI Inference Edge Product Line Launch | Telco central offices and manufacturing floors demand compact accelerated servers outside hyperscale footprints. |
Research Approach
SEC 10-K filings, hyperscaler capex disclosures, and EIA data center energy consumption reports formed the secondary backbone for volume and specification analysis. Primary interviews with data center infrastructure executives, cloud procurement officers, thermal engineering leads, and channel distribution managers validated demand assumptions and pricing benchmarks. Bottom-up unit economics triangulated against top-down facility capacity buildout tracking across Northern Virginia, Frankfurt, and Singapore investment zones.
Historical trendline analysis of server shipment patterns and refresh cycle compression informed the projection framework across the analysis window. Segmentation dimensions modeled include product type, end user procurement authority, deployment model, and regional regulatory cluster. CAGRs derived from unit shipment trajectories weighted by thermal density tier and cooling infrastructure attachment rates. Forecast inputs incorporated CoWoS packaging capacity expansion schedules and EU Ecodesign compliance phase-in timelines.
The model assumes a particular technology adoption path; alternative pathways for direct liquid cooling penetration would alter the outlook if air-cooled thermal designs achieve unexpected efficiency breakthroughs. Deviation in hyperscaler AI training cluster deployment timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Data Center Networks Market
Data Center and Networking
Poland Data Center Networking Market
Data Center and Networking
North America Subscriber Data Management Market
Data Center and Networking
Japan Data Center Server Market
Data Center and Networking
Middle East Data Center Networking Market
Data Center and Networking
Global Data Center Networking Market
Data Center and Networking
US Dark Fiber Network Market
Data Center and Networking
Cache Server Market
Data Center and Networking
China Data Center Networking Market
Data Center and Networking
Global Enterprise Networking Market
Data Center and Networking
Global Data Warehouse As a Service (Dwaas) Market
Data Center and Networking
Brazil Servers Market
Data Center and Networking
Vietnam Data Center Networking Market
Data Center and Networking
Edge Server Market
Data Center and Networking
Data Warehousing Market
Data Center and Networking
MPLS-Based Core Network Market