
 Edge Server Market | 2026-2036
Edge Server Market Size, Share, and Industry Trends Forecast 2026-2036
Edge Server Market Analysis
The EU Green Deal is broadening sustainability mandates for data infrastructure across European industrial zones. Dell Technologies leverages its server manufacturing scale to anchor supply chains for high-density edge deployments. Lenovo competes through vertical integration from component sourcing to rack integration. Cisco Systems specializes in networking-optimized edge nodes that extend enterprise security policies to distributed sites.
An edge server is a compact, ruggedized compute node designed for local data processing with specifications typically including Xeon-D or ARM-based processors, NVMe storage, and operating temperatures from minus twenty to sixty degrees Celsius; its primary purpose is to reduce latency for time-sensitive applications by processing data near its source rather than routing to centralized cloud facilities. Micro Data Center deployments dominate capital expenditure as enterprises seek self-contained power and cooling for factory floors and cell towers. Cloudlet configurations represent the fastest-growing segment as telecom operators deploy neutral-host infrastructure for 5G network slicing and low-latency gaming.
EMA guidelines on data integrity for pharmaceutical manufacturing, REACH restrictions on hazardous substances in electronics, and CE marking requirements for electromagnetic compatibility collectively shape hardware design cycles and market access across the European Economic Area. The EU AI Act adds algorithmic transparency obligations that edge server vendors must embed through auditable inference logging. Stakeholders should monitor how national implementations of the AI Act diverge across member states, as this fragmentation will determine where edge infrastructure investments flow for regulated industries.
Market Dynamics
EU AI Act compliance mandates are forcing edge server vendors to redesign inference logging architectures before the law's enforcement deadline, compressing product development cycles and redistributing R&D budgets toward auditability features.
Growth Catalysts
- Real-time manufacturing analytics:Factory floors in Germany's Baden-Württemberg region deploy edge nodes for predictive maintenance on CNC equipment, cutting unplanned downtime through localized vibration analysis.
- EU Green Deal mandates:Industrial zone operators face binding emissions targets for data infrastructure, accelerating replacement of legacy remote servers with thermally efficient edge deployments.
- 5G network slicing protocols:Telecom infrastructure specifications now require sub-10 millisecond latency guarantees that only distributed edge architectures can satisfy for autonomous vehicle coordination.
Market Restraints
- Silicon supply concentration:Xeon-D and ARM processor fabrication depends on three East Asian foundry complexes, exposing lead times to geopolitical friction and export control volatility.
- REACH substance restrictions:ECHA's evolving hazardous substance lists force hardware redesigns when flame retardants or solder materials lose authorization, freezing certification timelines.
- Thermal management costs:Ruggedized enclosures rated for minus twenty to sixty degrees Celsius operation require specialized phase-change materials that inflate bill-of-materials by fifteen to twenty-five percent versus standard servers.
Strategic Opportunities
- Pharmaceutical edge compliance:EMA data integrity guidelines create first-mover advantage for vendors offering GxP-validated edge servers with immutable audit trails for batch release decisions.
- Neutral-host telecom infrastructure:Cloudlet configurations enable tower operators to lease compute capacity to multiple carriers simultaneously, transforming capex-heavy deployments into recurring revenue models.
- Industrial AI Act readiness:High-risk system providers need embedded explainability chips that log inference decisions locally, opening premium hardware tiers for regulated sectors.
Industry Challenges
- Embedded systems firmware expertise:Vendors struggle to hire engineers capable of optimizing real-time operating systems for deterministic latency in safety-critical automotive applications.
- CE marking electromagnetic compatibility:Redesigned thermal solutions frequently fail radiated emissions retesting, forcing costly chamber time and mechanical revisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Edge Server Market |
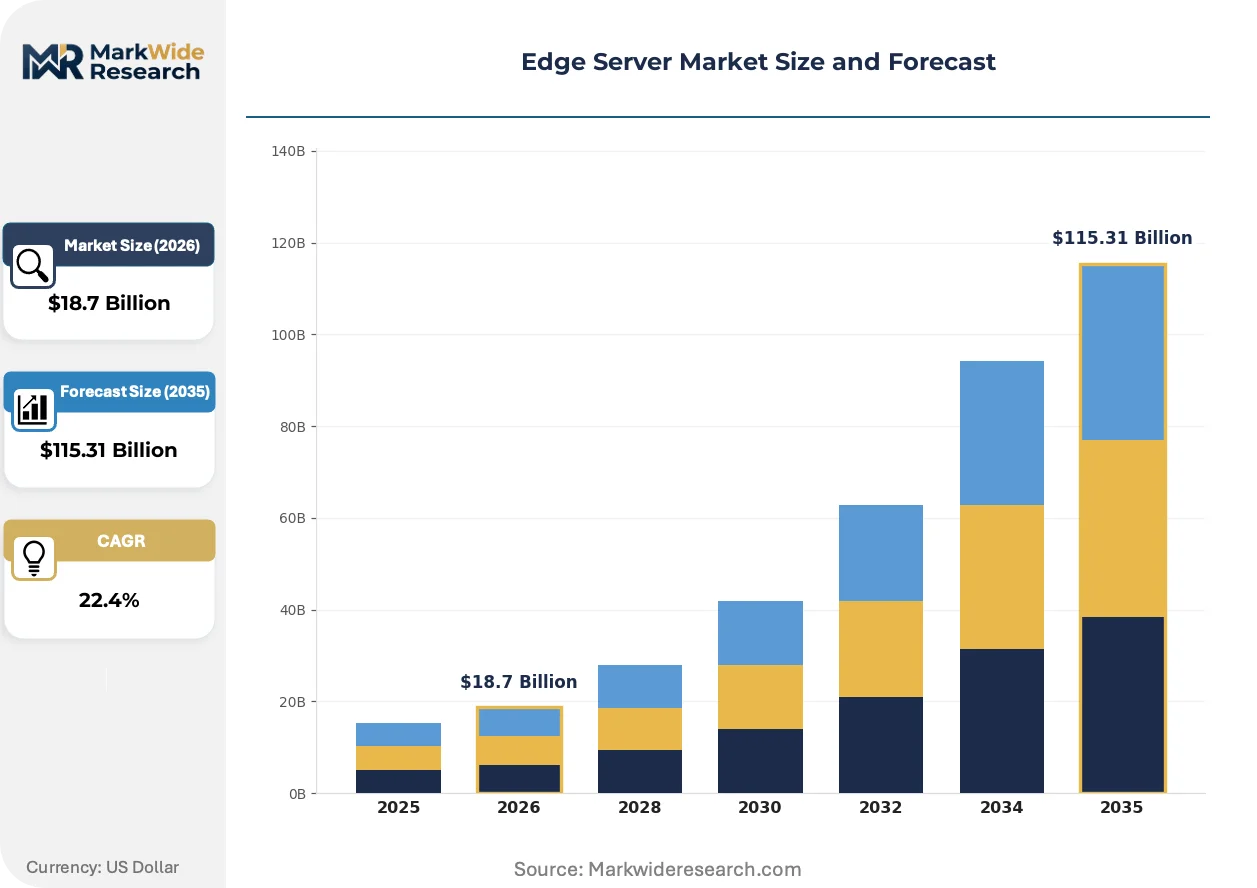
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $115.31 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Micro Data Center, Cloudlet, Edge Node, Mini-Server Deployment: On-Premises, Remote, Hybrid, Co-Location End User: Retail, Telecom, Healthcare, Manufacturing Technology: IoT, AI, 5G, Data Analytics |
| Companies Covered | Vapor IO, Zadara, Equinix, Lenovo, TierPoint, Cisco Systems, EdgeMicro, Nutanix, Dell Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Edge Server Market Emerging Trajectories
Edge server architectures are absorbing inference workloads that previously required cloud round-trips, compressing the functional boundary between on-premise and centralized compute.
NVMe-over-Fabric storage pooling is absorbing cold-tier data management responsibilities from traditional SAN arrays in micro data center deployments. Manufacturing facilities with high-speed vision inspection systems adopt these architectures fastest, cutting storage latency to under one hundred microseconds. The technology is absorbing capital that previously flowed to centralized hyperconverged infrastructure, reshaping vendor competitive sets.
CSRD sustainability disclosure rules now require granular Scope 3 emissions reporting for ICT hardware deployed across European industrial sites. Component-level carbon footprint tracking is becoming a procurement gate, with suppliers forced to submit lifecycle data through standardized digital product passports. Server vendors with embedded supply chain traceability systems capture preference in German and French manufacturing clusters.
Buyers are unbundling hardware acquisition from multi-year managed service contracts that previously dominated edge deployments. Mid-sized industrial firms now prefer capital purchase with separate break-fix support, reversing the as-a-service momentum of 2020-2023. This pattern concentrates in Central European markets where CFOs face rising interest rate environments and prefer balance sheet ownership.
Edge Server Market Segmentation
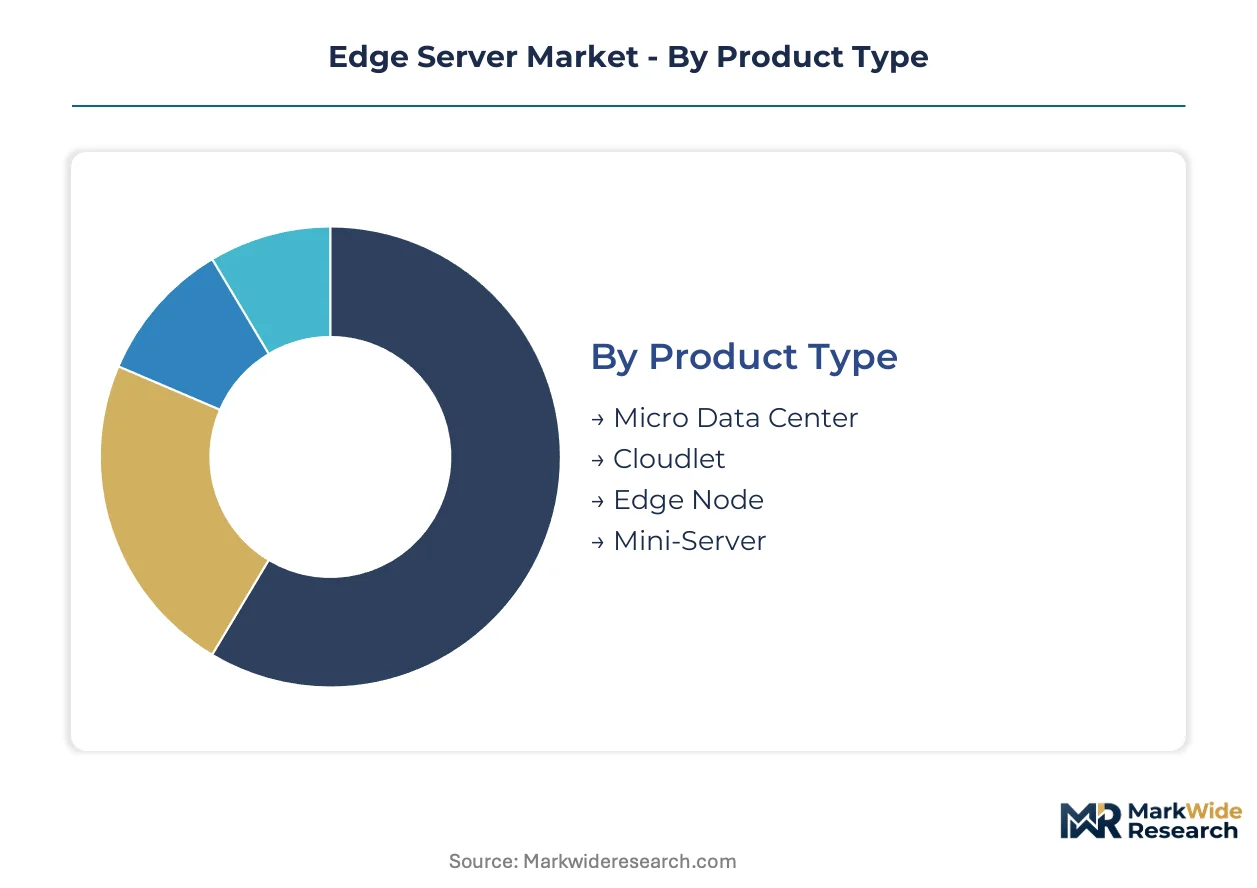
Edge server segmentation reveals how capital allocation patterns diverge across deployment models and end-use requirements. Infrastructure buyers prioritize form-factor decisions that balance thermal constraints against compute density for specific latency-sensitive workloads.
Product Type:
Capital intensity varies sharply across form factors, with enclosure-level power and cooling infrastructure driving the widest gaps in upfront expenditure.
- Micro Data Center:Self-contained enclosures integrate power distribution, cooling, and fire suppression in NEMA-rated housings. Manufacturing clusters in Bavaria deploy these for CNC equipment monitoring where factory-floor environmental controls are absent.
- Cloudlet:Compact compute nodes designed for neutral-host telecom infrastructure enable simultaneous multi-tenant access. Tower operators across Germany lease capacity to competing carriers, converting capex-heavy cell sites into recurring revenue platforms.
- Edge Node:Ruggedized units with Xeon-D or ARM processors operate across minus twenty to sixty degrees Celsius ranges.
- Mini-Server:Reduced-footprint units target retail backrooms and branch offices with constrained physical space.
Micro Data Center absorbs the bulk of installed capacity; Cloudlet is expanding most quickly.
Deployment:
Ownership models reshape procurement patterns as interest rate environments shift finance preferences across European industrial zones.
- On-Premises:Capital purchase with balance-sheet ownership dominates German manufacturing where CFOs face rising debt costs. Baden-Württemberg automotive suppliers prefer this model for predictive maintenance systems requiring direct asset control.
- Co-Location:Shared facility access reduces facility construction burdens for mid-sized firms lacking in-house data center expertise. Industrial automation clusters in Bavaria leverage these deployments for rapid capacity scaling without land acquisition delays.
- Remote:Distributed sites with minimal on-site technical staff rely on vendor-managed hardware replacement logistics.
- Hybrid:Split architectures route non-time-sensitive workloads to centralized cloud while retaining latency-critical processing locally.
On-Premises retains the largest installed base; Co-Location is climbing the fastest among mid-market manufacturers.
End User:
Regulatory exposure and uptime requirements create divergent specification demands across vertical purchasing committees.
- Manufacturing:Real-time vibration analysis and vision inspection systems require deterministic latency guarantees. EMA data integrity guidelines for pharmaceutical batch release are pushing German chemical producers toward GxP-validated edge configurations with immutable audit trails.
- Telecom:5G network slicing mandates sub-ten-millisecond latency for autonomous vehicle coordination protocols. EU AI Act transparency obligations are forcing inference logging redesigns before enforcement deadlines.
- Healthcare:Medical imaging and patient monitoring applications face strict electromagnetic compatibility requirements under CE marking rules.
- Retail:Inventory management and customer analytics drive demand for compact, fanless designs in backroom environments.
Manufacturing commands the deepest installed capacity; Telecom is gaining share fastest through infrastructure-neutral host models.
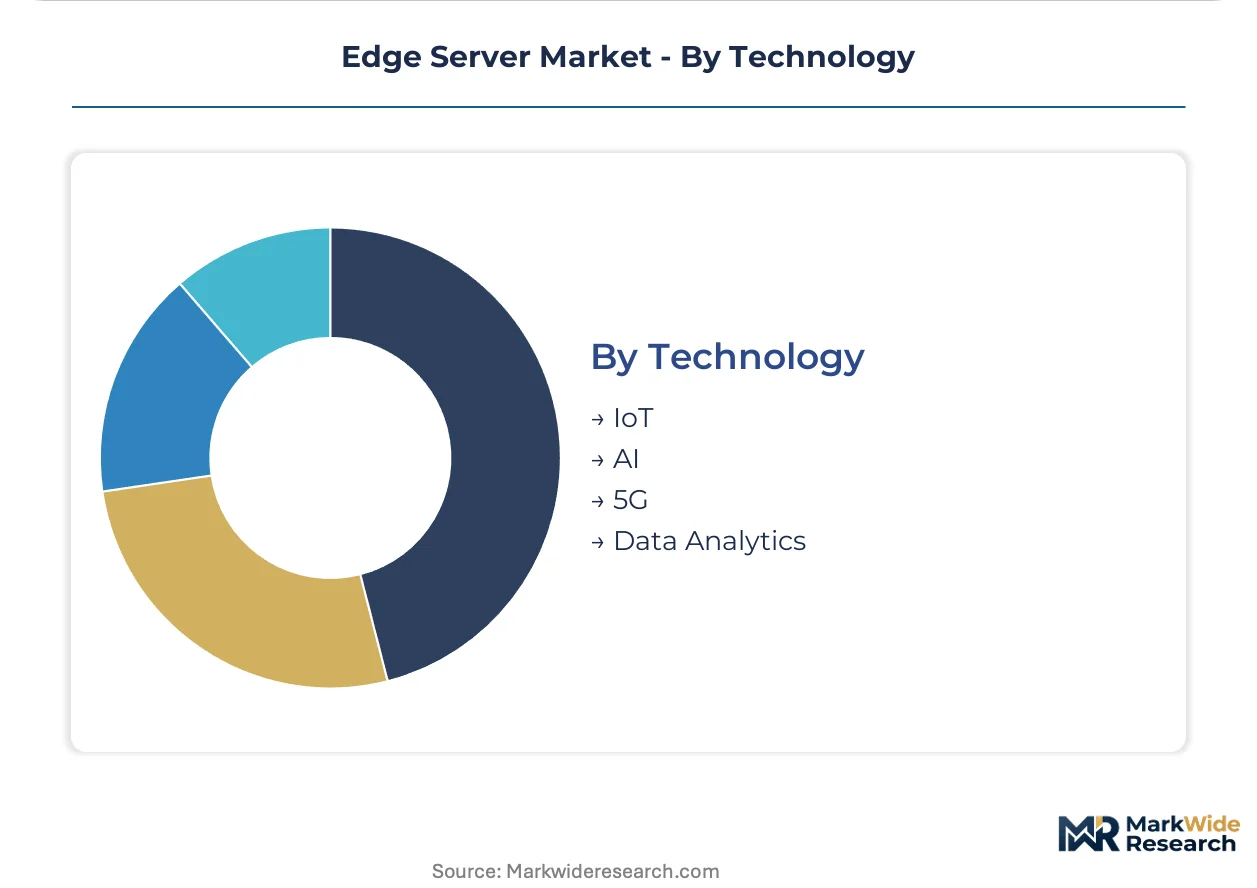
Technology:
Workload characteristics determine whether edge architectures prioritize sensor ingestion, inference acceleration, or protocol translation capabilities.
- AI:Embedded inference chips with explainability logging satisfy EU AI Act algorithmic transparency mandates for high-risk systems. Pharmaceutical manufacturers in Germany require these capabilities for automated batch release decisions.
- 5G:Radio access network disaggregation pushes compute toward cell tower bases to meet latency specifications for industrial automation and vehicular communication.
- IoT:Massive sensor aggregation protocols demand gateway functions that preprocess telemetry before cloud transmission.
- Data Analytics:Stream processing engines execute aggregation and anomaly detection without round-trip latency to centralized warehouses.
AI-enabled configurations capture the highest value per unit; 5G-integrated deployments are expanding most rapidly through telecom infrastructure mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Edge server fabrication concentrates in East Asian foundry complexes while consumption clusters in German industrial zones and US telecom corridors. This geographic split creates supply chain exposure that vendors mitigate through regional assembly partnerships.
Germany
Automotive suppliers in Baden-Württemberg deploy predictive maintenance nodes on CNC equipment to eliminate unplanned downtime. The EU AI Act mandates algorithmic transparency logging that vendors must embed before enforcement deadlines. Bavarian automation clusters drive co-location expansion as mid-sized manufacturers seek rapid capacity scaling without land acquisition.
United States
Telecom operators deploy cloudlet configurations for 5G network slicing and low-latency gaming infrastructure. FCC spectrum auctions have accelerated radio access network disaggregation toward cell tower bases. Tower operators in Texas and California convert capex-heavy sites into recurring revenue platforms through neutral-host leasing models.
China
Domestic cloud providers build edge capacity to support industrial IoT aggregation for smart factory initiatives. MIIT standards on data localization steer processing toward on-premise nodes rather than centralized facilities. Yangtze River Delta manufacturing hubs absorb the highest concentration of ruggedized deployments for vision inspection systems.
Japan
Automotive OEMs require deterministic latency guarantees for autonomous vehicle coordination protocols. METI guidelines on industrial data security favor localized processing architectures over cross-border transmission. Nagoya-area suppliers embed edge nodes directly into production lines for real-time quality control.
United Kingdom
Financial services firms in London deploy micro data centers for algorithmic trading latency reduction. The national data protection framework reinforces preferences for on-premise inference logging to satisfy audit requirements. Scotland's renewable energy clusters experiment with thermally efficient edge enclosures for remote wind farm monitoring.
Edge Server Market Vendor Landscape
The competitive structure tilts toward diversified technology conglomerates with captive server manufacturing capabilities. Three tiers have emerged: global infrastructure vendors with full-stack integration, networking specialists optimizing for distributed security policies, and neutral-host operators transforming tower real estate into compute platforms. Consolidation pressure intensifies as R&D budgets shift toward EU AI Act compliance features and thermal management innovations.
Among diversified technology conglomerates, Dell Technologies and Lenovo exemplify scale-driven archetypes with upstream control over component sourcing and rack integration. Cisco Systems occupies a distinct position as a networking-optimized specialist extending enterprise security policies to distributed sites. Vapor IO represents the infrastructure-neutral host model converting physical edge real estate into multi-tenant compute leasing platforms.
| Leading Market Players |
|---|
| Vapor IO |
| Zadara |
| Equinix |
| Lenovo |
| TierPoint |
| Cisco Systems |
| EdgeMicro |
| Nutanix |
| Dell Technologies |
| Others |
Supply Flow & Price Mechanics
Captive component sourcing from Xeon-D and ARM processor foundries anchors both supply security and pricing power for edge server vendors serving German industrial automation clusters. This integration choice insulates tier-one manufacturers from spot-market volatility while compressing margins for assemblers without upstream silicon access.
Pricing Analysis
Margin tightening in ruggedized edge nodes reflects REACH substance restrictions forcing flame-retardant material substitutions that inflate bill-of-materials. Three-tier pricing structure across GxP-validated, enterprise-grade, and standard configurations separates pharmaceutical manufacturers with EMA compliance mandates from price-sensitive retail backroom deployments. Cost-down pressure on thermal management subsystems accelerates as phase-change material suppliers consolidate. Telecom tower operators exhibit lowest price sensitivity due to neutral-host revenue conversion, while mid-sized Bavarian manufacturers negotiate hardest on capital purchase terms.
Supply Chain Analysis
Engineering talent scarcity in Taiwan, South Korea, and Germany constrains firmware optimization capacity for deterministic real-time operating systems. Processor fabrication draws from East Asian foundry complexes, NVMe controller supply rests on Korean semiconductor houses, and thermal material sourcing feeds from German specialty chemical producers. Single-source vulnerability concentrates in Xeon-D wafer starts at three fabrication facilities. Distribution runs through direct OEM channels for automotive tier-one suppliers and value-added resellers for mid-market industrial accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Edge server competition has become a vertical-integration race where captive silicon sourcing and in-house thermal engineering determine margin capture. Players without upstream component control face displacement by conglomerates with rack-to-chip integration.
For Market Incumbents: Anticipate EU AI Act enforcement compressing product development cycles by embedding auditable inference logging now rather than retrofitting later. Consolidate firmware engineering talent through targeted acquisition of real-time operating system specialists in Nagoya and Stuttgart. Secure captive supply agreements for phase-change thermal materials before REACH authorization reviews freeze alternative sourcing. For New Entrants and Emerging Players: Cloud-native management platforms offer the most penetrable entry vector for mid-sized German manufacturers unbundling hardware from managed service contracts. Target Baden-Württemberg automotive suppliers seeking predictive maintenance nodes with capital-purchase preference. Deploy channel partnerships with industrial automation integrators rather than direct field sales to bypass incumbent entrenched relationships. For Investors and Strategic Acquirers: Exit pathways concentrate in infrastructure-neutral host operators converting tower real estate into multi-tenant compute leasing platforms. Long-term viability hinges on regulatory compliance feature differentiation rather than raw compute density. Watch for divergence in national EU AI Act implementations as the inflection signal determining which edge infrastructure investments flow into regulated pharmaceutical and automotive sectors versus generic industrial deployments.| Strategic Initiative | Industry Significance |
|---|---|
| Embedded Inference Chip Development | EU AI Act transparency mandates create premium hardware tiers for pharmaceutical batch release automation in Germany. |
| Thermal Material Backward Integration | REACH substance restrictions favor vendors with captive phase-change material supply securing certification continuity. |
| Neutral-Host Infrastructure Partnership | Tower operators in Texas and California convert capex-heavy sites into recurring revenue platforms through multi-tenant cloudlet leasing. |
| Real-Time OS Talent Acquisition | Firmware expertise scarcity in safety-critical automotive applications concentrates competitive advantage with Nagoya and Stuttgart engineering clusters. |
| GxP Validation Certification Investment | EMA data integrity guidelines for pharmaceutical manufacturing create first-mover advantage with immutable audit trail capabilities. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with edge server product managers, industrial automation procurement leads, telecom infrastructure planners, and thermal engineering specialists combined with secondary validation from EMA guideline documents, EU AI Act implementation texts, and hyperscaler capex disclosures. Bottom-up unit shipment estimates triangulated against top-down infrastructure investment forecasts across the analysis window.
Segment-level modeling deployed product type, deployment model, end-use vertical, and technology integration as core dimensions throughout the projection horizon. CAGRs derived from regression analysis against industrial capital expenditure cycles and telecom infrastructure buildout schedules. Forecast inputs incorporated REACH substance authorization timelines and national EU AI Act implementation divergence patterns without specifying enforcement dates.
The model holds under stable East Asian foundry output and gradual REACH substance phaseouts; deviation in export control expansion or thermal material supply disruption would shift capacity allocation and pricing trajectories. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
China Data Center Networking Market
Data Center and Networking
Virtual Networking Market
Data Center and Networking
Data Center Market
Data Center and Networking
India Data Center Networking Market
Data Center and Networking
GPU Database Market
Data Center and Networking
Global Software Defined Networking (SDN) Market
Data Center and Networking
Global Content Delivery Network (CDN) Software Market
Data Center and Networking
Global Enterprise Networking Market
Data Center and Networking
Network Connectivity Tester Market
Data Center and Networking
South America Data Center Networking Market
Data Center and Networking
Philippines Data Center Networking Market
Data Center and Networking
Managed DNS Services Market
Data Center and Networking
Europe Data Center Networking Market
Data Center and Networking
Fog Networking Market
Data Center and Networking
Converged Data Platform Market
Data Center and Networking
Internet Protocol Version 6 (IPv6) Market