
 Data Center Networks Market | 2026-2036
Data Center Networks Market Size, Share, and Industry Trends Forecast 2026-2036
Data Center Networks Market Outlook
EU CSRD disclosure mandates and hyperscale buyer net-zero commitments are shifting procurement criteria toward power-efficient network fabrics. Cisco Systems leverages its merchant silicon partnerships to sustain switching portfolio breadth across enterprise and cloud segments. Arista Networks specializes in high-radix spine architectures that dominate AI training cluster deployments. NVIDIA anchors next-generation back-end network roadmaps through its InfiniBand and Ethernet adapter convergence strategy.
Data center networks constitute the interconnected switching, routing, and optical transport infrastructure that enables server-to-server, rack-to-rack, and facility-to-facility communication within and between computing facilities. These systems operate at speeds from 100 Gbps to 800 Gbps per port, employing Clos topologies and virtualized control planes to minimize latency and eliminate single points of failure for mission-critical workloads. Ethernet switching captures the dominant share of revenue as cloud providers standardize on merchant silicon-based white box platforms for cost scalability. InfiniBand maintains premium positioning in high-performance computing and generative AI training environments where remote direct memory access and ultra-low tail latency justify specialized adapter investments. Cloud computing application demand outpaces virtualization and disaster recovery as primary growth vectors, reflecting workload gravity shifts toward hyperscale operators.
FCC open internet rules and OSHA electrical safety standards shape equipment certification and installation protocols for US-based facility operators, while EU Ecodesign requirements and CE marking directives enforce minimum power efficiency thresholds for network hardware sold across member states. NIST cybersecurity frameworks increasingly influence procurement specifications for critical infrastructure operators seeking supply chain integrity assurances. Stakeholders must monitor evolving AI workload traffic patterns and corresponding port speed transition timelines to calibrate inventory and R&D commitments against actual deployment cadence rather than vendor roadmaps alone.
Market Dynamics
AI training cluster density is forcing hyperscale operators to rearchitect spine-leaf topologies around 800 Gbps merchant silicon, compressing upgrade cycles from five years to eighteen months.
Growth Catalysts
- EU CSRD carbon disclosure mandates:Facility operators face binding Scope 3 reporting requirements that favor energy-efficient switching fabrics. Procurement teams now prioritize power-per-bit metrics in vendor evaluations.
- Generative AI training workloads:Large language model clusters demand ultra-low latency east-west traffic patterns. InfiniBand and converged Ethernet adapters capture premium positioning for these deployments.
- Virginia's Northern Virginia corridor:Record connectivity investments concentrate in this fiber-dense region, absorbing disproportionate switch port volume as cloud providers expand campus footprints.
Market Restraints
- Merchant silicon supply concentration:Advanced switching ASIC fabrication depends on a single foundry geography, creating vulnerability to geopolitical disruption or capacity constraints.
- OSHA electrical safety certification timelines:New 800 Gbps equipment faces extended approval cycles for high-voltage rack integration, delaying revenue recognition for US facility deployments.
- Copper trace limitations at 112 Gbps PAM4:Signal integrity constraints on traditional PCB materials force costly substrate transitions, inflating bill-of-materials for high-radix switches.
Strategic Opportunities
- India's data center buildout:TRAI infrastructure guidelines and state-level incentives attract hyperscale investment. Greenfield facilities skip legacy 100 Gbps generations entirely.
- Liquid-cooled switching integration:Convergence of direct-to-chip cooling with high-density spine architectures enables rack-scale thermal management previously impossible with air-cooled designs.
- EU Green Deal efficiency thresholds:Ecodesign requirements for network hardware create first-mover advantage for vendors with sub-5-watt-per-100G port solutions.
Industry Challenges
- Optical interconnect skill scarcity:Deployment of co-packaged optics demands specialized fiber splicing and signal validation expertise that existing field engineering pools lack.
- Multi-vendor control plane integration:Heterogeneous switching environments from white-box and branded sources create SDN orchestration complexity that stalls production cutovers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Data Center Networks Market |
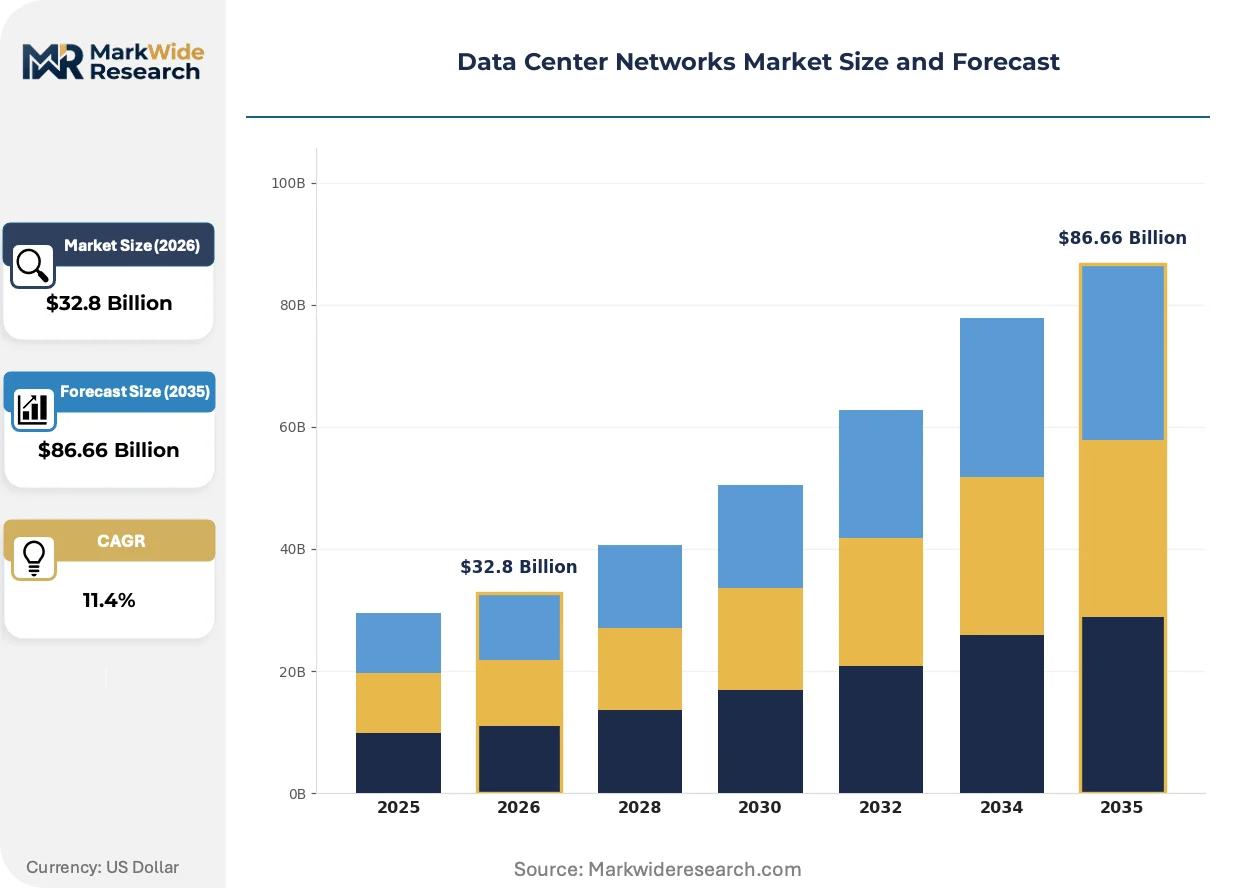
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $86.66 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Switches, Routers, Load Balancers, Firewalls Technology: Ethernet, InfiniBand, Fibre Channel, MPLS Application: Cloud Computing, Virtualization, Big Data, Disaster Recovery End User: Telecommunications, IT Services, BFSI, E-Commerce |
| Companies Covered | Cisco Systems, Arista Networks, NVIDIA, Juniper Networks, Hewlett Packard Enterprise, Dell Technologies, Intel Corporation, Broadcom, IBM Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Data Center Networks Market Strategic Shifts
Silicon photonics co-packaging is collapsing optical-electrical conversion layers, while regulatory pressure on embodied carbon reshapes hardware refresh economics.
Co-packaged optics is decentralizing the traditional pluggable transceiver supply chain by embedding lasers directly onto switch ASIC substrates. Hyperscale operators at the vanguard of AI cluster deployment are qualifying these designs for 51.2 Tbps radix switches. The technology is decentralizing procurement power from discrete optics vendors toward merchant silicon suppliers who control the co-design.
EU CSRD Scope 3 disclosure rules now require facility operators to report full lifecycle emissions for network hardware. This mandate is compressing supplier qualification timelines as procurement teams demand granular carbon accounting from switch vendors. European cloud and colocation providers are most affected, with several major operators embedding Ecodesign compliance into binding RFP criteria.
Hyperscale buyers are consolidating switching procurement under direct-to-fab contracts that bypass traditional distribution channels. Large cloud operators now negotiate merchant silicon allocation separately from hardware integration, fragmenting the value chain. This pattern is most visible in the United States, where top-three cloud providers account for disproportionate 800 Gbps port demand and have established captive supply relationships with foundry partners.
Data Center Networks Market Segmentation
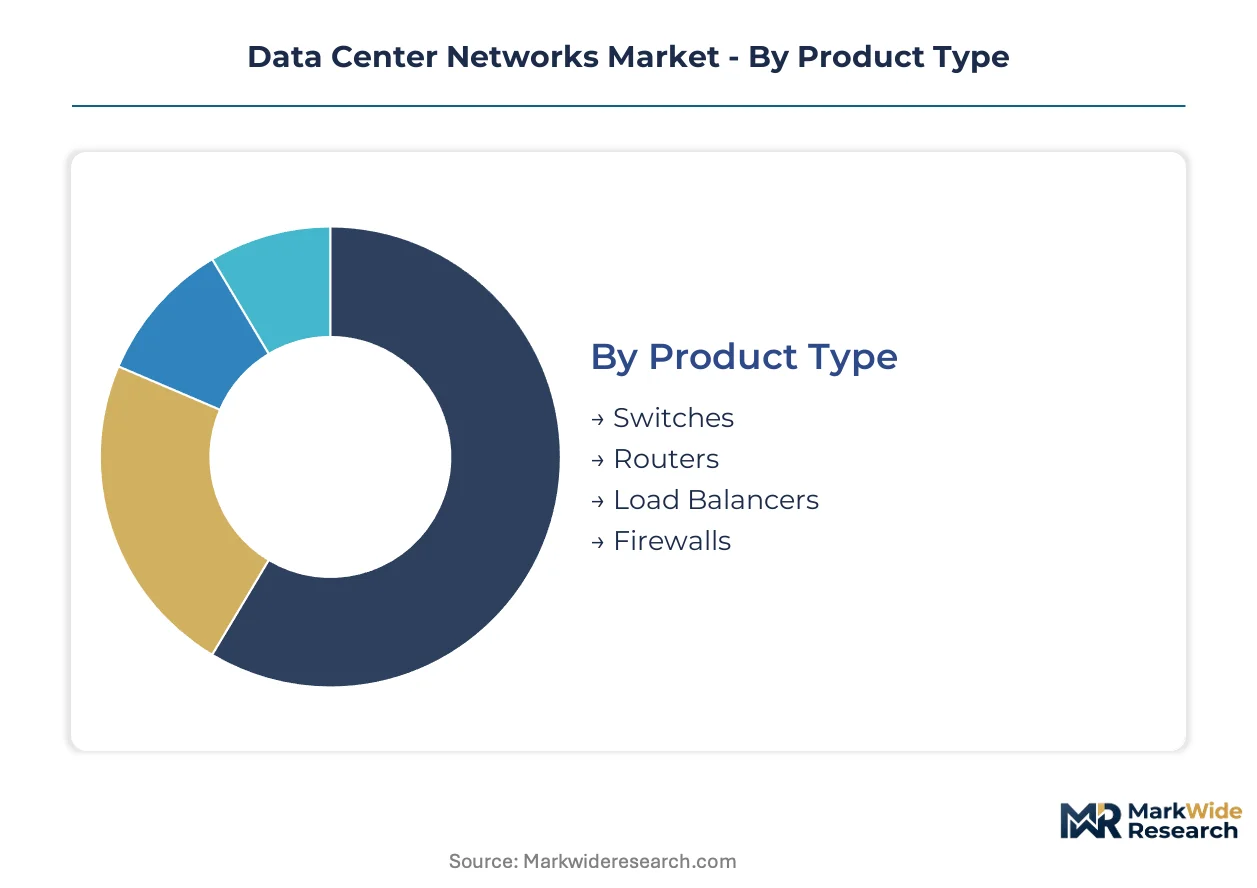
Segmentation in data center networks reveals how procurement criteria diverge between cost-optimized cloud operators and latency-sensitive enterprise workloads. Understanding these splits enables vendors to calibrate silicon roadmaps and channel strategies against actual deployment economics rather than aggregate demand signals.
Product Type:
Ethernet switches absorb the majority of port volume while specialized security appliances command premium pricing per rack unit.
- Switches:Merchant silicon-based spine and leaf platforms dominate hyperscale procurement, with 400 Gbps and 800 Gbps radix configurations now standard for AI training clusters. Cloud operators in Virginia's Northern Virginia corridor are absorbing record volumes of these devices as campus expansions accelerate.
- Routers:These devices handle facility-to-facility and WAN interconnects, with demand concentrating at internet exchange points and cloud on-ramps. FCC open internet rules shape certification requirements for US-based edge deployments, compressing vendor qualification timelines.
- Load Balancers:Application delivery controllers distribute traffic across server pools, with virtualized instances displacing hardware appliances in mid-market data centers.
- Firewalls:Next-generation platforms with deep packet inspection capabilities protect east-west traffic flows in zero-trust architectures.
Mature deployment sits with switches. Newer deployment is concentrated in software-defined load balancers.
Technology:
Physical layer protocols separate into volume Ethernet deployments and premium specialized interconnects for high-performance computing.
- Ethernet:The dominant transport protocol, standardized on IEEE 802.3 specifications from 100 Gbps to 800 Gbps per port. Merchant silicon from Broadcom and Marvell enables cost-scalable white-box switching for hyperscale operators.
- InfiniBand:Remote direct memory access capabilities deliver sub-microsecond latency for GPU-to-GPU communication in generative AI training clusters. NVIDIA's adapter convergence strategy anchors next-generation back-end network roadmaps for these deployments.
- Fibre Channel:Storage area network protocol maintains entrenched positions in enterprise disaster recovery environments despite Ethernet convergence pressure.
- MPLS:Multi-protocol label switching persists in carrier-managed WAN services connecting distributed data center footprints.
Enterprise legacy sits with Fibre Channel. Cloud-native expansion is climbing the fastest through converged Ethernet fabrics.
Application:
Workload gravity shifts favor cloud computing infrastructure over traditional virtualization and recovery use cases.
- Cloud Computing:Hyperscale operator demand for elastic compute and storage services drives port density requirements. AI training cluster density is forcing rearchitected spine-leaf topologies with compressed upgrade cycles from five years to eighteen months.
- Virtualization:Software-defined compute environments persist in enterprise private clouds, though growth has flattened as containerization displaces hypervisor-based workloads.
- Big Data:Analytics clusters require high-throughput east-west traffic patterns, with storage-class memory adoption reshaping network buffer requirements.
- Disaster Recovery:Synchronous replication between geographically separated facilities demands deterministic latency guarantees, favoring dedicated optical transport over switched fabrics.
Established spend sits with disaster recovery. Capacity expansion is gaining share fastest in cloud computing infrastructure.
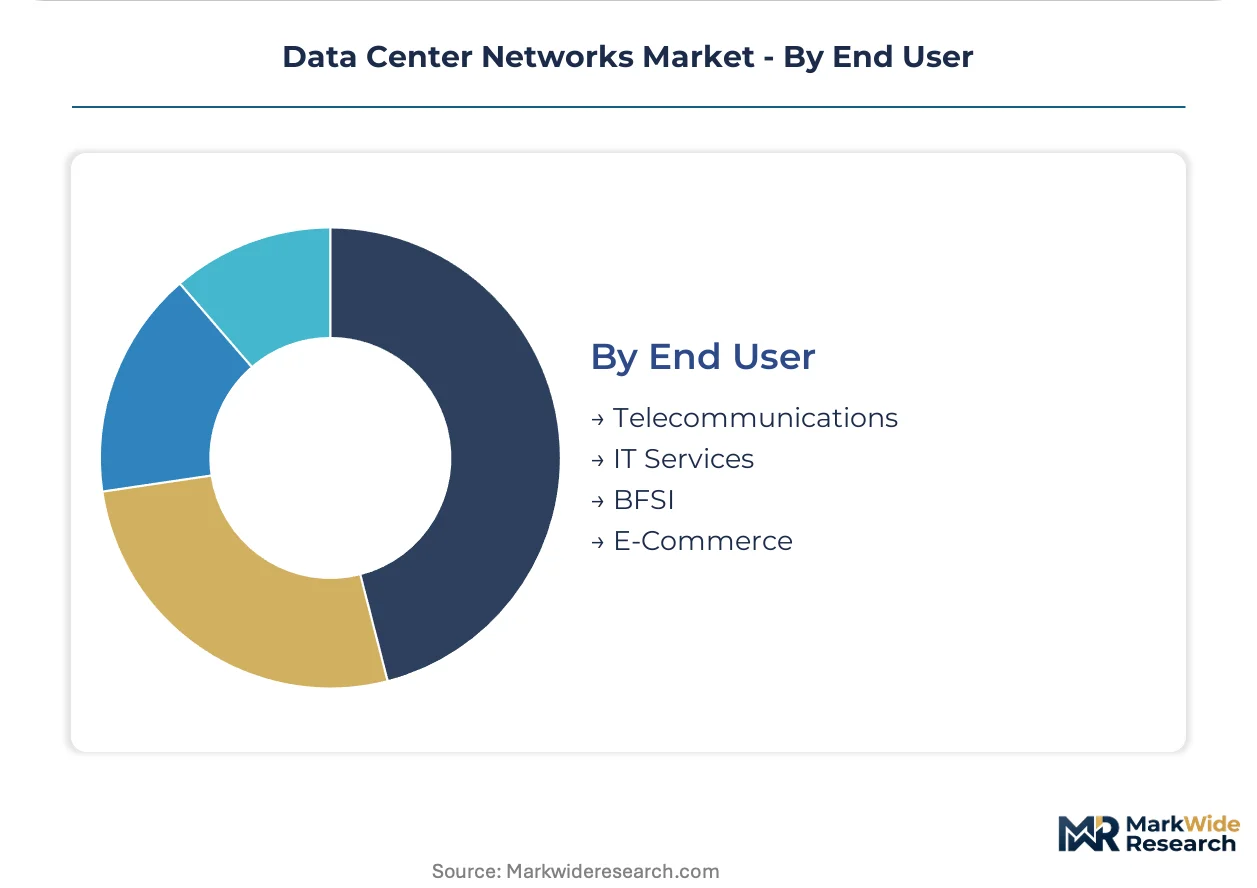
End User:
Vertical requirements diverge between bandwidth-intensive content delivery and latency-sensitive financial transaction processing.
- Telecommunications:5G core network virtualization drives edge data center buildouts, with Open RAN disaggregation creating new switching requirements at distributed radio access network sites.
- IT Services:Managed hosting and colocation providers face EU CSRD carbon disclosure mandates that favor energy-efficient switching fabrics with granular power-per-bit metrics.
- BFSI:Banking and financial services demand microsecond-precision timestamping and deterministic latency for algorithmic trading infrastructure.
- E-Commerce:Peak traffic resilience requirements during promotional events favor elastic cloud interconnects over fixed-capacity private deployments.
Regulatory pressure sits with IT services. Transaction volume growth is expanding most quickly in e-commerce infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States consumes the majority of high-radix switching capacity while merchant silicon fabrication concentrates in Taiwan and South Korea. This production-consumption divide shapes procurement vulnerability and regional investment patterns across the analysis window.
United States
Virginia's Northern Virginia corridor absorbs record 800 Gbps switch port volumes as hyperscale operators expand AI training campuses. FCC open internet rules compress equipment certification timelines for edge deployments. Ashburn and Loudoun County facilities now represent the densest fiber interconnect concentration outside of metropolitan cores.
Germany
Frankfurt's internet exchange points drive router demand for facility-to-facility interconnects. EU Ecodesign requirements enforce minimum power efficiency thresholds for network hardware sold across member states. Bavarian and Hesse data center clusters prioritize sub-5-watt-per-100G port solutions to meet binding CSRD carbon disclosure mandates.
India
Mumbai and Chennai greenfield facilities skip legacy 100 Gbps generations entirely, deploying 400 Gbps spine architectures from commissioning. TRAI infrastructure guidelines and state-level incentives attract hyperscale investment. Karnataka's Bengaluru corridor anchors domestic cloud operator expansion with direct-to-fab merchant silicon procurement.
Japan
Tokyo and Osaka financial services demand microsecond-precision timestamping for algorithmic trading infrastructure. METI efficiency standards accelerate adoption of liquid-cooled switching integration. Chubu region manufacturing data centers reshape network buffer requirements as storage-class memory adoption spreads.
Singapore
Marina Bay and Jurong East facilities serve as ASEAN cloud on-ramps, driving load balancer demand for traffic distribution across server pools. The country's central bank guidelines shape cybersecurity procurement specifications for critical infrastructure operators. Tropical thermal constraints accelerate direct-to-chip cooling deployment in high-density spine architectures.
Data Center Networks Market Competitive Environment
The competitive structure tilts toward merchant silicon-dependent fabricators with captive foundry relationships. Three tiers have crystallized: hyperscale-captive integrators negotiating direct-to-fab allocation, enterprise-focused branded vendors sustaining portfolio breadth through partnership models, and white-box specialists capturing cloud-native volume. M&A activity concentrates on optical interconnect capability and SDN orchestration software. Geographic expansion into India's greenfield buildout represents the dominant growth vector.
Among merchant silicon suppliers, Broadcom and Marvell occupy positions enabling cost-scalable white-box switching for volume procurement. Cisco Systems exemplifies the enterprise-branded archetype sustaining switching portfolio breadth across cloud and on-premise segments. Arista Networks represents the hyperscale-specialist position dominating high-radix spine architectures for AI training clusters.
| Leading Market Players |
|---|
| Cisco Systems |
| Arista Networks |
| NVIDIA |
| Juniper Networks |
| Hewlett Packard Enterprise |
| Dell Technologies |
| Intel Corporation |
| Broadcom |
| IBM Corporation |
| Others |
Value Chain & Pricing Dynamics
Merchant silicon tier divergence between hyperscale-direct procurement and enterprise-branded switching creates distinct pricing architectures and supply chain configurations. Cloud operators negotiating direct-to-fab allocation bypass traditional distribution markups, while enterprise buyers absorb channel premiums for integrated support services.
Pricing Analysis
Price erosion across enterprise-branded switches traces to hyperscale buyers consolidating procurement under captive foundry relationships. Three-tier pricing structure across premium InfiniBand, standard merchant silicon, and economy white-box platforms separates latency-sensitive AI training clusters from cost-optimized cloud fabrics. Certification investment for EU Ecodesign compliance and OSHA electrical safety drives differentiation. Enterprise procurement teams show highest price sensitivity as cloud migration accelerates, while AI cluster operators prioritize performance-per-watt over unit cost.
Supply Chain Analysis
Freight costs for advanced switching equipment remain secondary to foundry allocation premiums in total landed cost. Merchant silicon fabrication concentrates in Taiwan and South Korea, with assembly and integration distributed across Malaysia and Mexico. Supply chain vulnerability rests on single-geography ASIC production exposed to geopolitical disruption. Distribution runs through hyperscale-direct contracts that fragment traditional channel structures, bypassing distributors for top cloud operators while preserving two-tier models for mid-market enterprise sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Merchant silicon supply concentration and compressed upgrade cycles favor scale players with captive foundry access, forcing smaller fabricators toward niche specialization or exit.
For Market Incumbents: Extend merchant silicon partnerships to secure allocation priority as AI training cluster demand accelerates port speed transitions. Build captive optical interconnect capabilities to offset co-packaged optics supply chain decentralization. EU CSRD carbon disclosure mandates create defensive moat for vendors with sub-5-watt-per-100G port solutions already qualified. For New Entrants and Emerging Players: EU Ecodesign requirements in Germany and France open a window for energy-efficient switching specialists to penetrate European cloud and colocation procurement. India's greenfield data center buildout offers white-space entry as facilities skip legacy 100 Gbps generations entirely. Position around liquid-cooled switching integration as established vendors optimize air-cooled architectures. For Investors and Strategic Acquirers: Re-rating potential sits with optical interconnect capability owners given co-packaged optics procurement power shifts toward merchant silicon suppliers. Long-term viability favors specialists with SDN orchestration software and heterogeneous control plane integration expertise. Watch hyperscale capex disclosure inflections for 800 Gbps deployment cadence signals.| Strategic Initiative | Industry Significance |
|---|---|
| Merchant Silicon Partnership Extension | Secures foundry allocation priority for 51.2 Tbps radix switch production. |
| Co-Packaged Optics Capability Acquisition | Captures procurement power shift from discrete transceiver vendors toward ASIC-integrated designs. |
| Liquid-Cooled Switching Integration | Enables rack-scale thermal management for AI training clusters exceeding air-cooled density limits. |
| EU Ecodesign Compliance Investment | Creates binding RFP qualification barrier for European cloud and colocation procurement. |
| India Greenfield Market Entry | Captures 400 Gbps spine architecture demand as facilities bypass legacy 100 Gbps generations. |
Study Parameters
SEC filings, hyperscaler capital expenditure disclosures, and customs trade records formed the secondary backbone for demand quantification. Primary interviews with data center procurement officers, network engineering leads at cloud operators, and merchant silicon supplier strategy teams validated deployment timelines and technology transition assumptions. Bottom-up port shipment analysis triangulated against top-down infrastructure investment tracking across the analysis window.
Bottom-up modeling aggregated switch port shipments by speed tier and deployment topology, while top-down analysis calibrated against facility power capacity expansion and fiber interconnect investment. Segmentation dimensions included product type, technology protocol, application workload, and end-user vertical. CAGR derivation incorporated AI training cluster density trajectories and regulatory-driven refresh acceleration in European markets.
The model assumes a particular technology adoption path; alternative pathways for co-packaged optics or liquid-cooled switching would alter the outlook. Forecasts reflect assumptions about merchant silicon foundry capacity allocation and hyperscale buyer consolidation trends. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
SDN Orchestration Market
Data Center and Networking
Network As a Service (Naas) Market
Data Center and Networking
Ethernet Transceivers Market
Data Center and Networking
Edge Server Market
Data Center and Networking
Data Center Servers Market
Data Center and Networking
United States Data Center Networking Market
Data Center and Networking
Global Subscriber Data Management Market
Data Center and Networking
Hong Kong Data Center Networking Market
Data Center and Networking
Nosql Market
Data Center and Networking
Network Virtualization Software Market
Data Center and Networking
Saudi Arabia Data Center Networking Market
Data Center and Networking
Europe Data Center Market
Data Center and Networking
Internet Protocol Television (IPTV) Content Delivery Network (CDN) Market
Data Center and Networking
Indonesia Data Center Networking Market
Data Center and Networking
Communications Service Provider (CSP) Network Market
Data Center and Networking
5G Edge Cloud Network and Services Market