
 Data Center Direct-to-Chip Coolant Fluids Market | 2026-2036
Data Center Direct-to-Chip Coolant Fluids Market Size, Share, and Industry Trends Forecast 2026-2036
Data Center Direct-to-Chip Coolant Fluids Market Insights
Specialty chemical producers in Germany and the United States is realigning capacity toward dielectric fluid formulations optimized for direct-to-chip thermal management. Castrol leverages its synthetic lubricant heritage to develop low-viscosity hydrocarbon coolants with precise boiling-point engineering. 3M sustains technology leadership in fluorinated dielectric fluids despite regulatory pressure on perfluorinated chemistries. ExxonMobil anchors supply security through backward integration into base stock refining and additive blending.
Data Center Direct-to-Chip Coolant Fluids are thermally engineered dielectric liquids formulated with specific heat capacity above two kilojoules per kilogram-kelvin and electrical resistivity exceeding ten-to-the-fourteenth ohm-centimeter, designed to absorb and transport heat directly from processor dies through cold plate or microchannel interfaces without shorting electronic components. Single-phase hydrocarbon formulations currently dominate installed capacity due to material compatibility and lower cost per liter, while two-phase fluorocarbon systems command premium positioning in hyperscale facilities where phase-change latent heat enables extreme power density. Glycol-based blends occupy a narrowing mid-market niche as thermal performance limitations constrain deployment in next-generation GPU clusters exceeding one thousand watts per socket.
The EPA SNAP program restricts high-global-warming-potential fluorinated fluids in commercial refrigeration and data center applications, compelling fluid suppliers to reformulate toward hydrofluoroether alternatives or abandon fluorinated chemistries entirely. The EU F-Gas Regulation mandates phasedown of hydrofluorocarbon production quotas, directly constraining availability of legacy dielectric coolants across European data center builds. Stakeholders must monitor evolving material safety thresholds from NMPA in China and METI in Japan, as divergence in regional toxicity and biodegradability standards will fragment product qualification requirements and complicate global fleet deployments.
Market Dynamics
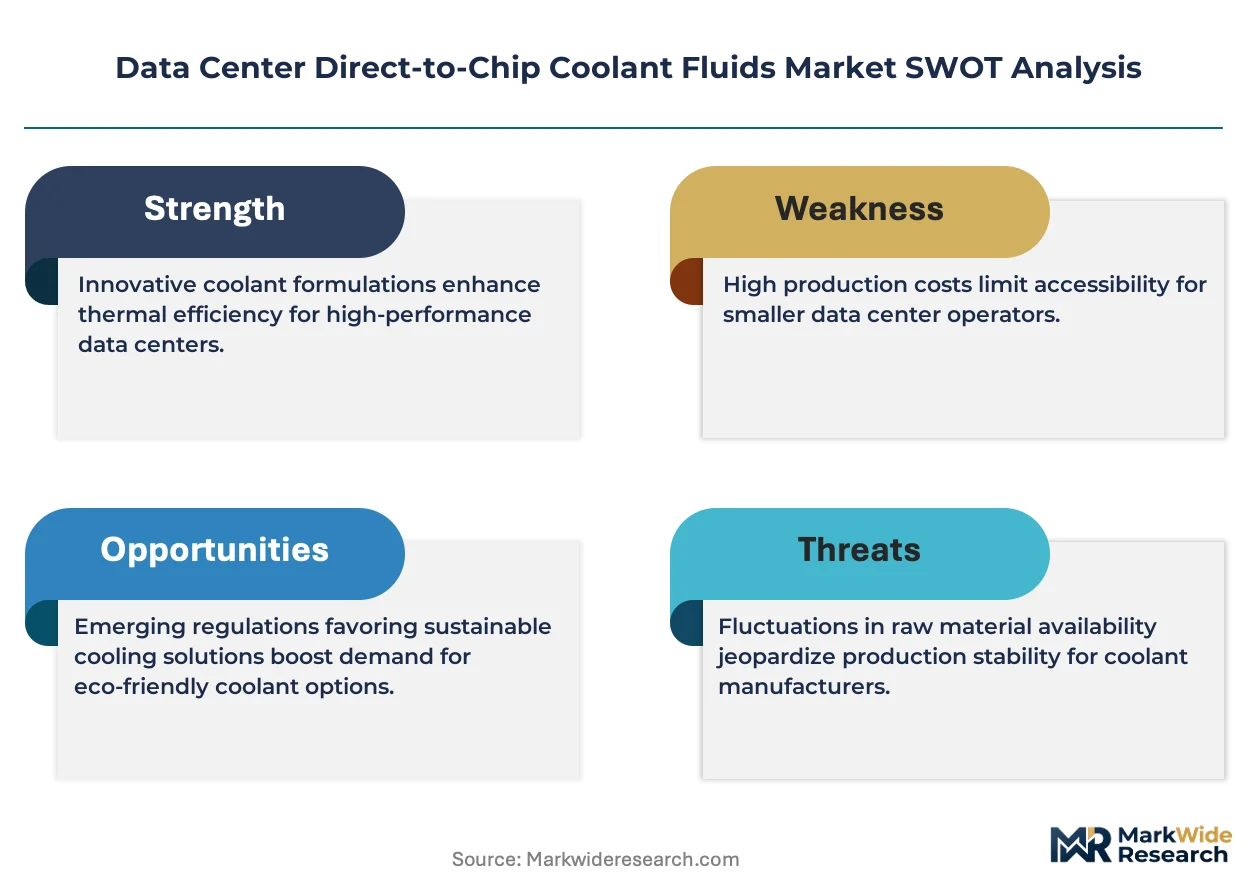
The EPA SNAP program and EU F-Gas Regulation are compressing the addressable market for high-GWP fluorinated dielectric fluids while simultaneously accelerating capital flows toward hydrocarbon and silicone alternatives. This regulatory compression is restructuring supplier R&D priorities and procurement specifications across hyperscale data center operators.
Growth Catalysts
- AI Training Cluster Density:Hyperscale cloud operators in the United States and Germany are specifying direct-to-chip cooling for GPU sockets exceeding 1000 watts, creating immediate demand pull for advanced dielectric formulations.
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon production quotas is forcing European data center builds to qualify lower-carbon coolant alternatives ahead of legacy supply constraints.
- Single-Phase Hydrocarbons:Material compatibility advantages and cost-per-liter economics are driving rapid qualification of synthetic hydrocarbon formulations for mainstream deployment.
Market Restraints
- Fluorinated Feedstock Concentration:Three chemical conglomerates control the majority of perfluorinated base stock refining capacity, creating supply vulnerability for premium two-phase systems.
- Electrical Resistivity Thresholds:Dielectric fluids must maintain resistivity above 10^14 ohm-centimeter across operating temperature ranges, eliminating marginal formulations from qualification.
- Glycol Thermal Ceiling:Heat capacity limitations of glycol-water blends constrain deployment in next-generation GPU clusters, narrowing the addressable mid-market segment.
Strategic Opportunities
- Japan AI Infrastructure Buildout:METI-backed semiconductor packaging initiatives are driving demand for precision-engineered coolants in Tokyo and Osaka data center corridors.
- Two-Phase Silicone Systems:Phase-change latent heat properties of engineered silicone fluids enable extreme power density without fluorinated chemistry regulatory exposure.
- Direct Procurement Channels:Hyperscale operators are bypassing traditional distribution to negotiate formulation-specific supply agreements with specialty chemical producers.
Industry Challenges
- Thermal Engineer Scarcity:Direct-to-chip system design requires expertise in microchannel fluid dynamics and dielectric material science that outpaces current training pipeline output.
- Multi-Jurisdiction Qualification:Divergent toxicity and biodegradability standards from EPA, ECHA, and NMPA force redundant testing protocols that extend product launch timelines.
- Cold Plate Integration Complexity:Retrofitting legacy server architectures with direct-to-chip manifolds demands precision machining capabilities that strain contract manufacturer capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Data Center Direct-to-Chip Coolant Fluids Market |
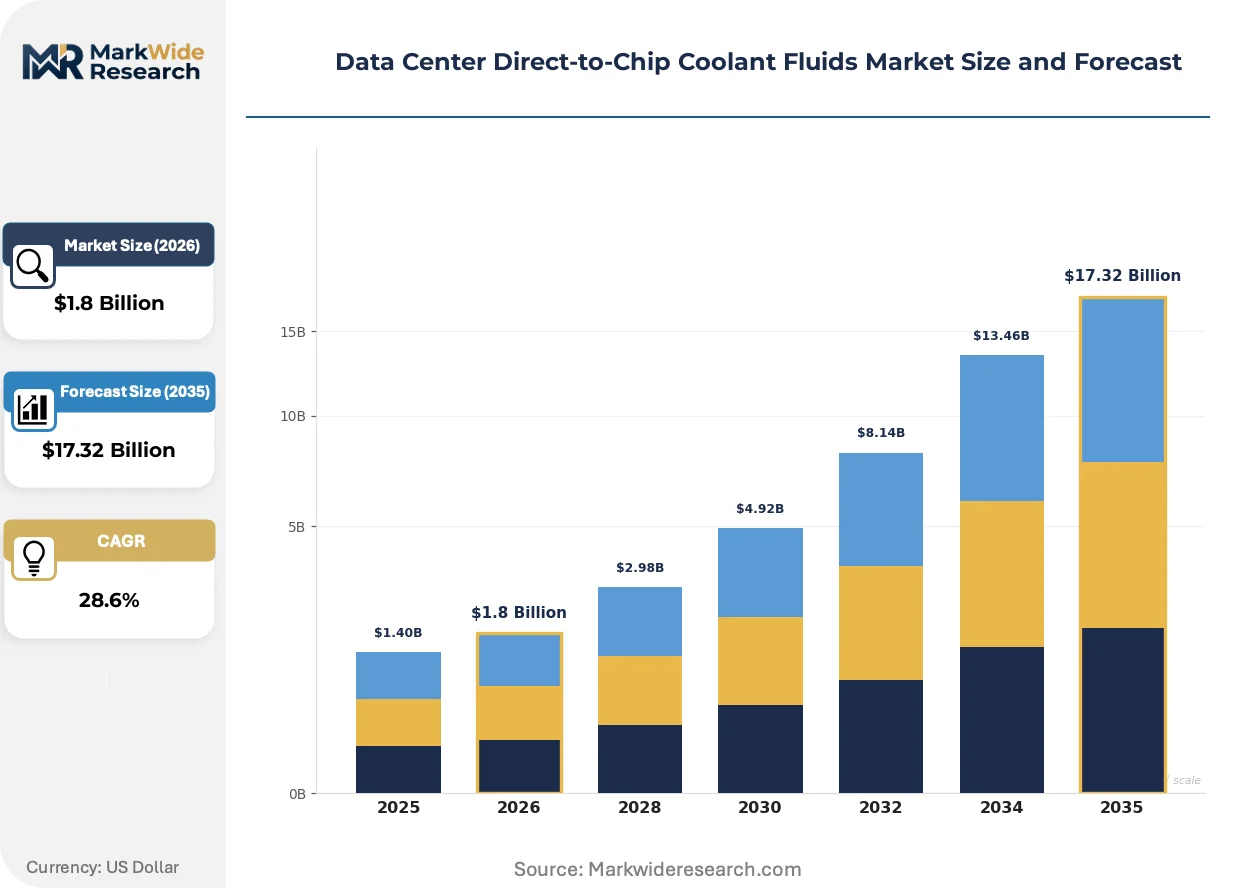
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $17.32 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fluorocarbon, Hydrocarbon, Silicone, Glycol-Based, Ionic Liquids Technology: Single-Phase Cooling, Two-Phase Cooling, Immersion Cooling, Spray Cooling, Microchannel Cooling Application: High-Performance Computing, Cloud Data Centers, Edge Data Nodes, Hyperscale Facilities, Colocation Centers End User: Cloud Service Providers, Telecommunication Firms, Research Institutions, Data Center Operators, Content Delivery Networks |
| Companies Covered | Castrol, ExxonMobil, 3M, LiquidStack, CoolIT Systems, Asetek, Vertiv, Schneider Electric, Submer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Data Center Direct-to-Chip Coolant Fluids Market Trends and Innovations
Formulation chemistry is pivoting away from fluorinated dielectrics toward engineered hydrocarbons and silicones as regulatory pressure compounds thermal performance requirements. This shift is reshaping supplier competitive advantages and procurement evaluation criteria.
Synthetic hydrocarbon coolants with viscosity-optimized molecular structures are overtaking fluorinated alternatives in hyperscale qualification programs. These formulations deliver comparable heat capacity at reduced material cost while eliminating regulatory compliance exposure. Google and Microsoft procurement teams have accelerated hydrocarbon qualification timelines from 18 months to 8 months. The technology is overtaking legacy fluorocarbon positioning in all new-build specifications outside specialized two-phase applications.
The EPA SNAP program restrictions on high-GWP fluorinated fluids are eliminating incumbent chemistries from data center applications. Industrial consequence includes forced reformulation of entire product lines and abandonment of perfluorinated R&D pipelines. European suppliers are responding fastest, with German chemical producers already shipping hydrofluoroether alternatives while US competitors retain legacy fluorinated inventories.
Specification authority is migrating from facilities engineering to silicon procurement teams as coolant selection becomes inseparable from GPU thermal design power envelopes. Channel disruption follows as hyperscale buyers negotiate directly with formulation houses, compressing distributor margins. This pattern is most visible in United States and Germany, where AI cluster deployment concentration creates procurement scale sufficient to justify direct supplier relationships.
Data Center Direct-to-Chip Coolant Fluids Market Segmentation
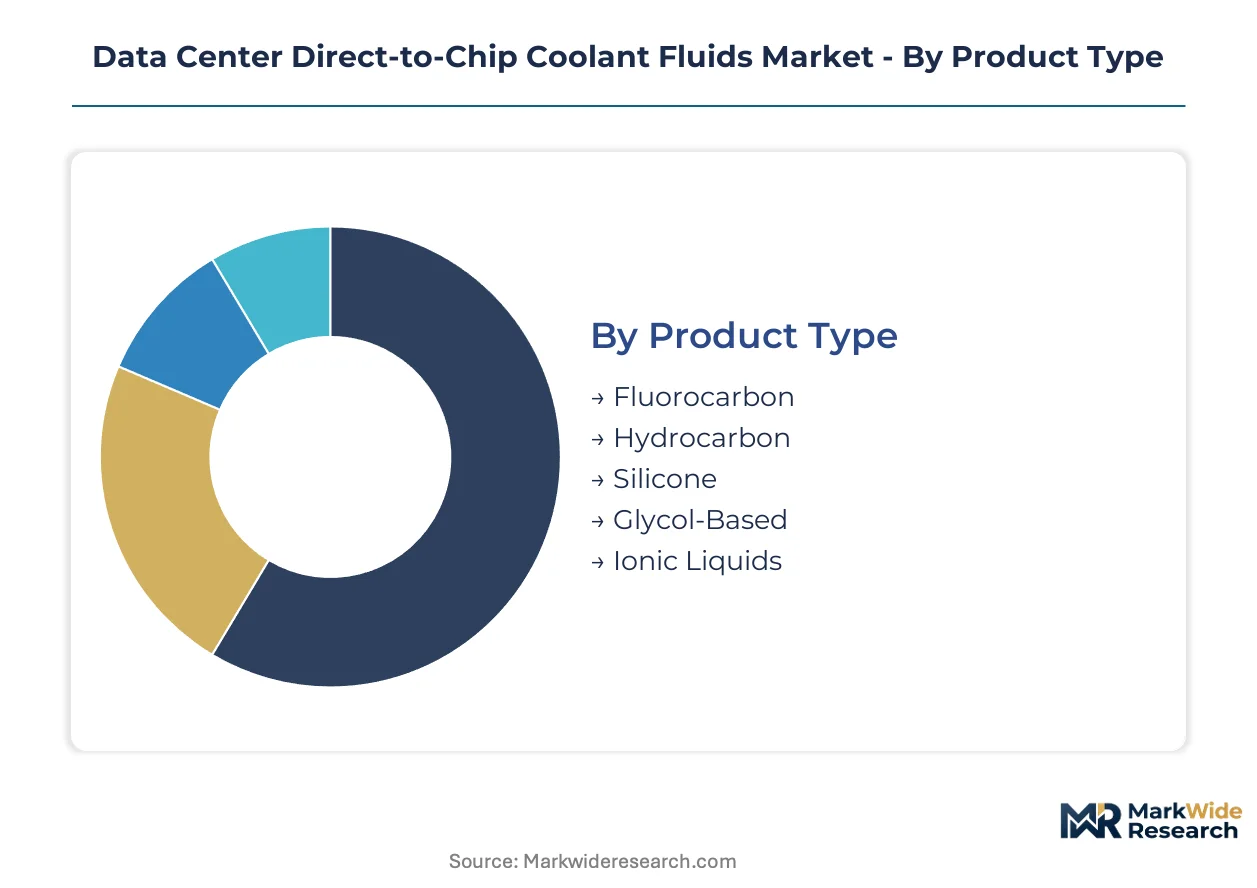
Direct-to-chip coolant selection hinges on thermal design power envelopes and integration architecture. Procurement teams evaluate fluids against dielectric strength, viscosity curves, and regulatory compliance profiles rather than cost alone.
Product Type:
Standalone dielectric formulations dominate new-build specifications, while embedded coolant systems require material compatibility with server-grade substrates.
- Fluorocarbon:Perfluorinated dielectric fluids deliver resistivity above 10^15 ohm-centimeter and precise boiling-point engineering for two-phase systems. Demand concentrates in hyperscale facilities across Germany and the United States where phase-change latent heat enables GPU clusters exceeding 1000 watts per socket, though EPA SNAP restrictions are compressing future deployment.
- Hydrocarbon:Synthetic alkane formulations with viscosity-optimized molecular structures achieve heat capacity above 2 kJ/kg-K at reduced material cost. Cloud operators in the United States have accelerated qualification timelines from 18 months to 8 months, displacing fluorocarbons in mainstream single-phase applications.
- Silicone:Engineered siloxane fluids combine phase-change thermal management with regulatory compliance outside fluorinated chemistry exposure.
- Glycol-Based:Ethylene and propylene glycol blends occupy legacy installations where thermal loads remain below next-generation thresholds.
- Ionic Liquids:Salt-derived non-aqueous electrolytes enable extreme electrical resistivity with negligible vapor pressure for specialized aerospace and defense computing.
Hydrocarbon leads volumes today; silicone is gaining share fastest.
Technology:
Cost tier separation emerges between precision-manufactured microchannel systems and commodity cold-plate configurations.
- Single-Phase Cooling:Forced convection through cold plate interfaces dominates installed capacity due to mechanical simplicity and maintenance accessibility. Hyperscale operators in Germany specify synthetic hydrocarbon single-phase systems for AI training clusters, prioritizing material compatibility over maximum thermal performance.
- Two-Phase Cooling:Boiling and condensation cycles exploit latent heat absorption for extreme power density applications. Facilities in the United States deploy fluorocarbon two-phase systems where chip-level heat flux exceeds 500 W/cm², constrained by feedstock concentration among three chemical conglomerates.
- Immersion Cooling:Submersion of entire server assemblies in dielectric baths eliminates cold plate machining complexity.
- Spray Cooling:Atomized dielectric impingement targets hotspot management for military and aerospace electronics.
- Microchannel Cooling:Etched silicon or copper manifolds enable millimeter-scale fluid routing for 3D-stacked memory architectures.
Single-phase cooling commands the largest installed base; microchannel cooling is climbing the fastest.
Application:
Volume concentration tracks AI infrastructure deployment corridors with distinct thermal density requirements.
- Hyperscale Facilities:Purpose-built data centers exceeding 50 megawatts of critical IT load specify direct-to-chip cooling as standard for GPU-intensive workloads. Operators in the United States and Germany are qualifying hydrocarbon and silicone formulations ahead of legacy fluorocarbon constraints, with procurement authority migrating from facilities engineering to silicon procurement teams.
- Cloud Data Centers:Multi-tenant compute environments balance thermal performance against operational flexibility and tenant certification requirements.
- High-Performance Computing:National laboratory and research installations demand precision thermal control for simulation workloads.
- Edge Data Nodes:Distributed computing sites prioritize passive or low-power cooling due to remote maintenance limitations.
- Colocation Centers:Third-party hosting providers face retrofit constraints from legacy raised-floor architectures and multi-tenant liability structures.
Hyperscale facilities anchor current demand; cloud data centers show steepest expansion trajectory.
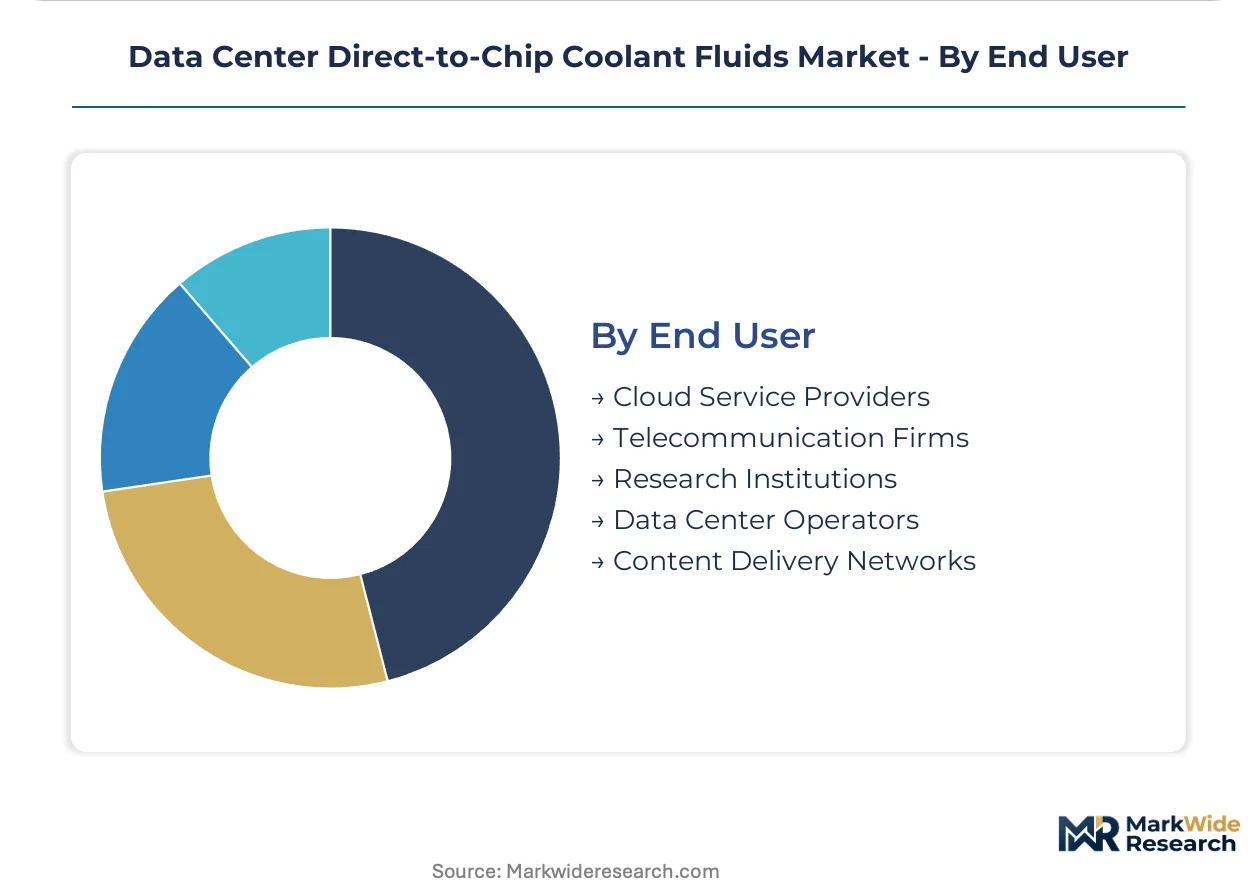
End User:
Procurement scale and technical specification authority vary sharply across customer categories.
- Cloud Service Providers:Amazon Web Services, Microsoft Azure, and Google Cloud Platform negotiate formulation-specific supply agreements directly with specialty chemical producers, bypassing traditional distribution channels. Their United States and Germany procurement teams have compressed qualification cycles and forced hydrocarbon formulation pivots.
- Data Center Operators:Equinix, Digital Realty, and CyrusOne manage multi-tenant thermal infrastructure with heterogeneous client requirements.
- Telecommunication Firms:5G edge computing deployments drive demand for compact, low-maintenance cooling solutions.
- Research Institutions:National laboratories and university computing centers specify custom thermal solutions for scientific simulation workloads.
- Content Delivery Networks:Cache-optimized architectures prioritize reliability and geographic distribution over maximum compute density.
Cloud service providers dominate specification authority; data center operators represent the most price-sensitive volume segment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States and Germany currently outpace all other markets in direct-to-chip coolant procurement velocity, though Japan's METI-backed semiconductor initiatives are compressing qualification timelines for precision-engineered formulations. Regulatory divergence across these three jurisdictions is fragmenting product approval pathways and forcing suppliers to maintain parallel formulation portfolios.
United States
Hyperscale cloud operators in Northern Virginia and Phoenix are specifying synthetic hydrocarbon coolants for GPU clusters exceeding 1000 watts per socket. The EPA SNAP program restricts high-GWP fluorinated fluids in commercial data center applications, compelling reformulation toward hydrofluoroether alternatives. Microsoft and Google procurement teams in Redmond and Mountain View have compressed hydrocarbon qualification cycles from 18 months to 8 months.
Germany
Frankfurt and Berlin data center corridors are driving European demand for single-phase hydrocarbon systems ahead of EU F-Gas Regulation phasedown deadlines. The ECHA oversees material safety thresholds for dielectric fluids entering the European market. Bavarian chemical producers are already shipping hydrofluoroether alternatives while competitors retain legacy fluorinated inventories.
Japan
METI-backed advanced semiconductor packaging initiatives in Tokyo and Osaka are creating demand for precision-engineered coolants in 3D-stacked memory architectures. The country's national chemical regulator maintains stringent toxicity and biodegradability standards that exceed baseline international requirements. Kanto region data center builds are specifying silicone-based two-phase systems to avoid fluorinated chemistry regulatory exposure.
China
Domestic cloud providers in Beijing and Shanghai are qualifying local hydrocarbon formulations as NMPA material safety thresholds diverge from Western standards. The Ministry of Ecology and Environment enforces dual carbon goals that constrain high-GWP coolant deployment in state-backed facilities. Yangtze River Delta data center clusters are prioritizing single-phase systems with in-country additive blending capabilities.
United Kingdom
Slough and London Docklands colocation facilities face retrofit constraints from legacy raised-floor architectures and multi-tenant liability structures. The Health and Safety Executive aligns with EU F-Gas Regulation phasedown timelines post-Brexit transition periods. Thames Valley data center operators are evaluating silicone alternatives as fluorocarbon supply quotas tighten across European supply chains.
Data Center Direct-to-Chip Coolant Fluids Market Competitive Landscape
German and United States producers anchor one tier; Japanese and Chinese specialists hold regional supply positions with formulation adaptations for local regulatory regimes. The supplier base concentrates around three chemical conglomerates controlling perfluorinated base stock refining capacity, creating supply vulnerability for premium two-phase systems. Strategic archetypes include backward-integrated petroleum majors, synthetic lubricant heritage players, and fluorinated chemistry specialists. Dominant competitive moves span capacity realignment toward hydrocarbon formulations and direct procurement channel establishment with hyperscale operators.
Within the synthetic lubricant heritage tier, Castrol leverages its formulation expertise to develop low-viscosity hydrocarbon coolants with precise boiling-point engineering. ExxonMobil anchors supply security through captive base stock refining and additive blending capabilities. 3M occupies a position within the fluorinated chemistry specialist archetype, sustaining technology leadership despite regulatory pressure on perfluorinated chemistries. These three entities exemplify the competitive positioning required to serve procurement teams migrating specification authority from facilities engineering to silicon procurement organizations.
| Leading Market Players |
|---|
| Castrol |
| ExxonMobil |
| 3M |
| LiquidStack |
| CoolIT Systems |
| Asetek |
| Vertiv |
| Schneider Electric |
| Submer |
| Others |
Pricing and Supply Chain Analysis
Performance-grade bifurcation between fluorinated dielectric fluids and synthetic hydrocarbon alternatives manifests in divergent margin structures and procurement channel configurations across the Data Center Direct-to-Chip Coolant Fluids Market. Premium two-phase fluorocarbon formulations command elevated unit economics through concentrated feedstock control, while hydrocarbon qualification acceleration by United States hyperscale operators compresses distributor margins and forces direct supplier relationships.
Pricing Analysis
Distributor margin compression dominates channel economics as hyperscale cloud operators negotiate direct formulation-specific supply agreements with specialty chemical producers. Three-tier pricing structure across premium fluorocarbon, standard hydrocarbon, and economy glycol-based tiers reflects certification grade and thermal performance thresholds. Price differentiation stems from electrical resistivity certification and volume scale commitments. Cost compression in standard hydrocarbon tiers is intensifying because Google and Microsoft procurement teams have compressed qualification cycles. Data center operators represent the most price-sensitive volume segment, while cloud service providers prioritize thermal performance over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand, bypassing traditional distribution networks and compressing intermediary margins. Supply concentrates in Germany, the United States, and Japan, where specialty chemical producers maintain formulation expertise and regulatory compliance infrastructure. Raw material dependencies include perfluorinated base stocks, synthetic alkane feedstocks, and engineered silicone precursors. Single-source vulnerability characterizes perfluorinated base stock refining, with three chemical conglomerates controlling majority capacity. Distribution runs through direct procurement agreements for hyperscale volumes and regional distributors for mid-market segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Data Center Direct-to-Chip Coolant Fluids Market functions as a regulatory compounder where EPA SNAP restrictions on high-GWP fluorinated fluids and EU F-Gas Regulation phasedown mandates create irreversible demand migration toward hydrocarbon and silicone alternatives.
For Market Incumbents: Deploy backward integration into base stock refining to secure feedstock autonomy against perfluorinated supply concentration. German and United States producers must accelerate hydrocarbon capacity realignment ahead of EU F-Gas quota constraints. Fluorinated chemistry specialists face substitution threat from silicone two-phase systems and must diversify formulation portfolios to maintain hyperscale procurement relationships. For New Entrants and Emerging Players: Digital-channel direct procurement platforms offer white-space entry around mid-market data center operators underserved by incumbent direct-sales organizations. Japan's METI-backed semiconductor packaging initiatives present the most penetrable geography for precision-engineered silicone formulations. Cloud data center retrofit applications represent underserved volume with lower qualification barriers than hyperscale new-build specifications. For Investors and Strategic Acquirers: Consolidation pressure builds where formulation expertise overlaps with regulatory compliance infrastructure across multiple jurisdictions. Long-term viability favors suppliers with parallel hydrocarbon and silicone portfolios capable of serving fragmented global standards. Acquisition target archetype: regional specialists with NMPA or METI certification assets. Signal to watch: divergence in toxicity thresholds between EPA, ECHA, and Asian regulators accelerating product launch timeline fragmentation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Base Stock Refining | ExxonMobil's captive supply of synthetic alkane feedstocks insulates margin position against petrochemical volatility. |
| Hydrocarbon Formulation Pivot | Castrol's low-viscosity synthetic coolant development captures hyperscale qualification cycles compressed by Google procurement teams. |
| Direct Procurement Channel Establishment | Microsoft Azure's formulation-specific supply agreements bypass distributor margins and lock in volume commitments. |
| Multi-Jurisdiction Regulatory Certification | 3M's parallel EPA SNAP and EU F-Gas compliance investments preserve fluorinated chemistry positioning in specialized applications. |
| Silicone Two-Phase System Development | Japanese chemical producers' engineered siloxane fluids enable extreme power density without perfluorinated regulatory exposure. |
Research Methodology
Multiple input streams — hyperscale procurement officer interviews, specialty chemical producer technical director consultations, and regulatory affairs specialist dialogues — were reconciled against customs trade data, SEC 10-K filings, and EPA SNAP program dockets. Secondary validation drew from ECHA substance registration databases, METI chemical safety notifications, and NMPA material approval records. Bottom-up volume modeling across coolant formulation types and top-down market sizing through end-use application analysis were cross-referenced for triangulation.
Historical shipment patterns were cross-referenced against expert panel inputs from thermal engineering directors and data center facilities planners. Segmentation dimensions modeled include coolant chemistry type, cooling technology architecture, facility application scale, and end-user procurement authority across the projection horizon. CAGRs were derived through regression analysis of hyperscale capex deployment corridors and thermal design power trajectories. Industry-specific forecast inputs encompass GPU socket power envelope evolution and regulatory phasedown timeline assumptions.
Regulatory enforcement delays, alternative cooling technology disruption, and feedstock supply concentration shocks are the dominant revision risks to baseline projections. Forecasts reflect documented assumptions regarding qualification timeline compression and hydrocarbon adoption curves. Periodic stress-testing of base assumptions against EPA rulemaking updates and EU quota allocation announcements is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Singapore Data Center Server Market
Data Center Infrastructure
Sweden Data Center Power Market
Data Center Infrastructure
Data Center Fabric Market
Data Center Infrastructure
South Korea Data Center Market
Data Center Infrastructure
Norway Data Center Server Market
Data Center Infrastructure
Europe Data Center Colocation Market
Data Center Infrastructure
Thailand Data Center Power Market
Data Center Infrastructure
Dedicated Server Hosting Market
Data Center Infrastructure
Blade Server Market
Data Center Infrastructure
Japan Data Center Market
Data Center Infrastructure
South Africa Data Center Rack Market
Data Center Infrastructure
Asia-Pacific Data Center Power Market
Data Center Infrastructure
Belgium Data Center Rack Market
Data Center Infrastructure
Belgium Data Center Power Market
Data Center Infrastructure
Global Cloud Infrastructure Service Market
Data Center Infrastructure
Advanced Data Center Infrastructure Market