
 Chile Data Center Cooling Market | 2026-2036
Chile Data Center Cooling Market Size, Share, and Industry Trends Forecast 2026-2036
Chile Data Center Cooling Market Insights
The direct sales and systems integration channel is rewriting how cooling equipment reaches Chilean data center operators. Schneider Electric SE leverages its local engineering presence to anchor large-scale projects in Santiago. Vertiv Group Corp competes through service density across Chile's emerging Tier-III facilities. Stulz GmbH specializes in precision climate units for high-altitude deployments where thermal efficiency drops.
Data center cooling encompasses engineered systems that regulate temperature, humidity, and airflow within server environments, typically operating within N+1 redundancy architectures with chilled water supply temperatures between 7°C and 12°C. These systems prevent thermal throttling of compute hardware and sustain uptime commitments in facilities ranging from 500 kW edge nodes to 30 MW hyperscale campuses. Air cooling still occupies the majority of installed base across Chilean colocation facilities, though liquid cooling is accelerating fastest among cloud providers deploying GPU-intensive AI workloads. Free cooling technology leads margin pools in the Atacama-adjacent northern zones where ambient temperatures permit extended economizer hours.
Chile's Ministry of Energy efficiency standards and the Superintendency of the Environment air quality protocols are tightening permissible power usage effectiveness thresholds for new data center construction. The country's central bank cybersecurity frameworks indirectly shape cooling redundancy requirements through operational resilience mandates. Stakeholders must monitor how Santiago's grid congestion and renewable curtailment patterns interact with cooling load profiles as capacity scales.
Market Dynamics
GPU-intensive AI workloads are forcing Chilean data center operators to abandon air-cooled architectures faster than infrastructure depreciation cycles allow, compressing the upgrade window for Santiago's colocation providers.
Growth Catalysts
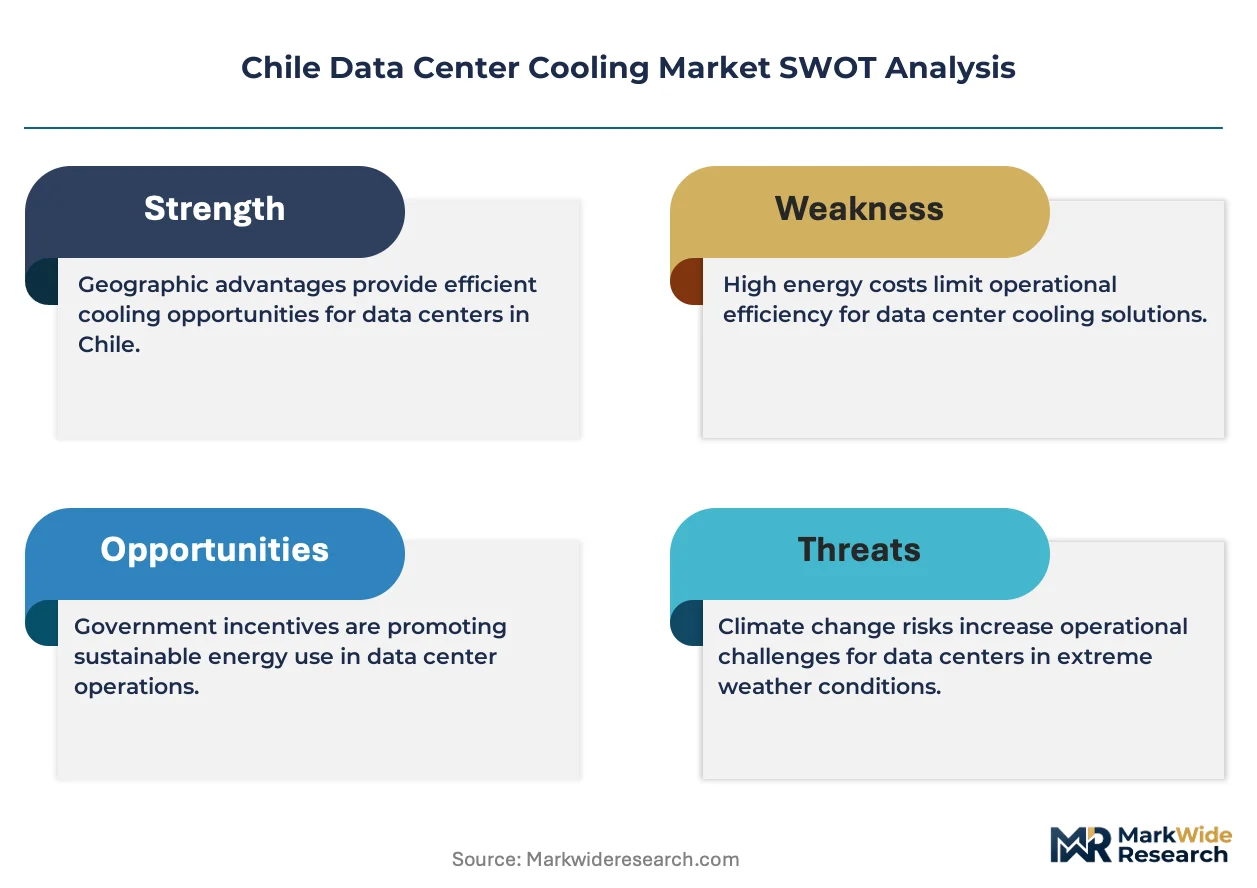
- Superintendency of the Environment air quality protocols:The tightening PUE thresholds for new construction are mandating economizer upgrades that free cooling technology suppliers can capture.
- Cloud provider expansion:Hyperscale campuses in the Santiago Metropolitan Region are pulling precision cooling capacity through direct procurement channels.
- Atacama-adjacent free cooling zones:Extended economizer hours in northern Chile are creating margin advantages for facilities locating near renewable energy clusters.
Market Restraints
- Liquid cooling infrastructure capex:The capital intensity of CDU deployment and coolant distribution networks limits Tier-II facility upgrades.
- Chilled water supply chain concentration:Chile's limited domestic chiller manufacturing creates import dependency for large-capacity units.
- Grid congestion in Santiago:Distribution network constraints restrict cooling load scaling before generation capacity binds.
Strategic Opportunities
- Valparaíso submarine cable landing zones:Secondary coastal markets offer lower land costs for edge deployments requiring precision climate control.
- Ministry of Energy efficiency code convergence:Updated standards for critical infrastructure create retrofit demand across existing facilities.
- Immersion cooling and waste heat recovery:Technology convergence enables district heating tie-ins with nearby industrial zones.
Industry Challenges
- Thermal-fluid engineering talent scarcity:Liquid cooling specialization outpaces Chilean technical education pipeline output.
- N+1 redundancy certification timelines:Central bank cybersecurity resilience mandates extend commissioning schedules for critical cooling systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chile Data Center Cooling Market |
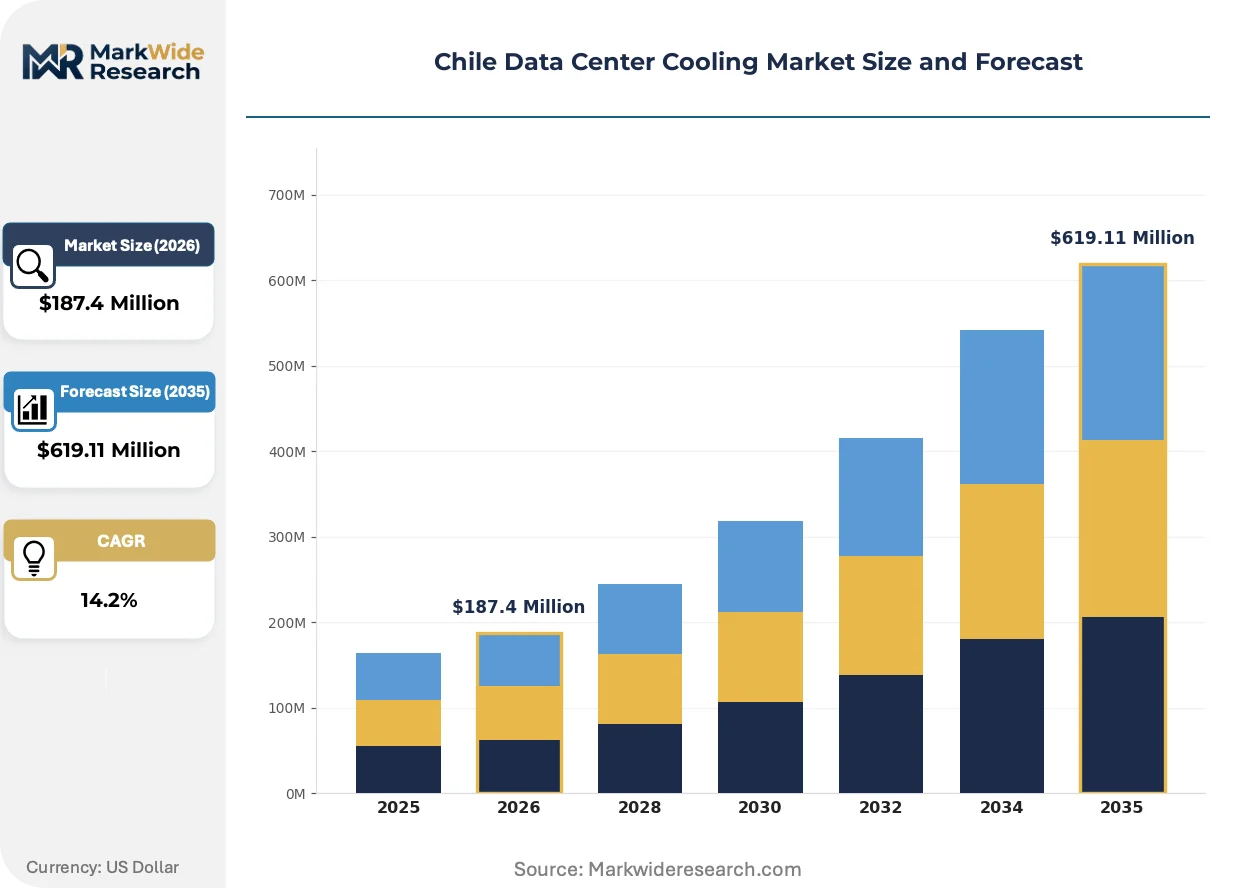
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Cooling Type: Air Cooling, Liquid Cooling, Hybrid Cooling, Immersion Cooling End User: Telecommunications, Cloud Providers, Enterprises, Colocation Facilities Installation Type: New Construction, Retrofit, Modular, Expansion Technology: Chilled Water Systems, Direct Expansion, Free Cooling, Evaporative Cooling |
| Companies Covered | Schneider Electric SE, Vertiv Group Corp, Stulz GmbH, Rittal GmbH & Co KG, Johnson Controls International PLC, Daikin Industries Ltd, Mitsubishi Electric Corporation, Carrier, Munters Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chile Data Center Cooling Market Trends and Innovations
Direct liquid cooling architectures are rewriting thermal management economics for Chile's GPU-heavy installations, while regulatory pressure on power usage effectiveness accelerates economizer technology deployment across facility tiers.
Single-phase direct-to-chip liquid cooling is collapsing the thermal design power ceiling that previously constrained AI training cluster density in Santiago's hyperscale facilities. Cloud providers deploying NVIDIA H100 and B200 infrastructure are specifying CDU-integrated rack architectures as standard. The technology is collapsing the space and power allocation ratios that defined traditional air-cooled data hall layouts.
Chile's Ministry of Energy efficiency standards for critical infrastructure are tightening permissible PUE thresholds for new construction permits. The industrial consequence is mandatory economizer hour minimums and chilled water temperature setpoint elevations. Northern zone facilities in Antofagasta and Tarapacá are responding with adiabatic cooling hybrids that maximize free cooling availability.
Service unbundling is fragmenting the traditional systems integration model for cooling procurement in Chilean colocation. Operators are separating equipment supply from commissioning and long-term maintenance contracts. Santiago-based Tier-III facilities are most visible in this shift, negotiating direct OEM relationships while sourcing local service labor independently.
Chile Data Center Cooling Market Segmentation
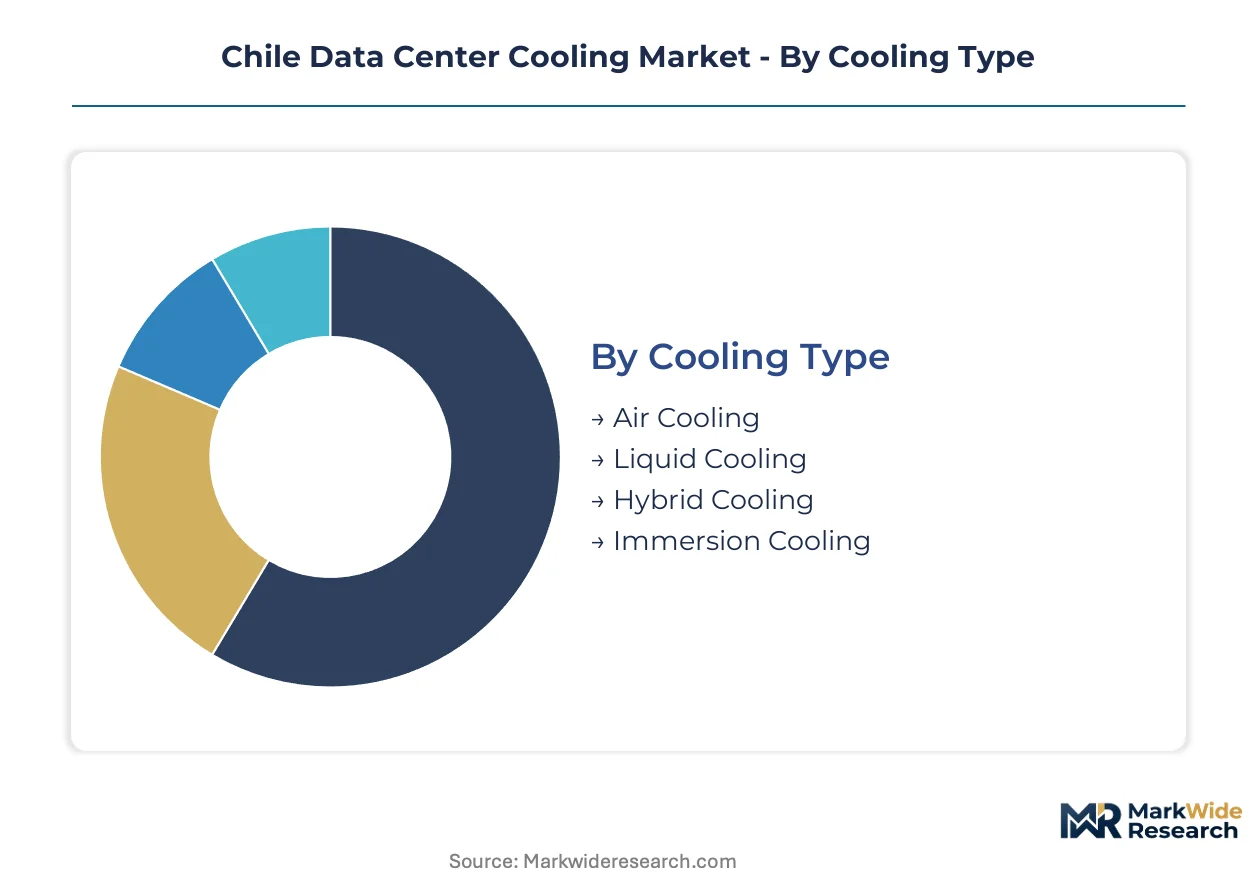
Cooling system segmentation in Chile reveals distinct service intensity profiles across deployment types. After-sales engineering requirements vary sharply between air-cooled retrofits and liquid-cooled hyperscale builds, reshaping vendor economics throughout the Santiago Metropolitan Region.
Cooling Type:
Service contract attach rates diverge most dramatically across cooling architectures, with liquid systems demanding specialized thermal-fluid expertise that local integrators struggle to provision.
- Air Cooling:Conventional raised-floor CRAC and CRAH units dominate Chile's installed base through mechanical refrigeration and perimeter air distribution. Colocation facilities in Santiago's Quilicura and Cerrillos districts anchor replacement demand as PUE regulations tighten operational standards.
- Liquid Cooling:Direct-to-chip and rear-door heat exchanger configurations target GPU-intensive AI clusters where thermal design power exceeds air-cooled limits. Cloud providers deploying NVIDIA infrastructure in the Santiago Metropolitan Region are specifying CDU-integrated architectures as standard equipment.
- Hybrid Cooling:Combined air-liquid architectures enable phased thermal upgrades without full infrastructure replacement. Enterprises with mixed workload densities favor this approach for extending facility lifecycles.
- Immersion Cooling:Dielectric fluid submersion eliminates mechanical refrigeration for extreme density deployments. Early trials at university research clusters in Valparaíso are testing waste heat recovery integration.
Air Cooling holds the largest share; momentum sits with Liquid Cooling.
End User:
Procurement sophistication tiers separate hyperscale direct buyers from intermediary-dependent segments, with cloud providers driving specification standards downward through vendor consolidation.
- Telecommunications:Edge node deployments for 5G infrastructure and content delivery networks require compact, N+1 redundant cooling across distributed sites. Antofagasta and Concepción are seeing concentrated tower-edge buildouts.
- Cloud Providers:Hyperscale campuses in Santiago's Lampa and Colina districts specify precision cooling through direct OEM relationships, bypassing traditional systems integrators for core infrastructure.
- Enterprises:Corporate data centers in banking and mining sectors prioritize operational continuity over density optimization, sustaining demand for proven air-cooled architectures.
- Colocation Facilities:Multi-tenant operators face tenant-mix complexity that rewards flexible cooling configurations. Tier-III providers in Vitacura and Las Condes are unbundling equipment supply from long-term service contracts.
Colocation Facilities anchor current revenue concentration; Cloud Providers are expanding most quickly.
Installation Type:
Project margin structures invert between greenfield and brownfield deployments, with retrofits capturing premium pricing for constrained-site engineering.
- New Construction:Greenfield hyperscale builds in northern free-cooling zones enable optimized thermal architecture from foundation. Permitting timelines under Ministry of Energy efficiency codes extend commissioning schedules.
- Retrofit:Existing facility upgrades face spatial constraints that demand custom piping and electrical infrastructure modifications. Santiago's aging colocation stock drives sustained retrofit demand.
- Modular:Prefabricated cooling plants accelerate deployment for time-constrained cloud expansions. Factory-integrated testing reduces on-site commissioning risk.
- Expansion:Phased capacity additions within operating facilities require live-environment installation protocols. N+1 redundancy mandates complicate construction sequencing.
New Construction commands the highest project values; Retrofit shows the steepest expansion trajectory.
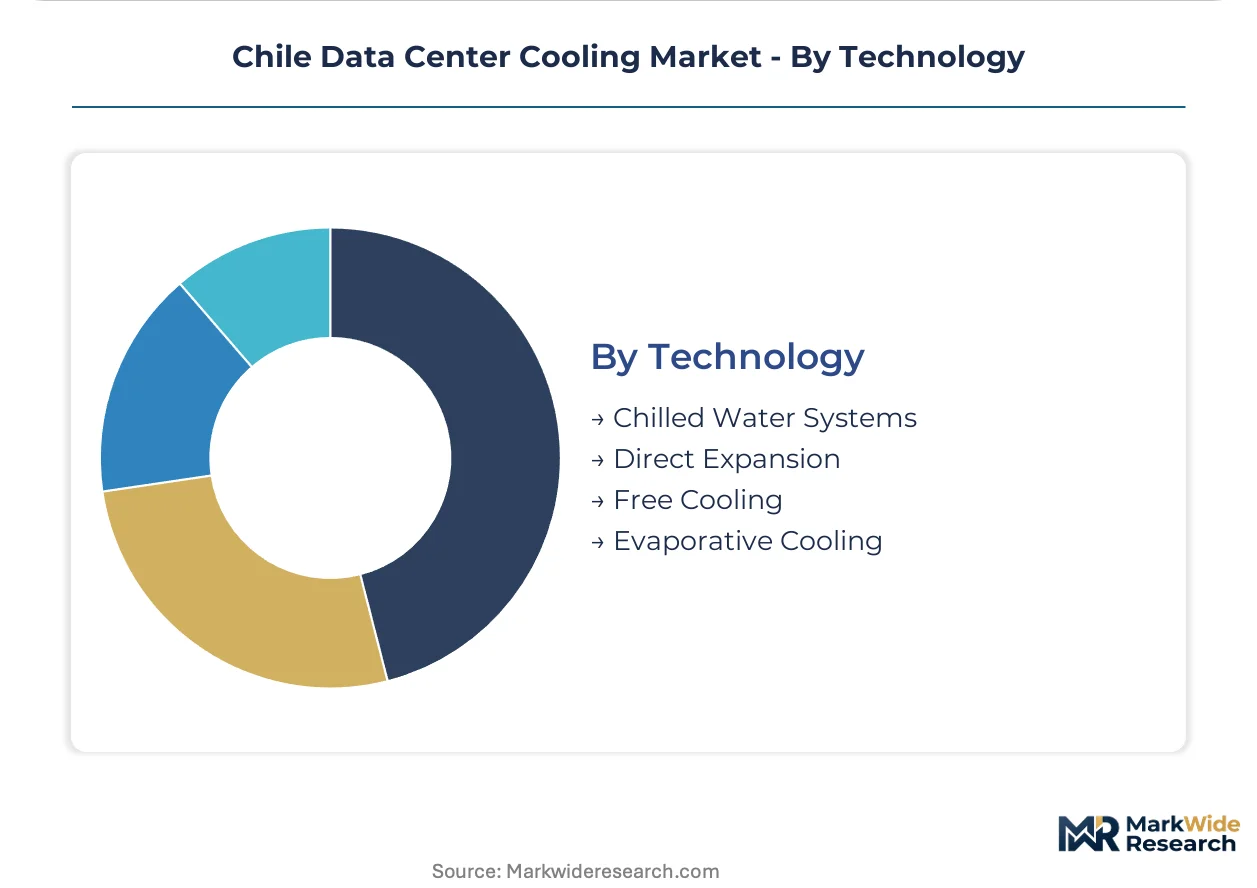
Technology:
Climate geography creates stark technology performance differentials, with Atacama-adjacent zones enabling operating economics impossible in Santiago's temperate valley.
- Chilled Water Systems:Centralized plant architectures with cooling towers and heat exchangers serve multi-megawatt facilities. Large-capacity chiller import dependency constrains deployment timelines.
- Direct Expansion:Refrigerant-based split systems dominate edge and small colocation deployments for simplified maintenance. DX units face refrigerant phase-down pressure under evolving environmental protocols.
- Free Cooling:Air-side and water-side economizers exploit ambient temperature differentials to reduce mechanical refrigeration hours. Northern zone facilities in Tarapacá achieve extended economizer availability.
- Evaporative Cooling:Adiabatic and direct evaporative systems maximize free cooling in arid climates with low wet-bulb temperatures. Water scarcity constraints limit deployment in some northern municipalities.
Chilled Water Systems retain dominant share; Free Cooling gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Prat Submarine Cable landing in Valparaíso underwrites Chile's position as South America's digital gateway. Santiago's metropolitan power grid interconnects renewable generation from the Atacama Desert with hyperscale compute demand. Northern free-cooling zones exploit altitude and aridity to compress operating costs below temperate-valley benchmarks.
Santiago Metropolitan Region
Hyperscale cloud campuses in Lampa and Colina districts concentrate precision cooling procurement through direct OEM channels. Chile's Ministry of Energy efficiency standards mandate economizer minimums for new construction permits. Quilicura and Cerrillos industrial zones anchor colocation retrofit demand as PUE thresholds tighten operational compliance.
Valparaíso Region
Submarine cable landings at Viña del Mar and San Antonio pull edge node deployments requiring compact N+1 redundant cooling. The Superintendency of the Environment air quality protocols extend permitting timelines for coastal facilities. University research clusters in Valparaíso proper are trialing immersion cooling with waste heat recovery integration.
Antofagasta Region
Solar and wind curtailment patterns in the Atacama create stranded renewable assets that data center cooling loads can absorb. Free cooling technology achieves extended economizer hours unavailable in temperate zones. Calama and Antofagasta city industrial parks are attracting modular prefabricated cooling plant deployments for time-constrained expansions.
Tarapacá Region
Adiabatic cooling hybrids maximize free cooling availability where wet-bulb temperatures permit evaporative augmentation. The national electrical coordinator's grid planning accommodates large industrial loads with dedicated substations. Iquique's Zona Franca tax incentives are positioning the port city for secondary cloud availability zones.
Bío Bío Region
Concepción's manufacturing base sustains enterprise data center demand prioritizing operational continuity over density optimization. Central bank cybersecurity resilience mandates shape cooling redundancy requirements for financial services infrastructure. The Concepción metropolitan grid offers distribution capacity absent from Santiago's congested network.
Chile Data Center Cooling Market Competitive Landscape
On the supply side, the industry is consolidating around engineering-intensive system integrators with local commissioning capability. Direct procurement channels are displacing traditional distribution for hyperscale projects. Three archetypes dominate: full-stack infrastructure vendors, precision climate specialists, and regional service integrators. Competitive moves center on unbundling equipment supply from long-term maintenance contracts and anchoring large-scale projects through local engineering presence.
Among European-headquartered full-stack providers, Schneider Electric SE anchors projects through Santiago-based engineering teams. Vertiv Group Corp occupies a position across Chile's emerging Tier-III facilities through service density investments. Stulz GmbH exemplifies the precision climate specialist archetype, with configurations targeting high-altitude thermal efficiency challenges. These three represent distinct competitive vectors: direct sales integration, service network coverage, and altitude-optimized engineering.
| Leading Market Players |
|---|
| Schneider Electric SE |
| Vertiv Group Corp |
| Stulz GmbH |
| Rittal GmbH & Co KG |
| Johnson Controls International PLC |
| Daikin Industries Ltd |
| Mitsubishi Electric Corporation |
| Carrier |
| Munters Corporation |
| Others |
Pricing and Supply Chain Analysis
The Valparaíso-Santiago freight corridor's elevated logistics costs concentrate supply-side power among importers of large-capacity chillers, compressing margins for Tier-II colocation operators while hyperscale cloud providers extract volume-discount advantages through direct OEM procurement channels.
Pricing Analysis
Volume-discount tiering separates hyperscale cloud providers securing direct OEM pricing from colocation operators dependent on systems integrator markups. Pricing stratifies across premium precision cooling with integrated CDUs, standard chilled water architectures, and economy-grade DX units for edge deployments. Cost compression in the standard tier intensifies as Schneider Electric and Vertiv consolidate direct sales channels. Tier-II colocation facilities exhibit highest price sensitivity due to constrained capex cycles, while cloud providers prioritize thermal performance over unit economics.
Supply Chain Analysis
Contract manufacturing concentration for precision cooling units rests with Schneider Electric's European and Asian facilities, Vertiv's North American plants, and Stulz's German production centers. Chile's market draws from these three manufacturing hubs plus limited regional assembly in Brazil. Critical dependencies include copper heat exchangers, refrigerant gases facing phase-down pressure, and specialized pumps for liquid cooling distribution. Single-source vulnerability concentrates in large-capacity chiller imports subject to extended lead times. Distribution runs through Santiago-based systems integrators for mid-market segments and direct OEM channels for hyperscale projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across cooling architectures creates specialized service niches as GPU-intensive workloads force rapid infrastructure turnover faster than traditional depreciation cycles permit.
For Market Incumbents: Entrench local engineering presence through Santiago-based commissioning teams capable of N+1 redundancy certification under central bank cybersecurity mandates. Deepen backward integration into thermal-fluid maintenance services to capture recurring revenue as equipment supply margins compress. Anchor large-scale projects in Lampa and Colina districts before modular prefabricated alternatives displace traditional buildouts. For New Entrants and Emerging Players: Establish a beachhead in immersion cooling waste heat recovery systems for university research clusters in Valparaíso. Target the Antofagasta free-cooling zone where adiabatic hybrid deployments outpace incumbent service coverage. Penetrate through equipment-only supply contracts unbundled from long-term maintenance, matching the procurement shift visible across Santiago's Tier-III facilities. For Investors and Strategic Acquirers: Regional service integrators with thermal-fluid engineering talent pools represent the most defensible acquisition archetype as liquid cooling specialization outpaces Chilean technical education output. Long-term viability hinges on positioning for the transition window where air-cooled retrofits coexist with liquid-cooled greenfield builds. Watch GPU deployment density in Santiago hyperscale facilities as the inflection signal for cooling architecture mix shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Direct OEM Channel Expansion | Bypasses systems integrator markups for hyperscale cloud providers deploying NVIDIA H100 infrastructure in Santiago. |
| Thermal-Fluid Engineering Talent Acquisition | Addresses scarcity constraining liquid cooling commissioning timelines under Ministry of Energy efficiency codes. |
| Free Cooling Zone Facility Development | Captures extended economizer hours in Antofagasta and Tarapacá regions with stranded renewable assets. |
| Service Contract Unbundling | Matches procurement shift across Vitacura and Las Condes Tier-III facilities separating equipment from maintenance. |
| Waste Heat Recovery Integration | Enables district heating tie-ins with Valparaíso industrial zones through immersion cooling trials at university clusters. |
Research Methodology
Initial hypotheses were tested against primary input from data center engineering directors, colocation procurement managers, cloud provider infrastructure leads, and thermal systems integrators, then refined through secondary validation against SEC filings from listed cooling equipment manufacturers, Chile's Ministry of Energy efficiency code documentation, and central bank cybersecurity framework circulars. Bottom-up sizing of installed cooling capacity across Santiago Metropolitan Region facilities was triangulated with top-down expenditure estimates derived from hyperscaler capex disclosures.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, modeling segmentation dimensions including cooling architecture type, end-user procurement sophistication tier, installation complexity grade, and regional climate zone advantage. CAGRs were derived from capacity expansion pipelines and regulatory mandate timelines. Forecast inputs incorporated GPU thermal design power trajectories and Santiago grid congestion constraints affecting cooling load scaling.
Macroeconomic conditions sit as an overlay; deviation in copper commodity prices, Chilean peso exchange rates, or renewable energy curtailment patterns would shift the trajectory. Forecasts reflect documented assumptions about technology adoption curves and regulatory enforcement intensity. Quarterly review of hyperscale deployment announcements and Ministry of Energy permitting data is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Cooling
Netherlands Data Center Cooling Market
Data Center Cooling
Immersion Cooling Market
Data Center Cooling
United States Data Center Cooling Market
Data Center Cooling
South Korea Data Center Cooling Market
Data Center Cooling
Global Laptop Cooling Pads Market
Data Center Cooling
Latin America Data Center Cooling Market
Data Center Cooling
Germany Data Center Cooling Market
Data Center Cooling
Malaysia Data Center Cooling Market
Data Center Cooling
Hong Kong Data Center Cooling Market
Data Center Cooling
Europe District Cooling Market
Data Center Cooling
Brazil Data Center Cooling Market
Data Center Cooling
Nigeria Data Center Cooling Market
Data Center Cooling
Data Center Liquid Immersion Cooling Market
Data Center Cooling
Vietnam Data Center Cooling Market
Data Center Cooling
Liquid Cooling Racks Market
Data Center Cooling
South Africa Data Center Cooling Market