
 Malaysia Data Center Server Market | 2026-2036
Malaysia Data Center Server Market Size, Share, and Industry Trends Forecast 2026-2036
Malaysia Data Center Server Market Insights
Platform licensing revenue is reshaping competitive economics in Malaysia's data center server landscape. Huawei Technologies leverages its integrated chip-to-system stack to dominate telco-grade deployments across Peninsular Malaysia. Dell Technologies anchors enterprise refresh cycles through direct channel control and localized configuration centers in Kuala Lumpur. Supermicro specializes in liquid-cooled GPU-dense architectures that serve AI training clusters in Johor's emerging cloud parks.
Data center servers are purpose-built compute nodes engineered around x86 and ARM processor architectures with thermal design power ratings from 150W to 700W per socket, designed for 24/7 operation in controlled environments. Rack servers occupy the volume core of Malaysian procurement, while blade server configurations concentrate in hyperscale colocation facilities where density per square meter drives returns. Artificial intelligence workloads represent the fastest-growing technology segment, with inference-optimized accelerators displacing general-purpose CPUs in training-heavy deployments.
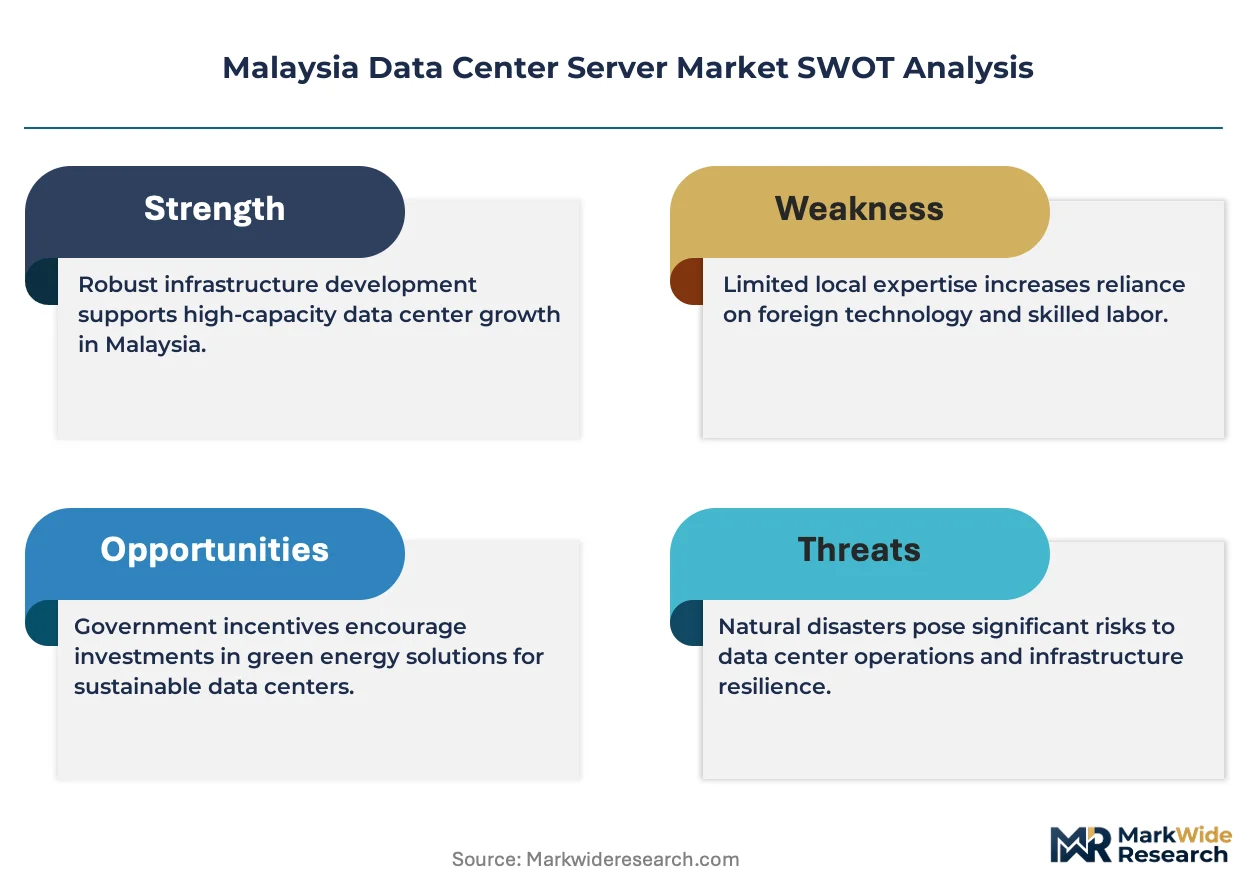
Malaysia's national regulator MCMC enforces facility certification under the Communications and Multimedia Act, while BIS-equivalent standards govern electrical safety and energy efficiency thresholds for imported server equipment. The Malaysian Investment Development Authority coordinates tax incentives with Cybersecurity Malaysia's data protection frameworks to shape foreign operator entry decisions. Stakeholders must track how Johor's power grid expansion timelines align with cooling-water availability constraints before committing to multi-megawatt facility designs.
Market Dynamics
AI inference workloads are compressing server refresh cycles across Malaysian financial services and cloud operators, forcing facility operators to reconfigure power and cooling architectures before grid expansion completes in Johor.
Growth Catalysts
- Cloud Banking Mandates:Bank Negara Malaysia's digitalization directives for financial institutions are accelerating procurement of GPU-dense compute nodes for risk modeling and fraud detection workloads.
- Cyberjaya Status Incentives:Multimedia Super Corridor tax holidays reduce effective capital expenditure for foreign hyperscalers establishing AI training clusters in the Klang Valley corridor.
- Johor-Singapore Power Interconnect:Cross-border electricity agreements are unlocking multi-megawatt facility deployments previously constrained by Peninsular Malaysia's northern grid limitations.
Market Restraints
- Copper and Rare Earth Price Volatility:Server motherboard and magnet supply chains face input cost pressure from concentrated Chinese processing capacity.
- Single-Source Liquid Cooling Dependency:Precision cooling system procurement concentrates among three European vendors, creating bottleneck risk for tropical-density deployments.
- MCMC Certification Timelines:Equipment type-approval processes under the Communications and Multimedia Act extend procurement lead times by eight to fourteen weeks for non-standard configurations.
Strategic Opportunities
- Iskandar Puteri Greenfield Zones:Untapped land parcels with direct seawater cooling access offer lower power usage effectiveness ratios than Cyberjaya's aging inventory.
- Islamic Finance AI Compliance:Shariah-compliant algorithmic trading platforms create specialized demand for inference-optimized servers with localized Arabic-language model support.
- Edge Micro-Data Center Incentives:MIDA's manufacturing investment credits extend to modular server assembly facilities serving ASEAN export markets.
Industry Challenges
- Thermal Engineer Scarcity:Liquid cooling system design expertise concentrates in Singapore and China, forcing Malaysian operators to import commissioning teams for AI cluster deployments.
- Legacy DCIM Integration:Existing facility management platforms in Cyberjaya's first-generation data centers require costly middleware development to interface with modern GPU server telemetry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Malaysia Data Center Server Market |
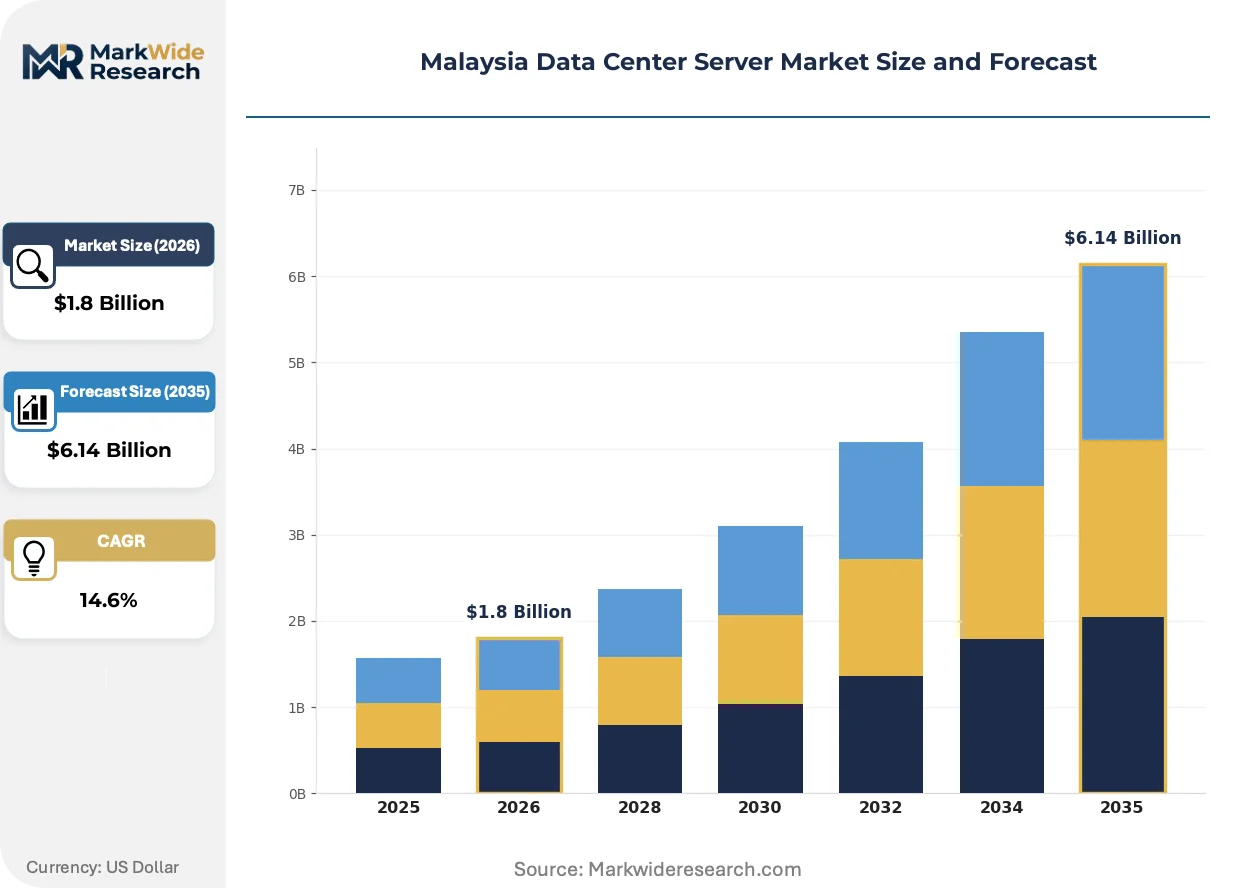
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blade Server, Rack Server, Tower Server, Modular Server End User: Telecommunications, BFSI, Government, Healthcare Technology: Virtualization, Cloud Computing, Artificial Intelligence, Big Data Service Type: Colocation, Managed Services, Hosting Services, Maintenance |
| Companies Covered | Huawei Technologies, Supermicro, Dell Technologies, Inspur, Wiwynn, Hewlett Packard Enterprise, Lenovo Group, IBM, Cisco Systems, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Malaysia Data Center Server Market Trends and Innovations
Compute architecture specialization is fragmenting procurement patterns as inference-optimized accelerators diverge from training-focused GPU configurations, creating distinct supply chains and certification pathways within the same facility footprints.
ARM-based server processors are penetrating Malaysian cloud deployments through Alibaba Cloud and Tencent configurations, offering watt-per-inference advantages for recommendation engine workloads. Financial services operators in Kuala Lumpur are piloting these chips for payment processing latency reduction. The architecture shift is digitizing procurement specifications that previously defaulted to x86 compatibility matrices.
MCMC's revised facility certification framework under the Communications and Multimedia Act now mandates redundant fiber paths and seismic isolation for Tier III-equivalent ratings. Colocation operators in Cyberjaya are retrofitting existing halls to meet these standards ahead of hyperscale lease renewals. The regulation is compressing available supply of certified white space as compliance timelines overlap with AI demand surges.
Buyers are consolidating server procurement through direct manufacturer relationships rather than systems integrator channels, driven by customization requirements for liquid cooling manifolds and accelerator densities. Enterprise accounts in Petaling Jaya and Shah Alam now specify bare-metal configurations with locally sourced rack integration. This channel compression is visible most acutely in the banking vertical, where procurement teams have hired former OEM field application engineers to manage vendor relationships directly.
Malaysia Data Center Server Market Segmentation
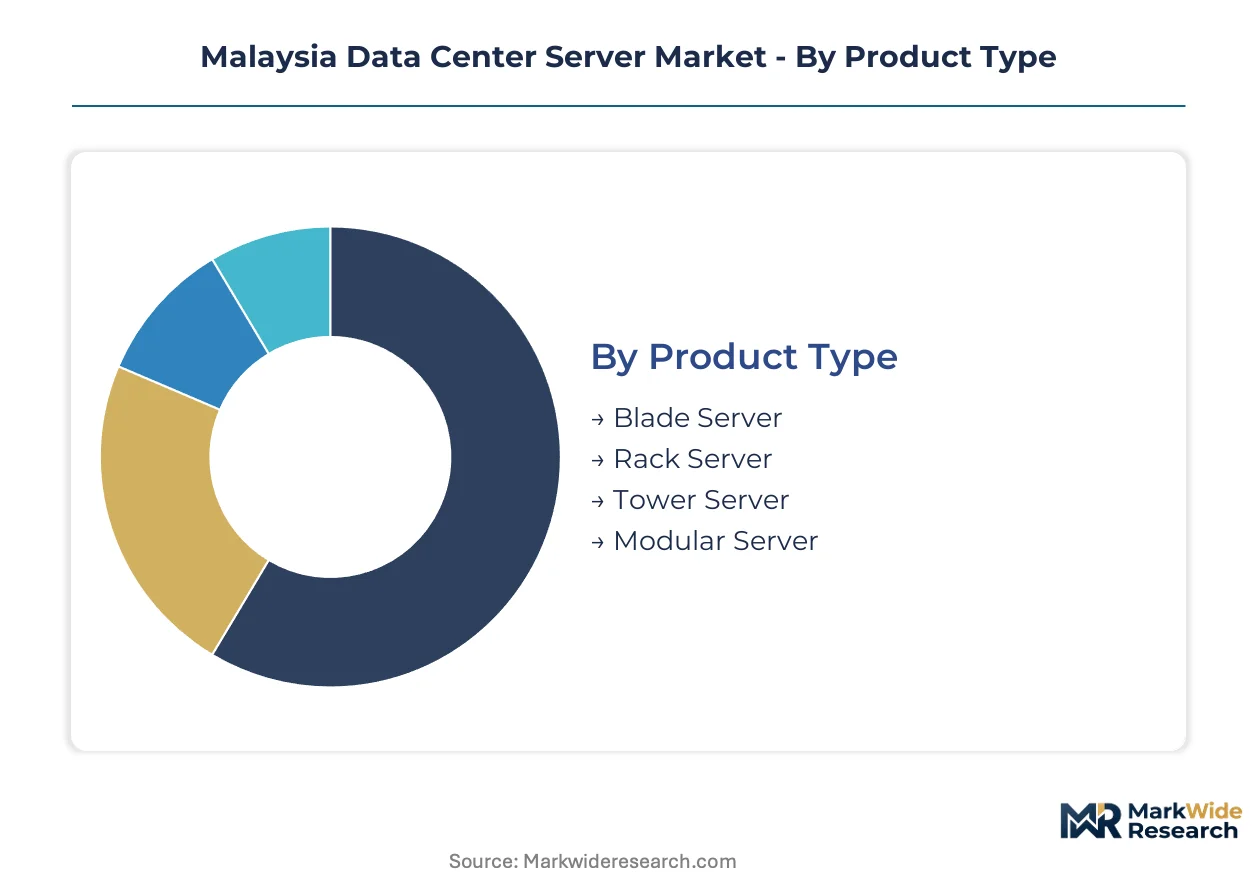
Server procurement patterns in Malaysia diverge sharply across deployment architectures and workload types. Understanding these fault lines reveals where infrastructure investment concentrates and which technology transitions threaten incumbent positions.
Product Type:
Mature rack configurations dominate volume procurement while emerging density-optimized form factors capture AI-driven refresh cycles.
- Rack Server:Standard 1U to 4U enclosures mount 19-inch rails with dual-socket x86 processors drawing 300W to 500W per node. Financial services operators in Kuala Lumpur deploy these for core banking virtualization, constrained by Cyberjaya's legacy power densities and MCMC certification timelines for non-standard configurations.
- Blade Server:Shared chassis architectures pack 8 to 16 half-height nodes with converged networking and storage backplanes. Hyperscale colocation facilities in Iskandar Puteri favor these for tenant flexibility, though single-source liquid cooling dependencies create procurement bottlenecks for tropical-density deployments.
- Tower Server:Standalone pedestal configurations serve edge and SMB deployments with minimal infrastructure requirements.
- Modular Server:Disaggregated compute sleds with pooled memory and accelerator resources target AI training clusters in Johor's greenfield zones.
Rack servers handle the majority of throughput; modular servers are the fastest mover on share.
End User:
Regulated verticals drive premium procurement specifications while government tenders emphasize localization requirements.
- BFSI:Risk modeling and fraud detection workloads demand GPU-dense nodes with inference-optimized accelerators. Bank Negara Malaysia's digitalization directives compress refresh cycles, forcing procurement teams to hire former OEM field application engineers for direct vendor management.
- Telecommunications:Telco-grade deployments require NEBS-compliant chassis with carrier-class redundancy. Huawei Technologies leverages integrated chip-to-system stacks across Peninsular Malaysia, though copper and rare earth price volatility pressures motherboard supply chains.
- Government:Cybersecurity Malaysia frameworks mandate data sovereignty with localized configuration centers.
- Healthcare:Diagnostic imaging and electronic medical records drive storage-heavy configurations with HIPAA-equivalent compliance.
BFSI absorbs the highest unit economics; telecommunications is expanding most quickly on infrastructure rollout.
Technology:
Workload abstraction layers determine hardware refresh urgency, with AI training clusters forcing power and cooling reconfigurations ahead of grid expansion.
- Artificial Intelligence:Training workloads deploy NVIDIA H100 or AMD MI300X accelerators at 700W per GPU, requiring direct liquid cooling manifolds. Inference-optimized configurations are displacing general-purpose CPUs in Malaysian cloud parks, fragmenting procurement patterns within single facilities.
- Cloud Computing:Alibaba Cloud and Tencent configurations introduce ARM-based processors for recommendation engine workloads, digitizing specifications that previously defaulted to x86 matrices.
- Virtualization:VMware and Hyper-V consolidation ratios drive memory-dense server configurations in enterprise refresh cycles.
- Big Data:Hadoop and Spark analytics clusters favor storage-heavy nodes with high-capacity NVMe arrays.
Cloud computing underpins the largest installed base; artificial intelligence is climbing the fastest on capital allocation.
Service Type:
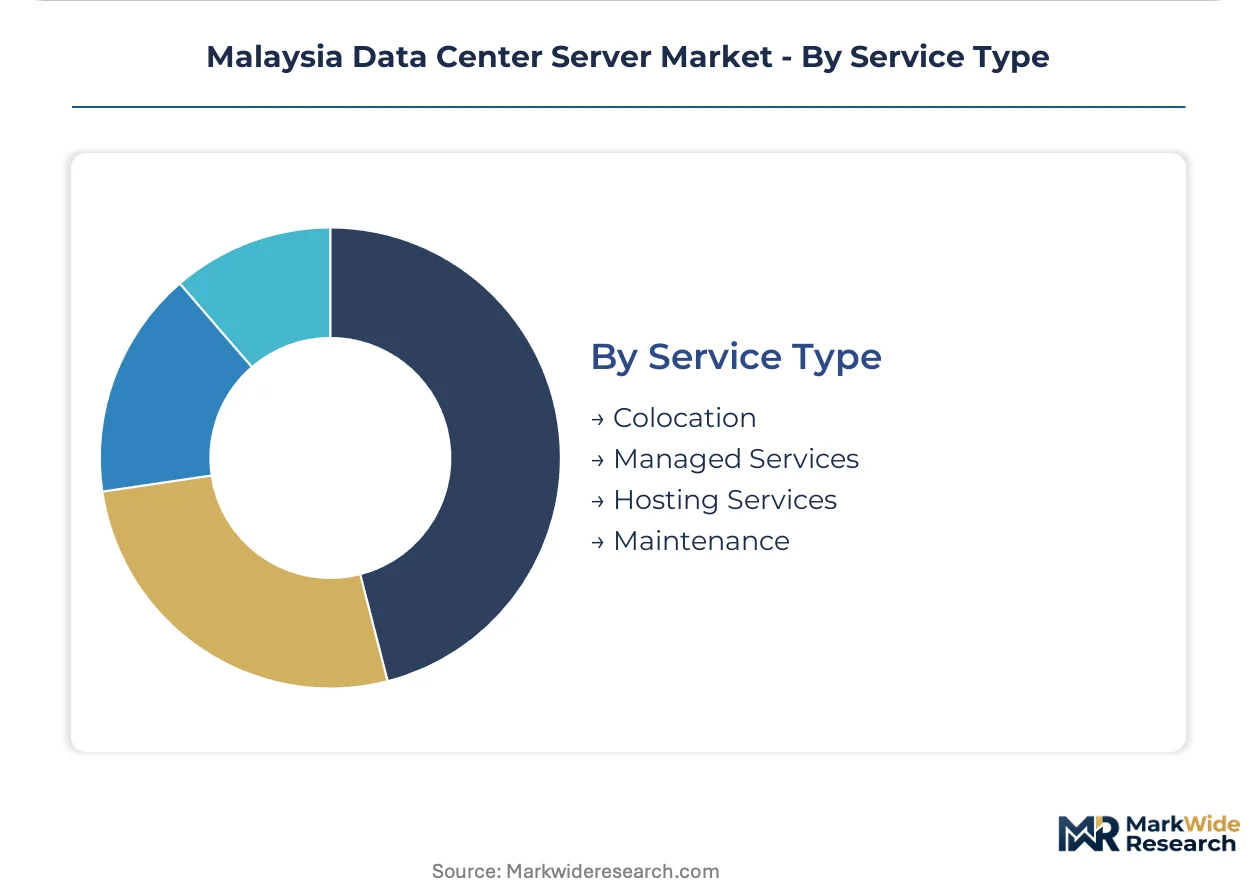
Facility economics and operational control preferences split procurement between asset-light and captive infrastructure models.
- Colocation:Wholesale and retail leasing in Cyberjaya and Iskandar Puteri offers certified white space with redundant fiber paths. MCMC's revised Tier III-equivalent mandates compress available supply as compliance timelines overlap with AI demand surges.
- Managed Services:Remote hands and smart hands contracts address thermal engineer scarcity by importing Singapore-based commissioning teams for AI cluster deployments.
- Hosting Services:Shared infrastructure models serve SMEs with standardized SLAs and minimal customization.
- Maintenance:Third-party support contracts extend lifecycle for first-generation Cyberjaya facilities facing legacy DCIM integration costs.
Colocation carries the dominant revenue share; managed services is gaining share fastest on skills arbitrage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Server deployment patterns across Malaysia diverge sharply between the Klang Valley's legacy-constrained corridors and Johor's greenfield expansions, with each sub-region optimizing around distinct power availability, cooling access, and regulatory maturity profiles.
Selangor and Kuala Lumpur
Financial services operators in Kuala Lumpur drive GPU-dense procurement for risk modeling workloads. Bank Negara Malaysia's digitalization directives compress refresh cycles, forcing direct OEM engagement. Cyberjaya's aging inventory faces MCMC certification bottlenecks as Tier III-equivalent mandates retrofit timelines.
Johor and Iskandar Puteri
Cross-border power interconnects with Singapore unlock multi-megawatt AI training clusters. Seawater cooling access lowers power usage effectiveness ratios below Cyberjaya benchmarks. Greenfield land parcels attract hyperscale colocation investments ahead of grid expansion completion.
Penang and Northern Corridor
Electronics manufacturing ecosystems generate edge micro-data center demand for industrial IoT workloads. MIDA's manufacturing investment credits extend to modular server assembly facilities. Telco-grade deployments favor integrated chip-to-system stacks from Chinese vendors.
Sarawak and East Malaysia
Hydropower abundance positions the state for energy-intensive compute deployments. Submarine cable landing stations at Kuching and Miri anchor regional connectivity hubs. Federal infrastructure programs lag behind Peninsular Malaysia's certification frameworks.
Malaysia Data Center Server Market Competitive Landscape
Capability concentration sits with integrated-system specialists; scale advantage sits with enterprise-channel incumbents. The vendor base organizes around three strategic archetypes: telco-grade integrated-stack providers, enterprise-refresh-cycle anchors, and liquid-cooled GPU-dense specialists. Dominant competitive moves include direct manufacturer relationship consolidation and localized configuration center establishment.
Among Chinese-originated integrated-system providers, Huawei Technologies and Inspur exemplify the telco-grade deployment archetype across Peninsular Malaysia. Dell Technologies, Hewlett Packard Enterprise, and Supermicro occupy positions spanning enterprise-channel control and AI-cluster specialization, with the latter anchoring liquid-cooled architectures in Johor's emerging facilities.
| Leading Market Players |
|---|
| Huawei Technologies |
| Supermicro |
| Dell Technologies |
| Inspur |
| Wiwynn |
| Hewlett Packard Enterprise |
| Lenovo Group |
| IBM |
| Cisco Systems |
| Others |
Pricing and Supply Chain Analysis
Single-source liquid cooling dependency determines both the premium tier spreads for GPU-dense deployments and the supply chain concentration among European precision cooling vendors serving tropical-density facilities in Cyberjaya and Iskandar Puteri.
Pricing Analysis
Long-term offtake agreements dominate hyperscale procurement in Johor's greenfield zones, while spot purchasing persists for enterprise refresh cycles in Kuala Lumpur constrained by MCMC certification timelines. Pricing stratifies across certified Tier III-equivalent configurations, liquid-cooled AI clusters, and standard air-cooled rack servers based on thermal design power ratings and redundant fiber path compliance. Cost compression in blade server configurations is intensifying because three European vendors control precision cooling system supply. Financial services operators show lowest price sensitivity due to Bank Negara Malaysia's digitalization mandates, while SME hosting customers face margin pressure from standardized SLA commoditization.
Supply Chain Analysis
Tariff exposure between Malaysia and China dominates motherboard and magnet procurement risk for server deployments across Peninsular Malaysia. Manufacturing concentrates in China, Taiwan, and South Korea for x86 and ARM processors, NVIDIA and AMD accelerators, and precision cooling components. Copper and rare earth supply chains feed from concentrated Chinese processing capacity, creating input cost volatility for telco-grade chassis. Distribution runs through direct manufacturer relationships consolidated by enterprise accounts in Petaling Jaya and Shah Alam, displacing systems integrator channels for customized bare-metal configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Liquid cooling system design expertise scarcity in Malaysia forces facility operators to import Singapore-based commissioning teams, creating structural margin capture opportunities for localized capability development.
For Market Incumbents: Build captive thermal engineering capacity through Kuala Lumpur-based training partnerships with Singapore technical institutes. Anchor enterprise refresh cycles by establishing localized configuration centers that compress MCMC certification timelines for non-standard GPU-dense deployments. Defend against ARM-based processor displacement by deepening x86 channel control in financial services verticals where Bank Negara Malaysia's risk modeling mandates sustain premium procurement. For New Entrants and Emerging Players: Mid-market colocation facilities in Iskandar Puteri with direct seawater cooling access represent the most penetrable entry point for Tier III-equivalent certified white space. Edge micro-data center assembly for ASEAN export markets under MIDA manufacturing investment credits offers second-mover advantage in modular server configurations. Pursue go-to-market partnerships with former OEM field application engineers hired by Malaysian banking procurement teams to bypass direct channel compression barriers. For Investors and Strategic Acquirers: The market sits at an infrastructure buildout phase that favors vertically integrated cooling-system specialists with commissioning capabilities. Long-term viability hinges on positioning ahead of Johor grid expansion completion and Cyberjaya retrofit compliance deadlines. Acquisition target archetype: precision cooling vendors with tropical-climate deployment track records and existing relationships with European equipment suppliers. Monitor cross-border power interconnect agreement finalization as inflection indicator for multi-megawatt facility investment velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Localized Configuration Center Establishment | Kuala Lumpur facilities compress MCMC certification timelines for GPU-dense server deployments. |
| Liquid Cooling Capability Partnership | Singapore technical institute alliances address thermal engineer scarcity in Cyberjaya retrofit projects. |
| Direct Manufacturer Relationship Consolidation | Banking vertical procurement teams bypass systems integrator channels for customized bare-metal specifications. |
| Seawater Cooling Access Development | Iskandar Puteri greenfield parcels achieve lower power usage effectiveness ratios than aging Cyberjaya inventory. |
| ARM-Based Processor Channel Entry | Alibaba Cloud and Tencent configurations penetrate cloud computing workloads with watt-per-inference advantages. |
Research Methodology
Initial hypotheses were tested against primary input from data center facility operators, thermal engineering contractors, enterprise IT procurement managers, and MCMC regulatory affairs specialists and refined through secondary validation against MCMC facility certification databases, BIS-equivalent electrical safety standards, MIDA investment incentive disclosures, and hyperscaler capex commitment announcements. Bottom-up server shipment estimates by configuration type triangulated against top-down facility power capacity expansion data across the analysis window.
Demand-supply-balance framing anchored the forecast framework across product type, end user vertical, workload technology, and service delivery model dimensions. CAGRs were derived from installation base growth rates, refresh cycle compression factors, and AI workload penetration curves. Model inputs included Bank Negara Malaysia digitalization directive implementation timelines, Johor-Singapore power interconnect capacity expansion schedules, and Cyberjaya land parcel availability constraints.
Practitioners should monitor copper and rare earth price volatility, European precision cooling vendor capacity allocation, and MCMC certification processing backlog for early signals of forecast revision triggers. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Sweden Data Center Power Market
Data Center Infrastructure
Data Center Virtualization Market
Data Center Infrastructure
Sweden Data Center Server Market
Data Center Infrastructure
IT Infrastructure Management Tools Market
Data Center Infrastructure
Switzerland Data Center Rack Market
Data Center Infrastructure
Australia Data Center Physical Security Market
Data Center Infrastructure
Mexico Data Center Market
Data Center Infrastructure
Norway Data Center Physical Security Market
Data Center Infrastructure
China Data Center Market
Data Center Infrastructure
UK Data Center Rack Market
Data Center Infrastructure
Server Station Market
Data Center Infrastructure
South Korea Data Center Physical Security Market
Data Center Infrastructure
Global Data Center RFID Market
Data Center Infrastructure
Saudi Arabia Data Center Rack Market
Data Center Infrastructure
Data Center Modeling and Simulation Tools Market
Data Center Infrastructure
North America Data Center Infrastructure Management Market