
 Brazil Servers Market | 2026-2036
Brazil Servers Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Servers Market Insights
Consolidation among Brazilian banking and fintech buyers is realigning procurement patterns toward fewer, larger server contracts with stricter uptime guarantees. Dell Technologies Inc. leverages its direct enterprise sales force to sustain relationships with top-tier financial institutions in São Paulo. Hewlett Packard Enterprise Co. anchors its position through GreenLake as-a-service offerings that reduce upfront capital burdens for mid-market buyers. Super Micro Computer Inc. differentiates via high-density rack configurations optimized for tropical climate data centers.
Servers are electromechanical computing systems built around x86 or ARM processors, memory modules, storage arrays, and network interface controllers housed in standardized chassis ranging from 1U to 4U rack heights, designed to process, store, and distribute data across enterprise networks and cloud infrastructures. Rack servers dominate Brazilian enterprise deployments due to their density advantages in space-constrained São Paulo facilities, while blade systems lead among telecommunications operators pursuing 5G core virtualization. Hybrid deployment models are expanding fastest as regulated industries balance LGPD compliance with cloud agility, concentrating margin pools in integration and managed services rather than bare-metal hardware.
ANVISA, the national pharmaceutical regulator, shapes healthcare server requirements through traceability mandates that demand localized data processing. BIS-equivalent INMETRO certification and ANATEL telecommunications standards govern electromagnetic compatibility and network equipment approval, creating compliance barriers for unqualified imports. The Central Bank of Brazil's Pix instant-payment infrastructure and open-banking directives force financial institutions to maintain low-latency, on-premises processing capacity. Stakeholders must monitor how proposed updates to Brazil's national data strategy redefine cross-border cloud restrictions and domestic infrastructure obligations.
Market Dynamics
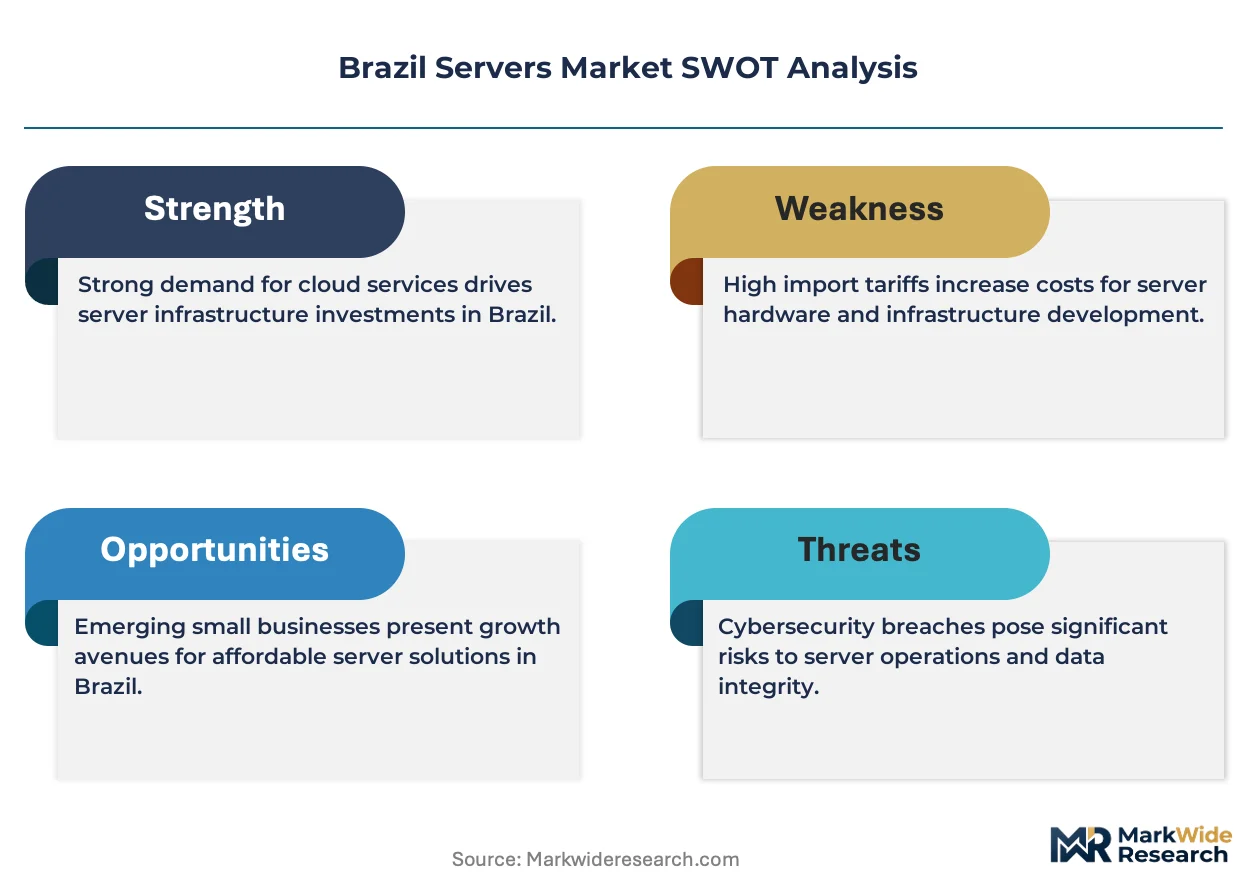
Pix instant-payment infrastructure and LGPD data residency mandates are forcing Brazilian financial institutions to expand on-premises processing capacity, compressing procurement cycles and favoring vendors with localized service footprints.
Growth Catalysts
- Pix Payment Platform Expansion:The Central Bank of Brazil's real-time settlement system processes billions of monthly transactions, compelling banks to deploy low-latency edge servers for transaction authorization.
- LGPD Compliance Infrastructure:Brazil's data protection law mandates domestic data storage for sensitive categories, directing cloud providers and enterprises toward localized server investments.
- Campinas Hyperscale Clustering:Fiber backbone density in São Paulo state's technology corridor attracts multi-megawatt facilities, concentrating demand for high-density rack configurations.
Market Restraints
- Import Certification Friction:INMETRO electromagnetic compatibility and ANATEL telecommunications approvals add months to server deployment timelines for non-domestic suppliers.
- Currency Volatility Exposure:Real-dollar exchange rate fluctuations inflate landed costs for processor and memory components sourced from Asian foundries.
- Tropical Climate Derating:Ambient temperature and humidity in Brazilian facilities force cooling overhead investments that erode total cost of ownership advantages against temperate-region competitors.
Strategic Opportunities
- Healthcare Traceability Mandates:ANVISA pharmaceutical serialization rules require localized data processing, opening server demand from hospital networks and drug distributors outside São Paulo's core.
- Edge Computing for 5G Core:Telecommunications operators virtualizing network functions present demand for compact, ruggedized server form factors at cell tower aggregation points.
- GreenLake-Style Consumption Models:As-a-service financing structures reduce upfront capital barriers for mid-market manufacturers in Minas Gerais and Rio Grande do Sul.
Industry Challenges
- Certification Timeline Compression:ANATEL approval backlogs delay revenue recognition for vendors targeting telecommunications and financial services verticals.
- Legacy Mainframe Integration:Brazil's banking sector maintains COBOL-based core systems, complicating hybrid cloud architectures and extending professional services engagements.
- Specialized Technician Scarcity:Liquid cooling and high-voltage power distribution expertise remains concentrated in São Paulo, inflating deployment costs for facilities in northern and northeastern states.
Report Scope
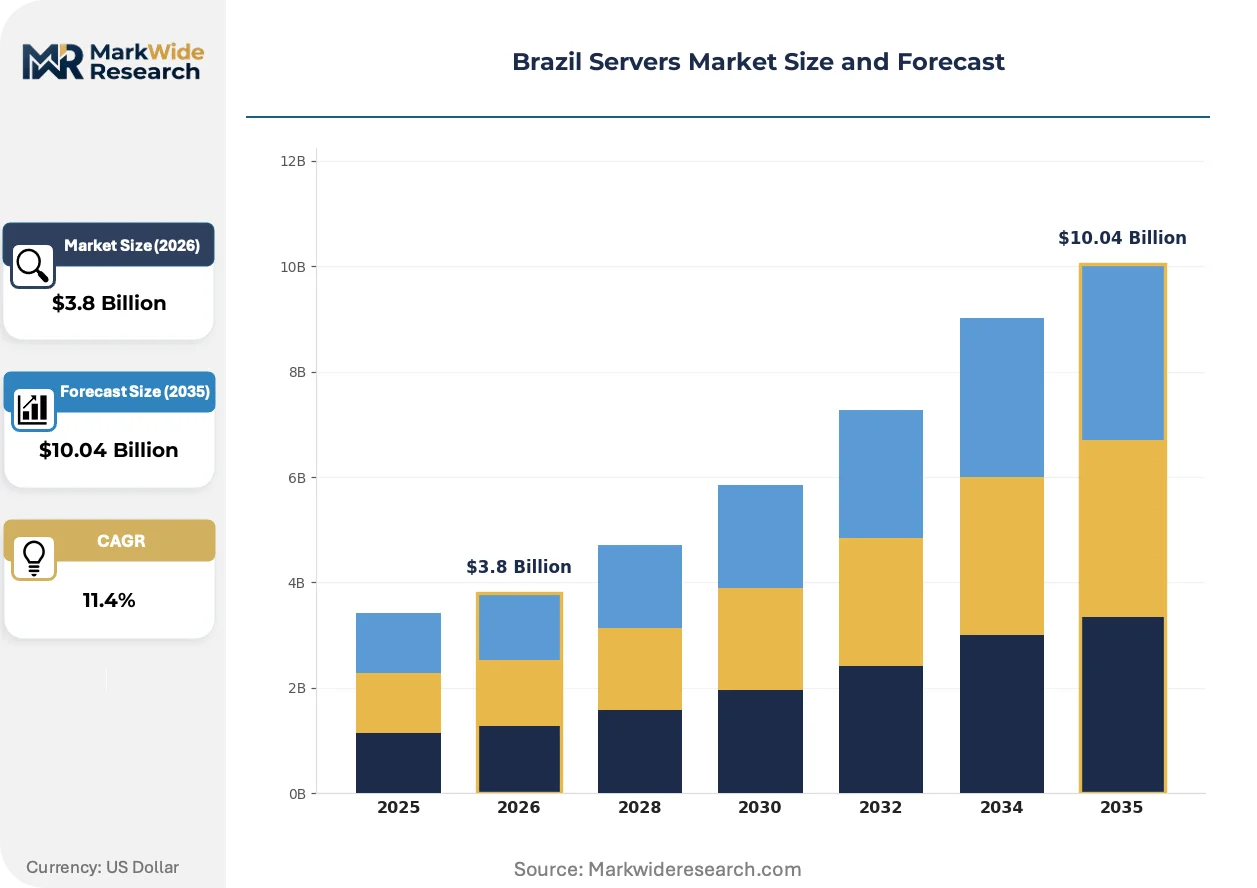
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Servers Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Server Type: Blade Servers, Rack Servers, Tower Servers, Modular Servers Deployment Model: On-Premises, Cloud-based, Hybrid, Multi-Cloud Industry Vertical: Finance, Telecommunications, Healthcare, Retail Form Factor: 1U, 2U, 3U, 4U |
| Companies Covered | Hewlett Packard Enterprise Co., Dell Technologies Inc., Lenovo Group Limited, Cisco Systems, Inc., Positivo Tecnologia S/A, IBM Corporation, Super Micro Computer Inc., Oracle Corporation, Fujitsu Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Servers Market Trends and Innovations
Arm-based processors and liquid cooling architectures are penetrating Brazilian data centers as density requirements climb and energy costs mount, while regulatory pressure accelerates domestic infrastructure deployment.
Arm processor architectures are rewriting server procurement patterns in Brazilian financial services. The instruction set's efficiency advantages attract institutions running containerized Pix microservices at scale. Banco do Brasil and Itaú Unibanco pilot deployments signal mainstream adoption within eighteen months.
LGPD enforcement actions by Brazil's national data protection authority are tightening cross-border data flow restrictions. Cloud providers must certify domestic server residency for healthcare and public sector contracts. ANVISA traceability mandates amplify this effect for pharmaceutical supply chain applications.
Consumption-based financing models are displacing traditional capital expenditure cycles among mid-market manufacturers. HPE GreenLake and Dell APEX structures convert server procurement to operational expenses, accelerating refresh cycles in Rio de Janeiro and Paraná industrial zones where credit constraints persist.
Brazil Servers Market Segmentation
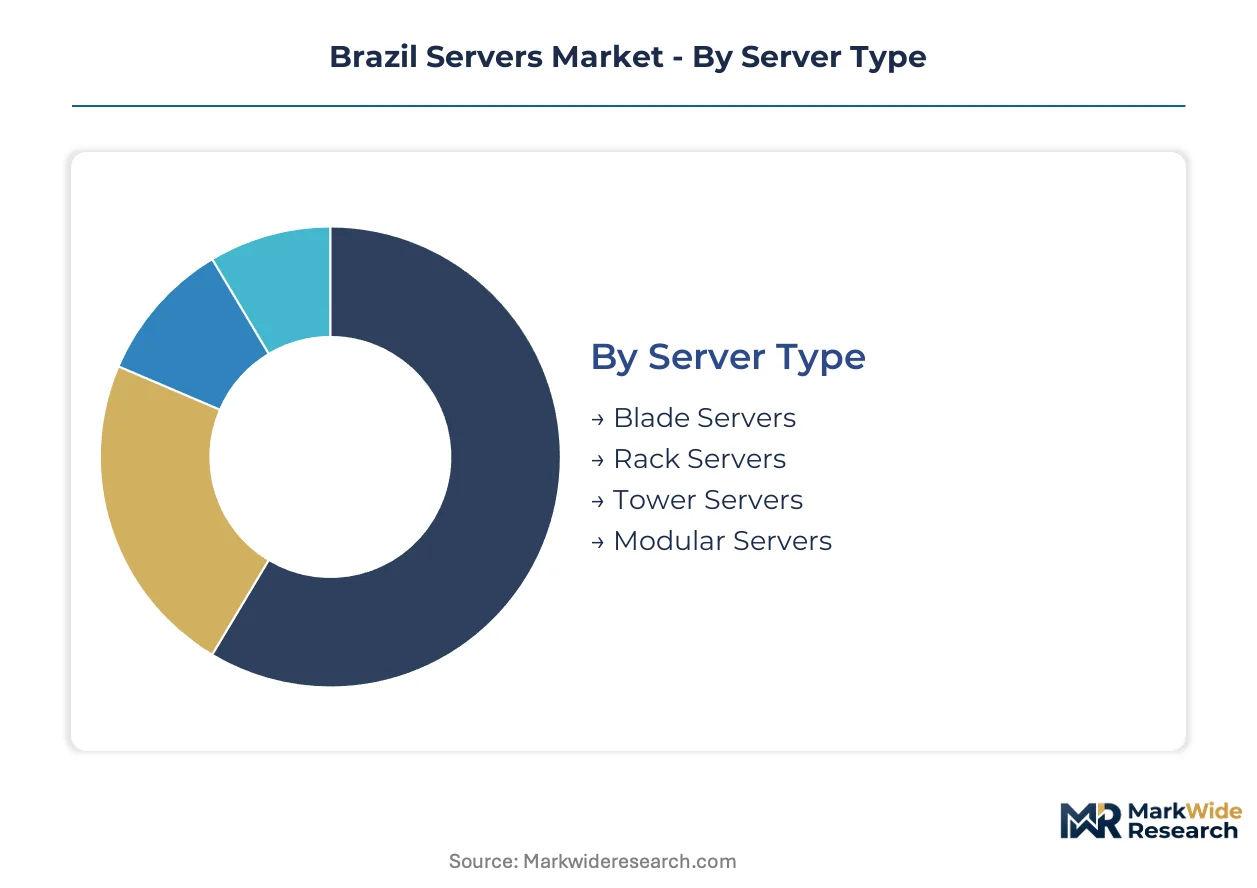
Server procurement in Brazil fragments across hardware configurations, operational architectures, and regulatory exposure levels. Each segmentation axis reveals distinct margin pools and vendor positioning strategies within the LGPD-compliant infrastructure buildout.
Server Type:
Standalone rack configurations dominate enterprise data centers, while blade systems embed deeply into telecommunications virtualization stacks.
- Rack Servers:Standardized chassis housing independent compute nodes in 1U to 4U heights, optimized for horizontal scaling in space-constrained São Paulo facilities. Financial institutions expanding Pix transaction processing favor these for thermal management flexibility in tropical climates.
- Blade Servers:High-density shared infrastructure enclosures with hot-swappable server modules, engineered for maximum compute per square meter. Telecommunications operators virtualizing 5G core functions in Campinas hyperscale campuses drive procurement volumes here.
- Tower Servers:Vertical standalone units designed for branch office and small data center deployments without rack infrastructure. Regional bank branches in Minas Gerais and Paraná deploy these for localized LGPD-compliant transaction logging.
- Modular Servers:Disaggregated compute, storage, and networking components in composable chassis architectures. Emerging interest from manufacturers seeking consumption-based financing models to bypass capital constraints.
Rack servers lead volumes today; blade servers are gaining share fastest among telecommunications verticals.
Deployment Model:
Cost tier stratification separates capital-intensive ownership from operational expenditure structures across Brazilian enterprise budgets.
- On-Premises:Dedicated physical infrastructure within enterprise-controlled facilities, mandatory for ANVISA pharmaceutical traceability and Central Bank Pix latency requirements. São Paulo financial institutions maintain these for transaction authorization sovereignty.
- Hybrid:Integrated on-premises and cloud resource orchestration, balancing LGPD data residency with elastic compute needs. Fastest-expanding architecture among healthcare networks navigating ANVISA compliance without full cloud migration.
- Cloud-based:Third-party hosted server resources with shared or dedicated tenancy, constrained by LGPD enforcement actions limiting cross-border data flows for sensitive categories.
- Multi-Cloud:Distributed workloads across multiple cloud service providers to mitigate vendor concentration risk. Retail chains with national footprints adopt this for regional resilience without single-provider dependency.
On-premises deployments anchor current infrastructure investment; hybrid architectures are climbing the fastest as regulated industries seek compliance agility.
Industry Vertical:
Application-specific workload characteristics determine processor selection, density requirements, and service level specifications across buyer segments.
- Finance:Low-latency transaction processing for Pix instant payments and open banking APIs, with stringent uptime guarantees and domestic data residency mandates. Banco do Brasil and Itaú Unibanco procurement patterns concentrate in high-frequency trading configurations.
- Healthcare:ANVISA-mandated pharmaceutical serialization and patient data processing, requiring localized server residency with audit trail capabilities. Hospital networks outside São Paulo's technology corridor drive geographic diversification of demand.
- Telecommunications:5G core virtualization and edge computing at cell tower aggregation points, demanding compact form factors with ruggedized thermal specifications.
- Retail:Omnichannel transaction processing and inventory management systems, with seasonal elasticity requirements favoring consumption-based procurement models.
Finance commands the largest procurement volumes; healthcare is expanding most quickly under ANVISA regulatory pressure.
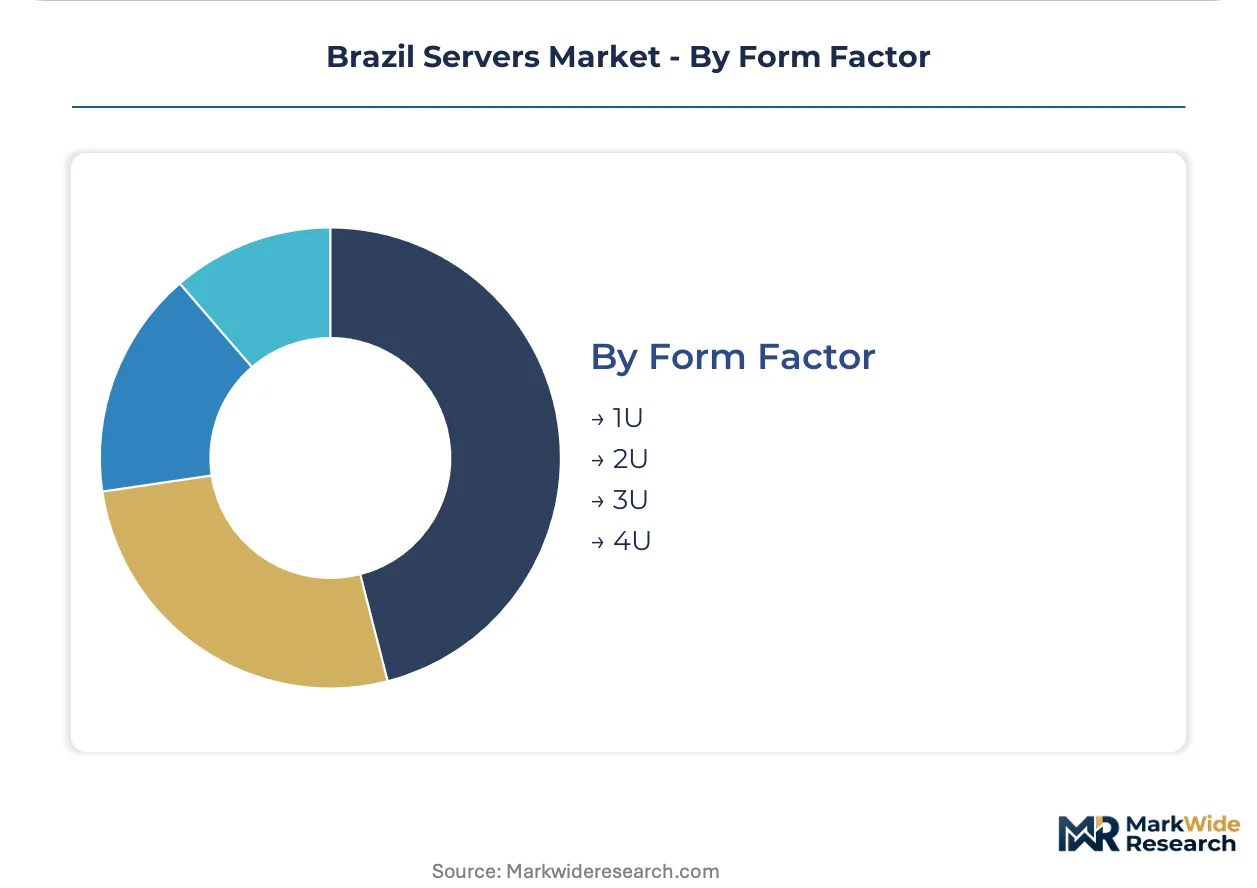
Form Factor:
Physical chassis height directly correlates with cooling overhead and power density constraints in tropical climate data centers.
- 1U:Single rack unit height maximizing server count per square meter, preferred for web serving and lightweight containerized microservices. Campinas hyperscale facilities optimize rack economics with these configurations.
- 2U:Dual rack unit chassis accommodating expanded storage arrays and accelerated processing cards. Financial services database workloads and virtualization clusters standardize on this density tier.
- 3U:Triple rack unit enabling specialized accelerator deployment and enhanced airflow management. Emerging adoption for AI inference workloads in research and development contexts.
- 4U:Quad rack unit maximum density for GPU-intensive computing and maximum storage expansion. Limited deployment due to thermal management complexity in Brazilian ambient conditions.
2U configurations dominate enterprise procurement today; 1U densities are gaining share fastest in hyperscale Campinas deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's server demand outpaces Mexico's fintech infrastructure buildout, while both markets navigate distinct regulatory compliance frameworks for data residency and financial transaction processing.
São Paulo
Pix instant-payment authorization drives low-latency server deployment across Banco do Brasil and Itaú Unibanco data centers. ANATEL telecommunications standards govern electromagnetic compatibility for network equipment entering this corridor. Campinas anchors the technology cluster where hyperscale facilities concentrate near fiber backbone intersections.
Rio de Janeiro
Petrochemical conglomerates and port logistics operators demand edge computing capacity for real-time supply chain orchestration. INMETRO certification requirements filter server imports through electromagnetic compatibility testing protocols. Duque de Caxias industrial zones host manufacturing facilities adopting consumption-based financing models to bypass capital constraints.
Minas Gerais
Regional banking networks deploy tower servers for branch-level LGPD-compliant transaction logging outside metropolitan cores. The state's pharmaceutical distributors face ANVISA traceability mandates requiring localized data processing infrastructure. Belo Horizonte technology parks attract mid-market manufacturers seeking hybrid cloud architectures.
Rio Grande do Sul
Meat processing and agricultural commodity trading firms invest in on-premises capacity for export documentation and cold chain monitoring. LGPD enforcement actions compel domestic server residency for sensitive commercial data. Porto Alegre industrial zones concentrate procurement from vendors offering GreenLake-style operational expenditure structures.
Paraná
Automotive parts manufacturers and soybean trading houses require localized processing for ERP systems and commodity exchange connectivity. The Central Bank's open-banking directives force financial institutions here to maintain sovereign transaction authorization capacity. Curitiba technology corridors see fastest adoption of Arm-based processor pilot programs.
Brazil Servers Market Competitive Landscape
United States-based technology conglomerates anchor the premium enterprise tier; Asian hardware specialists and domestic assemblers hold mid-market and cost-optimized segments. The vendor structure concentrates around three strategic archetypes: full-stack infrastructure providers with direct sales forces, component-optimized fabricators targeting density constraints, and local system integrators navigating certification friction. Competitive moves center on as-a-service financing conversions and tropical climate thermal engineering partnerships.
Among United States-based enterprises, Dell Technologies Inc., Hewlett Packard Enterprise Co., and Super Micro Computer Inc. occupy distinct positioning vectors. Dell exemplifies the direct enterprise relationship model sustaining top-tier financial institution accounts. HPE represents the consumption-based financing archetype converting capital expenditure cycles to operational structures. Super Micro anchors the high-density thermal optimization segment addressing tropical ambient derating requirements.
| Leading Market Players |
|---|
| Hewlett Packard Enterprise Co. |
| Dell Technologies Inc. |
| Lenovo Group Limited |
| Cisco Systems, Inc. |
| Positivo Tecnologia S/A |
| IBM Corporation |
| Super Micro Computer Inc. |
| Oracle Corporation |
| Fujitsu Limited |
| Others |
Pricing and Supply Chain Analysis
INMETRO electromagnetic compatibility certification gates qualified supply and premium-tier pricing access in Brazilian server procurement, filtering non-compliant imports toward economy tiers while certified vendors capture financial institution contracts with stricter uptime guarantees. LGPD data residency mandates compound this effect by concentrating buyer demand on domestic-assembled configurations that carry certification premiums.
Pricing Analysis
Capacity additions in Campinas hyperscale corridors are reshaping price floors for high-density rack configurations, compressing margins for legacy tower server suppliers. Three-tier pricing structure across certified-premium, standard-enterprise, and economy-import levels stratifies the market, with ANATEL telecommunications approval and tropical-climate thermal engineering as primary price differentiation drivers. Pricing pressure stems from real-dollar exchange volatility inflating landed processor costs. Mid-market manufacturers in Minas Gerais and Rio Grande do Sul exhibit highest price sensitivity, while São Paulo financial institutions prioritize certification compliance over unit cost.
Supply Chain Analysis
Liquid cooling technician scarcity in northern and northeastern states concentrates specialized deployment capacity around São Paulo, elongating project timelines for distributed facilities. Server component supply draws from Taiwan, South Korea, and China for processor and memory modules, with domestic assembly in Campinas and Manaus free trade zones. Raw material dependencies center on advanced silicon wafers, DDR5 memory substrates, and precision cooling hardware. Single-source vulnerability in x86 processor architectures from Intel and AMD creates concentration risk. Distribution runs through authorized enterprise resellers with INMETRO certification capabilities rather than direct OEM channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's server market functions as a regulatory compounder where LGPD enforcement actions and Central Bank Pix infrastructure mandates compound demand for certified domestic capacity.
For Market Incumbents: Extend GreenLake-style consumption financing to capture mid-market manufacturers in Rio Grande do Sul and Paraná, converting capital expenditure cycles to operational structures that accelerate refresh rates. Deepen tropical climate thermal engineering partnerships to defend margin position against Asian hardware specialists entering with cost-optimized air-cooled configurations. Certification investment in ANATEL and INMETRO pre-approval programs reduces deployment friction against emerging local assemblers. For New Entrants and Emerging Players: ANVISA pharmaceutical traceability mandates in Minas Gerais and Rio de Janeiro open a window for tower server deployments outside São Paulo's saturated technology corridor. Target hospital networks and drug distributors with localized data processing requirements as the most penetrable segment. Pursue joint certification pathways with established INMETRO laboratories to bypass approval timeline disadvantages against incumbent vendors. For Investors and Strategic Acquirers: Valuations sit cheapest among domestic system integrators with certification navigation expertise but limited direct sales reach. Long-term viability hinges on LGPD enforcement tightening cross-border data flow restrictions through the projection horizon. Acquisition target archetype: regional assemblers with ANATEL pre-certification and established relationships with telecommunications operators. Monitor Central Bank open-banking directive implementation velocity as inflection indicator for edge server demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Pre-Approval Investment | INMETRO electromagnetic compatibility pre-certification compresses deployment timelines for financial services contracts. |
| Consumption Model Expansion | GreenLake-style operational expenditure structures bypass credit constraints among Minas Gerais manufacturers. |
| Thermal Engineering Partnership | Liquid cooling expertise partnerships address tropical climate derating in northern state facilities. |
| Edge Computing Product Line | Compact ruggedized form factors capture telecommunications 5G core virtualization demand in Campinas. |
| Arm Architecture Migration | Processor efficiency advantages attract Banco do Brasil and Itaú Unibanco containerized microservices deployments. |
Research Methodology
Multiple input streams — primary interviews with data center operations directors, IT procurement officers at financial institutions, and ANATEL certification consultants — were reconciled against secondary validation from Central Bank of Brazil payment system disclosures, ANVISA pharmaceutical traceability regulations, and hyperscaler facility expansion announcements. Bottom-up server shipment estimates by form factor and deployment model were triangulated against top-down infrastructure investment projections across the analysis window.
Historical capacity utilization patterns were cross-referenced against panel input from Campinas facility developers and São Paulo enterprise architects to anchor growth assumptions. Segmentation dimensions modeled include server type, deployment architecture, industry vertical, and regional regulatory exposure tier. CAGRs were derived from installed base replacement cycles and net new capacity requirements under LGPD compliance timelines, incorporating Pix transaction volume growth as a demand elasticity input.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Real-dollar exchange rate volatility and ANATEL approval backlog extensions. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and telecommunications virtualization timelines. Material deviation in Central Bank open-banking directive implementation or LGPD cross-border restriction tightening warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Computer Network Design Services Market
Data Center and Networking
Global Database Management System (DBMS) Market
Data Center and Networking
Converged Data Platform Market
Data Center and Networking
Middle East Data Center Server Market
Data Center and Networking
Nvme Over Fiber Channel Market
Data Center and Networking
Global Virtual Network Functions Market
Data Center and Networking
Global Scalable Software Defined Networking Market
Data Center and Networking
Hong Kong Data Center Networking Market
Data Center and Networking
Japan Data Center Server Market
Data Center and Networking
North America Data Center Networking Market
Data Center and Networking
Netherlands Data Center Networking Market
Data Center and Networking
South Africa Data Center Networking Market
Data Center and Networking
Software Defined Networking (SDN) and Network Function Virtualization (NFV) Market
Data Center and Networking
Thailand Data Center Networking Market
Data Center and Networking
Mobile Data Market
Data Center and Networking
Australia Data Center Networking Market