
 Switzerland Cybersecurity Market | 2026-2036
Switzerland Cybersecurity Market Size, Share, and Industry Trends Forecast 2026-2036
Switzerland Cybersecurity Market Analytics
Quantum-resistant encryption is recalibrating product economics across the Switzerland Cybersecurity Market as post-quantum cryptographic standards render legacy RSA and elliptic-curve implementations obsolete. Kudelski Security leverages its hardware security roots to anchor cryptographic consulting for Swiss watchmakers and aerospace suppliers. IBM Security competes through its Zurich Research Lab's leadership in lattice-based encryption protocols. Deloitte Cyber Risk Services Switzerland dominates regulatory-driven transformation projects for FINMA-supervised institutions.
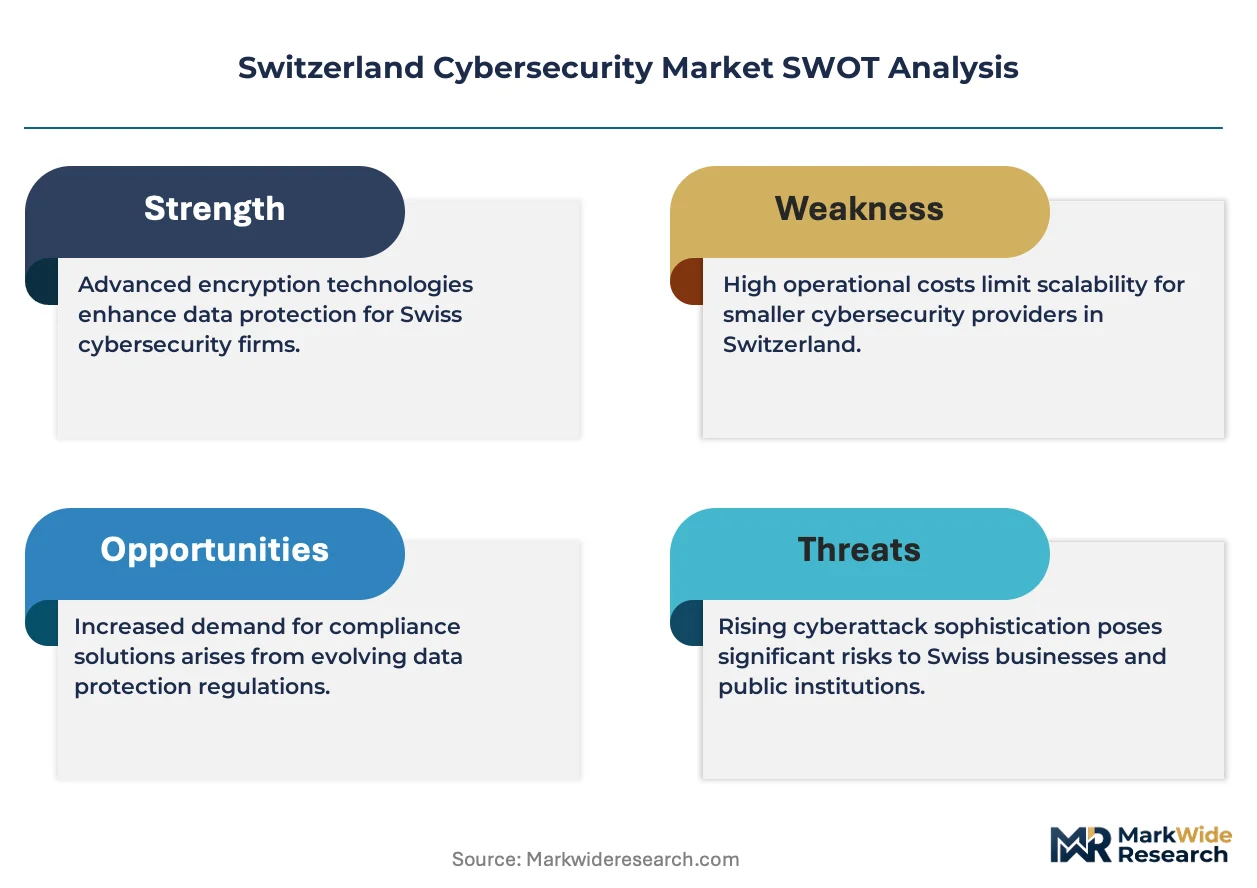
Cybersecurity encompasses technologies, processes, and controls designed to protect systems, networks, and data from digital attacks, with specifications including AES-256 encryption, zero-trust network architectures, and real-time threat detection operating at sub-millisecond latency. Its primary purpose spans confidentiality preservation, integrity assurance, and availability maintenance across critical infrastructure and commercial operations. Cloud-based deployment is capturing share fastest as Swiss SMEs abandon capital-intensive on-premises security stacks. Endpoint security solutions command concentrated margin pools due to remote work permanence and device proliferation. Managed services are maturing into subscription revenue anchors for incumbents serving under-resourced mid-market clients.
FINMA's Cyber Security Guidelines and the Federal Act on the Protection of the Population shape mandatory security baselines for systemically important financial institutions. Swissmedic's digital health oversight and ISO 27001 certification requirements from the Swiss Accreditation Service create layered compliance obligations that expand addressable spending. The Federal Intelligence Service's National Cyber Strategy adds sovereign capability expectations. Stakeholders must monitor quantum computing timelines to calibrate cryptographic refresh cycles against regulatory transition deadlines.
Market Dynamics
Post-quantum cryptographic migration is compressing product lifecycles across Swiss cybersecurity procurement, forcing financial institutions to accelerate encryption refresh cycles ahead of NIST standardization deadlines.
Growth Catalysts
- FINMA Cyber Security Guidelines:Mandatory operational resilience audits for systemically important banks are expanding managed security service contracts. Zurich's financial district concentrates compliance-driven spending.
- Remote work permanence:Device proliferation across Swiss private banking and wealth management is elevating endpoint detection and response procurement priority.
- Lattice-based encryption protocols:IBM Zurich Research Lab's leadership in post-quantum standards is attracting cryptographic consulting demand from aerospace and precision manufacturing supply chains.
Market Restraints
- Specialized talent scarcity:Quantum cryptography and zero-trust architecture skills command premium compensation, inflating delivery costs for Swiss service providers.
- Legacy system integration friction:FINMA-supervised institutions face multi-year migration timelines for mainframe-dependent core banking platforms.
- Vendor concentration risk:Cloud security tooling relies heavily on hyperscale infrastructure with limited Swiss sovereign hosting alternatives.
Strategic Opportunities
- Geneva private banking corridor:Family offices and wealth managers remain underpenetrated for advanced threat intelligence services relative to Zurich's institutional density.
- Swissmedic digital health oversight:Connected medical device security mandates are creating specialized compliance verticals for hospital networks and diagnostics manufacturers.
- AI-augmented security operations:Convergence of machine learning with security orchestration is opening subscription revenue models for mid-market manufacturing clients.
Industry Challenges
- ISO 27001 certification bottlenecks:Swiss Accreditation Service audit capacity constraints are extending compliance timelines for SME exporters.
- Cross-border data governance complexity:Federal Act on the Protection of the Population intersects with EU GDPR, creating jurisdictional ambiguity for multinational headquarters located in Switzerland.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Switzerland Cybersecurity Market |
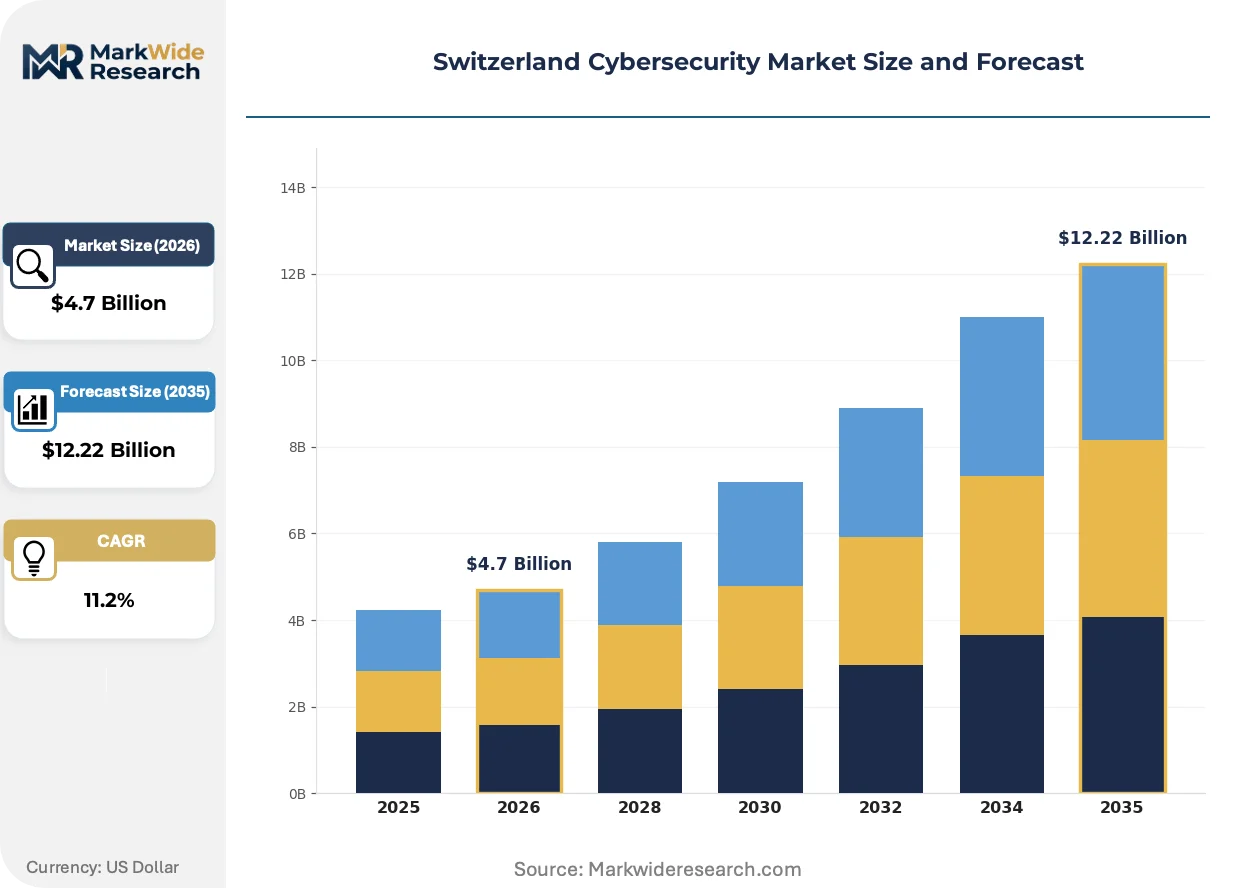
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $12.22 Billion |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: On-Premises, Cloud-Based, Hybrid, Managed Services Service Type: Consulting, Implementation, Risk Management, Training End User Sector: BFSI, Healthcare, Retail, Manufacturing Solution Type: Firewall, Intrusion Detection, Endpoint Security, SIEM |
| Companies Covered | Deloitte Cyber Risk Services Switzerland, EY Cybersecurity Services, Factosecure, IBM Security, Accenture Security Switzerland, Swisscom Security Services, PwC Cybersecurity & Privacy Switzerland, Trend Micro Switzerland, Kudelski Security, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Switzerland Cybersecurity Market Evolving Landscape
Zero-trust network architecture is displacing perimeter-based security models across Swiss financial infrastructure, reconfiguring vendor competitive positions and procurement evaluation criteria.
Confidential computing using hardware-based trusted execution environments is decentralizing data protection responsibilities from centralized security operations centers to individual workload levels. Swiss private banks are piloting these implementations for client portfolio analytics. This decentralization is compressing traditional network segmentation product margins while elevating chip-level security consulting value.
Federal Intelligence Service National Cyber Strategy mandates are tightening baseline security requirements for critical infrastructure operators. Energy and telecommunications sectors face accelerated incident reporting obligations. Healthcare networks under Swissmedic oversight are responding by consolidating security operations under specialized managed service providers.
Swiss manufacturing exporters are unbundling cybersecurity from general IT procurement, establishing direct vendor relationships with specialized security firms rather than channeling through systems integrators. This pattern is most visible in Basel's pharmaceutical cluster and Neuchâtel's precision engineering corridor, where supply chain security certifications now determine supplier eligibility independently of price.
Switzerland Cybersecurity Market Segmentation
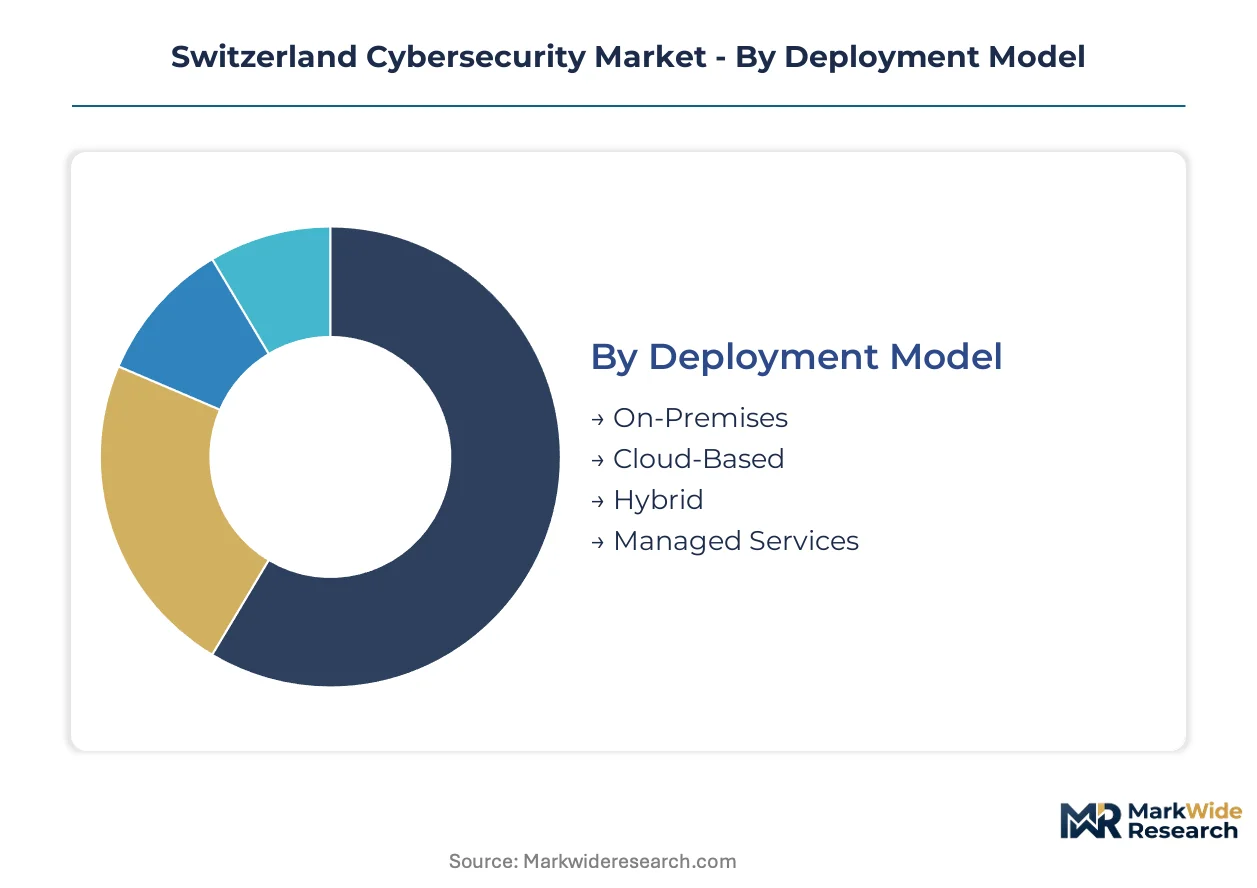
Swiss cybersecurity procurement patterns diverge sharply between Zurich's institutional banking core and Geneva's fragmented wealth management landscape. Deployment preferences, service procurement rhythms, and solution architectures all reflect these geographic and sectoral fault lines.
Deployment Model:
Technology architecture choices in Swiss cybersecurity track directly to capital intensity tolerance and regulatory scrutiny levels across financial districts.
- Cloud-Based:Multi-tenant security platforms eliminate data center overhead for Basel pharmaceutical SMEs and Neuchâtel precision engineering exporters. FINMA-supervised banks in Zurich pilot sovereign cloud configurations to satisfy cross-border data residency requirements.
- Managed Services:Subscription security operations centers absorb talent scarcity costs for mid-market manufacturers lacking in-house cryptographic expertise. Geneva family offices outsource endpoint monitoring to specialized Swiss providers rather than building captive capabilities.
- On-Premises:Air-gapped deployments persist among Swiss watchmakers protecting proprietary CAD files and aerospace suppliers guarding defense export-controlled specifications.
- Hybrid:Split architectures segment sensitive client data on-premises while pushing analytics workloads to cloud security fabrics.
Cloud-Based leads on scale; Managed Services leads on momentum.
Service Type:
Procurement priorities shift with compliance calendar intensity and internal capability gaps across Swiss industrial clusters.
- Consulting:Post-quantum cryptographic migration roadmaps command premium billing from IBM Zurich Research Lab affiliates serving aerospace supply chains. Lattice-based protocol selection demands specialized advisory absent from general IT consultancies.
- Risk Management:FINMA operational resilience audits drive continuous assessment contracts for systemically important banks. Swissmedic-connected hospital networks purchase medical device security risk quantification as standalone engagements.
- Implementation:Zero-trust architecture deployment projects concentrate in Zurich's financial district where legacy mainframe integration complexity requires vendor-managed rollout.
- Training:ISO 27001 certification preparation programs address Swiss Accreditation Service audit capacity constraints by building internal compliance capabilities.
Consulting commands margin concentration; Risk Management expands most quickly.
End User Sector:
Sectoral demand profiles map to regulatory exposure, asset criticality, and supply chain security certification requirements.
- BFSI:Zurich's banking concentration generates concentrated spending on real-time threat detection and zero-trust network segmentation. FINMA Cyber Security Guidelines mandate minimum security baselines that elevate procurement floors.
- Healthcare:Swissmedic digital health oversight creates specialized vertical for connected medical device security. Hospital networks consolidate security operations under managed service providers to meet accelerated incident reporting obligations.
- Manufacturing:Basel pharmaceutical exporters and Neuchâtel precision engineering firms unbundle cybersecurity from general IT procurement, establishing direct vendor relationships for supply chain security certifications.
- Retail:Payment card infrastructure and e-commerce platform protection drive endpoint security procurement for Swiss omnichannel operators.
BFSI dominates absolute spending; Healthcare shows steepest expansion trajectory.
Solution Type:
Technical specifications and latency requirements vary with threat surface geometry and data sensitivity classifications.
- Endpoint Security:Device proliferation across remote wealth management workforces elevates detection and response priority. Agent-based monitoring extends to personal devices accessing Swiss private banking client portfolios.
- SIEM:Security information and event management platforms aggregate telemetry from fragmented Swiss manufacturing supply chains seeking centralized visibility. Correlation engines operate at sub-millisecond latency for Zurich trading floor environments.
- Firewall:Next-generation perimeter controls segment legacy mainframe environments from modern cloud workloads in FINMA-supervised institutions.
- Intrusion Detection:Network-based and host-based systems monitor aerospace supplier environments for defense export control compliance.
Endpoint Security leads on scale; SIEM leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Zurich's financial district anchors Switzerland's cybersecurity demand concentration. Geneva's private banking corridor generates specialized endpoint security procurement. Basel's pharmaceutical cluster and Neuchâtel's precision engineering corridor unbundle security from general IT spending.
Zurich
FINMA-supervised banks drive zero-trust architecture deployment across legacy mainframe environments. The Cyber Security Guidelines mandate operational resilience audits that expand managed security service contracts. Zurich's trading floors demand sub-millisecond latency threat detection, elevating SIEM platform specifications.
Geneva
Family offices and wealth managers prioritize endpoint detection for remote device proliferation. Swiss data residency requirements shape cloud security procurement decisions. The private banking corridor remains underpenetrated for advanced threat intelligence relative to Zurich's institutional density.
Basel
Pharmaceutical exporters unbundle cybersecurity from general IT procurement to secure supply chain certifications. Swissmedic digital health oversight creates compliance verticals for connected medical device security. Roche and Novartis supplier networks demand specialized vendor relationships.
Neuchâtel
Precision engineering firms establish direct security vendor relationships for defense export control compliance. Aerospace suppliers guard CAD specifications through air-gapped deployments. The canton's watchmaking heritage translates into hardware security module adoption for proprietary design protection.
Lausanne
EPFL's cybersecurity research spinoffs commercialize lattice-based encryption protocols. The Lake Geneva tech corridor attracts cryptographic talent from IBM Zurich Research Lab affiliates. Hospital networks under CHUV consolidate security operations under managed service providers.
Switzerland Cybersecurity Market Competitive Landscape
Strategic partnerships dominate the current landscape as vendors combine platform capabilities with specialized consulting expertise. The market structures around three tiers: global professional services networks, Swiss telecom-anchored security divisions, and boutique cryptographic specialists. Consulting-led transformation projects and managed security service subscriptions represent the two primary competitive vectors. Vendor differentiation increasingly hinges on post-quantum cryptography readiness and FINMA audit relationship depth.
Among global professional services networks, Deloitte Cyber Risk Services Switzerland and PwC Cybersecurity & Privacy Switzerland occupy positions emphasizing regulatory-driven transformation. IBM Security represents the technology platform archetype through its Zurich Research Lab affiliation. Kudelski Security exemplifies the hardware-rooted specialist model serving aerospace and precision manufacturing supply chains. Swisscom Security Services anchors the telecom-originated competitive position with sovereign cloud hosting capabilities.
| Leading Market Players |
|---|
| Deloitte Cyber Risk Services Switzerland |
| EY Cybersecurity Services |
| Factosecure |
| IBM Security |
| Accenture Security Switzerland |
| Swisscom Security Services |
| PwC Cybersecurity & Privacy Switzerland |
| Trend Micro Switzerland |
| Kudelski Security |
| Others |
Value Network & Pricing Analysis
Semiconductor component price indices cascade through Swiss cybersecurity procurement tiers, compressing margins on hardware-dependent solutions while elevating subscription-based software premiums. FINMA compliance mandates insulate consulting and managed services from cost pass-through pressure, creating pricing stratification between regulated financial institutions and cost-sensitive mid-market manufacturers.
Pricing Analysis
Input-cost pass-through from specialized talent scarcity drives subscription pricing elevation across managed security services. Three-tier pricing structure across premium, standard, and economy levels separates FINMA-supervised banks with audit-embedded contracts from Geneva family offices purchasing endpoint monitoring, with Neuchâtel precision engineering firms occupying mid-tier procurement. Cost compression in cloud security tooling intensifies because hyperscale infrastructure commoditization erodes differentiation. Mid-market manufacturers demonstrate highest price sensitivity, while systemically important banks exhibit lowest sensitivity due to regulatory non-negotiability.
Supply Chain Analysis
Logistics and freight cost volatility from Asia-Pacific component sourcing elevates landed costs for hardware security modules and network appliances. Supply concentration centers on Taiwan for semiconductor fabrication, Israel for cybersecurity R&D talent pools, and the United States for cloud infrastructure orchestration. Raw material dependencies span silicon wafers, rare earth elements for encryption hardware, and specialized cryptographic ASICs. Single-source vulnerability from Taiwan semiconductor exposure threatens continuity. Distribution runs through Swisscom's sovereign cloud hosting and specialized security integrators serving Zurich's financial district.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Switzerland Cybersecurity Market compounds steadily as post-quantum cryptographic migration creates irreversible refresh cycles across FINMA-supervised institutions. Regulatory tailwinds ensure durable demand regardless of macroeconomic fluctuation.
For Market Incumbents: Cement FINMA audit relationship depth through embedded compliance tooling that increases switching costs. Deepen post-quantum cryptography consulting capabilities ahead of NIST standardization deadlines to capture migration project premiums. Vertical integration into sovereign cloud infrastructure addresses vendor concentration risk threatening Zurich banking clients. For New Entrants and Emerging Players: Capture Geneva's private banking corridor where family offices remain underpenetrated for advanced threat intelligence relative to Zurich's institutional density. Target Swissmedic-connected hospital networks in Lausanne and Basel seeking specialized medical device security compliance. Lead with AI-augmented security operations subscriptions priced below incumbent managed service anchors. For Investors and Strategic Acquirers: Consolidation pressure builds where boutique cryptographic specialists lack scale to serve FINMA transformation timelines independently. Long-term viability favors vendors with dual capability in quantum-resistant protocols and regulatory audit automation. Acquisition target archetype: Swiss mid-market security providers with ISO 27001 certification pipelines and healthcare vertical penetration. Monitor NIST post-quantum standardization announcements as inflection indicator for cryptographic refresh acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Post-Quantum Cryptographic Migration | FINMA deadlines force encryption refresh cycles across Zurich banking infrastructure. |
| Zero-Trust Architecture Deployment | Legacy mainframe integration complexity creates vendor-managed rollout opportunities. |
| Sovereign Cloud Infrastructure Investment | Swiss data residency requirements differentiate hosting from hyperscale alternatives. |
| AI-Augmented Security Operations | Machine learning convergence opens subscription models for mid-market manufacturers. |
| Swissmedic Compliance Verticalization | Connected medical device mandates create specialized hospital network engagements. |
Research Methodology
Bottom-up financial services deployment modeling reconciled against top-down managed service provider capacity tracking forms the analytical core of this study. Primary interviews with CISOs at FINMA-supervised banks, cybersecurity procurement officers at pharmaceutical exporters, Swissmedic compliance leads, and managed security service executives combined with secondary validation from FINMA circulars, Swiss Accreditation Service certification databases, Federal Intelligence Service strategy documents, and hyperscaler Swiss region capex disclosures. Triangulation across these sources ensures segment-level precision.
The input-output matrix framing connects endpoint security agent volumes to remote workforce expansion assumptions, SIEM platform specifications to trading floor latency requirements, and consulting project pipelines to NIST standardization timelines. Segmentation dimensions span deployment model, service type, end-user sector, solution architecture, and cantonal regulatory intensity. CAGRs derive from regression analysis against historical procurement patterns and forward regulatory obligation schedules, incorporating quantum computing threat modeling and FINMA audit frequency projections.
Underlying measurement precision varies by segment; Zurich BFSI spending carries tighter precision than Geneva family office procurement due to disclosure requirements. Forecasts reflect assumptions about NIST standardization adoption curves and FINMA enforcement consistency. A model refresh is warranted upon material change in post-quantum cryptography standardization timelines or FINMA operational resilience audit scope expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cybersecurity
5G Security Market
Cybersecurity
Global Healthcare IoT Security Market
Cybersecurity
Japan Ransomware Protection Market
Cybersecurity
Global Cyber Threat Intelligence Market
Cybersecurity
Middle East & Africa AI Cybersecurity Market
Cybersecurity
United States Cybersecurity Market
Cybersecurity
Global Dynamic Data Masking Market
Cybersecurity
Cyber Deception Market
Cybersecurity
United Kingdom Ransomware Protection Market
Cybersecurity
Managed SIEM Service Market
Cybersecurity
Dark Web Intelligence Market
Cybersecurity
Global Serverless Security Market
Cybersecurity
Europe Zero Trust Security Market
Cybersecurity
India Ransomware Protection Market
Cybersecurity
Cloud DLP Market
Cybersecurity
Germany Endpoint Detection and Response Market