
 Global Data Center Networking Market | 2026-2036
Global Data Center Networking Market Size, Share, and Industry Trends Forecast 2026-2036
Global Data Center Networking Market Foresight
Software-defined networking subscription models is broadening vendor revenue streams beyond hardware refresh cycles. Cisco Systems leverages extensive channel partnerships to sustain enterprise penetration across multi-site deployments. Arista Networks specializes in high-density switching for cloud-scale environments and occupies a differentiated position in low-latency fabrics. Juniper Networks competes through automation-first architectures that reduce operational overhead for telecom operators.
Data center networking encompasses the switching, routing, and interconnect infrastructure that enables compute and storage resource communication within and between facilities, typically operating at speeds from 100 Gbps to 800 Gbps with latency budgets under microseconds for AI workloads. Its primary purpose is to maintain deterministic performance across virtualized and containerized workloads while scaling to tens of thousands of endpoints. Ethernet switching commands the largest installed base among product types, though optical transceivers capture disproportionate margin pools as port speeds escalate. InfiniBand dominates high performance computing application environments where bandwidth and congestion management outweigh cost considerations. SDN technology is gaining traction in hyperscale data centers as disaggregated control planes enable programmatic traffic engineering.
FCC spectrum allocations in the United States, EU GDPR data-localization requirements, and China's MIIT cybersecurity standards collectively shape equipment certification timelines and cross-border deployment constraints. EMA and FDA frameworks indirectly influence networking specifications in pharmaceutical and healthcare data centers where audit trails mandate packet-level visibility. Stakeholders must weigh sovereign infrastructure mandates against interoperability standards when selecting vendor ecosystems for multi-country footprints.
Market Dynamics
AI training clusters are forcing hyperscale operators to rearchitect spine-leaf topologies, compressing upgrade cycles from 36 to 18 months as 800 Gbps ports become baseline for GPU interconnect.
Growth Catalysts
- EU AI Act compliance mandates:Data localization requirements in Germany and France are triggering greenfield facility builds with sovereign networking stacks.
- Optical co-packaging breakthroughs:Silicon photonics integration is reducing power-per-bit by half in AI training fabrics.
- India's domestic cloud buildout:PLI scheme incentives are accelerating indigenous switching capacity for government and telecom workloads.
Market Restraints
- Advanced CMOS node concentration:3nm and 5nm fabrication for high-bandwidth switch ASICs depends on Taiwan-based foundry capacity.
- Copper and rare earth volatility:Optical transceiver manufacturing faces input cost swings from dysprosium and terbium supply constraints.
- China MIIT cybersecurity certification:Cross-border equipment approvals now require 14-18 month validation cycles for foreign vendors.
Strategic Opportunities
- Brazil's underpenetrated colocation sector:ANATEL spectrum reforms are enabling edge networking investments outside São Paulo.
- Liquid cooling convergence with networking:Immersion-cooled switch designs are opening premium positioning for heat-dense AI clusters.
- Japan METI green data center incentives:Subsidies for energy-efficient interconnect are redirecting procurement toward low-power 800G platforms.
Industry Challenges
- InfiniBand-Ethernet protocol integration:Hybrid AI fabrics require scarce engineers fluent in both RDMA and RoCEv2 optimization.
- OSHA and EU machinery directive compliance:High-voltage 800G power-over-ethernet installations face extended safety certification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Data Center Networking Market |
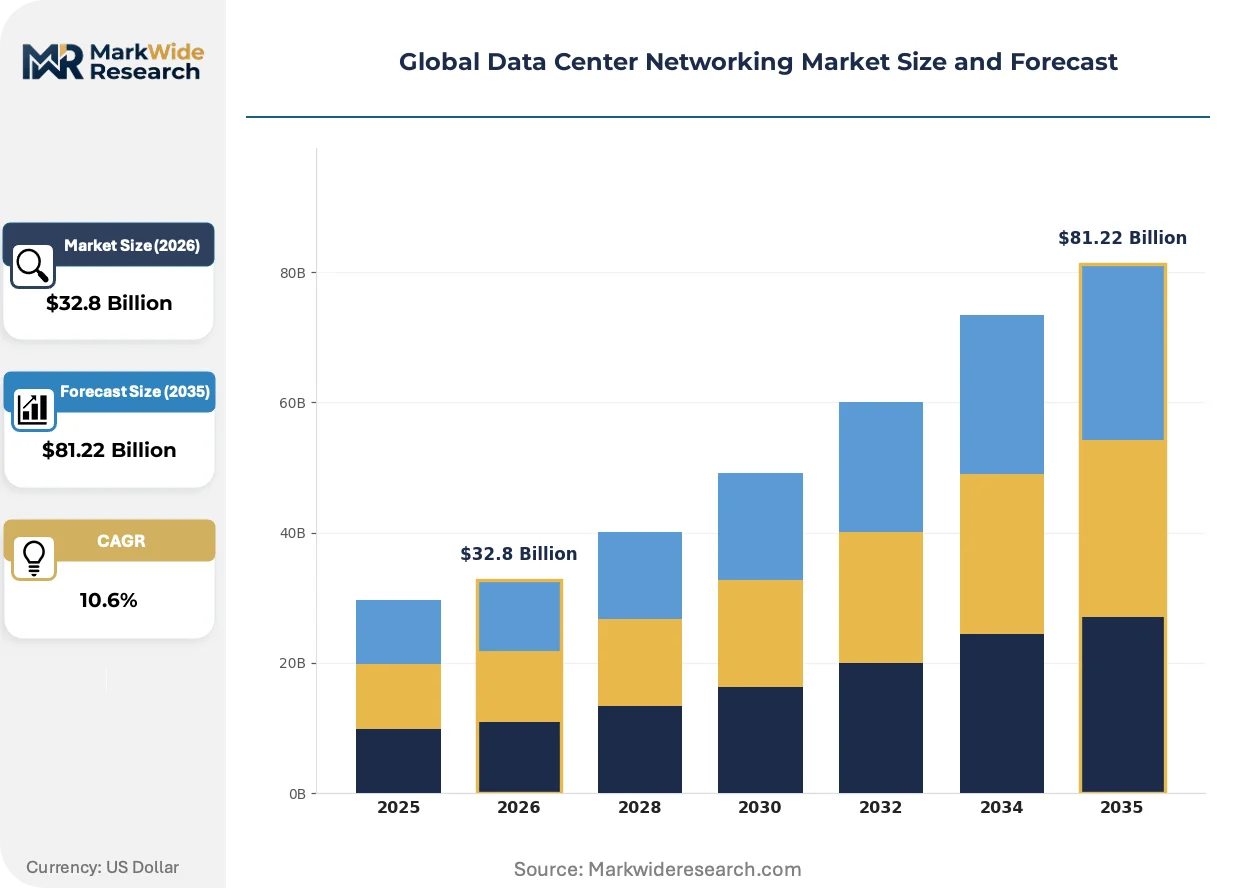
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $81.22 Billion |
| CAGR (2026 – 2036) | 10.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Switches, Routers, Network Interface Cards, Load Balancers, Firewalls, Optical Transceivers Technology: Ethernet, Fibre Channel, InfiniBand, MPLS, SDN, FCoE Application: Cloud Computing, Hyperscale Data Centers, Colocation Facilities, Edge Computing, Content Delivery Networks, High Performance Computing End User: Telecom Operators, Enterprise Data Centers, Government Agencies, Financial Institutions, E-commerce Companies, Research Organizations |
| Companies Covered | Cisco Systems, Arista Networks, Juniper Networks, Huawei Technologies, Dell Technologies, Hewlett Packard Enterprise, NVIDIA Corporation, Extreme Networks, Broadcom, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Data Center Networking Market Shifts & Advancements
Programmable data planes and merchant silicon commoditization are compressing vendor differentiation windows. Operators now demand interoperable white-box alternatives to proprietary chassis.
Co-packaged optics is consolidating switching and transceiver functions into single substrate designs. Hyperscale operators in the United States and China are deploying these in 51.2 Tbps generation switches. This consolidation is collapsing the traditional optical-discrete supply chain into vertically integrated switch manufacturing.
REACH substance restrictions and EU F-Gas Regulation are banning sulfur hexafluoride in high-voltage switchgear insulation. Equipment vendors must redesign arc-quenching systems using fluoronitrile or vacuum interrupters. German and French utilities are accelerating procurement of SF6-free substation networking ahead of 2030 mandates.
Consumption-based network-as-a-service contracts are displacing perpetual licensing in enterprise data centers. Managed service providers in India and Southeast Asia are bundling switching hardware with operational support. This model shifts capital risk to vendors while locking in 3-5 year revenue visibility.
Global Data Center Networking Market Segmentation
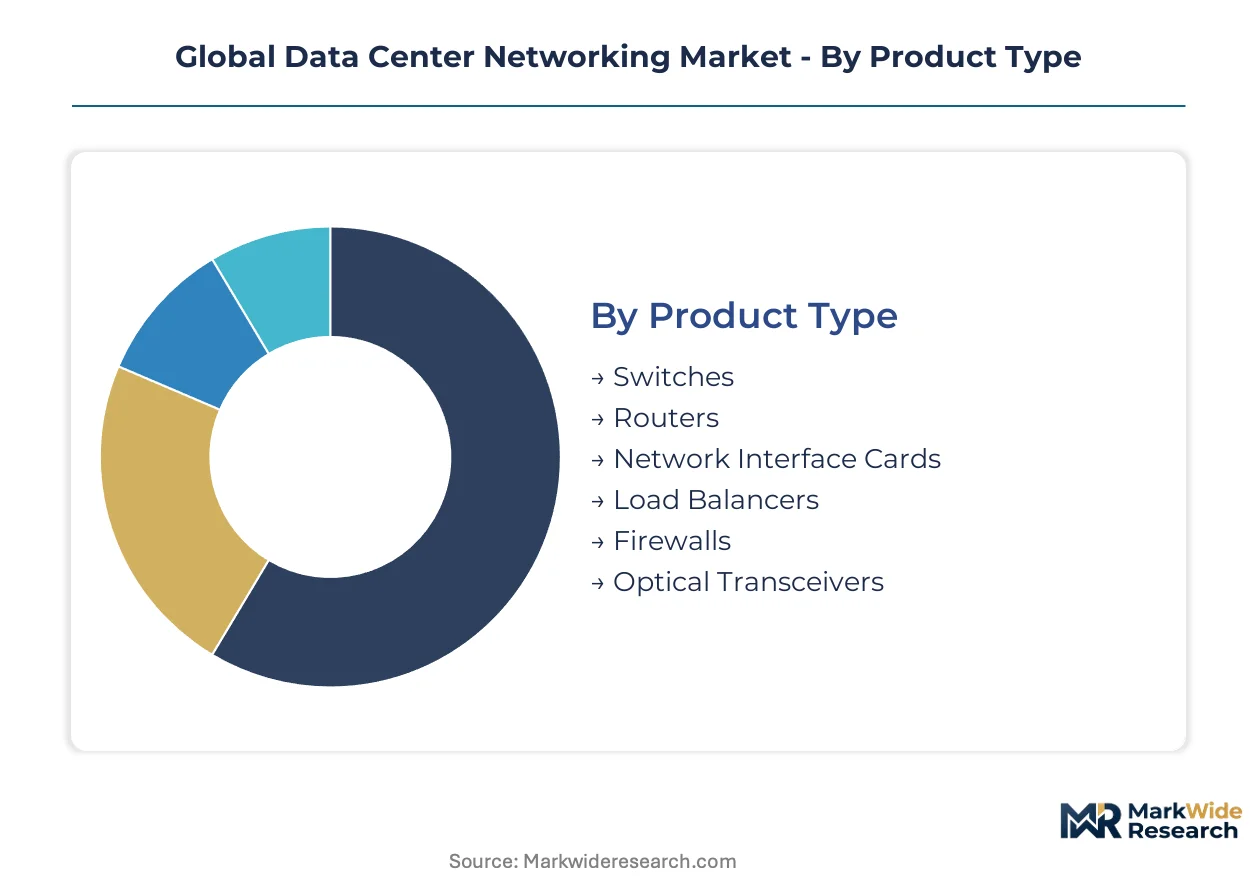
Segmentation in data center networking reveals how capital allocation priorities diverge across hardware layers, protocol stacks, and deployment archetypes. Infrastructure buyers optimize for latency budgets, port densities, or compliance requirements depending on workload type.
Product Type:
Capital intensity peaks in switching and optical subsystems, where 800 Gbps generation upgrades demand foundry commitments and silicon photonics co-development.
- Switches:Spine-leaf architectures deploy these at 100-800 Gbps port speeds with sub-microsecond latency budgets. Hyperscale operators in the United States and China compress refresh cycles to 18 months for GPU interconnect fabrics.
- Optical Transceivers:Silicon photonics integration consolidates laser, modulator, and receiver functions into single substrates. Germany and France drive demand through sovereign data localization builds under EU AI Act mandates.
- Routers:Border gateway and inter-facility traffic management devices handling BGP and segment routing protocols.
- Network Interface Cards:Server-attached adapters enabling RDMA offload for AI training clusters.
- Load Balancers:Application delivery controllers distributing traffic across distributed compute pools.
- Firewalls:East-west segmentation enforcement for zero-trust architectures in financial and government facilities.
Switches absorb the bulk of installed capacity; optical transceivers are expanding most quickly as port speeds escalate and co-packaged optics displace discrete modules.
Technology:
Protocol selection hinges on workload parallelism requirements, with bandwidth-hungry AI training favoring lossless fabrics over cost-optimized Ethernet.
- Ethernet:Dominates general-purpose compute with RoCEv2 extensions for RDMA compatibility. Enterprise data centers in India standardize on 100-400 Gbps deployments under PLI scheme incentives.
- InfiniBand:Lossless transport with hardware congestion management for GPU-to-GPU communication. China's hyperscale operators deploy this for exascale training clusters despite MIIT certification delays for foreign equipment.
- Fibre Channel:Storage-area network protocol for block-level data access in enterprise facilities.
- MPLS:Traffic engineering for multi-tenant colocation interconnection services.
- SDN:Disaggregated control planes enabling programmatic network management.
- FCoE:Converged storage and data traffic over Ethernet infrastructure.
Ethernet commands the largest installed base; InfiniBand is climbing the fastest as AI training clusters proliferate.
Application:
Deployment scale determines architectural complexity, from centralized hyperscale campuses to geographically distributed edge nodes.
- Hyperscale Data Centers:Facilities exceeding 50 MW power draw with spine-leaf fabrics scaling to 100,000+ endpoints. United States operators lead 800 Gbps generation adoption for generative AI training infrastructure.
- Edge Computing:Sub-10 MW facilities positioned within 20 milliseconds of population centers. Brazil's ANATEL spectrum reforms enable networking investments outside São Paulo for low-latency applications.
- Cloud Computing:Virtualized resource pools with software-defined networking overlays.
- Colocation Facilities:Multi-tenant environments requiring cross-connect and interconnection services.
- Content Delivery Networks:Caching-optimized nodes for video and software distribution.
- High Performance Computing:Research and simulation clusters with tightly coupled interconnect topologies.
Hyperscale data centers concentrate the majority of high-speed port shipments; edge computing is gaining share fastest as latency-sensitive workloads decentralize.
End User:
Procurement patterns diverge between regulated entities with audit requirements and cloud-native operators optimizing for speed-to-deploy.
- Telecom Operators:5G core and edge data center builds requiring carrier-grade reliability. Japan's NTT and KDDI leverage METI green data center subsidies for energy-efficient interconnect procurement.
- Financial Institutions:Low-latency trading infrastructure with packet-level visibility mandates. Frankfurt and London facilities face ECB and FCA audit trail requirements for network telemetry.
- Enterprise Data Centers:Private cloud and legacy application hosting with hybrid connectivity needs.
- Government Agencies:Sovereign cloud deployments with data localization and classification requirements.
- E-commerce Companies:Seasonal burst capacity with automated scaling policies.
- Research Organizations:Grant-funded HPC installations with InfiniBand preference for simulation workloads.
Telecom operators deploy the greatest switch volume by port count; financial institutions are expanding fastest as algorithmic trading infrastructure upgrades accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment fabrication concentrates in Taiwan and South Korea, while deployment demand clusters in the United States, China, and India. This geographic split creates supply chain exposure when sovereign data laws accelerate local builds.
United States
Hyperscale operators in Northern Virginia and Dallas-Fort Worth deploy 800 Gbps spine-leaf fabrics for generative AI training clusters. FCC spectrum allocations shape equipment certification timelines for cross-border deployments. Phoenix and Atlanta data center campuses absorb the majority of domestic optical transceiver shipments.
China
MIIT cybersecurity standards extend foreign equipment validation cycles to 14-18 months, accelerating domestic switching procurement. State-backed cloud operators in Beijing and Shanghai build exascale training infrastructure with indigenous interconnect stacks. Yangtze River Delta facilities lead domestic silicon photonics adoption.
Germany
EU AI Act data localization mandates trigger greenfield sovereign cloud builds in Frankfurt and Munich. KBA and federal cybersecurity frameworks enforce packet-level audit trails for financial data centers. Bavaria's industrial data lake projects demand low-latency fabrics for real-time manufacturing analytics.
India
PLI scheme incentives redirect telecom and government workloads toward indigenous switching capacity. TRAI spectrum reforms enable edge networking investments in Mumbai and Bangalore. Hyderabad and Chennai data center clusters scale 400 Gbps deployments under domestic cloud buildout programs.
Japan
METI green data center subsidies redirect procurement toward energy-efficient 800G platforms. Tokyo and Osaka hyperscale facilities prioritize liquid-cooled interconnect for heat-dense AI workloads. Chubu region manufacturing data centers adopt low-power optical transceivers under carbon reduction mandates.
Global Data Center Networking Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across switch ASIC and optical component layers. The vendor base organizes around three strategic archetypes: integrated chassis vendors, merchant silicon specialists, and optical subsystem suppliers. Consolidation pressure intensifies as co-packaged optics collapses traditional supply chain boundaries. Dominant competitive moves include strategic partnerships with hyperscale operators and backward integration into silicon photonics fabrication.
Among integrated platform vendors, Cisco Systems exemplifies the channel-anchored enterprise archetype with multi-site deployment reach. Arista Networks occupies a differentiated position in cloud-scale spine-leaf fabrics. Juniper Networks represents the automation-first positioning targeted at telecom operator infrastructure. These three anchors illustrate how vendor specialization maps to distinct procurement constituencies.
| Leading Market Players |
|---|
| Cisco Systems |
| Arista Networks |
| Juniper Networks |
| Huawei Technologies |
| Dell Technologies |
| Hewlett Packard Enterprise |
| NVIDIA Corporation |
| Extreme Networks |
| Broadcom |
| Others |
Supply & Pricing Matrix
Silicon photonics co-development costs cascade through switch ASIC procurement tiers, with 3nm foundry commitments in Taiwan and South Korea feeding premium chassis pricing while merchant silicon alternatives anchor mid-market Ethernet deployments.
Pricing Analysis
Cost-down pressure on 800 Gbps spine-leaf chassis accelerates because hyperscale operators in the United States and China compress refresh cycles to 18 months. Three-tier pricing structure across premium, standard, and economy levels separates co-packaged optical platforms from discrete transceiver bundles and white-box merchant silicon alternatives. Price differentiation rests on ASIC node geometry and silicon photonics integration depth. Telecom operators in India exhibit highest price sensitivity under PLI scheme procurement, while financial institutions in Frankfurt and London absorb premiums for packet-level audit trail compliance.
Supply Chain Analysis
Regional distribution centers in Singapore, Rotterdam, and Los Angeles warehouse finished switches before hub-and-spoke deployment to hyperscale campuses. Foundry capacity concentrates in Taiwan and South Korea for advanced CMOS nodes, while China and Japan anchor silicon photonics substrate fabrication. Raw material dependencies span dysprosium and terbium for optical transceiver magnetics, high-purity silicon for photonics, and copper for backplane interconnect. Single-source vulnerability around Taiwan-based 3nm production creates supply chain risk. Distribution runs through direct-vendor relationships with hyperscale operators and tier-one systems integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Programmable data planes and merchant silicon commoditization are displacing proprietary chassis architectures, forcing incumbents to defend through silicon photonics integration and automation software lock-in.
For Market Incumbents: Hedge against white-box erosion by deepening captive supply of silicon photonics components through backward integration into substrate fabrication. Fortify channel control over multi-site enterprise deployments to offset hyperscale procurement consolidation toward direct-merchant relationships. Automation software stacks represent the priority defensive lever as hardware margins compress. For New Entrants and Emerging Players: Capture underpenetrated edge networking demand in Brazil outside São Paulo where ANATEL spectrum reforms enable greenfield investments. Target liquid-cooled switch designs for heat-dense AI clusters in Japan under METI subsidy programs. Lead with consumption-based network-as-a-service contracts to bypass incumbent channel entrenchment. For Investors and Strategic Acquirers: MIIT certification delays for foreign equipment in China is the leading indicator that indigenous interconnect stacks will capture share in sovereign cloud builds. Long-term viability favors asset-light designers with optical subsystem partnerships over capital-heavy chassis vendors. Monitor 800 Gbps port attach rates in United States hyperscale facilities as the inflection signal for co-packaged optics adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Photonics Backward Integration | Captive substrate supply secures margin control as co-packaged optics collapses discrete supply chains. |
| Network-as-a-Service Contract Expansion | Consumption-based pricing locks in 3-5 year revenue visibility while shifting capital risk to vendors. |
| Liquid-Cooled Switch Platform Launch | Immersion-cooled designs command premium positioning for heat-dense AI training clusters under METI incentives. |
| EU AI Act Compliance Certification | Sovereign networking stack approval unlocks greenfield facility builds in Germany and France. |
| Merchant Silicon Partnership Expansion | White-box interoperability addresses hyperscale demand for disaggregated control planes. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with hyperscale network architects, telecom procurement officers, cloud platform engineers, and optical component sourcing leads. SEC 10-K disclosures, MIIT certification databases, EU AI Act implementation guidance, and hyperscaler capital expenditure reports provided demand-side validation. Bottom-up port shipment modeling triangulated against top-down infrastructure spending forecasts.
Granularity-level modeling deployed switch port speeds, protocol stacks, and deployment archetypes as core segmentation dimensions across the analysis window. CAGRs derived from unit economics of 100-800 Gbps transition curves and silicon photonics cost reduction trajectories. InfiniBand attach rates in AI training clusters and sovereign data localization build timelines in Germany and France served as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Taiwan foundry capacity allocation and rare earth supply constraints. Forecasts reflect documented assumptions around hyperscale capex commitment durability and regulatory certification timeline stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Voice Over Internet Protocol (Voip) Market
Data Center and Networking
Australia Data Center Networking Market
Data Center and Networking
Global Virtual Private Network Market
Data Center and Networking
France Data Center Networking Market
Data Center and Networking
Asia-Pacific Data Virtualization Market
Data Center and Networking
Germany Data Center Networking Market
Data Center and Networking
South America Data Center Networking Market
Data Center and Networking
Global Data Lakes Market
Data Center and Networking
Global Storage Area Network (SAN) Switches Market
Data Center and Networking
Ethernet Transceivers Market
Data Center and Networking
Global Scalable Software Defined Networking Market
Data Center and Networking
India Data Center Networking Market
Data Center and Networking
Middle East Data Center Server Market
Data Center and Networking
Chile Data Center Networking Market
Data Center and Networking
Global Virtual Network Functions Market
Data Center and Networking
Global Data Management Platform Market