
 North America Subscriber Data Management Market | 2026-2036
North America Subscriber Data Management Market Size, Share, and Industry Trends Forecast 2026-2036
North America Subscriber Data Management Market Analytics
Cloud-native infrastructure is broadening the economic viability of subscriber data platforms across tier-one and tier-two carriers. Oracle leverages its installed database base to anchor long-term telecom contracts. Cisco Systems dominates network-edge integration, while Nokia Corporation competes through 5G core alignment with operator subscriber functions.
Subscriber data management encompasses the collection, storage, governance, and real-time processing of subscriber identity, service entitlement, and usage records across telecommunications and digital service environments. Platforms typically integrate LDAP directories, policy control functions, and unified data repositories to enable authentication, authorization, and charging decisions at millisecond latency. Cloud-based deployment leads structural growth as operators retire on-premises directory systems for elastic, API-first architectures. Customer analytics within the solution layer captures expanding margin pools as carriers monetize behavioral data for personalized service packaging.
The FCC governs subscriber privacy and data breach notification requirements for U.S. communications providers, while state frameworks such as the California Consumer Privacy Act impose additional consent and deletion obligations that shape platform design priorities. Canada's Office of the Privacy Commissioner and the Personal Information Protection and Electronic Documents Act establish parallel compliance thresholds for cross-border operators. Stakeholders must monitor emerging state patchwork legislation and anticipate how interoperability mandates between North American regulators will influence data residency and portability feature roadmaps.
Market Dynamics
Telecom operators across the United States and Canada are dismantling legacy directory architectures to accommodate 5G-era identity volumes, forcing wholesale platform replacement cycles that concentrate procurement among cloud-native vendors.
Growth Catalysts
- 5G Core Network Rollouts:United States wireless carriers are deploying standalone 5G cores that require real-time subscriber authentication at millisecond latency, mandating modernized data management infrastructure.
- California Consumer Privacy Act (CCPA):Stringent consent and deletion obligations imposed by state-level frameworks are accelerating compliance-oriented platform upgrades across multi-state operators.
- API-First Architectures:Elastic cloud directories are displacing rigid LDAP systems, enabling tier-two carriers to access capabilities previously reserved for tier-one capital budgets.
Market Restraints
- Data Residency Requirements:Canada's Personal Information Protection and Electronic Documents Act establishes cross-border data flow restrictions that fragment platform deployment strategies.
- Specialized Engineering Talent:Scarcity of professionals skilled in telecom-grade directory services and real-time policy control functions inflates implementation timelines.
- Legacy System Entrenchment:Decades-old subscriber databases within incumbent operators create technical debt that resists cloud migration without costly parallel-run periods.
Strategic Opportunities
- Mid-Market Carrier Penetration:Tier-two and tier-three operators across the United States represent underserved demand for scalable, subscription-based subscriber data platforms.
- Behavioral Analytics Monetization:Machine learning integration with subscriber profiles creates new revenue streams through personalized service packaging and churn prediction.
- FCC Privacy Framework Evolution:Anticipated federal preemption of state privacy patchworks could standardize compliance requirements and accelerate procurement decisions.
Industry Challenges
- Interoperability Complexity:Synchronizing cloud-native subscriber platforms with existing billing, policy control, and network function virtualization stacks demands specialized integration expertise.
- Certification Timeline Compression:Rapid evolution of state-level data governance laws outpaces vendor certification cycles, creating compliance gaps during deployment windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Subscriber Data Management Market |
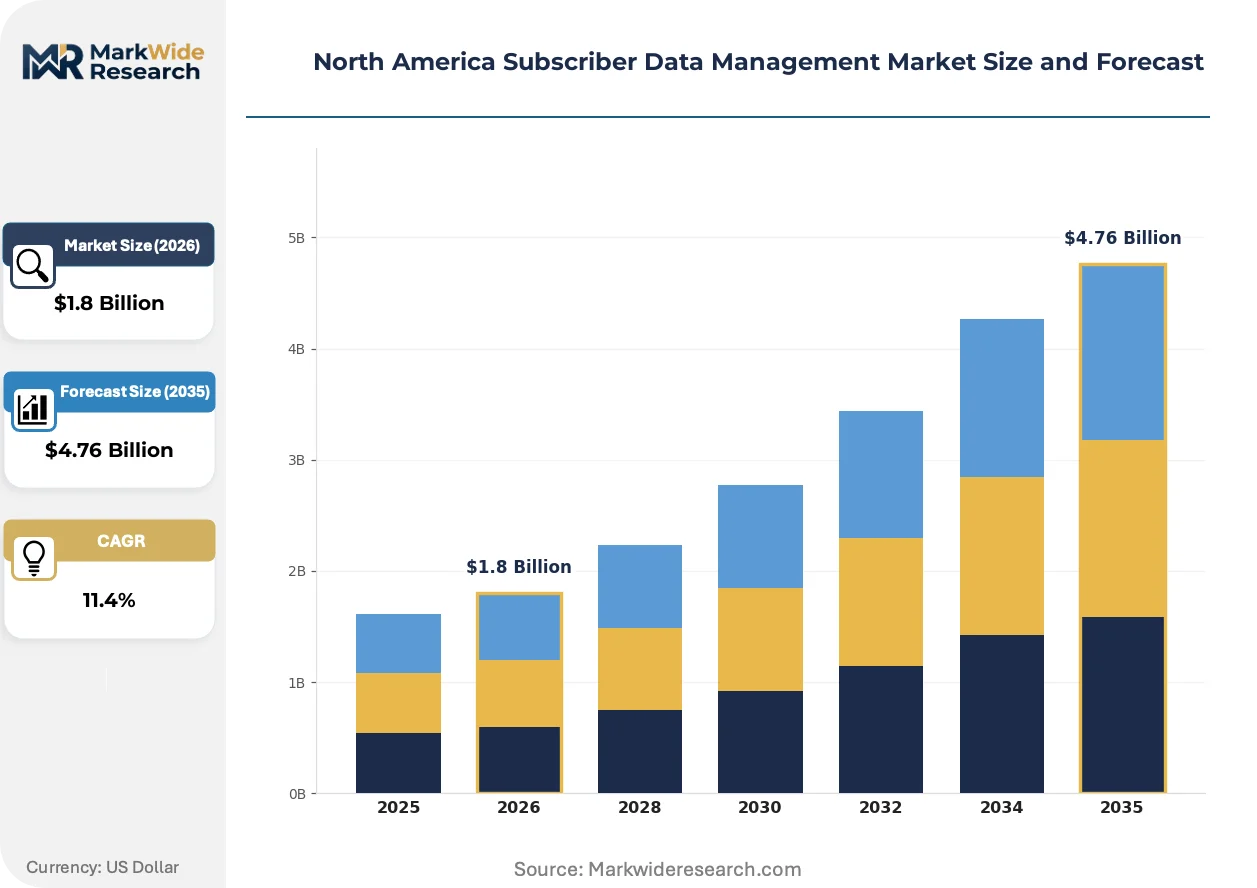
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, SaaS End User: Telecom Operators, Enterprises, Social Media Platforms, Streaming Services Solution: Data Quality Management, Identity Access Management, Customer Analytics, Data Integration Application: Customer Retention, Churn Management, Marketing Optimization, Revenue Management |
| Companies Covered | Oracle, IBM, Amdocs, Hewlett Packard Enterprise, Nokia Corporation, Telefonaktiebolaget LM Ericsson, Cisco Systems, Salesforce, Microsoft, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Subscriber Data Management Market Evolving Landscape
Cloud-native directory services are fundamentally restructuring how North American carriers provision identity and entitlement management, compressing deployment timelines while expanding functional scope beyond traditional subscriber repositories.
Containerized microservices architectures are expanding into real-time subscriber authentication workloads, replacing monolithic LDAP deployments. Tier-one United States wireless carriers are adopting Kubernetes-orchestrated directory services at scale. This shift is expanding into policy control and charging integration points previously handled by discrete network elements.
The FCC's evolving breach notification requirements are mandating granular audit trails and automated consent management modules. Platform vendors must now embed privacy-by-design features that satisfy both federal communications rules and state-level consumer protection frameworks. Canadian operators face parallel obligations under Office of the Privacy Commissioner guidance, driving cross-border feature standardization.
Carrier procurement of subscriber data platforms is consolidating around outcome-based performance contracts rather than perpetual license models. Large United States wireless operators now demand guaranteed latency thresholds and uptime commitments as contractual deliverables. This reconfiguration shifts vendor risk profiles and accelerates competitive displacement of traditional software licensing approaches.
North America Subscriber Data Management Market Segmentation
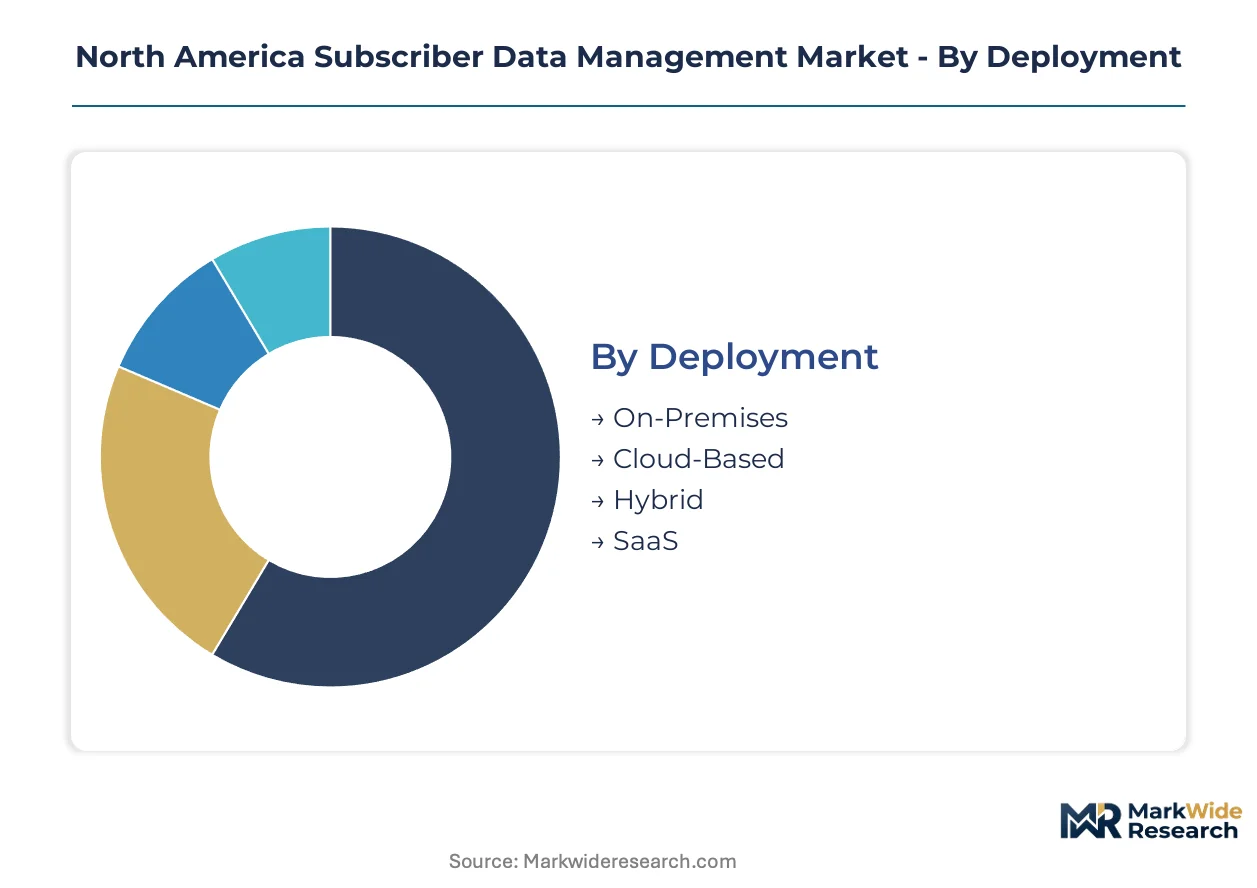
Subscriber data management platforms fragment across deployment architectures, end-user categories, solution layers, and application use cases. Each dimension carries distinct procurement patterns, margin profiles, and integration complexity that shape vendor positioning across United States and Canadian markets.
Deployment:
Supply concentration among cloud-native infrastructure providers is compressing deployment timelines while expanding functional scope beyond traditional subscriber repositories.
- Cloud-Based:Elastic, API-first architectures displace rigid legacy directories, enabling millisecond-latency authentication for 5G core networks. United States tier-one wireless carriers concentrate procurement here, driven by FCC-aligned privacy audit requirements and automated consent management needs.
- SaaS:Subscription models reduce capital expenditure barriers for tier-two and tier-three operators across the United States and Canada. Procurement is accelerating among mid-market carriers seeking guaranteed latency thresholds without perpetual license commitments.
- On-Premises:Incumbent operators with decades-old subscriber databases maintain these deployments during parallel-run migration periods. Technical debt resists immediate cloud migration without costly certification cycles.
- Hybrid:Combines cloud elasticity with on-premises data residency controls for cross-border operators navigating Canada's Personal Information Protection and Electronic Documents Act restrictions.
Cloud-Based absorbs the bulk of installed capacity; SaaS is expanding most quickly.
End User:
Customer type determines integration complexity, with telecom-grade requirements demanding specialized engineering talent that inflates implementation timelines.
- Telecom Operators:United States and Canadian wireless carriers require real-time policy control integration, charging system synchronization, and network function virtualization stack compatibility. 5G standalone core rollouts mandate modernized data management infrastructure.
- Enterprises:Large organizations across financial services and healthcare verticals adopt subscriber-data architectures for workforce identity management. CCPA and state-level deletion obligations shape platform selection.
- Social Media Platforms:Behavioral analytics monetization drives demand for machine learning-integrated subscriber profiles. Personalized service packaging creates new revenue streams.
- Streaming Services:Churn prediction and content recommendation engines require customer analytics modules. Subscription-based business models prioritize retention-focused data governance.
Telecom Operators command the deepest integration requirements; Streaming Services are climbing the fastest.
Solution:
Margin pools concentrate where platforms enable monetization of behavioral data beyond core identity management functions.
- Customer Analytics:Machine learning integration captures expanding margin pools as carriers monetize subscriber profiles for personalized service packaging. United States wireless operators prioritize churn prediction and marketing optimization capabilities.
- Identity Access Management:Real-time authentication at millisecond latency underpins 5G core network security. FCC breach notification requirements mandate granular audit trails and automated consent management.
- Data Quality Management:Ensures subscriber record accuracy across fragmented legacy and cloud-native repositories. Critical for cross-border operators managing Canada's data residency thresholds.
- Data Integration:Synchronizes subscriber platforms with billing, policy control, and network function virtualization stacks. Specialized integration expertise commands premium pricing.
Identity Access Management anchors the largest installed base; Customer Analytics is gaining share fastest.
Application:
Outcome-based performance contracts now tie vendor compensation to measurable business results rather than technical specifications alone.
- Customer Retention:Proactive subscriber engagement powered by behavioral analytics reduces churn. United States carriers demand guaranteed retention improvement metrics in procurement contracts.
- Churn Management:Predictive models identify at-risk subscribers before service cancellation. Machine learning integration with unified data repositories enables intervention workflows.
- Marketing Optimization:Personalized service packaging leverages real-time entitlement and usage records. API-first architectures enable dynamic offer orchestration.
- Revenue Management:Policy control functions integrated with subscriber data enable usage-based pricing and tiered service monetization. Critical for 5G network slicing commercialization.
Customer Retention absorbs the majority of platform investment; Churn Management is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States wireless carriers concentrate procurement among cloud-native infrastructure providers as 5G standalone core rollouts mandate millisecond-latency subscriber authentication. Canadian operators navigate cross-border data residency thresholds under federal privacy frameworks. Mexican telecom providers represent emerging demand as regional network modernization accelerates.
United States
Tier-one wireless carriers in the United States drive concentrated demand for elastic, API-first subscriber data architectures. The FCC's evolving breach notification requirements mandate granular audit trails and automated consent management modules. California's CCPA imposes stringent deletion obligations that shape platform design priorities for multi-state operators headquartered in San Francisco and Los Angeles.
Canada
Canadian telecom operators require hybrid deployment models combining cloud elasticity with on-premises data residency controls. The Office of the Privacy Commissioner and PIPEDA establish cross-border data flow restrictions that fragment platform strategies. Toronto and Vancouver host the primary engineering clusters where carriers synchronize subscriber platforms with billing and policy control stacks.
Mexico
Mexican wireless providers are dismantling legacy directory architectures to accommodate 5G-era identity volumes. The country's federal telecommunications regulator shapes compliance thresholds for subscriber privacy and data governance. Mexico City anchors the primary deployment activity as carriers modernize infrastructure to serve expanding digital service ecosystems.
North America Subscriber Data Management Market Competitive Landscape
Strategic partnerships dominate the current landscape as vendors align subscriber data platforms with 5G core network rollouts. The vendor base concentrates around three tiers: database-anchored incumbents with long-term telecom contracts, network-edge specialists integrating policy control functions, and cloud-native challengers offering subscription-based deployment. Consolidation pressures favor players with pre-existing carrier relationships and certified compliance frameworks. M&A activity and API-first portfolio diversification represent the dominant competitive vectors reshaping positioning.
Within the database-anchored tier, Oracle leverages installed base relationships to secure long-term telecom infrastructure contracts. Cisco Systems occupies a position exemplifying network-edge integration specialists, while Nokia Corporation represents the 5G core alignment archetype competing through subscriber function synchronization. These three anchors illustrate how vendor positioning stratifies across deployment architecture specializations rather than geographic origin alone.
| Leading Market Players |
|---|
| Oracle |
| IBM |
| Amdocs |
| Hewlett Packard Enterprise |
| Nokia Corporation |
| Telefonaktiebolaget LM Ericsson |
| Cisco Systems |
| Salesforce |
| Microsoft |
| Others |
Value Network & Pricing Analysis
Outcome-based performance contracts among United States tier-one wireless carriers are forcing vendors to absorb latency-uptime risk, compressing margins and accelerating the shift from perpetual licenses to subscription models across the vendor base.
Pricing Analysis
Volume concentrates in cloud-native SaaS tiers while margin pools accrue to customer analytics modules. Pricing stratifies across premium latency-guaranteed, standard API-access, and economy self-service tiers, with differentiation driven by FCC certification level and after-sales integration support. Cost compression in the economy tier is intensifying because mid-market carriers demand subscription access without perpetual license commitments. Tier-two operators exhibit highest price sensitivity; tier-one carriers prioritize guaranteed performance over unit cost.
Supply Chain Analysis
Domestic-content mandates under the FCC's evolving breach notification frameworks are reshaping sourcing toward U.S.-based engineering clusters and Canadian data residency-compliant infrastructure. Component supply draws from the United States, Canada, and Ireland for cloud directory services, policy control software, and real-time analytics engines. Raw material dependencies center on semiconductor substrates, optical networking hardware, and encryption modules. Single-source vulnerability in specialized telecom-grade directory talent inflates implementation timelines. Distribution runs through direct vendor-carrier procurement channels and systems integrator partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America Subscriber Data Management Market functions as a cost-of-compliance arena where the FCC's breach notification mandates erect barrier-to-entry moats favoring vendors with pre-certified privacy-by-design architectures.
For Market Incumbents: Acquire cloud-native engineering talent pools to defend against API-first challengers displacing legacy directory incumbents. Deepen backward integration into real-time policy control functions to capture margin pools leaking to network-edge specialists. Prioritize certification investment for automated consent management modules ahead of anticipated federal preemption of state privacy patchworks. For New Entrants and Emerging Players: Cloud-native channel partnerships with tier-two Canadian carriers represent the most penetrable white-space target, given PIPEDA-driven hybrid deployment demand underserved by U.S.-centric vendors. Machine learning integration for churn prediction offers a distinct go-to-market angle against database-anchored incumbents lacking behavioral analytics capabilities. For Investors and Strategic Acquirers: The window for entry favors compliance-certified platform vendors with pre-existing carrier relationships over pure-play analytics challengers. Long-term viability hinges on 5G core alignment and cross-border regulatory interoperability. Monitor FCC preemption signals as the inflection indicator accelerating procurement consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Migration | Elastic Kubernetes-orchestrated architectures displace monolithic LDAP systems at tier-one U.S. carriers. |
| Privacy-by-Design Certification | FCC-aligned automated consent modules embed compliance at the infrastructure layer for multi-state operators. |
| Customer Analytics Integration | Machine learning subscriber profiles enable churn prediction revenue streams beyond core identity management. |
| Hybrid Deployment Expansion | PIPEDA-compliant cross-border architectures capture Canadian operator procurement requiring data residency controls. |
| Outcome-Based Contracting | Latency-uptime guarantees shift vendor risk profiles and displace traditional software licensing approaches. |
Research Methodology
Document review covered FCC rulemaking dockets, state attorney general privacy enforcement actions, and carrier procurement disclosures, complemented by interviews with telecom infrastructure executives, cloud platform engineers, regulatory compliance officers, and systems integration specialists. Secondary validation drew from SEC filings of publicly traded vendors, hyperscaler capex disclosures, and Canadian Office of the Privacy Commissioner guidance documents. Bottom-up deployment volume estimates triangulated against top-down carrier capital expenditure projections.
Market size and growth trajectory outputs reflect segmentation across deployment architecture, end-user category, solution layer, and application use case, with additional granularity for regional regulatory cluster differences. CAGRs were derived from elasticity modeling of carrier procurement cycles against compliance mandate timelines. Forecast inputs incorporated 5G standalone core rollout schedules and state-level privacy law adoption patterns.
The model holds under stable regulatory enforcement intensity and continued carrier cloud migration; deviation in federal preemption timing or data residency restriction tightening would shift deployment mix assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Voice Over Internet Protocol (Voip) Market
Data Center and Networking
Nosql Market
Data Center and Networking
Global Software Defined Networking (SDN) Market
Data Center and Networking
Global Cloud Content Delivery Network Market
Data Center and Networking
MPLS-Based Core Network Market
Data Center and Networking
Software Defined Networking (SDN) and Network Function Virtualization (NFV) Market
Data Center and Networking
South Africa Data Center Networking Market
Data Center and Networking
Software Defined Video Networking Market
Data Center and Networking
Europe Subscriber Data Management Market
Data Center and Networking
Data Warehousing Market
Data Center and Networking
Global Subscriber Data Management Market
Data Center and Networking
Belgium Data Center Networking Market
Data Center and Networking
5G Edge Cloud Network and Services Market
Data Center and Networking
Converged Data Platform Market
Data Center and Networking
Europe Data Center Interconnect Market
Data Center and Networking
Data Center Networks Market