
 Middle East Data Center Networking Market | 2026-2036
Middle East Data Center Networking Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Data Center Networking Market Insights
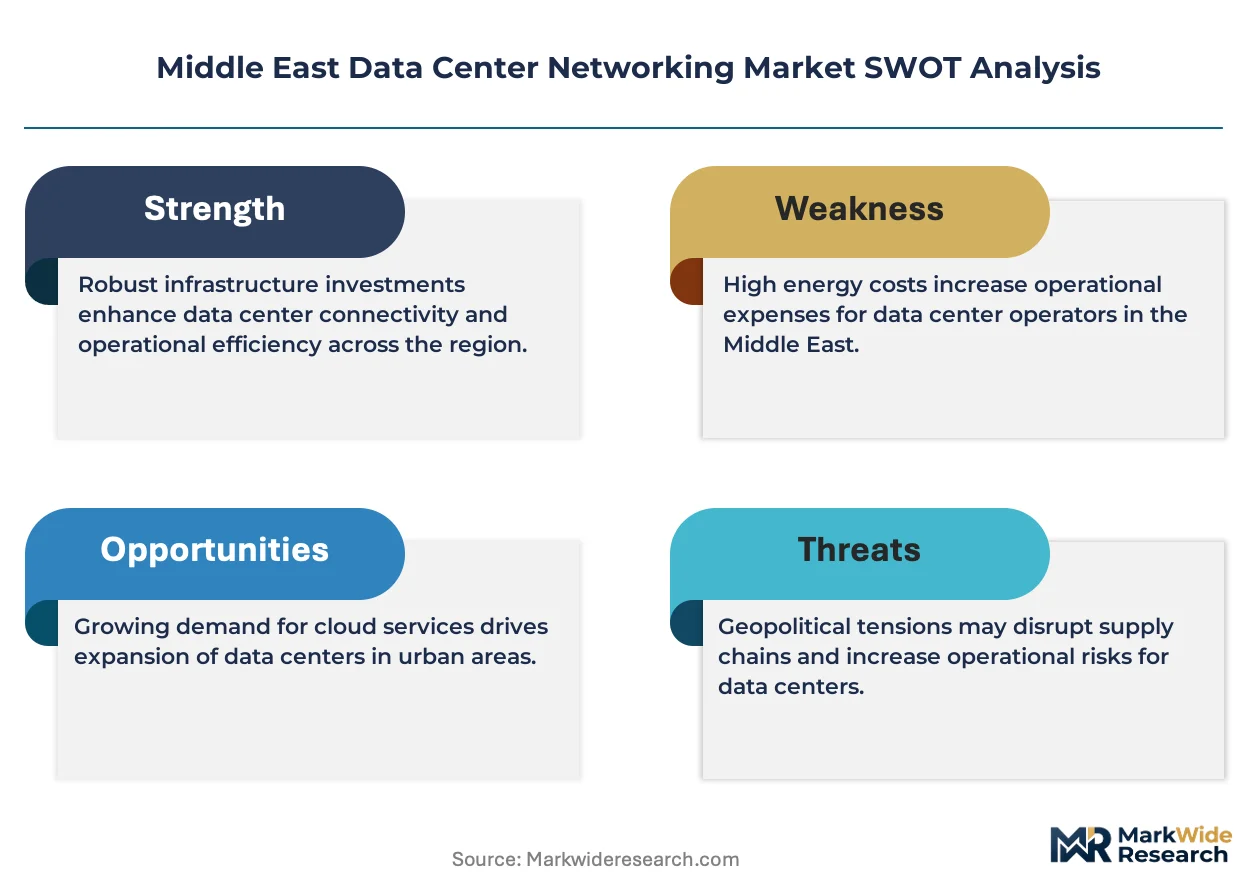
Project finance and sovereign wealth-backed leasing structures is tilting competitive dynamics toward capital-heavy entrants. Cisco Systems Inc. leverages its installed base of enterprise routing gear to anchor multi-year managed service contracts across Gulf state enterprises. Huawei Technologies Co. Ltd. sustains price-competitive bids on full-stack switching and optical transport through vendor financing arrangements tied to state-backed digital transformation programs.
Middle East data center networking comprises the switching, routing, security, and interconnect fabric that enables compute and storage resource communication within and between facilities, typically operating at speeds from 10 Gbps to 400 Gbps with sub-microsecond latency requirements for high-frequency trading and AI workloads. The primary commercial purpose is to guarantee deterministic packet delivery, traffic segmentation, and east-west bandwidth scaling as tenant density rises. Ethernet switching dominates current procurement cycles, while InfiniBand is capturing AI training cluster interconnects where remote direct memory access reduces GPU idle time. On-premises deployment retains share among defense and financial institutions with sovereign data obligations, though hybrid models are absorbing mid-market enterprises seeking burst capacity without full cloud migration.
The UAE's Telecommunications and Digital Government Regulatory Authority and Saudi Arabia's Communications, Space and Technology Commission both enforce data classification and cross-border transfer rules that dictate physical network topology and encryption standards. BIS-equivalent conformity assessment for networking equipment imports adds certification cost and timeline risk for non-domestic vendors. Stakeholders must weigh sovereign cloud mandates against the operational complexity of maintaining parallel network fabrics for regulated and unregulated workloads.
Market Dynamics
Sovereign data mandates across Gulf Cooperation Council states are forcing network architects to redesign physical topologies, bifurcating infrastructure between regulated and unregulated workloads while compliance costs compress margin structures for multinational operators.
Growth Catalysts
- Saudi Arabia's Personal Data Protection Law:Localization requirements compel hyperscale facility construction, driving demand for 400 Gbps spine-leaf architectures in Riyadh and Jeddah.
- AI training clusters:GPU-intensive workloads require InfiniBand interconnects with sub-microsecond latency, creating specialized procurement cycles separate from general-purpose Ethernet switching.
- UAE-Saudi digital hub rivalry:Both countries are accelerating sovereign cloud investments, generating redundant capacity buildouts that expand aggregate networking equipment demand.
Market Restraints
- Optical component supply concentration:Dependence on East Asian coherent DSP and transceiver manufacturing creates 26-32 week lead times for 800 Gbps-ready line cards.
- BIS-equivalent certification requirements:Equipment import approval processes in Saudi Arabia and the UAE add 4-6 month timeline risks for non-domestic vendors.
- Copper and rare earth price volatility:Switch chassis and cable assembly costs fluctuate with commodity markets, constraining fixed-price contract viability.
Strategic Opportunities
- Kuwait and Qatar underpenetration:Both markets lack hyperscale presence relative to UAE and Saudi Arabia, creating first-mover advantages for early facility networking contracts.
- Edge computing convergence with 5G:MEC nodes require distributed switching fabrics that interconnect radio access networks with metro data centers.
- Green data center mandates:Saudi Arabia's renewable energy targets for digital infrastructure create demand for low-power Ethernet PHY and liquid-cooled rack networking.
Industry Challenges
- InfiniBand-Ethernet skill bifurcation:GPU cluster networking requires specialized RDMA engineering talent scarce across Gulf engineering labor markets.
- Parallel fabric maintenance:Operators must simultaneously manage sovereign-compliant encrypted networks and standard cloud interconnects, doubling operational complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Data Center Networking Market |
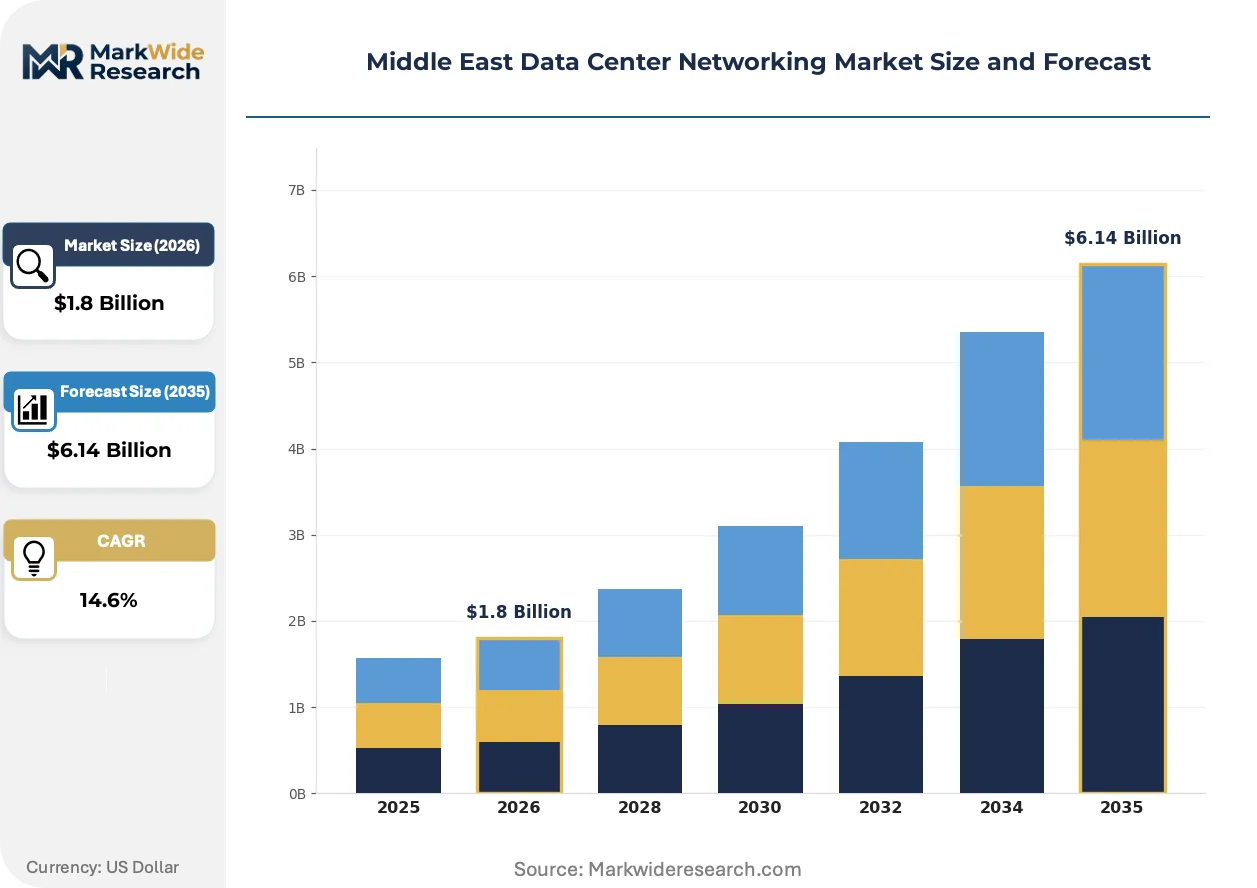
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Switches, Routers, Firewalls, Load Balancers Technology: Ethernet, Fiber Channel, InfiniBand, Wireless End User: Telecommunication, Government, BFSI, Healthcare Deployment Model: On-Premises, Cloud, Hybrid, Managed Services |
| Companies Covered | Huawei Technologies Co. Ltd., Cisco Systems Inc., F5 Networks Inc., Juniper Networks Inc., NEC Corporation, VMware Inc., A10 Networks Inc., Extreme Networks Inc., Hewlett Packard Enterprise Development LP, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Data Center Networking Market Trends and Innovations
Networking architectures across Middle East facilities are pivoting from generic bandwidth provisioning toward workload-specific deterministic performance, with AI training demands forcing protocol diversification beyond traditional Ethernet dominance.
Silicon photonics co-packaged optics is rendering obsolete pluggable transceiver architectures in high-density AI clusters. Saudi Aramco and UAE-based cloud operators are adopting 51.2 Tbps switch silicon with embedded optics to reduce power-per-bit by 30 percent. This compression of optical-electrical conversion layers is rendering obsolete legacy chassis designs that relied on front-panel pluggability.
The UAE's Telecommunications and Digital Government Regulatory Authority has tightened data classification enforcement, requiring physical network segmentation for critical national infrastructure workloads. This policy is fragmenting procurement patterns, with defense and financial institutions now mandating air-gapped switching fabrics separate from commercial cloud interconnects. Equipment vendors are responding with dual-product strategies: standard SKUs for commercial tenants and hardened variants for regulated verticals.
Leasing structures are displacing capital purchase models for core networking gear. STC, Etisalat, and Mobily now offer network-as-a-service arrangements where switching infrastructure remains vendor-owned and refreshed on 36-month cycles. This shift transfers obsolescence risk from enterprise IT to carrier balance sheets, with the model most advanced in Dubai Internet City and Riyadh's King Abdullah Financial District.
Middle East Data Center Networking Market Segmentation
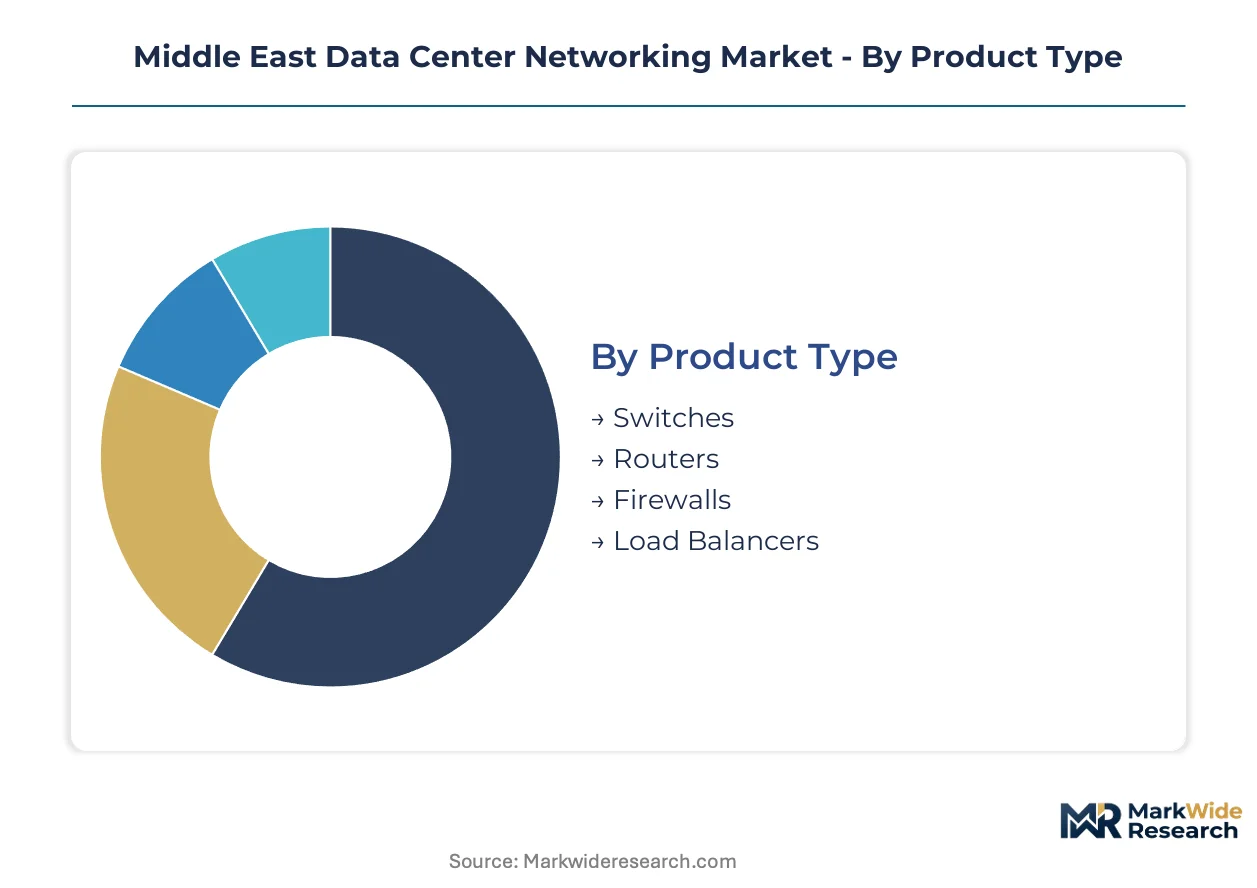
Segmentation reveals how workload specialization and regulatory fragmentation are splitting procurement patterns across Middle East facilities. Product categories diverge sharply between AI training clusters and sovereign-compliant enterprise deployments.
Product Type:
Mature switching hardware dominates installed base revenue while emerging security and traffic management layers capture incremental spend.
- Switches:Spine-leaf architectures at 100-400 Gbps form the backbone of hyperscale facilities in Riyadh and Dubai. Demand concentrates among cloud service providers scaling GPU clusters where east-west bandwidth requirements exceed 50 Tbps per pod.
- Routers:Border gateway and core aggregation platforms handle inter-facility traffic across UAE-Saudi digital corridors. Financial institutions in King Abdullah Financial District drive procurement for low-latency deterministic routing between primary and disaster recovery sites.
- Firewalls:Next-generation platforms with TLS inspection capabilities address data classification mandates from Saudi Arabia's Communications, Space and Technology Commission.
- Load Balancers:Application delivery controllers distribute traffic across containerized microservices in Kubernetes-orchestrated environments.
Switches retain volume leadership; load balancers hold the steepest expansion curve.
Technology:
Cost tier stratification separates commodity Ethernet from premium interconnect protocols purpose-built for latency-sensitive workloads.
- Ethernet:Dominates general-purpose traffic with 25-400 Gbps interfaces standard in commercial cloud deployments. UAE-based operators favor merchant silicon switches for cost efficiency in multi-tenant colocation facilities.
- InfiniBand:Remote direct memory access enables sub-microsecond GPU-to-GPU communication essential for Saudi Aramco's AI training infrastructure. Procurement runs through specialized system integrators with NVIDIA-certified engineering staff.
- Fiber Channel:Persists in legacy storage area networks serving healthcare and government verticals with block storage requirements.
- Wireless:Wi-Fi 6E and private 5G support edge device onboarding and out-of-band management access.
Ethernet commands the largest installed base; InfiniBand is climbing the fastest among emerging protocols.
End User:
Application intensity varies dramatically across verticals, with financial services and cloud infrastructure driving the most sophisticated networking requirements.
- Telecommunication:STC, Etisalat, and Mobily operate national backbone networks requiring carrier-grade routing with five-nines availability. These operators are expanding into network-as-a-service offerings that bundle switching infrastructure with managed connectivity.
- Government:Defense and critical national infrastructure mandates from the UAE's Telecommunications and Digital Government Regulatory Authority require physically segmented air-gapped networks. Procurement favors domestically certified vendors with local assembly capabilities.
- BFSI:Banks in Dubai International Financial Centre and Riyadh deploy redundant fabrics for real-time payment settlement systems.
- Healthcare:Hospital networks prioritize segmentation for medical device isolation and patient data protection.
Telecommunication captures the deepest vertical integration; government exhibits the most rapid policy-driven expansion.
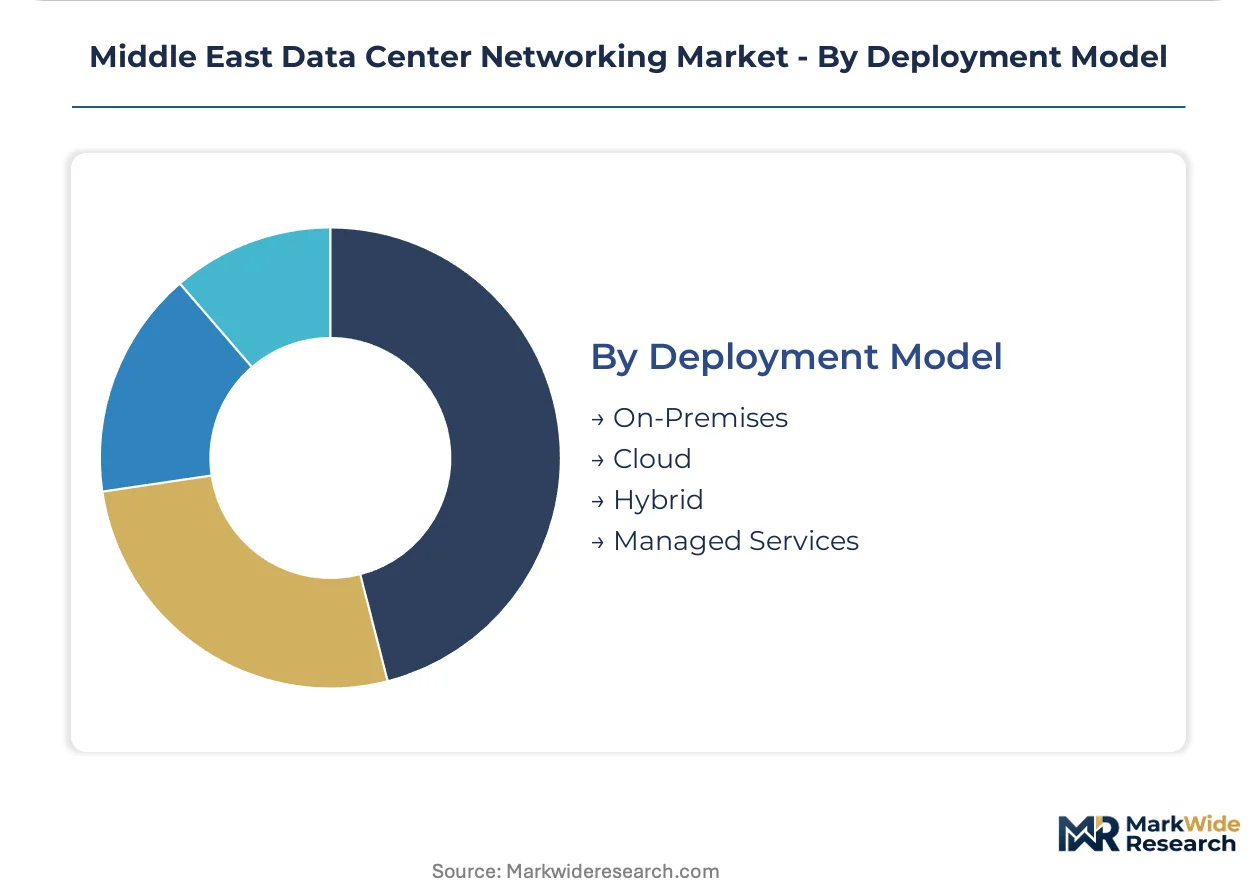
Deployment Model:
Customer type and operational maturity determine whether organizations own infrastructure or consume it as operational expenditure.
- On-Premises:Defense contractors and sovereign wealth funds maintain captive data centers with fully owned switching hardware. These deployments emphasize long asset lifecycles and extensive customization.
- Cloud:Hyperscale operators consume merchant silicon at massive scale, refreshing spine layers every 18-24 months to capture bandwidth density improvements.
- Hybrid:Mid-market enterprises in Qatar and Kuwait connect on-premises workloads to burst capacity in UAE facilities without full migration.
- Managed Services:Carrier-operated network-as-a-service transfers refresh risk from enterprise balance sheets to STC and Etisalat.
On-premises retains the largest revenue footprint; managed services is gaining share fastest among emerging consumption models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud service providers and sovereign wealth funds drive procurement across Gulf Cooperation Council states, with hyperscale facility investments concentrating in jurisdictions offering regulatory clarity and energy cost advantages.
United Arab Emirates
Dubai Internet City and Masdar City host the region's densest concentration of carrier-neutral facilities. The Telecommunications and Digital Government Regulatory Authority enforces data classification rules that mandate physical network segmentation for critical national infrastructure. Abu Dhabi's financial free zones attract redundant fabric deployments for real-time payment systems.
Saudi Arabia
Riyadh and Jeddah anchor hyperscale construction responding to the Personal Data Protection Law's localization mandates. The Communications, Space and Technology Commission certifies networking equipment through BIS-equivalent conformity assessment. King Abdullah Financial District drives low-latency deterministic routing procurement between primary and disaster recovery sites.
Qatar
Qatar's sovereign wealth-backed digital infrastructure program lags UAE and Saudi deployment scale. The national communications regulator imposes data residency requirements without matching enforcement capacity. Lusail and Education City clusters present first-mover opportunities for early facility networking contracts.
Kuwait
Kuwait's data center market remains underpenetrated relative to Gulf peers despite comparable per-capita wealth. The Ministry of Communications oversees licensing without specialized data protection legislation. Suburban Kuwait City zones offer land and power for hyperscale development pending regulatory modernization.
Middle East Data Center Networking Market Competitive Landscape
Channel-controlling players compete with product-specialist players for positioning across sovereign cloud and commercial multi-tenant segments. The vendor base stratifies between full-stack infrastructure providers and component specialists focused on switching silicon or optical transport. Three archetypes dominate: state-backed integrated technology conglomerates, Western enterprise networking incumbents with managed service capabilities, and merchant silicon specialists supplying white-label hardware. Competitive moves center on vendor financing arrangements tied to national digital transformation programs and multi-year network-as-a-service leasing structures that transfer refresh risk to carrier balance sheets.
Among the state-backed integrated technology conglomerates, Huawei Technologies Co. Ltd. occupies a position exemplifying vendor financing leverage in sovereign cloud tenders. Cisco Systems Inc. and Juniper Networks Inc. represent the Western enterprise networking archetype, anchoring managed service relationships through installed base advantages in Gulf state enterprises. These three entities illustrate the competitive tension between price-competitive full-stack bids and premium-positioned service-led contracts.
| Leading Market Players |
|---|
| Huawei Technologies Co. Ltd. |
| Cisco Systems Inc. |
| F5 Networks Inc. |
| Juniper Networks Inc. |
| NEC Corporation |
| VMware Inc. |
| A10 Networks Inc. |
| Extreme Networks Inc. |
| Hewlett Packard Enterprise Development LP |
| Others |
Pricing and Supply Chain Analysis
East Asian coherent DSP and transceiver manufacturing clusters in Taiwan and South Korea constrain downstream pricing power for Middle East data center operators, with 800 Gbps-ready line card availability determining contract terms for Riyadh and Dubai hyperscale builds.
Pricing Analysis
Certification level creates the primary spread between commercial and sovereign-grade networking equipment. Three-tier pricing structure across hardened, enterprise, and merchant silicon levels reflects BIS-equivalent conformity assessment costs and local assembly requirements. Pricing pressure stems from copper and rare earth volatility affecting switch chassis and cable assembly costs. Cloud service providers exhibit highest price sensitivity through merchant silicon procurement, while defense contractors absorb premium positioning for air-gapped fabric variants.
Supply Chain Analysis
Silicon wafer fabrication draws from Taiwan, South Korea, and the United States, with merchant switch silicon and coherent optical components anchoring upstream dependencies. Rare earth elements for magnetic components and high-purity copper for cable assemblies constitute critical input exposures. Single-source vulnerability in coherent DSP manufacturing creates timeline risk for 800 Gbps deployments. Distribution runs through authorized distributors with local certification capabilities serving UAE and Saudi Arabian facility projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Network-as-a-service leasing structures are converting capital expenditure into recurring revenue streams, with interoperability between sovereign-compliant and commercial cloud fabrics emerging as the decisive ecosystem battleground.
For Market Incumbents: Build switching fabric refresh moats through multi-year managed service contracts anchored to STC and Etisalat network-as-a-service platforms. Deepen backward integration into optical transport layers to offset Huawei's vendor financing leverage in state-backed tenders. Counter merchant silicon commoditization with certification-locked hardened variants for defense and financial verticals. For New Entrants and Emerging Players: Establish a beachhead in Kuwait and Qatar's underpenetrated hyperscale segments before UAE-Saudi capacity saturation. Target edge computing convergence opportunities where 5G MEC nodes require distributed switching fabrics absent incumbent dominance. Pursue system integrator partnerships with NVIDIA-certified engineering capabilities to capture InfiniBand procurement cycles for Saudi Aramco GPU clusters. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among carrier-operated network-as-a-service providers with 36-month refresh obligations. Prioritize acquisition targets with sovereign certification pipelines and local assembly partnerships. Watch InfiniBand-Ethernet protocol bifurcation as signal for specialized RDMA engineering talent scarcity valuation inflections.| Strategic Initiative | Industry Significance |
|---|---|
| Network-as-a-Service Platform Launch | Transfers refresh risk from enterprise IT to STC and Etisalat balance sheets across Dubai Internet City. |
| Silicon Photonics Co-Packaging Investment | Reduces power-per-bit by 30 percent for Saudi Aramco AI training infrastructure deployments. |
| Sovereign Certification Partnership | Secures BIS-equivalent approval pathways for UAE Telecommunications and Digital Government Regulatory Authority compliance. |
| Edge Computing Fabric Expansion | Interconnects 5G MEC nodes with metro data centers in Lusail and Education City clusters. |
| InfiniBand Engineering Acquisition | Addresses RDMA talent scarcity for GPU cluster networking in King Abdullah Financial District. |
Research Methodology
Cross-validation between hyperscaler capex disclosures and carrier procurement records anchors the qualitative findings across this study. Primary interviews with data center operations directors, network architects at cloud service providers, procurement leads at sovereign wealth funds, and regulatory affairs specialists at the UAE Telecommunications and Digital Government Regulatory Authority combined with secondary validation from SEC filings, Communications Space and Technology Commission certification databases, and hyperscale facility development permits. Bottom-up equipment unit economics and top-down addressable market sizing were reconciled through iterative triangulation.
Calibration against historical deployment velocity across Riyadh and Dubai hyperscale clusters shaped the projection framework. Segmentation dimensions modeled include product type, technology protocol, end-user vertical, and deployment model across the analysis window. CAGRs were derived from equipment refresh cycle analysis and sovereign cloud investment trajectories. InfiniBand penetration rates for AI training clusters and network-as-a-service adoption curves constituted industry-specific forecast inputs.
Stress conditions across optical component lead times, rare earth price bands, and BIS-equivalent certification timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding sovereign data mandate enforcement intensity and hyperscale facility completion schedules. Cross-checking against Communications Space and Technology Commission equipment approval databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Europe Data Center Networking Market
Data Center and Networking
Nigeria Data Center Networking Market
Data Center and Networking
Mexico Data Center Networking Market
Data Center and Networking
Europe Data Center Market
Data Center and Networking
Global Enterprise Networking Market
Data Center and Networking
Hong Kong Data Center Networking Market
Data Center and Networking
Voice Over Internet Protocol (Voip) Market
Data Center and Networking
Global Network Operating Systems Market
Data Center and Networking
Japan Data Center Networking Market
Data Center and Networking
Germany Data Center Server Market
Data Center and Networking
Global Cloud Content Delivery Network Market
Data Center and Networking
Global Data Center Networking Market
Data Center and Networking
Dark Fiber Network Market
Data Center and Networking
Italy Data Center Networking Market
Data Center and Networking
Brazil Servers Market
Data Center and Networking
Computer Servers Market