
 Vietnam Data Center Networking Market | 2026-2036
Vietnam Data Center Networking Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Data Center Networking Market Insights
Build-operate-transfer and power purchase agreement financing is tilting competitive dynamics toward asset-light entrants with strong vendor relationships. Cisco Systems Inc. leverages its global certification programs to anchor enterprise loyalty among Vietnamese banks and telcos. Huawei Technologies Co. Ltd. competes aggressively on total cost of ownership for state-backed infrastructure projects. Viettel IDC sustains domestic advantage through sovereign data requirements and localized support capabilities.
Vietnam data center networking encompasses the switching, routing, security, and cabling infrastructure that interconnects compute and storage resources within and between facilities, typically operating at speeds from 10 Gbps to 400 Gbps with latency requirements under 1 millisecond for high-frequency trading and AI workloads. Ethernet dominates technology selection due to its interoperability and declining cost per port, while InfiniBand captures hyperscale AI training clusters where bandwidth aggregation matters most. Component demand concentrates in switches and routers where margin pools are deepest, though firewall spending is accelerating fastest as Vietnam's cybersecurity law tightens compliance requirements for critical data infrastructure.
Vietnam's Ministry of Information and Communications and the Cybersecurity Law shape product standards by mandating data localization and cross-border flow controls, forcing network architectures that segment domestic from international traffic. BIS-equivalent technical regulations and the country's national cybersecurity regulator enforce equipment certification that favors vendors with established local testing partnerships. Stakeholders must monitor how forthcoming data classification rules reshape hybrid deployment patterns and whether domestic colocation providers can secure financing for tier-three facility expansion before foreign operators capture the premium segment.
Market Dynamics
Hyperscale cloud operators are compressing procurement cycles and forcing legacy network architectures toward spine-leaf topologies that demand 400 Gbps port densities. This infrastructure refresh cycle is reshaping vendor qualification timelines and capital deployment patterns across Vietnamese facilities.
Growth Catalysts
- Cybersecurity Law data localization:Vietnam's Ministry of Information and Communications mandates domestic storage for critical data categories, forcing enterprises to build or lease local capacity rather than route traffic through Singapore or Hong Kong.
- AI training clusters:Hyperscale operators deploying GPU-intensive workloads in Ho Chi Minh City require InfiniBand and high-radix Ethernet fabrics that upgrade entire facility network tiers.
- State-backed digital infrastructure:Government cloud-first policies and smart city initiatives in Hanoi create guaranteed demand for sovereign-grade colocation with certified network segmentation.
Market Restraints
- Submarine cable concentration:Vietnam's international bandwidth depends on five primary cable systems landing at Vung Tau and Da Nang, creating single-point-of-failure exposure for cross-border data flows.
- Copper and optical component input costs:Switch ASICs and 400G transceivers face pricing volatility tied to Taiwan Semiconductor Manufacturing capacity allocation and rare earth processing bottlenecks.
- Equipment certification delays:BIS-equivalent technical regulations require extended local testing partnerships, extending vendor qualification timelines by six to twelve months versus regional peers.
Strategic Opportunities
- Central Highlands edge deployment:Latency-sensitive manufacturing automation in Binh Duong and Dong Nai provinces lacks local compute infrastructure, creating demand for micro data centers with distributed switching fabrics.
- Converged security-networking stacks:Firewall and zero-trust network access functions are virtualizing onto programmable switches, collapsing separate hardware procurement cycles into single-vendor relationships.
- Green data center incentives:Vietnam's national energy efficiency program offers tariff reductions for facilities achieving PUE below 1.4, rewarding liquid-cooled network equipment that reduces HVAC load.
Industry Challenges
- Network engineering talent scarcity:Domestic universities produce insufficient graduates with hands-on experience in BGP peering, EVPN-VXLAN deployment, and hyperscale automation tooling.
- Legacy mainframe integration:Vietnamese banks and state enterprises maintain decades-old core banking systems that resist API-native network architectures, forcing expensive gateway layers.
- Multi-vendor interoperability certification:Enterprises demand proof of seamless operation across Cisco, Huawei, and Arista equipment in hybrid environments, extending proof-of-concept timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Data Center Networking Market |
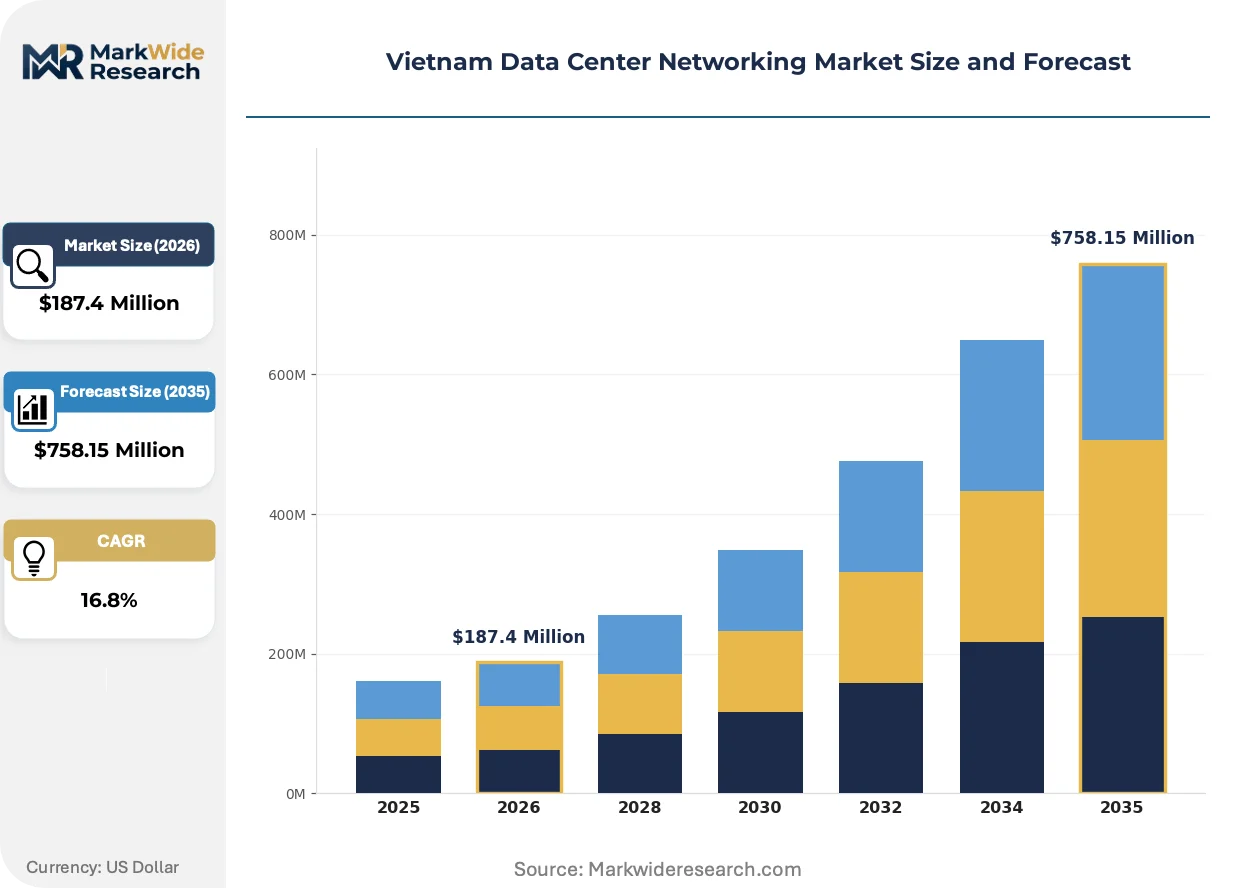
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $758.15 Million |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Ethernet, Fiber Channel, InfiniBand, IP Network Component: Switches, Routers, Firewalls, Cables End User: Telecommunications, BFSI, Healthcare, E-Commerce Deployment: On-Premises, Cloud-Based, Hybrid, Colocation |
| Companies Covered | Cisco Systems Inc., Huawei Technologies Co. Ltd., Hewlett Packard Enterprise, Arista Networks Inc., Dell Technologies Inc., Juniper Networks, Viettel IDC, VNPT, FPT Telecom, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Data Center Networking Market Trends and Innovations
Network function virtualization and software-defined fabrics are collapsing the traditional boundary between hardware switching and security enforcement. These architectural shifts are compressing vendor margins while opening new service revenue streams for operators who master programmable infrastructure.
Software-defined WAN edge platforms are virtualizing branch-to-data-center connectivity that previously required dedicated MPLS circuits and proprietary hardware appliances. Vietnamese conglomerates with distributed manufacturing sites are piloting these deployments to consolidate vendor relationships. The technology is virtualizing last-mile redundancy and traffic engineering functions that formerly demanded carrier-specific expertise.
Vietnam's Cybersecurity Law and forthcoming data classification rules are mandating network segmentation that isolates domestic traffic flows from international routes. Financial services and healthcare verticals face the strictest compliance timelines. Operators are responding by deploying policy-driven fabrics with automated traffic steering that satisfies audit requirements without manual rule maintenance.
Enterprise buyers are consolidating network and security procurement under single managed service contracts rather than maintaining separate hardware refresh cycles. Systems integrators with local Vietnamese engineering benches are displacing direct vendor relationships in mid-market accounts. This pattern is most visible among retail and logistics enterprises expanding e-commerce infrastructure ahead of peak seasonal demand.
Vietnam Data Center Networking Market Segmentation
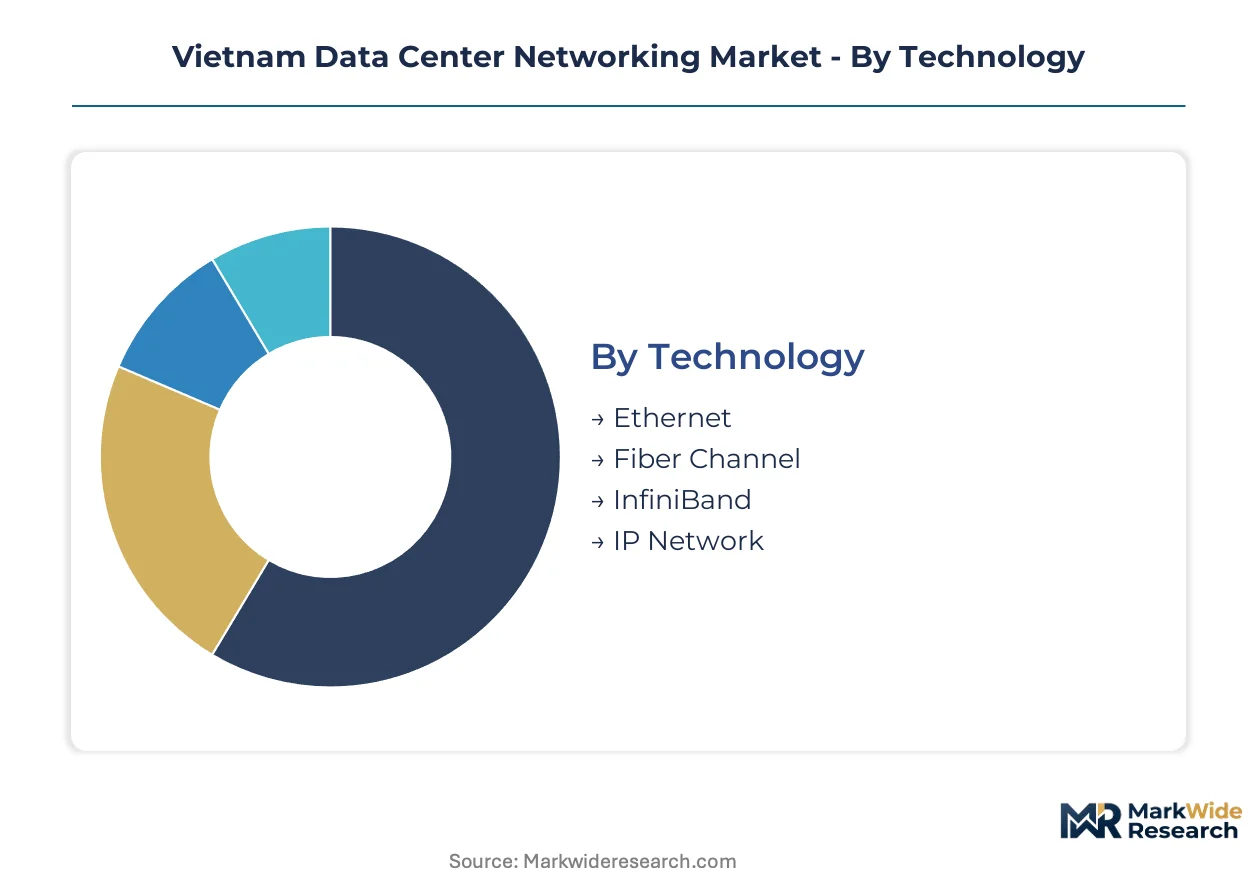
Network refresh cycles vary dramatically across technology layers in Vietnam's data center market. Understanding which segments compress procurement timelines versus which extend replacement windows shapes vendor strategy and capital allocation decisions.
Technology:
Ethernet turns over fastest at 18-24 month cycles driven by hyperscale bandwidth demands, while Fiber Channel persists longest due to storage array longevity in Vietnamese banking infrastructure.
- Ethernet:Dominates interconnect fabrics with speeds scaling from 25 Gbps to 400 Gbps. Demand concentrates in Ho Chi Minh City hyperscale facilities where spine-leaf architectures mandate high-radix switching. Cloud-first government policies accelerate refresh timelines beyond enterprise norms.
- InfiniBand:Captures GPU-intensive AI training clusters requiring sub-microsecond latency and 800 Gbps aggregate bandwidth. Viettel IDC and foreign operators deploying in Binh Duong province specify RDMA-capable fabrics for sovereign cloud infrastructure.
- Fiber Channel:Persists in legacy storage area networks at state-owned banks resisting full IP migration. Hanoi's core banking modernization programs represent the primary remaining demand pool.
- IP Network:Underlies software-defined overlays and BGP peering fabrics for internet exchange connectivity. Da Nang submarine cable landing stations drive specialized procurement for international gateway redundancy.
Ethernet dominates installed base. InfiniBand is where expansion concentrates.
Component:
Margin structures diverge sharply: switches and routers reward scale economies while firewalls command premium pricing from cybersecurity compliance mandates.
- Switches:Represent the deepest capital deployment layer with programmable ASICs enabling 400 Gbps port densities. Hyperscale operators in Ho Chi Minh City compress qualification timelines to match global procurement rhythms.
- Firewalls:Face steepest demand acceleration under Vietnam's Cybersecurity Law data localization requirements. Financial services verticals in Hanoi mandate next-generation inspection for cross-border traffic segmentation.
- Routers:Anchor internet exchange and WAN edge connectivity with carrier-grade reliability specifications. Viettel and VNPT backbone upgrades drive concentrated procurement cycles.
- Cables:Span copper DACs for intra-rack connectivity to single-mode fiber for inter-facility links. Central Highlands manufacturing automation projects create distributed demand for ruggedized outdoor-rated assemblies.
Switches anchor revenue volume. Firewalls are climbing the fastest.
End User:
Procurement sophistication separates telecommunications and BFSI buyers with dedicated network engineering teams from healthcare and e-commerce entrants relying on systems integrators.
- Telecommunications:Viettel, VNPT, and MobiFone operate captive data center networks with in-house peering expertise. 5G core deployment timelines synchronize infrastructure refresh across Hanoi and Ho Chi Minh City facilities.
- BFSI:State-owned banks maintain dual-vendor policies mandating Cisco-Huawei interoperability certification. Cybersecurity Law compliance deadlines force 12-month network segmentation projects.
- Healthcare:Hospital information systems migrate toward hybrid cloud with limited internal network engineering capacity. Ho Chi Minh City private hospital chains represent the most procurement-active segment.
- E-Commerce:Tiki, Shopee Vietnam, and Lazada logistics subsidiaries demand seasonal burst capacity with software-defined automation. Last-mile fulfillment center expansion in Dong Nai province drives edge networking procurement.
Telecommunications commands the largest absolute spend. E-commerce is gaining share fastest.
Deployment:
Ownership economics and compliance risk tolerance determine whether enterprises build, lease, or hybridize their network infrastructure.
- Colocation:Dominates enterprise adoption as domestic providers expand tier-three capacity in Hanoi and Ho Chi Minh City. Cross-connect pricing and inter-facility fiber availability shape vendor selection.
- Cloud-Based:Hyperscale operators deploy proprietary network fabrics with minimal external procurement. AWS, Azure, and Google Cloud local regions concentrate demand for InfiniBand and custom silicon.
- On-Premises:Persists in defense, critical infrastructure, and state security applications with sovereign data requirements. Legacy mainframe integration costs delay migration timelines.
- Hybrid:Emerges as the default architecture for regulated enterprises segmenting domestic and international traffic flows. Policy-driven automation tools collapse separate management planes.
Colocation captures the majority of third-party networking spend. Hybrid architectures show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud-first policies and data localization mandates across Southeast Asia are accelerating facility construction in metro clusters with submarine cable landing advantages. Vietnam's Ministry of Information and Communications anchors regional demand through sovereign data requirements that segment domestic from international traffic flows.
Ho Chi Minh City
Hyperscale operators deploying GPU-intensive AI training clusters drive 400 Gbps spine-leaf architecture demand. The city's Cybersecurity Law compliance deadlines force financial services verticals into 12-month network segmentation projects. Thu Duc City and District 7 concentrate tier-three colocation construction where Viettel IDC and foreign operators compete for sovereign cloud contracts.
Hanoi
State-owned bank core banking modernization sustains Fiber Channel demand while hybrid cloud migration accelerates Ethernet switching procurement. Government smart city initiatives create guaranteed demand for certified network segmentation. Cau Giay and Nam Tu Liem districts host the densest concentration of domestic colocation providers expanding tier-three capacity.
Da Nang
Submarine cable landing station proximity positions the city as Vietnam's primary international gateway redundancy hub. BIS-equivalent technical regulations enforce extended equipment certification timelines for vendors lacking local testing partnerships. The Hoa Vang district industrial zone attracts edge computing deployments serving Central Highlands manufacturing automation.
Binh Duong Province
Latency-sensitive manufacturing automation in Vietnam's industrial heartland lacks local compute infrastructure, creating demand for micro data centers with distributed switching fabrics. Japanese and South Korean electronics manufacturers drive private fiber deployment between production facilities and colocation points of presence. Thuan An and Di An cities anchor the province's data center networking procurement activity.
Dong Nai Province
E-commerce logistics subsidiaries demand seasonal burst capacity with software-defined automation for last-mile fulfillment center expansion. The province's proximity to Ho Chi Minh City enables hybrid architectures that segment domestic transaction processing from international cloud workloads. Bien Hoa and Long Thanh districts concentrate edge networking procurement serving Tiki, Shopee Vietnam, and Lazada infrastructure.
Vietnam Data Center Networking Market Competitive Landscape
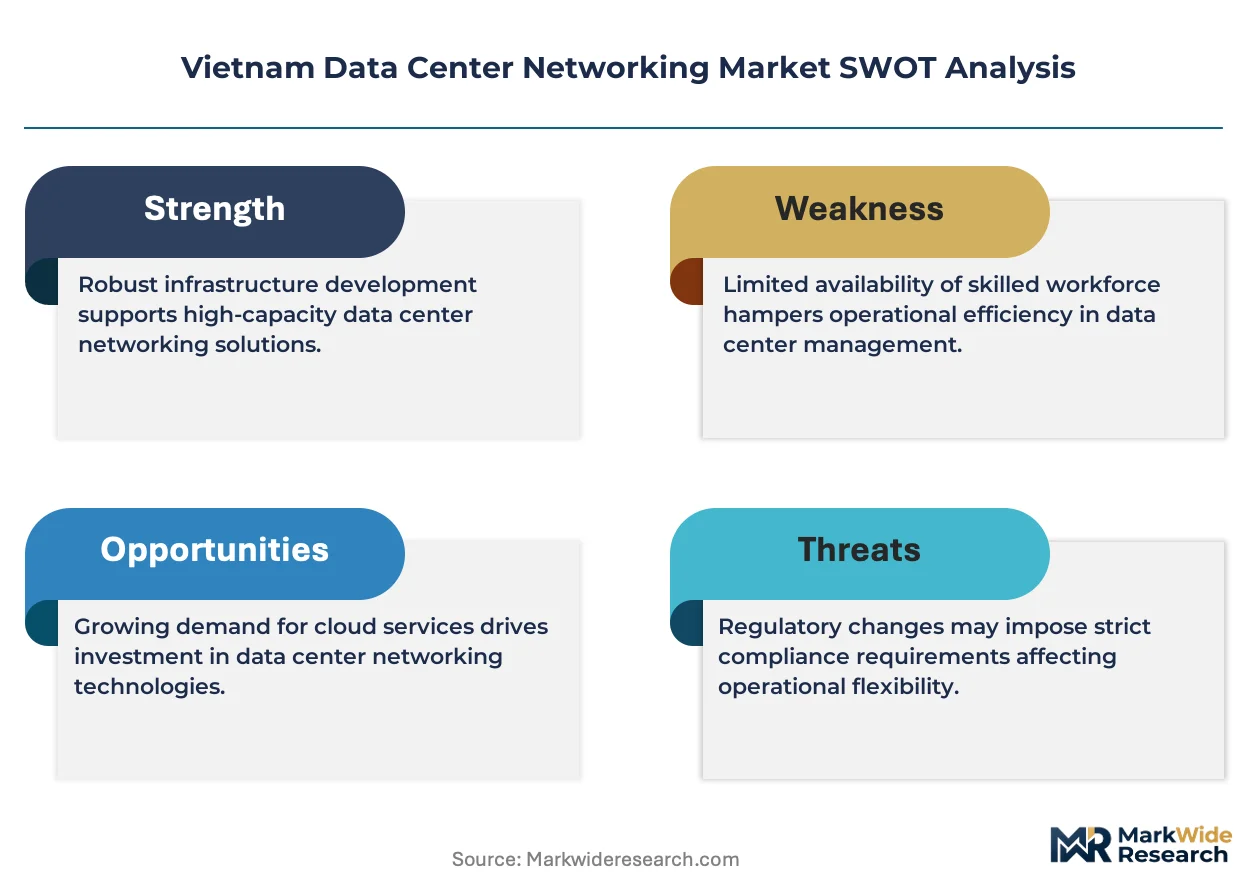
On the supply side, the industry is bifurcated between global networking equipment vendors with certification-heavy enterprise relationships and domestic operators leveraging sovereign data requirements. Three strategic archetypes dominate: hyperscale-optimized fabric specialists, compliance-anchored systems integrators, and carrier-captive infrastructure providers. Competitive intensity centers on vendor qualification timeline compression and localized support capability building rather than price-based rivalry.
Within the global equipment tier, Cisco Systems Inc. and Huawei Technologies Co. Ltd. represent opposing archetypes—one anchoring enterprise loyalty through certification ecosystems, the other competing on total cost of ownership for state-backed infrastructure. Viettel IDC occupies a distinct position as the domestic carrier-captive provider, converting sovereign data mandates into localized support advantages that foreign operators struggle to replicate.
| Leading Market Players |
|---|
| Cisco Systems Inc. |
| Huawei Technologies Co. Ltd. |
| Hewlett Packard Enterprise |
| Arista Networks Inc. |
| Dell Technologies Inc. |
| Juniper Networks |
| Viettel IDC |
| VNPT |
| FPT Telecom |
| Others |
Pricing and Supply Chain Analysis
Taiwan Semiconductor Manufacturing capacity allocation bottlenecks determine both pricing tier spreads across 400G transceiver grades and supply chain shape, compressing margins for vendors without direct foundry relationships while concentrating procurement power among hyperscale operators with volume guarantees.
Pricing Analysis
Certification level under Vietnam's BIS-equivalent technical regulations creates the primary spread between premium and standard tiers, with vendors bearing six-to-twelve-month local testing partnership costs passing through to enterprise buyers. Three-tier pricing structure across premium certified, standard compliant, and economy non-critical tiers separates state-owned bank procurement from e-commerce logistics subsidiaries. Cost compression in the economy tier is intensifying because hyperscale operators compress qualification timelines to match global procurement rhythms. E-commerce logistics subsidiaries show highest price sensitivity due to seasonal burst capacity demands, while state-owned banks prioritize certification compliance over unit cost.
Supply Chain Analysis
TSMC and Samsung Foundry hold captive capacity for switch ASICs and 400G transceiver silicon, with backend assembly concentrated in Malaysia and Thailand. Taiwan, South Korea, and Japan anchor optical component supply, while rare earth processing for laser diodes rests on Chinese refining capacity. Single-source vulnerability runs through submarine cable landing station equipment where five primary systems create concentration risk. Distribution runs through systems integrators with local Vietnamese engineering benches serving mid-market accounts, displacing direct vendor relationships in retail and logistics verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vietnam data center networking sits in early-cycle expansion as cloud-first government policies and Cybersecurity Law data localization mandates force enterprises to build domestic capacity rather than route traffic through Singapore or Hong Kong.
For Market Incumbents: Harden certification ecosystem moats by accelerating BIS-equivalent local testing partnership timelines to match hyperscale operator procurement rhythms. Defend against asset-light entrants with strong vendor relationships by deepening captive support capabilities in Hanoi and Ho Chi Minh City facilities. Prioritize sovereign-grade colocation certification investment as foreign operators capture premium segment share. For New Entrants and Emerging Players: Establish a beachhead in Central Highlands edge deployment serving latency-sensitive manufacturing automation in Binh Duong and Dong Nai provinces. Target micro data center distributed switching fabric demand where domestic providers lack localized compute infrastructure. Lead with converged security-networking stacks that collapse separate hardware procurement cycles into single-vendor relationships for manufacturing automation buyers. For Investors and Strategic Acquirers: Carrier-captive infrastructure providers with sovereign data mandate advantages present the strongest acquisition target archetype given Viettel IDC's demonstrated ability to convert compliance requirements into localized support leverage. Long-term viability hinges on whether domestic colocation providers can secure financing for tier-three facility expansion before foreign operators consolidate premium segment share. Watch hyperscale operator GPU cluster deployment announcements as inflection indicator for InfiniBand fabric demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Local Certification Partnership Investment | BIS-equivalent testing partnerships compress six-to-twelve-month vendor qualification timelines to match hyperscale procurement rhythms. |
| Central Highlands Edge Facility Buildout | Micro data center deployment in Binh Duong province captures latency-sensitive manufacturing automation demand. |
| Converged Security-Networking Stack Launch | Virtualized firewall and zero-trust functions on programmable switches collapse separate procurement cycles for mid-market retail and logistics buyers. |
| Liquid-Cooled Network Equipment Introduction | PUE below 1.4 achievement unlocks Vietnam national energy efficiency program tariff reductions for tier-three facilities. |
| Sovereign Cloud Interoperability Certification | Cisco-Huawei dual-vendor policy compliance opens state-owned bank network segmentation project procurement. |
Research Methodology
A spread of perspectives from data center network engineers, colocation procurement managers, systems integrator technical leads, and hyperscale operator infrastructure planners converged on the working assumptions shaping this analysis. Primary interviews with Viettel IDC architecture teams and foreign operator facility managers combined with secondary validation from Ministry of Information and Communications policy circulars, submarine cable landing station operator disclosures, and BIS-equivalent technical regulation filings. Bottom-up equipment procurement cycle analysis triangulated against top-down facility construction pipeline tracking across Ho Chi Minh City, Hanoi, and Da Nang metro clusters.
Demand-supply-balance framing anchored the analytical framework across the analysis window, modeling segmentation dimensions spanning technology layer, component category, end-user vertical sophistication, and deployment ownership structure. Hyperscale operator capex disclosure patterns and domestic carrier captive network upgrade timelines fed CAGR derivation for Ethernet switching and InfiniBand fabric demand trajectories. AI training cluster GPU deployment density assumptions and Cybersecurity Law compliance deadline phasing shaped scenario-weighted projections.
Sensitivities concentrate around Taiwan Semiconductor Manufacturing capacity allocation shifts, rare earth processing bottleneck resolution, and forthcoming data classification rule implementation timelines. Forecasts reflect assumptions on hyperscale operator commitment to Vietnam local region buildout and domestic colocation provider financing access for tier-three expansion. Quarterly review of submarine cable system outage frequency, BIS-equivalent certification queue depth, and hyperscale operator job postings for Ho Chi Minh City network engineering roles is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Global Virtual Private Network Market
Data Center and Networking
Data Deduplication Tools Market
Data Center and Networking
Global Network Operating Systems Market
Data Center and Networking
Global WAN Optimization Market
Data Center and Networking
Automotive Data Management Market
Data Center and Networking
South America Data Center Networking Market
Data Center and Networking
Global Data Management Platform Market
Data Center and Networking
Data Center Interconnect Market
Data Center and Networking
Mexico Data Center Networking Market
Data Center and Networking
Edge Server Market
Data Center and Networking
Europe Data Center Networking Market
Data Center and Networking
Data Deduplication Market
Data Center and Networking
DNA Digital Data Storage Market
Data Center and Networking
Global Data Warehouse Market
Data Center and Networking
Global Cloud Content Delivery Network Market
Data Center and Networking
US Dark Fiber Network Market