
 China Data Center Networking Market | 2026-2036
China Data Center Networking Market Size, Share, and Industry Trends Forecast 2026-2036
China Data Center Networking Market Insights
The China data center networking tier is pivoting on a widening gap between AI-optimized fabrics and standard enterprise interconnects. Cisco Systems Inc. dominates the premium segment through deep channel control across state-backed cloud builds. Arista Networks Inc. specializes in low-latency spine-leaf architectures for hyperscale facilities. Juniper Networks Inc. competes on routing intelligence for multi-tenant colocation environments.
China data center networking encompasses the switching, routing, cabling, and interface systems that interconnect compute, storage, and virtualization layers within facilities exceeding 5,000 square meters, typically operating at 100 Gbps port speeds with sub-500 nanosecond latency targets. Its primary purpose is to maintain deterministic packet flow across East-West traffic patterns generated by distributed workloads. Ethernet switching leads in volume terms due to its ubiquity across cloud service provider builds, while InfiniBand commands the fastest expansion trajectory tied to AI training cluster deployments. Edge deployment models now attract disproportionate capital allocation as latency-sensitive applications migrate outside core metros.
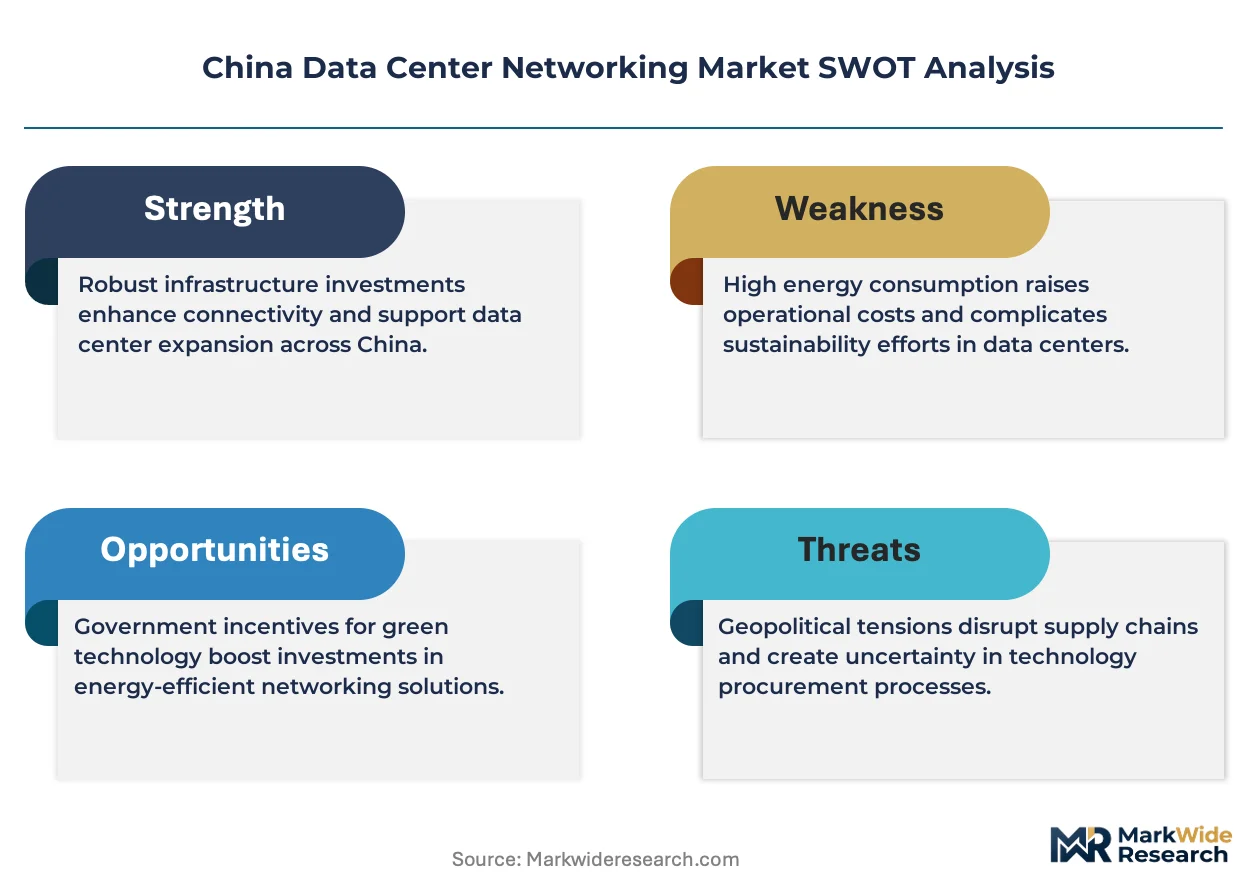
MIIT governs telecommunications equipment certification under GB standards, while NMPA-aligned cybersecurity review processes shape cross-border data flow architectures. SAMR enforces antitrust scrutiny on platform-affiliated infrastructure procurement, indirectly diversifying vendor selection pools. Stakeholders must track how dual carbon goals from MEE will rewrite power density specifications and cooling-network co-design requirements before the next planning cycle concludes.
Market Dynamics
AI training clusters are forcing a bifurcation between InfiniBand fabrics for GPU interconnect and Ethernet for general-purpose traffic, with MIIT's east-to-west computing mandate redistributing deployment geography across provincial boundaries.
Growth Catalysts
- MIIT east-to-west computing transfer:The policy redistributes data center construction toward western provinces with abundant renewable energy, expanding addressable floor space in Chengdu-Chongqing and Guizhou clusters.
- Hyperscale AI training demand:Cloud service providers are building 10,000+ GPU clusters that require spine-leaf architectures with sub-500 nanosecond latency targets.
- Dual carbon goals from MEE:Power density specifications are accelerating liquid cooling adoption, creating retrofit demand for networking equipment rated for immersion environments.
Market Restraints
- Advanced ASIC supply concentration:Merchant switch silicon fabrication concentrates at TSMC foundries, creating allocation risk for 7nm and 5nm networking chips during capacity constraints.
- GB standards certification timelines:MIIT telecommunications equipment approval processes extend 6-12 months for new 400G platforms, delaying product availability versus overseas markets.
- Copper interconnect substitution:Passive direct attach cables are displacing short-reach optical transceivers in rack-scale deployments, compressing component margins.
Strategic Opportunities
- Edge computing in tier-3 cities:Latency-sensitive manufacturing and autonomous vehicle infrastructure in Changsha, Hefei, and Xi'an remains underserved by high-bandwidth interconnect.
- Convergence of silicon photonics with co-packaged optics:This integration path reduces power per bit and enables 51.2Tbps switch capacity without front-panel pluggable congestion.
- State-backed cloud procurement diversification:SAMR antitrust scrutiny on platform-affiliated infrastructure is opening vendor selection pools beyond incumbent relationships.
Industry Challenges
- Optical transport engineering talent scarcity:The shortage of 400G/800G transceiver design specialists extends product development cycles and inflates compensation costs.
- Legacy three-tier architecture integration:Enterprises with existing core-aggregation-access deployments face forklift upgrade costs and operational retraining to adopt spine-leaf topologies.
- Cross-border data flow compliance architecture:NMPA-aligned cybersecurity review processes require segmented network designs that increase complexity for multinational operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Data Center Networking Market |
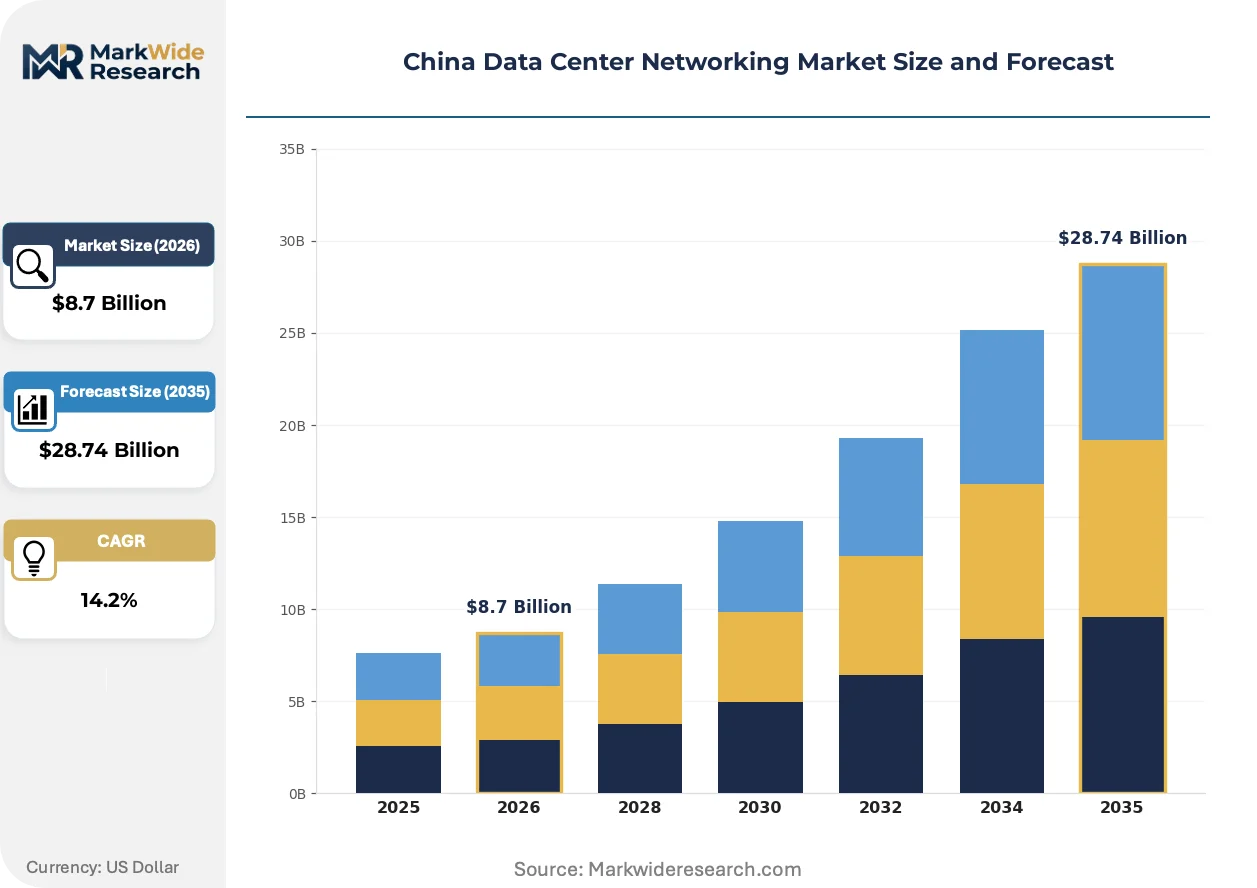
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Switches, Routers, Cables, Network Interface Cards End User: Telecom Providers, Cloud Service Providers, Enterprises, Government Technology: Ethernet, Fibre Channel, InfiniBand, MPLS Deployment Model: On-Premises, Colocation, Hybrid, Edge |
| Companies Covered | Cisco Systems Inc., Arista Networks Inc., Juniper Networks Inc., Dell EMC, IBM Corporation, Schneider Electric, Extreme Networks Inc., NEC Corporation, ALCATEL-LUCENT ENTERPRISE, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Data Center Networking Market Trends and Innovations
Silicon photonics and co-packaged optics are compressing power budgets while policy mandates reshape deployment geography. Buyers are restructuring procurement relationships to accommodate sovereign infrastructure requirements.
Co-packaged optics is integrating photonic engines directly onto switch ASIC substrates, eliminating pluggable transceiver power and latency overhead. Hyperscale facilities in the Greater Bay Area are piloting this technology for 800G links. The approach is integrating optical and electrical domains at the package level, enabling 51.2Tbps radix without front-panel thermal constraints.
MIIT's dual carbon goals are mandating power usage effectiveness ceilings and renewable energy quotas for new data center licenses. Operators must document cooling-network co-design and liquid cooling readiness in permit applications. Facilities in Inner Mongolia and Guizhou are responding fastest, leveraging existing clean energy surpluses to meet compliance timelines.
State-backed cloud providers are consolidating procurement through centralized infrastructure funds rather than individual business unit decisions. This concentration is compressing vendor negotiation cycles and favoring suppliers with GB certification breadth. The shift is most visible in state-owned enterprise migrations, where single-source framework agreements now cover three-year networking refresh cycles.
China Data Center Networking Market Segmentation
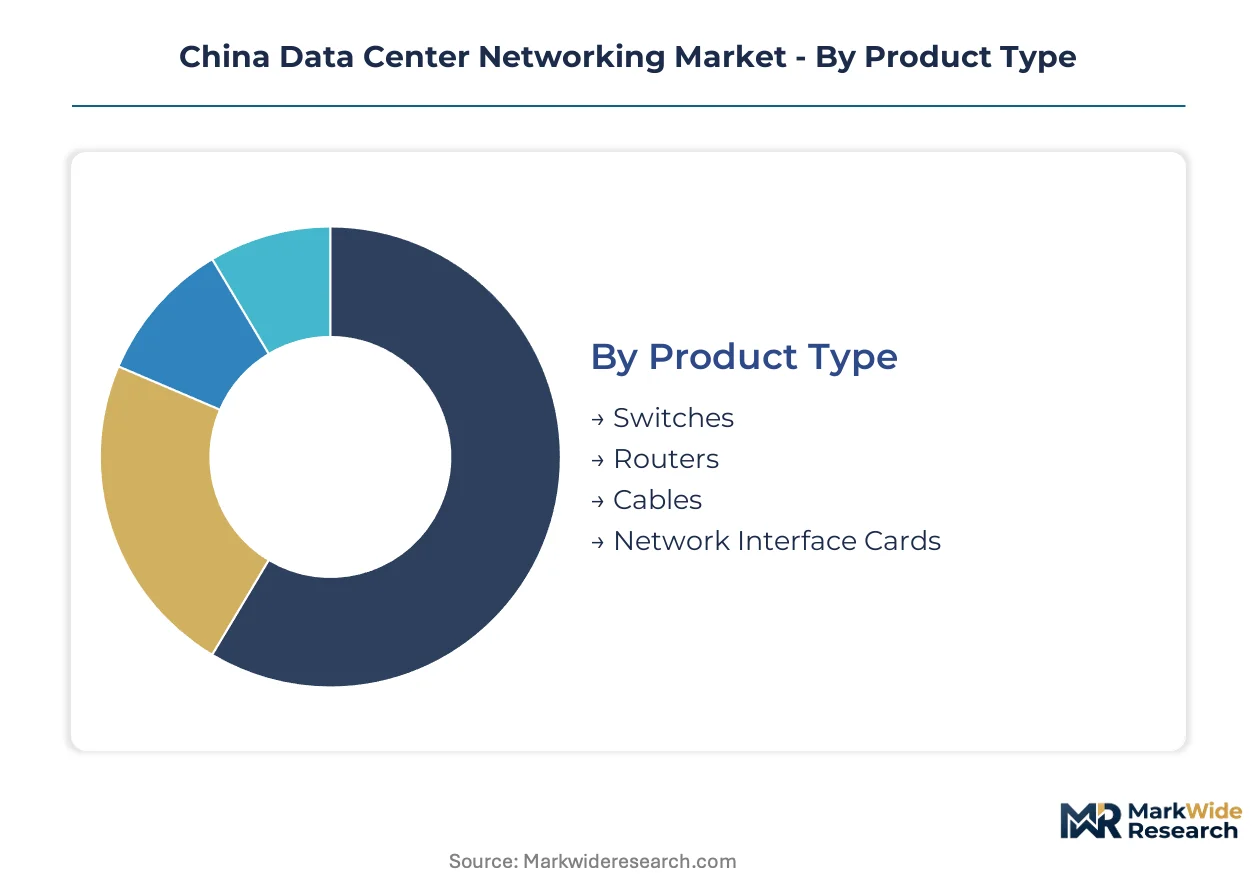
China data center networking procurement splits sharply between hyperscale cloud builds requiring spine-leaf fabrics and legacy enterprise three-tier architectures. MIIT's east-to-west computing mandate further fragments demand patterns across provincial clusters with divergent power and latency requirements.
Product Type:
Standardization dominates switches and routers through GB-certified SKUs, while cables and NICs fragment into application-specific configurations for AI training versus general-purpose workloads.
- Switches:Spine-leaf architectures at 400G/800G port speeds anchor hyperscale deployments. Demand concentrates in the Greater Bay Area cluster spanning Shenzhen, Guangzhou, and Hong Kong, driven by cloud service provider infrastructure expansion.
- Routers:Border gateway and core aggregation systems handle multi-tenant traffic segmentation. State-backed cloud providers in Beijing and Shanghai drive procurement, constrained by MIIT's 6-12 month GB certification timelines for new platforms.
- Cables:Passive direct attach copper and active optical assemblies interconnect rack-scale resources. Manufacturing automation in Changsha and Hefei creates localized demand for high-density fiber trunking.
- Network Interface Cards:SmartNICs and DPUs offload virtualization overhead from host CPUs. AI training clusters in Chengdu-Chongqing require RDMA-capable adapters for GPU interconnect.
Leading the category by volume: Switches. Growing fastest: Network Interface Cards.
End User:
Procurement concentration varies by capital source — state-backed entities consolidate through framework agreements while enterprises negotiate discrete purchases.
- Cloud Service Providers:Hyperscale operators deploy 10,000+ GPU clusters with sub-500 nanosecond latency targets. Builds concentrate in Guizhou and Inner Mongolia to satisfy MEE dual carbon compliance.
- Telecom Providers:State-owned carriers integrate data center networking with national backbone infrastructure. East-to-west computing mandates redirect investment toward western provincial clusters.
- Enterprises:Financial services and manufacturing firms migrate from legacy three-tier architectures. Forklift upgrade costs delay spine-leaf adoption outside tier-1 metros.
- Government:Sovereign cloud and smart city deployments require segmented network designs. NMPA-aligned cybersecurity reviews shape cross-border data flow architectures.
Cloud service providers command the largest capital allocation. Government procurement is climbing the fastest under digital infrastructure stimulus.
Technology:
Performance tier separates InfiniBand's premium positioning for AI workloads from Ethernet's volume dominance in general-purpose traffic.
- Ethernet:100G/400G switching ubiquity across cloud service provider builds. The Greater Bay Area cluster anchors deployment volume for spine-leaf fabrics.
- InfiniBand:GPU interconnect for AI training clusters with deterministic latency requirements. Hyperscale facilities pilot 800G links with co-packaged optics.
- Fibre Channel:Storage area networking persists in legacy enterprise environments. State-owned enterprise migrations in Beijing retain FC for SAN continuity.
- MPLS:Traffic engineering for multi-tenant colocation and telecom-integrated facilities. Carrier-neutral data centers in Shanghai deploy MPLS for tenant segmentation.
Ethernet leads by installed port volume. InfiniBand is gaining share fastest on AI training cluster expansion.
Deployment Model:
Geography and latency sensitivity determine model selection — core metros favor colocation while manufacturing hubs drive edge builds.
- Colocation:Multi-tenant facilities in Beijing and Shanghai offer carrier-neutral interconnection. SAMR antitrust scrutiny is diversifying vendor selection pools beyond platform-affiliated suppliers.
- On-Premises:Enterprise-owned facilities retain control over security architecture. Financial institutions in Shenzhen maintain captive data centers for regulatory compliance.
- Edge:Latency-sensitive manufacturing and autonomous vehicle infrastructure in Changsha, Hefei, and Xi'an. Tier-3 cities remain underserved by high-bandwidth interconnect.
- Hybrid:Workload portability between on-premises and colocation resources. State-backed cloud providers consolidate procurement through centralized infrastructure funds.
Colocation leads by revenue contribution. Edge deployment is expanding most quickly under latency-driven application migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Greater Bay Area cluster spanning Shenzhen, Guangzhou, and Hong Kong commands the densest concentration of data center networking deployment in China. This southern corridor anchors hyperscale cloud infrastructure builds with sub-500 nanosecond latency requirements. MIIT's east-to-west computing mandate is redistributing subsequent investment toward western provincial clusters.
Guangdong Province
Hyperscale operators deploy 10,000+ GPU clusters requiring spine-leaf architectures at 400G/800G port speeds. MIIT telecommunications equipment certification under GB standards governs all switching and routing platforms entering facilities. Shenzhen and Guangzhou host the bulk of cloud service provider infrastructure, with Hong Kong providing cross-border interconnection capacity.
Beijing-Tianjin-Hebei
State-backed cloud providers and government sovereign cloud deployments concentrate procurement through centralized infrastructure funds. SAMR antitrust scrutiny on platform-affiliated infrastructure is diversifying vendor selection pools beyond incumbent relationships. The Beijing metro anchors multi-tenant colocation facilities serving financial services and state-owned enterprise migrations.
Shanghai Yangtze River Delta
Carrier-neutral data centers deploy MPLS traffic engineering for multi-tenant segmentation and telecom-integrated facilities. NMPA-aligned cybersecurity review processes shape cross-border data flow architectures requiring segmented network designs. The Shanghai metro leads in financial institution captive data center maintenance for regulatory compliance.
Sichuan-Chongqing
AI training clusters drive demand for RDMA-capable Network Interface Cards and InfiniBand fabrics for GPU interconnect. MEE dual carbon goals mandate power usage effectiveness ceilings and renewable energy quotas for new data center licenses. Chengdu-Chongqing leverages abundant clean energy surpluses to attract east-to-west computing transfers.
Guizhou and Inner Mongolia
Western provincial clusters attract cloud service provider builds seeking MEE compliance through existing renewable energy infrastructure. Facilities document cooling-network co-design and liquid cooling readiness in permit applications. Guiyang and Hohhot respond fastest to MIIT's geographic redistribution mandate with purpose-built hyperscale campuses.
China Data Center Networking Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification depth and channel control dimensions in China data center networking. The vendor base organizes into three tiers: global networking incumbents with MIIT GB certification breadth, specialized low-latency fabric providers, and diversified IT infrastructure conglomerates. Dominant competitive moves include strategic partnerships with state-backed cloud procurement funds and portfolio diversification into liquid-cooled networking equipment.
Within the premium-tier vector, Cisco Systems Inc. and Arista Networks Inc. exemplify archetypes of deep channel control and specialized spine-leaf architectures respectively. Juniper Networks Inc. occupies a position representing routing intelligence specialization for multi-tenant environments. These three entities anchor the competitive structure without exhausting the vendor landscape.
| Leading Market Players |
|---|
| Cisco Systems Inc. |
| Arista Networks Inc. |
| Juniper Networks Inc. |
| Dell EMC |
| IBM Corporation |
| Schneider Electric |
| Extreme Networks Inc. |
| NEC Corporation |
| ALCATEL-LUCENT ENTERPRISE |
| Others |
Pricing and Supply Chain Analysis
Captive silicon sourcing from TSMC anchors the supply position and pricing power of merchant switch vendors, with GB certification requirements layering compliance premiums atop hardware costs. MIIT's equipment approval timelines compress margin flexibility for new 400G platform introductions.
Pricing Analysis
Throughput-based pricing anchors hyperscale procurement, with cloud service providers negotiating per-port costs tied to aggregate bandwidth commitments and latency guarantees. Pricing stratifies across InfiniBand premium tiers for AI training clusters, Ethernet standard tiers for general-purpose traffic, and copper interconnect economy tiers for rack-scale deployments. Cost compression in optical transceivers is intensifying because passive direct attach cables displace short-reach fiber in hyperscale builds. State-backed cloud providers exhibit lowest price sensitivity due to centralized infrastructure fund procurement, while tier-3 edge operators face acute budget constraints.
Supply Chain Analysis
Merchant switch silicon rests on Taiwanese foundry capacity, with advanced ASIC fabrication concentrating at TSMC's 7nm and 5nm nodes. Memory buffers and photonic engines draw from South Korean and Japanese specialty component suppliers. Single-source vulnerability at the foundry level creates allocation risk during capacity constraints. Distribution runs through state-backed cloud procurement funds and systems integrators holding MIIT certification breadth.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MIIT's GB standards certification operates as a cost-of-compliance moat, with 6-12 month approval timelines filtering out vendors lacking regulatory investment capacity. This barrier rewards incumbents with established certification pipelines.
For Market Incumbents: Hedge against copper interconnect substitution by diversifying into liquid-cooled networking equipment rated for immersion environments. Deepen channel control through exclusive framework agreements with state-backed cloud procurement funds to lock out emerging entrants. Prioritize R&D in co-packaged optics to defend margin position against commodity switch vendors. For New Entrants and Emerging Players: Tier-3 edge operators in Changsha, Hefei, and Xi'an represent the most penetrable buyer archetype, with latency-sensitive manufacturing and autonomous vehicle infrastructure remaining underserved by high-bandwidth interconnect. Target smart city deployments requiring segmented network designs under NMPA-aligned cybersecurity reviews. Pursue go-to-market partnerships with regional systems integrators holding existing MIIT relationships. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified IT infrastructure conglomerates seeking networking capability adjacencies. Long-term viability favors vendors with silicon photonics integration roadmaps and liquid cooling certification breadth. Watch for MIIT dual carbon enforcement tightening power density specifications as the inflection indicator for retrofit demand cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Co-packaged Optics Integration | Reduces power per bit and enables 51.2Tbps switch capacity for hyperscale facilities. |
| Liquid Cooling Certification | MEE dual carbon compliance mandates cooling-network co-design for new data center licenses. |
| GB Standards Pre-certification | MIIT telecommunications equipment approval timelines favor vendors with established pipelines. |
| Edge Computing Partnership | Tier-3 cities like Changsha and Hefei remain underserved by high-bandwidth interconnect infrastructure. |
| State Cloud Procurement Alignment | SAMR antitrust scrutiny opens vendor selection pools beyond platform-affiliated incumbent relationships. |
Research Methodology
SEC filings from hyperscale cloud providers, MIIT equipment certification databases, and customs import records formed the secondary backbone for volume and value estimation. Primary interviews with data center infrastructure directors, network engineering leads at state-backed cloud operators, procurement managers for telecom carriers, and technical directors at systems integrators validated segmentation assumptions. Bottom-up port shipment analysis triangulated against top-down capex disclosure tracking across the analysis window.
Historical trendline analysis of hyperscaler networking equipment spend informed the projection framework. Segmentation dimensions modeled include product type, end user archetype, technology protocol, and deployment geography across the projection horizon. CAGR derivation incorporated AI training cluster buildout trajectories, MIIT east-to-west computing transfer pace, and MEE dual carbon compliance enforcement intensity as industry-specific forecast inputs.
Revisions become necessary when TSMC foundry allocation constraints intensify, MIIT accelerates GB certification timeline compression, or copper interconnect substitution rates exceed baseline assumptions. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Netherlands Data Center Networking Market
Data Center and Networking
Saudi Arabia Data Center Server Market
Data Center and Networking
Spain Data Center Networking Market
Data Center and Networking
Brazil Servers Market
Data Center and Networking
Mobile Data Market
Data Center and Networking
Australia Data Center Networking Market
Data Center and Networking
Virtual Data Optimizer Market
Data Center and Networking
Europe Data Center Market
Data Center and Networking
Fog Networking Market
Data Center and Networking
Global Mobile Content Delivery Network Market
Data Center and Networking
Managed DNS Services Market
Data Center and Networking
Taiwan Data Center Networking Market
Data Center and Networking
Vietnam Data Center Networking Market
Data Center and Networking
Singapore Data Center Networking Market
Data Center and Networking
Global Cloud Content Delivery Network Market
Data Center and Networking
Service Provider Router Market