
 Global Enterprise Networking Market | 2026-2036
Global Enterprise Networking Market Size, Share, and Industry Trends Forecast 2026-2036
Global Enterprise Networking Market Foresight
The gap between premium cloud-native fabrics and commodity on-premise hardware is expanding in enterprise networking. Cisco Systems leverages its installed base to sustain high-margin recurring revenue through subscription software. Hewlett Packard Enterprise anchors its position in hybrid environments where customers straddle legacy and cloud infrastructure. Juniper Networks differentiates through AI-driven operations that reduce manual network management overhead.
Enterprise networking encompasses the hardware, software, and protocols that enable data exchange across organizational IT environments, typically operating at throughput rates from 1 Gbps to 400 Gbps in modern data center fabrics. Its primary purpose is ensuring reliable, secure connectivity for applications spanning on-premise servers, cloud services, and distributed edge locations. Switches and routers capture the largest installed base, though edge computing deployments represent the fastest structural expansion as latency-sensitive workloads proliferate. Cloud-based deployment models are displacing pure on-premise installations in mid-market accounts, while network security applications command premium pricing due to compliance complexity.
FCC spectrum allocations shape wireless access point deployment timelines in the United States, while the EU AI Act and GDPR impose data governance requirements on network analytics platforms processing European traffic. China's MIIT enforces domestic encryption standards that condition market access for foreign equipment suppliers. Stakeholders must weigh regulatory fragmentation against the operational cost of maintaining region-specific product certifications.
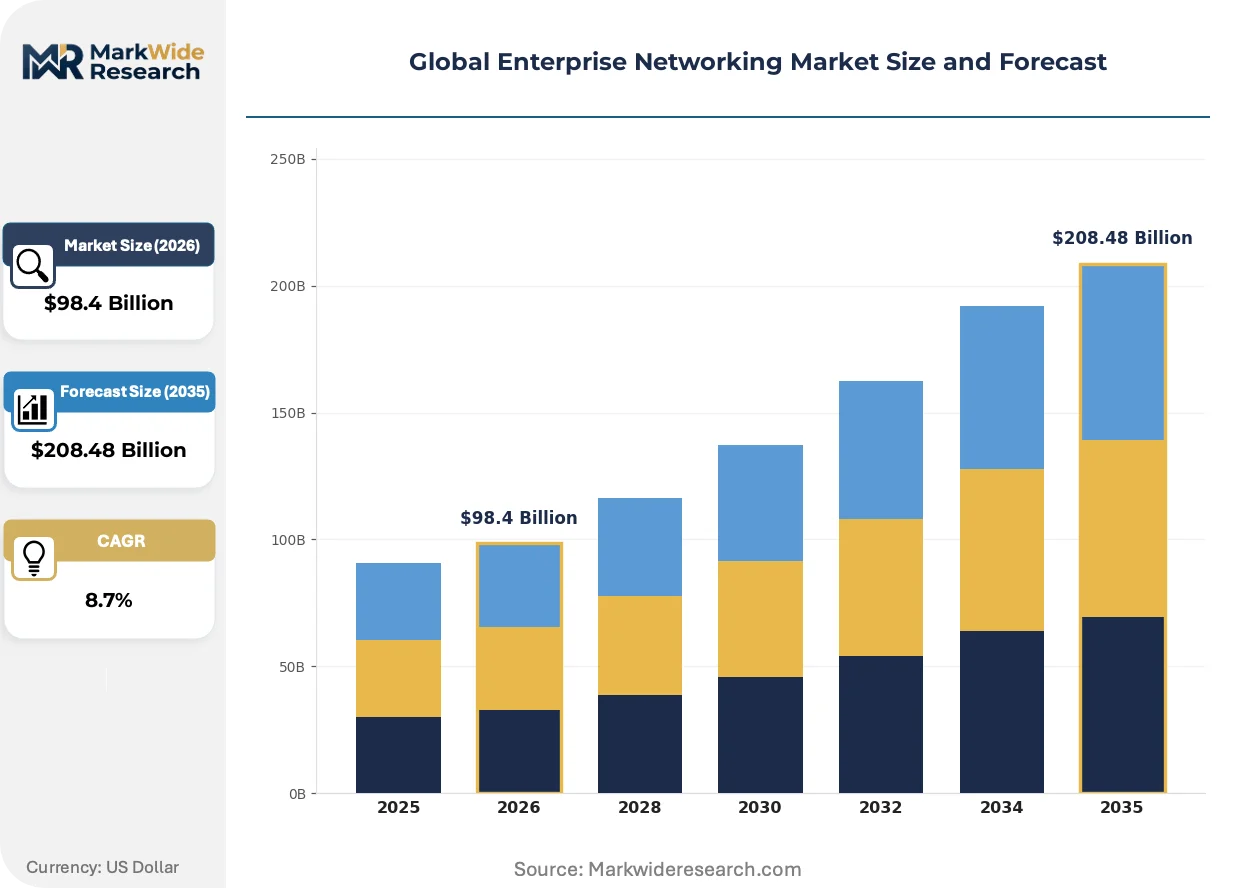
Market Dynamics
Zero-trust security architectures are forcing wholesale redesign of enterprise network topologies as financial institutions and critical infrastructure operators dismantle implicit trust models. This structural shift compresses refresh cycles for perimeter-based hardware while expanding addressable market for identity-aware microsegmentation platforms.
Growth Catalysts
- EU NIS2 Directive:The directive mandates binding cybersecurity standards for essential and important entities across member states. Network security vendors capture expanded procurement windows as compliance deadlines tighten through 2025.
- AI-driven operations:Machine learning platforms for predictive network maintenance reduce mean-time-to-resolution. Enterprise IT teams adopt these tools to offset staffing constraints in hybrid cloud environments.
- Germany's industrial corridor:Manufacturing automation and Industry 4.0 deployments concentrate demand for deterministic low-latency networking. Automotive and precision engineering facilities drive 400 Gbps fabric upgrades.
Market Restraints
- Semiconductor supply concentration:Advanced switching ASICs depend on Taiwan-based foundry capacity. Geopolitical friction threatens delivery timelines for next-generation data center hardware.
- Legacy protocol fragmentation:IPv4 exhaustion and uneven IPv6 adoption create interoperability friction. Enterprises maintain dual-stack configurations that inflate operational complexity.
- Qualified security architect scarcity:Zero-trust implementation demands cross-functional expertise spanning identity management, cloud architecture, and threat modeling. Talent gaps extend deployment timelines.
Strategic Opportunities
- India's digital infrastructure buildout:Data localization requirements under TRAI guidelines and RBI directives drive demand for sovereign cloud networking. Domestic enterprises and multinational subsidiaries require compliant on-premise and edge deployments.
- Private 5G convergence:Integration of cellular radio access with existing Ethernet fabrics enables unified management for industrial campuses. Mining, ports, and logistics operators pilot these converged architectures.
- FCC CBRS spectrum liberalization:Mid-band access enables enterprise-controlled wireless without carrier dependency. Manufacturing and warehousing verticals deploy private cellular for mobility-sensitive automation.
Industry Challenges
- Multi-cloud orchestration complexity:Enterprises operate across AWS, Azure, and Google Cloud with inconsistent networking abstractions. Network teams struggle to enforce unified policy across disparate control planes.
- Encryption performance bottlenecks:TLS 1.3 and post-quantum cryptography algorithms consume switch forwarding capacity. Hardware refresh cycles accelerate to maintain application throughput under full payload inspection.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Enterprise Networking Market |
| Market Size in 2026 | $98.4 Billion |
| Market Size in 2035 | $208.48 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Switches, Routers, Firewalls, Access Points, Network Interface Cards Deployment: On-Premise, Cloud-Based, Hybrid, Edge Computing Application: Data Center Connectivity, Unified Communications, Network Security, Remote Connectivity End User: Telecommunication Providers, Financial Institutions, Government Agencies, Educational Institutions |
| Companies Covered | Cisco Systems, Hewlett Packard Enterprise, Juniper Networks, Arista Networks, Broadcom, Huawei Technologies, Dell Technologies, Fortinet, Extreme Networks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Enterprise Networking Market Shifts & Advancements
Intent-based networking systems are replacing manual configuration workflows across enterprise data centers. Automation platforms now interpret business policies and translate them into device-level commands without CLI intervention.
Silicon photonics is consolidating optical and electronic switching functions onto single substrates. Hyperscale data center operators adopt co-packaged optics to reduce power consumption per bit. This integration is compressing the traditional transceiver supply chain and shifting value capture toward switch vendors with in-house photonics capabilities.
The EU AI Act imposes risk classification requirements on network analytics platforms processing European traffic. Vendors must document training data provenance and algorithmic transparency for systems performing automated threat detection. Financial services and healthcare networks in Germany, France, and the Netherlands face the steepest compliance curves as supervisory authorities begin enforcement.
Enterprise buyers now demand consumption-based licensing for campus and branch networking. Hardware vendors respond with as-a-service portfolios that bundle equipment, software, and managed operations. This model is most advanced in the United States where IT outsourcing maturity supports operational expenditure treatment of network infrastructure.
Global Enterprise Networking Market Segmentation
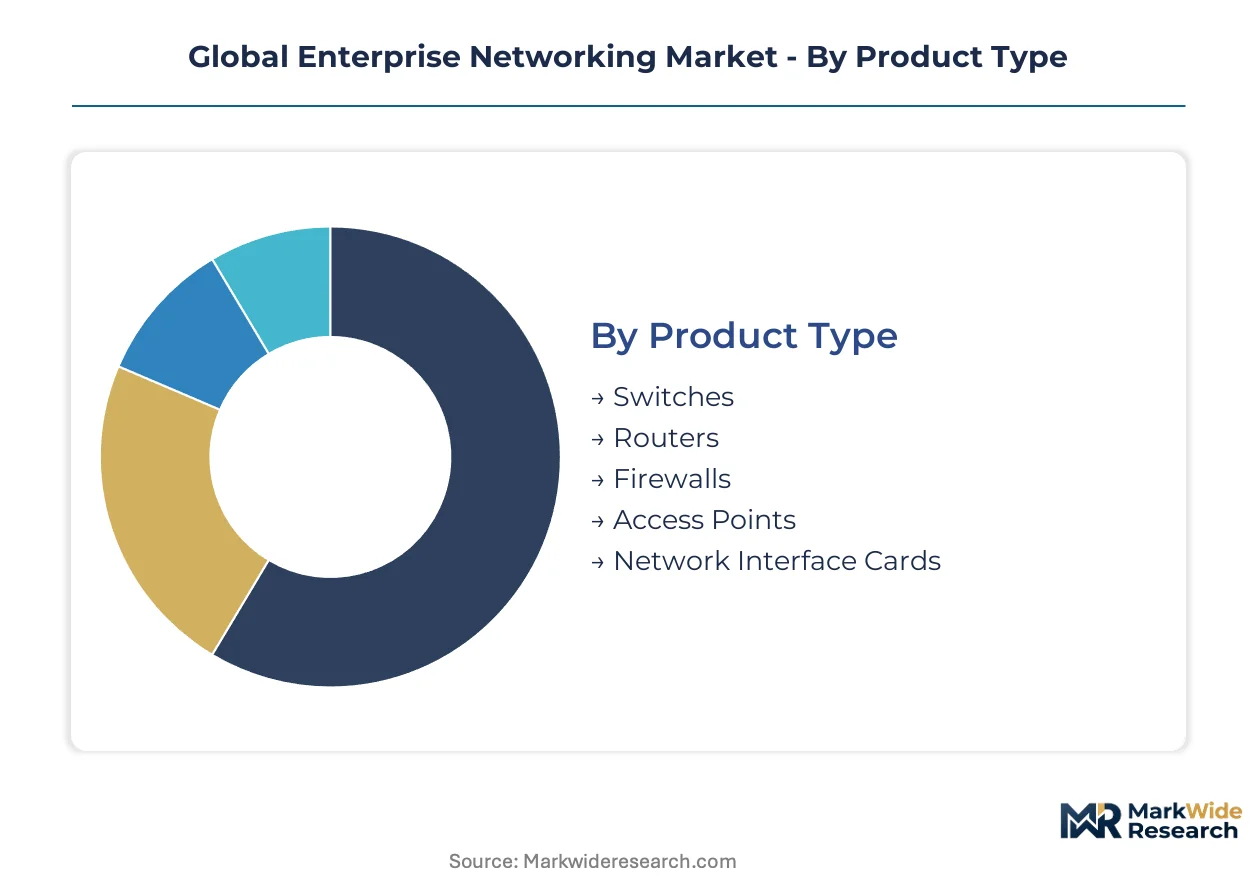
Enterprise networking procurement patterns diverge sharply across infrastructure layers. Product categories reflect distinct semiconductor dependencies, while deployment models track organizational cloud maturity. Application focus and end-user verticals determine pricing tolerance and compliance requirements.
Product Type:
Supply concentration in advanced switching ASICs and specialized security processors shapes vendor margins and delivery timelines across hardware categories.
- Switches:Ethernet switches from 1 Gbps access layer to 400 Gbps spine fabrics dominate capital expenditure. German automotive plants and hyperscale data centers in the United States drive demand for high-density 400 Gbps deployments to support AI training clusters.
- Routers:Carrier-grade and enterprise edge routers handle inter-site traffic engineering and WAN optimization. Telecommunication providers in India and Brazil upgrade core networks to manage 5G backhaul and sovereign cloud traffic under data localization mandates.
- Firewalls:Next-generation appliances with deep packet inspection and zero-trust enforcement command premium pricing. EU NIS2 compliance deadlines accelerate replacement of legacy perimeter devices.
- Access Points:Wi-Fi 6E and Wi-Fi 7 radios with 6 GHz support enable high-density wireless coverage. FCC spectrum allocations determine deployment velocity in US enterprise campuses.
- Network Interface Cards:SmartNICs and DPUs offload virtualization and security processing from host CPUs. Cloud service providers and financial exchanges adopt these for latency-sensitive workloads.
Switches absorb the bulk of installed capacity; Network Interface Cards are expanding most quickly as computational offload demands intensify.
Deployment:
Cost tier differentiation separates capital-intensive ownership models from operational expenditure alternatives that transfer hardware risk to vendors.
- On-Premise:Traditional data center builds with customer-owned hardware retain dominance in regulated sectors. Banks in Switzerland and government agencies in Japan maintain sovereign infrastructure for data residency compliance.
- Cloud-Based:Fully managed network-as-a-service offerings eliminate hardware procurement cycles. Mid-market enterprises in the United Kingdom and Australia adopt these to redirect IT staffing toward application development.
- Hybrid:Split architectures connect owned facilities with cloud-hosted control planes. Manufacturing conglomerates in Germany operate this model to preserve OT network isolation while leveraging cloud analytics.
- Edge Computing:Distributed micro data centers process latency-critical workloads close to source. Mining operations in Australia and autonomous logistics hubs in Singapore deploy converged edge networking for real-time decisioning.
On-Premise retains the largest installed base; Edge Computing is climbing the fastest as IoT and AI inference workloads proliferate.
Application:
Volume concentration in data center interconnect contrasts with security applications where compliance complexity sustains pricing power.
- Data Center Connectivity:Spine-leaf architectures and software-defined fabrics unify compute and storage networks. Hyperscale operators in the United States and co-location providers in the Netherlands drive 400 Gbps upgrade cycles.
- Unified Communications:Converged voice, video, and messaging platforms demand deterministic QoS policies. Healthcare systems in Canada and professional services firms in France prioritize these deployments for distributed workforce coordination.
- Network Security:Zero-trust segmentation and encrypted traffic inspection protect lateral movement paths. Financial institutions face the steepest compliance curves under EU DORA and US SEC cybersecurity rules.
- Remote Connectivity:SD-WAN and SASE architectures extend corporate policy to distributed endpoints. Professional services and media companies with nomadic workforces represent primary demand.
Data Center Connectivity commands the greatest capital allocation; Network Security is gaining share fastest as regulatory pressure intensifies.
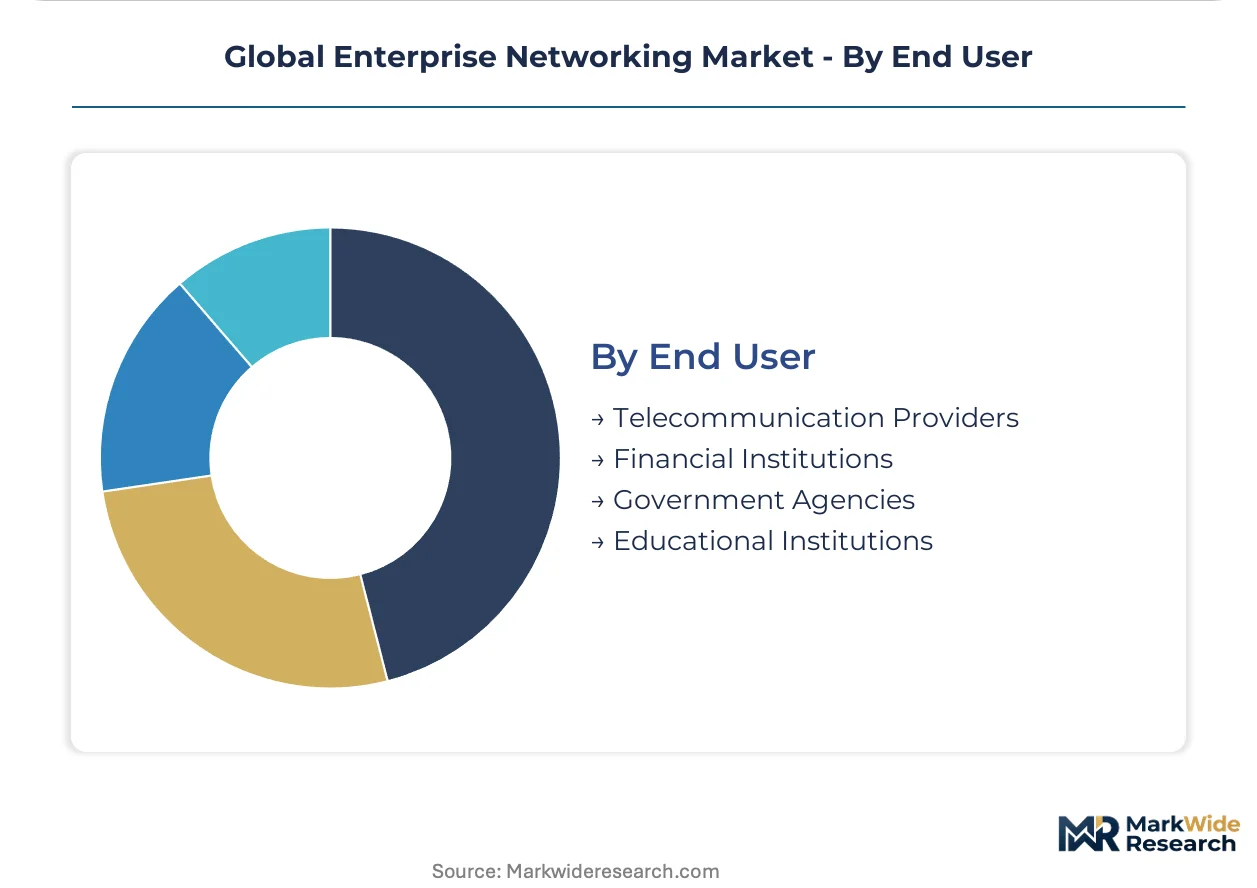
End User:
Customer type determines procurement sophistication, with telecommunication providers demanding carrier-grade reliability and financial institutions prioritizing compliance certification.
- Telecommunication Providers:National carriers and mobile operators build core and access networks serving millions of subscribers. India's TRAI-mandated infrastructure investments and Brazil's 5G spectrum obligations drive sustained equipment demand.
- Financial Institutions:Banks, insurers, and payment processors operate under stringent operational resilience mandates. EU NIS2 and US SEC disclosure rules compress refresh cycles for perimeter and core networking.
- Government Agencies:Defense, civilian, and intelligence entities require TEMPEST-rated and domestically sourced equipment. Classification levels and foreign ownership restrictions fragment procurement pools.
- Educational Institutions:Universities and K-12 districts balance coverage expansion against constrained capital budgets. E-rate funding in the United States and national digital education programs in South Korea shape purchasing patterns.
Telecommunication Providers represent the deepest installed base; Financial Institutions are expanding most quickly as zero-trust mandates take hold.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's industrial corridor from Stuttgart to Munich concentrates the densest concentration of 400 Gbps fabric deployments for automotive and precision engineering automation.
United States
FCC spectrum allocations for 6 GHz Wi-Fi and CBRS private cellular accelerate wireless infrastructure refresh cycles. The SEC's cybersecurity disclosure rules compress upgrade timelines for publicly traded enterprises. Silicon Valley hyperscale operators and Wall Street financial institutions drive spine-leaf architecture investments for AI training clusters.
Germany
EU NIS2 Directive compliance deadlines force zero-trust redesigns across banking and manufacturing networks. The national automotive sector mandates deterministic low-latency networking for Industry 4.0 production lines. Bavarian precision engineering facilities anchor 400 Gbps upgrade demand in the Munich-Stuttgart corridor.
China
MIIT domestic encryption standards condition market access for foreign equipment suppliers. Data localization requirements under national cybersecurity law drive sovereign cloud networking buildouts. Yangtze River Delta manufacturing hubs deploy converged edge architectures for real-time quality control systems.
India
TRAI data localization guidelines and RBI directives mandate on-premise infrastructure for financial services. 5G spectrum obligations require core network upgrades at national carriers. Mumbai and Bengaluru technology corridors concentrate demand for hybrid cloud networking among multinational subsidiaries.
United Kingdom
NCSC cyber assessment frameworks elevate procurement standards for critical national infrastructure operators. Mid-market enterprises adopt network-as-a-service models to redirect IT staffing toward application development. London financial services and Manchester media clusters drive SD-WAN deployments for distributed workforces.
Global Enterprise Networking Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the enterprise networking supply base. Switch silicon foundry capacity concentrates among Taiwan-based manufacturers while systems vendors operate fabless or hybrid models. Three strategic archetypes dominate: integrated platform vendors with installed base leverage, pure-play disruptors with cloud-native architectures, and component suppliers capturing value through merchant silicon. Consolidation pressure intensifies as scale requirements for AI-optimized hardware favor portfolio breadth over point solutions.
Within the integrated platform tier, Cisco Systems and Hewlett Packard Enterprise exemplify vendors leveraging subscription software to sustain recurring revenue from legacy hardware footprints. Juniper Networks occupies a position among AI-driven operations specialists reducing manual network management overhead. These three represent contrasting approaches to hybrid cloud environments where customers straddle on-premise and cloud infrastructure.
| Leading Market Players |
|---|
| Cisco Systems |
| Hewlett Packard Enterprise |
| Juniper Networks |
| Arista Networks |
| Broadcom |
| Huawei Technologies |
| Dell Technologies |
| Fortinet |
| Extreme Networks |
| Others |
Supply & Pricing Matrix
Hyperscale cloud operators and sovereign data center builders dominate procurement volumes, anchoring enterprise networking pricing to subscription-based consumption models that bundle hardware, software, and managed operations. This buyer concentration shifts vendor revenue toward recurring streams while compressing upfront capital expenditure recognition.
Pricing Analysis
Value-based pricing anchored to network uptime guarantees and throughput commitments commands premium positioning in financial services and healthcare verticals. Three-tier pricing structure across premium, standard, and economy levels separates AI-optimized 400 Gbps fabrics from commodity access-layer switches. Cost compression in mid-market campus equipment is intensifying because cloud-native competitors displace legacy hardware refresh cycles. Small and medium enterprises exhibit the highest price sensitivity, while telecommunication providers prioritize carrier-grade reliability over unit cost.
Supply Chain Analysis
Engineering talent shortages in Taiwan and South Korea constrain foundry capacity expansion for advanced switching ASICs. Manufacturing concentration centers on Taiwan for merchant silicon, China for optical transceiver assembly, and Mexico for final systems integration. Raw material dependencies span gallium arsenide substrates, specialized photonics packaging, and rare earth elements for magnetics. Single-source vulnerability in Taiwan-based 5nm and 3nm wafer production threatens delivery timelines for next-generation data center hardware. Distribution runs through authorized value-added resellers and direct hyperscale contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enterprise networking is consolidating around vendors with captive silicon design capabilities, as AI-optimized hardware demands force pure-play software entrants toward acquisition or exit. Scale requirements for 400 Gbps fabric development eliminate sub-billion-dollar revenue competitors.
For Market Incumbents: Deploy subscription software layers to capture recurring revenue from installed base hardware. Backward integration into merchant silicon design secures supply priority during foundry allocation constraints. Cisco Systems and Arista Networks exemplify this playbook. Threats include cloud-native disruptors offering network-as-a-service without capital expenditure requirements. For New Entrants and Emerging Players: Cloud-managed wireless platforms offer the lowest barrier to entry for channel-focused entrants. India's sovereign cloud buildout under TRAI guidelines presents the most penetrable geography for compliant edge networking solutions. Target mid-market manufacturing verticals in Germany's industrial corridor through channel partnerships with systems integrators. For Investors and Strategic Acquirers: The window for entry favors AI-operations software specialists with proven reduction in mean-time-to-resolution metrics. Long-term viability rests on differentiation in hybrid cloud orchestration as multi-environment complexity deepens. Watch hyperscaler capex allocation shifts as the inflection signal for demand acceleration or contraction.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Photonics Integration | Co-packaged optics reduce power consumption per bit for hyperscale operators in United States and Netherlands. |
| Zero-Trust Architecture Certification | EU NIS2 compliance deadlines accelerate replacement cycles for legacy perimeter firewalls across German banking networks. |
| Private 5G Convergence | Unified cellular-Ethernet management captures mining and logistics operators in Australia and Singapore. |
| Intent-Based Networking Platform | Policy-to-configuration automation addresses qualified security architect scarcity extending deployment timelines. |
| Edge Computing Micro Data Center | Distributed inference processing serves autonomous logistics hubs requiring sub-10 millisecond latency in Singapore. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with data center infrastructure executives, network operations directors, hyperscale procurement officers, and channel partner principals combined with secondary validation from FCC spectrum allocation records, EU NIS2 implementation guidance, SEC cybersecurity disclosure filings, and Taiwan Semiconductor Industry Association capacity reports. Bottom-up equipment shipment modeling and top-down IT spending allocation triangulated market sizing across the analysis window.
Granularity-level modeling tracked deployment mode, product category, and end-user vertical at country-level resolution. CAGRs derived from regression against macro IT capital expenditure indicators and segment-specific adoption curves. Forecast inputs incorporated AI training cluster buildout schedules, EU NIS2 compliance deadline phasing, and private 5G spectrum liberalization timelines.
The model holds under stable foundry capacity allocation and gradual IPv6 migration; deviation in Taiwan geopolitical friction or accelerated post-quantum cryptography mandates would shift equipment refresh assumptions. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Software Defined Networking (SDN) and Network Function Virtualization (NFV) Market
Data Center and Networking
Graph Database Market
Data Center and Networking
Data Center Interconnect Market
Data Center and Networking
Global WAN Optimization Market
Data Center and Networking
Japan Data Center Networking Market
Data Center and Networking
Europe Data Center Interconnect Market
Data Center and Networking
Spain Data Center Networking Market
Data Center and Networking
Global Subscriber Data Management Market
Data Center and Networking
Global Data Management Platform Market
Data Center and Networking
Global Storage Area Network (SAN) Switches Market
Data Center and Networking
Global Virtual Private Server Market
Data Center and Networking
Vietnam Data Center Server Market
Data Center and Networking
Denmark Data Center Networking Market
Data Center and Networking
United States Data Center Networking Market
Data Center and Networking
North America Subscriber Data Management Market
Data Center and Networking
Saudi Arabia Data Center Server Market