
 Smart Sprinkler Controller Market | 2026-2036
Smart Sprinkler Controller Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Sprinkler Controller Market Analytics
A capital-intensity divergence between cloud-platform investments and basic timer hardware is bifurcating competitive tiers in the smart sprinkler controller space. Rain Bird Corporation leverages its legacy irrigation infrastructure to sustain channel dominance across commercial properties and agricultural distributors. Rachio, Inc. competes through software-centric differentiation, anchoring its position in direct-to-consumer online retail where mobile application integration drives replacement cycles.
A smart sprinkler controller is an electromechanical device that modulates valve actuation based on real-time soil moisture, weather forecast API feeds, and evapotranspiration algorithms, typically operating at 24 VAC output to interface with standard irrigation solenoids. Its primary commercial purpose is to minimize water waste while maintaining turf and crop health through zone-specific scheduling automation. Wi-Fi controllers occupy the largest installed base due to backward compatibility with existing residential wiring, though multi-protocol controllers that unify Bluetooth mesh with cloud backhaul represent the fastest-growing margin pool as commercial properties demand redundant connectivity. Sensor technology segments lead in agricultural deployments where soil volumetric water content probes justify hardware costs through yield protection.
EPA WaterSense specifications and the EU Green Deal's water efficiency directives shape product certification requirements, with California's Model Water Efficient Landscape Ordinance mandating smart controller compatibility for new commercial developments above specified irrigated areas. The Federal Communications Commission regulates radio frequency emissions for wireless irrigation hardware, creating compliance barriers for unlicensed spectrum devices. Stakeholders must monitor evolving municipal rebate eligibility criteria as drought declarations expand geographically, since program qualification increasingly requires cloud-based water usage reporting that excludes basic timer-only systems.
Market Dynamics
EPA WaterSense certification mandates and California's Model Water Efficient Landscape Ordinance are compressing replacement cycles for legacy timer hardware while elevating cloud-connected controllers to default specification status in new commercial developments.
Growth Catalysts
- Soil Sensor Integration:Volumetric water content probes are penetrating agricultural deployments where yield protection justifies hardware costs. California almond and grape growers deploy zone-specific moisture monitoring to optimize deficit irrigation protocols.
- Municipal Rebate Programs:Drought declarations in Texas and Arizona have expanded rebate eligibility to require cloud-based water usage reporting, excluding basic timer-only systems from qualification.
- Evapotranspiration Algorithms:Real-time weather API feeds are automating schedule adjustments that previously demanded manual intervention, reducing residential water waste by an estimated 15-30% in pilot programs.
Market Restraints
- Copper and Semiconductor Input Costs:24 VAC transformer components and Wi-Fi radio modules face price volatility from concentrated Asian foundry capacity, compressing margins on entry-tier hardware.
- Legacy Solenoid Compatibility:Standard 24 VAC output interfaces limit voltage optimization opportunities, forcing redundant power conversion stages that add BOM cost without performance differentiation.
- Unlicensed Spectrum Congestion:FCC Part 15 restrictions on 2.4 GHz device density create connectivity failures in dense multi-zone commercial installations, driving demand for wired backhaul that undermines wireless convenience value propositions.
Strategic Opportunities
- Bluetooth Mesh Convergence:Multi-protocol controllers unifying short-range mesh with cellular backhaul address redundant connectivity demands from golf courses and corporate campuses in water-stressed Sun Belt states.
- EU Green Deal Alignment:Water efficiency directives are creating certification pathways for North American manufacturers seeking European commercial landscape contracts, particularly in Mediterranean climate zones.
- Insurance Risk Models:Property casualty underwriters in wildfire-prone California counties are incorporating smart irrigation compliance into premium calculations, creating channel partnerships with homeowner associations.
Industry Challenges
- API Standardization Delays:Proprietary weather data feeds from competing cloud platforms prevent interoperability, forcing installers to maintain multiple mobile applications and fragmenting customer support workflows.
- Electrical Contractor Skill Gaps:Low-voltage irrigation wiring expertise concentrates among legacy landscape specialists, while residential electricians lack training in valve troubleshooting and soil sensor calibration protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Sprinkler Controller Market |
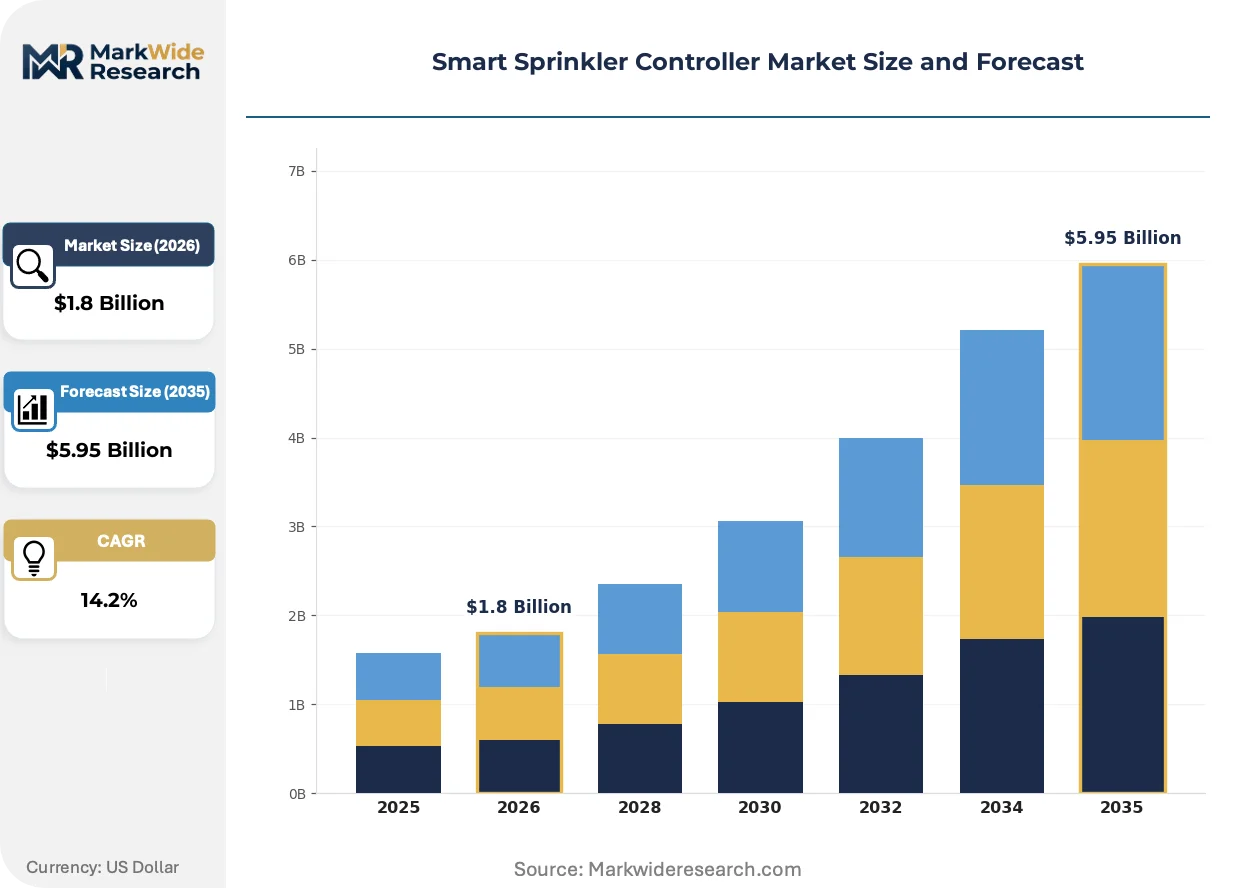
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wi-Fi Controller, Bluetooth Controller, Multi-Protocol Controller, Smart Irrigation System Technology: Cloud-Based, Mobile Application, Sensor Technology, Automated Scheduling End User: Residential Users, Commercial Properties, Agricultural Businesses, Landscaping Companies Distribution Channel: Online Retail, Specialty Stores, Direct Sales, Wholesale Distributors |
| Companies Covered | Rain Bird Corporation, Hunter Industries, The Toro Company, Netafim, Rachio, Inc., HydroPoint Data Systems, Weathermatic, Galcon, Orbit, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Sprinkler Controller Market Evolving Landscape
Machine learning inference at the edge is compressing latency for irrigation decisions while reducing cloud data egress costs, enabling subscription-free business models that challenge incumbent recurring-revenue structures.
LoRaWAN long-range radio modules are supplanting Wi-Fi as the dominant connectivity layer in agricultural and large-format commercial deployments. Texas cotton operations and California vineyard managers prioritize kilometer-range signal propagation over bandwidth-intensive firmware updates. This shift is enabling hardware vendors to decouple controller placement from router proximity, reducing trenching costs for retrofit installations.
California's Model Water Efficient Landscape Ordinance now mandates smart controller compatibility for new commercial developments exceeding specified irrigated areas. The regulation compresses specification timelines for landscape architects and forces distributor inventory rebalancing toward EPA WaterSense-certified SKUs. Texas and Colorado municipalities are adopting similar language, creating template effects for drought-response legislation.
Homeowner procurement patterns are fragmenting across direct-to-consumer online retail and professional irrigation contractor channels. Rachio and competitors capture replacement cycles through mobile application stickiness, while Rain Bird defends commercial specifications through distributor relationships with agricultural supply cooperatives. This bifurcation is most visible in California's Central Valley, where residential DTC penetration exceeds national averages while commercial sales remain contractor-mediated.
Smart Sprinkler Controller Market Segmentation
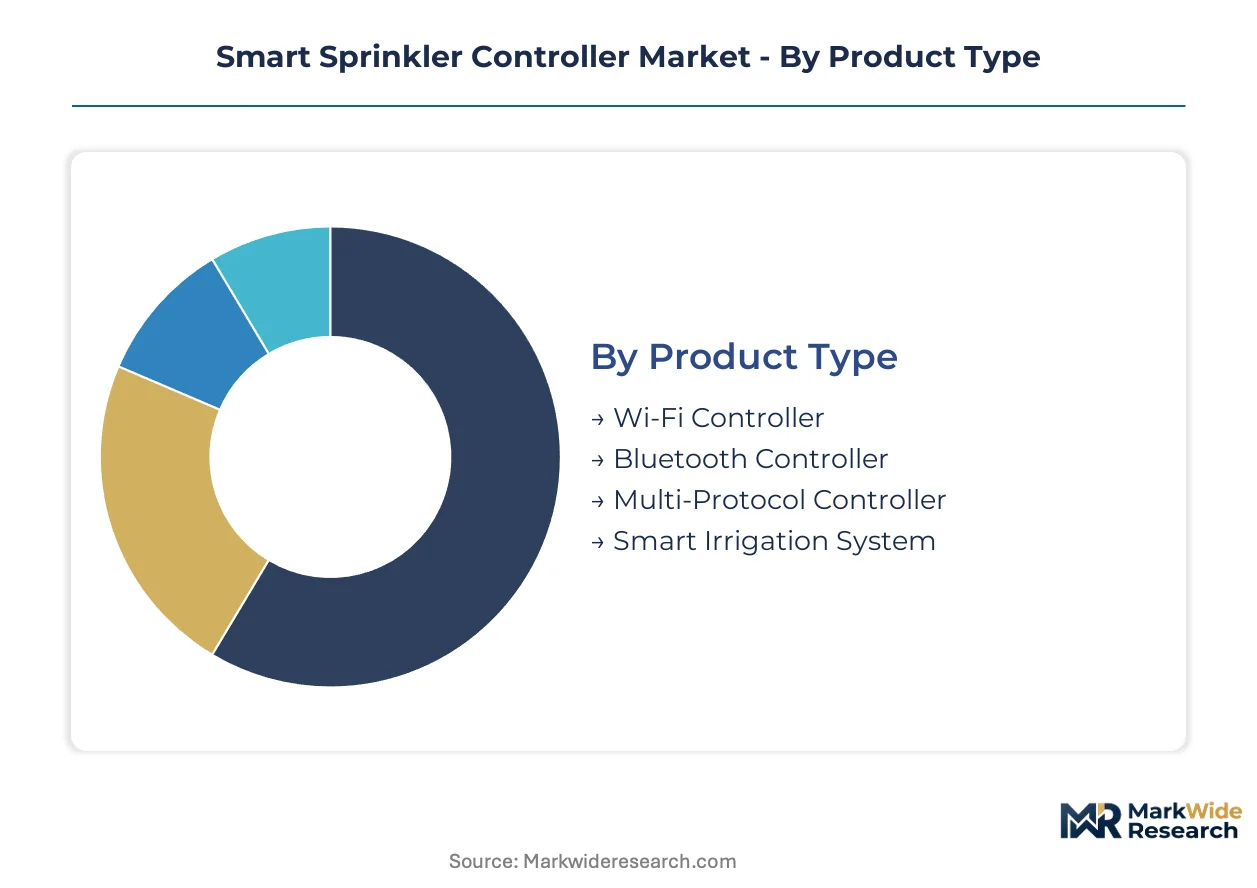
Smart sprinkler controller segmentation reveals distinct channel pathways where Wi-Fi hardware flows through mass retail while sensor-integrated systems concentrate in agricultural supply cooperatives. Understanding these routing patterns exposes margin structure and replacement cycle dynamics across residential, commercial, and farming deployments.
Product Type:
Channel mix bifurcates sharply between backward-compatible hardware for residential retrofit and multi-protocol systems for commercial redundancy requirements.
- Wi-Fi Controller:Operates on standard 2.4 GHz unlicensed spectrum with 24 VAC output interfaces for legacy solenoid compatibility. Demand clusters in California and Texas suburban developments where municipal rebate programs mandate cloud connectivity for qualification.
- Bluetooth Controller:Utilizes short-range mesh networking for localized zone control without internet dependency. Adoption concentrates in golf course and corporate campus installations across Arizona and Colorado where redundant connectivity justifies hardware premiums.
- Multi-Protocol Controller:Unifies cellular backhaul with mesh redundancy for agricultural and large-format commercial sites.
- Smart Irrigation System:Integrated valve-sensor-controller packages for new construction specifications.
Wi-Fi Controller dominates installed base. Multi-Protocol Controller is where expansion concentrates.
Technology:
Cost tier separation runs between subscription-dependent cloud platforms and edge-computing hardware that eliminates recurring fees.
- Cloud-Based:Centralized data processing with API-fed weather forecasting and remote schedule management. Concentration in residential DTC channels where mobile application stickiness drives replacement cycles and recurring revenue attachment.
- Sensor Technology:Soil volumetric water content probes with zone-specific moisture monitoring. Deployment centers on California almond and grape operations where yield protection justifies per-zone hardware costs through deficit irrigation optimization.
- Mobile Application:Smartphone-centric control interfaces for consumer-facing hardware tiers.
- Automated Scheduling:Evapotranspiration algorithm execution with minimal user intervention requirements.
Cloud-Based commands volume leadership. Sensor Technology captures the steepest expansion trajectory in agricultural verticals.
End User:
Customer type determines specification authority—homeowners self-direct online purchases while irrigation contractors gate commercial and agricultural procurement.
- Residential Users:Homeowners replacing mechanical timers with Wi-Fi-enabled controllers through direct-to-consumer retail. EPA WaterSense certification requirements in the United States compress replacement cycles as efficiency mandates tighten.
- Agricultural Businesses:Large-scale farming operations deploying zone-specific moisture monitoring for crop yield protection. California Central Valley almond growers and Texas cotton operations prioritize sensor-integrated systems with LoRaWAN backhaul for kilometer-range coverage.
- Commercial Properties:Corporate campuses and municipalities with multi-zone redundancy requirements.
- Landscaping Companies:Contractor-mediated procurement for maintenance-contract irrigation upgrades.
Residential Users anchor volume consumption. Agricultural Businesses generate the fastest margin expansion.
Distribution Channel:
Volume concentration shifts toward online retail for replacement cycles while professional channels defend commercial specification control.
- Online Retail:Direct-to-consumer platforms capturing residential replacement demand through mobile application stickiness and installation simplicity. Rachio and software-centric competitors anchor positioning here with subscription-free models challenging recurring-revenue incumbents.
- Wholesale Distributors:Agricultural supply cooperatives and irrigation specialists maintaining contractor relationships for commercial and farming specifications. Rain Bird leverages legacy infrastructure dominance across these channels for multi-zone institutional deployments.
- Specialty Stores:Regional hardware and garden centers with localized rebate program knowledge.
- Direct Sales:Manufacturer-led specification for large-format agricultural and municipal contracts.
Wholesale Distributors control commercial specification flow. Online Retail is gaining share fastest in residential replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in California and Texas where drought-driven rebate programs sustain hardware premiums, while Australian and European markets compress margins through efficiency-mandate standardization. Municipal procurement authority varies sharply across geographies.
United States
California's almond growers and Texas cotton operations drive agricultural demand for sensor-integrated systems with LoRaWAN backhaul. EPA WaterSense certification requirements compress replacement cycles for legacy timers in municipal rebate territories. Los Angeles and Phoenix metropolitan corridors concentrate residential retrofit volume through contractor-mediated channel flow.
Australia
Water efficiency standards in Victoria and New South Wales shape product development trajectories for export-oriented manufacturers. The country's national water regulator mandates smart controller compatibility for commercial developments above specified irrigated thresholds. Sydney and Melbourne urban clusters anchor demand concentration through drought-response infrastructure programs.
Germany
EU Green Deal water efficiency directives create certification pathways for commercial landscape contracts in Mediterranean climate zones. REACH and RoHS compliance requirements elevate hardware testing costs for market entry. Bavaria's precision agriculture sector pilots zone-specific moisture monitoring for vineyard yield optimization.
China
Dual carbon goals and MIIT efficiency standards accelerate domestic controller adoption in high-value crop regions. GB standards for irrigation equipment create technical barriers for unlicensed spectrum devices. Shandong Peninsula greenhouse operations deploy automated scheduling systems for water-intensive vegetable production.
Canada
Health Canada and PMRA regulate agricultural chemical runoff adjacent to smart irrigation deployments in Prairie Provinces. Ontario's greenhouse sector integrates volumetric water content probes for controlled-environment tomato and pepper cultivation. Toronto and Vancouver metropolitan areas concentrate residential Wi-Fi controller penetration through utility-sponsored rebate frameworks.
Smart Sprinkler Controller Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with software-centric specialists commanding premium positioning against legacy hardware incumbents. The market structure splits between cloud-platform investors and basic timer manufacturers, creating tiered competitive dynamics. Two dominant archetypes emerge: irrigation infrastructure incumbents with distributor channel control, and direct-to-consumer software platforms with mobile application stickiness. Competitive moves concentrate on M&A for sensor technology capabilities and strategic partnerships for municipal rebate program qualification.
Among legacy irrigation specialists, Rain Bird Corporation and Hunter Industries occupy positions within the commercial and agricultural specification tiers, anchoring distributor relationships across water-stressed Sun Belt states. Rachio, Inc. exemplifies the software-centric archetype competing through direct-to-consumer online retail channels. These three company structures illustrate the bifurcation between contractor-mediated commercial procurement and homeowner-driven replacement cycles.
| Leading Market Players |
|---|
| Rain Bird Corporation |
| Hunter Industries |
| The Toro Company |
| Netafim |
| Rachio, Inc. |
| HydroPoint Data Systems |
| Weathermatic |
| Galcon |
| Orbit |
| Others |
Value Network & Pricing Analysis
LoRaWAN radio module substitution for Wi-Fi chipsets is redrawing component sourcing maps toward Taiwan and South Korean foundries while compressing margins on legacy 2.4 GHz hardware tiers. This displacement simultaneously elevates pricing power for multi-protocol controller vendors and erodes cost advantages of single-connectivity residential units.
Pricing Analysis
The customization-premium spread separates EPA WaterSense-certified controllers with zone-specific sensor integration from basic timer replacements. Subscription-dependent cloud platforms anchor pricing in residential DTC channels, while certification-grade differentiation and volume scale drive tier separation. Pricing pressure stems from copper transformer and semiconductor input volatility, squeezing entry-tier margins. Agricultural buyers exhibit lowest price sensitivity due to yield-protection ROI, whereas residential retrofit segments demand rebate-qualified economy positioning.
Supply Chain Analysis
Port congestion on the Trans-Pacific trade lane elevates inbound logistics costs for 24 VAC transformer assemblies and Wi-Fi radio modules. Manufacturing concentrates in China, Taiwan, and South Korea for semiconductor components, with Mexico emerging for final assembly serving North American rebate program demand. Raw material dependencies include copper magnet wire, FR4 PCB substrates, and injection-molded ABS enclosures. Single-source vulnerability concentrates in Asian foundry capacity for LoRaWAN chipsets. Distribution runs through agricultural supply cooperatives for commercial specifications and direct-to-consumer platforms for residential replacement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory-entrenchment defensive moat, where EPA WaterSense certification and municipal rebate program qualification create structural switching costs that lock in specification cycles and distributor relationships.
For Market Incumbents: Secure exclusive distributor agreements with agricultural supply cooperatives in California's Central Valley and Texas cotton regions to block software-centric entrants from commercial channel access. Deepen backward integration into soil sensor manufacturing to capture margin pools from deficit irrigation protocols, while investing in LoRaWAN certification to defend against cellular-backhaul substitutes.
For New Entrants and Emerging Players: EPA WaterSense fast-track certification unlocks municipal rebate program eligibility in Arizona and Colorado expansion territories. White-space concentration sits in Bluetooth mesh controllers for golf course and corporate campus redundancy requirements, where incumbent channel control remains weakest. A direct-to-consumer mobile-first go-to-market angle bypasses contractor-mediated procurement friction in residential retrofit segments.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed irrigation hardware platforms lacking sensor technology integration. Five-to-ten year viability hinges on cloud-data-API differentiation and recurring revenue attachment rates. The signal to watch is municipal rebate program expansion into Pacific Northwest states, which would validate geographic diversification beyond Sun Belt drought territories.
| Strategic Initiative | Industry Significance |
|---|---|
| EPA WaterSense Certification Fast-Track | Unlocks municipal rebate program eligibility in California, Texas, and Arizona drought-response territories. |
| LoRaWAN Radio Module Integration | Enables kilometer-range connectivity for Texas cotton and California vineyard agricultural deployments. |
| Soil Sensor Technology Acquisition | Captures deficit irrigation optimization demand from almond and grape growers in water-stressed regions. |
| Bluetooth Mesh Platform Launch | Addresses redundant connectivity requirements from golf courses and corporate campuses in Sun Belt states. |
| Direct-to-Consumer Channel Expansion | Bypasses contractor-mediated procurement friction through mobile application stickiness in residential retrofit. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with irrigation contractors, agricultural supply cooperative procurement managers, landscape architects, and municipal water authority rebate program administrators; and secondary validation through EPA WaterSense certification databases, FCC Part 15 equipment authorization filings, California Department of Water Resources rebate tracking, and customs import records for 24 VAC transformer components. Bottom-up unit economics triangulated against top-down market sizing across product type, connectivity protocol, and end-user segmentation dimensions.
Across the analysis window, the forecasting framework modeled volume and value trajectories through product type, technology tier, end-user category, and distribution channel segmentation. CAGRs derived from replacement cycle compression rates, municipal rebate program expansion assumptions, and agricultural yield-protection ROI thresholds. Industry-specific inputs included evapotranspiration algorithm adoption curves, LoRaWAN network deployment timelines, and cloud-platform subscription attachment rates.
The analysis sits within stated boundaries; outcomes outside sustained drought declarations, stable semiconductor foundry capacity, and continued EPA WaterSense program funding would require recalibration. Forecasts reflect documented assumptions regarding rebate program eligibility criteria evolution and unlicensed spectrum regulatory stability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
IoT Cloud Platform Market
Internet of Things (IoT)
Asia-Pacific Massive IoT Market
Internet of Things (IoT)
IoT Gateway Devices Market
Internet of Things (IoT)
Global Military IoT Market
Internet of Things (IoT)
Global IoT Devices Market
Internet of Things (IoT)
Connected Bottles Market
Internet of Things (IoT)
Smart Sound and Gateway Market
Internet of Things (IoT)
Healthcare M2M Market
Internet of Things (IoT)
Global Machine-To-Machine (M2M) Connections Market
Internet of Things (IoT)
IoT Cellular Market
Internet of Things (IoT)
Edge Computing in IoT Market
Internet of Things (IoT)
North America and Europe IoT Gateway Market
Internet of Things (IoT)
IoT Market
Internet of Things (IoT)
Narrow Band IoT Tracker Market
Internet of Things (IoT)
UK IoT Software Market
Internet of Things (IoT)
IoT Lpwans Market