
 Global Data Warehouse As a Service (Dwaas) Market | 2026-2036
Global Data Warehouse As a Service (Dwaas) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Data Warehouse As a Service (Dwaas) Market Foresight
The capital-intensity divergence between hyperscale infrastructure operators and pure-play software vendors is unwinding traditional competitive boundaries in data warehousing. Amazon Web Services leverages its global server footprint to bundle compute and storage at scale. Snowflake Inc. differentiates through a consumption-based pricing architecture that decouples storage from compute resources. Microsoft Corporation anchors enterprise trust via deep integration with productivity suites and hybrid cloud orchestration tools.
Data Warehouse As a Service denotes a cloud computing model where organizations access fully managed data warehousing infrastructure, query engines, and storage layers via subscription or consumption-based contracts, typically supporting SQL analytics, petabyte-scale datasets, and elastic compute provisioning without on-premises hardware ownership. Its primary commercial purpose is to eliminate capital expenditure on physical data centers while enabling business intelligence, machine learning feature stores, and regulatory reporting pipelines. Public cloud deployment dominates volume due to hyperscaler economies of scope, yet hybrid cloud configurations are capturing margin pools from enterprises with sovereignty-sensitive workloads in banking and pharmaceuticals. Managed data warehouse solutions lead current revenue, while embedded analytics and real-time streaming integrations represent the fastest-expanding solution offerings as vendors embed visualization and alerting directly into operational applications.
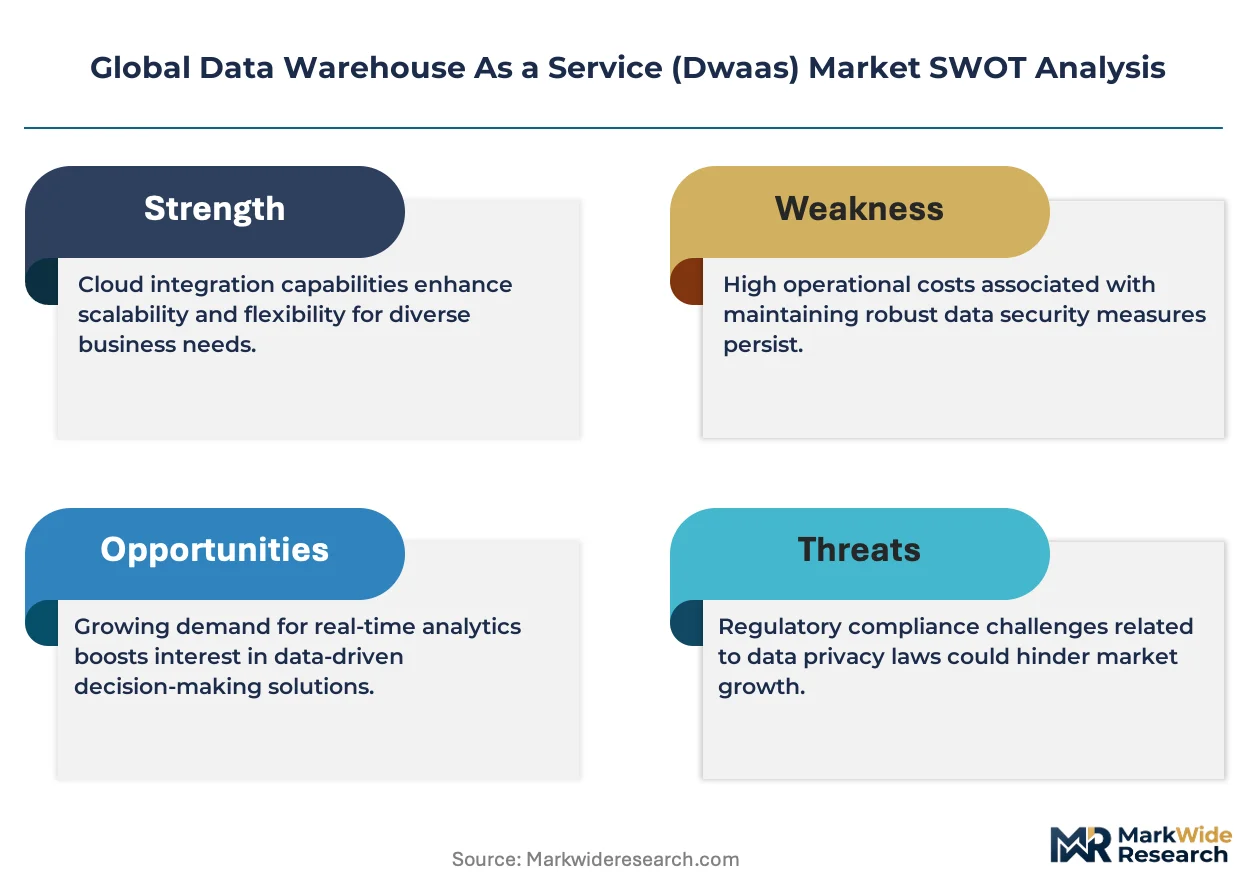
FDA 21 CFR Part 11 guidelines for electronic records in pharmaceuticals, the EU GDPR framework governing cross-border data residency, and China's GB standards for cloud service security assessments collectively shape product architecture and geographic market access for DWaaS providers. Compliance with these regimes forces vendors to maintain region-specific encryption key management, audit logging, and data localization capabilities that raise operational complexity but create defensive moats against unqualified entrants. Stakeholders must monitor evolving AI governance frameworks and sovereign cloud certification requirements as determinants of which platforms win regulated industry workloads.
Market Dynamics
Hyperscaler infrastructure investments are compressing unit economics for storage and compute, forcing pure-play software vendors toward consumption-based pricing architectures that decouple resources and accelerate margin pressure across the DWaaS landscape.
Growth Catalysts
- EU AI Act compliance mandates:European enterprises face binding algorithmic transparency and data governance requirements that push workloads toward managed cloud platforms with built-in audit trails and encryption key localization.
- Real-time risk analytics in banking:Financial services firms deploy streaming data pipelines for fraud detection and regulatory reporting, creating sustained demand for elastic compute provisioning and sub-second query latency.
- Federal cloud migration directives:United States government agencies accelerate FedRAMP-authorized platform adoption, channeling sovereign-sensitive workloads through certified hyperscaler environments.
Market Restraints
- Cross-border data residency friction:China's GB standards for cloud service security assessments and data localization requirements fragment global architecture consistency and raise operational complexity for multinational deployments.
- Concentrated silicon supply:Specialized AI accelerator chip fabrication concentrates in Taiwan and South Korea, creating input cost volatility and capacity constraints for GPU-intensive warehouse workloads.
- Substitution by lakehouse architectures:Apache Iceberg and Delta Lake formats enable query engines to operate directly on object storage, compressing demand for traditional warehouse abstraction layers in analytics-native enterprises.
Strategic Opportunities
- Sovereign cloud certification in Germany:C5 and BSI standards create defensive moats for compliant providers targeting automotive and pharmaceutical supply chain data hubs in Baden-Württemberg and Bavaria.
- Embedded analytics convergence:Integration of visualization and alerting directly into operational applications via real-time streaming APIs opens margin pools in retail inventory management and logistics orchestration.
- Pharmaceutical 21 CFR Part 11 digitization:FDA electronic records guidelines drive replacement of on-premises validation infrastructure with managed platforms offering immutable audit logs and electronic signature workflows.
Industry Challenges
- Multi-cloud orchestration expertise scarcity:Organizations struggle to hire engineers proficient in Kubernetes-based workload portability across AWS, Azure, and GCP environments, delaying hybrid deployment timelines.
- Legacy mainframe extraction complexity:COBOL-based core banking and insurance policy systems resist API-native connectivity, requiring costly middleware development for warehouse ingestion pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Data Warehouse As a Service (Dwaas) Market |
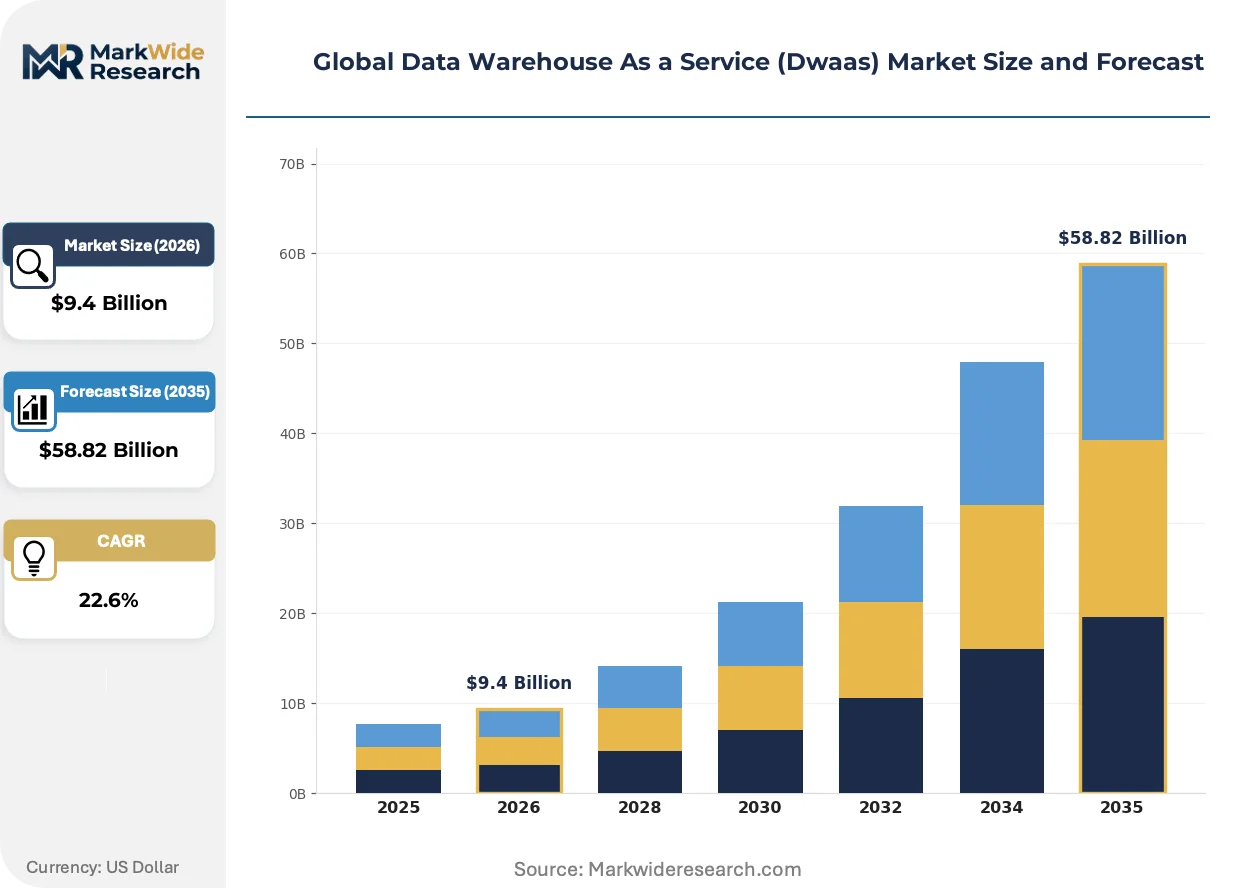
| Market Size in 2026 | $9.4 Billion |
| Market Size in 2035 | $58.82 Billion |
| CAGR (2026 – 2036) | 22.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Solution Offering: Managed Data Warehouse, Self-Service Data Warehouse, Embedded Analytics, Data Lake Integration, Real-Time Analytics Use Case: Customer Analytics, Fraud Detection, Supply Chain Optimization, Predictive Maintenance, Market Intelligence End User Industry: Telecommunications, Hospitality, Pharmaceuticals, Banking & Financial Services, Media & Entertainment |
| Companies Covered | Amazon Web Services, Snowflake Inc., Google LLC, Microsoft Corporation, IBM Corporation, Oracle Corporation, Teradata, SAP SE, Databricks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Data Warehouse As a Service (Dwaas) Market Shifts & Advancements
Query engine architectures are fragmenting as vendors race to embed vector search, real-time streaming, and AI-native operations directly into warehouse substrates, compressing the boundary between analytical and transactional systems.
Serverless query execution is miniaturizing operational overhead for intermittent analytics workloads. Retail and logistics firms adopt pay-per-query models for seasonal demand forecasting, eliminating provisioned cluster management. This compression of fixed infrastructure commitments is accelerating displacement of reserved instance contracts in price-sensitive segments.
REACH chemical data governance extensions and the EU CSRD sustainability reporting mandate are forcing warehouse providers to implement granular lineage tracking and carbon footprint attribution at the query level. Pharmaceutical and industrial manufacturing buyers in the Netherlands and Belgium now require ESG-certified data residency as a procurement precondition.
Consumption-based pricing is unbundling storage from compute commitments across enterprise procurement cycles. Chief data officers in United States healthcare and financial services negotiate granular rate cards for cold archive versus hot query tiers, replacing flat-rate subscriptions with metered contracts indexed to actual query volume and data temperature.
Global Data Warehouse As a Service (Dwaas) Market Segmentation
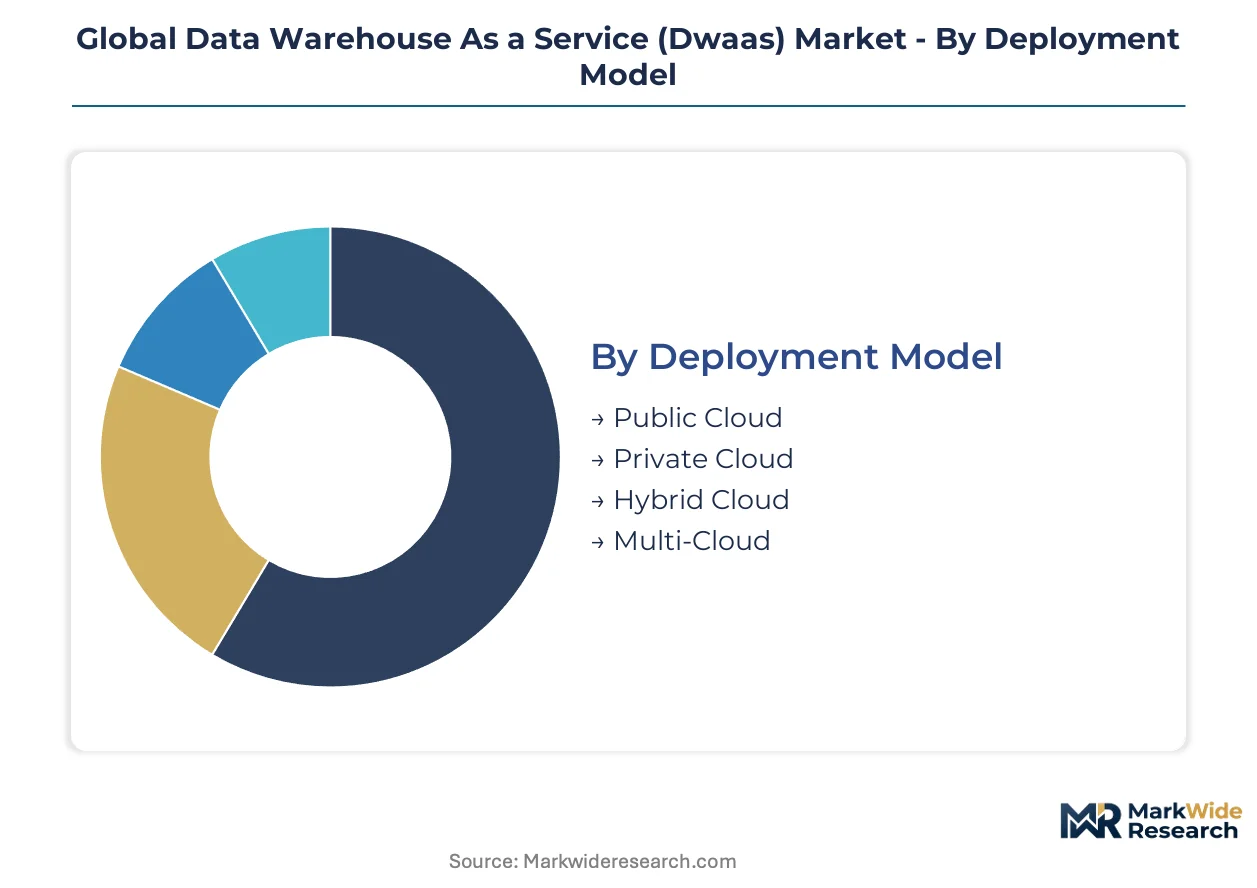
DWaaS procurement patterns diverge sharply between latency-sensitive operational workloads and batch-oriented analytical pipelines. Deployment sovereignty requirements and consumption economics reshape how enterprises allocate budgets across infrastructure tiers.
Deployment Model:
Public cloud configurations dominate transaction volumes in North American and Western European markets, while hybrid and sovereign deployments concentrate in regulated Asian and Middle Eastern jurisdictions.
- Public Cloud:Hyperscaler-managed infrastructure delivers elastic compute provisioning without capital expenditure. Demand concentrates among United States retail and media firms seeking seasonal burst capacity for campaign analytics and inventory forecasting.
- Private Cloud:Dedicated tenant environments with isolated hardware stacks serve defense contractors and Swiss banking consortiums requiring cryptographic key custody on sovereign soil. German automotive suppliers in Baden-Württemberg mandate C5-certified private deployments for powertrain telemetry archives.
- Hybrid Cloud:Split architectures partition sensitive master data on-premises while pushing transformation workloads to elastic cloud tiers. Japanese pharmaceutical manufacturers deploy hybrid models to satisfy PMDA audit requirements for clinical trial records.
- Multi-Cloud:Orchestrated workloads across AWS, Azure, and GCP reduce vendor lock-in risk. Australian federal agencies mandate multi-cloud strategies under TGA-aligned procurement frameworks for healthcare data interoperability.
Public cloud commands the established base. The steepest expansion runs through hybrid configurations as sovereignty mandates proliferate.
Solution Offering:
Enterprise procurement cycles increasingly favor consumption-metered contracts over reserved capacity, compressing margin structures for provisioned-cluster offerings.
- Managed Data Warehouse:Fully operated infrastructure with automated patching, backup, and query optimization. Banking and financial services firms in Singapore and London deploy managed platforms to satisfy MAS and FCA operational resilience directives without internal platform engineering teams.
- Self-Service Data Warehouse:Browser-based schema design and ETL configuration tools enable analyst-led pipeline construction. United States healthcare systems adopt self-service layers to decentralize HIPAA-compliant reporting across regional hospital networks.
- Embedded Analytics:Visualization and alerting APIs integrated directly into operational applications. French logistics providers embed warehouse-derived ETA predictions into customer-facing tracking portals.
- Data Lake Integration:Federated query engines spanning structured warehouse tables and raw object storage. Brazilian agribusiness conglomerates query satellite imagery archives alongside transactional grain pricing through unified SQL interfaces.
- Real-Time Analytics:Sub-second latency streaming ingestion with continuous SQL evaluation. South Korean telecommunications operators deploy real-time pipelines for 5G network slice performance monitoring and automated congestion routing.
Managed data warehouse retains the revenue base. Real-time analytics gains share fastest as streaming infrastructure commodifies.
Use Case:
Operational workload requirements fragment procurement criteria between batch latency tolerance and sub-second decision windows.
- Customer Analytics:Unified profile construction across CRM, web, and mobile touchpoints. Indian e-commerce marketplaces deploy customer analytics layers to segment price-sensitive buyers for festival-season promotional targeting.
- Fraud Detection:Anomaly scoring on transaction streams with automated account suspension triggers. Italian banking cooperatives in Lombardy implement fraud detection warehouses to comply with ECB instant payment verification timelines.
- Supply Chain Optimization:Multi-echelon inventory positioning and demand sensing across supplier networks. Canadian mining operators optimize concentrate shipment routing through warehouse-driven rail and port capacity forecasting.
- Predictive Maintenance:Sensor telemetry aggregation for equipment failure probability modeling. Saudi petrochemical facilities deploy predictive maintenance warehouses to minimize unplanned cracker unit downtime in Jubail Industrial City clusters.
- Market Intelligence:Competitive pricing surveillance and sentiment extraction from unstructured sources. Dutch flower auction cooperatives aggregate global supply signals to optimize daily tulip and rose pricing at Aalsmeer trading floors.
Fraud detection anchors financial services procurement. Predictive maintenance climbs fastest as industrial IoT sensor density accelerates.
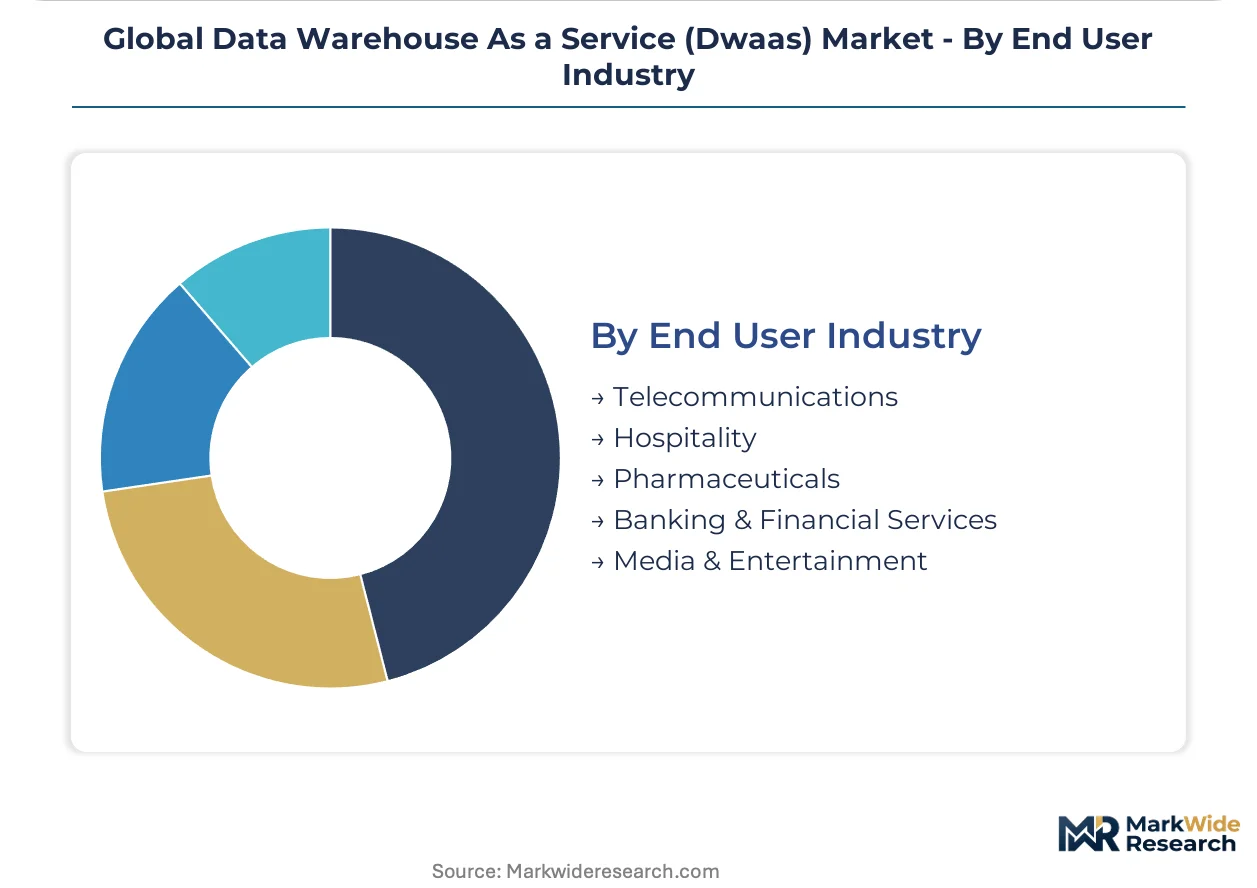
End User Industry:
Regulatory stringency and data gravity determine whether industries adopt public, hybrid, or sovereign deployment configurations.
- Telecommunications:Subscriber data monetization and network performance analytics at petabyte scale. Nordic operators in Sweden and Finland deploy DWaaS for cross-border roaming revenue assurance under GDPR-aligned data processing agreements.
- Hospitality:Dynamic pricing optimization and guest preference personalization. Dubai hotel groups leverage warehouse-derived demand forecasting to adjust room rates across properties during conference and exhibition peaks.
- Pharmaceuticals:Clinical trial data management and pharmacovigilance signal detection. FDA 21 CFR Part 11 compliance mandates drive replacement of validated on-premises systems with audit-capable managed platforms.
- Banking & Financial Services:Risk-weighted asset calculation and real-time liquidity monitoring. United Kingdom challenger banks adopt cloud-native warehouses to satisfy PRA operational resilience standards without legacy mainframe dependency.
- Media & Entertainment:Content recommendation engines and advertising yield optimization. Brazilian streaming platforms deploy viewer behavior warehouses to localize original production investments for Portuguese-language markets.
Banking and financial services underpins the revenue foundation. Pharmaceuticals expands most rapidly as electronic records mandates displace legacy validation infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States buyers prioritize elastic burst capacity for seasonal workloads, while German and Japanese procurement teams emphasize cryptographic sovereignty and audit-grade compliance over unit cost minimization.
United States
FedRAMP-authorized platform adoption channels sovereign-sensitive federal workloads through certified hyperscaler environments. HIPAA and SEC record-keeping rules force healthcare and financial services firms toward managed platforms with immutable audit trails. Silicon Valley and Seattle tech clusters drive consumption-based pricing negotiations for AI training pipelines.
Germany
Automotive suppliers in Baden-Württemberg mandate C5-certified private deployments for powertrain telemetry archives under BSI baseline protection standards. The EU AI Act's algorithmic transparency requirements push Mittelstand manufacturers toward cloud platforms with built-in governance tooling. Munich and Stuttgart banking consortia require cryptographic key custody on sovereign soil.
Japan
PMDA audit requirements for clinical trial records drive hybrid deployments among Tokyo and Osaka pharmaceutical manufacturers. METI's data free flow with trust principles shape cross-border architecture decisions for automotive exporters. Yokohama-based logistics operators deploy real-time streaming warehouses for port capacity optimization.
United Kingdom
PRA operational resilience standards accelerate cloud-native warehouse adoption among London challenger banks seeking mainframe independence. FCA fraud detection timelines mandate sub-second query latency for payment verification pipelines. The Edinburgh-Glasgow financial corridor concentrates RegTech procurement for GDPR-aligned data processing agreements.
Singapore
MAS operational resilience directives channel banking workloads toward managed platforms without internal platform engineering teams. Cross-border data flow agreements with ASEAN partners shape multi-cloud orchestration strategies for regional headquarters. The Marina Bay fintech cluster drives demand for real-time risk analytics on commodity trading flows.
Global Data Warehouse As a Service (Dwaas) Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with hyperscalers leveraging infrastructure scale against pure-play vendors emphasizing consumption-based pricing architectures. The market structure concentrates around three strategic archetypes: hyperscale cloud operators with bundled compute-storage offerings, independent software vendors with decoupled resource pricing, and legacy enterprise database providers migrating installed bases to managed services. Dominant competitive moves include strategic partnerships for sovereign cloud certification and portfolio diversification into real-time streaming and vector search capabilities.
Within the hyperscale tier, Amazon Web Services and Microsoft Corporation anchor infrastructure-heavy positioning through global server footprints and productivity suite integration. Snowflake Inc. exemplifies the independent software archetype with consumption-metered contracts that separate storage from compute commitments. Google LLC occupies a position between these vectors, leveraging AI-native tooling and search infrastructure heritage for analytics workloads.
| Leading Market Players |
|---|
| Amazon Web Services |
| Snowflake Inc. |
| Google LLC |
| Microsoft Corporation |
| IBM Corporation |
| Oracle Corporation |
| Teradata |
| SAP SE |
| Databricks |
| Others |
Supply & Pricing Matrix
Apache Iceberg and Delta Lake formats replacing traditional warehouse abstraction layers simultaneously redraw supply geography toward open-source query engine developers and compress pricing power for proprietary storage-layer vendors. This substitution dynamic shifts procurement leverage toward enterprises with in-house data engineering capabilities while eroding margin pools for managed-platform providers dependent on storage-compute bundling.
Pricing Analysis
Consumption-based service tiers and reserved capacity contracts drive lifetime value for DWaaS providers, with metered query execution capturing recurring revenue from intermittent analytics workloads. Three-tier pricing structure across premium, standard, and economy levels separates FedRAMP-authorized sovereign deployments from multi-tenant public cloud instances and cold archive storage. Cost compression in standard-tier offerings is intensifying because hyperscaler infrastructure investments compress unit economics for compute and storage. Healthcare systems in the United States exhibit highest price sensitivity due to HIPAA compliance overhead, while defense contractors accept premium pricing for cryptographic key custody on sovereign soil.
Supply Chain Analysis
Port congestion on Asia-Pacific trade lanes elevates inbound logistics costs for GPU accelerator shipments destined for hyperscaler data centers in Oregon and Virginia. Taiwan and South Korea anchor specialized AI chip fabrication, while China concentrates server motherboard assembly and memory module production. The supply chain draws from NVIDIA and AMD accelerators, DDR5 memory modules, and custom ASICs for query optimization. Single-source vulnerability in Taiwan semiconductor fabrication creates capacity constraints for GPU-intensive warehouse workloads. Distribution runs through direct hyperscaler procurement channels and value-added resellers serving regulated industry verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as sovereignty mandates proliferate, with EU AI Act compliance requirements and China's GB standards creating protected niches for certified regional providers that hyperscalers cannot easily replicate.
For Market Incumbents: Secure FedRAMP and C5 certifications ahead of federal cloud migration directives and BSI baseline protection standards in Germany. Invest in sovereign cloud infrastructure in Baden-Württemberg and Bavaria to defend against emerging European specialists capturing automotive and pharmaceutical procurement. Vertical integration into real-time streaming query engines counters displacement by lakehouse architectures.
For New Entrants and Emerging Players: Differentiate on sovereign certification depth rather than unit cost, targeting German automotive suppliers and Swiss banking consortiums requiring cryptographic key custody on domestic soil. The most penetrable segment lies in hybrid cloud orchestration for Japanese pharmaceutical manufacturers satisfying PMDA audit requirements. A channel partnership strategy with systems integrators experienced in legacy mainframe extraction accelerates time-to-revenue.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed pure-play software vendors struggling to match hyperscaler infrastructure scale. Long-term viability favors platforms with durable compliance moats and consumption-based pricing architectures decoupled from provisioned cluster commitments. Watch for inflection in sovereign cloud certification velocity as signal for which regional specialists achieve enterprise procurement eligibility.
| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Certification | C5 and BSI standards unlock procurement from German automotive suppliers in Baden-Württemberg. |
| Real-Time Streaming Integration | Sub-second latency APIs capture margin pools in South Korean 5G network performance monitoring. |
| Consumption-Based Pricing Unbundling | Metered contracts indexed to query volume displace reserved instance commitments in United States healthcare. |
| Legacy Mainframe Connectivity | COBOL-native middleware enables warehouse ingestion from core banking systems resisting API extraction. |
| Vector Search Embedding | AI-native operations in warehouse substrates compress boundaries between analytical and transactional systems. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of hyperscaler capex disclosures, SEC 10-K filings, and regulatory certification databases for FedRAMP, C5, and BSI standards. Chief data officers, cloud platform engineers, and procurement leads at financial services and pharmaceutical enterprises provided operational perspectives on deployment decisions and vendor selection criteria. Bottom-up sizing of consumption-metered contracts triangulates against top-down analysis of hyperscaler infrastructure investments and regional cloud revenue disclosures.
Segmentation dimensions modeled include deployment model, solution offering, use case, and end user industry across the projection horizon. CAGRs derive from regression analysis of historical consumption patterns and forward projections of sovereign cloud adoption velocity. Forecast inputs incorporate EU AI Act implementation timelines and FDA 21 CFR Part 11 digitization mandates in pharmaceuticals.
The analysis sits within stated boundaries; outcomes outside sustained hyperscaler infrastructure investment and stable cross-border data flow agreements would require recalibration. Forecasts reflect assumptions regarding regulatory certification velocity and enterprise migration timelines from on-premises validation infrastructure. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Global Data Warehouse Market
Data Center and Networking
Application Delivery Network (ADN) Market
Data Center and Networking
Global Virtual Private Server Market
Data Center and Networking
Global Data Fabric Market
Data Center and Networking
Global Enterprise Networking Market
Data Center and Networking
Europe Data Center Market
Data Center and Networking
Thailand Data Center Networking Market
Data Center and Networking
India Data Center Networking Market
Data Center and Networking
Service Provider Router Market
Data Center and Networking
Nigeria Data Center Networking Market
Data Center and Networking
Converged Data Platform Market
Data Center and Networking
Japan Data Center Networking Market
Data Center and Networking
Cluster Computing Market
Data Center and Networking
Brazil Servers Market
Data Center and Networking
Ireland Data Center Networking Market
Data Center and Networking
Middle East Data Center Server Market