
 Blade Server Market | 2026-2036
Blade Server Market Size, Share, and Industry Trends Forecast 2026-2036
Blade Server Market Intelligence
Demand from large-scale Cloud Service Providers is collapsing the traditional enterprise IT procurement model for blade servers. Hewlett Packard Enterprise leverages its extensive portfolio to serve both segments. Dell Technologies competes on direct-to-customer sales and supply chain efficiency. Cisco Systems differentiates through its integrated networking and computing solutions, particularly in hybrid cloud environments.
A blade server is a stripped-down server computer with a modular design optimized for minimizing physical space and energy consumption. Each blade contains processors, memory, and sometimes storage, slotting into a larger enclosure that provides shared power and cooling. Within product types, enclosures and the blades themselves constitute the core hardware investment, while management software becomes a key point of differentiation. Among end users, Data Centers and Cloud Service Providers represent the largest and fastest-growing segments, eclipsing traditional enterprise deployments.
Energy efficiency regulations, such as the EU Green Deal's focus on data center sustainability and the EPA's Energy Star program in the United States, are shaping server design. These frameworks mandate lower power consumption and promote the use of advanced cooling, directly influencing hardware development and procurement criteria. Vendor success will depend on navigating the complex trade-offs between compute density, power efficiency, and total cost of ownership.
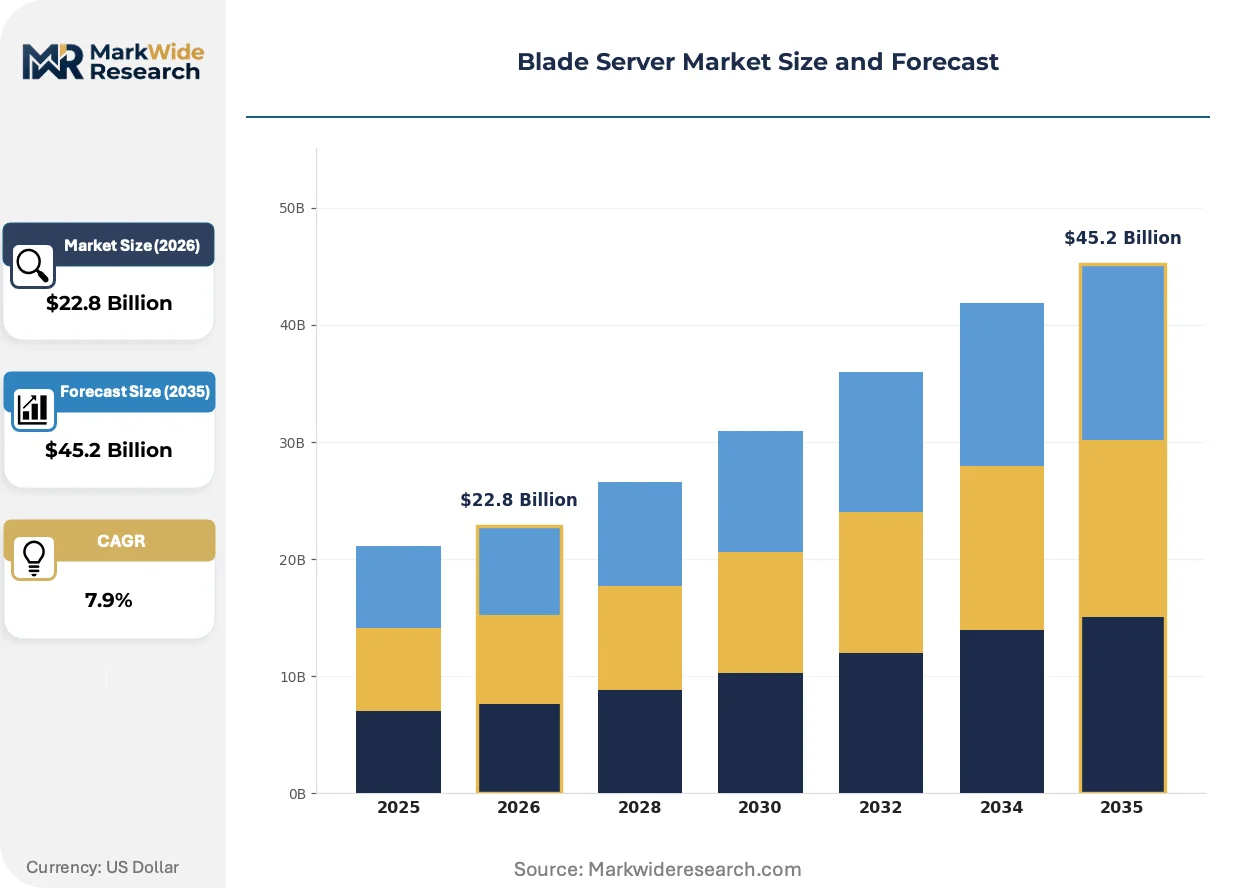
Market Dynamics
The central structural force shaping the blade server market is the escalating tension between the demand for higher compute density and the physical limits of air cooling. This dynamic compels innovation in thermal management and enclosure design, directly impacting total cost of ownership.
Growth Catalysts
- Liquid Cooling Adoption:The proliferation of direct-to-chip and immersion cooling technologies enables higher power density per rack, allowing data centers to support more powerful processors for AI and HPC workloads without expanding their physical footprint.
- Cloud Provider Expansion:Hyperscale cloud service providers are building out new availability zones in regions like Southeast Asia and the Middle East, creating sustained, large-volume demand for standardized blade server configurations.
- Energy Efficiency Mandates:Regulations such as the EU Green Deal and the EPA's Energy Star program incentivize the procurement of energy-efficient servers, favoring blade designs optimized for low power consumption.
Market Restraints
- High Upfront Investment:The initial capital outlay for blade enclosures, which include shared power, cooling, and networking components, is substantially higher than for individual rack servers, posing a barrier for smaller enterprises. *Proprietary Architectures: Vendor lock-in remains a significant restraint, as blades from one manufacturer are typically incompatible with enclosures from another, limiting customer flexibility and increasing long-term switching costs.
- Competition from HCI:The rise of hyper-converged infrastructure (HCI) presents a strong substitution threat, offering an alternative software-defined approach to compute and storage that appeals to enterprises seeking simplified management.
Strategic Opportunities
- Edge Computing Deployments:The need for powerful, compact compute resources at the network edge for applications like industrial IoT and autonomous systems creates an opportunity for ruggedized, small-footprint blade servers.
- AI Accelerator Integration:Integrating specialized processors like GPUs, FPGAs, and custom ASICs directly onto blade modules offers a path to create workload-optimized servers for AI training and inference tasks.
- Managed Services for Enterprises:Vendors can develop new revenue streams by offering managed hardware services, allowing enterprises to consume blade infrastructure on an as-a-service basis, mitigating high upfront costs.
Industry Challenges
- Supply Chain Volatility:The market is subject to long lead times and price fluctuations for critical components like high-performance CPUs and high-bandwidth memory, complicating production planning and delivery schedules.
- Thermal Management Complexity:Designing and implementing advanced liquid cooling solutions at scale requires specialized engineering expertise in fluid dynamics and thermal engineering, creating a talent gap within the industry.
- Legacy System Integration:Enterprises face significant challenges in integrating modern blade systems and their associated management software with existing, often heterogeneous, data center infrastructure and operational workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blade Server Market |
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $45.2 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Enclosures, Blades, Management Software, Power Supplies End User: Data Centers, Enterprises, Cloud Service Providers, Telecom Operators Deployment: On-Premises, Hybrid Cloud, Private Cloud, Colocation Solution: Integration Services, Maintenance & Support, Customization, Backup Solutions |
| Companies Covered | Cisco Systems, Huawei Technologies, Hewlett Packard Enterprise, Inspur Group, Fujitsu, Dell Technologies, International Business Machines, Super Micro Computer, Lenovo Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blade Server Market Strategic Shifts & Innovations
Workload-specific optimization is defining the next generation of blade server architecture. The market is evolving beyond general-purpose computing to deliver highly specialized hardware configurations tailored for artificial intelligence, data analytics, and high-performance computing, driving new thermal and design paradigms.
Direct Liquid Cooling (DLC) is a thermal management technology using fluids to dissipate heat directly from high-power components like CPUs. Hyperscale data centers and research institutions are the primary adopters, driven by the need to cool processors with increasing thermal design power. This adoption is bifurcating the market into traditional air-cooled systems for general enterprise workloads and advanced liquid-cooled designs for performance-intensive applications.
European Union sustainability regulations, particularly the energy efficiency reporting requirements under the Corporate Sustainability Reporting Directive (CSRD), are influencing server procurement. These rules compel data center operators to measure and disclose their energy consumption and carbon footprint. Consequently, data centers in the EU are prioritizing blade servers that demonstrate superior power usage effectiveness (PUE) and incorporate advanced power management features.
A significant demand-side shift is the move from direct hardware ownership by enterprises to consumption-based models. Instead of purchasing and managing their own servers, many organizations now access compute resources through cloud providers or co-location facilities. This trend, most visible in North America, concentrates buying power with a smaller number of large-scale buyers and changes the sales focus from individual enterprises to hyperscale operators.
Blade Server Market Segmentation
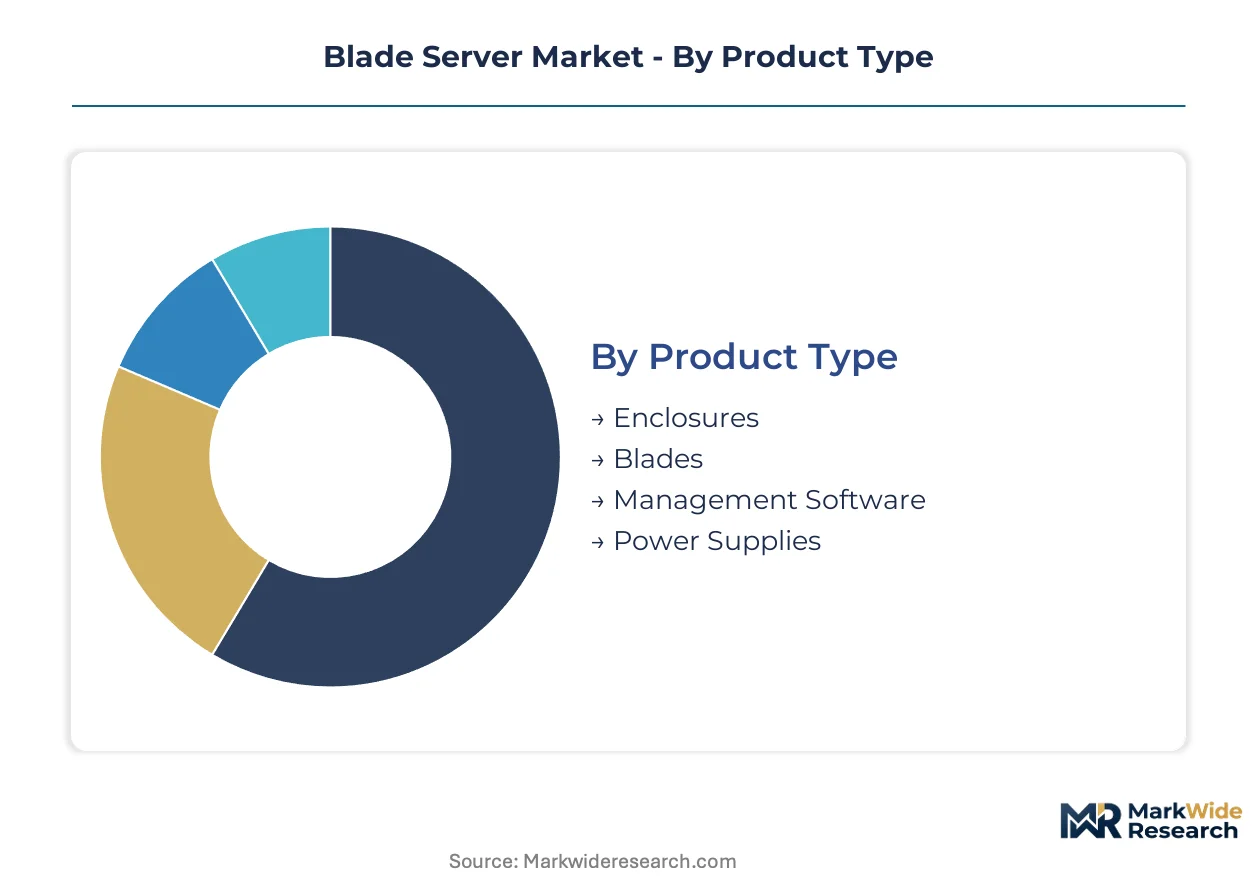
The blade server market's segmentation reflects the diverse technological requirements and operational strategies of various end-users. Understanding these distinct segments provides clarity on where innovation is concentrated and how different deployment models influence procurement decisions.
Product Type:
The geographic distribution of blade server product types reflects varying infrastructure maturity and regulatory landscapes across different regions.
- Blades:These stripped-down server computers contain processors, memory, and sometimes storage, slotting into a larger enclosure. Demand is concentrating in major data center hubs like Ashburn and Frankfurt, driven by hyperscale cloud provider expansion.
- Enclosures:These larger chassis provide shared power, cooling, and networking for multiple blade servers. Demand is concentrating in Asia-Pacific and North America, fueled by new data center builds and modernization projects.
- Management Software:This software facilitates the orchestration and monitoring of blade server resources within an integrated environment.
- Power Supplies:Critical components within the blade enclosure, responsible for efficient energy delivery to all installed blades and shared components.
Blades hold the largest share; momentum sits with Management Software.
End User:
Different end-user segments exhibit distinct procurement patterns and operational demands for blade server infrastructure.
- Cloud Service Providers:Hyperscale operators require standardized, high-density configurations for their global data centers. Their expansion into new availability zones drives significant volume demand.
- Data Centers:These facilities host IT infrastructure for various clients, increasingly adopting blade servers for efficiency and space optimization. Advanced cooling technologies enable higher power densities for these operators.
- Enterprises:Traditional businesses are transitioning from direct hardware ownership to consumption-based models, impacting their blade server procurement.
- Telecom Operators:Deploy blade servers for network function virtualization and edge computing applications, requiring compact and robust solutions.
Cloud Service Providers represent the fastest-growing segment, driven by continuous hyperscale expansion.
Deployment:
The choice of deployment model for blade servers reflects an organization's strategic priorities regarding control, scalability, and operational flexibility.
- Hybrid Cloud:This model combines on-premises infrastructure with public cloud services, allowing workloads to move between environments. Hybrid Cloud appeals to enterprises seeking flexibility and data residency compliance.
- On-Premises:Organizations maintain full control over their server infrastructure within their own facilities. This remains prevalent for sensitive data and legacy applications requiring specific security protocols.
- Private Cloud:A dedicated cloud environment for a single organization, often built on blade server infrastructure for enhanced security and performance.
- Colocation:Data centers host customer-owned servers, providing shared power, cooling, and network connectivity, reducing on-site infrastructure burden.
Hybrid Cloud deployments are gaining significant traction, while On-Premises solutions continue to dominate for specific critical workloads.
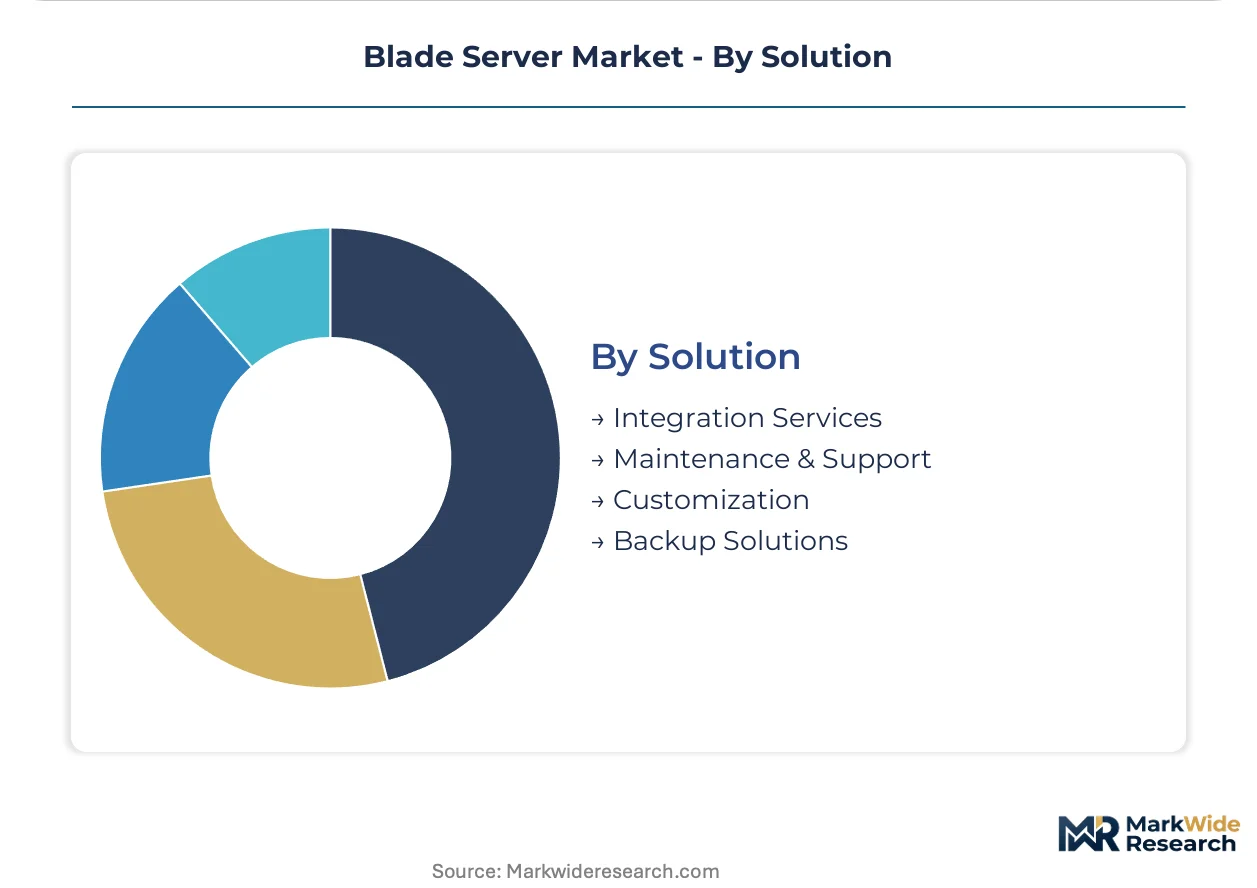
Solution:
Blade server solutions extend beyond hardware, encompassing a range of services that enhance operational efficiency and system longevity.
- Maintenance & Support:Essential services ensuring continuous operation and maximizing the lifespan of blade server infrastructure. Providers offer various service level agreements to meet diverse enterprise needs.
- Integration Services:Facilitate the seamless deployment of new blade server systems into existing data center environments. This includes network configuration, software installation, and compatibility testing.
- Customization:Tailoring blade server configurations to meet specific workload requirements, such as AI accelerator integration or specialized networking.
- Backup Solutions:Protect data stored on blade servers, ensuring business continuity and disaster recovery capabilities for critical applications.
Maintenance & Support services are critical for long-term operational success, with Customization emerging as a key differentiator.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Global fiber optic networks underpin the geographic distribution of the blade server market, connecting major data center hubs worldwide. This infrastructure facilitates the rapid expansion of cloud services and the deployment of high-performance computing resources. The market's growth patterns reflect significant investments in digital infrastructure across key economic regions.
United States
The United States drives blade server demand through hyperscale cloud expansion and the proliferation of artificial intelligence workloads. EPA's Energy Star program influences procurement decisions, favoring energy-efficient server designs. Ashburn, Virginia, continues to expand as a primary internet exchange point, driving significant blade server deployments for cloud and colocation providers.
Germany
Germany's market for blade servers benefits from stringent data sovereignty requirements and the EU Green Deal's sustainability mandates. The EU Green Deal's focus on data center energy efficiency directly shapes hardware development. Frankfurt serves as a critical European internet hub, attracting new data center investments and blade server installations for both enterprise and cloud clients.
Singapore
Singapore's strategic location positions it as a hub for Southeast Asian cloud expansion and regional digital transformation initiatives. The country's Green Data Centre Roadmap promotes energy-efficient IT infrastructure, influencing server design and deployment. Jurong and Punggol host numerous hyperscale data centers, fueling demand for high-density blade solutions.
China
Within China, hyperscale cloud growth and ambitious domestic AI initiatives are significant drivers for blade server adoption. China's dual carbon goals incentivize energy-efficient data center technologies and advanced cooling solutions. Beijing and Shanghai are central to the country's digital economy, driving demand for advanced blade server architectures for both public and private cloud deployments.
India
India's market for blade servers is propelled by Digital India initiatives and the rapid expansion of local cloud providers. The National Digital Communications Policy emphasizes data localization and green data center development. Mumbai and Hyderabad are rapidly emerging data center corridors, attracting significant blade server investments from both domestic and international players.
Blade Server Market Key Industry Players
Concentration sits with established global technology conglomerates that leverage extensive distribution networks and deep client relationships. The market structure features a tiered landscape, with large-scale providers offering integrated solutions alongside specialized component manufacturers. Leading players pursue portfolio diversification and strategic partnerships to address evolving customer needs and expand their market reach.
Among the established global players, Dell Technologies and Hewlett Packard Enterprise occupy a strong position, offering broad portfolios that cater to both hyperscale cloud providers and traditional enterprise clients. Cisco Systems exemplifies a strategy focused on integrated networking and computing solutions, particularly for hybrid cloud environments. These companies anchor the supply of core blade server hardware and associated management software, defining industry standards and driving innovation in density and efficiency.
| Leading Market Players |
|---|
| Cisco Systems |
| Huawei Technologies |
| Hewlett Packard Enterprise |
| Inspur Group |
| Fujitsu |
| Dell Technologies |
| International Business Machines |
| Super Micro Computer |
| Lenovo Group |
| Others |
Cost & Logistics Intelligence
Economies of scale in blade server manufacturing drive intense competition, concentrating production among a few large players and establishing aggressive price floors for high-volume orders.
Pricing Analysis
Volume-discounted contract pricing structures dominate the blade server market, particularly for hyperscale cloud providers. Price differentiation stems from customization levels for AI accelerators and the breadth of integrated management software. Pricing softness persists due to intense competition among major vendors for large-volume cloud contracts. Cloud Service Providers exhibit the highest price sensitivity, while enterprises prioritizing specific workload optimization show less.
Supply Chain Analysis
Extended component lead times for high-performance CPUs and high-bandwidth memory characterize the blade server supply chain. Manufacturing concentration sits in China and Taiwan for core components, with final assembly often occurring in the USA or Europe. Single-source vulnerability for specialized liquid cooling components presents a structural risk. Downstream distribution primarily channels through direct sales to hyperscale operators and value-added resellers for enterprise clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The blade server market presents a significant service-attach opportunity, with management software and managed services expanding faster than hardware sales. This shift allows vendors to capture recurring revenue streams beyond initial equipment procurement.
For Market Incumbents: Shield core market share by deepening vertical integration into specialized cooling technologies and expanding service level agreement portfolios. Hyper-converged infrastructure presents a substitution threat, necessitating continued R&D in hybrid cloud integration. Control over proprietary management software ecosystems becomes a critical lever against emerging competition.
For New Entrants and Emerging Players: Energy Star certification fast-tracks offer a competitive entry point for specialized blade server modules. Target edge computing deployments for industrial IoT applications, leveraging compact, ruggedized designs. The most penetrable segment involves niche workload optimization, using a direct-to-developer go-to-market angle emphasizing performance per watt.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized component manufacturers and software providers in the blade server ecosystem. Long-term viability hinges on supporting AI and HPC growth through advanced thermal management solutions over the next decade. Acquisition targets include firms with patented liquid cooling technologies or robust management software platforms. The signal to watch is hyperscale cloud provider investment in next-generation data center architectures.
| Strategic Initiative | Industry Significance |
|---|---|
| Liquid Cooling Technology Acquisition | Secures proprietary thermal management expertise crucial for high-density AI workloads. |
| Managed Services Portfolio Expansion | Captures recurring revenue from enterprises transitioning to consumption-based IT models. |
| AI Accelerator Integration R&D | Develops workload-optimized blade modules for rapidly expanding artificial intelligence applications. |
| Edge Computing Product Line Launch | Addresses demand for compact, robust compute resources in industrial IoT and autonomous systems. |
| Supply Chain Resilience Investment | Mitigates risks from component lead times and geopolitical factors affecting critical hardware. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through primary interviews with data center architects, IT procurement officers, and hardware engineers. This primary data was validated against extensive secondary research from SEC filings, industry association reports, and technical publications. The analysis employed both bottom-up and top-down triangulation to ensure robust data integrity across all segments.
The forecast framework extends across the analysis window, integrating historical data with projected trends for blade server product types, end-users, and deployment models. Compound annual growth rates were derived from a multi-factor regression model considering data center expansion and liquid cooling adoption. Key inputs included hyperscale cloud provider capital expenditure plans and energy efficiency regulation timelines.
The analysis sits within stated boundaries; outcomes outside significant geopolitical shifts or unforeseen technological breakthroughs would require recalibration. Forecasts reflect current market assumptions regarding component availability and data center build-out rates. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Global Cloud Computing Data Center IT Asset Disposition (ITAD) Market
Data Center Infrastructure
Taiwan Data Center Power Market
Data Center Infrastructure
Shanghai Data Center Market
Data Center Infrastructure
South America Data Center Market
Data Center Infrastructure
Global Hyper-Converged Infrastructure Market
Data Center Infrastructure
Public Cloud System Infrastructure Service Market
Data Center Infrastructure
Nigeria Data Center Power Market
Data Center Infrastructure
Global Data Center Rack Server Market
Data Center Infrastructure
Hyperscale Data Center Market
Data Center Infrastructure
Data Center Virtualization Market
Data Center Infrastructure
Stockholm Data Center Market
Data Center Infrastructure
China Data Center Construction Market
Data Center Infrastructure
France Data Center Construction Market
Data Center Infrastructure
Server Operating Environments Market
Data Center Infrastructure
China Data Center Power Market
Data Center Infrastructure
Hong Kong Data Center Construction Market