
 India Enteral Feeding Devices Market | 2026-2036
India Enteral Feeding Devices Market Size, Share, and Industry Trends Forecast 2026-2036
India Enteral Feeding Devices Market Foresight
Homecare settings are unwinding the historical dominance of hospital-based enteral feeding in India. Abbott leverages its nutrition science heritage to anchor premium pump portfolios across tertiary care networks. Fresenius SE & Co. KGaA competes through dialysis-to-nutrition cross-selling in chronic care facilities. B. Braun SE differentiates with German-engineered feeding tube safety systems that target super-specialty institutional buyers.
Enteral feeding devices comprise pumps, tubes, gastrostomy kits, and accessories engineered to deliver liquid nutrition directly into the gastrointestinal tract via nasoenteric, gastrostomy, or jejunostomy routes, with flow rates typically calibrated between 1 mL/hr and 300 mL/hr depending on patient tolerance and caloric density. These systems serve patients with functional GI tracts who cannot meet nutritional requirements orally, spanning cancer, critical illness, and neurological impairment. Feeding pumps command the highest margin pool due to software-controlled safety interlocks and alarm systems, while accessories generate recurring revenue through disposable consumption cycles. Bolus delivery is gaining traction in pediatric homecare where caregiver-administered feeding schedules replace continuous hospital protocols.
CDSCO's Medical Device Rules mandate quality management system certification for Class C and D enteral devices, while BIS standards govern electrical safety and electromagnetic compatibility of feeding pumps. The PLI scheme for medical devices is attracting component localization investments that reshape cost structures for domestic assembly. Stakeholders must monitor how state-level procurement centralization in Karnataka and Gujarat alters distributor economics and service-level requirements.
Market Dynamics
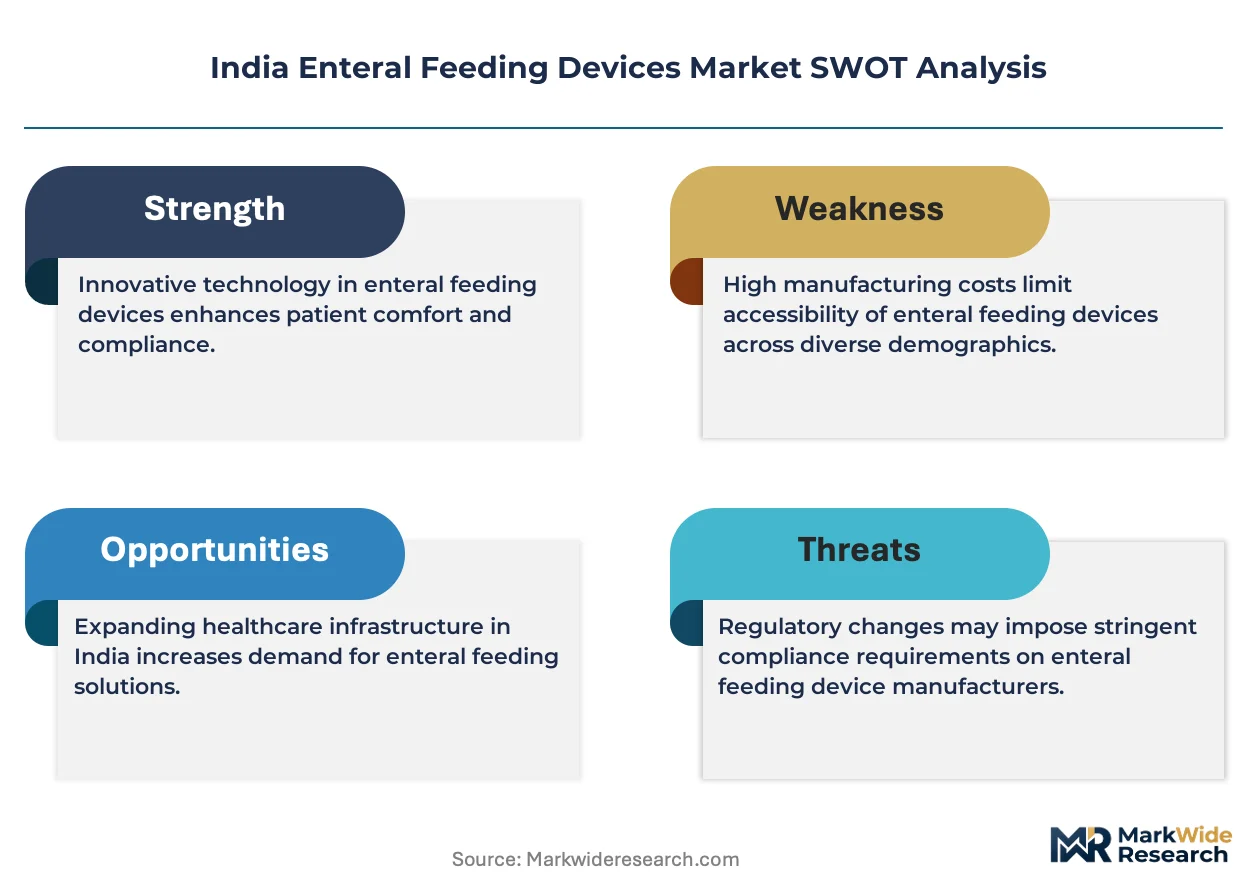
CDSCO's tightened quality certification mandates for Class C and D medical devices are forcing domestic manufacturers to restructure quality management systems and redirect capital toward compliance infrastructure rather than capacity expansion.
Growth Catalysts
- Homecare migration:Post-acute care decentralization from tertiary hospitals to residential settings accelerates demand for portable enteral feeding pumps with extended battery life and simplified caregiver interfaces.
- PLI scheme incentives:India's production-linked incentive scheme for medical devices attracts component localization investments that reduce import dependency for precision pump motors and disposable tubing.
- Chronic disease burden:Rising cancer and neurological impairment prevalence in Maharashtra and Tamil Nadu generates sustained institutional demand for long-term enteral nutrition support.
Market Restraints
- Import concentration:Critical pump electronics and safety sensor modules rely heavily on East Asian suppliers, exposing assemblers to semiconductor availability volatility and currency fluctuation risk.
- CDSCO compliance costs:Mandatory quality management system certification for Class C devices imposes six-figure audit and documentation burdens that exclude smaller domestic manufacturers from institutional procurement pools.
- Silicone tubing price instability:Medical-grade silicone feedstock costs fluctuate with petrochemical feedstock markets, compressing margins on high-volume disposable accessories.
Strategic Opportunities
- Karnataka procurement centralization:State-level hospital procurement aggregation creates volume consolidation opportunities for device vendors capable of meeting stringent service-level agreements and statewide logistics coverage.
- Pediatric bolus feeding:Caregiver-administered intermittent feeding protocols in home pediatric settings open segments underserved by continuous-flow hospital-centric pump designs.
- BIS-CDSCO convergence:Aligned electrical safety and electromagnetic compatibility standards streamline dual certification pathways, reducing time-to-market for next-generation pump platforms.
Industry Challenges
- Biomedical technician scarcity:Specialized pump calibration and alarm troubleshooting expertise concentrates in tier-1 city hospital clusters, limiting service penetration into tier-2 and tier-3 homecare markets.
- Legacy system integration:New smart pump platforms with wireless connectivity and electronic health record interoperability face adoption friction in hospital networks running outdated infrastructure.
- Disposable supply chain reconfiguration:Domestic tubing and connector manufacturing scale-up lags behind pump assembly localization, creating mismatched inventory cycles and working capital strain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Enteral Feeding Devices Market |
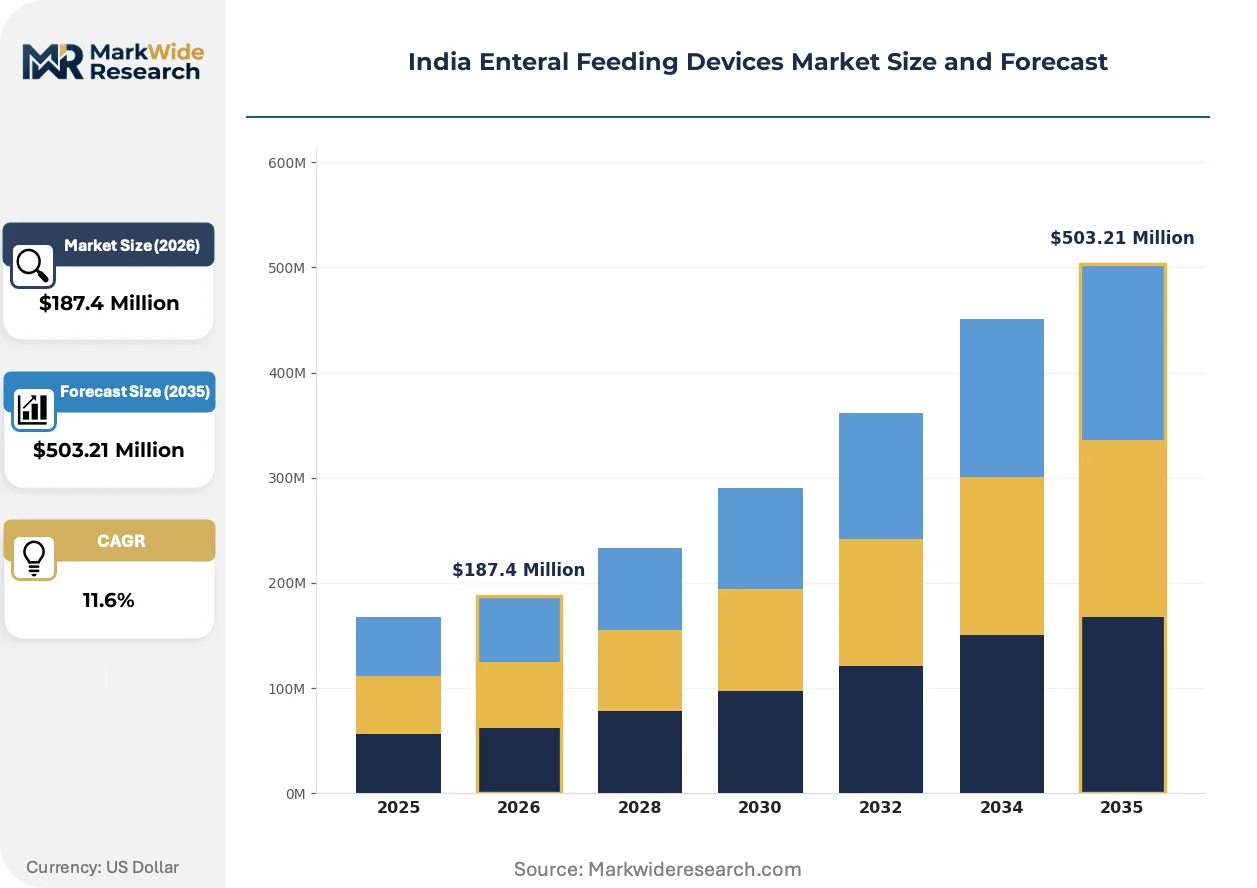
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Enteral Feeding Pumps, Feeding Tubes, Gastrostomy Devices, Accessories Delivery Mode: Continuous Delivery, Intermittent Delivery, Bolus Delivery, Gravity Delivery End User: Hospitals, Homecare, Rehabilitation Centers, Long-term Care Facilities Application: Malnutrition, Cancer Care, Critical Care, Neurological Disorders |
| Companies Covered | Abbott, B. Braun SE, Boston Scientific Corporation, Fresenius SE & Co. KGaA, Nestlé, BD (Becton, Dickinson and Company), Cardinal Health, CONMED Corporation, Cook Medical Incorporated, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Enteral Feeding Devices Market Shifts & Advancements
Software-defined safety architectures and connected health capabilities are redefining competitive differentiation in enteral feeding devices, shifting value capture from hardware durability toward data-enabled clinical decision support.
Smart enteral feeding pumps with integrated occlusion detection algorithms and wireless connectivity to hospital information systems are supplanting electromechanical pumps with basic alarm functions. Super-specialty tertiary care networks in Maharashtra and Tamil Nadu prioritize these platforms for ICU nutrition protocols. The technology is compressing service revenue models toward subscription-based software maintenance and remote monitoring contracts rather than transactional equipment sales.
CDSCO's 2017 Medical Device Rules amendment tightened adverse event reporting timelines and post-market surveillance obligations for Class C enteral devices. Manufacturers must now maintain vigilance systems capable of capturing and analyzing device malfunctions across distributed hospital installations. The regulation most affects pump vendors with legacy installed bases lacking remote diagnostics capabilities, forcing retrofit investments or accelerated replacement cycles.
Hospital procurement committees increasingly unbundle enteral feeding pump purchases from disposable supply contracts, reversing historical bundled pricing arrangements. Large hospital networks in Gujarat and Karnataka negotiate pump hardware through capital equipment tenders while sourcing tubes and accessories via separate consumables frameworks. This bifurcation pressures vendors to defend margin positions across two distinct competitive arenas rather than cross-subsidizing hardware with disposable volume commitments.
India Enteral Feeding Devices Market Segmentation
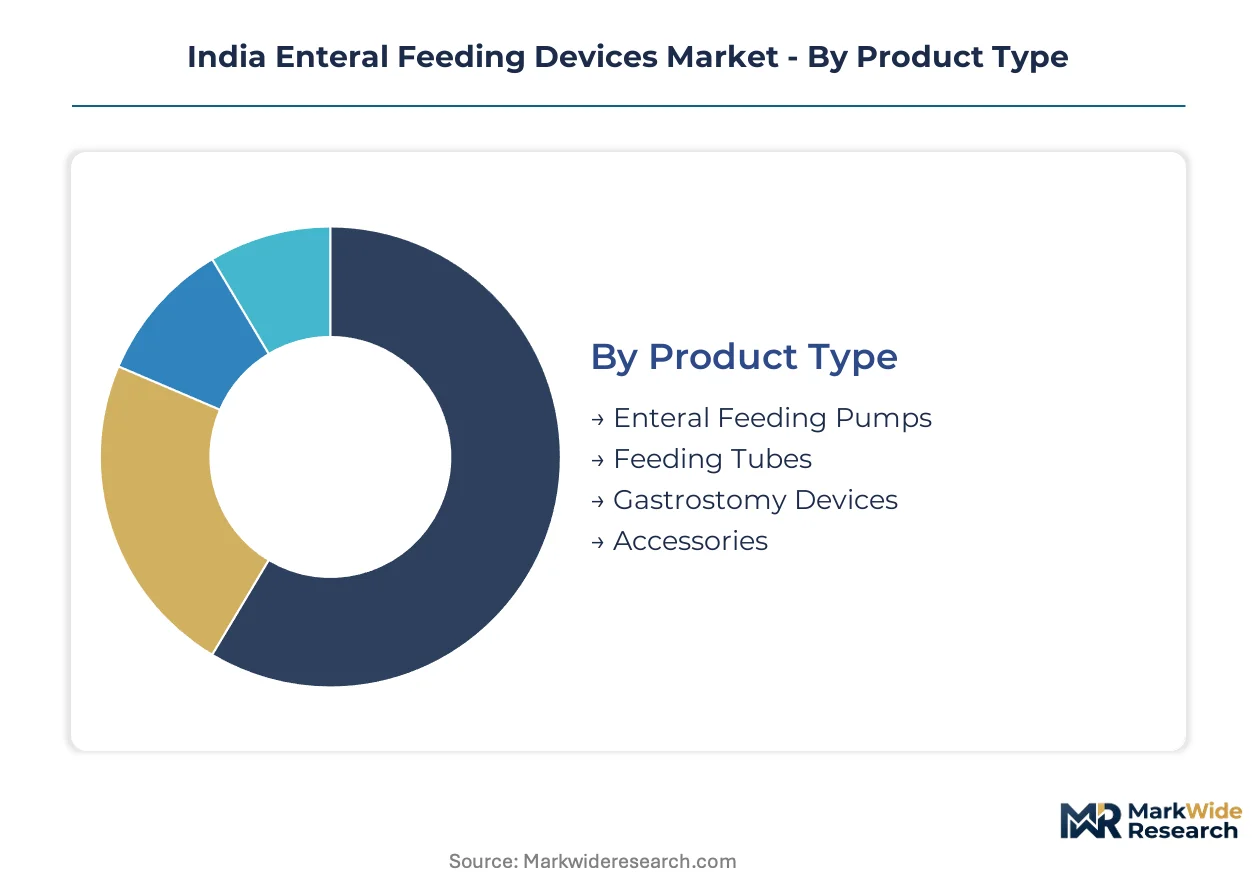
Enteral feeding device segmentation in India reflects divergent channel economics between institutional procurement and homecare retail. Product specifications, delivery protocols, and end-user settings each create distinct margin profiles and service requirements that shape vendor strategies across Maharashtra's hospital clusters and Tamil Nadu's production corridors.
Product Type:
Pumps flow through capital equipment tenders with multi-year service contracts, while tubes and accessories route through high-frequency consumables procurement with working capital intensity.
- Enteral Feeding Pumps:Software-controlled delivery systems with occlusion detection algorithms and programmable flow rates between 1 mL/hr and 300 mL/hr. Demand concentrates in Maharashtra's tertiary ICU networks where CDSCO Class C certification requirements filter vendor pools to quality-compliant manufacturers.
- Feeding Tubes:Silicone or polyurethane nasoenteric, gastrostomy, and jejunostomy tubes sized by French gauge. Tamil Nadu's medical device production corridors are scaling domestic tubing extrusion capacity under PLI scheme incentives to reduce import dependency.
- Gastrostomy Devices:Percutaneous endoscopic gastrostomy kits comprising introducer needles, retention balloons, and external bolsters. Karnataka's centralized hospital procurement aggregates volume for button-style low-profile devices.
- Accessories:Syringes, extension sets, connectors, and carrying cases forming recurring revenue streams. Homecare channels in Gujarat drive demand for portable pump backpacks and battery replacements.
Enteral feeding pumps dominate installed base. Accessories represent where expansion concentrates as homecare volumes multiply disposable consumption cycles.
Delivery Mode:
Cost tier separation runs deep: continuous systems command premium pricing for ICU precision, while gravity and bolus methods serve price-sensitive homecare segments.
- Continuous Delivery:Electromechanical or smart pump-driven 24-hour nutrition administration with alarm interlocks for occlusion and empty container detection. Critical care wards in Maharashtra's super-specialty hospitals specify these systems for hemodynamically unstable patients requiring steady caloric input.
- Intermittent Delivery:Programmed pump cycles mimicking meal schedules over 30-60 minute intervals. Rehabilitation centers in Tamil Nadu favor this modality for patients transitioning from hospital to home protocols.
- Bolus Delivery:Manual syringe or gravity-assisted rapid infusion mimicking oral meal volumes. Pediatric homecare in Karnataka is climbing the fastest as caregiver-administered feeding reduces device dependency.
- Gravity Delivery:Height-differential flow without electromechanical components, using roller clamps for rate adjustment. Long-term care facilities in Gujarat specify these for cost containment in stable chronic patients.
Continuous delivery commands margin concentration. Bolus delivery is where expansion concentrates as pediatric homecare protocols proliferate.
End User:
Customer type determines service intensity: hospitals demand 4-hour response SLAs, while homecare prioritizes remote troubleshooting and caregiver training.
- Hospitals:Tertiary and secondary care institutions with biomedical engineering departments and centralized sterilization facilities. Maharashtra's Mumbai-Pune hospital corridor generates concentrated demand for ICU-integrated smart pumps with wireless connectivity.
- Homecare:Residential settings with family caregivers or visiting nurses managing enteral nutrition. Tamil Nadu's Chennai metropolitan area is expanding fastest as post-acute discharge protocols accelerate.
- Rehabilitation Centers:Post-stroke and trauma recovery facilities with transitional feeding protocols. Karnataka's Bangalore cluster specializes in neuro-rehabilitation enteral weaning programs.
- Long-term Care Facilities:Nursing homes and assisted living centers managing chronic neurological conditions. Gujarat's Ahmedabad-Surat corridor aggregates procurement for stable geriatric populations.
Hospitals dominate installed base. Homecare is where expansion concentrates as reimbursement shifts favor residential post-acute care.
Application:
Clinical indication drives specification intensity: cancer and critical care demand precision pumps, while neurological cases span the full product spectrum.
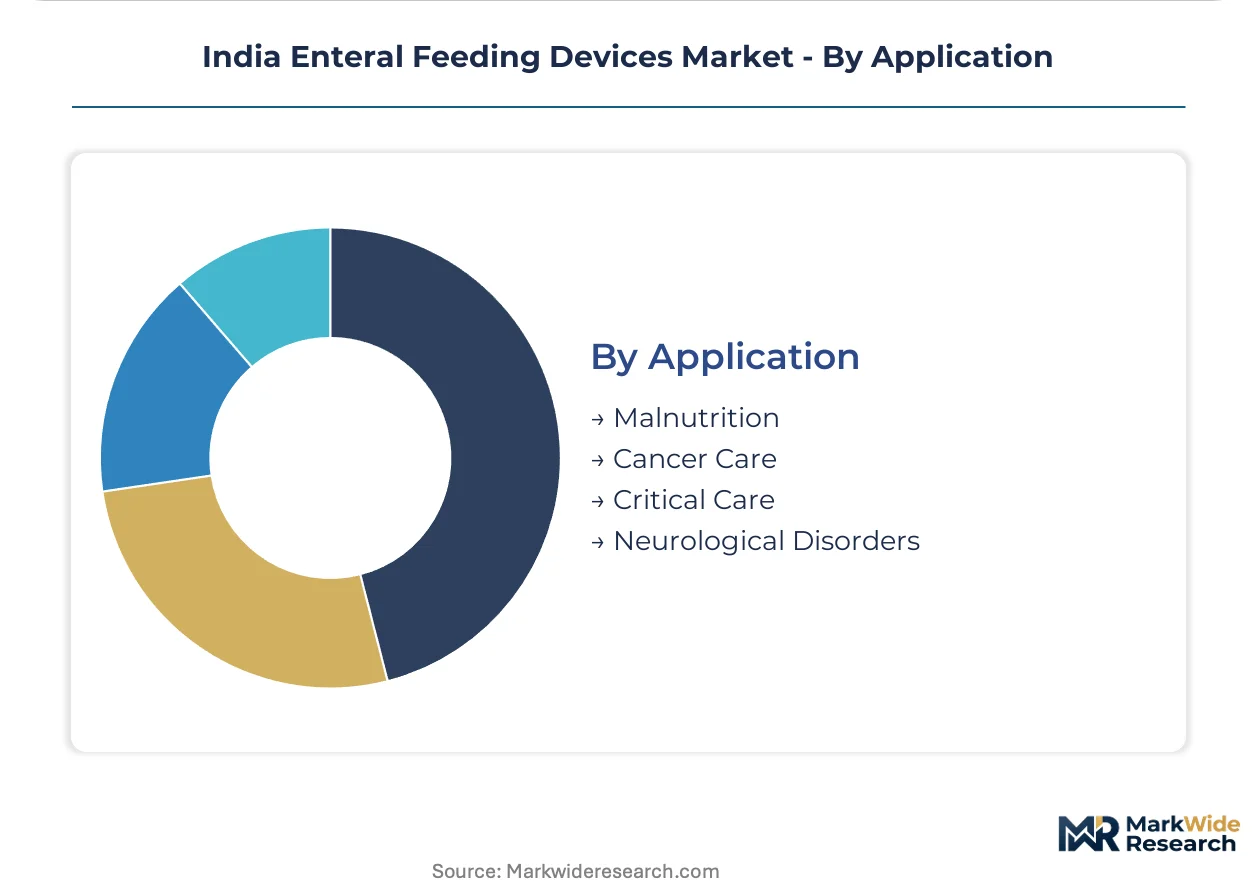
- Malnutrition:Protein-energy malnutrition and micronutrient deficiency requiring caloric repletion via enteral route. Pediatric wards in Maharashtra's government hospitals specify high-osmolarity formula compatibility for severe wasting protocols.
- Cancer Care:Head and neck malignancies and gastrointestinal obstructions preventing oral intake. Tamil Nadu's comprehensive cancer centers drive demand for ambulatory pumps enabling chemotherapy-compatible nutrition.
- Critical Care:ICU patients with intact GI function but compromised consciousness or mechanical ventilation. Karnataka's private hospital networks specify dual-chamber pumps for simultaneous enteral and medication delivery.
- Neurological Disorders:Stroke, dementia, and motor neuron disease with dysphagia and aspiration risk. Gujarat's long-term care corridor generates sustained demand across the full pump-to-gravity product range.
Critical care commands technology premium. Cancer care is where expansion concentrates as oncology infrastructure expands beyond tier-1 cities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Jawaharlal Nehru Port Trust anchors Maharashtra's dominance in medical device distribution, connecting Mumbai-Pune hospital clusters to global supply chains for precision pump electronics and silicone feedstock.
Maharashtra
Mumbai's super-specialty tertiary care networks drive concentrated demand for ICU-integrated smart pumps with wireless connectivity. CDSCO's Class C certification requirements filter vendor participation in government hospital tenders. The Pune-Aurangabad corridor hosts domestic assembly operations for feeding tube connectors under PLI scheme incentives.
Tamil Nadu
Chennai's comprehensive cancer centers generate sustained institutional demand for ambulatory pumps enabling chemotherapy-compatible nutrition protocols. BIS electrical safety standards govern pump electromagnetic compatibility testing at regional certification laboratories. The Sriperumbudur-Oragadam medical device production corridor scales domestic silicone tubing extrusion capacity.
Karnataka
Bangalore's neuro-rehabilitation facilities specialize in enteral weaning programs for post-stroke patients transitioning to homecare protocols. State-level hospital procurement centralization aggregates volume for button-style low-profile gastrostomy devices. The city's biomedical engineering talent pool supports pump calibration service networks extending into tier-2 districts.
Gujarat
Ahmedabad-Surat long-term care corridors aggregate procurement for stable geriatric populations requiring gravity delivery systems. CDSCO's tightened adverse event reporting timelines accelerate vigilance system investments among regional distributors. The Mundra Port facilitates silicone feedstock imports for domestic tubing manufacturers.
Delhi-NCR
Central government hospital networks in the capital region specify dual-chamber pumps for simultaneous enteral and medication delivery in critical care wards. CDSCO headquarters proximity enables faster regulatory consultation for device registration applications. Gurugram's emerging medical device parks attract pump assembly investments targeting northern India distribution.
India Enteral Feeding Devices Market Competitive Landscape
Listed leaders compete with private specialists across certification compliance and service infrastructure dimensions. The vendor base stratifies between multinational corporations with established CDSCO registration portfolios and domestic assemblers leveraging PLI scheme incentives for component localization. Three archetypes dominate: nutrition science conglomerates with cross-portfolio hospital relationships, German-engineered precision specialists targeting super-specialty buyers, and diversified medical technology groups with dialysis-to-nutrition cross-selling capabilities. Competitive moves concentrate on procurement unbundling responses and software subscription model transitions.
Within the nutrition-heritage tier, Abbott and Nestlé exemplify conglomerate positioning anchored in clinical nutrition science credentials. Among German-engineered specialists, B. Braun SE and Fresenius SE & Co. KGaA occupy positions emphasizing precision manufacturing heritage and chronic care facility relationships respectively. Boston Scientific Corporation represents the diversified medical technology archetype with endoscopic placement system integration capabilities.
| Leading Market Players |
|---|
| Abbott |
| B. Braun SE |
| Boston Scientific Corporation |
| Fresenius SE & Co. KGaA |
| Nestlé |
| BD (Becton, Dickinson and Company) |
| Cardinal Health |
| CONMED Corporation |
| Cook Medical Incorporated |
| Others |
Supply & Pricing Matrix
CDSCO's Class C and D device certification regime gates both supplier qualification and price differentiation simultaneously, compressing domestic manufacturers into compliance-heavy cost structures while multinational incumbents capture premium positioning through pre-certified installed bases. The regulatory threshold fragments vendor pools into quality-tiered pricing bands that reward CDSCO-registered importers and penalize smaller assemblers lacking audit infrastructure.
Pricing Analysis
Volume-discount tiering structures separate Maharashtra's government hospital tenders from Tamil Nadu's private oncology networks, with the former extracting 15-20% price concessions on pump hardware through centralized procurement aggregation. Three-tier pricing stratifies across German-engineered premium pumps, Korean-standard mid-tier systems, and domestic economy gravity sets. Price differentiation hinges on CDSCO registration status and wireless connectivity capability. Cost compression in the economy tier intensifies as PLI scheme beneficiaries scale tubing assembly. Homecare segments exhibit highest price sensitivity due to out-of-pocket caregiver expenditure, while ICU procurement committees prioritize alarm reliability over unit cost.
Supply Chain Analysis
Jawaharlal Nehru Port congestion and container availability volatility on the East Asia-India trade lane inflate inbound logistics costs for precision pump motors and sensor modules sourced from South Korea, Japan, and Taiwan. Critical electronics feedstock draws from East Asian semiconductor clusters, while medical-grade silicone tubing extrusion feeds from Thailand and Malaysia. Single-source vulnerability concentrates in stepper motor controllers and occlusion detection sensors. Distribution runs through Maharashtra's hospital cluster distributors for institutional sales and Tamil Nadu's homecare retail channels for patient-direct accessories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's enteral feeding device market sits at a high-growth inflection as CDSCO's 2017 Medical Device Rules amendment forces compliance investments that reshape competitive moats around quality certification rather than manufacturing scale alone.
For Market Incumbents: Compound installed base advantages by retrofitting legacy pumps with remote diagnostics modules that satisfy tightened adverse event reporting timelines, while acquiring distressed domestic assemblers to capture PLI scheme localization incentives and deny component supply to emerging competitors. For New Entrants and Emerging Players: Differentiate on pediatric bolus feeding system design for Karnataka's expanding homecare market, where caregiver-administered protocols remain underserved by continuous-flow hospital-centric platforms. Target neuro-rehabilitation centers in Bangalore with simplified weaning-program interfaces, bypassing Maharashtra's saturated ICU procurement committees through direct-to-patient rental models. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across disposable accessories manufacturing as domestic silicone tubing extrusion scales under PLI incentives, improving return thresholds for component-focused acquisition targets. Long-term viability over a 5-10 year window favors CDSCO-registered assemblers with backward-integrated tubing capacity. The signal to watch is BIS-CDSCO standard convergence accelerating dual-certification timelines for next-generation pump platforms.| Strategic Initiative | Industry Significance |
|---|---|
| CDSCO Class C Certification Investment | Quality management system audits unlock government hospital procurement pools in Maharashtra and Karnataka. |
| Silicone Tubing Backward Integration | In-house extrusion capacity under PLI scheme reduces import dependency and working capital cycles. |
| Software Subscription Transition | Remote monitoring contracts shift revenue from transactional hardware sales toward recurring service streams. |
| Pediatric Bolus System Development | Caregiver-administered feeding protocols capture expansion in Karnataka's homecare discharge pathways. |
| State Procurement Centralization Partnership | Karnataka and Gujarat volume aggregation agreements secure multi-year installed base commitments. |
Research Methodology
Cross-validation between primary interviews with hospital biomedical engineers, GPO contracts managers, and CDSCO regulatory consultants anchors the qualitative findings against secondary validation from hospital procurement databases, BIS certification records, and PLI scheme disclosure filings. Bottom-up triangulation aggregates state-level tender volumes and distributor shipment data, while top-down approaches benchmark against macro healthcare infrastructure spending patterns. The analysis integrates continuous delivery modality adoption rates with homecare discharge protocol expansion metrics.
Sensitivity analysis around semiconductor availability volatility and silicone feedstock price scenarios frames the analytical approach across the projection horizon. Segmentation dimensions modeled include product type, delivery mode, end-user setting, and application indication, with regional regulatory cluster differentiation. CAGRs derive from fitted growth curves adjusted for PLI scheme incentive phase-ins and CDSCO compliance cost trajectories. Forecast inputs incorporate cancer incidence projections and neuro-rehabilitation bed capacity expansion in tier-2 cities.
Material uncertainties — supply chain disruption, regulatory enforcement intensity variation, and reimbursement policy shifts — sit outside the modeled envelope. Forecasts reflect documented assumptions about PLI scheme continuity and BIS-CDSCO standard alignment timelines. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Sinus Irrigation Systems Market
Medical Devices
Global Electromyography Devices Market
Medical Devices
United Kingdom General Surgical Devices Market
Medical Devices
Light Therapy Beauty Devices Market
Medical Devices
US Orthopedic Spine Navigation Systems Market
Medical Devices
Assisted Walking Devices Market
Medical Devices
Global Uterine Manipulation Devices Market
Medical Devices
Global Insufflation Devices Market
Medical Devices
Acellular Dermal Matrix Market
Medical Devices
Global Body Composition Analyzers Market
Medical Devices
Cardiac Implants Market
Medical Devices
ECG Patch and Holter Monitor Market
Medical Devices
Medical Devices Vigilance Market
Medical Devices
Australia Aesthetic Devices Market
Medical Devices
Pulmonary Heart Valve Replacement Market
Medical Devices
Baby Thermometer Market