
 Global Obstetrics Devices Market | 2026-2036
Global Obstetrics Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Obstetrics Devices Market Foresight
Modular obstetrics device bundles that pair fetal monitors with ultrasound peripherals is expanding buyer flexibility across hospital procurement teams. GE HealthCare leverages its imaging heritage to anchor premium configurations in integrated delivery networks. Philips Healthcare competes through wireless monitoring ecosystems that extend across prenatal and intrapartum settings. Hologic Inc. specializes in diagnostic precision within gynecological exam workflows, sustaining channel loyalty among outpatient clinics.
Obstetrics devices encompass instruments and electronic systems designed for fetal assessment, cervical intervention, and maternal monitoring during gestation, delivery, and postpartum recovery, typically incorporating transducer arrays operating at 2-10 MHz for ultrasonic imaging and pressure-sensitive electromechanical sensors for uterine contraction measurement. Their primary commercial purpose centers on reducing perinatal morbidity through real-time physiological surveillance and operative assistance. Fetal monitors and ultrasound devices occupy the dominant margin pool as capital-intensive digital imaging platforms command replacement cycles and service contracts. Wireless monitoring and non-invasive sensors represent the fastest-expanding technology dimension, displacing wired legacy systems in ambulatory and home-based prenatal care settings. Electromechanical instruments including labor forceps and cervical dilators remain structurally mature, with price competition concentrated among manufacturers serving public hospital tenders.
FDA premarket notification requirements for obstetric ultrasound and fetal monitor systems shape product development timelines and predicate device selection strategies for US market entrants, while CE marking under the EU MDR imposes clinical evidence thresholds that filter smaller manufacturers from European distribution. China's NMPA classification rules for maternal-fetal monitoring equipment create a separate conformity pathway that favors domestic producers with established GB standard compliance. Stakeholders must monitor evolving cybersecurity guidance for wireless perinatal sensors as connectivity becomes standard across all price tiers.
Market Dynamics
Wireless fetal monitoring systems are displacing wired legacy infrastructure across hospital maternity wards and birthing centers, compressing replacement cycles and forcing incumbent manufacturers to reconfigure hardware-software bundles around connectivity rather than standalone device margins.
Growth Catalysts
- FDA 510(k) Clearance Streamlining:The FDA's premarket notification pathway for non-invasive obstetric sensors accelerates product entry timelines, enabling faster commercialization of wearable fetal monitors in the United States.
- Reimbursement Framework Alignment:Germany's statutory health insurance system codes digital prenatal monitoring as reimbursable preventive care, directing capital allocation toward Doppler ultrasound platforms in integrated delivery networks.
- Home-Based Prenatal Surveillance:Remote patient monitoring protocols adopted by United States health systems during the pandemic have institutionalized ambulatory fetal assessment, sustaining demand for Bluetooth-enabled contraction sensors.
Market Restraints
- Semiconductor Supply Concentration:Taiwan-based foundries fabricate the majority of MEMS pressure sensors used in uterine contraction transducers, exposing device manufacturers to geopolitical disruption risk.
- EU MDR Clinical Evidence Thresholds:CE marking under the EU Medical Device Regulation demands prospective clinical studies for wireless perinatal sensors, filtering smaller manufacturers from European distribution channels.
- Substitute Modalities:Maternal-fetal medicine specialists increasingly rely on MRI for complex anomaly screening, constraining addressable volume for high-end ultrasound platforms in tertiary referral centers.
Strategic Opportunities
- Underpenetrated Rural China:County-level hospitals in Henan and Sichuan provinces lack continuous electronic fetal monitoring capacity, creating whitespace for portable, battery-operated systems at price points below imported equipment.
- Convergence of AI and Ultrasound:Deep learning algorithms trained on fetal biometric datasets enable automated measurement of nuchal translucency and femur length, reducing operator dependency in high-throughput screening workflows.
- India's PLI Scheme for Medical Devices:Production-linked incentives for domestic manufacturing of electronic diagnostic equipment reduce landed cost disadvantages for NMPA-compliant Chinese and Korean competitors establishing local assembly.
Industry Challenges
- Cybersecurity Certification Complexity:Wireless perinatal sensors must satisfy FDA guidance on premarket cybersecurity submissions while simultaneously meeting IEC 81001-5-1 requirements, extending validation timelines by 8-14 months.
- Integration Friction with Legacy EMR:Hospital IT departments face middleware development costs to connect cloud-based fetal monitoring platforms to on-premise electronic medical record systems running 1990s-era HL7 interfaces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Obstetrics Devices Market |
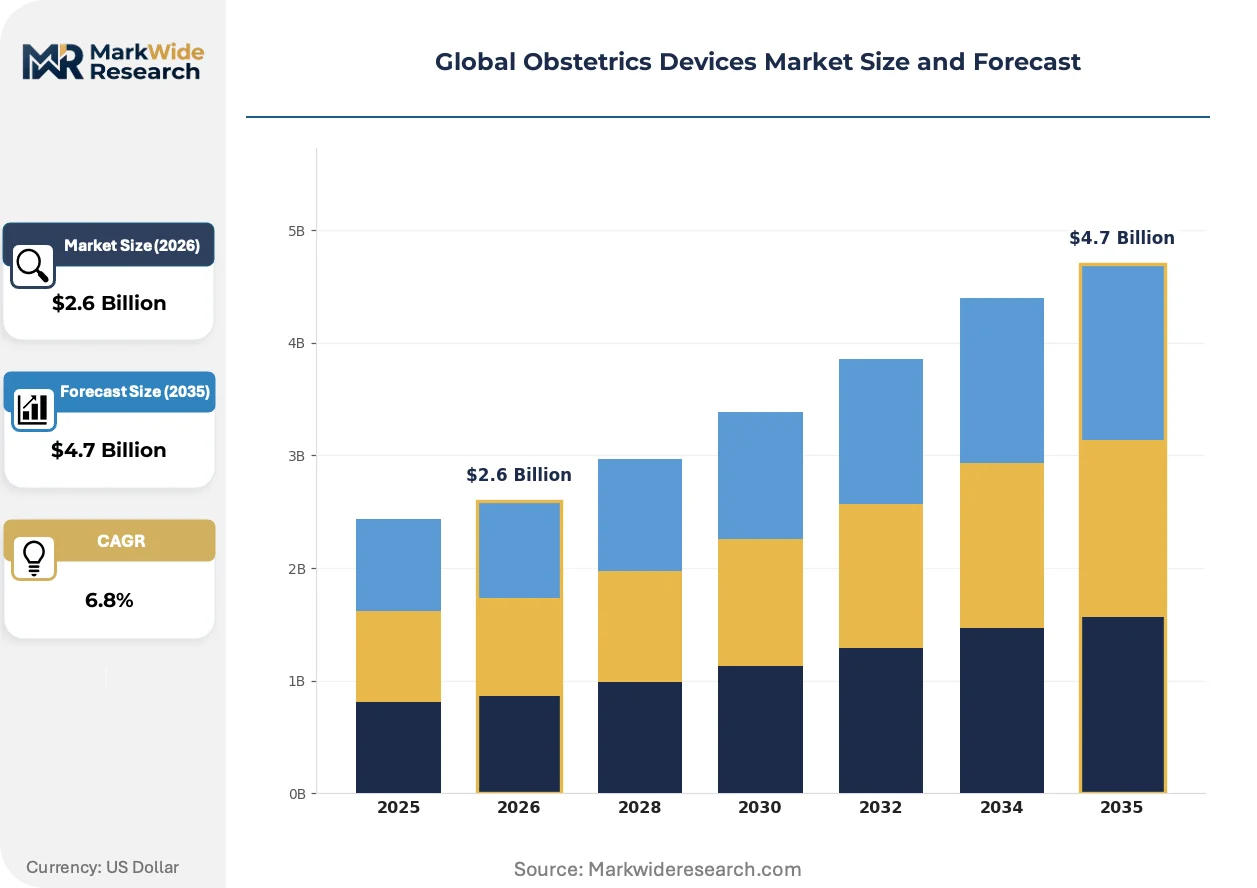
| Market Size in 2026 | $2.6 Billion |
| Market Size in 2035 | $4.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fetal Monitors, Ultrasound Devices, Labor Forceps, Amniotomy Instruments, Cervical Dilators Application: Prenatal Care, Intrapartum Monitoring, Postpartum Care, Fertility Procedures, Gynecological Exams End User: Birthing Centers, Maternity Clinics, Diagnostic Laboratories, Midwifery Services, Fertility Centers Technology: Digital Imaging, Non-invasive Sensors, Wireless Monitoring, Doppler Ultrasound, Electromechanical Instruments |
| Companies Covered | GE HealthCare, Philips Healthcare, Medtronic plc, Olympus Corporation, CooperSurgical, Boston Scientific Corporation, Hologic Inc., Stryker Corporation, Mindray Medical International Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Obstetrics Devices Market Shifts & Advancements
Obstetrics device architecture is fragmenting from monolithic capital platforms into configurable subsystems, enabling procurement teams to source transducers, software, and analytics modules from competing vendors rather than locked single-source contracts.
Sensor miniaturization and edge computing is modularizing fetal monitor design, allowing hospital biomedical engineering departments to swap ultrasound transducer heads, tocodynamometer arrays, and wireless telemetry packs across different manufacturer bases. Mid-tier regional hospitals in Spain and Italy now assemble customized monitoring stations from CE-marked subcomponents rather than purchasing integrated suites. This interoperability is compressing service contract margins for incumbent full-stack suppliers while expanding addressable market for specialized sensor OEMs.
China's NMPA issued technical review guidelines for artificial intelligence-assisted obstetric ultrasound in 2023, establishing clinical validation requirements for algorithms performing fetal biometry and anatomical survey. Domestic manufacturers including Mindray and Edan Instruments have restructured R&D roadmaps around prospective multicenter trials to secure Class III registration for AI-embedded systems. The regulation is accelerating consolidation among software-only AI developers lacking in-house ultrasound hardware platforms.
Birthing center administrators increasingly unbundle device acquisition from long-term service agreements, negotiating separate contracts for preventive maintenance, software updates, and clinical training. This disintermediation of the traditional capital-plus-service bundle is most pronounced in the United Kingdom's NHS Foundation Trusts, where procurement frameworks now mandate three-year total cost of ownership comparisons rather than upfront capital expenditure evaluation. Independent service organizations are capturing aftermarket revenue previously retained by original equipment manufacturers.
Global Obstetrics Devices Market Segmentation
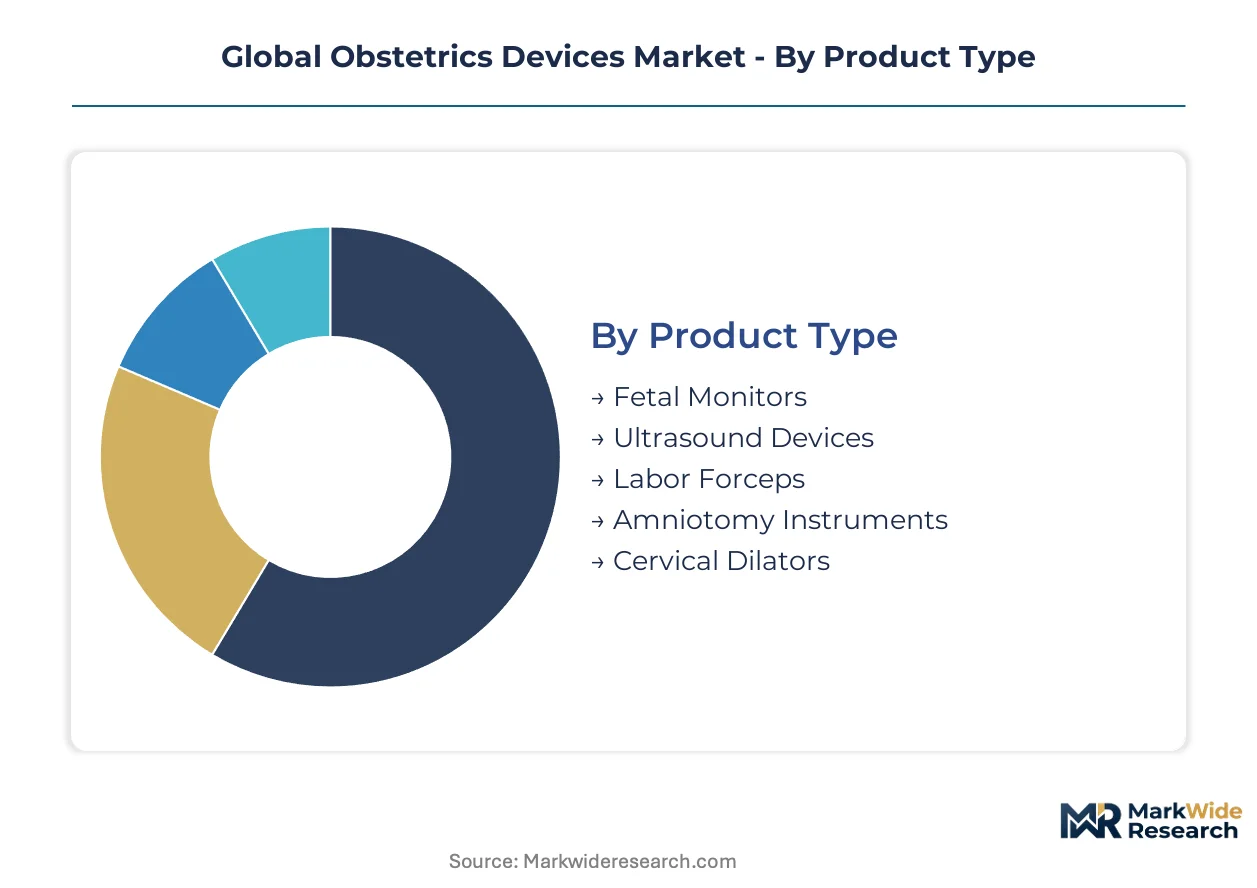
Device segmentation in obstetrics reveals divergent margin profiles across capital-intensive imaging platforms and commoditized mechanical instruments. Procurement patterns vary sharply between integrated hospital networks seeking bundled digital ecosystems and standalone birthing centers prioritizing portable, interoperable subsystems.
Product Type:
Volume concentration sits with fetal monitors and ultrasound devices, while mechanical instruments compete on price in public tender environments.
- Fetal Monitors:Electronic systems integrating tocodynamometer arrays for uterine contraction measurement and transducer heads for fetal heart rate detection. Hospital maternity wards in the United States and Germany dominate procurement, driven by replacement cycles compressing from seven to four years as wireless telemetry becomes standard.
- Ultrasound Devices:Imaging platforms operating at 2-10 MHz for fetal biometry, anatomical survey, and anomaly screening. Tertiary referral centers in China concentrate demand for premium configurations, though MRI substitution constrains addressable volume for high-end systems in complex cases.
- Labor Forceps:Stainless steel obstetric instruments for operative vaginal delivery. Public hospital tenders in India and Brazil sustain price-competitive manufacturing clusters.
- Amniotomy Instruments:Perforators and hooks for artificial membrane rupture during labor induction. Midwifery services in the United Kingdom and Netherlands standardize on single-use disposable variants.
- Cervical Dilators:Mechanical and osmotic devices for cervical ripening. Outpatient clinics in Japan favor hygroscopic laminaria over synthetic alternatives.
Today's leader: Fetal Monitors. Tomorrow's challenger: Ultrasound Devices with embedded AI biometry.
Application:
Revenue gravity pulls toward intrapartum and prenatal settings where continuous monitoring commands premium pricing.
- Prenatal Care:First and second-trimester screening, fetal biometry, and maternal risk assessment workflows. Ambulatory expansion in the United States institutionalizes remote monitoring protocols adopted during the pandemic.
- Intrapartum Monitoring:Continuous fetal heart rate and uterine contraction surveillance during labor and delivery. Wireless systems displace wired legacy infrastructure across hospital maternity wards, compressing replacement cycles.
- Postpartum Care:Uterine involution assessment, hemorrhage detection, and lactation support. Birthing centers in Germany bundle postpartum monitoring into statutory preventive care reimbursement.
- Fertility Procedures:Ultrasound-guided oocyte retrieval and embryo transfer. Fertility centers in Spain and Italy concentrate demand for high-frequency transvaginal probes.
- Gynecological Exams:Cervical visualization, biopsy guidance, and IUD placement. Outpatient clinics sustain channel loyalty for diagnostic precision platforms.
Intrapartum Monitoring captures current margin concentration. Prenatal Care gains share fastest as home-based surveillance protocols mature.
End User:
Procurement authority fragments across centralized hospital networks and distributed independent facilities with divergent technical specifications.
- Birthing Centers:Low-intervention delivery facilities emphasizing physiological birth. NHS Foundation Trusts in the United Kingdom mandate three-year total cost of ownership comparisons, unbundling device acquisition from service agreements.
- Maternity Clinics:Dedicated obstetric facilities within integrated delivery networks. China's county-level hospitals in Henan and Sichuan provinces lack continuous electronic fetal monitoring capacity.
- Diagnostic Laboratories:Centralized prenatal screening and genetic testing services. Germany's statutory health insurance system directs capital toward Doppler ultrasound platforms.
- Midwifery Services:Community-based prenatal and intrapartum care. Netherlands and United Kingdom midwife-led units prioritize portable, battery-operated systems.
- Fertility Centers:Assisted reproductive technology clinics requiring precision imaging. Spain's private fertility sector sustains premium ultrasound demand.
Maternity Clinics anchor volume procurement today. Birthing Centers represent the steepest expansion trajectory as unbundled purchasing spreads.
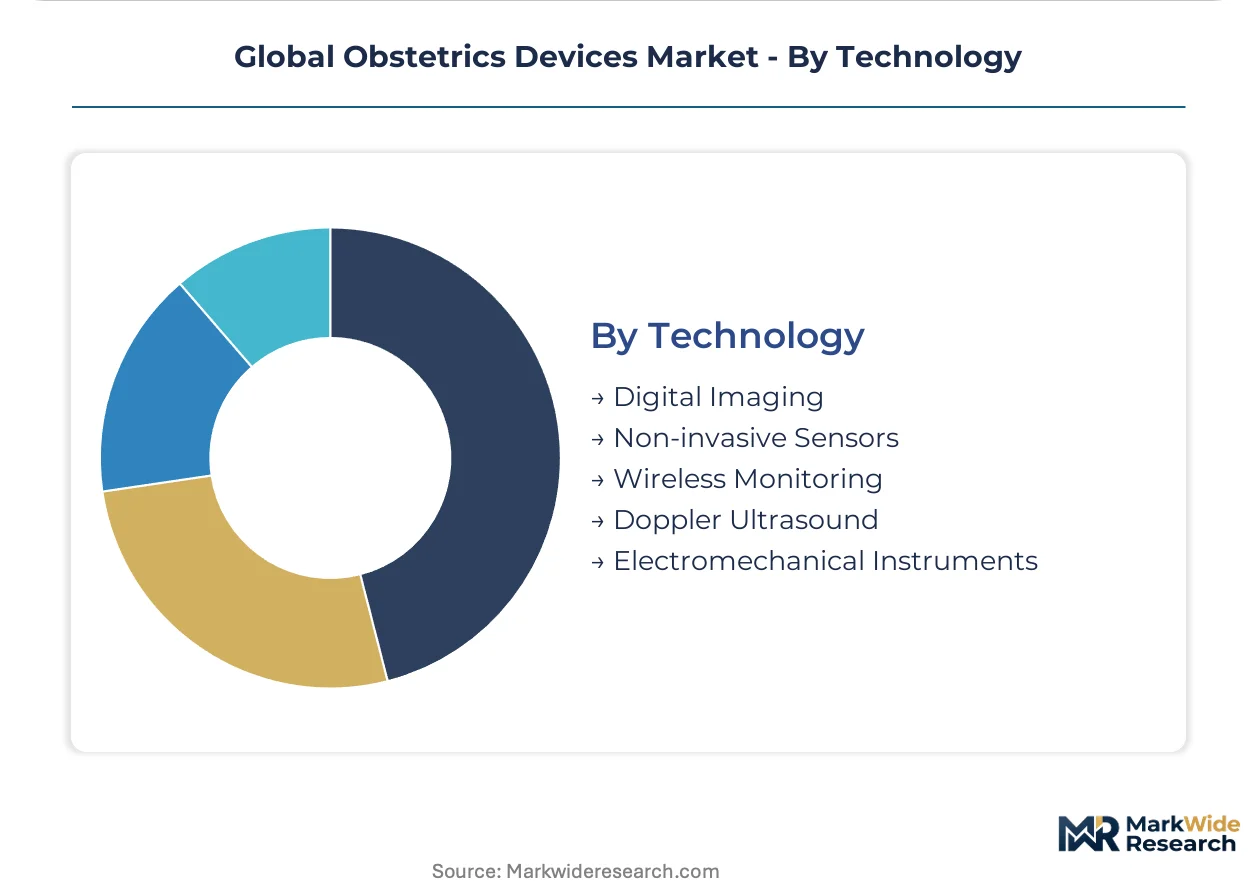
Technology:
Digital and wireless modalities command margin premiums while electromechanical instruments face structural commoditization.
- Digital Imaging:High-resolution ultrasound platforms with automated measurement algorithms. FDA premarket notification requirements shape development timelines for US market entrants.
- Non-invasive Sensors:Wearable fetal monitors and maternal physiology trackers. CE marking under EU MDR demands prospective clinical studies, filtering smaller manufacturers.
- Wireless Monitoring:Bluetooth-enabled telemetry systems for ambulatory and home-based care. United States health systems institutionalized remote patient monitoring protocols.
- Doppler Ultrasound:Frequency-shift detection for fetal heart rate and blood flow assessment. Germany's reimbursement framework codes digital prenatal monitoring as preventive care.
- Electromechanical Instruments:Forceps, vacuum extractors, and mechanical dilators. Public hospital tenders concentrate price competition among manufacturers serving India and Brazil.
Digital Imaging leads margin capture currently. Wireless Monitoring climbs fastest as cybersecurity certification complexity resolves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The obstetrics devices industry traces its commercial roots to post-war medical electronics development in the United States and Germany, where fetal heart rate monitoring systems first achieved hospital standardization. Wireless telemetry and AI-embedded ultrasound now drive geographic expansion beyond these founding markets.
United States
FDA 510(k) clearance pathways for non-invasive obstetric sensors accelerate wearable fetal monitor commercialization. Remote patient monitoring protocols institutionalized during the pandemic sustain ambulatory care demand. Hospital networks in California and Texas concentrate procurement of Bluetooth-enabled contraction sensors.
Germany
Statutory health insurance reimbursement codes digital prenatal monitoring as preventive care, directing capital toward Doppler ultrasound platforms. CE marking under EU MDR imposes clinical evidence thresholds that reshape competitive entry. Integrated delivery networks in Bavaria and North Rhine-Westphalia anchor premium system procurement.
China
NMPA technical review guidelines for AI-assisted obstetric ultrasound establish validation requirements for fetal biometry algorithms. County-level hospitals in Henan and Sichuan provinces lack continuous electronic fetal monitoring capacity, creating whitespace for portable systems. Domestic manufacturers in Shenzhen and Shanghai restructure R&D around multicenter trials.
India
Production-linked incentive schemes for medical device manufacturing reduce landed cost disadvantages for electronic diagnostic equipment. Public hospital tenders sustain price-competitive manufacturing clusters for mechanical instruments. Device assembly operations concentrate in Maharashtra and Gujarat medical technology corridors.
United Kingdom
NHS Foundation Trust procurement frameworks mandate three-year total cost of ownership comparisons, unbundling device acquisition from service agreements. Midwife-led units prioritize portable, battery-operated systems for community-based care. London and Southeast England birthing centers lead adoption of modular monitoring subsystems.
Global Obstetrics Devices Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology intensity, with full-stack imaging platforms commanding service contract premiums while electromechanical instrument manufacturers compete on tender price. The vendor base organizes into three archetypes: diversified health technology conglomerates anchoring integrated delivery networks, specialized diagnostics firms occupying outpatient clinic channels, and regional manufacturers capturing public hospital tenders through cost positioning. Dominant competitive moves include portfolio modularization to unbundle hardware-software-service packages and geographic licensing partnerships to satisfy NMPA and FDA conformity pathways without direct market establishment.
Within the diversified conglomerate tier, GE HealthCare and Philips Healthcare occupy positions defined by imaging heritage and wireless ecosystem breadth. Hologic Inc. exemplifies the diagnostic precision archetype, sustaining channel relationships through gynecological workflow specialization. Mindray Medical International Limited represents the regional scale-driven competitor, leveraging domestic regulatory compliance and manufacturing proximity to capture county-level hospital procurement in underpenetrated provinces.
| Leading Market Players |
|---|
| GE HealthCare |
| Philips Healthcare |
| Medtronic plc |
| Olympus Corporation |
| CooperSurgical |
| Boston Scientific Corporation |
| Hologic Inc. |
| Stryker Corporation |
| Mindray Medical International Limited |
| Others |
Supply & Pricing Matrix
Wireless telemetry miniaturization is compressing manufacturing cost curves while concentrating component sourcing among Taiwan-based MEMS foundries and Shenzhen assembly operations. This dual shift simultaneously erodes hardware margins for legacy device manufacturers and amplifies pricing power for specialized sensor OEMs capable of cross-platform interoperability.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared wireless ecosystems from CE-marked modular configurations and unbranded electromechanical instruments. Price differentiation rests on cybersecurity certification grade and after-sales service bundling. Cost compression in economy-tier mechanical instruments is intensifying because Indian and Brazilian public tenders prioritize lowest-unit-cost award criteria. Birthing centers in the United Kingdom exhibit highest price sensitivity due to unbundled procurement mandates, while tertiary referral centers in Germany show lowest sensitivity where statutory reimbursement insulates capital decisions.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan-based foundries fabricating MEMS pressure sensors for uterine contraction transducers. Component sourcing draws from Taiwan, South Korea, and China for semiconductor inputs, with stainless steel instrument forging concentrated in India and Pakistan. Supply chain risk centers on geopolitical disruption exposure to Taiwan Strait logistics chokepoints. Distribution runs through hospital GPO contracts in the United States, integrated delivery network procurement frameworks in Germany, and county-level hospital tenders in China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where India's PLI scheme for medical device manufacturing creates a 15-20% landed cost advantage versus imported Chinese equipment, redirecting capital flows toward Maharashtra and Gujarat assembly corridors.
For Market Incumbents: Lock in service contract renewals through cybersecurity certification investments that extend validation timelines for challengers. Backward integration into MEMS sensor design reduces Taiwan foundry dependency. Prioritize FDA premarket notification pathway expertise as a barrier against emerging AI-embedded ultrasound developers lacking regulatory infrastructure.
For New Entrants and Emerging Players: Begin with portable battery-operated fetal monitors targeting county-level hospitals in Henan and Sichuan provinces where continuous electronic monitoring capacity remains underdeveloped. Pursue NMPA Class III registration through domestic partnership structures rather than direct establishment. Leverage India's PLI scheme for local assembly cost positioning against established Chinese competitors.
For Investors and Strategic Acquirers: Roll-up economics work for specialized sensor OEMs because hospital procurement teams increasingly assemble customized monitoring stations from interoperable subcomponents rather than integrated suites. Long-term viability favors platform-agnostic hardware developers with embedded AI biometry capabilities. Watch FDA guidance evolution on premarket cybersecurity submissions as inflection indicator for wireless monitoring segment consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Accelerates wearable fetal monitor commercialization in United States hospital networks. |
| CE Marking Pathway | EU MDR clinical evidence requirements filter smaller manufacturers from European distribution. |
| Hospital System Partnership | NHS Foundation Trust unbundled procurement mandates favor modular subsystem suppliers. |
| Software Companion Development | AI-embedded ultrasound biometry reduces operator dependency in high-throughput screening. |
| Reimbursement Strategy | Germany's statutory health insurance coding directs capital toward Doppler ultrasound platforms. |
Research Methodology
Direct dialogue with hospital purchasing committees, biomedical engineering directors, GPO contracts managers, and maternal-fetal medicine specialists grounded qualitative assessment. Secondary validation drew from FDA 510(k) filings, NMPA registration databases, NHS procurement framework disclosures, and CMS Medicare reimbursement schedules. Bottom-up demand modeling across device categories triangulated against top-down macroeconomic indicators.
Bottom-up volume estimates by product type, application setting, technology modality, and end-user facility tier fed into value projections across the analysis window. CAGRs derived from replacement cycle compression rates, wireless adoption curves, and reimbursement policy trajectories. Industry-specific forecast inputs incorporated NMPA AI-assisted ultrasound guideline implementation timelines and EU MDR transition completion patterns.
Caveats apply where FDA cybersecurity guidance revisions, Taiwan semiconductor supply disruptions, or MRI substitution acceleration in tertiary centers could materially shift the outlook. Forecasts reflect documented assumptions about regulatory pathway efficiency and hospital capital expenditure prioritization. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Catheter Coatings Market
Medical Devices
Smart Syringe Pumps Market
Medical Devices
Laryngeal Airway Mask Market
Medical Devices
Dialysis Disposable Devices Market
Medical Devices
Sonohysterography Catheters Market
Medical Devices
Pelvic Muscle Probes Market
Medical Devices
Echogenic Catheters Market
Medical Devices
Implantable Port Market
Medical Devices
North America and Europe Medical Technology Market
Medical Devices
Infertility Treatment Devices Market
Medical Devices
Breast Localization System Market
Medical Devices
Insulin Storage Devices Market
Medical Devices
Supraglottic Device Market
Medical Devices
Personal-Use Facial and Skin Therapy Devices Market
Medical Devices
Trocars Market
Medical Devices
Light Therapy Beauty Devices Market