
 Radial Compression Devices Market | 2026-2036
Radial Compression Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Radial Compression Devices Market Outlook
Market Context
EU MDR is decoupling legacy product registrations from new market access, forcing manufacturers to rebuild technical documentation and clinical evidence packages. Abbott Laboratories leverages its vascular access portfolio breadth to sustain European commercial presence through notified body recertification. Merit Medical Systems anchors North American hospital contracting with integrated transradial product suites spanning sheaths, guidewires, and compression bands.
Radial compression devices are mechanical or electromechanical systems that apply controlled circumferential pressure to the radial artery puncture site following catheterization, typically achieving hemostasis within two to fifteen minutes through adjustable force delivery. These devices serve the primary purpose of reducing vascular complications, shortening ambulation time, and enabling same-day discharge in interventional cardiology and peripheral vascular procedures. Automated electromechanical variants command premium positioning due to programmable pressure curves and digital feedback interfaces, while disposable manual bands dominate procedural volume in cost-sensitive emergency settings. Application focus clusters on cardiac procedures where transradial coronary intervention protocols have displaced femoral access across major health systems.
FDA 510(k) clearance pathways and EU MDR conformity assessment govern device classification and clinical data requirements, with Japan's PMDA adding supplemental stability testing for pneumatic compression mechanisms. Health Canada and Australia's TGA align with ISO 13485 quality management standards but impose distinct labeling and post-market surveillance obligations. Stakeholders must monitor evolving notified body capacity constraints in Europe and the trajectory of CMS reimbursement coding for transradial-specific device categories.
Market Dynamics
Transradial access protocols are displacing femoral routes across cardiac catheterization networks, compressing device replacement cycles and forcing manufacturers to rebuild technical documentation under EU MDR recertification timelines.
Growth Catalysts
- EU MDR recertification mandates:Stricter clinical evidence requirements for legacy products are filtering out marginal competitors and consolidating shelf space for compliant manufacturers in European tertiary hospitals.
- Same-day discharge protocols:US health systems pursuing ambulatory surgery center expansion are standardizing radial compression devices to reduce post-procedure observation times and bed utilization.
- Pneumatic mechanism advances:Programmable pressure curves with digital feedback interfaces are enabling automated variants to capture premium positioning in high-volume Japanese cardiac centers.
Market Restraints
- Silicone membrane supply concentration:Single-source dependence on Southeast Asian polymer suppliers exposes device manufacturers to input cost volatility and qualification delays for alternative materials.
- Manual band commoditization:Disposable compression bands face margin compression from contract manufacturers in cost-sensitive emergency department procurement, limiting R&D recovery.
- Femoral access persistence:Complex coronary interventions and peripheral vascular cases retain femoral dominance where sheath size requirements exceed radial anatomical limits.
Strategic Opportunities
- Indian cath lab expansion:Government-funded cardiac care infrastructure under the PLI scheme is creating first-mover advantages for device suppliers establishing training partnerships with metropolitan hospital chains.
- Electromechanical-patient monitoring convergence:Integration of compression devices with EHR systems and remote monitoring platforms is opening subscription revenue models in integrated US delivery networks.
- Australian TGA streamlined pathways:Priority review designation for radial access innovations is accelerating market entry timelines relative to EU notified body queues.
Industry Challenges
- Notified body capacity scarcity:EU MDR recertification backlogs are extending conformity assessment timelines to 18-24 months, freezing product modifications and geographic expansion plans.
- Interventional cardiologist training gaps:Transradial technique proficiency varies across regional hospital networks, requiring sustained proctoring investment to sustain device utilization rates.
- Legacy pneumatic stability testing:Japan's PMDA supplemental validation requirements for electromechanical variants are adding 6-9 months to regulatory filing preparation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Radial Compression Devices Market |
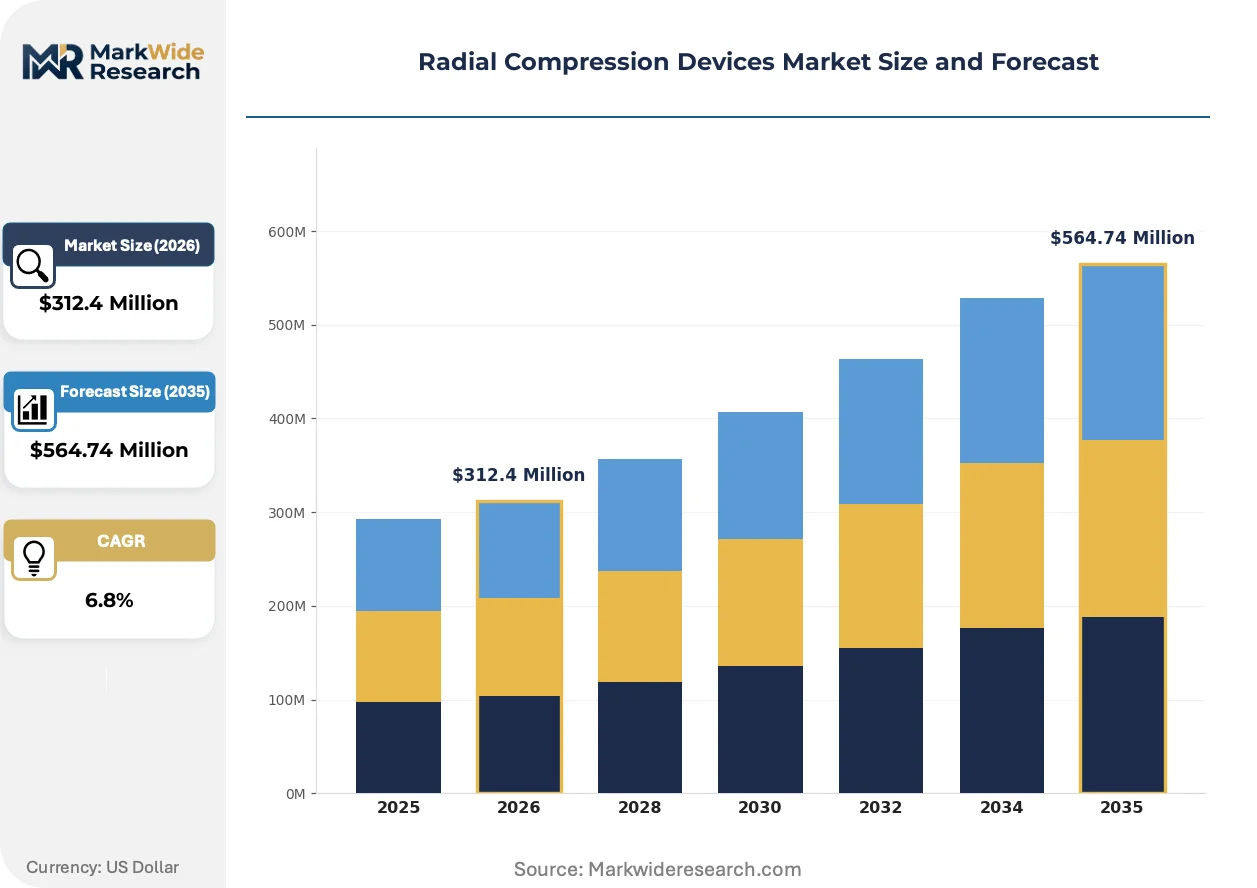
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Devices, Automated Devices, Disposable Devices, Reusable Devices End User: Hospitals, Clinics, Ambulatory Surgery Centers, Emergency Services Technology: Mechanical Devices, Electromechanical Devices, Hydraulic Systems, Pneumatic Systems Application: Cardiac Procedures, Vascular Interventions, Catheterization, Trauma Management |
| Companies Covered | Terumo Corporation, Abbott Laboratories, Teleflex Incorporated, Merit Medical Systems, Comed B.V., Beijing Demax Medical Technology, Semler Technologies, TZ Medical, Lepu Medical Technology (Beijing), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Radial Compression Devices Market Strategic Shifts
Device architectures are converging around sensor-enabled feedback systems that compress hemostasis windows while generating procedure data for quality registries and outcome-based contracting.
Electromechanical radial compression systems are integrating capacitive pressure sensors and Bluetooth telemetry to enable real-time force adjustment and automated documentation. Tertiary cardiac centers in Germany and Japan are adopting these platforms at replacement cycle points, with adoption rates accelerating where same-day discharge protocols are mandatory. This sensor integration is compressing differentiation timelines for manual band manufacturers and shifting procurement criteria toward data interoperability.
EU MDR technical documentation requirements are forcing manufacturers to rebuild clinical evidence packages for legacy pneumatic and mechanical devices previously cleared under the Medical Device Directive. The industrial consequence is a bifurcation between firms with notified body relationships sustaining European market access and those redirecting volume to US and Asia-Pacific markets. Electromechanical variants with novel pressure algorithms face the steepest evidence burdens, extending time-to-revenue for automated platform launches.
Hospital procurement departments are unbundling radial compression devices from traditional catheterization kit bundles and negotiating direct manufacturer contracts based on utilization guarantees. This disintermediation is displacing distributor markup layers in US integrated delivery networks and concentrating purchasing leverage among health system central procurement offices. The shift is most visible in metropolitan hospital systems pursuing standardization across multiple cath lab sites.
Radial Compression Devices Market Segmentation
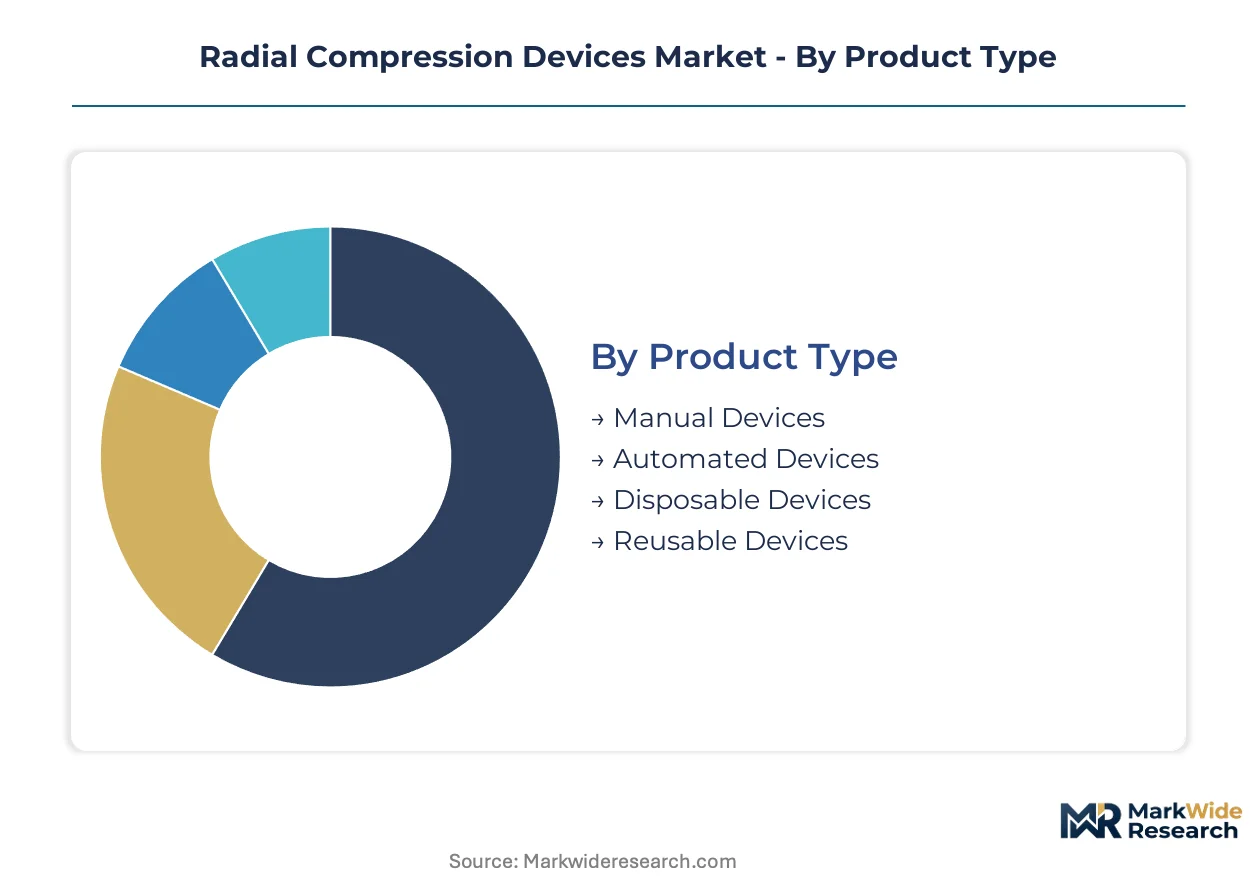
Radial compression devices fragment across four distinct category axes, with product architecture and care setting driving procurement differentiation. Understanding these segment boundaries clarifies where automated platforms command premium positioning versus where manual bands face commoditization pressure.
Product Type:
Standalone pneumatic and electromechanical systems anchor premium hospital contracts, while disposable bands embed into emergency department supply chains as single-use consumables.
- Manual Devices:Spring-loaded or screw-adjusted bands deliver circumferential pressure through mechanical force application without external power. Demand clusters in emergency services and rural clinics across India and Brazil where capital equipment budgets are constrained and procedure volumes are intermittent.
- Automated Devices:Programmable electromechanical platforms integrate pressure sensors with digital feedback loops for real-time adjustment. Japanese cardiac centers and German tertiary hospitals drive procurement as same-day discharge protocols mandate precise hemostasis documentation and reduced nursing observation.
- Disposable Devices:Single-use compression bands with adhesive or strap fixation eliminate sterilization logistics. These dominate ambulance services and satellite cath labs where infection control protocols prioritize elimination of reprocessing steps.
- Reusable Devices:Durable pneumatic cuffs and mechanical housings designed for 50-100 sterilization cycles. These find placement in high-volume US hospital systems where utilization rates justify capital investment and central sterile processing capacity is established.
Volume placements concentrate in disposable manual bands; the faster expansion belongs to automated electromechanical platforms.
End User:
Procurement authority shifts from centralized hospital supply chains to distributed clinic purchasing as care settings fragment across the acuity spectrum.
- Hospitals:Tertiary cardiac centers with dedicated cath labs represent the core revenue base, with integrated delivery networks negotiating multi-site contracts for standardized device platforms. These facilities prioritize automated systems with EHR integration to support quality registry reporting.
- Clinics:Outpatient diagnostic and interventional sites favor portable manual devices for occasional radial access procedures. Cost sensitivity dominates as procedure volumes rarely justify dedicated electromechanical capital.
- Ambulatory Surgery Centers:Medicare-certified ASCs in the United States are expanding transradial PCI capacity under same-day discharge reimbursement incentives. These facilities demand compact, rapid-turnover devices that minimize recovery room occupancy.
- Emergency Services:Pre-hospital and emergency department applications require immediate deployment without setup time. Disposable bands with intuitive application dominate this segment where training time is minimal and storage space is limited.
Revenue gravity sits with hospital cath labs; ambulatory surgery centers are climbing the fastest as site-of-care migration accelerates.
Technology:
Force delivery mechanisms differentiate on precision, speed, and capital intensity, with pneumatic and electromechanical platforms displacing purely mechanical systems in high-acuity settings.
- Mechanical Devices:Screw, cam, or spring mechanisms apply pressure through physical displacement without energy input. These retain presence in cost-constrained environments but face displacement where digital documentation is required.
- Electromechanical Devices:Motor-driven pressure application with sensor feedback enables programmable force curves and automated documentation. Japanese PMDA stability requirements and EU MDR clinical evidence burdens slow new entrant penetration.
- Hydraulic Systems:Fluid-filled bladders transmit pressure through incompressible medium, offering smooth force distribution. Limited commercial presence due to complexity and maintenance requirements relative to pneumatic alternatives.
- Pneumatic Systems:Air-filled cuffs with regulated inflation provide rapid pressure adjustment and deflation. These dominate automated device architectures in German and US cardiac centers where speed-to-hemostasis drives throughput metrics.
Installed base tilts toward mechanical legacy systems; pneumatic-electromechanical hybrids are gaining share fastest as replacement cycles accelerate.
Application:
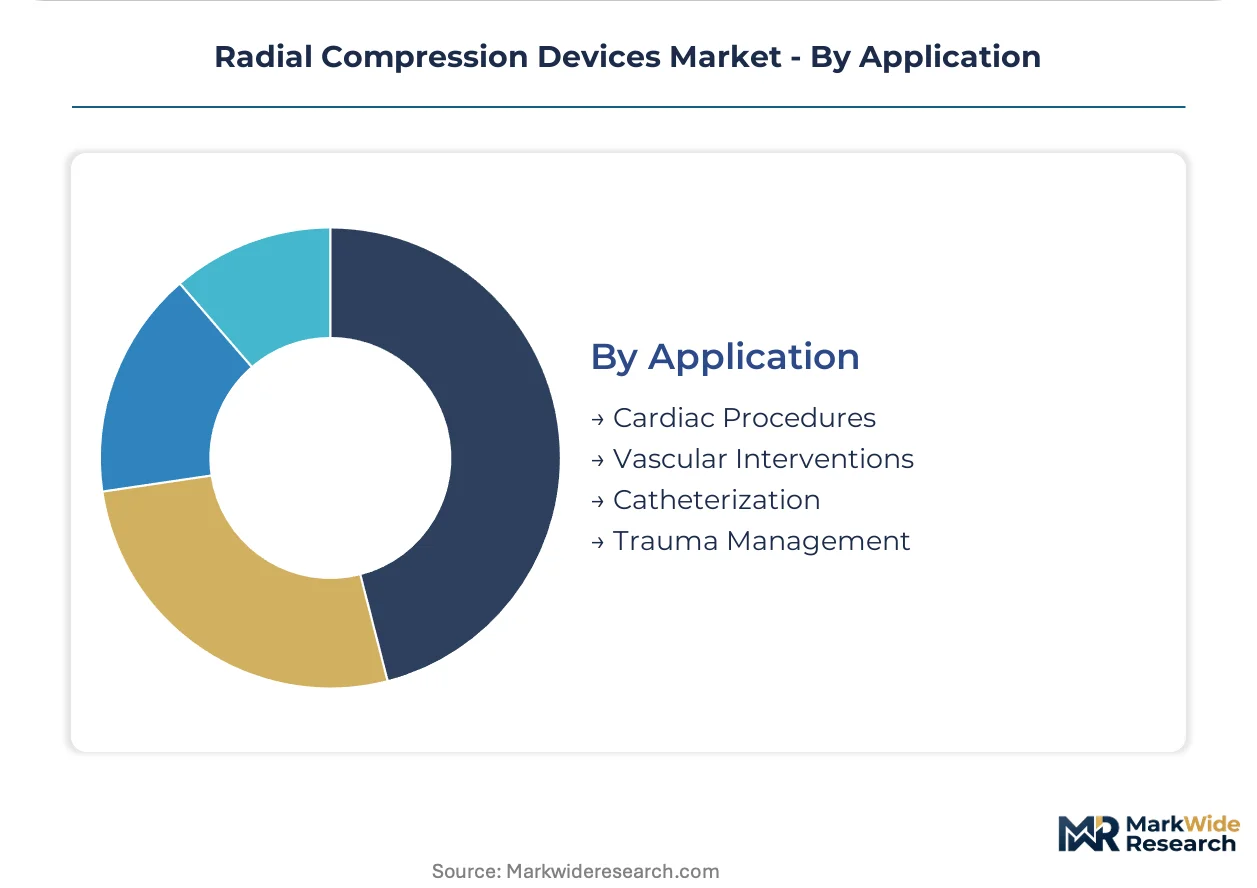
Procedure-specific anatomical and hemostasis requirements shape device selection, with cardiac applications demanding the most sophisticated pressure control.
- Cardiac Procedures:Transradial coronary intervention and diagnostic catheterization require precise pressure modulation to balance hemostasis against radial artery occlusion risk. Electromechanical platforms with programmable deflation protocols dominate in high-volume Japanese and German centers.
- Vascular Interventions:Peripheral angiography and intervention through radial access is expanding as sheath technology enables larger bore compatibility. Device demand follows the spread of "radial-first" protocols in peripheral vascular programs.
- Catheterization:Non-coronary diagnostic procedures including right heart catheterization and electrophysiology studies utilize radial access selectively. Manual bands suffice for these lower-complexity applications.
- Trauma Management:Emergency radial artery access for hemorrhage control or monitoring represents a niche application with distinct device requirements for field deployment and rapid application.
Procedure volume concentrates in cardiac applications; vascular interventions are expanding most quickly as radial access protocols extend beyond coronary anatomy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free Trade Zones in Shenzhen and Shanghai concentrate electromechanical device manufacturing for Asia-Pacific distribution, while cardiac catheterization networks in Germany, Japan, and the United States absorb premium automated systems.
United States
Medicare-certified ambulatory surgery centers are expanding transradial PCI capacity under same-day discharge reimbursement incentives. FDA 510(k) clearance pathways govern device classification for electromechanical variants. The Cleveland Clinic and Mayo Clinic cardiac networks in Ohio and Minnesota anchor procurement standardization across integrated delivery systems.
Germany
Tertiary hospital cath labs in Bavaria and North Rhine-Westphalia drive replacement cycles for pneumatic compression platforms with EHR integration requirements. EU MDR conformity assessment through notified bodies like TÜV SÜD filters legacy product registrations. The Munich-Berlin corridor concentrates procurement authority for multi-site standardization contracts.
Japan
High-volume cardiac centers in Tokyo and Osaka mandate programmable pressure curves with digital documentation for hemostasis protocols. PMDA supplemental stability testing adds validation requirements for electromechanical mechanisms. The Kanto region anchors adoption of automated platforms with remote monitoring capabilities.
India
Production-Linked Incentive scheme funding for cardiac care infrastructure is expanding metropolitan cath lab capacity in Maharashtra and Karnataka. CDSCO medical device rules govern import registration for compression device categories. Mumbai and Bangalore hospital chains are establishing training partnerships for transradial technique standardization.
Australia
TGA priority review designation for radial access innovations accelerates market entry relative to EU notified body queues. Queensland and New South Wales health systems are standardizing disposable manual bands for emergency department deployment. The Sydney-Melbourne corridor concentrates procurement for state-level hospital networks.
Radial Compression Devices Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across the radial compression device landscape, creating a tiered structure where vascular access portfolio breadth determines hospital contracting leverage. The vendor base separates into three strategic archetypes: integrated medical technology conglomerates with cath lab ecosystem control, dedicated hemostasis device specialists with procedural workflow expertise, and regional contract manufacturers serving cost-sensitive emergency segments. Dominant competitive moves include notified body recertification investments for EU MDR compliance and direct hospital contracting that disintermediates traditional distributor networks.
Among diversified medical technology conglomerates, Terumo Corporation and Abbott Laboratories occupy positions defined by vascular access portfolio integration, while Merit Medical Systems exemplifies the dedicated specialist archetype with transradial product suite concentration. Beijing Demax Medical Technology and Lepu Medical Technology (Beijing) represent Chinese manufacturers positioned for domestic cath lab expansion and emerging market export.
| Leading Market Players |
|---|
| Terumo Corporation |
| Abbott Laboratories |
| Teleflex Incorporated |
| Merit Medical Systems |
| Comed B.V. |
| Beijing Demax Medical Technology |
| Semler Technologies |
| TZ Medical |
| Lepu Medical Technology (Beijing) |
| Others |
Value Chain & Pricing Dynamics
Silicone membrane feedstock from Southeast Asian polymer suppliers travels through three pricing tiers before reaching hospital procurement desks, with pneumatic cuff manufacturers absorbing qualification delays and passing selective premiums to automated device buyers while manual band producers compete on spot inventory availability.
Pricing Analysis
Short lead-time premiums separate emergency department spot purchasers from contracted integrated delivery networks. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 510(k) clearance status and EU MDR certification tier. Price differentiation stems from pneumatic mechanism complexity and sterilization cycle guarantees. Cost compression in disposable manual bands is intensifying because contract manufacturers in India and Brazil are undercutting established suppliers. Ambulance services and rural clinics exhibit highest price sensitivity; German and Japanese tertiary cardiac centers prioritize programmable pressure documentation over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Malaysian and Thai silicone membrane suppliers who feed pneumatic cuff assembly operations in Shenzhen and Shanghai. Electromechanical device production draws from Japanese pressure sensor foundries, German precision motor suppliers, and Chinese PCB fabrication clusters. Supply chain risk centers on notified body capacity scarcity extending EU MDR recertification timelines and freezing product modifications. Distribution runs through regional medical device distributors in North America, direct hospital contracting in Western Europe, and government tender channels in India and Brazil.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR notified body queue lengths are the capacity bottleneck propping pricing power for compliant manufacturers, as recertification backlogs freeze competitor product modifications and geographic expansion plans.
For Market Incumbents: Hedge silicone membrane supply exposure through dual-source qualification programs with Indian polymer suppliers under CDSCO medical device rules. Anchor hospital contracting leverage by integrating compression devices with EHR systems for quality registry reporting. Defend against pneumatic mechanism commoditization by accelerating electromechanical platform replacement cycles in German and Japanese tertiary centers. For New Entrants and Emerging Players: TGA priority review designation in Australia opens a window for electromechanical variants facing EU notified body queues of 18-24 months. Target Queensland and New South Wales health system standardization programs for disposable manual band placement. Pursue training partnership models with Mumbai and Bangalore hospital chains to establish transradial technique credibility before device procurement decisions. For Investors and Strategic Acquirers: First-mover establishment of notified body relationships sustaining European commercial presence is the leading indicator that electromechanical platform manufacturers will capture replacement cycle revenue concentration. Position for 5-10 year consolidation of hospital procurement authority toward integrated delivery networks demanding data interoperability. Monitor Japanese PMDA supplemental stability testing completion timelines as signal for electromechanical variant market entry readiness.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Notified Body Recertification | Sustains European market access for Abbott Laboratories and Terumo Corporation through TÜV SÜD relationships. |
| Electromechanical-EHR Integration Development | Enables subscription revenue models in US integrated delivery networks pursuing same-day discharge protocols. |
| Indian PLI Scheme Training Partnerships | Creates first-mover positioning for device suppliers establishing transradial technique standardization in Maharashtra cath labs. |
| Pneumatic Mechanism Dual-Source Qualification | Reduces silicone membrane supply concentration risk from Southeast Asian polymer suppliers. |
| Australian TGA Priority Review Pathway | Accelerates market entry timelines relative to EU notified body queues for radial access innovations. |
Study Parameters
FDA 510(k) clearance databases, EU MDR notified body registration records, and Japanese PMDA submission filings formed the secondary backbone for device classification and clinical evidence requirement mapping. Primary interviews with interventional cardiologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers validated procurement criteria and replacement cycle timing. Bottom-up modeling of cath lab procedure volumes and top-down triangulation against medical device trade data ensured segmentation consistency.
Historical trendline analysis of transradial access protocol adoption across German, Japanese, and US cardiac centers informed penetration rate assumptions. The forecast framework modeled product type segmentation across manual, automated, disposable, and reusable architectures; end user segmentation across hospitals, clinics, ambulatory surgery centers, and emergency services; and technology segmentation across mechanical, electromechanical, and pneumatic mechanisms. CAGRs were derived from procedure volume elasticity to same-day discharge reimbursement incentives and replacement cycle compression in high-volume centers.
The model assumes a particular technology adoption path; alternative pathways for electromechanical-patient monitoring convergence would alter the outlook if EHR integration costs exceed hospital IT budget constraints. Forecasts reflect assumptions about EU MDR recertification timeline resolution and Japanese PMDA stability testing standardization. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Bone Cement Mixers Market
Medical Devices
Global Traumatic Brain Injury Assessment and Management Devices Market
Medical Devices
Active Implantable Devices Market
Medical Devices
Medical Oxygen Sensors Market
Medical Devices
US Medical Sector Contract Electronic Manufacturing Market
Medical Devices
Prosthetic Liners Market
Medical Devices
Orthodontic Equipment Market
Medical Devices
Dynamic Spinal Tethering Systems Market
Medical Devices
Membrane Oxygenators Market
Medical Devices
Ultrasonic Dissection Devices Market
Medical Devices
Global Pessary Market
Medical Devices
Middle East and Africa Micro Invasive Glaucoma Surgery (MIGS) Devices Market
Medical Devices
United Kingdom Drug Delivery Devices Market
Medical Devices
Global Cardiac Reader System Market
Medical Devices
Global Medical Radiation Shielding Market
Medical Devices
Heart Defect Closure Devices Market