
 Anti-Fatigue Lenses Market | 2026-2036
Anti-Fatigue Lenses Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Fatigue Lenses Market Insights
Modular lens-coating bundles are rebalancing how buyers configure anti-fatigue solutions. EssilorLuxottica leverages its integrated lab network to pair progressive designs with proprietary blue light stacks. HOYA anchors premium positioning through high-index material specialization. Nikon competes on precision surfacing technology for sustained visual comfort.
Anti-fatigue lenses incorporate aspheric or atoric front surfaces with subtle addition power in the lower portion to reduce accommodative stress during near work. Polycarbonate and Trivex materials dominate volume production due to impact resistance and thin-profile feasibility. Progressive lens types command margin pools as presbyopic digital workers seek seamless distance-to-near transitions. Blue light filter coatings represent the fastest-growing segment as employers adopt display ergonomics standards.
FDA 510(k) clearance pathways govern medical device claims for anti-fatigue designs in the United States. EMA harmonization through the EU Medical Device Regulation shapes conformity assessment for European distribution. China's NMPA and GB standards for ophthalmic optics govern domestic manufacturing quality and import access. Stakeholders must monitor evolving screen-time exposure guidelines from occupational health bodies to anticipate prescription volume shifts and coating specification requirements.
Market Dynamics
Digital eye strain protocols from occupational health regulators are compressing replacement cycles and forcing coating specification upgrades across prescription fulfillment networks. This structural pressure is redistributing margin toward labs with integrated blue light deposition capabilities.
Growth Catalysts
- Screen-time exposure guidelines:OSHA and EU-OSHA draft standards for display ergonomics are mandating employer-funded vision assessments. This institutionalizes anti-fatigue lens procurement as a workplace compliance expense.
- Myopia progression management:China's NMPA has expanded reimbursement eligibility for aspheric designs in pediatric populations. Clinicians now prescribe anti-fatigue configurations as early-intervention tools.
- High-index material penetration:Trivex and polycarbonate substrates are displacing crown glass in volume production. Thinner profiles enable stronger prescriptions without cosmetic resistance.
Market Restraints
- Monomer feedstock volatility:Crude-derived optical-grade polymers face price swings that compress coating lab margins. EssilorLuxottica and HOYA have both cited thiourethane cost pressure in quarterly disclosures.
- Coating equipment concentration:Vacuum deposition chambers for multi-layer AR stacks are manufactured by a narrow German and Japanese supplier base. Lead times now extend eighteen months for new capacity.
- Limited presbyopic awareness:Many forty-plus screen workers attribute near-vision discomfort to aging rather than accommodative stress. This diagnostic gap delays first purchase by two to three years.
Strategic Opportunities
- Rural China penetration:Tier-three and tier-four cities show sub-fifteen percent anti-fatigue adoption against forty-plus percent in Shanghai and Beijing. Domestic chains are deploying mobile refraction vans to close this gap.
- Gaming and esports verticals:Professional competitors now specify blue-light-filtering designs under team medical contracts. This creates a premium channel with annual replacement cadence.
- EU MDR harmonization:The Medical Device Regulation's clarity on ophthalmic device claims is enabling direct-to-employer bulk procurement. Occupational health departments are consolidating vendor lists.
Industry Challenges
- Surfacing technician scarcity:Freeform generator operation requires hybrid optical-mechanical training that vocational programs have not scaled. Labs report six-month hiring timelines for qualified operators.
- ISO 8980-1 certification backlog:Testing queue delays at notified bodies are extending product launch timelines by four to six months for new progressive designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Fatigue Lenses Market |
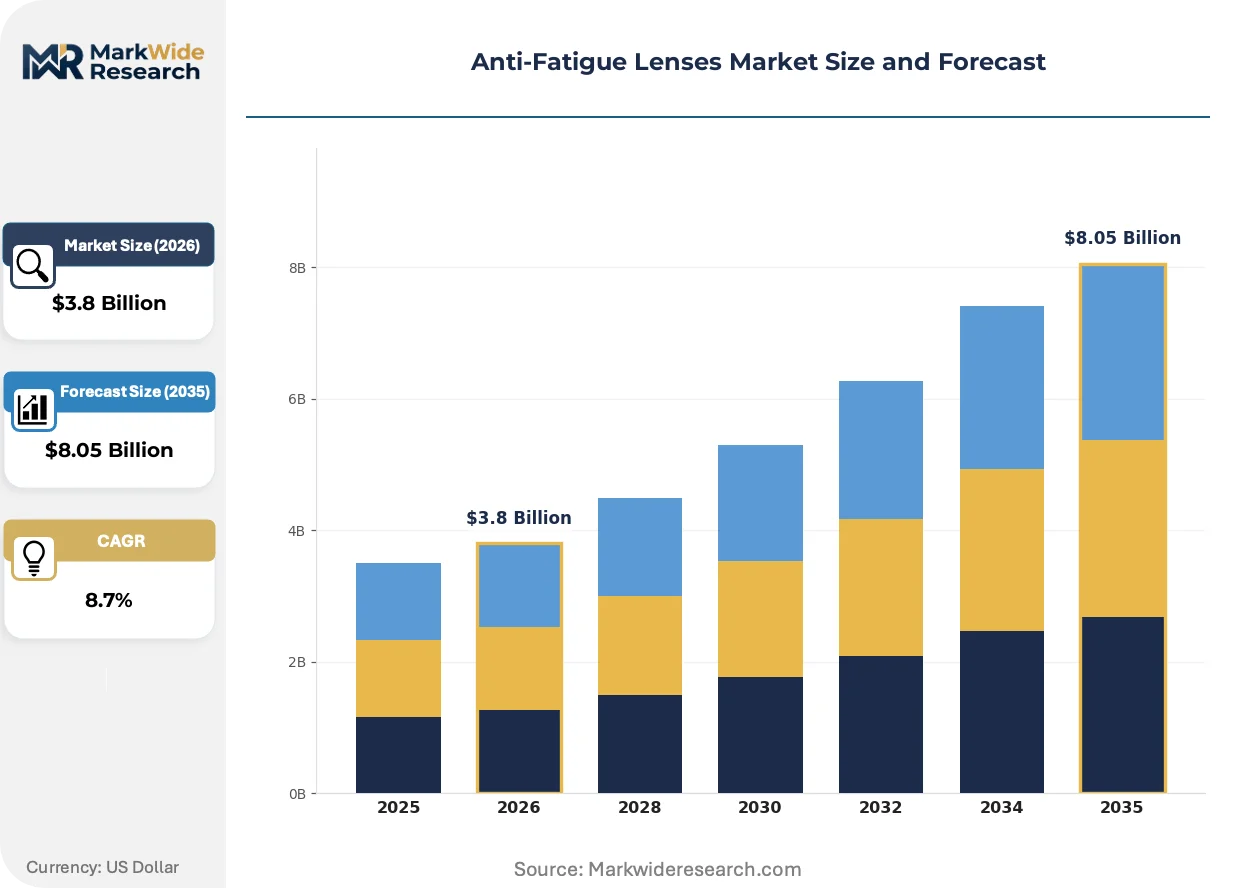
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Lens Type: Single Vision, Bifocal, Progressive, Blue Light Filter Target Consumer: Office Workers, Students, Gamers, Seniors Material: Polycarbonate, Trivex, High-Index Plastic, Glass Coating: Anti-Reflective, UV Protection, Scratch-Resistant, Photochromic |
| Companies Covered | Nikon, Rodenstock, ZEISS, TOKAI Optec, SEIKO Optical, EssilorLuxottica, Shamir Optical, Mingyue Optical Lens, HOYA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Fatigue Lenses Market Trends and Innovations
Anti-fatigue lens development is converging on three vectors: proprietary coating stacks that differentiate at point-of-sale, regulatory frameworks that institutionalize employer payment, and material science that enables stronger prescriptions in thinner profiles.
Photochromic-integrated blue light filters are absorbing a growing share of premium configurations. These dual-function coatings appeal to workers with variable lighting conditions. Corporate benefit administrators are selecting this specification for executive tiers. The technology is absorbing margin from standalone AR coatings by bundling two purchase triggers into one invoice line.
EU MDR's 2021 implementation tightened clinical evidence requirements for medical device claims on ophthalmic products. Manufacturers must now submit biocompatibility and optical performance data to notified bodies before marketing progressive designs as fatigue-reducing. German and French labs are responding by consolidating testing partnerships with TÜV Süd and BSI to accelerate clearance timelines.
Employer-sponsored vision benefits are restructuring how end-users select lens tiers. Large corporations in the United States and United Kingdom are negotiating direct contracts with EssilorLuxottica and VSP Global, bypassing traditional retail intermediaries. Procurement teams are specifying minimum blue light attenuation thresholds and demanding usage analytics. This channel shift is most visible in technology and financial services sectors where screen exposure averages exceed six hours daily.
Anti-Fatigue Lenses Market Segmentation
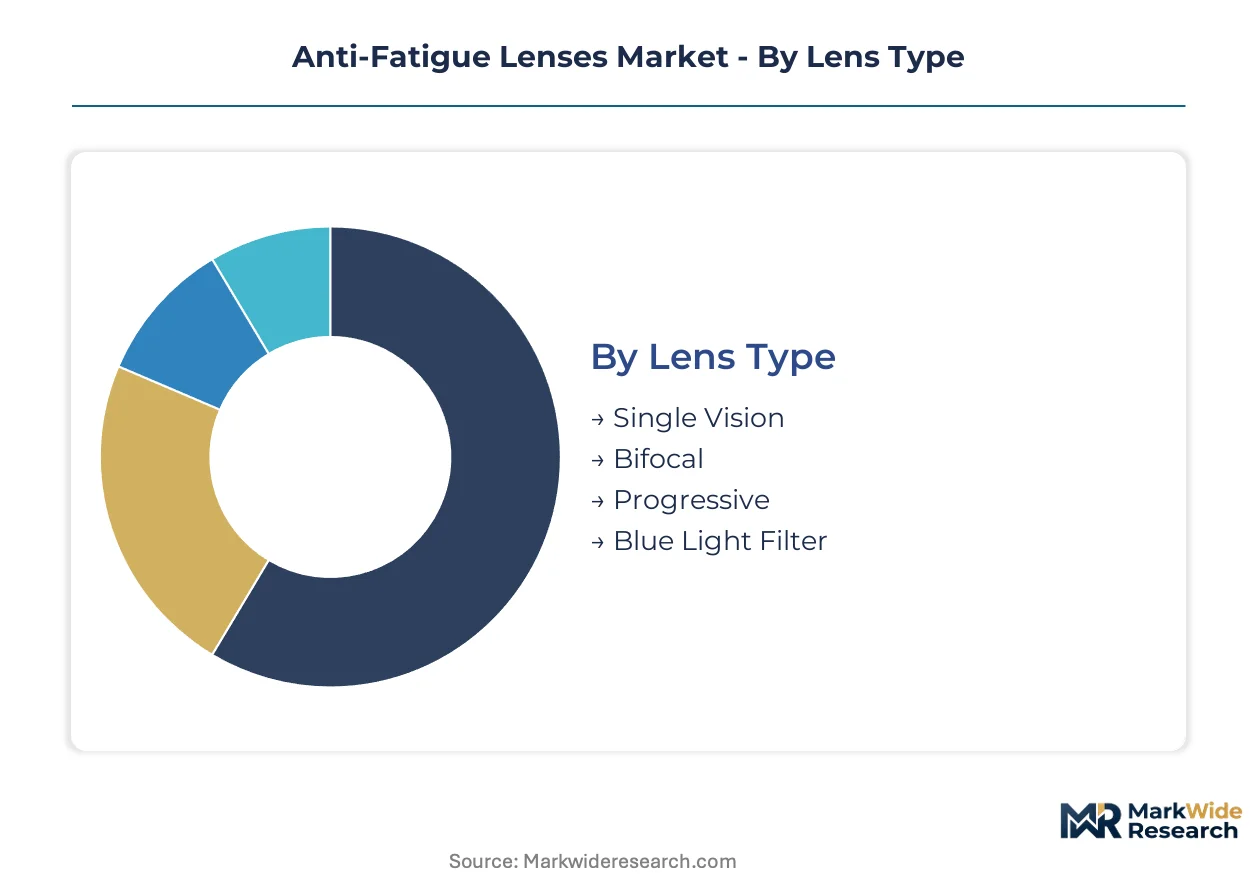
Anti-fatigue lens segmentation reveals how prescription complexity, occupational exposure patterns, and material specifications create distinct procurement channels. Each dimension shapes margin structure and vendor positioning differently across patient populations.
Lens Type:
Buyer differentiation hinges on presbyopic status and near-work intensity rather than age alone.
- Progressive:These designs integrate distance, intermediate, and near zones through freeform surfacing technology. Demand concentrates among presbyopic office workers in China's tier-one cities where employers fund vision benefits. The seamless transition reduces head movement during screen work.
- Blue Light Filter:Discrete coating stacks or substrate-integrated pigments attenuate high-energy visible light. Gaming teams and financial services firms in London and New York specify these under occupational health contracts. Regulatory momentum from EU-OSHA display ergonomics guidelines accelerates employer-funded procurement.
- Single Vision:Uniform power distribution serves pre-presbyopic digital workers with simple myopic or hyperopic correction. Students in South Korea and Japan represent concentrated demand.
- Bifocal:Segmented designs with visible dividing lines persist in cost-sensitive procurement channels. Adoption concentrates among seniors in Medicare-funded US markets.
Progressive designs lead volumes today; blue light filter configurations are gaining share fastest.
Target Consumer:
Volume distribution follows screen-time exposure curves and employer benefit sophistication.
- Office Workers:Six-plus hour daily display exposure creates accommodative stress that anti-fatigue designs specifically address. Corporate vision benefit administrators in Germany and the United Kingdom negotiate direct lab contracts. Procurement specifications now mandate minimum blue light attenuation thresholds.
- Gamers:Professional esports competitors and streamers replace lenses annually under team medical agreements. Teams in Seoul, Los Angeles, and Stockholm specify photochromic-integrated blue light stacks for variable arena lighting.
- Students:Pediatric myopia progression protocols in China expand reimbursement eligibility for aspheric anti-fatigue designs. Clinicians prescribe these as early-intervention tools.
- Seniors:Medicare and NHS coverage frameworks shape price ceilings. Presbyopic awareness gaps delay first purchase by two to three years in this cohort.
Office workers anchor current procurement volumes; gamers drive the steepest expansion trajectory.
Material:
Thickness tolerance and impact resistance requirements separate premium from standard tiers.
- Polycarbonate:Impact-resistant thermoplastic dominates volume production with thin-profile feasibility for moderate prescriptions. US safety-conscious employers specify this for warehouse and field staff with dual screen-exposure duties.
- Trivex:Urethane-based monomer delivers superior optical clarity and lighter weight than polycarbonate. Premium positioning in Japanese and German markets reflects higher monomer costs.
- High-Index Plastic:Refractive indices above 1.60 enable cosmetically acceptable thickness for strong prescriptions. China's myopic population drives concentrated uptake.
- Glass:Crown glass persists in specialty applications requiring maximum scratch resistance. Niche demand from laboratory and manufacturing environments.
Polycarbonate holds the volume lead; Trivex climbs fastest among premium configurations.
Coating:
Functional layering determines point-of-sale differentiation and replacement cycle timing.
- Anti-Reflective:Multi-layer vacuum deposition reduces ghost images and glare from overhead lighting. German and Japanese equipment suppliers concentrate manufacturing capacity with eighteen-month lead times.
- Photochromic:Light-adaptive technology integrates with blue light filtration for dual-function premium bundles. Corporate benefit administrators select this specification for executive tiers.
- UV Protection:Standard blocking of ultraviolet-A and ultraviolet-B radiation. Regulatory baseline in EU, US, and Chinese ophthalmic standards.
- Scratch-Resistant:Hardcoat layers extend functional lifespan. Expected in economy-tier configurations.
Anti-reflective coatings dominate attachment rates; photochromic stacks expand most quickly in premium channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Anti-fatigue lens manufacturing originated in German precision optics workshops during the mid-twentieth century, then migrated to Japanese surfacing technology centers before China's production scale redefined volume economics. Today demand patterns diverge across regulatory environments and employer benefit structures.
China
Domestic myopia prevalence among students drives pediatric prescriptions for aspheric anti-fatigue designs under NMPA reimbursement protocols. Tier-one cities Shanghai and Beijing exhibit adoption rates above forty percent, while mobile refraction vans now penetrate tier-three and tier-four markets. Guangdong province hosts concentrated coating lab clusters serving both domestic consumption and export fulfillment.
United States
Corporate vision benefit administrators negotiate direct contracts with lens laboratories, bypassing retail intermediaries. FDA 510(k) clearance pathways govern medical device claims for progressive fatigue-reducing designs. California and New York technology firms specify minimum blue light attenuation thresholds for employees averaging six-plus hours of daily screen exposure.
Germany
Freeform generator operation requires hybrid optical-mechanical training that vocational programs have not scaled, creating six-month hiring timelines for qualified surfacing technicians. EU MDR harmonization through notified bodies TÜV Süd and BSI shapes conformity assessment timelines. Bavaria maintains precision optics heritage with consolidated testing partnerships accelerating product launches.
Japan
Trivex material specialization commands premium positioning in domestic markets despite higher monomer costs. METI industrial standards intersect with occupational health guidelines for display ergonomics. Tokyo and Osaka metropolitan areas concentrate presbyopic office worker demand for progressive lens configurations with seamless distance-to-near transitions.
United Kingdom
NHS coverage frameworks establish price ceilings for bifocal configurations among seniors, though presbyopic awareness gaps delay first purchase by two to three years. Financial services firms in London specify photochromic-integrated blue light stacks under occupational health contracts. EU-OSHA draft standards for display ergonomics accelerate employer-funded procurement across Greater London and Southeast England.
Anti-Fatigue Lenses Market Competitive Landscape
Premium-margin players sit above commodity-margin players across coating sophistication and freeform surfacing capability. The vendor base stratifies into three tiers: integrated optical groups with captive lab networks, specialized coating technology developers, and regional surfacing operations serving price-sensitive channels. Consolidation pressure intensifies as employer procurement teams consolidate vendor lists and demand usage analytics. Dominant competitive moves include backward integration into monomer production and strategic partnerships with vacuum deposition equipment suppliers.
Within the integrated optical group tier, EssilorLuxottica, HOYA, and ZEISS exemplify divergent strategic positioning. EssilorLuxottica leverages its lab network density across multiple continents. HOYA anchors premium-tier material science specialization. ZEISS occupies a position centered on precision surfacing heritage. These three represent archetypal approaches to capturing margin pools as presbyopic digital workers seek seamless visual transitions.
| Leading Market Players |
|---|
| Nikon |
| Rodenstock |
| ZEISS |
| TOKAI Optec |
| SEIKO Optical |
| EssilorLuxottica |
| Shamir Optical |
| Mingyue Optical Lens |
| HOYA |
| Others |
Pricing and Supply Chain Analysis
EU MDR harmonization requirements for ophthalmic device biocompatibility documentation gate qualified supply access and premium-tier pricing power. Labs lacking notified body partnerships face exclusion from employer-funded procurement channels where EssilorLuxottica and HOYA anchor pricing benchmarks.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by coating sophistication and freeform surfacing capability. Price differentiation hinges on ISO 8980-1 certification status and blue light attenuation thresholds specified by corporate benefit administrators. Cost compression in economy-tier polycarbonate configurations is intensifying because thiourethane monomer feedstock volatility squeezes coating lab margins. Students and seniors in Medicare-funded channels exhibit highest price sensitivity; gaming teams and financial services firms show least sensitivity under occupational health contracts.
Supply Chain Analysis
Freight cost differentials between German vacuum deposition equipment suppliers and Chinese coating lab clusters shape regional margin structures. Manufacturing concentrates in China, Germany, and Japan where freeform generator operation and multi-layer AR stack deposition anchor production capability. Raw material dependencies center on optical-grade thiourethane monomers, polycarbonate substrates, and rare-earth coating pigments. Single-source vulnerability in vacuum chamber manufacturing from Japanese and German equipment suppliers creates eighteen-month capacity expansion bottlenecks. Distribution runs through integrated lab networks for premium tiers and regional surfacing operations for price-sensitive channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where NMPA reimbursement protocols in China enable margin capture unavailable under FDA 510(k) cost structures in the United States.
For Market Incumbents: Deepen backward integration into monomer production to defend against thiourethane cost volatility cited in quarterly disclosures by EssilorLuxottica and HOYA. Consolidate testing partnerships with TÜV Süd and BSI to compress ISO 8980-1 certification timelines that currently extend product launches by four to six months. For New Entrants and Emerging Players: EU-OSHA draft display ergonomics standards in the United Kingdom open a window for direct-to-employer bulk procurement bypassing retail intermediaries. Target tier-three and tier-four Chinese cities where mobile refraction vans have driven adoption below fifteen percent against forty-plus percent in Shanghai and Beijing. Lead with photochromic-integrated blue light bundles that bundle two purchase triggers into single invoice lines. For Investors and Strategic Acquirers: Valuations sit cheapest among regional surfacing operations serving price-sensitive channels without captive coating deposition capability. Long-term viability over the next decade hinges on employer benefit consolidation and regulatory institutionalization of vision assessments as workplace compliance expenses. Watch OSHA and EU-OSHA final rule publication as inflection indicator for replacement cycle compression.| Strategic Initiative | Industry Significance |
|---|---|
| Notified Body Partnership Consolidation | TÜV Süd and BSI partnerships compress EU MDR clearance timelines for progressive designs. |
| Backward Integration into Monomer Production | Captive thiourethane supply hedges against crude-derived optical polymer price swings. |
| Mobile Refraction Van Deployment | Tier-three and tier-four Chinese city penetration closes adoption gaps against tier-one benchmarks. |
| Direct-to-Employer Contract Negotiation | Corporate benefit administrators in technology and financial services bypass retail intermediaries. |
| Photochromic-Blue Light Bundle Development | Dual-function coatings absorb margin from standalone AR configurations in executive benefit tiers. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary engagement with lens laboratory operations directors, corporate vision benefit administrators, freeform generator technicians, ophthalmic coating R&D leads, and notified body certification managers informed supply-side and demand-side dynamics. Secondary validation drew from FDA 510(k) filings, EMA MDR submissions, NMPA ophthalmic optics standards, OSHA draft display ergonomics guidelines, and EU-OSHA technical reports. Bottom-up prescription volume modeling and top-down employer benefit spend analysis triangulated market sizing.
Segment-weighting approaches distributed value across lens type, target consumer archetype, material substrate, and coating configuration dimensions. CAGRs were derived from prescription volume trajectories, replacement cycle compression rates, and coating attachment trend analysis across the projection horizon. Forecast inputs incorporated NMPA reimbursement expansion protocols, EU MDR implementation timelines, and occupational health regulatory momentum in the United States, United Kingdom, and Germany.
Revisions become necessary when thiourethane monomer cost volatility exceeds historical bands, notified body certification queues extend beyond current four-to-six month baselines, or OSHA final rules diverge from draft display ergonomics standards. Forecasts reflect documented assumptions about employer benefit expansion and regulatory harmonization timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Electroencephalography (EEG) Amplifier System Market
Medical Devices
Airway Management Tubes Market
Medical Devices
ECG Telemetry Devices Market
Medical Devices
Global Digital Dose Inhaler Market
Medical Devices
Portable Medical Electronic Products Market
Medical Devices
Transradial Access Devices Market
Medical Devices
Global Holter ECG Market
Medical Devices
Global Healthcare Nanotechnology (Nanomedicine) Market
Medical Devices
Global Portable Ventilators Market
Medical Devices
Disposable Medical Devices Sensors Market
Medical Devices
Automated Insulin Delivery Device Market
Medical Devices
Canada Ultrasound Devices Market
Medical Devices
Vortex Mixer Market
Medical Devices
Global Airway Stent/Lung Stent Market
Medical Devices
Automatic Pill Dispenser Machine Market
Medical Devices
China Ultrasound Devices Market