
 Ehealth Devices Market | 2026-2036
Ehealth Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Ehealth Devices Market Intelligence
FDA 510(k) premarket notification volume for software-based devices is expanding, raising engineering documentation costs for new entrants. Medtronic leverages its cardiac rhythm portfolio to anchor remote patient monitoring revenue streams. Abbott Laboratories specializes in glucose-sensing wearables that integrate with cloud analytics platforms. Koninklijke Philips competes across sleep therapy and telehealth infrastructure, sustaining installed base loyalty through subscription services.
Ehealth devices encompass networked hardware and software systems that capture, transmit, and analyze physiological data outside traditional clinical settings, typically operating via Bluetooth Low Energy or wireless sensor networks with cloud backhaul for real-time clinician dashboards. Their primary purpose is to enable continuous chronic disease management and reduce acute care utilization. Wearable devices occupy the largest revenue pool as consumer familiarity with wrist-worn biosensors deepens, while remote monitoring captures the fastest expansion as accountable care organizations seek hospital-at-home reimbursement. Telehealth platforms remain margin-diluted due to high customer acquisition costs, though cloud computing infrastructure underpins scalability for multi-tenant health system deployments.
FDA digital health pre-certification, HIPAA security rule enforcement, and EU MDR Class IIa reclassification for connected diagnostic accessories are reshaping product development timelines and liability exposure. Health Canada and Japan's PMDA maintain aligned but distinct software validation requirements that fragment regulatory strategy for multinational device portfolios. Stakeholders must monitor evolving interoperability mandates from ONC and the pace of national reimbursement code creation for asynchronous telehealth encounters.
Market Dynamics
Home-based patient monitoring is compressing care delivery timelines as elderly populations demand continuous chronic disease management outside hospital walls, forcing device manufacturers to reengineer hardware for unsupervised use.
Growth Catalysts
- Hospital-at-home reimbursement codes:Accountable care organizations in the United States now secure Medicare reimbursement for remote physiological monitoring, accelerating capital deployment into connected diagnostic infrastructure.
- Bluetooth Low Energy sensor miniaturization:Wearable biosensors now transmit continuous glucose and cardiac rhythm data with sub-1mW power budgets, enabling week-long untethered operation.
- FDA software-as-a-medical-device guidance:The agency's 2022 enforcement discretion updates clarified predicate pathways for algorithm-driven diagnostics, reducing regulatory uncertainty for cloud-connected entrants.
Market Restraints
- Lithium polymer battery supply concentration:Cylindrical cell production clusters in China and South Korea expose device OEMs to freight volatility and export license delays.
- EU MDR Class IIa reclassification:Connected diagnostic accessories now require notified body review under stricter clinical evidence standards, extending time-to-market by 12-18 months.
- Optical sensor performance ceilings:PPG-based heart rate monitors face accuracy degradation in dark skin phototypes and high-motion environments, limiting addressable populations.
Strategic Opportunities
- Rural Medicare Advantage penetration:United States counties with fewer than 50,000 residents show 40% lower RPM adoption rates than urban benchmarks, presenting whitespace for cellular-enabled device bundles.
- Japan PMDA fast-track pathway:The regulator's Sakigake designation grants priority review to software-driven therapeutics, compressing approval timelines for AI-integrated monitoring platforms.
- Continuous temperature and respiratory rate convergence:Multi-parameter patches combining MEMS thermistors and impedance pneumography are displacing single-vital devices in post-acute care protocols.
Industry Challenges
- FDA 510(k) engineering documentation burden:Pre-submission meetings now require executable algorithm validation datasets, straining quality management systems at sub-$50M revenue device firms.
- HIPAA security rule technical safeguard implementation:Encryption key management for Bluetooth Low Energy peripheral-to-cloud transmission chains demands dedicated cybersecurity headcount.
- Legacy EHR integration complexity:HL7 FHIR API maturity varies across Epic, Cerner, and Meditech installations, forcing custom interface development for each health system deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ehealth Devices Market |
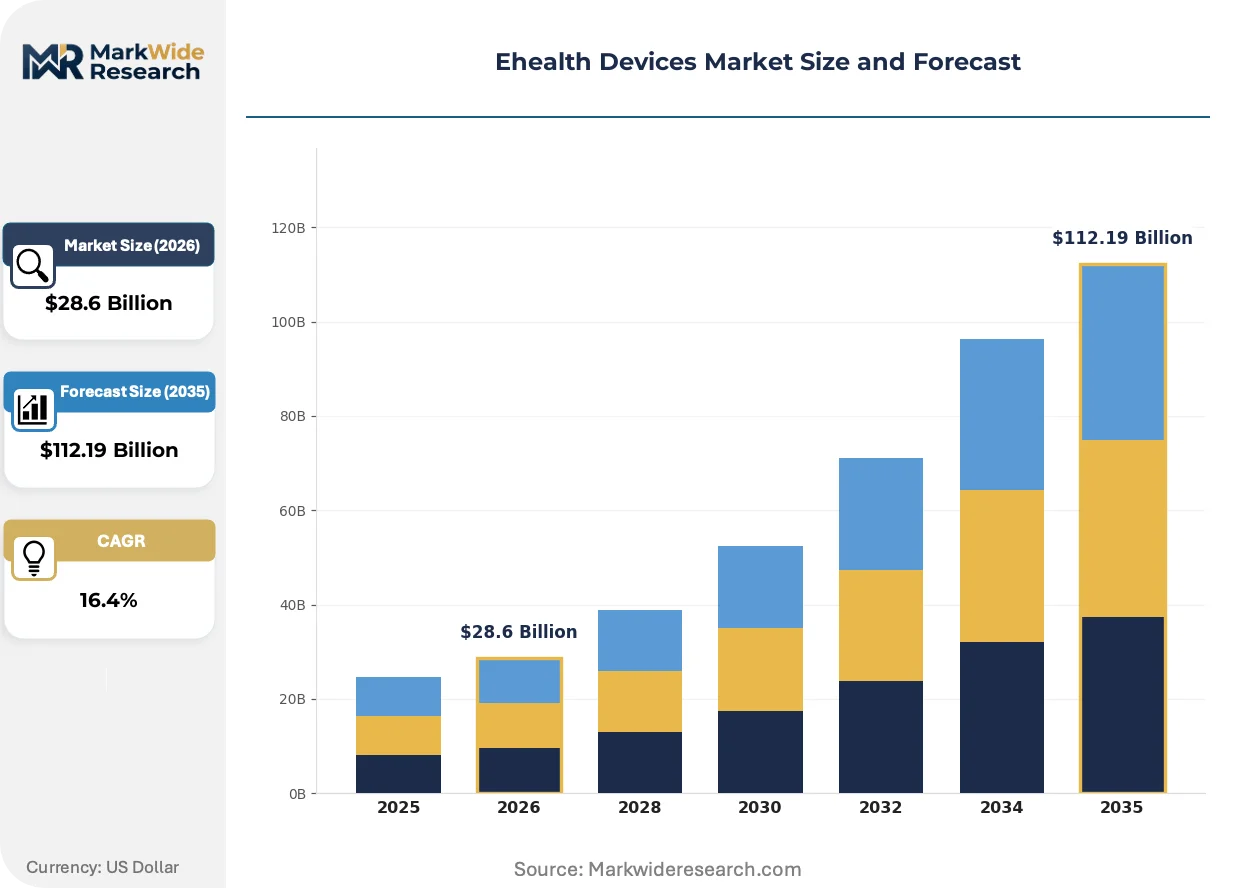
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $112.19 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Devices, Remote Monitoring, Telehealth Platforms, Mobile Health Apps Technology: Bluetooth, NFC, Wireless Sensor Networks, Cloud Computing End User: Patients, Healthcare Providers, Insurance Companies, Researchers Delivery Mode: Direct Sales, Online Distribution, Third-party Retail, Subscription Services |
| Companies Covered | GE Healthcare, Siemens Healthineers, Medtronic, Abbott Laboratories, Koninklijke Philips, Boston Scientific, OMRON Healthcare, Johnson & Johnson, Fitbit, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ehealth Devices Market Strategic Shifts & Innovations
Edge computing architectures are redistributing analytical workloads from centralized clouds to device-local processors, reshaping power budgets, data governance frameworks, and real-time alerting latency requirements across the connected health stack.
Photoplethysmography is absorbing multi-wavelength LED configurations that enable non-invasive hemoglobin and blood pressure estimation. Cardiology-focused RPM vendors in Germany and Japan are piloting these enhanced optical stacks for heart failure exacerbation prediction. The technology is absorbing analytical functions previously requiring cuff-based or invasive measurement, compressing device form factors and patient adherence barriers.
EU MDR Article 10 post-market surveillance requirements now mandate systematic literature review and periodic safety update reporting for all Class IIa connected devices. This obligation is forcing device firms to maintain dedicated clinical affairs teams or contract with European authorized representatives. Sleep therapy and continuous glucose monitoring categories face the steepest compliance cost escalation as their installed bases generate voluminous real-world performance data.
Health system procurement committees now require interoperability certification against ONC's 21st Century Cures Act information blocking rules before contract execution. Device vendors lacking standardized FHIR APIs are losing RFP eligibility at integrated delivery networks in California, Texas, and New York. This behavioral shift is privileging established platform players with dedicated integration engineering teams over point-solution hardware specialists.
Ehealth Devices Market Segmentation
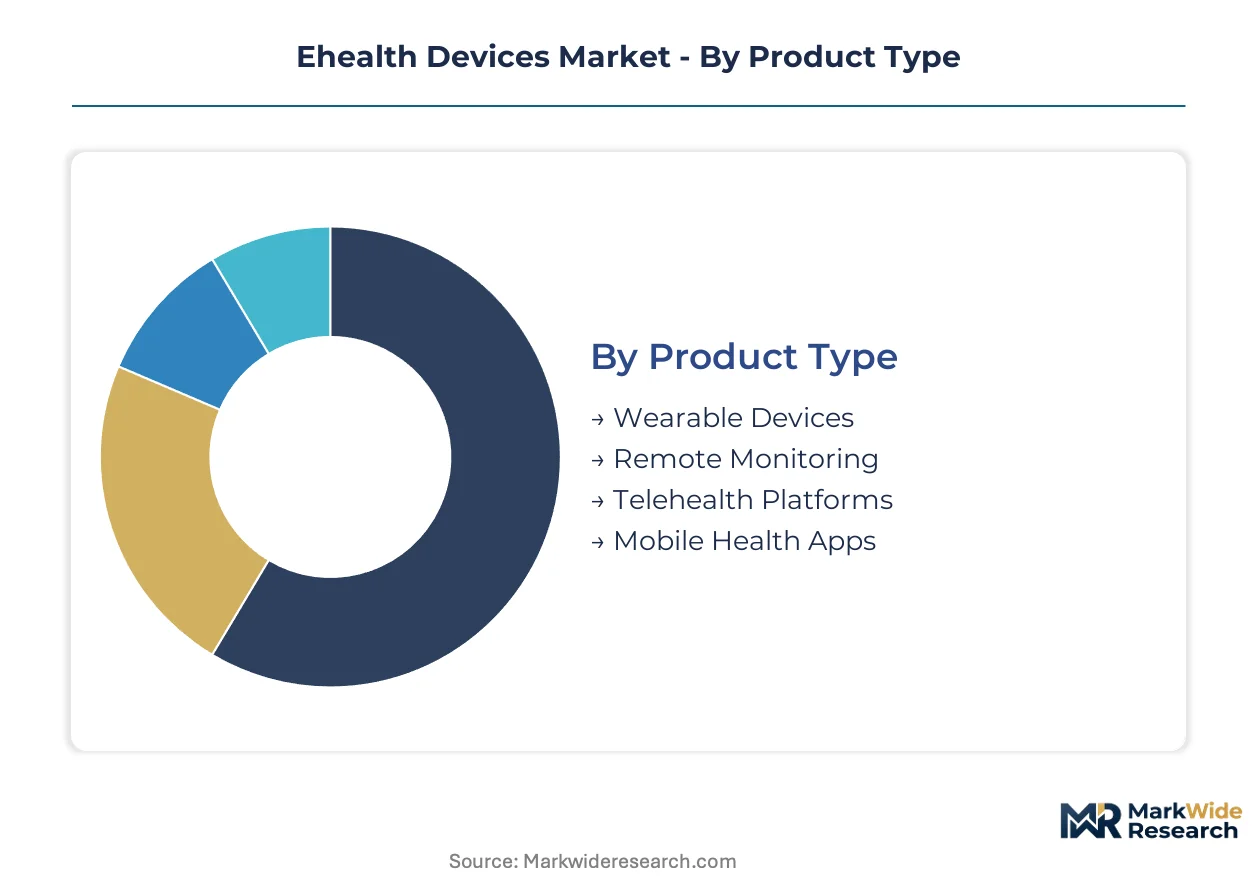
Ehealth device manufacturers face divergent engineering and commercial requirements across patient-facing hardware, clinician dashboards, and reimbursement infrastructure. Segmentation reveals where capital deployment concentrates versus where regulatory complexity erodes margins.
Product Type:
Standardization dominates at the component level while software layers enable customization for disease-specific protocols and health system integration requirements.
- Wearable Devices:Wrist-worn and patch-based biosensors incorporating PPG, accelerometry, and temperature sensing for continuous ambulatory monitoring. Demand concentrates in United States Medicare Advantage populations seeking glucose and cardiac rhythm tracking, driven by CMS reimbursement expansion for remote physiological monitoring.
- Remote Monitoring:Hub-and-peripheral systems transmitting vital signs to cloud-based clinician dashboards via cellular or Wi-Fi backhaul. United States hospital-at-home programs and German cardiac rehabilitation centers anchor procurement, propelled by accountable care organization savings incentives and DiGA (Digital Health Applications) prescription pathways.
- Telehealth Platforms:Video consultation and asynchronous messaging infrastructure with EHR integration capabilities.
- Mobile Health Apps:Smartphone-based symptom tracking and medication adherence tools with varying degrees of FDA-regulated diagnostic functionality.
Leading the category by volume: Wearable Devices. Expanding most quickly: Remote Monitoring.
Technology:
Cost tier separation runs from commodity wireless protocols to specialized infrastructure requiring dedicated IT security investment.
- Bluetooth:Low Energy 5.0 and 5.3 implementations enabling sub-1mW power consumption for week-long untethered biosensor operation. United States and Japanese device OEMs standardize on Nordic Semiconductor and Silicon Labs chipsets, pressured by FDA cybersecurity guidance mandating encrypted peripheral-to-hub transmission.
- Cloud Computing:Multi-tenant AWS, Azure, and Google Cloud deployments supporting real-time analytics and HIPAA-compliant data residency. United States integrated delivery networks and German university hospitals drive demand, constrained by EU GDPR data localization requirements and Health Canada PIPEDA alignment obligations.
- NFC:Near-field pairing and authentication for device onboarding and medication compliance verification.
- Wireless Sensor Networks:Mesh topology implementations for inpatient and residential facility-wide monitoring.
Dominating procurement budgets: Cloud Computing. Gaining share fastest: Bluetooth.
End User:
Customer type determines pricing power, with direct-to-patient models facing higher acquisition costs than institutional procurement.
- Patients:Direct consumers and caregivers purchasing wearables and apps through retail or subscription channels. United States seniors with chronic conditions represent the addressable core, though optical sensor accuracy limitations in dark skin phototypes restrict penetration.
- Healthcare Providers:Hospitals, physician practices, and home health agencies deploying RPM for population health management. United States accountable care organizations and Japan's community-based integrated care systems anchor volume, motivated by bundled payment incentives and PMDA fast-track reimbursement.
- Insurance Companies:Payers subsidizing device deployment for risk stratification and utilization reduction.
- Researchers:Academic and pharmaceutical clinical trial sponsors requiring regulatory-grade data capture.
Capturing largest procurement volume: Healthcare Providers. Steepest expansion trajectory: Patients.
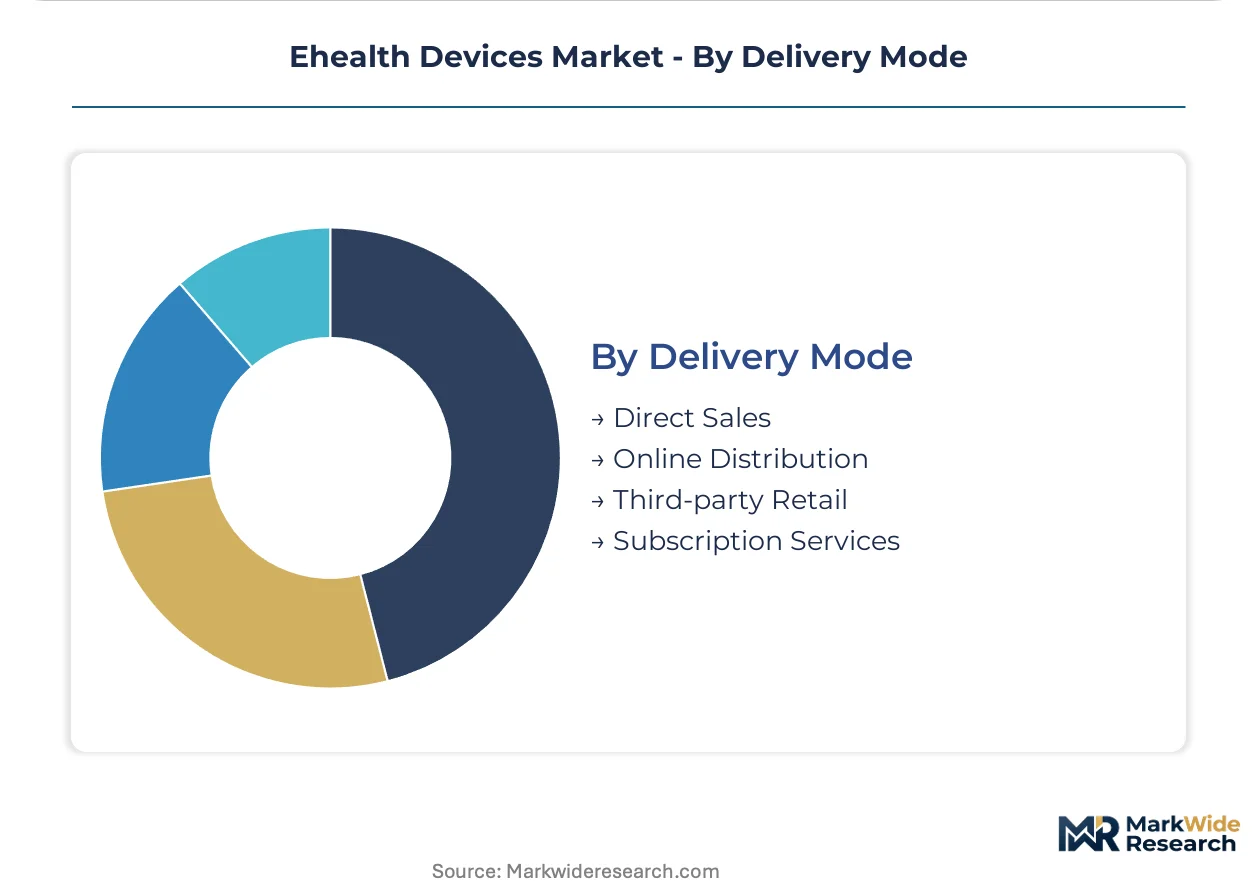
Delivery Mode:
Margin structure varies sharply between capital-intensive direct sales forces and asset-light digital distribution.
- Subscription Services:Recurring-revenue models bundling hardware, connectivity, and clinical monitoring with per-patient-per-month pricing. United States RPM vendors and German sleep therapy providers prioritize this structure, responding to health system procurement committees demanding operational expenditure treatment versus capital equipment purchase.
- Direct Sales:Field-based account executives targeting integrated delivery network procurement committees with multi-year enterprise agreements. United States medical device incumbents and Philips in the Netherlands maintain dedicated health system sales teams, challenged by elongated buying cycles and interoperability certification requirements.
- Online Distribution:Direct-to-consumer and B2B e-commerce for standardized wearable hardware.
- Third-party Retail:Pharmacy and consumer electronics storefronts for over-the-counter biosensors.
Highest revenue concentration: Subscription Services. Fastest channel growth: Direct Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States Medicare reimbursement expansion for remote physiological monitoring concentrates demand among accountable care organizations seeking hospital-at-home savings. Germany's DiGA prescription pathway and Japan's PMDA fast-track designation accelerate regulatory approval for software-driven therapeutics.
United States
CMS reimbursement codes for remote patient monitoring drive procurement among Medicare Advantage plans and integrated delivery networks. FDA 510(k) premarket notification volume for software-based devices raises engineering documentation costs for connected health entrants. The Minneapolis medical technology corridor anchors cardiac rhythm and glucose-sensing wearable development.
Germany
DiGA prescription reimbursement under the Digital Healthcare Act accelerates adoption of app-based therapeutic interventions. EU MDR Class IIa reclassification for connected diagnostic accessories extends time-to-market through stricter notified body review. The Erlangen healthcare engineering cluster concentrates imaging and patient monitoring system manufacturing.
Japan
Community-based integrated care systems deploy remote monitoring for aging populations under PMDA fast-track pathways. METI promotes standardization of wireless sensor networks for home-based chronic disease management. The Tokyo-Osaka corridor anchors sleep therapy and telehealth infrastructure development.
United Kingdom
NHS Long Term Plan targets for digital-first primary care expand procurement of clinician dashboard platforms. MHRA alignment with EU MDR post-market surveillance requirements elevates clinical evidence standards for connected accessories. The Cambridge-Oxford-London triangle concentrates health AI and biosensor startup formation.
China
NMPA regulatory pathways for software-as-a-medical-device clarify predicate requirements for algorithm-driven diagnostics. MIIT 5G infrastructure deployment enables real-time vital sign transmission for tiered hospital networks. The Shenzhen hardware ecosystem concentrates wearable biosensor manufacturing and Bluetooth Low Energy chipset integration.
Ehealth Devices Market Key Industry Players
United States producers anchor the premium-tier device segment; European specialists hold regulatory compliance and imaging integration capabilities. The vendor base stratifies across diversified health technology conglomerates, pure-play wearable manufacturers, and regional monitoring system suppliers. Three archetypes dominate: cardiac rhythm portfolio owners, glucose-sensing wearable specialists, and sleep therapy platform operators. Competitive moves concentrate on strategic partnerships with health systems and portfolio diversification into subscription-based remote monitoring services.
Within the diversified health technology tier, Medtronic and Abbott Laboratories occupy positions exemplifying cardiac and metabolic monitoring specialization respectively. Koninklijke Philips represents the integrated platform archetype spanning sleep therapy and telehealth infrastructure. These three entities anchor distinct competitive vectors—implantable device ecosystems, consumer-facing biosensor-cloud analytics integration, and health system subscription services—each capturing procurement committees through installed base loyalty and interoperability certification.
| Leading Market Players |
|---|
| GE Healthcare |
| Siemens Healthineers |
| Medtronic |
| Abbott Laboratories |
| Koninklijke Philips |
| Boston Scientific |
| OMRON Healthcare |
| Johnson & Johnson |
| Fitbit |
| Others |
Cost & Logistics Intelligence
Firmware engineering talent concentration in the Minneapolis medical technology corridor widens labor-cost differentials between premium-tier cardiac rhythm device manufacturers and economy-tier consumer wearable producers, compressing mid-market pricing spreads as quality validation requirements escalate.
Pricing Analysis
Volume-vs-margin splits sharply across the ehealth device landscape, with subscription-based remote patient monitoring services capturing recurring revenue premiums while transactional wearable hardware faces commoditization pressure. Three-tier pricing structure across FDA-cleared clinical grade, wellness-certified consumer grade, and unregulated economy grade separates procurement committees at integrated delivery networks from direct-to-patient retail buyers. Cost compression in the wellness tier intensifies because optical sensor module prices are falling amid Chinese manufacturing scale. Healthcare providers show lowest price sensitivity due to bundled payment incentives, while uninsured direct consumers exhibit highest elasticity.
Supply Chain Analysis
Local-content-rule angles are reshaping sourcing as the United States Buy American provisions and EU strategic autonomy initiatives pressure device OEMs to qualify secondary component vendors outside China. Lithium polymer cell production clusters in China and South Korea, Bluetooth Low Energy chipset fabrication in Taiwan, and MEMS sensor packaging in Malaysia anchor upstream supply. Raw material dependencies span cobalt for battery cathodes, gallium arsenide for optical emitters, and medical-grade silicones for skin-contact adhesives. Single-source vulnerability in cylindrical battery supply creates exposure to export license delays. Distribution runs through health system procurement committees for institutional volumes and direct-to-consumer e-commerce for retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ehealth device manufacturing is consolidating around platform-scale players as FDA 510(k) engineering documentation burdens force sub-$50M revenue firms toward acquisition or exit.
For Market Incumbents: Hedge regulatory exposure by acquiring notified body relationships in Europe ahead of EU MDR Class IIa reclassification deadlines. Deepen backward integration into cloud computing infrastructure to capture subscription service margins currently flowing to AWS and Azure. Defensive positioning against pure-play wearable entrants requires interoperability certification investments that smaller competitors cannot fund. For New Entrants and Emerging Players: Begin with rural Medicare Advantage penetration in United States counties below 50,000 residents where RPM adoption lags urban benchmarks by 40%. Cellular-enabled device bundles bypass the Bluetooth pairing complexity that frustrates elderly patient onboarding. Direct sales to community-based integrated care systems in Japan offers faster reimbursement traction than United States hospital procurement cycles. For Investors and Strategic Acquirers: Re-rating potential sits with software-as-a-medical-device specialists given FDA pre-certification pathway maturation compressing approval timelines for algorithm-driven diagnostics. Long-term viability over the coming decade favors platforms with installed base loyalty through EHR integration rather than point-solution hardware vendors. Watch Japan PMDA Sakigake designation grants as the inflection signal for AI-integrated monitoring platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Premarket Submission | Software-based device entrants secure predicate pathways under 2022 enforcement discretion updates. |
| CE Marking Pathway | EU MDR Class IIa reclassification demands notified body review extending time-to-market timelines. |
| Hospital System Partnership | Integrated delivery network procurement committees require ONC interoperability certification before contract execution. |
| Software Companion Development | Cloud analytics platforms differentiate glucose-sensing wearables from commodity hardware competitors. |
| Reimbursement Strategy | Medicare Advantage remote physiological monitoring codes drive accountable care organization capital deployment. |
Research Approach
Multi-period observation of FDA 510(k) clearance volumes, CMS reimbursement code creation, and EU MDR notified body queue lengths anchored the trend analysis, supplemented by interviews with biomedical engineers at cardiac rhythm device manufacturers, GPO contracts managers at United States integrated delivery networks, regulatory affairs leads at glucose-sensing wearable firms, and cloud platform architects at telehealth infrastructure providers. Secondary validation drew from FDA 510(k) database filings, EU MDR Article 10 post-market surveillance reports, CMS Medicare claims data, and hospital procurement database records. Bottom-up device shipment modeling and top-down healthcare IT spending estimates provided triangulation checks.
Input-output matrix framing structured the forecast framework across product type dimensions of wearable hardware, remote monitoring systems, and telehealth platforms; technology dimensions of Bluetooth Low Energy, cloud computing, and wireless sensor networks; and end user dimensions of patients, healthcare providers, and insurance payers. CAGRs were derived from segment-level growth rate reconciliation against macro healthcare expenditure trends. Industry-specific forecast inputs included lithium polymer battery supply elasticity and health system EHR integration pipeline capacity.
FDA guidance revision, EU MDR implementation delays, and optical sensor accuracy litigation are the dominant revision risks that could compress or extend the projected expansion trajectory. Forecasts reflect assumptions about reimbursement code stability and regulatory pathway predictability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Tattoo Removal Devices Market
Medical Devices
3D Printing for Surgical Procedures Market
Medical Devices
Epilepsy Treatment Devices Market
Medical Devices
Global Hip Implant Market
Medical Devices
Transcatheter Bioprosthesis Market
Medical Devices
High Pressure Contrast Media Injectors Market
Medical Devices
Global Bone Tumor Ablation Devices Market
Medical Devices
Venous Procedure Devices Market
Medical Devices
IV Fluid Monitoring Device Market
Medical Devices
Electrocardiograph (ECG) Market
Medical Devices
Ambulatory Polysomnography (Psg) Systems Market
Medical Devices
Cardiac Rhythm Management (CRM) Devices Batteries Market
Medical Devices
3D-Printed Prosthetic Implants Market
Medical Devices
Global Ultrasound Devices Market
Medical Devices
Pelvic Electro-Stimulators Market
Medical Devices
Epistaxis Devices Market