
 Global Orthopedic Surgical Robots Market | 2026-2036
Global Orthopedic Surgical Robots Market Size, Share, and Industry Trends Forecast 2026-2036
Global Orthopedic Surgical Robots Market Foresight
The capability gap between capital-heavy integrated platform developers and component-focused vendors is collapsing as software-defined surgical workflows commoditize hardware margins. Stryker leverages its installed base of Mako robotic arm systems to sustain recurring revenue from instrument and implant attachments. Zimmer Biomet competes through ROSA platform specialization in knee arthroplasty, while Medtronic anchors its position via navigation system integration with spinal procedure portfolios.
Orthopedic surgical robots are electromechanical systems combining robotic arms, optical tracking arrays, and preoperative planning software to execute bone resection and implant positioning with submillimeter accuracy. These systems serve the primary purpose of reducing mechanical alignment errors in joint replacement and improving reproducibility across surgeon experience levels. Robotic arm systems command the dominant share of capital expenditure as hospitals prioritize platforms with multi-procedure versatility across knee and hip applications. Artificial intelligence integration represents the fastest-expanding technology segment, with algorithms now automating preoperative planning and intraoperative adjustment protocols that previously required manual surgeon input.
FDA 510(k) clearance requirements and EU MDR conformity assessment shape product development timelines and geographic launch sequencing for manufacturers. ISO 13485 quality management standards and IEC 60601 electrical safety specifications govern manufacturing protocols that determine market access eligibility across regulated jurisdictions. Stakeholders must monitor how reimbursement coding decisions by CMS and analogous national health technology assessment bodies influence hospital capital allocation toward robotic platforms versus conventional instrumentation.
Market Dynamics
Software-defined surgical workflows are collapsing the traditional hardware margin advantage of integrated platform developers, forcing vendors to compete on algorithmic differentiation rather than mechanical precision alone. This shift concentrates competitive advantage in data-rich installed bases and recurring software revenue streams.
Growth Catalysts
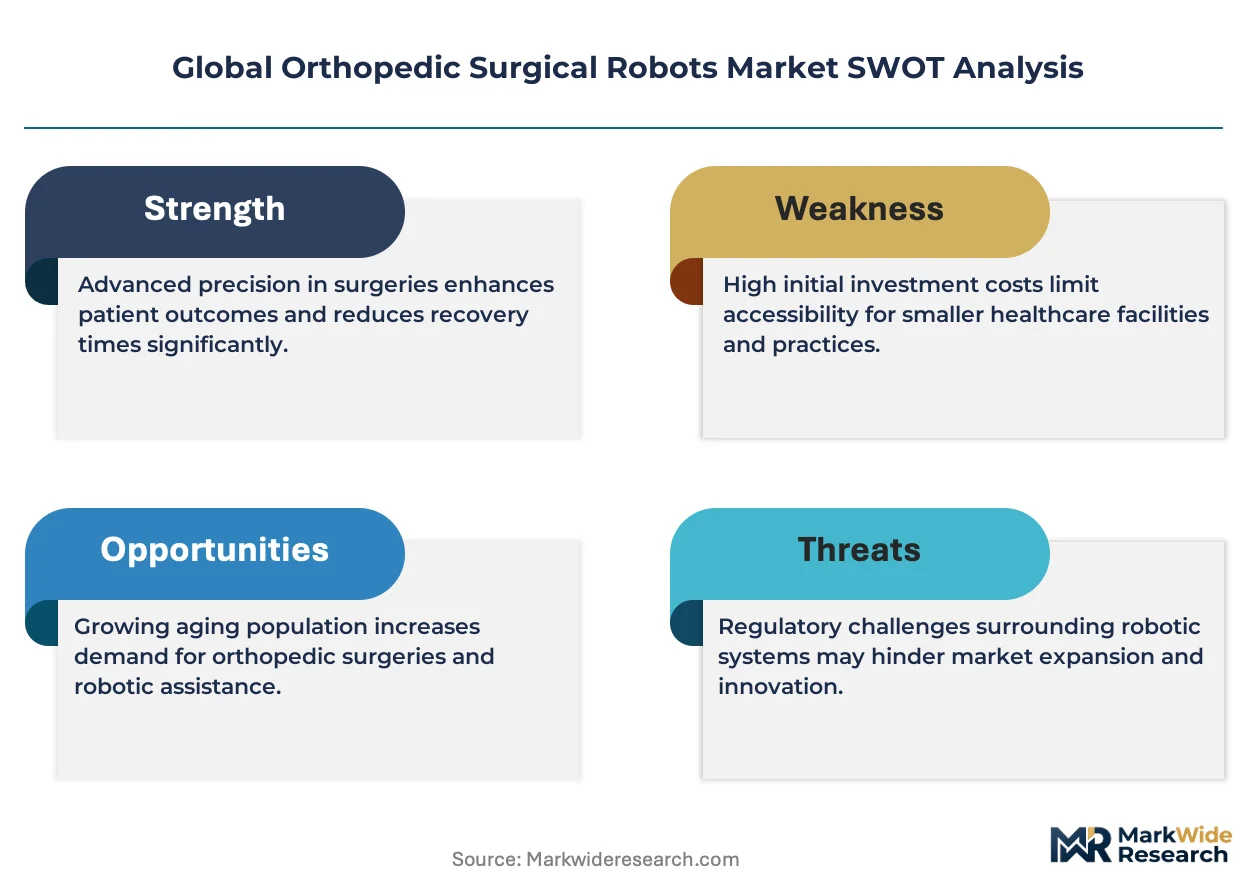
- FDA 510(k) Clearance Pathways:Streamlined premarket notification procedures for computer-assisted orthopedic devices accelerate time-to-market for robotic arm systems and navigation platforms entering US hospital networks.
- Germany's Reimbursement Alignment:National health technology assessment bodies in Germany now cover knee and hip arthroplasty procedures performed with robotic assistance, directly accelerating capital procurement cycles for university hospitals.
- Machine Learning Integration:Artificial intelligence algorithms automating preoperative planning and intraoperative adjustment protocols reduce surgeon cognitive load and standardize outcomes across experience levels.
Market Restraints
- Capital Equipment Intensity:Robotic arm platforms require seven-figure upfront investment plus dedicated surgical suite retrofitting, limiting penetration to tier-one academic medical centers and constraining community hospital adoption.
- Titanium and Cobalt-Chrome Supply Concentration:Implant-grade alloy supply chains concentrate in Chinese and Russian primary metal producers, exposing manufacturers to input cost volatility and export restriction risk.
- EU MDR Conformity Assessment:Extended clinical evaluation requirements and notified body capacity constraints delay product launches in European markets by 18-24 months versus previous Medical Device Directive timelines.
Strategic Opportunities
- Outpatient Surgery Center Penetration:Ambulatory surgical facilities in the United States represent underpenetrated deployment sites for compact robotic platforms designed for same-day discharge protocols.
- Shoulder and Ankle Arthroplasty Expansion:Robotic systems historically optimized for knee and hip applications now extend into upper extremity and small-joint procedures, opening addressable procedure volumes.
- Japan's Super-Aged Society Demographics:METI innovation subsidies and PMDA accelerated review pathways for aging-related medical devices create favorable regulatory tailwinds for orthopedic robot manufacturers targeting Japanese hospital procurement.
Industry Challenges
- Surgeon Training Pipeline Constraints:Proctorship requirements and case volume thresholds for robotic certification create bottlenecks in qualified operator availability, limiting system utilization rates post-installation.
- Legacy EMR Integration Complexity:Robotic platforms must interface with heterogeneous hospital information systems, requiring custom API development and IT security validation that extends implementation timelines.
- Patent Thicket Navigation:Dense intellectual property landscapes around haptic feedback mechanisms and optical tracking arrays generate licensing disputes and freedom-to-operate analysis costs for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Orthopedic Surgical Robots Market |
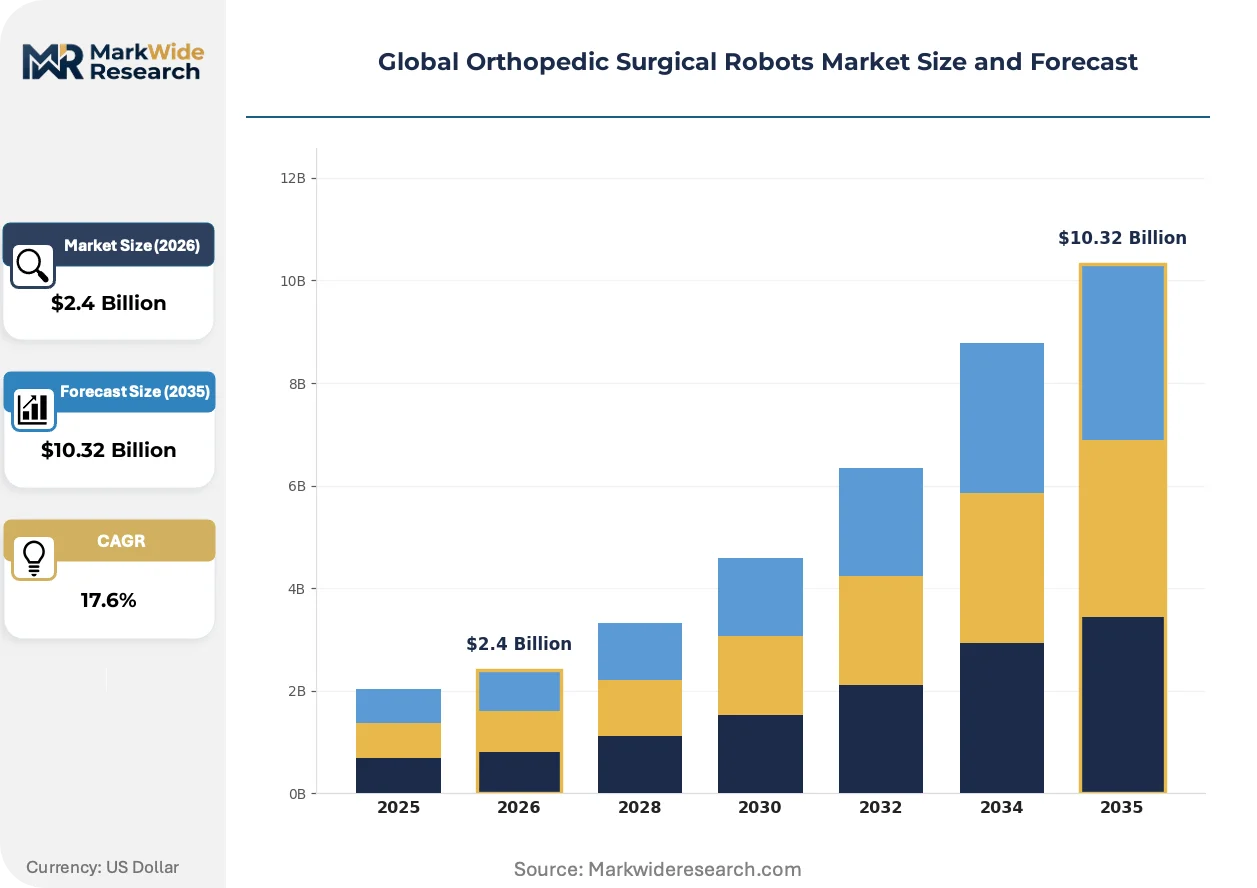
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $10.32 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Robotic Arm Systems, Navigation Systems, Imaging Systems, Integrated Solutions End User: Hospitals, Ambulatory Surgery Centers, Orthopedic Clinics, Rehabilitation Centers Technology: Minimally Invasive, Computer-Assisted Surgery, Augmented Reality, Artificial Intelligence Procedure Type: Knee Surgery, Hip Surgery, Spine Surgery, Shoulder Surgery |
| Companies Covered | Stryker, Zimmer Biomet, Medtronic, Smith & Nephew, Johnson & Johnson, Intuitive Surgical, Globus Medical, Brainlab, Think Surgical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Orthopedic Surgical Robots Market Shifts & Advancements
Orthopedic surgical robotics is experiencing a fundamental recomposition where hardware commoditization and algorithmic differentiation are simultaneously reshaping vendor economics and hospital procurement criteria.
Cloud-native surgical planning software is bifurcating the competitive landscape between vendors offering closed-loop integrated ecosystems and those pursuing interoperability-first architectures. Tier-one academic medical centers in the United States and Germany are adopting hybrid deployment models that combine proprietary robotic hardware with third-party AI planning tools. This technology convergence is compressing margins on standalone navigation systems while elevating data platform subscriptions to primary revenue contributors.
EU MDR Article 61 clinical evidence requirements are forcing manufacturers to generate prospective registry data for legacy robotic platforms previously cleared under the Medical Device Directive. The industrial consequence is a diversion of R&D expenditure toward post-market surveillance infrastructure rather than next-generation hardware development. Knee arthroplasty systems face the steepest compliance burden due to high implant volumes and existing national joint registries in Sweden, the United Kingdom, and Australia.
Hospital procurement committees are consolidating vendor relationships around single-platform contracts that bundle capital equipment, disposables, and extended warranty coverage. Orthopedic service lines in US health systems are replacing transactional instrument purchasing with multi-year total cost-of-ownership agreements. This behavioral shift is most visible in integrated delivery networks across Texas, Florida, and California where centralized supply chain governance overrides individual surgeon equipment preferences.
Global Orthopedic Surgical Robots Market Segmentation
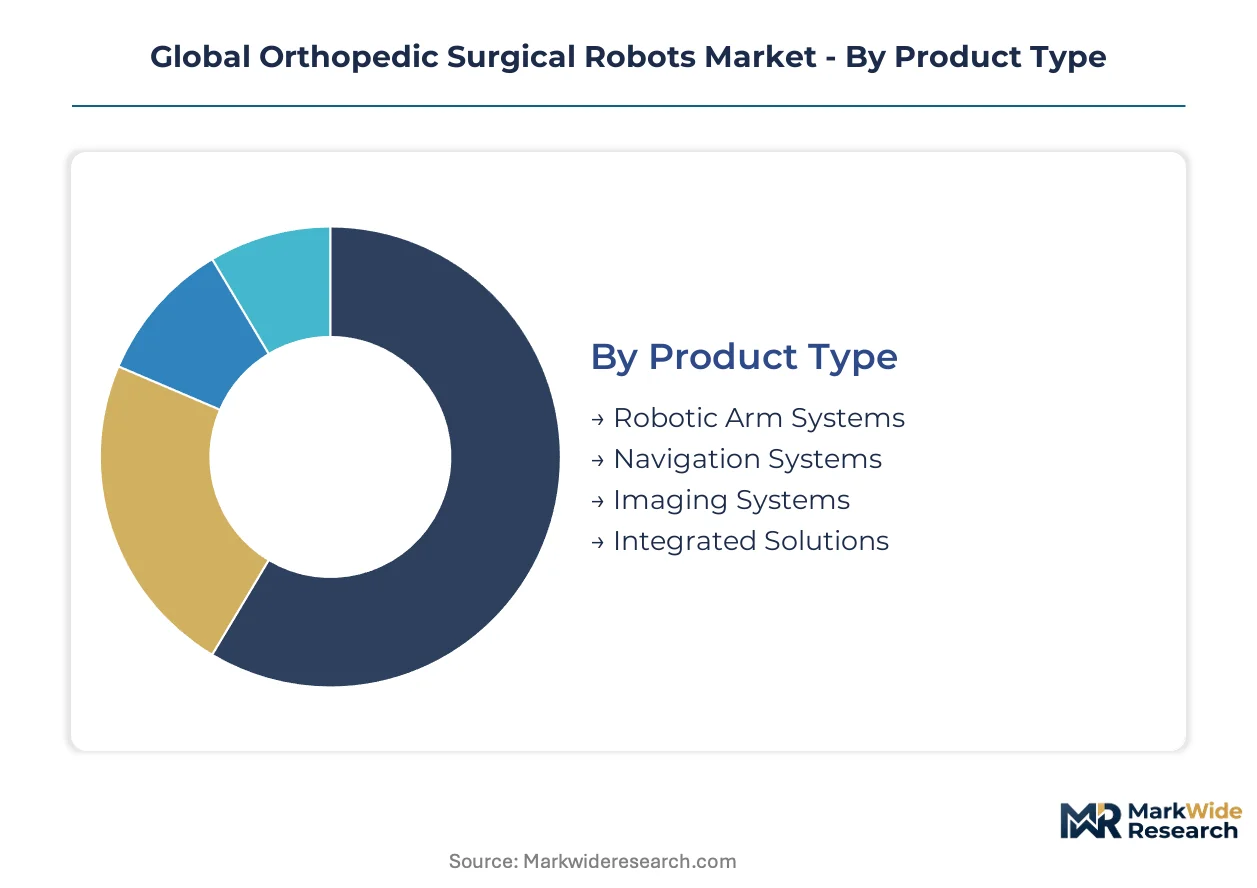
Segmentation in orthopedic surgical robotics reveals how regulatory pathways, capital intensity, and procedure specialization create distinct competitive arenas. Product architecture and end-user economics determine vendor strategy more than raw technical capability alone.
Product Type:
FDA 510(k) clearance timelines diverge sharply between capital-intensive robotic arm platforms and software-centric navigation tools, creating tiered market entry barriers.
- Robotic Arm Systems:Electromechanical platforms combining servo-controlled manipulators with optical tracking arrays for bone resection and implant positioning. Demand concentrates in German university hospitals and US academic medical centers where CMS reimbursement codes for computer-assisted arthroplasty justify seven-figure capital outlays. EU MDR Article 61 clinical evidence requirements extend conformity assessment timelines for these Class IIb devices.
- Navigation Systems:Optical and electromagnetic tracking platforms providing real-time instrument localization without robotic actuation. Adoption accelerates in Japanese orthopedic clinics where METI innovation subsidies offset equipment costs for aging-related procedures. PMDA accelerated review pathways compress regulatory lead times versus full robotic platforms.
- Imaging Systems:Intraoperative CT and fluoroscopy modules enabling three-dimensional surgical planning.
- Integrated Solutions:Closed-loop platforms bundling robotic hardware, navigation, and proprietary implant systems.
Established volume favors Robotic Arm Systems; emerging adoption favors Navigation Systems.
End User:
Capital deployment patterns track reimbursement density and surgical volume thresholds across facility types.
- Hospitals:Tier-one academic medical centers with dedicated orthopedic service lines and established robotic surgery programs. German DRG-based reimbursement for knee and hip arthroplasty procedures performed with robotic assistance drives procurement cycles at university hospitals in Berlin, Munich, and Hamburg. US health systems in Texas, Florida, and California consolidate vendor relationships around multi-year total cost-of-ownership agreements.
- Ambulatory Surgery Centers:Same-day discharge facilities requiring compact platforms with reduced footprint and sterilization infrastructure. US outpatient procedural volume growth and site-of-service payment differentials create favorable economics for ASC deployment in suburban Dallas, Phoenix, and Tampa markets.
- Orthopedic Clinics:Specialist practices with limited surgical suite infrastructure and lower case volume thresholds.
- Rehabilitation Centers:Post-acute facilities focusing on recovery protocols rather than primary surgical intervention.
Procurement concentration sits with Hospitals; Ambulatory Surgery Centers offer the steepest expansion trajectory.
Technology:
Software-defined differentiation is compressing hardware margins while elevating algorithmic capabilities as primary competitive vectors.
- Minimally Invasive:Tissue-sparing approaches through smaller incisions reducing recovery timelines and complication rates. Demand concentrates in US metropolitan markets where patient-reported outcome metrics influence hospital quality ratings and payer contracting.
- Computer-Assisted Surgery:Preoperative planning software and intraoperative guidance systems standardizing mechanical alignment across surgeon experience levels. German health technology assessment bodies explicitly evaluate CAS outcomes in national joint registry data.
- Augmented Reality:Head-mounted displays and holographic visualization overlaying patient anatomy onto the surgical field.
- Artificial Intelligence:Machine learning algorithms automating preoperative planning and intraoperative adjustment protocols.
Computer-Assisted Surgery commands current installed base; Artificial Intelligence is gaining share fastest.
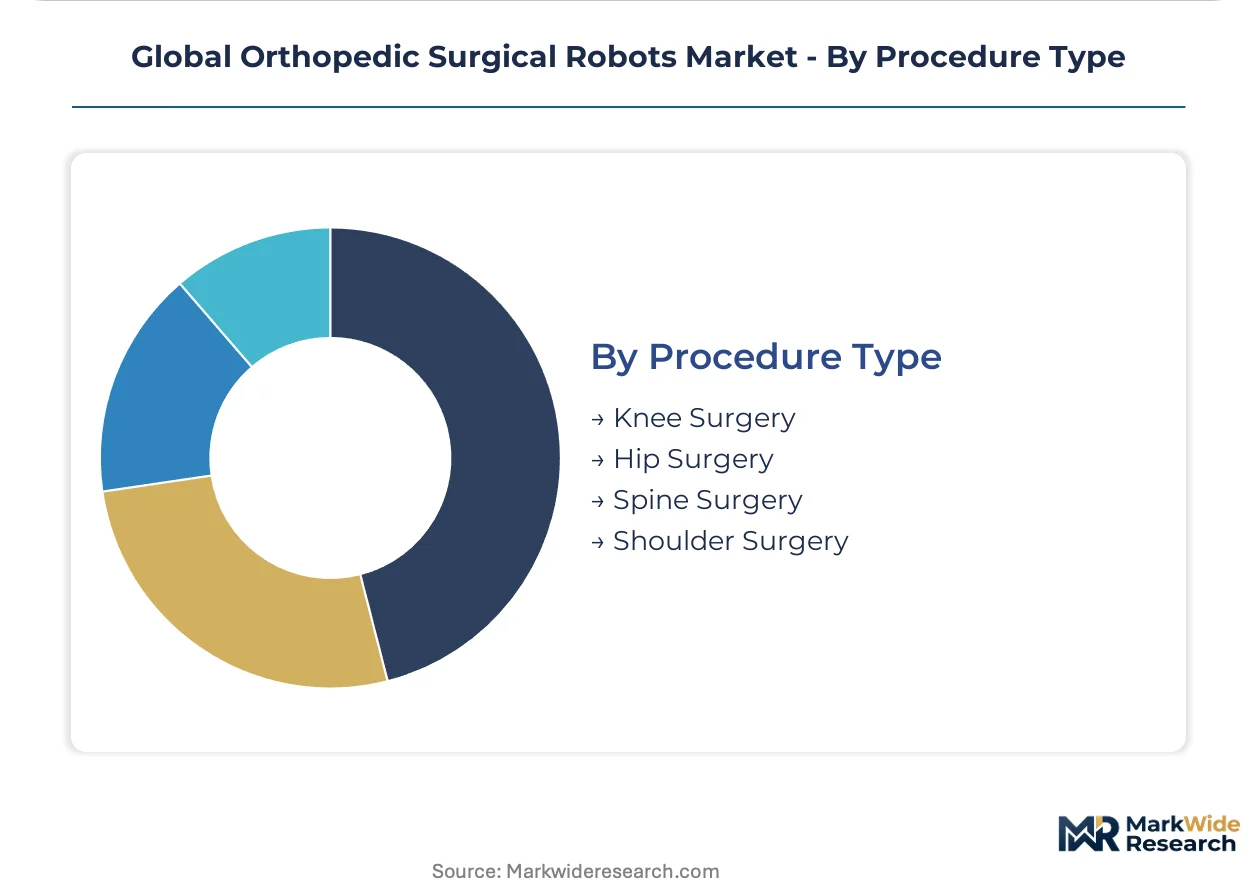
Procedure Type:
Procedure-specific regulatory clearances and implant portfolio alignment determine vendor addressable market scope.
- Knee Surgery:Total and partial knee arthroplasty representing the largest procedural volume with established robotic platforms. Swedish, UK, and Australian national joint registries generate prospective outcome data that EU MDR now mandates for continued market access.
- Hip Surgery:Total hip arthroplasty and resurfacing procedures requiring distinct acetabular resection and femoral preparation workflows. German reimbursement alignment for hip arthroplasty performed with robotic assistance parallels knee procedure coverage.
- Spine Surgery:Pedicle screw placement and interbody fusion procedures integrating navigation with spinal implant systems.
- Shoulder Surgery:Upper extremity arthroplasty representing emerging application expansion with smaller addressable volumes.
Knee Surgery anchors current revenue; Shoulder Surgery presents the most open competitive terrain.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement committees in Germany extract 15-20% price premiums for robotic platforms versus identical systems sold to US academic medical centers, reflecting divergent reimbursement density and capital allocation authority. Japanese manufacturers face compressed margins in domestic tenders despite METI subsidies, while Chinese hospital groups leverage volume aggregation to force steeper discounts from multinational vendors.
United States
Integrated delivery networks in Texas, Florida, and California consolidate vendor relationships around multi-year total cost-of-ownership agreements that bundle capital equipment, disposables, and extended warranty coverage. FDA 510(k) clearance pathways for computer-assisted orthopedic devices streamline market entry for robotic arm systems entering US hospital networks. Suburban Dallas, Phoenix, and Tampa ambulatory surgery centers drive compact platform deployment for same-day discharge protocols.
Germany
University hospitals in Berlin, Munich, and Hamburg accelerate capital procurement cycles as national health technology assessment bodies cover knee and hip arthroplasty procedures performed with robotic assistance. EU MDR Article 61 clinical evidence requirements extend conformity assessment timelines for Class IIb robotic arm devices. German DRG-based reimbursement alignment directly justifies seven-figure capital outlays at academic medical centers.
Japan
METI innovation subsidies and PMDA accelerated review pathways for aging-related medical devices create favorable regulatory tailwinds for orthopedic robot manufacturers targeting Japanese hospital procurement. Navigation system adoption accelerates in orthopedic clinics where equipment cost offsets address super-aged society demographics. Kanto and Kansai metropolitan hospital clusters prioritize compact platforms with reduced surgical suite footprints.
Australia
National joint registry data in Australia generates prospective outcome evidence that EU MDR now mandates for continued market access of knee arthroplasty systems. TGA regulatory frameworks align with ISO 13485 quality management standards governing manufacturing protocols. Sydney and Melbourne teaching hospitals concentrate robotic surgery program expansion alongside established national registry infrastructure.
United Kingdom
Swedish, UK, and Australian national joint registries collectively generate prospective outcome data elevating compliance burdens for knee arthroplasty systems under EU MDR transition timelines. NHS procurement frameworks emphasize outcome-based contracting that favors vendors with established real-world evidence portfolios. London and Manchester academic medical centers lead capital deployment within constrained national budget envelopes.
Global Orthopedic Surgical Robots Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated platform developers commanding premium pricing through data-rich installed bases while component-focused vendors compete on hardware commoditization. The market structure concentrates around three strategic tiers: multinational conglomerates with diversified medtech portfolios, specialized robotics pure-plays, and emerging regional challengers. Dominant competitive moves include strategic partnerships bundling capital equipment with proprietary implant systems, and geographic expansion targeting underpenetrated ambulatory surgery center channels.
Among US-based diversified medtech conglomerates, Stryker and Zimmer Biomet occupy positions anchoring the premium-tier integrated platform segment, while Medtronic represents the navigation-system specialization archetype. These three companies exemplify how recurring revenue from instrument and implant attachments sustains competitive positioning against hardware-margin compression. Their collective presence shapes procurement committee vendor consolidation patterns across German university hospitals and US integrated delivery networks.
| Leading Market Players |
|---|
| Stryker |
| Zimmer Biomet |
| Medtronic |
| Smith & Nephew |
| Johnson & Johnson |
| Intuitive Surgical |
| Globus Medical |
| Brainlab |
| Think Surgical |
| Others |
Supply & Pricing Matrix
FDA 510(k) clearance tiers and ISO 13485 certification grades simultaneously gate supplier qualification and stratify price levels across robotic arm systems and navigation platforms. Hospitals in Germany pay configured-to-order premiums for systems with integrated implant portfolios, while US ambulatory surgery centers negotiate standard-platform discounts based on case volume commitments.
Pricing Analysis
Configured-to-order pricing for robotic arm systems with proprietary implant attachments commands spreads of 40-60% above standard navigation-only configurations. Three-tier pricing structure across premium integrated platforms, standard robotic arms, and economy navigation systems reflects FDA clearance tier and after-sales service bundling. Cost compression in standard-tier hardware is intensifying because software-defined workflows commoditize mechanical precision. Ambulatory surgery centers exhibit highest price sensitivity due to capital constraints, while German university hospitals accept premium pricing for DRG-reimbursed procedures.
Supply Chain Analysis
Inventory lead times for implant-grade titanium and cobalt-chrome alloys extend 12-18 months due to concentrate processing bottlenecks in Chinese and Russian primary metal producers. Electromechanical servo systems and optical tracking arrays source from Japanese and German precision component manufacturers, while surgical planning software development centers on US and Israeli engineering clusters. Single-source vulnerability concentrates in rare earth magnet supply for robotic joint actuators. Distribution runs through authorized dealer networks with direct-to-hospital contracting for tier-one academic medical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Orthopedic surgical robotics functions as a service-attach business where software subscription revenue and instrument disposable streams expand faster than capital hardware sales. Cloud-native planning platforms and AI-powered intraoperative adjustment protocols now generate recurring revenue multiples exceeding traditional equipment financing arrangements.
For Market Incumbents: Secure data platform dominance by consolidating proprietary surgical outcome databases before open-architecture interoperability standards commoditize algorithmic differentiation. Defend against component-focused vendors by deepening backward integration into implant-grade alloy supply and expanding captive production of optical tracking arrays in Japan and Germany.
For New Entrants and Emerging Players: Lead with compact robotic platforms designed for ambulatory surgery center footprints and same-day discharge protocols in suburban US markets. Target shoulder and ankle arthroplasty applications where regulatory clearance pathways remain less crowded than knee and hip segments. Pursue white-label software partnerships with established implant manufacturers lacking robotic hardware capabilities.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed navigation system specialists seeking exit liquidity amid EU MDR compliance cost pressures. Five-to-ten year viability hinges on installed base data richness and recurring revenue attachment rates rather than hardware shipment volumes. Monitor PMDA accelerated review pathway utilization rates as inflection indicator for Japanese market penetration trajectories.
| Strategic Initiative | Industry Significance |
|---|---|
| Software Companion Development | Cloud-native planning platforms from Brainlab and Think Surgical enable recurring subscription revenue independent of hardware sales cycles. |
| Hospital System Partnership | Multi-year total cost-of-ownership agreements with Texas and Florida integrated delivery networks lock in instrument disposable streams. |
| Reimbursement Strategy | CMS coding alignment for computer-assisted arthroplasty directly influences capital procurement committee authorization timelines. |
| CE Marking Pathway | EU MDR Article 61 clinical evidence requirements force diversion of R&D expenditure toward post-market surveillance infrastructure. |
| FDA Submission | Streamlined 510(k) premarket notification for orthopedic navigation systems accelerates US market entry versus full robotic platform pathways. |
Research Methodology
Initial hypotheses were tested against primary input from orthopedic surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers and refined through secondary validation. Primary interviews explored capital allocation criteria, vendor consolidation patterns, and software integration requirements across German university hospitals and US integrated delivery networks. Secondary sources encompassed FDA 510(k) clearance databases, EU MDR notified body documentation, CMS reimbursement coding decisions, and national joint registry datasets from Sweden, the United Kingdom, and Australia. Bottom-up procedure volume modeling and top-down capital expenditure estimates were triangulated to converge market size figures.
Variance decomposition across product type, end user, technology, and procedure type segmentation dimensions isolated growth contribution by category. CAGRs were derived from logistic diffusion curves fitted to historical adoption rates and adjusted for regulatory timeline impacts and reimbursement policy shifts. Forecast inputs incorporated EU MDR transition timelines, METI subsidy program allocations, and ambulatory surgery center procedural volume migration patterns.
The analysis sits within stated boundaries; outcomes outside sustained CMS reimbursement alignment or accelerated EU MDR notified body capacity expansion would require recalibration. Forecasts reflect documented assumptions regarding software attach rates and implant disposable pricing stability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Eye Examination Equipment Market
Medical Devices
Home-Use Water Flosser Market
Medical Devices
Electroceutical Devices Market
Medical Devices
Microcurrent Facial Market
Medical Devices
Neurointerventional Devices Market
Medical Devices
Injection Practice Pad Market
Medical Devices
Oxygenator Market
Medical Devices
Germany Drug Delivery Devices Market
Medical Devices
Global Pulse Oximetry Market
Medical Devices
Pocket Ventilation Systems Market
Medical Devices
North America Renal Denervation Devices Market
Medical Devices
Australia Respiratory Devices Market
Medical Devices
Ophthalmic Ultrasound Devices Market
Medical Devices
Mexico Aesthetic Devices Market
Medical Devices
Global Cranial Implants Market
Medical Devices
Table-Top Autorefractor Market