
 Disposable Medicine Measuring Cups Market | 2026-2036
Disposable Medicine Measuring Cups Market Size, Share, and Industry Trends Forecast 2026-2036
Disposable Medicine Measuring Cups Market Outlook
Multi-source procurement among hospital buying groups is shifting toward contracted manufacturers with dedicated medical-grade molding lines. Origin Pharma Packaging leverages European regulatory certifications to sustain supply relationships with national health services. McKesson anchors North American distribution through its direct-to-pharmacy logistics network. SKYDEAR PLASTIC TECHNOLOGY (ZHEJIANG) CO.LTD competes on polystyrene cup volumes for export markets.
Disposable medicine measuring cups are single-dose or multi-dose polypropylene or polystyrene vessels with calibrated graduations, manufactured through injection molding to deliver precise liquid medication volumes for oral administration. Graduated cups dominate hospital procurement due to dosing accuracy requirements, while child-friendly cups represent the fastest-growing category as pediatric formulation volumes expand. Biodegradable materials remain niche but attract pharmacy chains seeking to differentiate on sustainability credentials.
FDA enforces strict material biocompatibility standards for devices contacting oral medications, while EMA's Medical Device Regulation classifies dosing cups as Class I accessories with escalating documentation requirements. China's NMPA aligns with GB standards for plastic food-contact materials that extend to pharmaceutical applications. Stakeholders must monitor evolving pediatric dosing regulations and material substitution timelines to align capacity investments with compliance deadlines.
Market Dynamics
FDA and EMA pediatric dosing mandates are compressing procurement timelines for medical-grade graduated vessels, forcing manufacturers to requalify molding lines ahead of compliance deadlines.
Growth Catalysts
- EMA Medical Device Regulation:Class I reclassification of dosing accessories is accelerating documentation investments by European suppliers seeking notified body certification.
- Home care pharmacies:Outpatient medication management programs across the United States are expanding unit-dose procurement of calibrated cups for chronic disease patients.
- Polystyrene-to-polypropylene substitution:Heat-resistant resin grades are displacing legacy materials in multi-dose warming applications.
Market Restraints
- Medical-grade resin cost volatility:Polypropylene homopolymer prices fluctuate with propylene feedstock exposure, squeezing margin on standard graduated cups.
- Mold fabrication concentration:Precision injection tooling for 1-milliliter graduation accuracy concentrates among German and Japanese specialty moldmakers.
- Reusable glass alternatives:Hospital sustainability committees are evaluating autoclavable glass dosing vessels for high-volume pharmacy compounding operations.
Strategic Opportunities
- India outpatient expansion:CDSCO alignment with ISO 8319 dosing device standards creates entry pathway for exporters serving government health missions.
- Biodegradable PLA formulations:Pharmacy chains seeking differentiation are piloting compostable cups in sustainability-focused metropolitan markets.
- Direct-to-pharmacy logistics:Regional distributors are bypassing wholesale tiers to capture margin on high-frequency restocking contracts.
Industry Challenges
- Biocompatibility testing backlog:FDA cytotoxicity validation queues for new resin grades extend qualification timelines by eight to fourteen months.
- Cleanroom molding capacity:ISO 14644 Class 8 certification requirements for pediatric dosing devices demand capital redeployment from food-contact lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Disposable Medicine Measuring Cups Market |
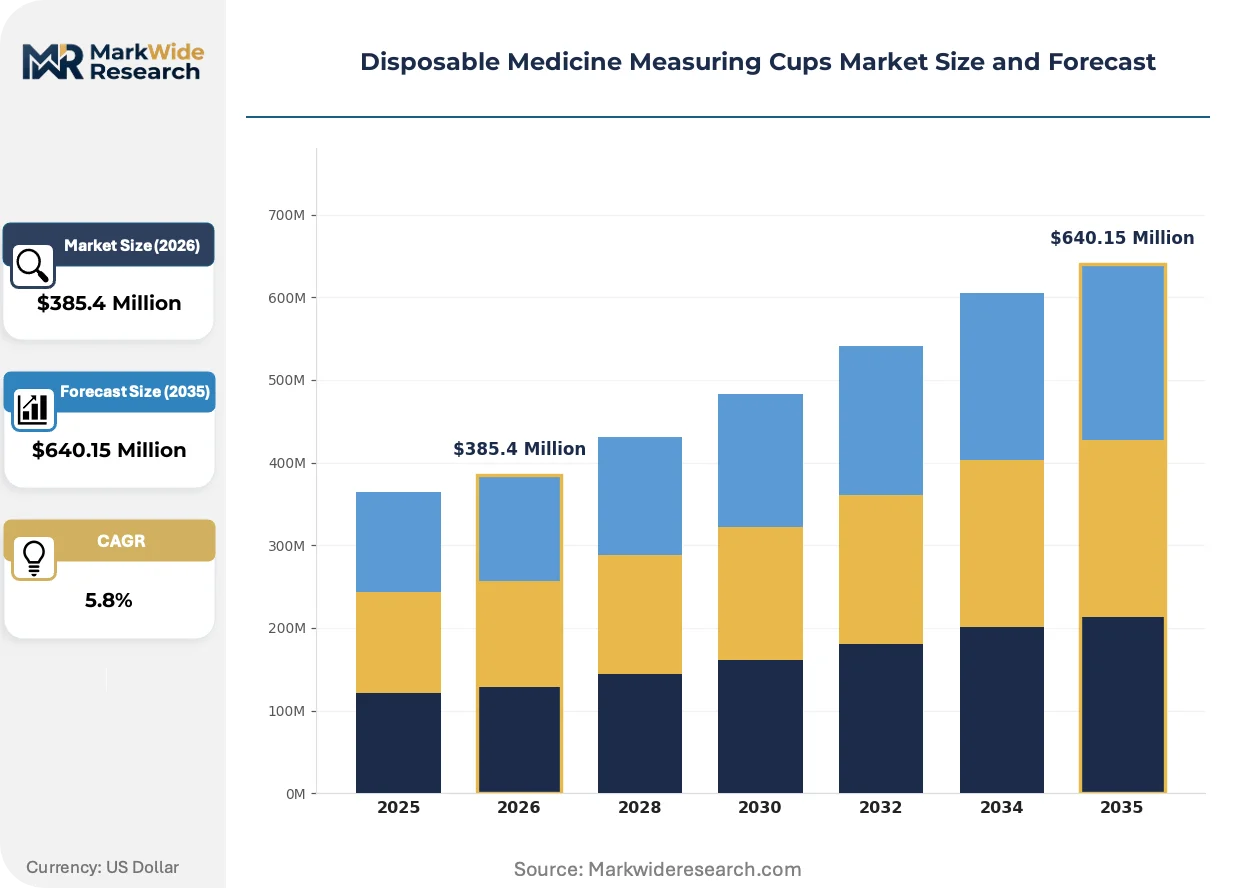
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $640.15 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Use Cups, Multi-Dose Cups, Graduated Cups, Child-Friendly Cups Material: Plastic, Polypropylene, Polystyrene, Biodegradable Materials Capacity: 5 ml, 10 ml, 20 ml, 30 ml End User: Hospitals, Pharmacies, Home Care, Clinics |
| Companies Covered | Origin Pharma Packaging, SGH HEALTHCARING, Hammarplast Medical AB, A.M.G. Medical Inc., Suzhou Xuanweicheng Biological Co.Ltd., SKYDEAR PLASTIC TECHNOLOGY (ZHEJIANG) CO.LTD, McKesson, Dynarex Corporation, Medline, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Disposable Medicine Measuring Cups Market Strategic Shifts
Digital printing and connected packaging are converging with material science advances to transform how dosing accuracy is verified and tracked across pharmaceutical supply chains.
Photopolymer inkjet printing of graduation marks is unifying decoration and calibration functions into single-pass production, eliminating separate pad-printing stations. Hospital buying groups in Germany are specifying digitally printed cups for lot-level traceability. This convergence is compressing equipment footprints for mid-volume manufacturers seeking flexible short-run capabilities.
REACH restrictions on intentionally added microplastics are compelling reformulation of color masterbatches used in pediatric cup production. European compounders are migrating to mineral-based pigments ahead of enforcement timelines. The regulation is accelerating qualification of alternative visual differentiation methods including embossed graduation textures.
Consolidated buying by national pharmacy chains is compressing supplier rosters to three approved vendors per region. Independent pharmacies are responding through cooperative purchasing organizations that aggregate volume for direct manufacturer negotiation. This concentration is most visible in United States retail pharmacy networks where CVS and Walgreens procurement teams centralize dosing device specifications.
Disposable Medicine Measuring Cups Market Segmentation
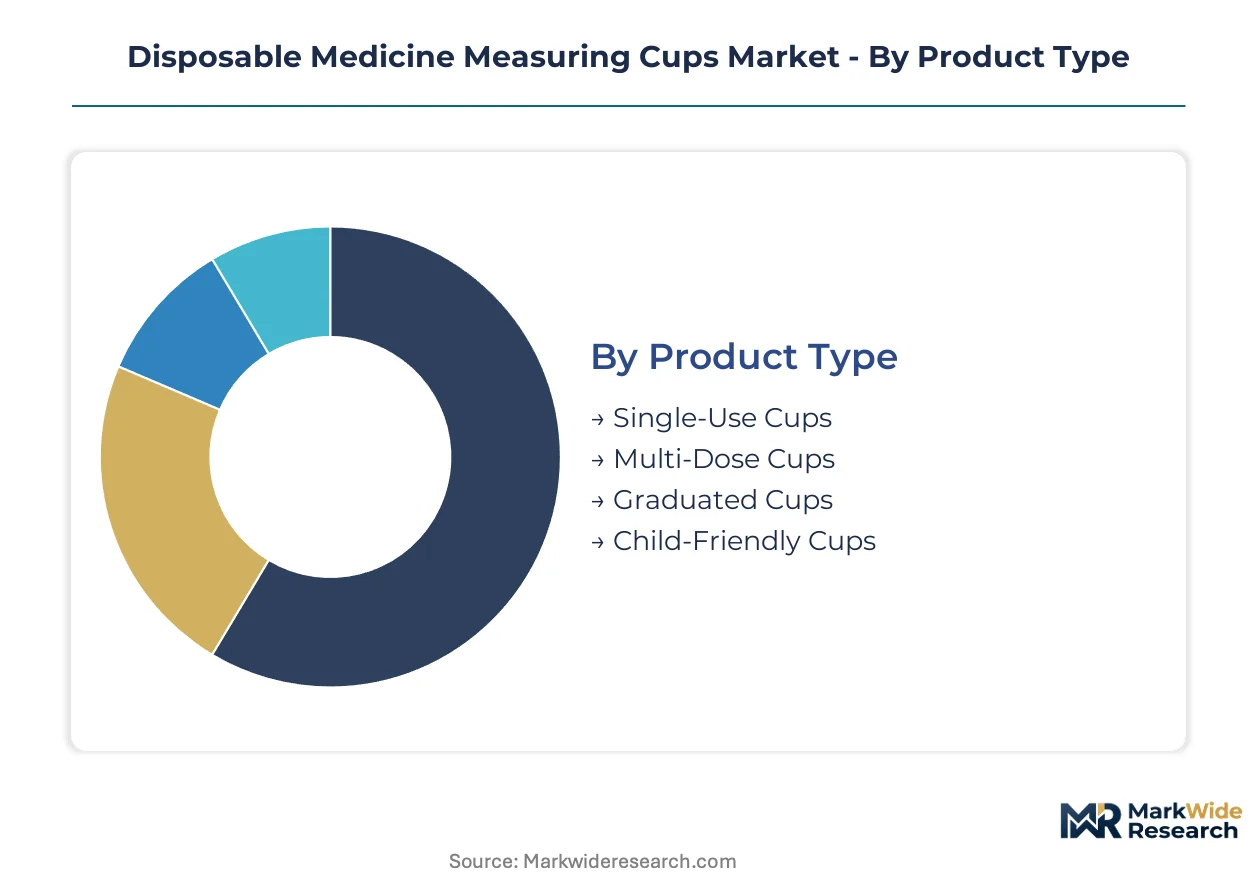
Segmentation in disposable medicine measuring cups reveals how procurement specifications diverge across clinical settings and patient populations. Manufacturers must align molding capacity with distinct accuracy, safety, and sustainability requirements rather than treating the category as uniform.
Product Type:
Supply concentration tilts toward graduated vessels as hospital buying groups consolidate specifications around calibrated dosing accuracy.
- Single-Use Cups:Ungraduated polypropylene vessels for one-time oral medication administration. Demand concentrates in United States retail pharmacies dispensing over-the-counter liquid formulations where cost minimization outweighs precision requirements.
- Multi-Dose Cups:Reusable-capacity vessels with reinforced rims for sequential dosing across a treatment course. German hospital pharmacies specify these for oncology outpatient protocols where thermal stability during warming cycles is mandatory.
- Graduated Cups:Calibrated vessels with 1-milliliter graduation accuracy for precise liquid measurement. FDA pediatric dosing mandates are compressing procurement timelines for medical-grade graduated vessels.
- Child-Friendly Cups:Color-differentiated vessels with spill-resistant rims and tactile graduation markers. Pediatric formulation expansion across China's tier-one cities is accelerating volume requirements.
Today's leader: Graduated Cups. Tomorrow's challenger: Child-Friendly Cups.
Material:
Cost tier stratification separates commodity resins from certified medical grades with biocompatibility documentation.
- Plastic:Generic resin category encompassing uncertified polymers for non-regulated markets. Indian government health missions procure these for rural dispensaries where cost thresholds dominate over FDA alignment.
- Polypropylene:Heat-resistant homopolymer and copolymer grades displacing legacy materials in multi-dose warming applications. EMA Medical Device Regulation reclassification is accelerating documentation investments by European suppliers seeking notified body certification.
- Polystyrene:Crystal and high-impact grades for cost-sensitive single-use applications. SKYDEAR PLASTIC TECHNOLOGY competes on polystyrene cup volumes for export markets.
- Biodegradable Materials:PLA and PHA formulations for compostable end-of-life pathways. Pharmacy chains in sustainability-focused metropolitan markets are piloting these for differentiation.
Cost compression favors Polystyrene today. Regulatory pressure and warming applications elevate Polypropylene tomorrow.
Capacity:
Volume scale concentrates procurement around mid-range capacities that balance pediatric precision with adult dosing flexibility.
- 5 ml:Micro-volume vessels for neonatal and pediatric formulations requiring sub-milliliter accuracy. Concentrated demand in United States children's hospitals and NICU settings.
- 10 ml:Standard pediatric capacity with 0.5-milliliter graduation intervals. China's NMPA alignment with GB standards for plastic food-contact materials extends to these pharmaceutical applications.
- 20 ml:Adult maintenance dosing standard for chronic disease outpatient management. Home care pharmacies across North America are expanding procurement of this capacity for unit-dose programs.
- 30 ml:Maximum single-dose capacity for antibiotic suspensions and liquid nutritional supplements. German national health services specify these for hospital discharge medication kits.
20 ml dominates current procurement volumes. 5 ml is gaining share fastest as pediatric formulation pipelines mature.
End User:
Customer type determines packaging configuration, with hospitals demanding lot-level traceability and home care prioritizing patient compliance features.
- Hospitals:Integrated health systems with centralized pharmacy compounding and barcode verification requirements. Consolidated buying by national pharmacy chains is compressing supplier rosters to three approved vendors per region.
- Pharmacies:Retail and outpatient dispensaries with direct-to-consumer packaging needs. McKesson anchors North American distribution through its direct-to-pharmacy logistics network.
- Home Care:Chronic disease patients managing multi-dose regimens outside clinical settings. Outpatient medication management programs across the United States are expanding unit-dose procurement for this segment.
- Clinics:Ambulatory care facilities with intermediate volume and specification requirements. Origin Pharma Packaging leverages European regulatory certifications to sustain supply relationships with national health services in this channel.
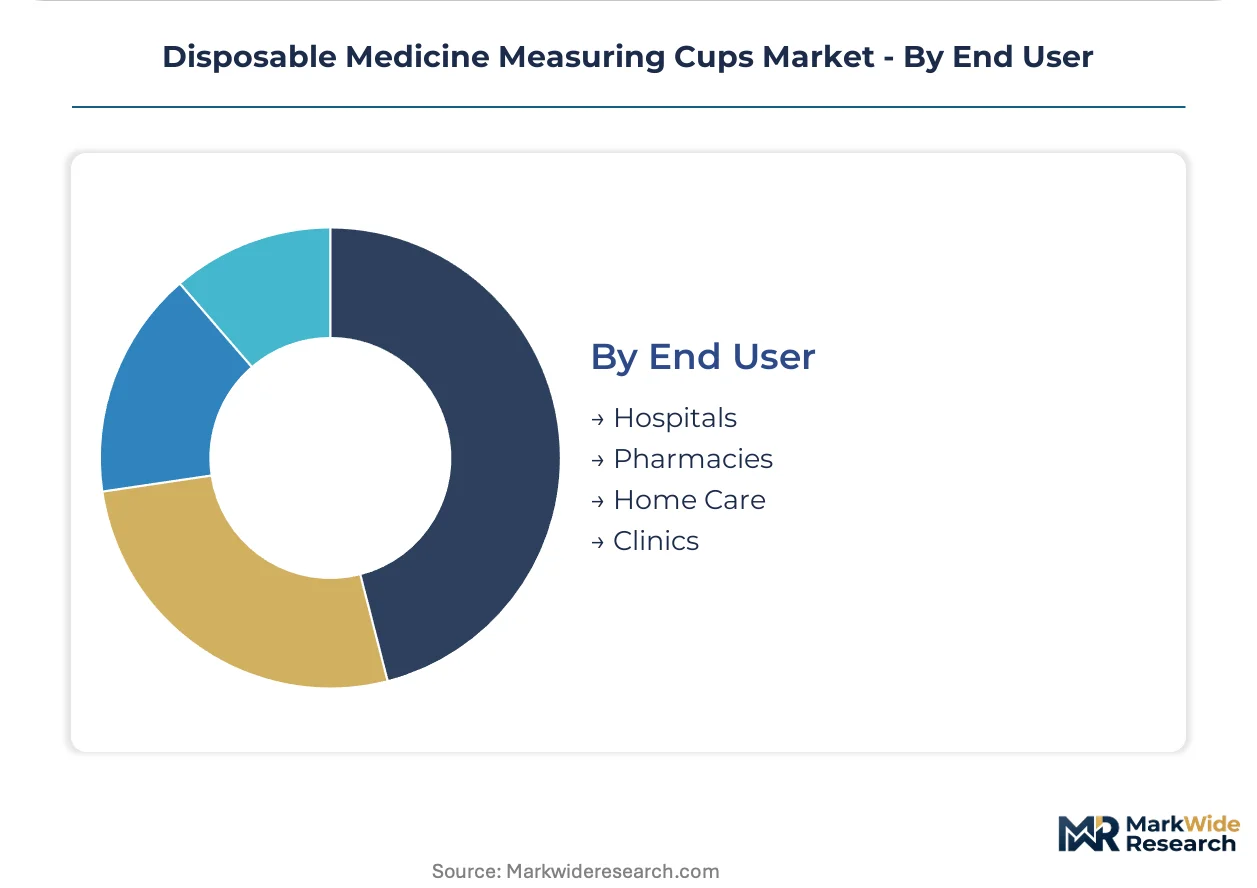
Hospitals command specification authority today. Home Care is climbing the fastest as outpatient medication management scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturers migrate production toward jurisdictions where medical-grade resin compliance costs diverge from end-market pricing power. FDA pediatric dosing mandates in the United States compress supplier margins while EMA documentation requirements in Europe accelerate qualification investments. This regulatory-arbitrage dynamic concentrates molding capacity in Germany, China, and the United States.
United States
Home care pharmacies expand unit-dose procurement for chronic disease outpatient programs. FDA enforces strict material biocompatibility standards for devices contacting oral medications. McKesson anchors distribution through direct-to-pharmacy logistics networks serving retail and hospital channels.
Germany
National health services consolidate buying around three approved vendors per region. EMA Medical Device Regulation reclassifies dosing cups as Class I accessories with escalating documentation requirements. Precision injection tooling clusters in Baden-Württemberg support 1-milliliter graduation accuracy for hospital pharmacy compounding.
China
Tier-one cities scale pediatric formulation volumes driving child-friendly cup demand. NMPA aligns with GB standards for plastic food-contact materials extending to pharmaceutical applications. SKYDEAR PLASTIC TECHNOLOGY in Zhejiang competes on polystyrene cup volumes for export markets.
India
Government health missions procure graduated dosing tools for rural dispensary expansion. CDSCO alignment with ISO 8319 dosing device standards creates entry pathways for exporters. Maharashtra-based distributors aggregate cooperative purchasing volume for direct manufacturer negotiation.
United Kingdom
Hospital buying groups specify digitally printed cups for lot-level traceability. REACH restrictions on intentionally added microplastics compel reformulation of color masterbatches. London-Southeast pharmacy chains pilot biodegradable PLA formulations for sustainability differentiation.
Disposable Medicine Measuring Cups Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue biodegradable material differentiation and direct-to-pharmacy logistics bypasses. The vendor base stratifies across three tiers: European regulatory-certified specialists, North American distribution-anchored suppliers, and Asian volume exporters. Two dominant competitive moves define current positioning: multi-source procurement consolidation by hospital buying groups and polystyrene-to-polypropylene material substitution investments.
Within the regulatory-certified tier, Origin Pharma Packaging leverages European certifications to sustain supply relationships with national health services. McKesson anchors North American distribution infrastructure through direct-to-pharmacy logistics networks. SKYDEAR PLASTIC TECHNOLOGY occupies the volume-export position competing on polystyrene cup production for cost-sensitive markets.
| Leading Market Players |
|---|
| Origin Pharma Packaging |
| SGH HEALTHCARING |
| Hammarplast Medical AB |
| A.M.G. Medical Inc. |
| Suzhou Xuanweicheng Biological Co.Ltd. |
| SKYDEAR PLASTIC TECHNOLOGY (ZHEJIANG) CO.LTD |
| McKesson |
| Dynarex Corporation |
| Medline |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap molders in Baden-Württemberg and Zhejiang anchor capacity investments to long-term pharmacy contracts, translating supply discipline into stable pricing corridors that resist spot-market volatility. This ownership pattern reinforces patient capital deployment toward medical-grade resin qualification and ISO 14644 cleanroom certification, creating tiered supply reliability that buyers price into contract premiums.
Pricing Analysis
Distributor margin layers compress pricing transparency as McKesson's direct-to-pharmacy logistics network captures 15-20 point spreads between manufacturer net and retail shelf. Three-tier pricing structure across FDA-validated premium, ISO-certified standard, and uncertified economy grades separates hospital buying groups from independent pharmacies and rural dispensaries. Cost compression in polystyrene single-use cups is intensifying because propylene feedstock volatility squeezes polypropylene homopolymer margins. Retail pharmacy chains exhibit highest price sensitivity, while German national health services prioritize documentation compliance over unit cost.
Supply Chain Analysis
Trans-Pacific container rates and European road freight costs are reshaping regional sourcing decisions as manufacturers evaluate nearshoring against Asian volume advantages. Injection molding capacity clusters in Germany, China, and the United States, with precision tooling dependencies drawing from Japanese and German specialty moldmakers. Raw material supply rests on propylene monomer availability, medical-grade color masterbatch qualification, and biocompatible additive sourcing. Single-source vulnerability concentrates in 1-milliliter graduation mold fabrication, where three specialty producers control precision tooling. Distribution runs through consolidated hospital buying groups, cooperative pharmacy purchasing organizations, and direct-to-pharmacy logistics networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Disposable medicine measuring cups function as a stable compounder anchored by non-discretionary demand from chronic disease outpatient programs and pediatric formulation expansion.
For Market Incumbents: Extend cleanroom molding capacity ahead of FDA pediatric dosing compliance deadlines to capture requalification-driven procurement consolidation. Defend margin position by backward integration into medical-grade resin compounding, reducing exposure to polypropylene homopolymer price volatility. Anchor relationships with national health services through dedicated regulatory affairs support for EMA Medical Device Regulation documentation. For New Entrants and Emerging Players: Launch via cooperative purchasing organizations serving independent United States pharmacies, bypassing consolidated wholesale tiers. Target India's government health mission procurement for rural dispensary expansion, where CDSCO alignment with ISO 8319 standards creates entry pathways. Differentiate through biodegradable PLA formulations for sustainability-focused metropolitan pharmacy chains seeking brand differentiation. For Investors and Strategic Acquirers: Hospital buying groups and pharmacy chain procurement teams are the most active acquirer categories in this space, consolidating supplier rosters to three approved vendors per region. Acquisition targets should display European regulatory certifications paired with underutilized cleanroom capacity. Watch for FDA biocompatibility testing backlog resolution as an inflection signal for new resin qualification timelines and capacity redeployment windows.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Pediatric Dosing Compliance Investment | Medical-grade graduated vessel requalification captures procurement consolidation from hospital buying groups. |
| EMA Notified Body Certification Pathway | Class I accessory documentation investments sustain supply relationships with German national health services. |
| Direct-to-Pharmacy Logistics Bypass | Regional distributors capture margin compression from McKesson-anchored wholesale networks. |
| Biodegradable Material Formulation Development | PLA and PHA pilot programs differentiate pharmacy chains in sustainability-focused metropolitan markets. |
| Precision Injection Tooling Capacity Expansion | 1-milliliter graduation accuracy capabilities address mold fabrication concentration among German and Japanese specialty producers. |
Study Parameters
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining interviews with hospital pharmacy procurement managers, GPO contracts specialists, medical device regulatory affairs leads, and injection molding operations directors. Secondary validation draws from FDA 510(k) filings, EMA Medical Device Regulation guidance documents, hospital procurement databases, and customs trade data for medical-grade resin imports. Bottom-up capacity modeling triangulates against top-down spending estimates from national health service budget disclosures.
Granularity-level modeling disaggregates volume and value across product type, material grade, capacity tier, and end-user channel, with additional segmentation by regional regulatory cluster. CAGRs derive from patient population growth in chronic disease management, pediatric formulation pipeline maturation, and outpatient medication management program expansion. Forecast inputs incorporate medical-grade resin price elasticity, cleanroom certification capacity constraints, and procurement consolidation timelines from hospital buying groups.
Several conditions sit outside the modeled scope, including sudden FDA guidance revisions on pediatric dosing device specifications, REACH enforcement acceleration on intentionally added microplastics, and sovereign trade policy shifts affecting medical-grade resin tariffs. Forecasts reflect assumptions about regulatory alignment timelines and material substitution trajectories that may shift with biocompatibility testing queue resolution. Stakeholders should weight assumptions against their own operating context and qualification pipeline visibility.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Midline Catheters Market
Medical Devices
Artificial Respirator Market
Medical Devices
Biologic Injectors Market
Medical Devices
Pet Mobility Aids Market
Medical Devices
Global Extracorporeal Shock Wave Lithotripsy Market
Medical Devices
High Tibial Osteotomy (HTO) Plates Market
Medical Devices
Enteral Feeding Devices Market
Medical Devices
Skull Clamp Market
Medical Devices
Australia Respiratory Devices Market
Medical Devices
Hemoconcentrators Market
Medical Devices
Carotid Stenting Systems Market
Medical Devices
Global Medical Footwear Market
Medical Devices
Global Oxygen Cylinders and Concentrators Market
Medical Devices
Portable OT Light Market
Medical Devices
Endoscopic Mucosal Resection Device Market
Medical Devices
Sinus Dilation Devices Market